
 Gunn Diode Market | 2026-2036
Gunn Diode Market Size, Share, and Industry Trends Forecast 2026-2036
Gunn Diode Market Analytics
Defense procurement channels is reconfiguring as prime contractors consolidate vendor lists for microwave subsystems. Thales Group leverages its European radar integration footprint to sustain captive demand for high-power Gunn diodes. MITEQ Inc. competes through specialized amplifier-diode pairing capabilities that anchor its position in test and measurement segments. Microwave Dynamics differentiates via millimeter-wave packaging expertise that controls niche aerospace qualification pathways.
A Gunn diode is a two-terminal semiconductor device fabricated from n-type gallium arsenide or indium phosphide that exploits the transferred electron effect to generate microwave oscillations, typically operating between 1 GHz and 100 GHz with output power ranging from milliwatts to several watts. Its primary purpose is to serve as a compact, solid-state source for radar transmitters, microwave relay systems, and electronic warfare countermeasure equipment. Millimeter Wave Gunn Diodes command premium positioning as aerospace and defense programs phase out magnetron tubes in favor of solid-state alternatives. Low-Power Gunn Diodes occupy mature volume tiers where telecommunications infrastructure refresh cycles sustain baseline demand without margin expansion. THz Gunn Diodes represent the fastest-growing category as semiconductor lithography enables sub-millimeter emission frequencies for next-generation imaging arrays.
FCC equipment authorization rules constrain unlicensed microwave transmission bands, shaping product frequency specifications for US-bound communication equipment. EAR dual-use export controls administered by the US Department of Commerce restrict GaAs and InP diode transfers to designated countries, fragmenting supplier access patterns. Japan's METI oversees domestic production reporting for compound semiconductor devices under its materials security framework. Stakeholders must monitor how emerging quantum radar programs and 6G terrestrial backhaul specifications redefine oscillator performance benchmarks ahead of specification freezes.
Market Dynamics
Defense radar modernization programs across NATO members are consolidating vendor lists for microwave subsystems, compressing qualification timelines and favoring suppliers with captive GaAs fabrication capabilities.
Growth Catalysts
- GaN-on-SiC Substrate Advances:US and Japanese foundries are improving thermal performance thresholds for high-power variants, enabling extended duty cycles in phased-array radar transmitters.
- FCC Equipment Authorization Rules:Unlicensed microwave transmission band constraints in the United States are shaping product frequency specifications that favor solid-state oscillator adoption over magnetron tubes.
- 6G Terrestrial Backhaul Specifications:Emerging millimeter-wave infrastructure requirements are expanding addressable frequency bands for low-phase-noise Gunn diode sources.
Market Restraints
- EAR Dual-Use Export Controls:US Department of Commerce restrictions on GaAs and InP diode transfers fragment supplier access patterns to designated countries, complicating international distribution.
- Input Cost Volatility in Indium:Indium phosphide substrate pricing fluctuates with photovoltaic and display panel demand, squeezing margins on millimeter-wave variants.
- Magnetron Tube Substitution Economics:Vacuum tube sources retain cost advantages in high-pulse-power marine radar applications where solid-state replacement remains uneconomical.
Strategic Opportunities
- Quantum Radar Oscillator Benchmarks:Emerging quantum radar programs in Germany and the United Kingdom are redefining low-phase-noise performance specifications ahead of formal requirement freezes.
- Japan's Materials Security Framework:METI domestic production reporting mandates for compound semiconductor devices are incentivizing captive supply chain investments by Japanese system integrators.
- THz Imaging Array Convergence:Semiconductor lithography enabling sub-millimeter emission frequencies is opening next-generation security screening and medical imaging applications.
Industry Challenges
- Millimeter-Wave Packaging Skill Gap:Aerospace qualification pathways require specialized hermetic sealing expertise that concentrates among a limited supplier base in Japan and Germany.
- Integration Complexity with Legacy Magnetron Systems:Radar platform retrofit programs demand mechanical and electrical interface adaptation that extends engineering validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gunn Diode Market |
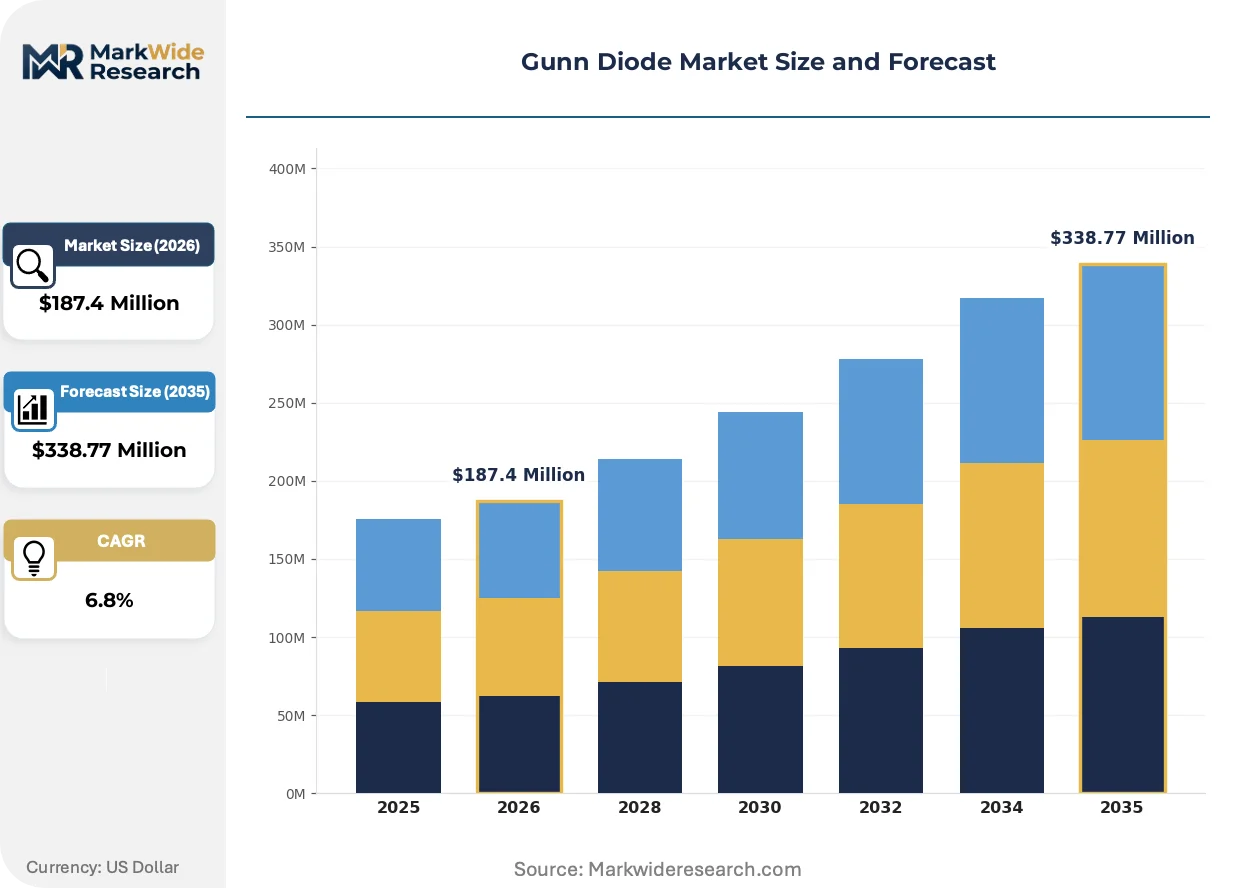
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Power Gunn Diodes, Low-Power Gunn Diodes, Millimeter Wave Gunn Diodes, THz Gunn Diodes End User: Aerospace, Telecommunications, Automotive, Industrial Application: Radar Systems, Microwave Transmission, Communication Equipment, Test and Measurement Technology: Monolithic Integrated Circuit, Heterojunction Bipolar Transistor, Hybrid Technology, GaN Technology |
| Companies Covered | Thales Group, MITEQ Inc., Microwave Dynamics, Teratech Components, American Microsemiconductor, ROHM CO., LTD., TeraSense Group, Microsemi Corporation, Teledyne Lincoln Microwave, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gunn Diode Market Evolving Landscape
Active electronically scanned array architectures are displacing mechanically steered radar systems, redrawing component specifications across defense and civil aviation segments.
Transferred electron device modeling software is digitizing the traditional empirical design cycle for Gunn diode oscillators. Defense prime contractors in Germany and the United Kingdom are adopting computational electromagnetic simulation suites that compress prototype iteration timelines from months to weeks. This capability is digitizing the competitive barrier between established suppliers and specialized entrants.
REACH substance restrictions on hexavalent chromium coatings are forcing migration to alternative passivation chemistries for hermetic package sealing. European aerospace suppliers face reformulation costs and requalification delays. Millimeter-wave variants with ceramic-metal packages are most affected, with German integrators accelerating supplier audits to secure compliant sources.
Buyer consolidation among tier-one radar integrators is compressing component vendor lists and extending sole-source agreement durations. Thales Group and similar primes are narrowing approved supplier pools to capture volume pricing and technical roadmapping alignment. This pattern is most visible in NATO defense procurement channels, where multi-year framework agreements now dominate high-power Gunn diode sourcing.
Gunn Diode Market Segmentation
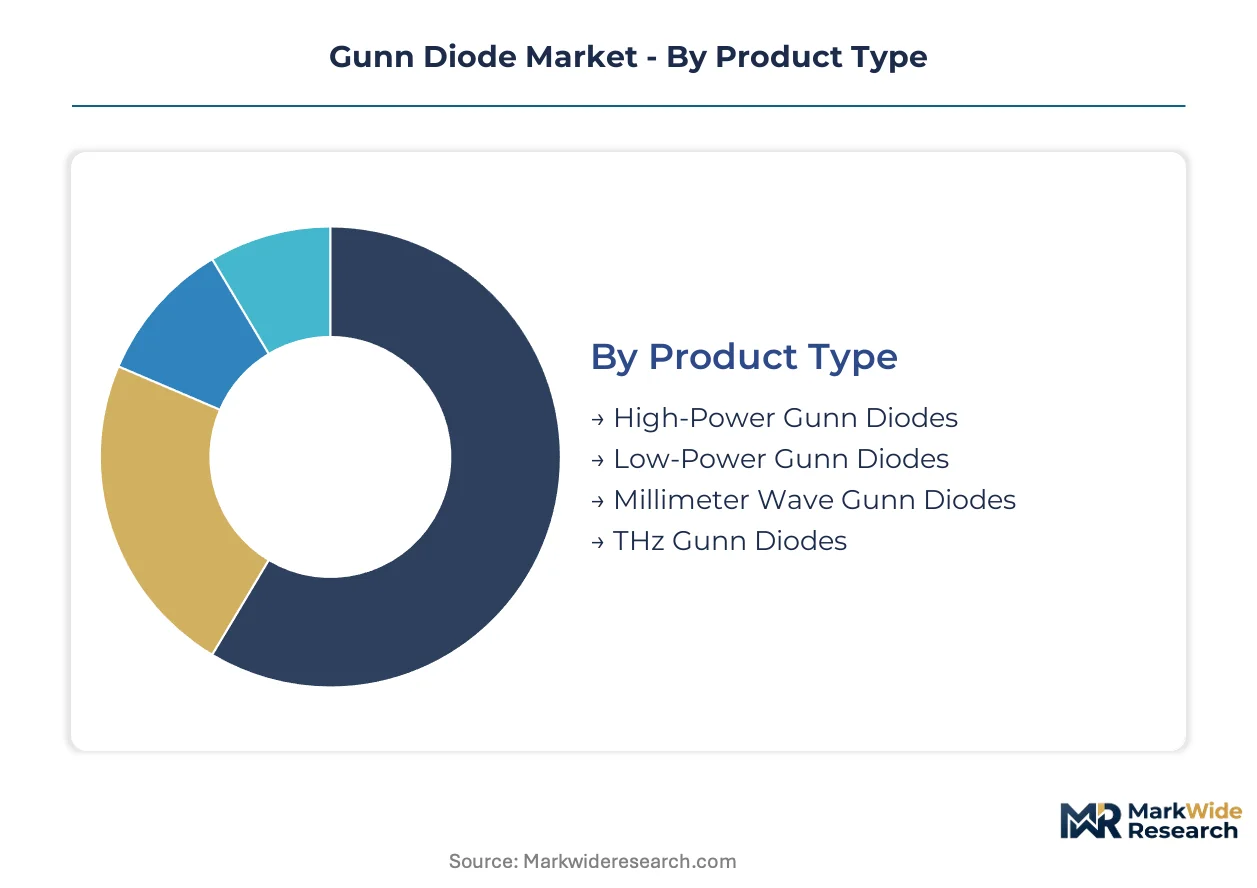
Gunn diode market segmentation reveals distinct performance tiers where thermal tolerance and frequency range determine procurement economics. Defense contractors prioritize high-power variants for radar transmitters while telecommunications infrastructure sustains volume demand for low-power alternatives.
Product Type:
Maturity splits sharply between established millimeter-wave platforms and emerging terahertz architectures.
- Millimeter Wave Gunn Diodes:Operating between 30 GHz and 300 GHz, these devices leverage GaAs and InP substrates for phased-array radar and satellite communication terminals. NATO defense procurement in Germany and the United Kingdom concentrates demand as active electronically scanned arrays displace mechanically steered systems.
- THz Gunn Diodes:Sub-millimeter emission frequencies enabled by advanced semiconductor lithography target next-generation security screening and medical imaging arrays. Research programs in Japan's METI-funded institutes are accelerating qualification timelines for commercial deployment.
- High-Power Gunn Diodes:Output power exceeding one watt serves military radar transmitters and electronic warfare systems with extended duty cycle requirements.
- Low-Power Gunn Diodes:Milliwatt-range output dominates telecommunications infrastructure refresh cycles without significant margin expansion.
Millimeter Wave Gunn Diodes handle the majority of throughput; THz Gunn Diodes are expanding most quickly on share.
End User:
Application complexity varies from aerospace qualification rigor to industrial volume procurement.
- Aerospace:Hermetic packaging and radiation-hardened specifications dominate defense radar and satellite payload applications. Japanese and German suppliers control qualification pathways for NATO prime contractor vendor lists.
- Telecommunications:Baseline oscillator demand from 5G backhaul infrastructure refresh sustains volume without premium pricing. FCC equipment authorization rules constrain frequency specifications for US-bound equipment.
- Automotive:Emerging 77 GHz radar modules for advanced driver-assistance systems create new frequency band requirements.
- Industrial:Process control and non-destructive testing applications favor cost-optimized packaging over aerospace-grade specifications.
Aerospace commands the steepest expansion trajectory; telecommunications absorbs the largest unit volumes.
Application:
System integration depth separates radar platforms from test equipment procurement patterns.
- Radar Systems:Phased-array transmitters in Germany and the United Kingdom require low-phase-noise oscillators with GaN-on-SiC thermal management. Defense modernization programs consolidate vendor lists around captive fabrication capabilities.
- Microwave Transmission:Point-to-point relay infrastructure in Japan sustains demand for stable frequency sources across millimeter-wave bands.
- Communication Equipment:Backhaul and terrestrial links favor solid-state replacement of magnetron tubes in unlicensed band applications.
- Test and Measurement:Specialized amplifier-diode pairing requirements anchor demand in calibration and signal generation equipment.
Radar Systems generate the dominant revenue concentration; Test and Measurement shows the fastest share gain.
Technology:
Substrate material and integration architecture determine thermal performance thresholds and manufacturing cost structures.
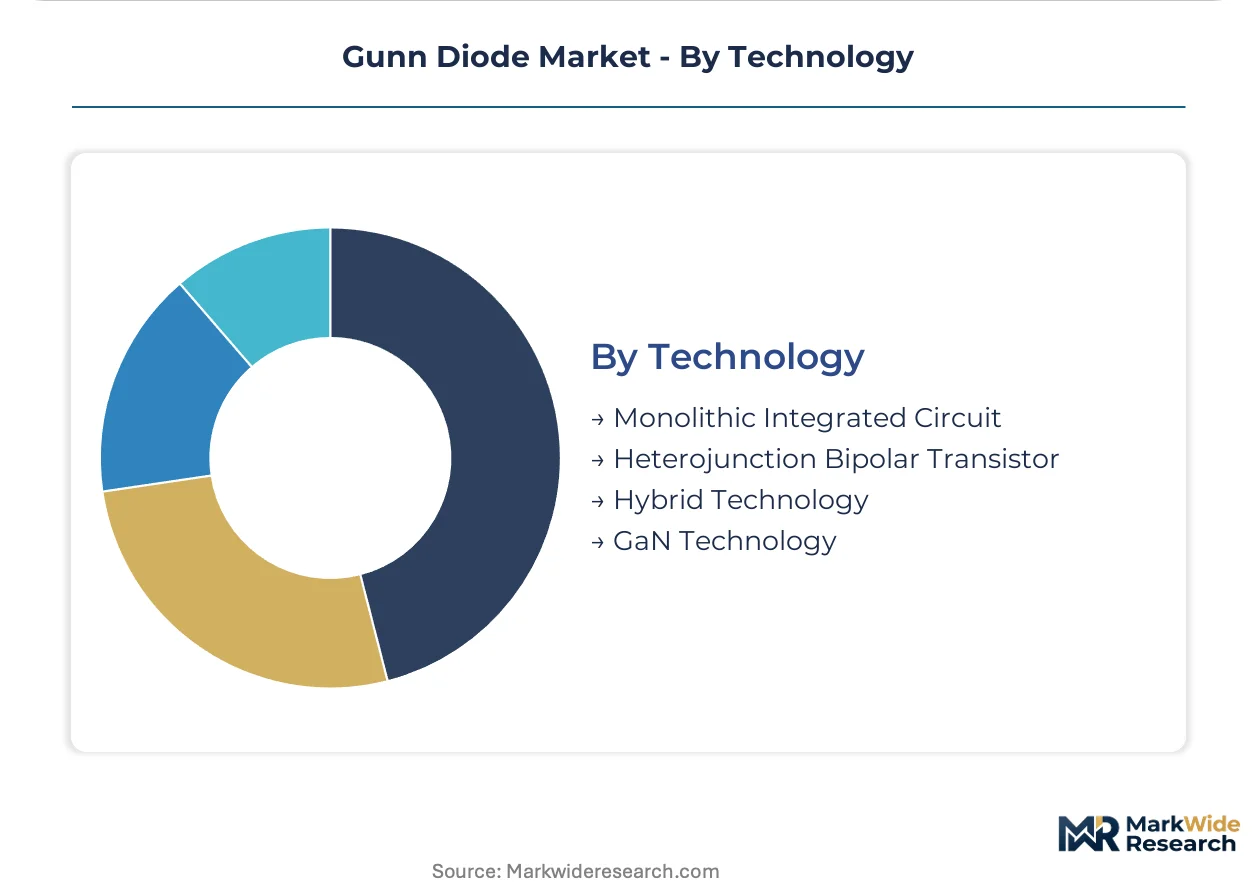
- GaN Technology:Gallium nitride on silicon carbide substrates from US and Japanese foundries enable highest power-density operation for extended duty cycle radar transmitters. Thermal conductivity improvements support active electronically scanned array packaging density.
- Monolithic Integrated Circuit:Single-chip integration of oscillator and control functions reduces footprint for space-constrained aerospace applications.
- Heterojunction Bipolar Transistor:InP-based HBT structures target low-phase-noise specifications for quantum radar oscillator benchmarks.
- Hybrid Technology:Discrete component assembly retains cost advantages for industrial and legacy system retrofit applications.
GaN Technology captures the premium tier; Hybrid Technology maintains volume leadership in cost-sensitive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC equipment authorization rules in the United States shape frequency specifications for unlicensed microwave transmission bands, while METI in Japan and national regulators across Europe enforce distinct compound semiconductor frameworks that fragment procurement patterns.
United States
Defense radar modernization programs drive procurement of high-power variants for phased-array transmitters. FCC equipment authorization rules constrain unlicensed microwave transmission bands, favoring solid-state oscillator adoption. Boston-area defense contractors and California foundries concentrate GaN-on-SiC substrate development for thermal performance gains.
Germany
Active electronically scanned array architectures displace mechanically steered radar systems across NATO defense programs. REACH substance restrictions on hexavalent chromium coatings force migration to alternative passivation chemistries for hermetic package sealing. Bavarian aerospace suppliers accelerate supplier audits to secure compliant millimeter-wave component sources.
United Kingdom
Quantum radar oscillator benchmarks redefine low-phase-noise performance specifications ahead of formal requirement freezes. National security frameworks govern compound semiconductor procurement for defense applications. Scottish and southern England radar integration clusters consolidate vendor lists around captive fabrication capabilities.
Japan
METI domestic production reporting mandates for compound semiconductor devices incentivize captive supply chain investments by system integrators. GaN-on-SiC substrate advances from domestic foundries improve thermal performance thresholds for extended duty cycle applications. Nagoya and Tokyo metropolitan areas concentrate millimeter-wave packaging expertise for aerospace qualification pathways.
France
Radar platform retrofit programs demand mechanical and electrical interface adaptation that extends engineering validation cycles. EU defense procurement coordination shapes multi-year framework agreements for microwave subsystems. Paris-region prime contractors narrow approved supplier pools to capture volume pricing alignment.
Gunn Diode Market Competitive Landscape
Defense-anchored integrators and specialized component fabricators split the market along qualification depth and thermal performance vectors. Thales Group exemplifies the captive integration archetype, while MITEQ Inc. and Microwave Dynamics occupy specialized amplifier-diode and millimeter-wave packaging niches. Consolidation concentrates among tier-one radar integrators compressing vendor lists, with strategic partnerships and multi-year framework agreements dominating competitive moves.
Within the defense integration tier, Thales Group represents European radar system anchoring. MITEQ Inc. exemplifies specialized amplifier-diode pairing capabilities. Microwave Dynamics occupies millimeter-wave packaging expertise controlling niche aerospace qualification pathways. These three entities illustrate how vendor consolidation and technical specialization stratify competitive positioning across NATO procurement channels and test equipment segments.
| Leading Market Players |
|---|
| Thales Group |
| MITEQ Inc. |
| Microwave Dynamics |
| Teratech Components |
| American Microsemiconductor |
| ROHM CO., LTD. |
| TeraSense Group |
| Microsemi Corporation |
| Teledyne Lincoln Microwave |
| Others |
Value Network & Pricing Analysis
Undercapacity in Japanese millimeter-wave packaging facilities drives supplier selectivity and sustains premium pricing for aerospace-qualified Gunn diodes. GaN-on-SiC substrate allocation from US and Japanese foundries tightens when defense procurement cycles peak, compressing margins on mid-tier commercial variants.
Pricing Analysis
Geographic price spreads of 40-60 percent separate German aerospace-grade hermetic packages from industrial-tier Asian sourcing. Three-tier pricing structure across military-qualified, commercial-grade, and unscreened economy levels reflects certification depth and thermal performance guarantees. Cost compression in low-power telecommunications tiers intensifies as volume buyers consolidate vendor lists. Defense contractors exhibit lowest price sensitivity due to sole-source qualification requirements, while industrial process-control buyers negotiate aggressively on unit economics.
Supply Chain Analysis
Extended payment terms from NATO prime contractors now stretch to 90-120 days, forcing component suppliers to access supply-chain finance facilities. Manufacturing concentrates in Japan, Germany, and the United States, with Nagoya and Bavarian clusters controlling aerospace qualification pathways. Indium phosphide substrates, GaAs wafers, and ceramic-metal package housings anchor raw material dependencies. Single-source vulnerability concentrates in sub-millimeter lithography equipment for THz variants. Distribution runs through authorized defense procurement channels and specialized microwave component distributors serving test equipment segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gunn diode procurement is shifting toward platform-standardized active electronically scanned arrays, where oscillator interoperability across radar generations locks in long-term supply relationships.
For Market Incumbents: Build captive fabrication moats through in-house GaAs and InP wafer processing to defend against fabless entrants exploiting transferred-electron device modeling software. Consolidate millimeter-wave packaging expertise via targeted acquisition of Japanese hermetic sealing specialists. Capacity expansion in Germany addresses REACH-compliant passivation chemistry bottlenecks threatening aerospace qualification continuity. For New Entrants and Emerging Players: Establish a beachhead in THz imaging array development programs where semiconductor lithography barriers remain lower than mature millimeter-wave defense supply chains. Target automotive 77 GHz radar modules as the most penetrable volume segment, leveraging standard PCB packaging to bypass aerospace qualification hurdles. Pursue amplifier-diode pairing partnerships with test equipment OEMs to secure reference design wins. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among suppliers holding multi-year NATO framework agreements with Thales Group and similar primes. Five-to-ten-year viability favors specialists with METI-registered Japanese production facilities and EAR-compliant US export authorization. Watch quantum radar oscillator specification freezes in Germany and the United Kingdom as inflection signals for low-phase-noise premium tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-SiC Foundry Partnership | Secures thermal performance thresholds for extended duty cycle phased-array transmitters. |
| Hermetic Packaging Certification Investment | Unlocks NATO prime contractor vendor lists controlled by Japanese and German specialists. |
| THz Lithography Capability Buildout | Positions for METI-funded security screening and medical imaging array deployments. |
| REACH-Compliant Passivation Migration | Preserves European aerospace qualification as hexavalent chromium restrictions tighten. |
| Amplifier-Diode Integration Partnership | Anchors test equipment segment positioning through MITEQ-style pairing expertise. |
Research Methodology
The analysis maps millimeter-wave, THz, high-power, and low-power Gunn diode sub-sectors, each validated through primary interviews with radar system procurement officers, compound semiconductor fabrication managers, and microwave component distribution executives. Secondary sources include FCC equipment authorization filings, METI domestic production reports, EAR dual-use export control classifications, and NATO defense procurement databases. Bottom-up unit demand modeling triangulates against top-down defense budget allocation assessments.
Assumptions held fixed include active electronically scanned array displacement timelines and REACH substance restriction phase-out schedules, while GaN-on-SiC substrate yield improvements and quantum radar program funding trajectories were varied across sensitivity scenarios. Segmentation dimensions encompass product type, end user, application, and technology substrate. CAGRs derive from installed base replacement cycles and emerging THz imaging array penetration curves. Forecast inputs incorporate indium phosphide pricing volatility and EAR export control enforcement intensity.
Sensitivities concentrate around defense modernization program delays, indium supply disruptions from photovoltaic demand competition, and 6G backhaul specification timing. Forecasts reflect these documented assumptions without claiming predictive certainty. Macroeconomic contraction, regulatory restriction expansion, or solid-state oscillator technology substitution would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Asia-Pacific Optoelectronics Market
Optoelectronics
Quantum Dot Lasers Market
Optoelectronics
Quantum Cascade Lasers Market
Optoelectronics
Algainp Epitaxial Wafers Market
Optoelectronics
Vertical Cavity Surface Emitting Laser (Vcsels) Market
Optoelectronics
China Optical Detector Market
Optoelectronics
Automotive Optoelectronics Market
Optoelectronics
United States Optoelectronics Market
Optoelectronics
Smart Compact Projectors Market
Optoelectronics
Optoelectronic Development Tools Market
Optoelectronics
Taiwan Optoelectronics Market
Optoelectronics
Laser Diode Market
Optoelectronics
Gaas Wafer and Epiwafer Market
Optoelectronics
Quantum Dot Solar Cell Market
Optoelectronics
Optoelectronics Market
Optoelectronics
Integrated Circuit Optocouplers Market