
 IFF System Market | 2026-2036
IFF System Market Size, Share, and Industry Trends Forecast 2026-2036
IFF System Market Foresight
Multi-source procurement toward dual-qualified vendors is consolidating as defense ministries reduce sole-source dependency for critical identification subsystems. RTX Corporation leverages its captive semiconductor fabrication to secure transponder supply chains against foreign foundry risk. Thales Group anchors European Mode 5 certification programs through national military procurement frameworks in France and the United Kingdom. BAE Systems differentiates via software-defined radio architectures that merge legacy interrogator compatibility with advanced encryption standards.
An Identification Friend or Foe system comprises encrypted transponder-interrogator pairs operating across L-band frequencies, with Mode 5 employing GPS-synchronized time-of-arrival validation to prevent spoofing. The system enables real-time combatant identification in contested electromagnetic environments where visual recognition fails. Active IFF technology leads installed base volumes due to NATO-mandated upgrade cycles, while Hybrid IFF architectures represent the fastest-expanding category as navies integrate passive spectral sensing for reduced emission signatures. Aircraft applications command the largest component spend because fighter and transport fleets require redundant transponder configurations with embedded antitamper modules.
The FAA mandates civil-military transponder interoperability under Mode S Extended Squitter protocols, while the DoD's AIMS certification program governs cryptographic waveform compliance for all NATO-aligned suppliers. ETSI standards in Europe and Japan's MIC radio equipment regulations create parallel certification pathways that fragment vendor qualification costs. Stakeholders must monitor pending software export control reclassifications that could restrict cross-border maintenance access for embedded cryptographic libraries.
Market Dynamics
Cryptographic modernization mandates across NATO-aligned defense ministries are forcing accelerated replacement of legacy transponder architectures, compressing procurement cycles from typical ten-year intervals to five-year refresh schedules.
Growth Catalysts
- Mode 5 Certification Mandates:The FAA's AIMS certification program requires all military aircraft operating in controlled airspace to deploy GPS-synchronized transponders by 2025, creating immediate retrofit demand across fighter and transport fleets.
- Passive Spectral Sensing Integration:Naval combatant programs in France, the United Kingdom, and Italy are embedding hybrid IFF architectures that combine active interrogation with reduced electromagnetic signatures for contested littoral operations.
- Semiconductor Supply Security:Defense ministries in Germany and the United States are prioritizing domestic foundry qualification for gallium nitride power amplifiers used in next-generation interrogator transmitters.
Market Restraints
- Export Control Fragmentation:Pending software export reclassifications under the Wassenaar Arrangement threaten to restrict cross-border maintenance access for embedded cryptographic libraries in transponder firmware.
- Dual-Use Component Scarcity:Specialized radiation-hardened FPGAs required for space-qualified IFF systems concentrate fabrication capacity at a single qualified foundry in the United States.
- Certification Cost Burden:Parallel ETSI and AIMS certification pathways force European vendors to duplicate electromagnetic compatibility testing, adding eighteen to twenty-four months to qualification timelines.
Strategic Opportunities
- Unmanned Platform Integration:NATO's Next Generation Rotorcraft Capability program in Italy and Germany specifies software-defined IFF modules for optionally piloted helicopters, opening modular procurement channels.
- Civil-Military Convergence:Japan's MIC radio equipment regulations now recognize Mode S Extended Squitter interoperability as equivalent to military Mode 5 validation, reducing dual-certification requirements for commercial derivative aircraft.
- Blockchain-Enabled Logistics:The United States Department of Defense is piloting distributed ledger verification for transponder key distribution, creating demand for cybersecurity-integrated supply chain management platforms.
Industry Challenges
- Cryptographic Engineering Talent Gap:Qualified firmware architects capable of implementing NSA Suite B algorithms in resource-constrained transponder microcontrollers command premium compensation, constraining vendor scaling.
- Legacy Interoperability Burden:Mode 4 and Mode C transponders remain operational across reserve fleets in Spain, Portugal, and Greece, forcing manufacturers to maintain three-generation backward compatibility in interrogator waveform libraries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IFF System Market |
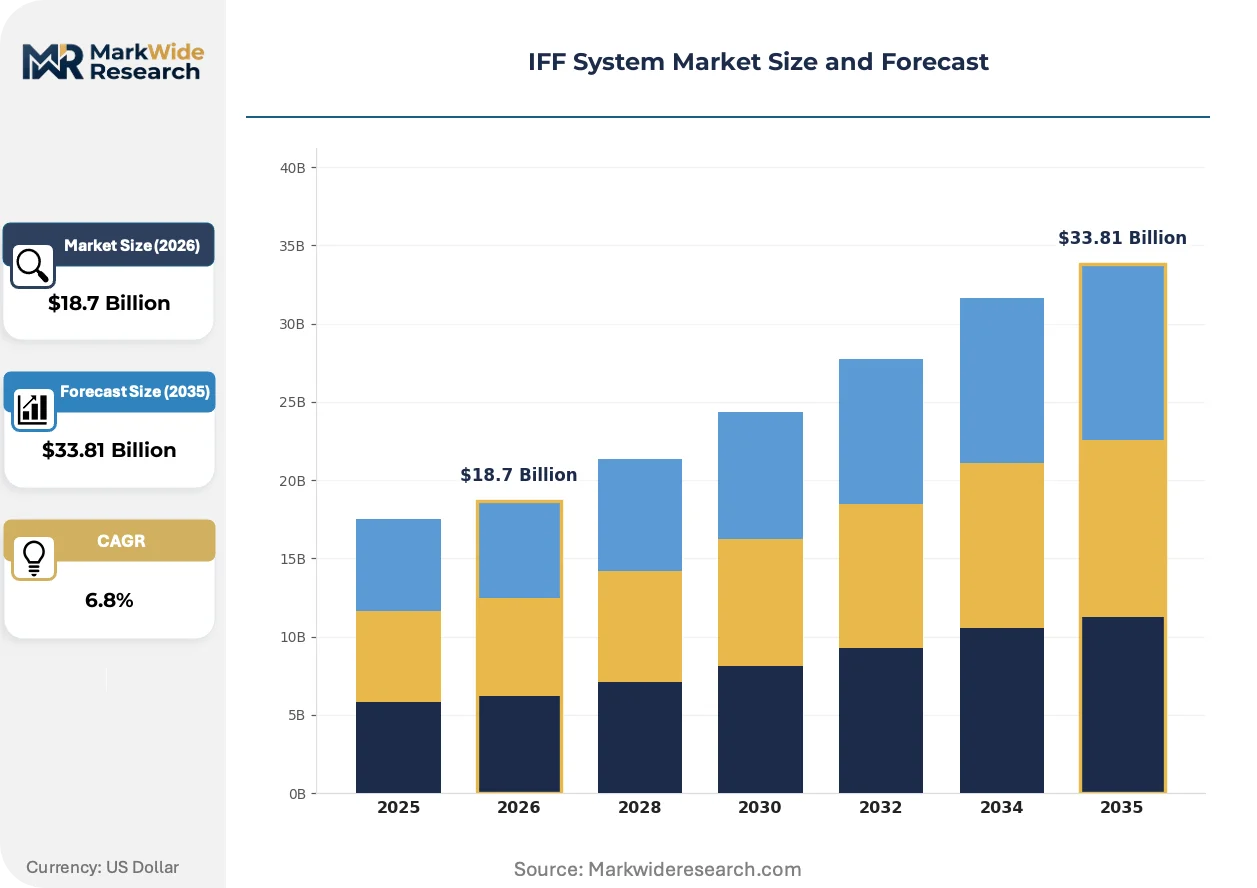
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Active IFF, Passive IFF, Advanced IFF, Hybrid IFF End User: Military, Aerospace, Defense Contractors, Government Agencies Application: Aircraft, Naval Vessels, Ground Vehicles, UAVs Component: Transponders, Sensors, Software, Control Systems |
| Companies Covered | RTX Corporation, Thales Group, BAE Systems, Northrop Grumman, Leonardo S.p.A., L3Harris Technologies, Lockheed Martin, Saab Group, Elbit Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IFF System Market Shifts & Advancements
Waveform agility and software-defined architectures are displacing fixed-function hardware across interrogator and transponder designs, enabling cryptographic updates without physical module replacement.
Hybrid IFF architectures merge active L-band interrogation with passive radio frequency sensing, reducing electromagnetic emissions during covert naval operations. The French Navy's FTI frigate program and the United Kingdom's Type 26 program are expanding into this dual-mode configuration for contested Indo-Pacific deployments. This convergence is compressing supplier margins as single-function vendors must acquire spectral analysis capabilities.
The European Union's Cyber Resilience Act imposes mandatory security update obligations on radio equipment manufacturers, extending vendor liability periods from typical five-year warranties to full fifteen-year service lives. Transponder suppliers serving NATO markets must now embed over-the-air cryptographic refresh capabilities. Aircraft integrators in Italy and Germany are selecting vendors based on demonstrated secure firmware pipeline maturity rather than hardware specifications alone.
Defense procurement offices are consolidating transponder purchases under multi-year enterprise agreements, displacing platform-specific competitive tenders. The United States Navy's PMA-209 program office and the United Kingdom's DE&S are negotiating five-year sole-source arrangements with qualified Mode 5 vendors. This concentration is visible most acutely in fighter aircraft retrofit programs, where platform primes now subcontract IFF integration to pre-approved transponder specialists rather than conducting open competitions.
IFF System Market Segmentation
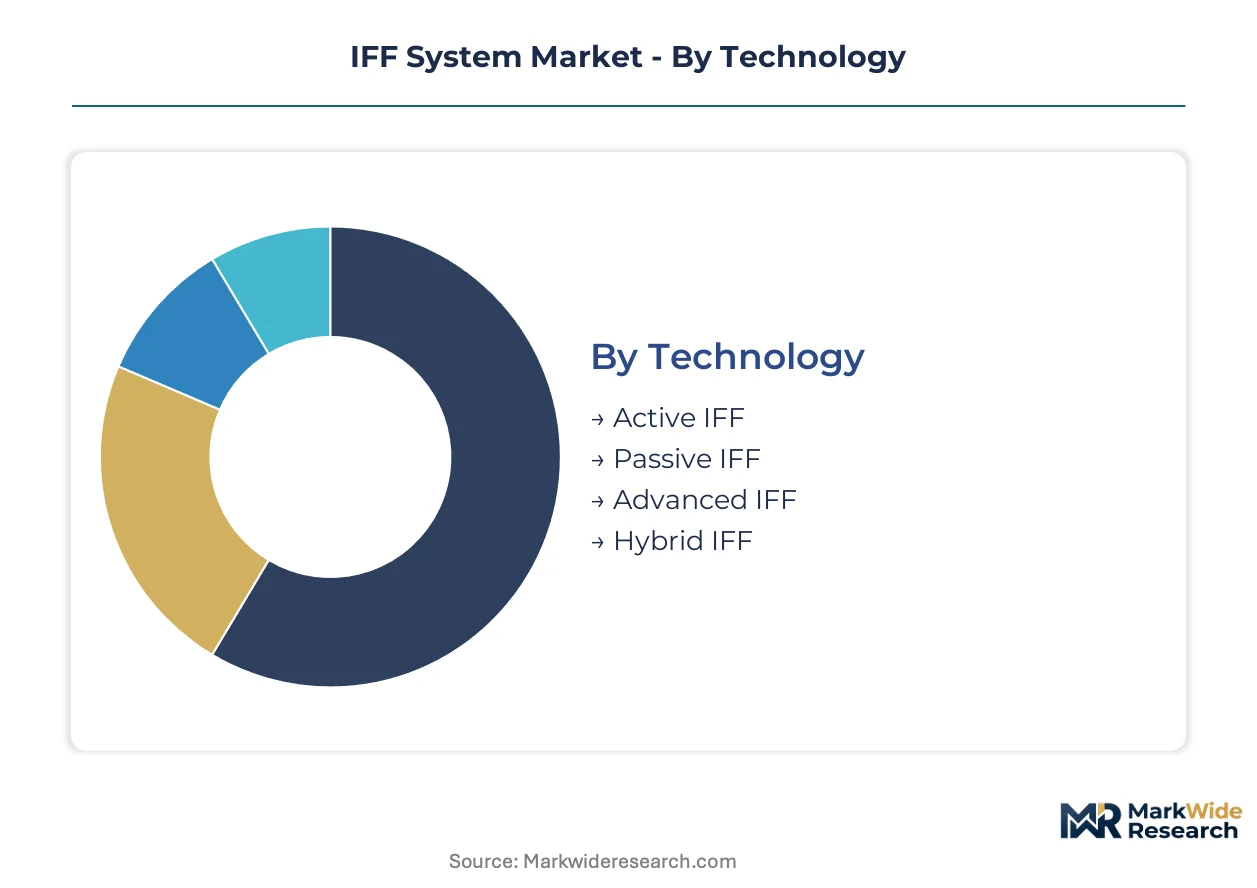
IFF system procurement patterns diverge sharply across technology maturity levels and operational domains, with defense ministries prioritizing cryptographic upgrade pathways over platform-agnostic specifications. Component sourcing strategies and certification requirements create distinct supplier ecosystems for each segment category.
Technology:
Transponder and interrogator fabrication capacity concentrates at foundries with AIMS certification, creating supply bottlenecks for advanced waveform architectures.
- Active IFF:L-band transponder-interrogator pairs with GPS-synchronized time-of-arrival validation form the NATO-mandated baseline for combatant identification. United States Department of Defense procurement accounts for dominant retrofit volumes as legacy Mode 4 systems face accelerated replacement schedules.
- Hybrid IFF:Dual-mode architectures merge active interrogation with passive spectral sensing to reduce electromagnetic signatures during naval operations. French and United Kingdom frigate programs are driving qualification demand for reduced-emission configurations in contested littoral environments.
- Passive IFF:Non-emitting identification relies on radar cross-section analysis and signature databases for covert detection scenarios.
- Advanced IFF:Software-defined radio architectures enable cryptographic waveform updates without hardware replacement.
Active IFF absorbs the bulk of installed capacity; Hybrid IFF is expanding most quickly.
End User:
Procurement authority fragmentation across defense ministries and civilian regulators creates divergent certification requirements for identical hardware configurations.
- Military:Fighter and transport fleets require redundant transponder configurations with embedded antitamper modules and NSA Suite B cryptographic compliance. NATO member states are consolidating Mode 5 upgrade contracts under multi-year enterprise agreements to reduce sole-source dependency.
- Defense Contractors:System integrators face compressed qualification timelines as platform primes subcontract IFF integration to pre-approved transponder specialists rather than conducting open competitions.
- Aerospace:Commercial derivative aircraft serving dual civil-military roles must satisfy both FAA Mode S Extended Squitter and military Mode 5 mandates.
- Government Agencies:Border patrol and coast guard units operate mixed fleets with fragmented interoperability standards.
Military end users command dominant procurement volumes; Defense Contractors are gaining share fastest as platform integration responsibilities shift downstream.
Application:
Platform-specific environmental stress requirements—altitude, salt corrosion, vibration spectra—force component customization that fragments supplier economies of scale.
- Aircraft:Fighter and transport platforms demand redundant transponder configurations with embedded antitamper modules certified for high-g maneuvering environments. United States Navy and Air Force retrofit programs concentrate component spend in this category.
- Naval Vessels:Surface combatants require hybrid architectures combining active L-band interrogation with passive radio frequency sensing for reduced electromagnetic emissions during covert operations.
- Ground Vehicles:Armored formations prioritize low-probability-of-intercept waveforms for identification in contested electromagnetic environments.
- UAVs:Optionally piloted platforms specify software-defined IFF modules with minimal size, weight, and power constraints.
Aircraft applications absorb the bulk of component spend; Naval Vessels are climbing the fastest as hybrid architectures proliferate.
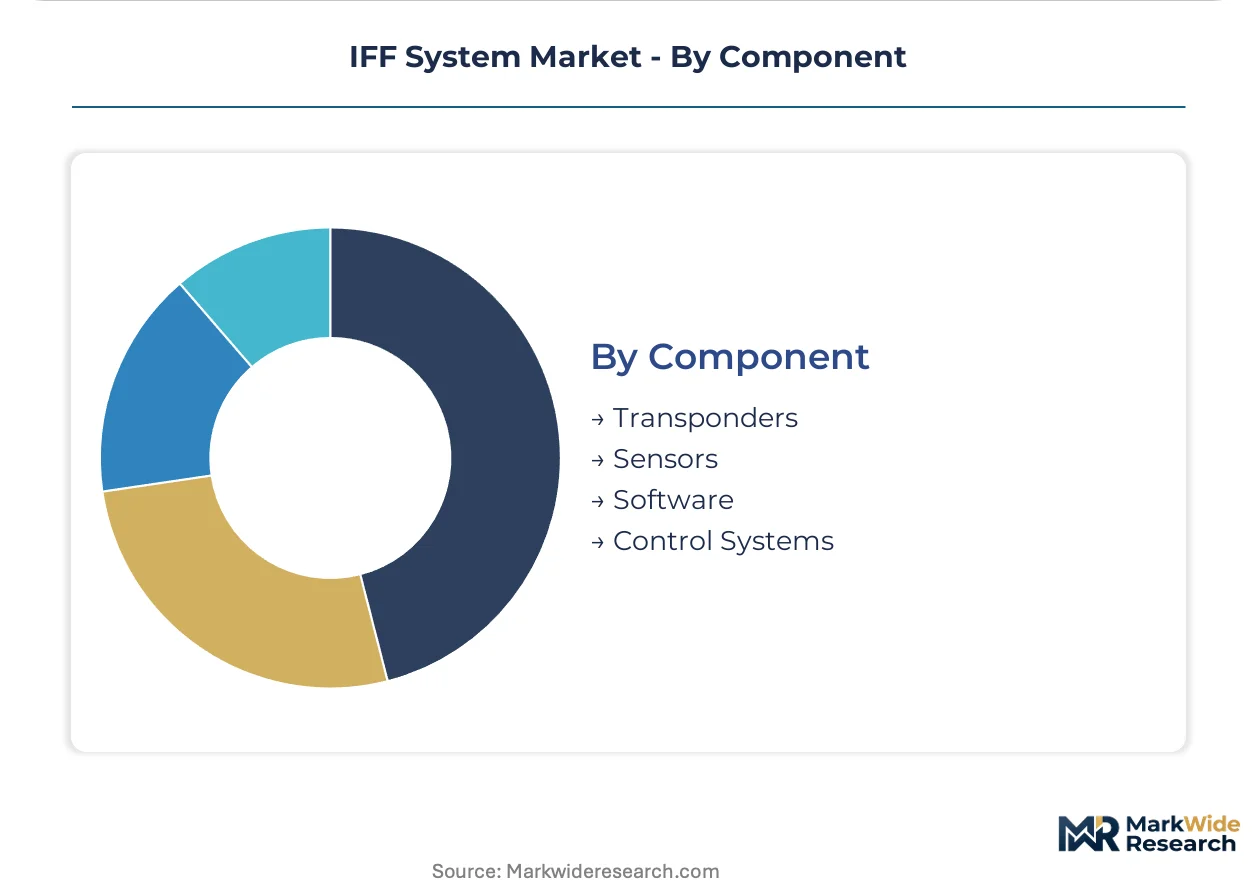
Component:
Semiconductor supply security initiatives in Germany and the United States are prioritizing domestic foundry qualification for gallium nitride power amplifiers, reshaping sourcing geography for interrogator transmitters.
- Transponders:Encrypted responder units operating across L-band frequencies with GPS-synchronized validation prevent spoofing in contested electromagnetic environments. Gallium nitride power amplifier sourcing concentrates at qualified foundries with defense ministry security clearances.
- Software:Firmware implementing cryptographic waveforms faces pending export control reclassifications under the Wassenaar Arrangement that threaten cross-border maintenance access.
- Sensors:Passive spectral detection modules enable reduced-emission identification for naval covert operations.
- Control Systems:Interrogator management units coordinate waveform libraries across multi-generation backward compatibility requirements.
Transponders absorb the bulk of qualified supplier capacity; Software is gaining share fastest as over-the-air cryptographic refresh capabilities become mandatory under the European Union's Cyber Resilience Act.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gallium arsenide foundry capacity in the United States anchors transponder semiconductor supply, while European cryptographic certification programs and Asian naval modernization drive procurement geography across the IFF system market.
United States
The Department of Defense compresses procurement cycles from ten-year to five-year refresh schedules for Mode 5 transponder upgrades. FAA mandates under the AIMS certification program require GPS-synchronized military aircraft transponders for controlled airspace access by 2025. RTX Corporation's captive semiconductor fabrication in Massachusetts secures domestic gallium nitride power amplifier supply for interrogator transmitters.
United Kingdom
The Ministry of Defence consolidates transponder purchases under multi-year enterprise agreements through Defence Equipment and Support. DE&S negotiates five-year sole-source arrangements with qualified Mode 5 vendors for fighter retrofit programs. BAE Systems' software-defined radio architectures in Lancashire merge legacy interrogator compatibility with advanced encryption standards for Royal Air Force and Royal Navy platforms.
France
The Direction Générale de l'Armement anchors European Mode 5 certification through national military procurement frameworks for naval and air force fleets. Thales Group leverages French national security clearances to supply transponder-interrogator pairs for the FTI frigate program. The Provence-Alpes-Côte d'Azur region concentrates hybrid IFF development combining active L-band interrogation with passive spectral sensing for contested littoral operations.
Germany
The Federal Ministry of Defence prioritizes domestic foundry qualification for gallium nitride components under semiconductor supply security initiatives. NATO's Next Generation Rotorcraft Capability program with Italy specifies software-defined IFF modules for optionally piloted helicopters. Bavarian defense contractors face compressed qualification timelines as platform primes subcontract integration to pre-approved transponder specialists.
Japan
The Ministry of Internal Affairs and Communications recognizes Mode S Extended Squitter interoperability as equivalent to military Mode 5 validation for commercial derivative aircraft. Maritime Self-Defense Force frigate programs drive demand for reduced-emission hybrid architectures in contested Indo-Pacific deployments. Tokyo-based system integrators navigate parallel ETSI and AIMS certification pathways that fragment vendor qualification costs for dual-use exports.
IFF System Market Competitive Landscape
Multi-year sole-source contracting dominates the current landscape as defense procurement offices consolidate transponder purchases under enterprise agreements. The vendor base concentrates around qualified Mode 5 suppliers with AIMS certification and captive semiconductor fabrication. Three archetypes define competitive positioning: integrated defense primes with captive foundry capacity, European national champions leveraging security-cleared supply chains, and software-defined radio specialists. Geographic expansion through national procurement frameworks and cryptographic waveform licensing represent the dominant competitive moves.
Among United States-based integrated primes, RTX Corporation and Northrop Grumman exemplify the foundry-anchored archetype with domestic gallium nitride supply chain control. Thales Group occupies a position within the European national champion tier, leveraging French and British security clearances for transponder certification programs. These three entities represent the consolidated supplier base that defense ministries increasingly depend upon as platform primes subcontract IFF integration downstream.
| Leading Market Players |
|---|
| RTX Corporation |
| Thales Group |
| BAE Systems |
| Northrop Grumman |
| Leonardo S.p.A. |
| L3Harris Technologies |
| Lockheed Martin |
| Saab Group |
| Elbit Systems |
| Others |
Supply & Pricing Matrix
Captive semiconductor fabrication anchors both supply security and pricing power for qualified Mode 5 transponder vendors. RTX Corporation's in-house gallium nitride foundry in Massachusetts insulates interrogator transmitter costs from foreign foundry volatility while enabling premium positioning against fabless competitors.
Pricing Analysis
Warranty bundling separates enterprise-grade transponder contracts from unbundled component sales to smaller integrators. Three-tier pricing structure across AIMS-certified premium, national-standard mid-tier, and legacy-compatible economy levels reflects certification grade and cryptographic refresh obligations. Cost compression in the mid-tier intensifies as European vendors absorb duplicated ETSI and AIMS electromagnetic compatibility testing. Defense contractors serving platform primes exhibit lowest price sensitivity due to sole-source pass-through arrangements, while border patrol agencies in mixed-fleet environments drive hardest bargain negotiations.
Supply Chain Analysis
Reverse logistics for cryptographic module refurbishment flows through qualified depots in the United States, France, and the United Kingdom. Gallium nitride power amplifiers and radiation-hardened FPGAs draw from foundries concentrated in the United States and Taiwan. Single-source vulnerability concentrates at one qualified radiation-hardened FPGA fabricator for space-qualified systems. Distribution runs through defense ministry enterprise procurement frameworks rather than open commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from cryptographic certification mandates is forcing sub-scale firmware vendors toward acquisition or exit. Multi-year sole-source contracting by NATO procurement offices leaves limited oxygen for undifferentiated competitors.
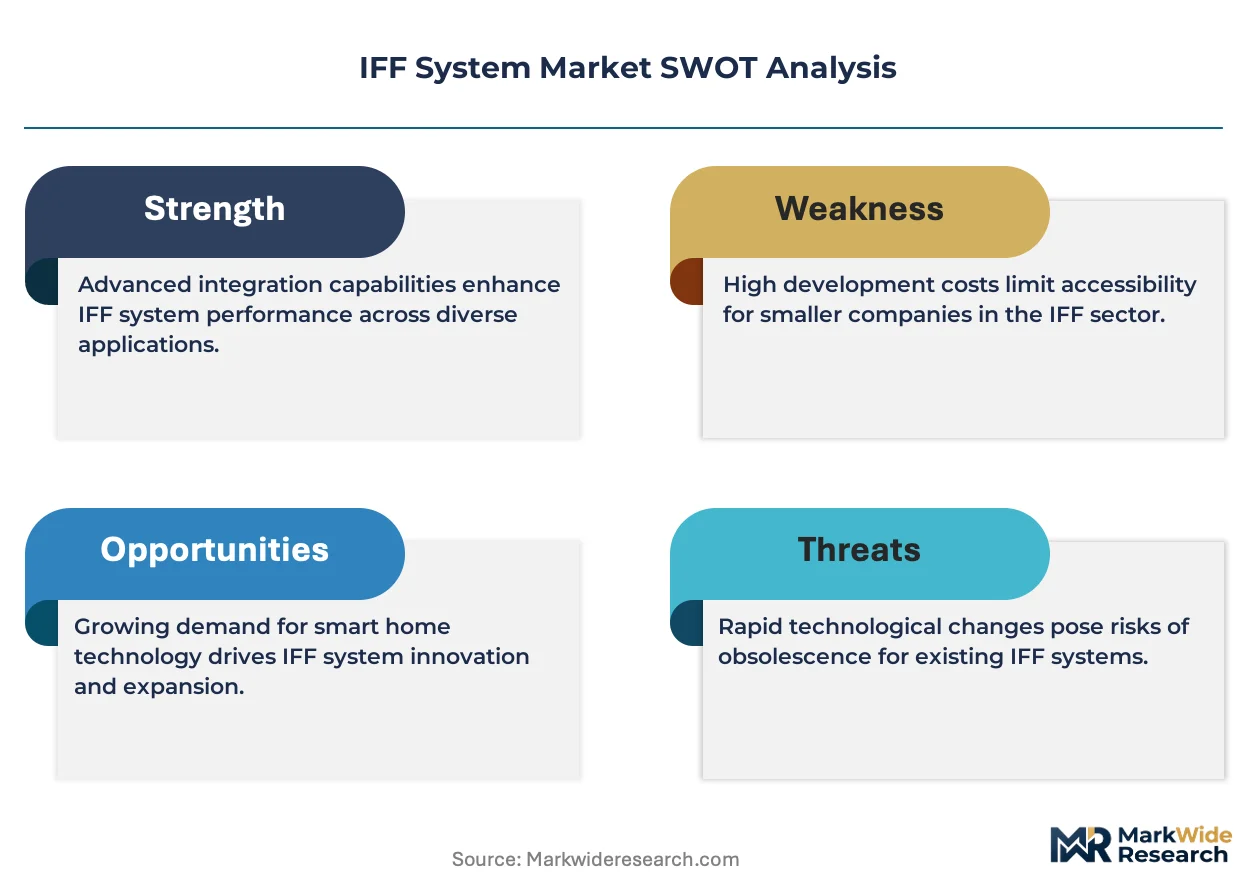
For Market Incumbents: Cement AIMS certification moats through accelerated NSA Suite B algorithm implementation in resource-constrained transponder microcontrollers. Acquire spectral analysis capabilities to defend against hybrid IFF margin compression from naval combatant programs. Captive gallium nitride foundry capacity represents the priority defensive lever against fabless entrants.
For New Entrants and Emerging Players: Platform prime subcontractors present the most penetrable channel for bypassing direct defense ministry qualification barriers. Target UAV software-defined IFF modules where minimal size-weight-power constraints favor modular over integrated architectures. Pursue civil-military dual-certification pathways under Japan's MIC equivalency recognition to reduce entry cost burden.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated defense primes seeking cryptographic waveform libraries. Long-term viability favors vendors with demonstrated secure firmware pipeline maturity under EU Cyber Resilience Act mandates. Watch for Wassenaar Arrangement software export reclassifications as inflection signal for maintenance-access valuation discounts.
| Strategic Initiative | Industry Significance |
|---|---|
| AIMS Certification Acceleration | Shortens qualification timelines for NATO-aligned defense procurement frameworks. |
| Captive Gallium Nitride Foundry Investment | Secures domestic interrogator transmitter supply against foreign semiconductor chokepoints. |
| Spectral Analysis Capability Acquisition | Enables hybrid IFF architectures for French and United Kingdom naval frigate programs. |
| Secure Firmware Pipeline Development | Satisfies EU Cyber Resilience Act mandatory update obligations across fifteen-year service lives. |
| Civil-Military Dual Certification Pursuit | Leverages Japan's MIC Mode S Extended Squitter equivalency to reduce duplicate testing costs. |
Research Methodology
Document review covered defense ministry procurement disclosures, FAA AIMS certification registers, and ETSI electromagnetic compatibility filings, complemented by interviews with platform integration engineers, cryptographic firmware architects, and defense procurement officers. Secondary validation drew from customs trade data for gallium nitride component flows, SEC filings from integrated defense primes, and NATO standardization office publications. Bottom-up transponder shipment estimates triangulated against top-down defense budget allocation analysis.
Historical procurement volume patterns cross-referenced against expert panel input on Mode 5 retrofit acceleration timelines. Segmentation modeling spanned technology tier, platform application, end-user authority, and regional regulatory cluster. CAGRs were derived from fitted growth curves across the projection horizon. Industry-specific inputs included cryptographic modernization mandate compliance schedules and gallium nitride foundry qualification status.
Caveats apply where Wassenaar Arrangement software export reclassifications or semiconductor supply security initiative expansions could materially shift the outlook. Forecasts reflect assumptions regarding NATO member state budget continuity and AIMS certification program stability. Practitioners should monitor pending EU Cyber Resilience Act implementation guidance and domestic foundry qualification announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ISR
Air Based C4ISR Market
ISR
North America C5ISR Market
ISR
Saudi Arabia C4ISR Market
ISR
Active Phased Array Radar (APAR) Market
ISR
Land Based C4ISR Market
ISR
Low Altitude Radar Market
ISR
Europe C5ISR Market
ISR
Asia-Pacific C4ISR Market
ISR
C5ISR Market
ISR
Airborne ISR Market
ISR
Infrared Suppression Systems Market
ISR
Synthetic Aperture Radar (SAR) Market
ISR
United States C4ISR Market
ISR
C6ISR Market
ISR
C4ISR Market
ISR
Eastern Europe C4ISR Market