
 Japan C4ISR Market | 2026-2036
Japan C4ISR Market Size, Share, and Industry Trends Forecast 2026-2036
Japan C4ISR Market Foresight
Sensor-to-shooter latency reduction is narrowing the gap between intelligence collection and kinetic response in Japanese defense architecture. Toshiba Corporation leverages its legacy radar and satellite communications expertise to anchor naval C4ISR programs. Mitsubishi Heavy Industries sustains platform-level integration dominance across maritime patrol and fighter systems. NEC Corporation differentiates through cybersecurity-hardened command networks that protect against electromagnetic and digital intrusion.
C4ISR denotes the integrated military framework combining command, control, communications, computers, intelligence, surveillance, and reconnaissance into interoperable battle management networks operating across radio frequency, satellite, and optical data links with sub-second latency requirements for time-critical targeting. The architecture serves to compress decision cycles and enable joint-force coordination across air, maritime, ground, and space domains. Intelligence Systems and Surveillance Systems command the largest solution allocations due to Japan's maritime perimeter monitoring priorities and island defense requirements. Cybersecurity Solutions within the technology dimension is gaining structural weight as electromagnetic spectrum contestation intensifies in the Indo-Pacific.
METI sets industrial policy direction for defense technology supply chain security, while Japan's Ministry of Defense procurement guidelines mandate interoperability with U.S. forces through standardized data link protocols. JIS standards and PMDA-equivalent defense certification processes shape product qualification timelines and vendor eligibility for classified programs. Stakeholders must weigh sovereign capability investment against alliance integration imperatives as Tokyo revises its National Security Strategy implementation.
Market Dynamics
Japan's C4ISR architecture is undergoing fundamental restructuring as METI mandates domestic semiconductor resilience for mission-critical defense electronics, forcing contractors to reconfigure supply chains away from legacy dependencies while maintaining interoperability with U.S. joint-force networks.
Growth Catalysts
- Island Defense Requirements:Japan's southwestern island chain monitoring needs are accelerating procurement of integrated maritime surveillance systems with real-time data fusion capabilities.
- METI's Semiconductor Security Framework:Industrial policy incentives are channeling investment into domestic fabrication of radiation-hardened chips for space-based C4ISR assets.
- Electromagnetic Spectrum Contestation:Indo-Pacific rivalries are driving demand for frequency-agile communications and electronic warfare-hardened command networks.
Market Restraints
- Specialized Compound Semiconductor Costs:Gallium nitride and silicon carbide substrate prices for high-power radar applications remain volatile due to limited qualified foundry capacity.
- Single-Source Dependencies:Precision timing modules and certain cryptographic processors concentrate among a narrow vendor base in allied nations.
- Legacy Platform Integration Friction:JIS certification timelines for retrofitting existing maritime patrol aircraft with modern data links extend qualification cycles.
Strategic Opportunities
- Space Domain Awareness:Japan's expanding satellite constellation creates demand for ground-based command infrastructure with cross-domain tracking capabilities.
- Cyber-Physical Convergence:Integration of quantum-resistant encryption with existing fiber networks offers upgrade pathways for critical command nodes.
- Kyushu Aerospace Cluster Development:Fukuoka and Saga prefectures are emerging as alternative manufacturing locations to reduce Tokyo-Kanagawa concentration risk.
Industry Challenges
- Cleared Personnel Scarcity:Security-cleared systems engineers with both defense domain knowledge and commercial semiconductor experience command premium compensation.
- Dual-Use Classification Complexity:Export control determinations under Japan's Foreign Exchange and Foreign Trade Act create licensing uncertainty for subsystem suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan C4ISR Market |
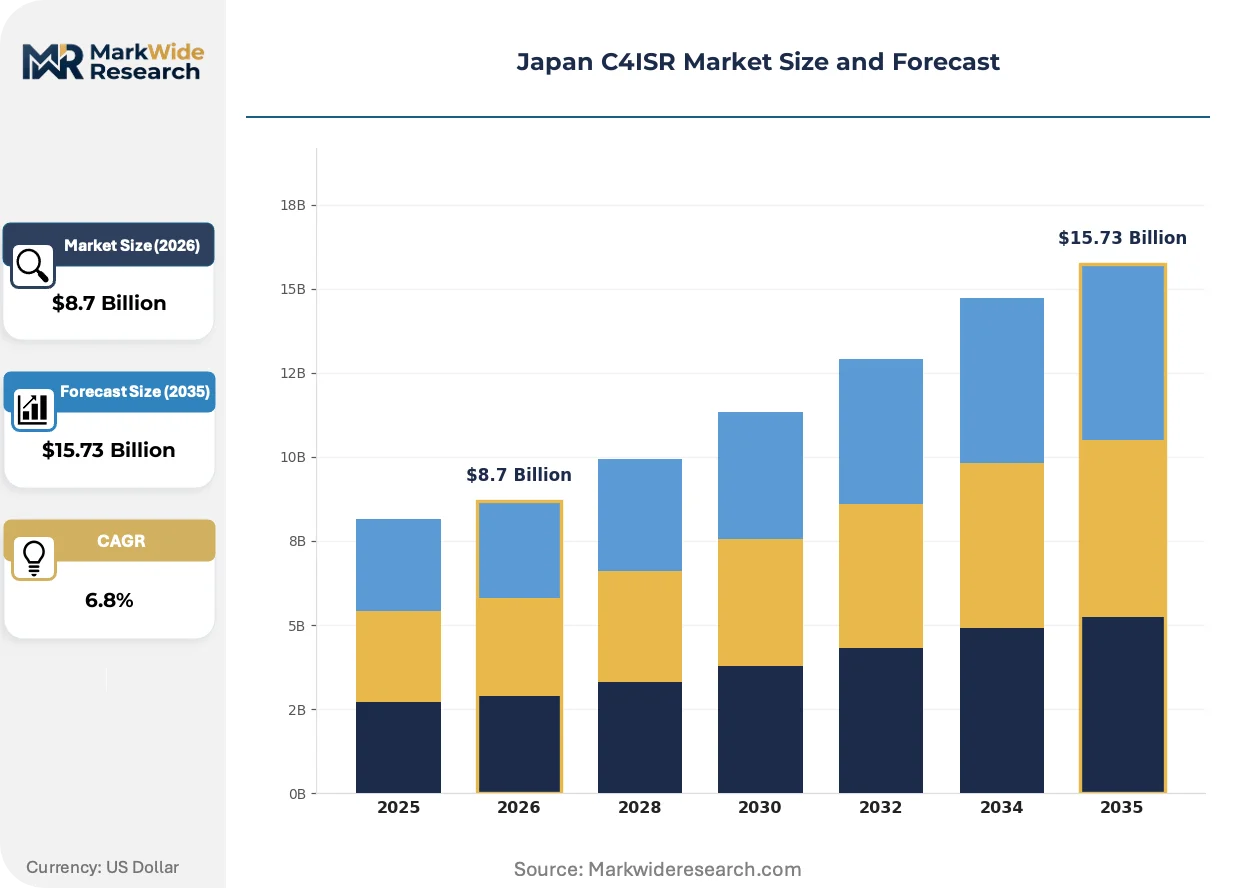
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Intelligence Systems, Surveillance Systems, Communication Networks, Command Systems Technology: Satellite Communication, Data Link, Wireless Networks, Cybersecurity Solutions End User: Defense Forces, Government Agencies, Research Institutions, Private Sector Service Type: Managed Services, Consulting Services, Training Services, Support Services |
| Companies Covered | Toshiba Corporation, Kawasaki Heavy Industries, Mitsubishi Heavy Industries, Lockheed Martin Corporation, Hitachi Ltd, NEC Corporation, IHI Corporation, Northrop Grumman Corporation, Fujitsu Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan C4ISR Market Shifts & Advancements
Artificial intelligence inference at the network edge is compressing decision cycles across Japanese defense architecture, while sovereign capability imperatives are reshaping how contractors source mission-critical components.
Multi-spectral sensor fusion is hybridizing electro-optical, synthetic aperture radar, and signals intelligence inputs into unified targeting tracks. The Japan Maritime Self-Defense Force is fielding these capabilities on next-generation destroyers with compressed integration timelines. This convergence is hybridizing traditional platform-centric procurement into system-of-systems acquisitions that prioritize interoperability over individual unit specifications.
METI's Critical Supply Chain Resilience Program is mandating domestic buffer stocks of advanced packaging substrates for defense-qualified semiconductors. Contractors must now qualify secondary Japanese foundries for radiation-tolerant designs previously sole-sourced overseas. Defense electronics divisions are responding by accelerating JIS certification of alternative substrate materials to meet procurement guidelines.
Self-Defense Forces buyers are consolidating vendor relationships around prime contractors capable of delivering integrated battle management solutions rather than discrete subsystems. Tier-two suppliers face pressure to embed within larger platform teams or exit defense-qualified production entirely. This concentration is most visible in Kanagawa's aerospace corridor, where Mitsubishi Heavy Industries has absorbed multiple specialized sensor houses into captive engineering divisions.
Japan C4ISR Market Segmentation
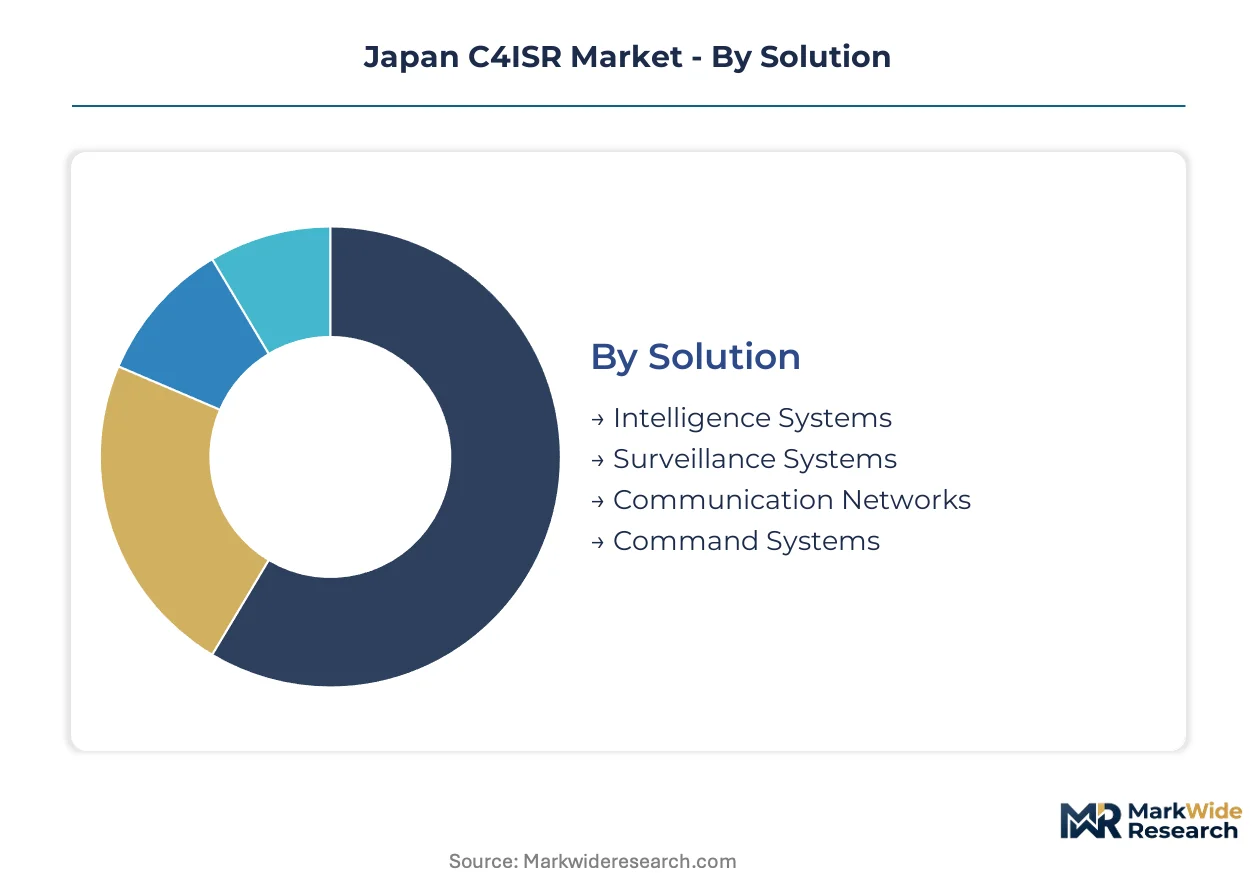
Japan's C4ISR procurement patterns reveal distinct technology maturity curves across solution categories, with defense buyers prioritizing integrated system-of-systems architectures over discrete component purchases. Segmentation clarity enables contractors to align qualification investments with actual budget allocation priorities.
Solution:
Mature battlefield management platforms coexist with emerging cross-domain fusion architectures as the Japan Self-Defense Forces restructure procurement around joint-force interoperability mandates.
- Intelligence Systems:Multi-source data fusion platforms integrating signals intelligence, imagery analysis, and open-source monitoring into unified operational pictures. Maritime patrol aircraft and ground-based analysis centers in Tokyo's defense corridor drive procurement concentration, with METI pushing domestic processing chip qualification to reduce foreign dependency.
- Surveillance Systems:Electro-optical and radar-based perimeter monitoring assets spanning airborne, maritime, and space-based sensor networks. Southwestern island chain defense requirements accelerate demand for persistent wide-area coverage with automated anomaly detection capabilities.
- Communication Networks:Frequency-agile tactical data links connecting dispersed platforms across contested electromagnetic environments.
- Command Systems:Decision-support software layers enabling compressed sensor-to-shooter timelines for time-critical targeting scenarios.
Surveillance Systems retains volume leadership; Intelligence Systems holds the steepest expansion curve.
Technology:
Cost tier stratification separates radiation-hardened space-qualified components from commercial-grade terrestrial alternatives, with defense procurement guidelines mandating JIS certification for mission-critical applications.
- Satellite Communication:X-band and Ka-band terminals for beyond-line-of-sight connectivity across Japan's expansive maritime territory. Space domain awareness investments are expanding ground station networks in Kyushu and Hokkaido to support growing constellation operations.
- Cybersecurity Solutions:Quantum-resistant encryption modules and electromagnetic intrusion detection systems protecting command networks. Electromagnetic spectrum contestation in the Indo-Pacific is accelerating procurement of frequency-hardened architectures with automated threat response protocols.
- Data Link:Standardized protocols ensuring interoperability with U.S. joint-force networks per bilateral alliance requirements.
- Wireless Networks:Mesh architectures for tactical formations operating in GPS-denied environments.
Satellite Communication commands premium pricing tiers; Cybersecurity Solutions is gaining share fastest.
End User:
Customer type concentration reflects procurement authority structures, with platform-level acquisition budgets concentrating in uniformed services while research institutions access development funding through separate METI channels.
- Defense Forces:The Japan Self-Defense Forces dominate platform integration procurement, with Maritime and Air Self-Defense Forces driving maritime surveillance and fighter system investments respectively. Budget allocation priorities favor integrated battle management solutions over discrete subsystem purchases.
- Government Agencies:Cabinet Satellite Intelligence Center and coast guard organizations procure specialized monitoring capabilities outside military procurement frameworks.
- Research Institutions:JAXA and defense technology research centers access development funding for next-generation sensor and communication technologies.
- Private Sector:Critical infrastructure operators purchase hardened communication systems under government cybersecurity guidance.
Defense Forces retains absolute budget authority; Government Agencies show the steepest budget growth trajectory.
Service Type:
Application intensity varies by operational tempo, with frontline units requiring continuous managed support while acquisition programs demand concentrated consulting engagement during integration phases.
- Managed Services:Continuous network operations and maintenance contracts ensuring 24/7 command system availability. Maritime Self-Defense Force destroyer fleets and Air Self-Defense Force fighter wings concentrate demand for operational support services.
- Consulting Services:System architecture design and interoperability certification support for major procurement programs. Complex platform integration timelines extending JIS qualification cycles sustain demand for specialized engineering advisory.
- Training Services:Operator certification and maintenance technician instruction for fielded systems.
- Support Services:Spare parts logistics and depot-level repair for deployed hardware assets.
Managed Services captures recurring revenue concentration; Consulting Services exhibits the most volatile demand cyclicality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement authority concentrates in Japan's uniformed services and METI-directed industrial policy channels, with platform integration budgets flowing through distinct geographic corridors.
Kanto/Tokyo
Maritime patrol aircraft modernization and naval C4ISR programs drive procurement concentration in Tokyo's defense contractor corridor. METI's semiconductor security framework channels investment into domestic fabrication capabilities for radiation-hardened components. The capital region anchors systems integration activity, with prime contractors consolidating vendor relationships around integrated battle management solutions.
Kansai/Osaka
Industrial electronics manufacturing and precision component supply sustain C4ISR subsystem production in western Japan's manufacturing belt. PMDA-equivalent defense certification processes shape product qualification timelines for suppliers seeking entry into classified programs. Osaka-based engineering divisions specialize in cryptographic processor modules and secure communications hardware.
Kyushu
Space domain awareness investments expand ground station networks across Fukuoka and Saga prefectures to support growing satellite constellation operations. The aerospace cluster development initiative reduces Tokyo-Kanagawa concentration risk for mission-critical manufacturing. Local facilities qualify alternative substrate materials under METI's Critical Supply Chain Resilience Program.
Chubu/Nagoya
Aerospace platform integration and fighter system production sustain demand for command network hardware in central Japan's industrial corridor. JIS certification timelines for retrofitting existing aircraft with modern data links extend qualification cycles for regional suppliers. Nagoya-based engineering centers focus on electromagnetic-hardened architectures for contested spectrum environments.
Hokkaido
Northward-facing surveillance requirements and satellite ground station expansion drive infrastructure investment in Japan's northernmost prefecture. Maritime perimeter monitoring priorities accelerate deployment of persistent wide-area coverage systems with automated anomaly detection. Cold-weather testing facilities support qualification of tactical communications equipment for extreme environment operations.
Japan C4ISR Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Japan's C4ISR procurement landscape, with prime contractors absorbing specialized sensor houses into captive engineering divisions. The vendor base stratifies between platform-level integrators capable of delivering system-of-systems solutions and subsystem suppliers facing pressure to embed within larger teams. Three archetypes dominate: aerospace-industrial conglomerates with defense electronics divisions, specialized communications technology providers, and foreign defense contractors operating through alliance partnerships. Competitive moves concentrate on vendor relationship consolidation around integrated procurement and JIS certification acceleration for alternative domestic foundries.
Among Japan-based defense-industrial conglomerates, Toshiba Corporation, Mitsubishi Heavy Industries, and NEC Corporation occupy anchor positions across distinct technology vectors. Toshiba exemplifies the radar and satellite communications specialist archetype, while Mitsubishi Heavy Industries represents platform-level integration dominance. NEC Corporation sits within the cybersecurity-hardened command network tier, protecting against electromagnetic and digital intrusion. These three entities channel procurement relationships and shape vendor eligibility for classified programs through their consolidated buyer positions.
| Leading Market Players |
|---|
| Toshiba Corporation |
| Kawasaki Heavy Industries |
| Mitsubishi Heavy Industries |
| Lockheed Martin Corporation |
| Hitachi Ltd |
| NEC Corporation |
| IHI Corporation |
| Northrop Grumman Corporation |
| Fujitsu Limited |
| Others |
Supply & Pricing Matrix
Tokyo's defense contractor corridor concentrates platform integration capacity, translating upstream semiconductor scarcity into extended procurement timelines and elevated qualification premiums for radiation-hardened components. METI's domestic resilience mandates compound this dynamic by forcing secondary foundry qualification investments that propagate through subsystem pricing tiers.
Pricing Analysis
Cost-plus contracts with semiconductor price indexation dominate prime-tier procurement, insulating platform integrators from gallium nitride substrate volatility while passing compound semiconductor cost swings to government buyers. Three-tier pricing structure across radiation-hardened, industrial-grade, and commercial-off-the-shelf levels separates mission-critical space applications from terrestrial alternatives. Pricing pressure stems from JIS certification backlogs extending qualification cycles for alternative domestic foundries. System integrators exhibit lowest price sensitivity due to sole-source platform mandates, while tier-two subsystem suppliers face acute margin compression from consolidation-driven procurement consolidation.
Supply Chain Analysis
Compound semiconductor feedstock draws from Taiwan, the United States, and South Korea for gallium nitride and silicon carbide substrates essential to high-power radar applications. Raw material dependencies center on precision timing modules from Swiss manufacturers, cryptographic processors from allied nations, and advanced packaging substrates from South Korean suppliers. Single-source vulnerability concentrates in radiation-tolerant chip designs previously sole-sourced overseas before METI's reshoring push. Distribution runs through prime contractor captive engineering divisions rather than open component markets, with Mitsubishi Heavy Industries and Toshiba Corporation controlling channel access for classified programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Security-cleared systems engineers possessing both defense domain expertise and commercial semiconductor fabrication knowledge represent the critical bottleneck constraining Japan's C4ISR expansion. This scarcity gap widens as METI accelerates domestic foundry qualification timelines while legacy workforce retirement erodes specialized institutional knowledge.
For Market Incumbents: Harden supply chain resilience by accelerating JIS certification of Kyushu-based alternative foundries before geopolitical friction disrupts Taiwan-sourced substrate flows. Deepen backward integration into radiation-hardened packaging capabilities to capture margin currently leaking to South Korean suppliers. Consolidate vendor relationships around integrated battle management solutions to defend against emerging cybersecurity-specialist entrants poaching command network contracts. For New Entrants and Emerging Players: Quantum-resistant encryption modules for fiber backbone upgrades represent the most penetrable entry point, as electromagnetic spectrum contestation accelerates procurement of frequency-hardened architectures outside prime contractor captive divisions. Kyushu ground station infrastructure for space domain awareness offers geographic white space distant from Tokyo-Kanagawa concentration. Partner with JAXA research channels to bypass JIS qualification barriers through development funding pathways rather than direct platform procurement competition. For Investors and Strategic Acquirers: Long-term, this sits as a sovereign capability consolidation play because METI's semiconductor security framework guarantees sustained procurement preference for domestic-qualified suppliers regardless of cost premiums. Acquisition targets should emphasize cleared personnel density and existing JIS certification pipelines over current revenue scale. Monitor Kyushu aerospace cluster facility announcements as inflection indicators for geographic diversification momentum away from Tokyo-Kanagawa risk concentration.| Strategic Initiative | Industry Significance |
|---|---|
| JIS Certification Acceleration | Shortens qualification cycles for alternative domestic foundries under METI's Critical Supply Chain Resilience Program. |
| Quantum-Resistant Encryption Deployment | Protects command networks against electromagnetic intrusion in contested Indo-Pacific spectrum environments. |
| Kyushu Manufacturing Footprint Expansion | Reduces Tokyo-Kanagawa concentration risk for space-qualified component production. |
| Prime Contractor Vendor Consolidation | Absorbs specialized sensor houses into captive engineering divisions for integrated battle management delivery. |
| Space Domain Awareness Ground Station Buildout | Supports Japan's expanding satellite constellation with cross-domain tracking infrastructure in Fukuoka and Saga prefectures. |
Research Methodology
Operator-level perspectives from Japan Self-Defense Forces procurement officers, METI industrial policy directors, prime contractor program managers, and tier-two subsystem engineering leads anchored the qualitative base. Secondary validation drew from Japan Ministry of Defense budget submissions, METI Critical Supply Chain Resilience Program documentation, JIS certification registry data, and bilateral alliance interoperability guidelines. Bottom-up segment sizing across solution, technology, end user, and service type dimensions triangulated against top-down defense expenditure allocation analysis.
Scenario-bracketing around semiconductor reshoring velocity and electromagnetic spectrum contestation intensity framed the analytical approach across the projection horizon. Segmentation dimensions modeled include solution maturity tier, radiation-hardening certification level, platform integration depth, and regional manufacturing cluster concentration. CAGRs were derived from defense procurement pipeline visibility and METI industrial policy incentive trajectories, with specific weighting applied to space domain awareness investment acceleration and quantum-resistant encryption upgrade cycles.
Practitioners should monitor JIS certification backlog clearance rates and Kyushu facility qualification announcements for early signals of supply chain restructuring pace. Cross-checking against Japan Ministry of Defense budget execution reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ISR
Global Interferometric Synthetic Aperture Radar (Insar) Market
ISR
Saudi Arabia C4ISR Market
ISR
Air Based C4ISR Market
ISR
C6ISR Market
ISR
Infrared Suppression Systems Market
ISR
Intelligence Surveillance and Reconnaissance (ISR) Market
ISR
C5ISR Market
ISR
Australia C4ISR Market
ISR
Asia-Pacific C4ISR Market
ISR
United States C4ISR Market
ISR
Eastern Europe C4ISR Market
ISR
North America Airborne ISR Market
ISR
Naval ISR Market
ISR
Low Altitude Radar Market
ISR
NATO C4ISR Market
ISR
Europe C5ISR Market