
 Military UAV Sensor Market | 2026-2036
Military UAV Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Military UAV Sensor Market Foresight
AS9100D and MIL-STD-810H qualification cycles are redrawing competitive boundaries for military UAV sensor suppliers. Lockheed Martin leverages captive aerospace manufacturing to sustain end-to-end electro-optical payload production. RTX Corporation anchors its position through classified radar development programs with the US Department of Defense. Northrop Grumman Corporation dominates high-altitude long-endurance sensor integration for strategic reconnaissance platforms.
Military UAV sensors comprise purpose-built detection and measurement devices engineered to operate across spectral bands from ultraviolet through long-wave infrared, typically incorporating stabilized gimbal mounts with sub-arcsecond pointing accuracy and hardened electronics rated for electromagnetic interference environments. These systems enable real-time battlefield awareness, precision targeting, and signals intelligence collection in contested airspace. Electro-optical and infrared sensor categories command established procurement budgets from defense ministries, while synthetic aperture radar and multi-spectral technologies represent the fastest-expanding technology segments as operators demand all-weather, day-night operational capability. AI-driven processing architectures are emerging as the critical margin pool, where onboard edge computing reduces bandwidth requirements and accelerates target identification timelines.
The US Department of Defense, the European Defence Agency, and NATO standardization bodies govern interoperability, frequency allocation, and cross-border technology transfer for military UAV sensors. ITAR compliance in the United States and the EU Dual-Use Regulation create divergent certification pathways that fragment vendor market access. Stakeholders must monitor evolving sovereign payload requirements and alignment between national security classifications and alliance-wide interoperability standards.
Market Dynamics
Defense procurement offices are consolidating sensor purchases under platform-agnostic framework contracts, compressing vendor lists and privileging suppliers with dual-use civilian-military production lines.
Growth Catalysts
- Multi-domain operations doctrine:NATO's Joint All-Domain Command and Control framework mandates interoperable sensor data formats across air, land, and maritime unmanned platforms.
- Export control harmonization:The EU Dual-Use Regulation's 2021 recast creates streamlined licensing pathways for intra-alliance sensor transfers, reducing administrative friction for European defense integrators.
- Hyperspectral imaging maturation:Laboratory-grade spectral resolution is migrating to tactical payload form factors, opening vegetation stress detection and concealed target identification applications.
Market Restraints
- Gallium arsenide substrate scarcity:Foundry capacity for high-frequency radar components concentrates in East Asian supply chains, exposing lead time volatility for Western sensor manufacturers.
- ITAR classification drag:US International Traffic in Arms Regulations impose multi-month technical data review cycles, delaying foreign military sales of electro-optical systems with embedded software.
- Synthetic aperture radar resolution limits:Atmospheric moisture absorption at Ku-band frequencies degrades image quality in tropical operating environments, constraining all-weather mission profiles.
Strategic Opportunities
- Poland's defense modernization:The country's Technical Modernisation Plan 2021-2035 allocates substantial unmanned systems procurement, creating entry points for sensor vendors establishing regional maintenance hubs.
- AI-enabled sensor fusion:Convolutional neural networks trained on multi-spectral datasets are compressing target recognition timelines from minutes to seconds, differentiating next-generation payload offerings.
- Swarm architecture integration:Distributed aperture networks linking multiple UAV sensor nodes enable synthetic baseline interferometry, opening synthetic aperture radar applications previously reserved to manned platforms.
Industry Challenges
- Electromagnetic spectrum certification:MIL-STD-461G testing for conducted emissions and susceptibility requires specialized anechoic chamber access, creating bottlenecks for smaller payload developers.
- Embedded software vulnerability assessment:Department of Defense Cybersecurity Maturity Model Certification mandates are extending development timelines for sensor control architectures with network-connected processing units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military UAV Sensor Market |
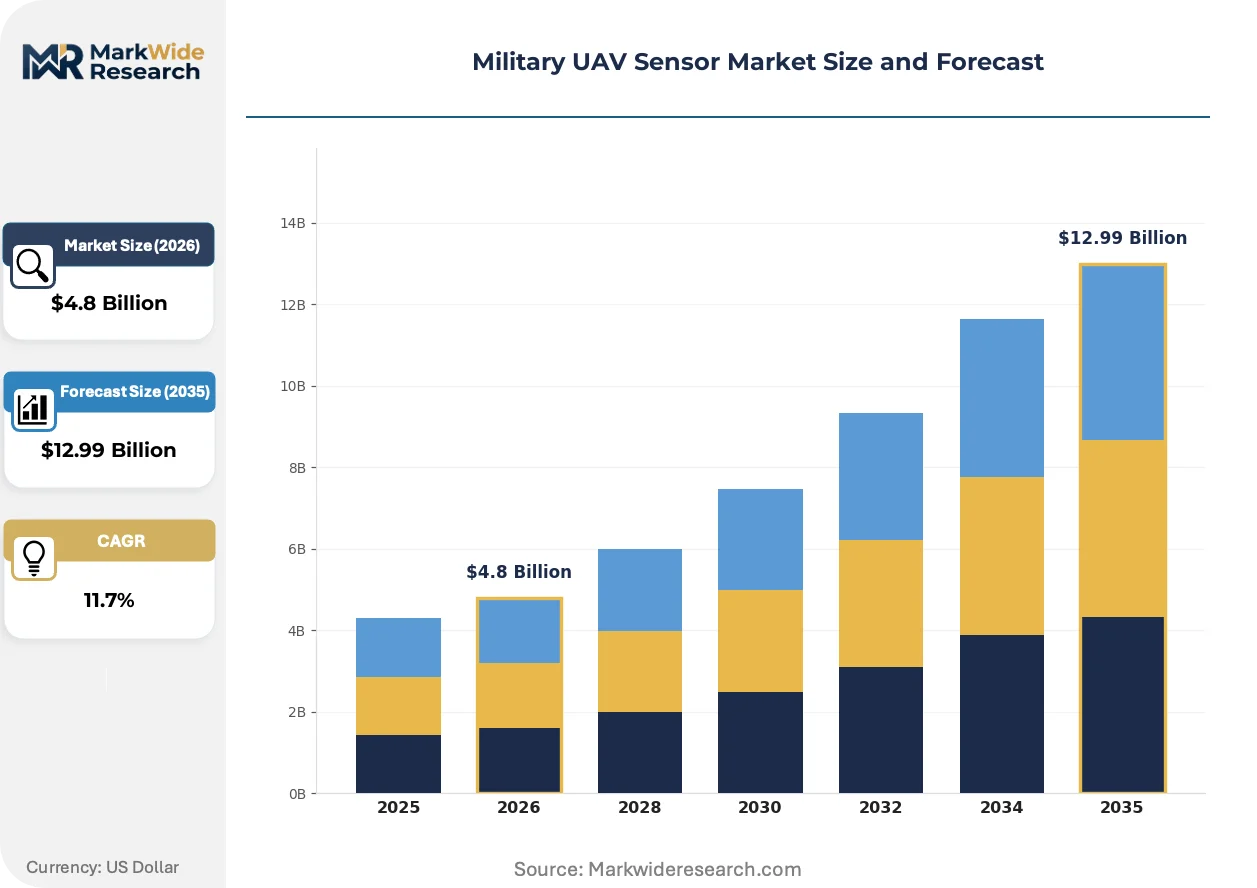
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electro-Optical Sensors, Infrared Sensors, Radar Sensors, Acoustic Sensors Technology: AI-Driven, Hybrid Systems, Multi-Spectral, Synthetic Aperture Radar Application: Surveillance, Reconnaissance, Target Acquisition, Intelligence Gathering End User: Defense Ministries, Private Contractors, Intelligence Agencies, Research Institutions |
| Companies Covered | Lockheed Martin Corporation, RTX Corporation, Northrop Grumman Corporation, BAE Systems plc, L3Harris Technologies, Teledyne FLIR LLC, Honeywell International Inc., Thales Group, General Atomics Aeronautical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military UAV Sensor Market Shifts & Advancements
Sensor processing architectures are migrating from centralized ground stations to edge-deployed compute nodes, compressing decision loops while exposing new attack surfaces requiring hardened cybersecurity protocols.
Quantum cascade laser technology is bifurcating the infrared detection landscape. These solid-state sources deliver tunable mid-wave infrared illumination without cryogenic cooling, enabling compact gimbal designs. Special operations commands are accelerating field trials of quantum cascade laser-equipped payloads for covert target designation. The technology is bifurcating procurement budgets away from legacy mercury cadmium telluride focal plane arrays toward room-temperature alternatives.
The EU AI Act's high-risk system classification is reshaping development roadmaps for autonomous target recognition algorithms. Manufacturers must maintain human-in-the-loop override capabilities and algorithmic transparency documentation. ISR platform integrators in Germany and France are restructuring software supply chains to segregate training data governance from inference engine deployment, adding compliance overhead but preserving market access.
Defense ministries are unbundling sensor hardware from platform prime contracts, creating direct procurement relationships with payload specialists. The UK Ministry of Defence's Team Complex Weapons framework exemplifies this disaggregation, permitting sensor vendors to compete independently of airframe manufacturers. This channel restructuring concentrates in Anglo-American procurement systems, where budgetary transparency rules facilitate line-item visibility, contrasting with continental European integrated platform contracting traditions.
Military UAV Sensor Market Segmentation
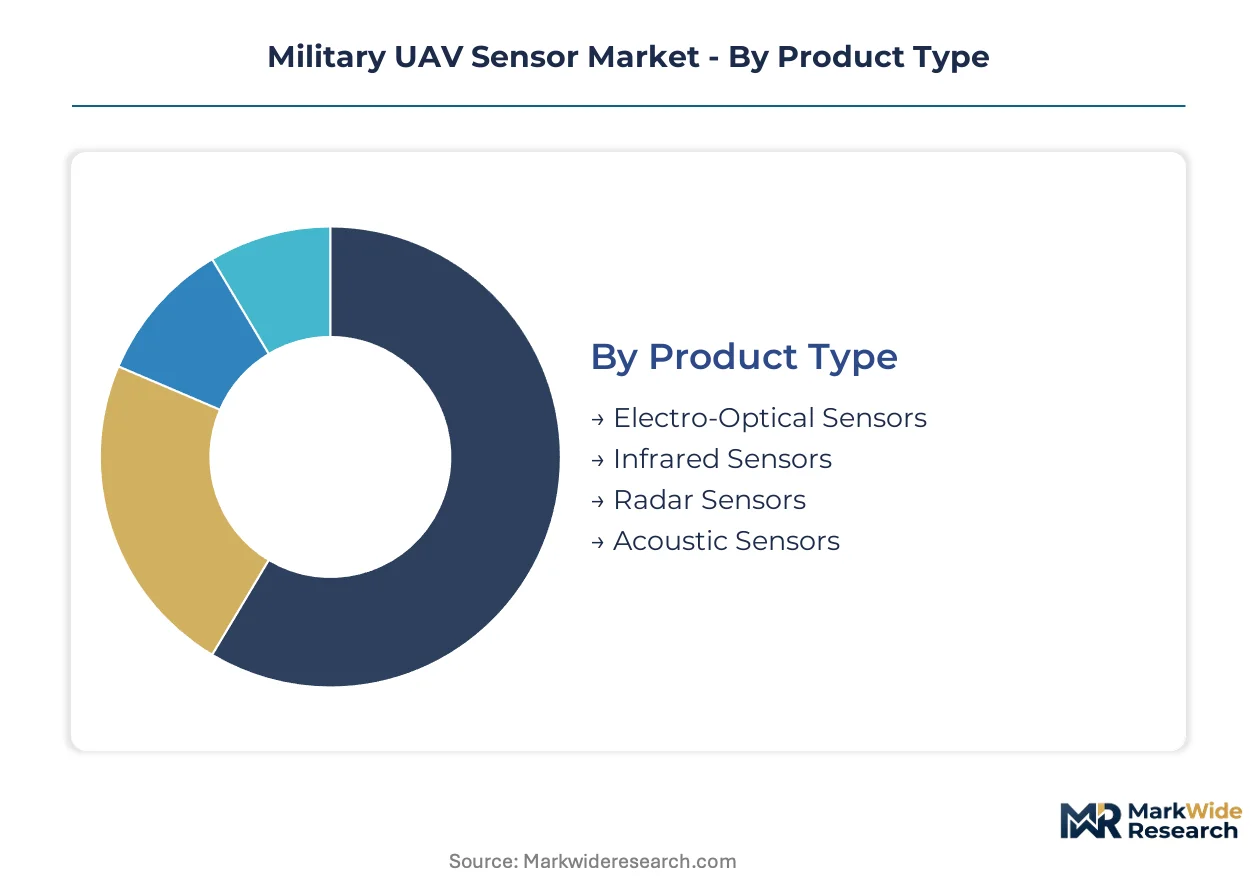
Military UAV sensor procurement channels fragment across sovereign defense budgets, classified development programs, and dual-use export frameworks. Understanding how technical specifications align with operational doctrines and regulatory clearance pathways determines vendor market access and pricing power.
Product Type:
ITAR classification tiers in the United States and EU Dual-Use Regulation export licenses create divergent commercial pathways for each sensor modality, with cryogenically-cooled infrared arrays facing stricter controls than uncooled electro-optical alternatives.
- Electro-Optical Sensors:Visible-spectrum imaging systems employing silicon-based focal plane arrays with stabilized gimbal mounts achieve sub-arcsecond pointing accuracy. Pentagon procurement for Group 4-5 tactical UAVs concentrates demand in the United States, though ITAR technical data review cycles extend foreign military sale timelines by four to six months.
- Infrared Sensors:Mercury cadmium telluride and indium antimonide detector arrays operating across short-wave, mid-wave, and long-wave spectral bands enable night operations and thermal signature detection. NATO member states' multi-domain operations doctrine is accelerating demand for cooled infrared payloads with integrated laser rangefinders.
- Radar Sensors:Active electronically scanned arrays for synthetic aperture and moving target indication modes.
- Acoustic Sensors:Directional microphone arrays and gunshot detection systems for low-altitude acoustic surveillance.
Electro-optical sensors handle the majority of throughput across tactical UAV fleets; infrared sensors are gaining share fastest as operators prioritize day-night operational parity.
Technology:
Development cost structures bifurcate sharply between software-defined processing architectures and hardware-intensive radio frequency components, with AI-driven systems attracting venture-backed defense technology entrants while radar development remains captive to prime contractor laboratories.
- AI-Driven:Edge-deployed convolutional neural networks for real-time target classification and anomaly detection. The EU AI Act's high-risk system classification is mandating human-in-the-loop override capabilities and algorithmic transparency documentation for German and French integrators, adding compliance overhead but preserving European market access.
- Hybrid Systems:Architectures combining electro-optical, infrared, and radar modalities with centralized sensor fusion processors. Poland's Technical Modernisation Plan is driving procurement of hybrid payloads for its Gryf and Orka unmanned programs.
- Multi-Spectral:Simultaneous imaging across discrete spectral bands for vegetation analysis and concealed target detection.
- Synthetic Aperture Radar:Side-looking radar systems generating high-resolution imagery independent of weather or illumination conditions.
Hybrid systems dominate current procurement volumes; AI-driven architectures show the steepest expansion trajectory as defense ministries prioritize reduced bandwidth requirements and accelerated decision timelines.
Application:
Mission profiles dictate sensor payload configuration, with persistent surveillance platforms prioritizing wide-area electro-optical coverage while time-sensitive targeting missions demand multi-spectral precision.
- Surveillance:Wide-area motion imagery and pattern-of-life analysis for border monitoring and force protection. United States Customs and Border Protection operates the largest fleet of surveillance-optimized Predator B variants along the southwest border.
- Reconnaissance:Deep-penetration missions requiring low-observable signatures and beyond-line-of-sight datalinks. High-altitude long-endurance platforms with synthetic aperture radar dominate strategic reconnaissance budgets.
- Target Acquisition:Laser designation and coordinate generation for precision strike missions.
- Intelligence Gathering:Signals intelligence and communications intercept payloads for electronic warfare support.
Surveillance missions absorb the largest share of flight hours; target acquisition applications are climbing fastest as close air support doctrines integrate unmanned forward air controllers.
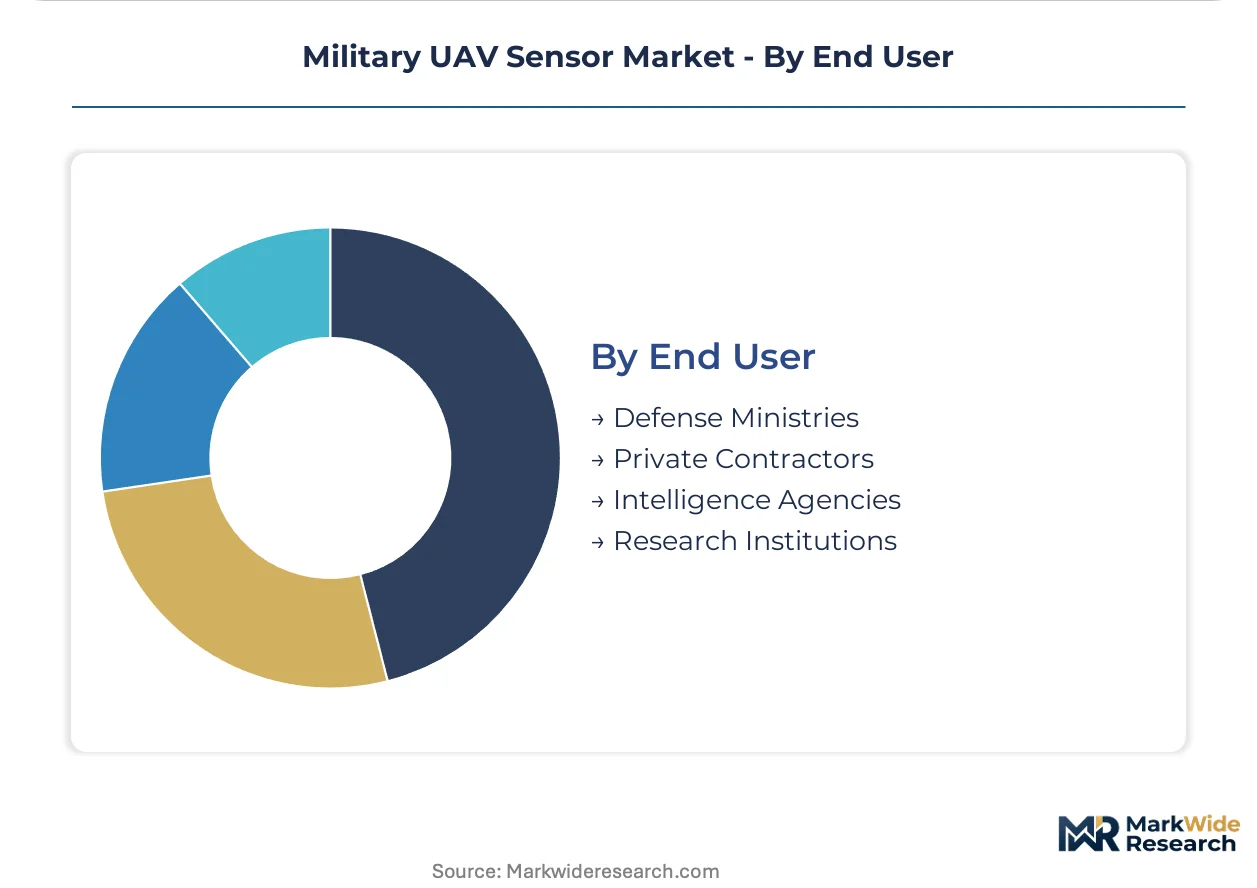
End User:
Budgetary authority and classification clearance levels determine procurement channel structure, with defense ministries maintaining platform prime relationships while intelligence agencies conduct direct payload acquisitions.
- Defense Ministries:Sovereign military procurement offices managing fleet-wide standardization and interoperability mandates. The UK Ministry of Defence's Team Complex Weapons framework exemplifies disaggregated sensor procurement independent of airframe manufacturers.
- Intelligence Agencies:National technical means programs with specialized requirements for low-probability-of-intercept datalinks and enhanced electromagnetic spectrum protection.
- Private Contractors:Defense integrators and system-of-systems providers subcontracting payload development.
- Research Institutions:National laboratories and university-affiliated research centers advancing quantum cascade laser and hyperspectral technologies.
Defense ministries control the preponderance of procurement volume; intelligence agencies are expanding most quickly as classified development programs accelerate beyond traditional acquisition timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement offices in NATO member states concentrate demand for electro-optical and multi-spectral payloads, with sovereign budgets diverging on ITAR versus EU Dual-Use Regulation compliance pathways. Poland's Technical Modernisation Plan and classified US Department of Defense programs anchor near-term procurement volumes.
United States
The Pentagon's Group 4-5 tactical UAV fleet expansion and classified high-altitude long-endurance programs drive electro-optical and synthetic aperture radar demand. ITAR technical data review cycles extend foreign military sale timelines by four to six months for embedded software systems. Tucson, Arizona hosts concentrated electro-optical payload integration facilities serving Customs and Border Protection Predator B operations.
Poland
The Technical Modernisation Plan 2021-2035 allocates substantial unmanned systems procurement for Gryf and Orka programs, creating entry points for sensor vendors establishing regional maintenance hubs. EU Dual-Use Regulation recast provisions streamline intra-alliance licensing for hybrid electro-optical-infrared payloads. Warsaw defense clusters are attracting NATO-standard payload specialists for localized support infrastructure.
Germany
The European Defence Agency's multi-domain operations doctrine mandates interoperable sensor data formats, accelerating hybrid system procurement for tactical UAV fleets. EU AI Act high-risk system classifications require human-in-the-loop override capabilities for autonomous target recognition algorithms. Bavarian aerospace corridors host sensor fusion processor development for Franco-German unmanned programs.
United Kingdom
The Ministry of Defence's Team Complex Weapons framework disaggregates sensor procurement from airframe manufacturers, permitting payload specialists to compete independently. Budgetary transparency rules facilitate line-item visibility for electro-optical and radar subsystem acquisitions. Greater Bristol clusters concentrate on signals intelligence payload integration for strategic reconnaissance platforms.
Israel
Specialized low-probability-of-intercept datalink requirements and enhanced electromagnetic spectrum protection drive intelligence agency procurement outside traditional defense ministry channels. National technical means programs accelerate beyond standard acquisition timelines for covert operational profiles. Tel Aviv metropolitan defense technology corridors concentrate on miniaturized multi-spectral gimbal development for export-restricted markets.
Military UAV Sensor Market Competitive Landscape
Player mix skews toward vertically integrated aerospace primes with captive electro-optical manufacturing and classified radar development capabilities. Tier-one suppliers with AS9100D and MIL-STD-810H qualification cycles dominate framework contract positions, while smaller payload specialists compete on disaggregated procurement channels. Two strategic archetypes prevail: platform-agnostic sensor houses with dual-use civilian-military production lines, and prime contractors with end-to-end payload integration. M&A consolidation and regional maintenance hub establishment represent the dominant competitive moves as vendors defend positions against export control fragmentation.
Within the prime contractor tier, Lockheed Martin Corporation and RTX Corporation exemplify vertically integrated aerospace manufacturers with captive sensor production capabilities. Northrop Grumman Corporation occupies a specialized position in high-altitude long-endurance sensor integration. Among European-based defense integrators, BAE Systems plc and Thales Group represent platform-agnostic payload specialists competing through disaggregated procurement frameworks. L3Harris Technologies and Teledyne FLIR LLC sit within the electro-optical sensor house archetype, leveraging dual-use production scale for defense ministry framework contracts.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| RTX Corporation |
| Northrop Grumman Corporation |
| BAE Systems plc |
| L3Harris Technologies |
| Teledyne FLIR LLC |
| Honeywell International Inc. |
| Thales Group |
| General Atomics Aeronautical Systems |
| Others |
Supply & Pricing Matrix
Foundry utilization rates above 85 percent at gallium arsenide substrate manufacturers in Taiwan and South Korea compress margin buffers for Western radar component suppliers, elevating price floors for active electronically scanned arrays while ITAR compliance costs add fixed overhead layers to electro-optical payload quotations.
Pricing Analysis
Cost-plus contracts with Bureau of Labor Statistics producer price index adjustments dominate Pentagon sensor procurement, embedding inflation protection for prime contractors. Price differentiation hinges on MIL-STD-810H qualification tier and after-sales field service bundling. Cost compression in uncooled electro-optical tiers is intensifying because Taiwanese foundry expansion lags demand growth. Intelligence agencies show least price sensitivity due to classified program budgets; Eastern European defense ministries exhibit highest sensitivity under EU structural fund constraints.
Supply Chain Analysis
Container availability constraints at Port of Long Beach and Rotterdam-Antwerp corridor elevate inbound logistics costs for germanium lens blanks and precision gyroscope subassemblies. Gallium arsenide wafer fabrication concentrates in Taiwan, South Korea, and Japan; mercury cadmium telluride detector arrays draw from US and French foundries. Single-source vulnerability pervades cryogenic cooler compressor supply. Distribution runs through defense ministry framework contracts with regional maintenance hub requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense procurement disaggregation creates fragmentation opportunity as ministries unbundle sensor hardware from airframe primes, opening direct contracting channels for payload specialists with AS9100D qualification and NATO interoperability certification.
For Market Incumbents: Compound captive electro-optical manufacturing scale through backward integration into precision gimbal actuator production, countering emerging sensor houses from Israeli defense corridors. Anchor framework contract positions by establishing Polish maintenance hubs under Technical Modernisation Plan procurement windows.
For New Entrants and Emerging Players: AS9100D fast-track certification through accredited aerospace registrars unlocks UK Ministry of Defence Team Complex Weapons disaggregated procurement channel. Poland's Gryf and Orka unmanned programs represent most penetrable geography; lead with hybrid electro-optical-infrared payloads featuring EU Dual-Use Regulation streamlined licensing.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors AI-enabled sensor fusion specialists with convolutional neural network training pipelines and human-in-the-loop compliance architectures for EU AI Act high-risk system classification. Acquisition target archetype: venture-backed edge compute payload developers with NATO STANAG datalink integration. Signal to watch: Department of Defense Cybersecurity Maturity Model Certification mandate enforcement timelines for embedded software architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| AS9100D Certification Investment | Unlocks NATO defense ministry framework contract eligibility and ITAR technical data access. |
| Regional Maintenance Hub Establishment | Secures Polish Technical Modernisation Plan procurement preference for Gryf and Orka programs. |
| AI-Driven Sensor Fusion Development | Compresses target recognition timelines for JADC2 multi-domain operations doctrine compliance. |
| EU Dual-Use Regulation Compliance Pathway | Streamlines intra-alliance licensing for German and French integrator subcontracting relationships. |
| Quantum Cascade Laser Payload Miniaturization | Displaces legacy mercury cadmium telluride arrays in special operations covert designation missions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Department of Defense budget justification documents, EU Dual-Use Regulation licensing databases, and NATO standardization agreements. Defense procurement officers, electro-optical payload engineering directors, and military flight test program managers contributed operational perspective. Customs trade data for gallium arsenide substrate flows, SEC 10-K filings from prime contractors, and Bureau of Industry and Security export license records furnished validation. Bottom-up sensor unit demand estimates and top-down defense budget allocation analysis provided triangulation.
Segmentation dimensions modeled encompass product type across electro-optical, infrared, radar, and acoustic modalities; technology tier spanning AI-driven, hybrid, multi-spectral, and synthetic aperture radar architectures; application profile from surveillance through target acquisition; and end-user category distinguishing defense ministry, intelligence agency, and private contractor procurement channels. CAGRs derive from regression analysis of historical procurement volumes against doctrinal shift indicators and regulatory implementation timelines. Gallium arsenide foundry capacity expansion schedules and ITAR technical data review cycle durations inform supply-constrained scenario outputs.
Decision-makers should treat outputs as directional under assumptions of sustained NATO defense spending growth and stable US-EU export control harmonization; material deviation would warrant model refresh. Classified program budget opacity and rapid algorithmic warfare doctrine evolution constitute primary forecast revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Drone Telematics Market
UAV
Global Drone Services Market
UAV
Utility Drone Market
UAV
North America Small UAV Market
UAV
Asia-Pacific Drone Motor Market
UAV
Global Aerial Survey Services Market
UAV
Industrial Drones Market
UAV
UAV Payload and Subsystems Market
UAV
Stratospheric Flying Drone Market
UAV
Unmanned Combat Aerial Vehicle Market
UAV
Airborne Digital Battlefield Market
UAV
Asia-Pacific Tactical UAV Market
UAV
Latin America Small UAV Market
UAV
Anti-Drone Technology Market
UAV
Drone Data Management Market
UAV
UAV Payload Market