
 Drone Jamming System Market | 2026-2036
Drone Jamming System Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Jamming System Market Insights
Defense procurement is recalibrating from single-source government contracts toward multi-vendor frameworks with technology-sharing clauses. RTX Corporation leverages its radar-integrated jamming architecture to anchor long-term military service contracts. Lockheed Martin Corporation sustains dominance in fixed-site perimeter defense through classified frequency-management protocols. Thales Group competes across European NATO tenders with modular vehicle-mounted platforms.
Drone jamming systems are electronic warfare devices that emit targeted radio-frequency energy to disrupt command links, GPS navigation, and telemetry between unmanned aerial vehicles and their operators, typically operating across 400 MHz to 6 GHz bands with effective ranges from 500 meters to over 10 kilometers depending on output power and antenna configuration. Portable jamming devices lead current procurement volumes due to rapid deployment requirements for mobile security teams and forward military units, while RF signal disruption captures the largest technology share as the foundational layer for multi-protocol suppression. Vehicle-mounted jammers represent the fastest-growing product category as mechanized infantry and convoy protection programs expand across Eastern European defense budgets.
The FCC restricts civilian jamming under Communications Act provisions, while the EU AI Act and CE marking frameworks shape certification pathways for autonomous threat-detection modules integrated into jamming platforms. Military forces in Germany, France, and Poland navigate divergent national frequency-allocation rules that complicate cross-border interoperability standards. Stakeholders must monitor evolving spectrum-management policies and electromagnetic-compatibility mandates to anticipate procurement specification shifts.
Market Dynamics
Defense procurement across NATO member states is pivoting toward multi-vendor frameworks with embedded technology-sharing requirements, compressing traditional single-source contracting timelines and forcing incumbent suppliers to open proprietary architectures.
Growth Catalysts
- EU AI Act certification pathways:The European Union's artificial intelligence governance framework creates standardized approval routes for autonomous threat-detection modules, accelerating procurement cycles for integrated jamming platforms.
- Mechanized infantry convoy protection:Eastern European defense budgets are channeling resources into vehicle-mounted counter-UAS systems for mobile force protection along contested supply corridors.
- FCC civilian frequency restrictions:The United States Communications Act limitations on non-military jamming push security buyers toward certified military-grade systems with lawful spectrum access.
Market Restraints
- Cross-border frequency fragmentation:Germany, France, and Poland maintain divergent national spectrum-allocation rules that obstruct interoperability standards for multinational NATO operations.
- High-power amplifier supply concentration:Gallium nitride semiconductor fabrication for jamming transmitters concentrates among a limited set of foundries, creating input bottlenecks during surge procurement.
- Electromagnetic compatibility mandates:CE marking requirements for electromagnetic coexistence impose testing burdens that extend development timelines for multi-band systems.
Strategic Opportunities
- Polish defense modernization:Poland's accelerated military spending creates white-space demand for portable counter-UAS units deployable across forward operating positions.
- RF-GPS convergence architectures:Integration of radio-frequency disruption with precision navigation spoofing enables layered defeat mechanisms against hardened drone autopilots.
- Direct military-to-manufacturer contracting:Bypassing traditional prime contractor tiers allows specialized jamming vendors to capture service-contract revenue streams previously captured by systems integrators.
Industry Challenges
- Electromagnetic warfare talent scarcity:The specialized skill set spanning spectrum engineering, antenna design, and protocol analysis concentrates among defense contractors with classified clearance pipelines.
- Legacy radar integration complexity:Fielding jamming systems alongside existing air-defense networks requires protocol adaptation that extends deployment timelines and inflates integration costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Jamming System Market |
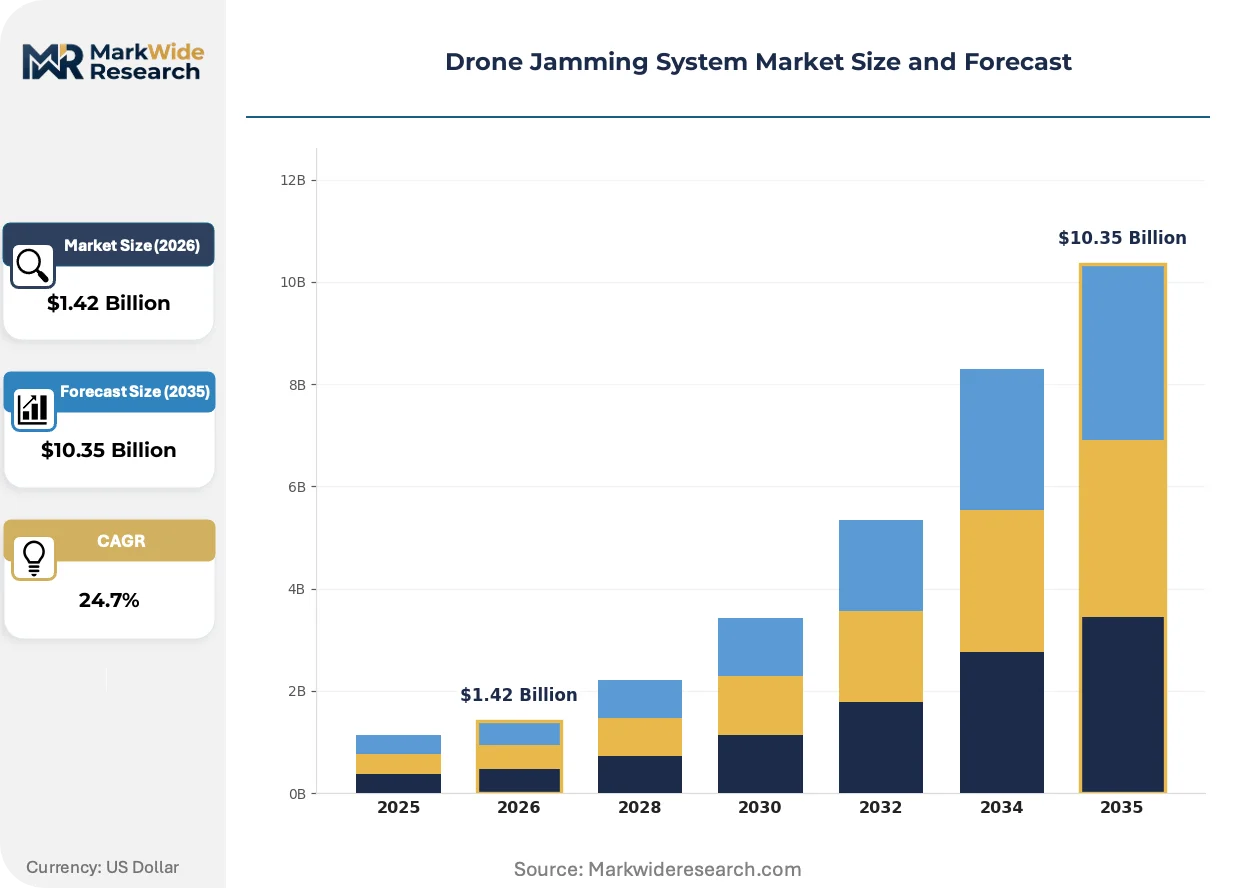
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $10.35 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Jamming Devices, Fixed Jamming Stations, Vehicle-Mounted Jammers, Handheld Suppressors, Trojan Jamming Tools Technology: GPS Signal Jamming, RF Signal Disruption, Frequency Hopping Suppression, Drone Control Signal Blocking, Pulse Wave Interference Application: Critical Infrastructure Protection, Event Security, Wildlife Preservation, Border Surveillance, Prison Security, VIP Protection End User: Military Forces, Law Enforcement, Security Agencies, Private Security Firms, Emergency Response Teams |
| Companies Covered | RTX Corporation, Lockheed Martin Corporation, Thales Group, Israel Aerospace Industries Ltd., Leonardo S.p.A., Northrop Grumman Corporation, Saab AB, DroneShield Ltd, Dedrone Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Jamming System Market Trends and Innovations
Electronic warfare architectures are fragmenting from monolithic platforms into distributed node networks, enabling adaptive spectrum dominance without single-point vulnerability. This structural shift redefines competitive advantage around software-defined flexibility rather than hardware scale.
Software-defined radio cores are modularizing jamming system design by replacing fixed-frequency hardware banks with reprogrammable digital signal processors. Military procurement offices in NATO member states are mandating open-architecture interfaces that permit rapid waveform updates against evolving drone command protocols. This technology compression is collapsing the traditional 18-24 month product refresh cycle into continuous firmware deployment models.
REACH substance restrictions and RoHS compliance deadlines are forcing European manufacturers to eliminate lead-based solders and restricted flame retardants from jamming electronics. The industrial consequence is a supply-chain migration toward certified component vendors with documented material traceability. Vehicle-mounted platforms with extended operational lifecycles face the most acute reformulation pressure as they fall under broader electrical equipment waste directives.
Buyer concentration around framework contracting is consolidating vendor relationships into multi-year service agreements with embedded technology refresh clauses. Security agencies in the United Kingdom and Germany are displacing transactional equipment purchases with performance-based availability contracts. This pattern is most visible in critical infrastructure protection programs where downtime penalties now exceed capital equipment costs.
Drone Jamming System Market Segmentation
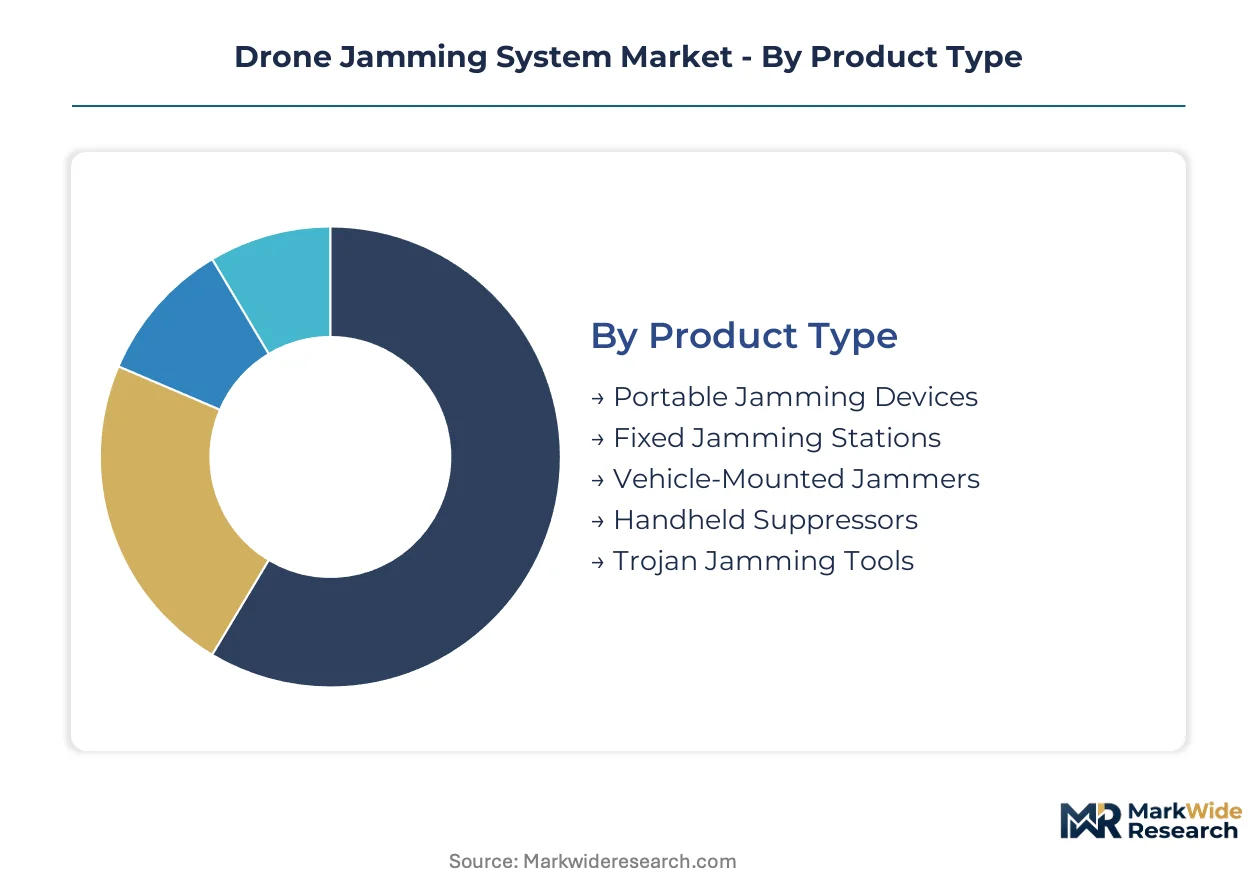
Drone jamming system procurement divides sharply across deployment mobility, electromagnetic technique, operational mission, and institutional buyer type. Each segmentation axis carries distinct supply chain configurations, certification requirements, and competitive dynamics that shape vendor positioning and contract profitability.
Product Type:
Supply concentration for high-power amplifiers and gallium nitride semiconductors concentrates fabrication among limited foundries, creating procurement bottlenecks that favor vendors with captive component access or long-term supply agreements.
- Portable Jamming Devices:Battery-powered units weighing under 15 kilograms deliver 500-meter to 3-kilometer disruption ranges for dismounted infantry and mobile security teams. NATO mechanized units in Poland and Germany are accelerating procurement of man-portable systems for forward operating base perimeter defense amid Eastern European force posture adjustments.
- Vehicle-Mounted Jammers:Platform-integrated systems with 360-degree antenna arrays and 10-kilometer-plus effective ranges protect convoys and mechanized formations. Eastern European defense budgets are channeling resources into these platforms for contested supply corridor protection, representing the steepest expansion trajectory across product categories.
- Fixed Jamming Stations:Permanent installations with grid power and networked sensor fusion for airfield and critical site defense.
- Handheld Suppressors:Pistol-grip devices for close-range drone neutralization by individual operators.
- Trojan Jamming Tools:Covert systems designed for clandestine electromagnetic operations and intelligence applications.
Today's leader: Portable Jamming Devices. Tomorrow's challenger: Vehicle-Mounted Jammers.
Technology:
Cost tier differentiation separates foundational RF disruption from specialized GPS spoofing and adaptive frequency-hunting capabilities, with premium pricing attaching to multi-protocol suppression and software-defined waveform agility.
- RF Signal Disruption:Broadband radio-frequency flooding across 400 MHz to 6 GHz bands interrupts command links between drones and ground control stations. Military procurement offices in NATO member states treat RF suppression as the mandatory baseline layer for layered counter-UAS architectures, driving the largest technology share by contract volume.
- GPS Signal Jamming:Targeted denial of satellite navigation signals forces drones into degraded flight modes or controlled landings. Integration with RF disruption in converged architectures is gaining share fastest among hardened drone threats with autopilot redundancy.
- Frequency Hopping Suppression:Adaptive tracking of spread-spectrum command protocols used by advanced military-grade drones.
- Drone Control Signal Blocking:Protocol-specific disruption targeting commercial off-the-shelf drone command sets.
- Pulse Wave Interference:High-power burst transmission for momentary link severance with reduced collateral spectrum occupation.
Foundation technology: RF Signal Disruption. Emerging differentiator: GPS Signal Jamming.
Application:
Volume concentration clusters around perimeter defense missions with recurring procurement budgets and multi-year service contracts, while specialized applications like wildlife preservation remain fragmented with episodic purchasing.
- Critical Infrastructure Protection:Permanent counter-UAS coverage for power generation, telecommunications, and transportation nodes. Security agencies in the United Kingdom and Germany are displacing transactional equipment purchases with performance-based availability contracts where downtime penalties exceed capital costs.
- Military Convoy and Base Defense:Mobile and fixed protection for armed forces installations and transiting formations. Eastern European NATO members are expanding procurement most aggressively for mechanized unit protection along contested corridors.
- Event Security:Temporary deployment for sporting venues, political summits, and public gatherings.
- Wildlife Preservation:Protection of conservation areas from poaching surveillance drones.
- Border Surveillance:Counter-smuggling and illegal crossing prevention along national boundaries.
- Prison Security:Prevention of contraband delivery and unauthorized surveillance over correctional facilities.
- VIP Protection:Close-range mobile security for government and corporate principals.
Contract value anchor: Critical Infrastructure Protection. Fastest budget growth: Military Convoy and Base Defense.
End User:
Customer type determines certification pathway complexity, with military buyers requiring classified clearance pipelines and electromagnetic compatibility testing that exclude commercial security vendors from prime contracting tiers.
- Military Forces:Armed services procurement with classified frequency-management protocols and multi-vendor framework contracting. Defense procurement across NATO member states is pivoting toward embedded technology-sharing requirements that compress traditional single-source contracting timelines.
- Law Enforcement:Police and gendarmerie units with civilian frequency-use restrictions pushing buyers toward certified military-grade systems with lawful spectrum access under FCC and national communications act provisions.
- Security Agencies:Government protective services with critical infrastructure protection mandates.
- Private Security Firms:Commercial operators serving corporate and high-net-worth clients with unclassified threat profiles.
- Emergency Response Teams:First responders requiring rapid-deployment capabilities for disaster scene airspace control.
Procurement volume leader: Military Forces. Regulatory access gatekeeper: Law Enforcement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European defense cluster concentrates procurement momentum for drone jamming systems, with NATO mechanized units driving vehicle-mounted platform demand across contested Eastern European corridors.
United States
FCC Communications Act restrictions on civilian frequency use push defense and security buyers toward certified military-grade systems with lawful spectrum access. The Pentagon's multi-vendor framework contracting compresses traditional single-source timelines and forces technology-sharing clauses. RTX Corporation anchors radar-integrated jamming architecture in Arizona and Massachusetts defense corridors.
Germany
Bundeswehr procurement offices mandate open-architecture interfaces for rapid waveform updates against evolving drone protocols. The country's national frequency-allocation rules diverge from neighboring states, complicating cross-border NATO interoperability standards. Bavaria and Baden-Württemberg host vehicle-mounted jammer integration facilities serving mechanized infantry modernization programs.
United Kingdom
Ofcom tightened civilian frequency-use rules accelerate migration toward certified military-grade counter-UAS procurement. Security agencies displace transactional equipment purchases with performance-based availability contracts where downtime penalties exceed capital costs. London and Southeast England concentrate critical infrastructure protection deployments.
France
EU AI Act certification pathways create standardized approval routes for autonomous threat-detection modules integrated into jamming platforms. Thales Group competes across European NATO tenders with modular vehicle-mounted platforms from Île-de-France engineering centers. Provence-Alpes-Côte d'Azur hosts fixed-site perimeter defense installations.
Poland
Accelerated defense modernization creates white-space demand for portable counter-UAS units deployable across forward operating positions. Divergent national spectrum-allocation rules obstruct interoperability standards for multinational NATO operations. Eastern border regions channel vehicle-mounted jammer procurement for contested supply corridor protection.
Drone Jamming System Market Competitive Landscape
Global majors compete with regional champions across NATO defense procurement frameworks, creating a tiered structure where classified clearance pipelines and electromagnetic warfare talent scarcity erect entry barriers. The vendor base clusters around three strategic archetypes: radar-integrated systems integrators, modular vehicle-mounted platform specialists, and portable counter-UAS device manufacturers. Dominant competitive moves include direct military-to-manufacturer contracting that bypasses traditional prime contractor tiers, and backward integration into gallium nitride semiconductor fabrication to secure high-power amplifier supply.
Within the classified systems integrator tier, RTX Corporation and Lockheed Martin Corporation exemplify vendors capturing long-term military service contracts through proprietary frequency-management protocols. Thales Group occupies a position representing European modular platform competition across NATO tenders. These three anchors illustrate how technology-sharing mandates and open-architecture requirements are reshaping competitive positioning toward software-defined flexibility rather than hardware scale.
| Leading Market Players |
|---|
| RTX Corporation |
| Lockheed Martin Corporation |
| Thales Group |
| Israel Aerospace Industries Ltd. |
| Leonardo S.p.A. |
| Northrop Grumman Corporation |
| Saab AB |
| DroneShield Ltd |
| Dedrone Holdings Inc. |
| Others |
Pricing and Supply Chain Analysis
Gallium nitride wafer pricing cascades through jamming system manufacturing into three-tier pricing structure across premium, standard, and economy levels, with military-grade GaN-on-SiC substrates commanding five-fold premiums over commercial RF components and certification-grade assemblies absorbing margin compression from REACH substance reformulation mandates.
Pricing Analysis
Input-cost pass-through from high-power amplifier fabrication concentrates pricing power among vendors with captive gallium nitride foundry access or long-term supply agreements. Three-tier pricing structure across premium, standard, and economy levels separates classified military systems with frequency-hopping suppression from modular vehicle-mounted platforms and portable dismounted units. Pricing pressure stems from gallium nitride semiconductor supply concentration among limited foundries during surge procurement cycles. Military Forces exhibit lowest price sensitivity due to classified clearance requirements and multi-year framework contracting, while Private Security Firms face acute budget constraints and unclassified threat profiles.
Supply Chain Analysis
Reverse-logistics flows for vehicle-mounted jamming platforms center on Bavarian and Baden-Württemberg refurbishment facilities serving Bundeswehr mechanized infantry modernization programs, with end-of-life RF modules recovered for protocol analysis and waveform database updates. Geographic supply concentration clusters in the United States, Germany, and Taiwan for gallium nitride semiconductors, high-power amplifiers, and software-defined radio cores. Raw material dependencies rest on rare earth elements for magnetron assemblies, copper-nickel alloys for antenna substrates, and lithium-polymer cells for portable power systems. Single-source vulnerability concentrates in GaN-on-SiC wafer fabrication. Distribution runs through direct military-to-manufacturer contracting that bypasses traditional prime contractor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Drone Jamming System Market reads as a late-cycle quality story as NATO procurement offices mandate open-architecture interfaces and software-defined waveform agility that favor vendors with sustained R&D investment over hardware-scale competitors.
For Market Incumbents: Extend service-contract revenue capture through performance-based availability agreements with embedded technology refresh clauses, defending against direct military-to-manufacturer contracting that disintermediates traditional prime contractor tiers. Deepen backward integration into gallium nitride semiconductor fabrication to secure high-power amplifier supply against foundry concentration bottlenecks. For New Entrants and Emerging Players: Capture white-space demand in Polish defense modernization for portable counter-UAS units deployable across forward operating positions, where accelerated military spending outpaces incumbent vendor capacity. Target direct contracting relationships with Eastern European mechanized infantry programs for vehicle-mounted convoy protection systems, leveraging RF-GPS convergence architectures as technical differentiation. For Investors and Strategic Acquirers: Consolidation pressure builds where electromagnetic warfare talent scarcity concentrates among defense contractors with classified clearance pipelines and protocol analysis capabilities. Long-term viability favors vendors with software-defined radio cores and continuous firmware deployment models over fixed-frequency hardware platforms. Acquisition target archetype: specialized jamming vendors with NATO framework contract access and gallium nitride supply agreements. Signal to watch: frequency-allocation harmonization initiatives between Germany, France, and Poland that would unlock cross-border interoperability standards.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into GaN Fabrication | Captive wafer supply insulates against foundry concentration during NATO surge procurement cycles. |
| Open-Architecture Interface Certification | Bundeswehr mandates accelerate vendor positioning for rapid waveform update contracts. |
| Direct Military Contracting Bypass | Specialized jamming vendors capture service revenue previously held by systems integrators. |
| RF-GPS Convergence Platform Development | Layered defeat mechanisms address hardened drone autopilots in Eastern European corridors. |
| Performance-Based Availability Agreements | UK and German security agencies displace transactional purchases with downtime-penalty contracts. |
Research Methodology
Multiple input streams — electromagnetic warfare program managers at NATO procurement offices, RF systems engineers at defense contractors with classified clearance pipelines, and regulatory affairs specialists navigating FCC and Ofcom frequency-use frameworks — were reconciled against secondary validation from EU AI Act certification documentation, SEC 10-K filings of listed defense contractors, and electromagnetic compatibility test reports under CE marking frameworks. Bottom-up triangulation across portable, vehicle-mounted, and fixed jamming system deployments converged with top-down demand estimation from national defense budget allocations and critical infrastructure protection program announcements.
Historical procurement volume patterns were cross-referenced against expert panel inputs from spectrum engineering directors and antenna design specialists to anchor growth trajectory assumptions across the analysis window. Segmentation dimensions modeled include deployment mobility tier, electromagnetic technique type, operational mission profile, and institutional buyer category with classified clearance requirements. CAGRs were derived from deployment timeline acceleration in Eastern European defense budgets and mechanized infantry modernization program ramps. Industry-specific forecast inputs incorporated gallium nitride foundry capacity expansion announcements and REACH substance restriction compliance deadlines.
Regulatory harmonization delays, gallium nitride supply chain disruptions, and electromagnetic warfare talent pipeline constraints are the dominant revision risks that could compress or extend projected procurement cycles. Practitioners should monitor frequency-allocation negotiation outcomes between Germany, France, and Poland for early signals of cross-border interoperability standard adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Maritime Drone Market
Unmanned Systems
Loitering Munition System Market
Unmanned Systems
Bomb Disposal Robot Market
Unmanned Systems
Autonomous Drone Platform Market
Unmanned Systems
High Altitude Aeronautical Platform Stations Market
Unmanned Systems
Brazil ROV Market
Unmanned Systems
Drone Tethered Stations Market
Unmanned Systems
Remote Weapon Systems Market
Unmanned Systems
Unmanned Surface Vessel (USV) Market
Unmanned Systems
North America Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Unattended Ground Sensors (UGS) Market
Unmanned Systems
High Altitude Platform Market
Unmanned Systems
Unmanned Aerial Vehicle Payload and Subsystems Market
Unmanned Systems
Unmanned Underwater Vehicles (UUV) Market
Unmanned Systems
Europe Unmanned Systems Market
Unmanned Systems
Unmanned Ground Vehicle Market