
 Air Based C4ISR Market | 2026-2036
Air Based C4ISR Market Size, Share, and Industry Trends Forecast 2026-2036
Air Based C4ISR Market Analysis
The customer base for airborne command and control systems is broadening beyond traditional air force branches to include naval aviation, special operations commands, and coalition interoperability programs. Lockheed Martin leverages its integrated warfare systems portfolio to anchor large-scale platform integration contracts across multiple service branches. Northrop Grumman sustains technology leadership in autonomous mission systems and advanced radar architectures. Elbit Systems competes through specialized electronic warfare suites tailored to medium-tier defense budgets.
Air based C4ISR denotes airborne platforms and payloads that integrate command, control, communications, computers, intelligence, surveillance, and reconnaissance functions through networked sensor arrays, datalink architectures, and real-time battle management software operating at altitudes from tactical low-level to high-altitude long-endurance orbits. These systems process multi-spectral intelligence feeds to enable time-critical targeting and distributed decision-making across joint force structures. Surveillance applications dominate current procurement volumes due to persistent demand for wide-area motion imagery in contested environments. Sensor fusion technology is expanding fastest as operators require correlated outputs from radar, electro-optical, and signals intelligence sources rather than stovepiped feeds. Electronic warfare represents a concentrated margin pool where proprietary jamming algorithms and threat library updates create recurring revenue attachments.
The US Department of Defense's JADC2 framework and the FAA's airspace integration standards for unmanned systems shape certification pathways and operational envelopes for new platforms. NATO's standardization agreements for tactical datalinks and interoperability protocols dictate subsystem compatibility requirements for cross-border coalition operations. Stakeholders must monitor how software-defined radio architectures and open systems standards alter supplier competitive dynamics in platform electronics.
Market Dynamics
The US Department of Defense's JADC2 architecture is compressing platform development cycles and forcing subsystem interoperability across previously stovepiped air, space, and cyber domains. Defense contractors must now engineer for networked kill chains rather than standalone platform performance.
Growth Catalysts
- NATO Standardization Agreements:STANAG 4586 and 4671 mandates for unmanned systems interoperability are accelerating cross-border procurement of compatible datalink architectures.
- Electronic Warfare Modernization:Contested electromagnetic spectrum operations in Eastern Europe are driving replacement of analog jamming systems with software-defined radio payloads.
- Special Operations Commands:USSOCOM and allied special forces are expanding dedicated airborne intelligence platforms beyond traditional air force procurement channels.
Market Restraints
- Gallium Nitride Supply Concentration:High-performance radar and electronic warfare systems depend on GaN substrates sourced primarily from East Asian foundries, creating single-source vulnerability.
- FAA Certification Bottlenecks:Airspace integration standards for large unmanned systems in US national airspace impose multi-year operational approval timelines.
- Legacy Platform Interoperability:Cold War-era command and control aircraft lack open systems architectures, forcing expensive middleware development for JADC2 compatibility.
Strategic Opportunities
- Poland and Baltic States:NATO's eastern flank members are building indigenous airborne ISR capabilities with US Foreign Military Financing support.
- AI-Assisted Sensor Fusion:Machine learning inference at the edge is converging with multi-spectral imaging to enable autonomous target recognition without ground station dependency.
- Commercial Derivative Aircraft:Modified business jets are displacing dedicated military platforms for medium-altitude ISR missions, opening new supplier tiers.
Industry Challenges
- Cleared Workforce Scarcity:TS/SCI-cleared software engineers and systems integrators remain concentrated around Fort Meade and Palmdale, constraining program scaling.
- Platform Integration Complexity:Third-party payload certification on manned aircraft requires FAA Supplemental Type Certificate processes that conflict with accelerated defense procurement timelines.
- Intellectual Property Fragmentation:Proprietary battle management software from prime contractors creates vendor lock-in that complicates joint force interoperability mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Based C4ISR Market |
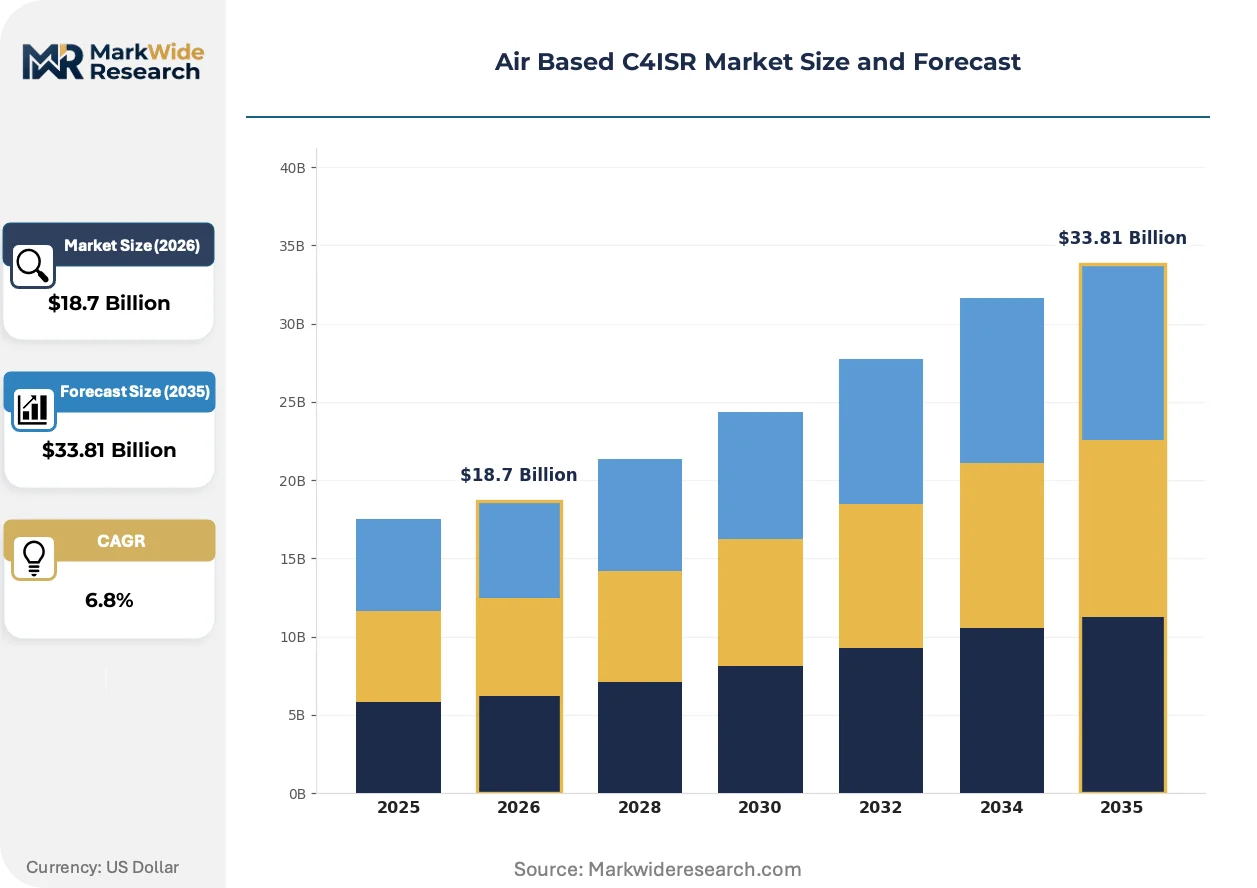
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Surveillance, Reconnaissance, Communication, Electronic Warfare Technology: Radar, Satcom, Data Link, Sensor Fusion End User: Military, Government Agencies, Private Sector, Defense Contractors Service Type: Consulting, Integration, Maintenance, Training |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, BAE Systems PLC, L3Harris Technologies Inc., RTX Corporation, Elbit Systems Ltd., The Boeing Company, General Dynamics Corporation, Thales, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Based C4ISR Market Emerging Trajectories
Software-defined architectures are displacing hardware-centric designs across airborne mission systems, enabling rapid capability updates through firmware rather than platform modification. This shift is altering supplier competitive dynamics and contracting models.
Multi-domain sensor fusion is converging with edge computing architectures to process radar, electro-optical, and signals intelligence feeds aboard the platform rather than transmitting raw data to ground stations. Naval aviation and special operations commands are adopting these capabilities fastest due to contested communications environments. The structural consequence is compression in ground infrastructure requirements and expanded operational radius for distributed missions.
The FAA's Part 89 remote identification mandate and emerging detect-and-avoid standards for unmanned aircraft are forcing redesign of small ISR drone architectures. Manufacturers must now integrate broadcast transponders and collision avoidance sensors that add weight and power draw. The commercial unmanned systems segment is absorbing these compliance costs fastest, while defense platforms pursue waiver pathways.
Service-based contracting models are displacing traditional platform acquisition for persistent surveillance missions. Intelligence community customers now prioritize guaranteed availability hours over asset ownership, shifting risk to contractors for maintenance and obsolescence. This pattern is most visible in US Africa Command and US Southern Command operational areas where contractor-owned/contractor-operated platforms dominate orbits.
Air Based C4ISR Market Segmentation
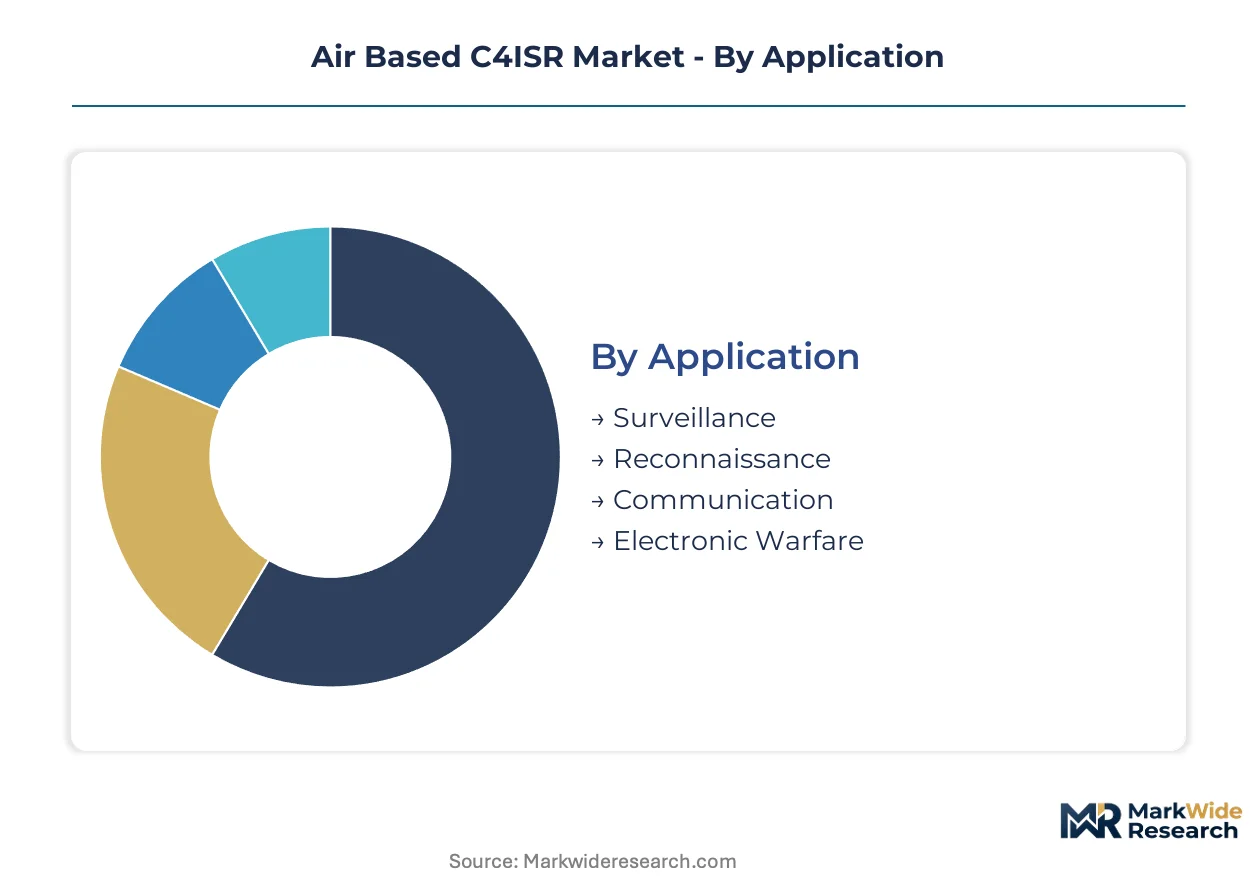
Segmentation in airborne C4ISR reveals how procurement priorities diverge across mission types and technology readiness levels. Contractors must align platform configurations to specific operator workflows rather than delivering standardized architectures.
Application:
Supply concentration in airborne mission systems clusters around persistent surveillance platforms, with prime contractors controlling integration bottlenecks for multi-spectral payloads.
- Surveillance:Wide-area motion imagery systems dominate current procurement volumes, with demand concentrating in US Africa Command operational areas where contractor-owned platforms sustain persistent orbits. FAA certification bottlenecks for unmanned systems constrain rapid scaling of new entrants.
- Electronic Warfare:Software-defined radio payloads with proprietary jamming algorithms generate recurring revenue through threat library updates. Contested electromagnetic spectrum operations in Eastern Europe accelerate replacement of analog systems.
- Reconnaissance:Time-critical targeting missions require correlated multi-intelligence feeds rather than stovepiped sensor outputs.
- Communication:Battle management software integrates tactical datalinks across joint force structures per NATO standardization mandates.
Today's leader: Surveillance. Tomorrow's challenger: Electronic Warfare.
Technology:
Cost tier differentiation separates mature radar architectures from emerging sensor fusion investments requiring substantial software development.
- Sensor Fusion:Machine learning inference at the edge converges with multi-spectral imaging to enable autonomous target recognition without ground station dependency. Naval aviation and special operations commands adopt these capabilities fastest due to contested communications environments.
- Radar:Gallium nitride substrate dependence creates single-source vulnerability for high-performance systems, with foundry concentration in East Asian supply chains.
- Data Link:STANAG 4586 and 4671 protocols mandate unmanned systems interoperability for cross-border coalition operations.
- Satcom:Beyond-line-of-sight connectivity requirements expand operational radius for distributed missions.
Sensor fusion is climbing the fastest as operators demand correlated outputs; radar maintains volume leadership through platform refresh cycles.
End User:
Customer type fragmentation intensifies as special operations commands bypass traditional air force procurement channels for dedicated airborne intelligence platforms.
- Military:Joint All-Domain Command and Control architecture mandates compress platform development cycles and force subsystem interoperability across air, space, and cyber domains.
- Defense Contractors:Service-based contracting models shift risk to vendors for maintenance and obsolescence in persistent surveillance missions.
- Government Agencies:Intelligence community customers prioritize guaranteed availability hours over asset ownership.
- Private Sector:Modified business jets displace dedicated military platforms for medium-altitude ISR missions.
Military branches anchor current procurement volume; defense contractors are gaining share fastest through availability-based service models.
Service Type:
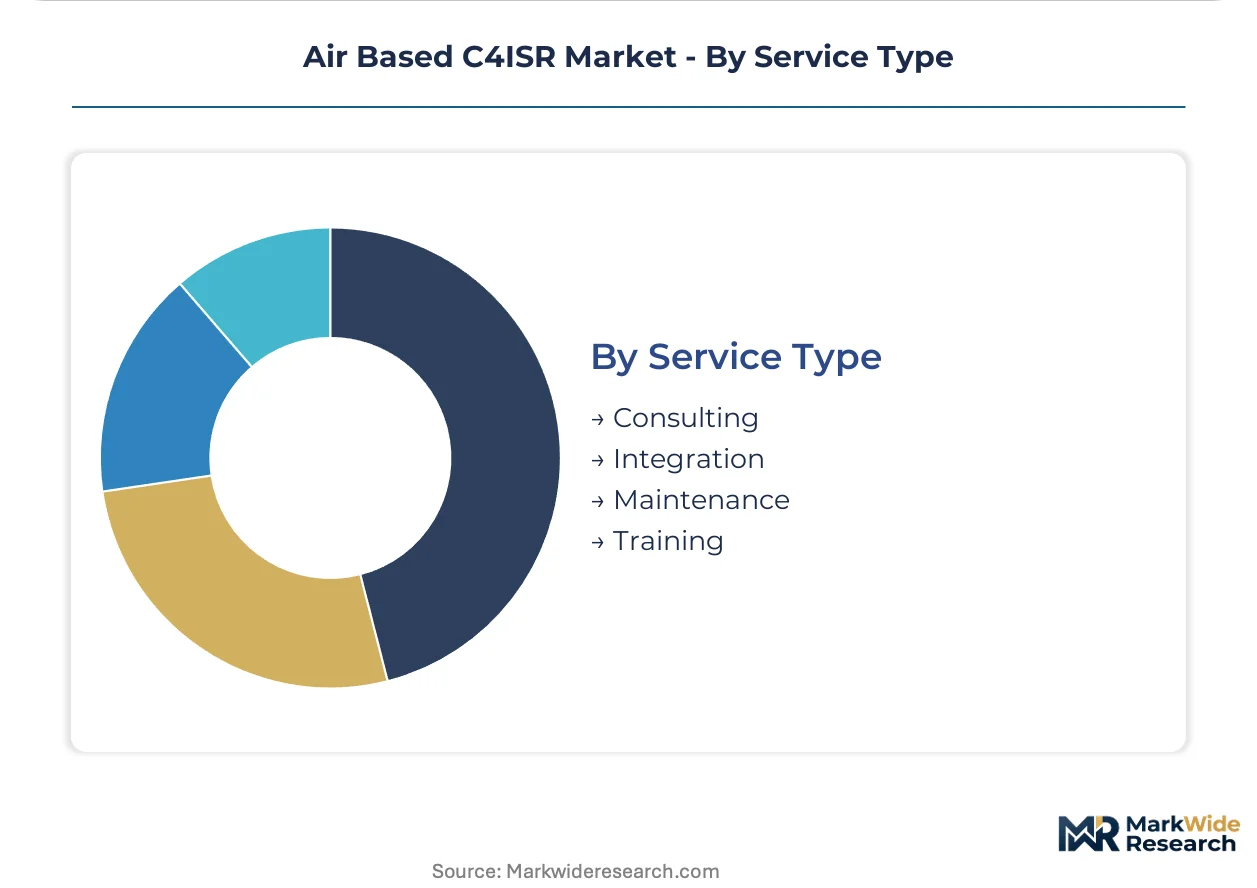
Margin distribution favors integration and maintenance over consulting, with proprietary battle management software creating vendor lock-in that complicates joint force interoperability.
- Integration:Third-party payload certification on manned aircraft requires FAA Supplemental Type Certificate processes that conflict with accelerated defense procurement timelines.
- Maintenance:Contractor-owned/contractor-operated platforms dominate orbits in US Southern Command areas, shifting obsolescence risk from government to vendor.
- Consulting:Systems engineering support for JADC2 compatibility with Cold War-era command and control aircraft drives middleware development demand.
- Training:TS/SCI-cleared workforce scarcity around Fort Meade and Palmdale constrains program scaling for specialized operator instruction.
Integration commands premium pricing today; maintenance revenue is expanding most quickly through service-based contracting adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland outpaces Germany in NATO eastern flank procurement velocity, while Japan accelerates indigenous airborne sensor development. Canada leverages Arctic sovereignty missions to justify specialized platform investments.
United States
JADC2 architecture mandates compress development cycles across California and Texas aerospace clusters. The FAA's Part 89 remote identification standards reshape unmanned system certification pathways. Palmdale and Fort Worth sustain concentrated prime contractor integration activity for next-generation battle management platforms.
Poland
Foreign Military Financing accelerates indigenous airborne ISR capability building along NATO's eastern flank. The country's national defense procurement agency prioritizes STANAG-compatible datalink architectures for coalition interoperability. Warsaw and Rzeszów host emerging integration facilities serving Baltic regional requirements.
United Kingdom
Special operations commands bypass traditional Royal Air Force channels for dedicated intelligence platforms. Ministry of Defence standardization offices enforce open systems mandates for joint force compatibility. Greater London and Lancashire sustain concentrated systems engineering workforce pools for classified program execution.
Japan
Contested electromagnetic spectrum operations in the Indo-Pacific drive software-defined radio modernization. METI industrial policy directs domestic foundry capacity toward compound semiconductor substrates for radar applications. Nagoya and Komaki host specialized mission system integration for maritime patrol derivatives.
Israel
Export-oriented electronic warfare specialists capture medium-tier defense budget segments across NATO and Asia-Pacific markets. The country's national defense export control framework governs proprietary jamming algorithm transfers. Haifa and Beersheba sustain dense concentrations of signals intelligence engineering talent.
Air Based C4ISR Market Vendor Landscape
United States producers anchor the prime contractor tier; Israeli and European specialists hold differentiated positions in electronic warfare subsystems. Market structure concentrates around five dominant platform integrators controlling multi-billion dollar development programs. Two strategic archetypes predominate: vertically integrated warfare systems houses and payload-focused technology specialists. Competitive dynamics center on strategic partnerships for JADC2 interoperability certification and selective M&A to capture software-defined radio capabilities.
Within the integrated warfare systems tier, Lockheed Martin Corporation and Northrop Grumman Corporation represent consolidated platform architecture control. Elbit Systems Ltd. occupies a distinct position among specialists exporting electronic warfare suites to medium-tier defense budgets. RTX Corporation and L3Harris Technologies Inc. exemplify diversified component suppliers spanning radar, datalink, and signals intelligence subsystems. These named entities anchor archetype positions rather than exhaust competitive segmentation.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| BAE Systems PLC |
| L3Harris Technologies Inc. |
| RTX Corporation |
| Elbit Systems Ltd. |
| The Boeing Company |
| General Dynamics Corporation |
| Thales |
| Others |
Supply Flow & Price Mechanics
Gallium nitride substrate pricing indices cascade through airborne mission system manufacturing, compressing margins for radar and electronic warfare integrators while amplifying pricing power for compound semiconductor foundries in East Asian supply chains.
Pricing Analysis
Capacity additions in Japanese compound semiconductor foundries are reshaping price floors for high-performance radar substrates, though gallium nitride supply concentration in East Asia sustains premium tier pricing for military-grade specifications. Three-tier pricing structure across proprietary jamming algorithms, STANAG-compatible datalink architectures, and open-systems middleware separates defense prime contractors from subsystem specialists and commercial derivative platform providers. Cost compression in commercial unmanned systems segments is intensifying because FAA certification timelines force extended R&D amortization periods. Intelligence community buyers exhibit lowest price sensitivity due to mission-critical requirements, while private sector operators of modified business jet platforms demonstrate highest elasticity.
Supply Chain Analysis
Photoresist and advanced substrate supply rests on Japanese specialty chemical producers and Taiwanese gallium nitride foundries, with secondary dependencies on South Korean memory component manufacturers for edge computing architectures. Raw material feeds draw from rare earth processing facilities in China, precision optics from German and Israeli suppliers, and software-defined radio chipsets from US fabless designers. Single-source vulnerability in GaN substrate supply creates procurement risk exposure for prime contractors executing JADC2 platform refresh programs. Distribution runs through defense prime contractor integration facilities in California and Texas, with subsystem specialists delivering certified payloads through Foreign Military Financing channels to NATO eastern flank operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense contractors arbitrage labor cost differentials between cleared workforce clusters in Maryland and emerging engineering centers in Poland, exploiting regulatory harmonization across NATO standardization agreements to capture margin expansion.
For Market Incumbents: Deploy software-defined radio architecture licensing as a recurring revenue lever to counter margin erosion from hardware commoditization. Lockheed Martin and Northrop Grumman anchor platform integration bottlenecks through JADC2 certification control, while legacy middleware development for Cold War-era aircraft sustains service revenue attachments. Capacity addition in Polish integration facilities threatens geographic rent extraction from Palmdale and Fort Meade labor markets. For New Entrants and Emerging Players: AI-assisted sensor fusion at the edge offers technology-first entry into special operations command procurement channels bypassing traditional air force acquisition. Medium-tier NATO members in the Baltic region present most penetrable geographic white space, with Foreign Military Financing availability reducing customer credit risk. Go-to-market execution should anchor on STANAG 4586 interoperability certification as a coalition operations enabler. For Investors and Strategic Acquirers: Asymmetric upside sits with electronic warfare subsystem specialists possessing proprietary threat library update mechanisms and export-controlled jamming algorithm portfolios. Five-to-ten year viability hinges on software-defined architecture transitions displacing hardware-centric platform refresh cycles. Watch for FAA Part 89 waiver approvals for large unmanned systems as inflection signal for commercial derivative platform scaling.| Strategic Initiative | Industry Significance |
|---|---|
| JADC2 Interoperability Certification | Lockheed Martin and Northrop Grumman control platform integration bottlenecks through architecture mandates. |
| Software-Defined Radio Modernization | Elbit Systems and RTX Corporation capture recurring revenue via threat library update subscriptions. |
| Foreign Military Financing Expansion | Poland and Baltic states accelerate indigenous airborne ISR procurement through US security assistance. |
| GaN Substrate Supply Diversification | Japanese METI industrial policy directs domestic foundry investment toward radar applications. |
| Contractor-Owned Platform Orbits | US Africa Command and Southern Command shift risk to vendors through availability-based service models. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with program managers at defense prime contractors, systems engineers at subsystem specialists, procurement officers at NATO standardization offices, and intelligence community acquisition leads with secondary validation against FAA certification databases, DoD budget justification materials, SEC 10-K filings from named contractors, and NATO STANAG documentation repositories. Bottom-up platform delivery forecasts triangulated against top-down defense expenditure projections.
Segment-weighting applied differential growth assumptions across surveillance, electronic warfare, reconnaissance, and communication applications, with technology trajectories modeled for sensor fusion, radar, datalink, and satcom subsystems. End-user segmentation distinguished military branch procurement, defense contractor service models, government agency requirements, and private sector adoption patterns. CAGRs derived from platform refresh cycle analysis, JADC2 architecture rollout timelines, and Foreign Military Financing authorization trends across the projection horizon.
The model holds under sustained NATO interoperability mandates and FAA unmanned systems integration progress; deviation in gallium nitride supply chain disruption or TS/SCI-cleared workforce availability would shift platform delivery timelines. A small set of named triggers warrants ongoing watch: FAA Part 89 waiver approvals, Polish defense procurement acceleration, and software-defined radio export control modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ISR
Brazil C4ISR Market
ISR
Naval ISR Market
ISR
Synthetic Aperture Radar (SAR) Market
ISR
Land Based C4ISR Market
ISR
United States C4ISR Market
ISR
Asia-Pacific C4ISR Market
ISR
Europe C5ISR Market
ISR
Low Altitude Radar Market
ISR
Global Interferometric Synthetic Aperture Radar (Insar) Market
ISR
Infrared Suppression Systems Market
ISR
Intelligence Surveillance and Reconnaissance (ISR) Market
ISR
North America Airborne ISR Market
ISR
C6ISR Market
ISR
Active Phased Array Radar (APAR) Market
ISR
North America C5ISR Market
ISR
C4ISR Market