
 Europe Digital Radiology Market | 2026-2036
Europe Digital Radiology Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Digital Radiology Market Analytics
Buyer concentration among hospital networks is shifting toward centralized procurement consortia spanning multiple regions. Siemens Healthineers leverages its installed base across German university hospitals to sustain service revenue streams. Philips Healthcare anchors its position through integrated PACS-DICOM workflows that reduce radiologist reading times. GE HealthCare competes on detector manufacturing scale, controlling a significant share of flat-panel supply for European OEMs.
Digital radiology encompasses the acquisition, processing, storage, and transmission of medical images using electronic detectors with spatial resolution typically exceeding 2.5 line pairs per millimeter, replacing analog film-screen combinations to enable immediate image review and remote consultation. The technology serves primarily to accelerate diagnostic workflows and reduce radiation exposure in clinical settings. CT scan systems generate the largest revenue pool among product types due to replacement cycles of seven to ten years in high-throughput hospitals. Cloud-based solutions represent the fastest-expanding technology segment as imaging centers seek to offload storage infrastructure costs. Oncology applications command premium pricing among clinical segments, driven by precision staging requirements in multidisciplinary tumor boards.
The EU Medical Device Regulation (MDR) and CE marking framework govern market access, with notified bodies extending review timelines for software-as-medical-device classifications including AI-assisted detection algorithms. The F-Gas Regulation constrains cooling system choices for MRI superconducting magnets, pushing manufacturers toward closed-loop helium recovery designs. Stakeholders must monitor evolving MDR guidance on machine-learning-based diagnostic tools to anticipate conformity assessment pathways.
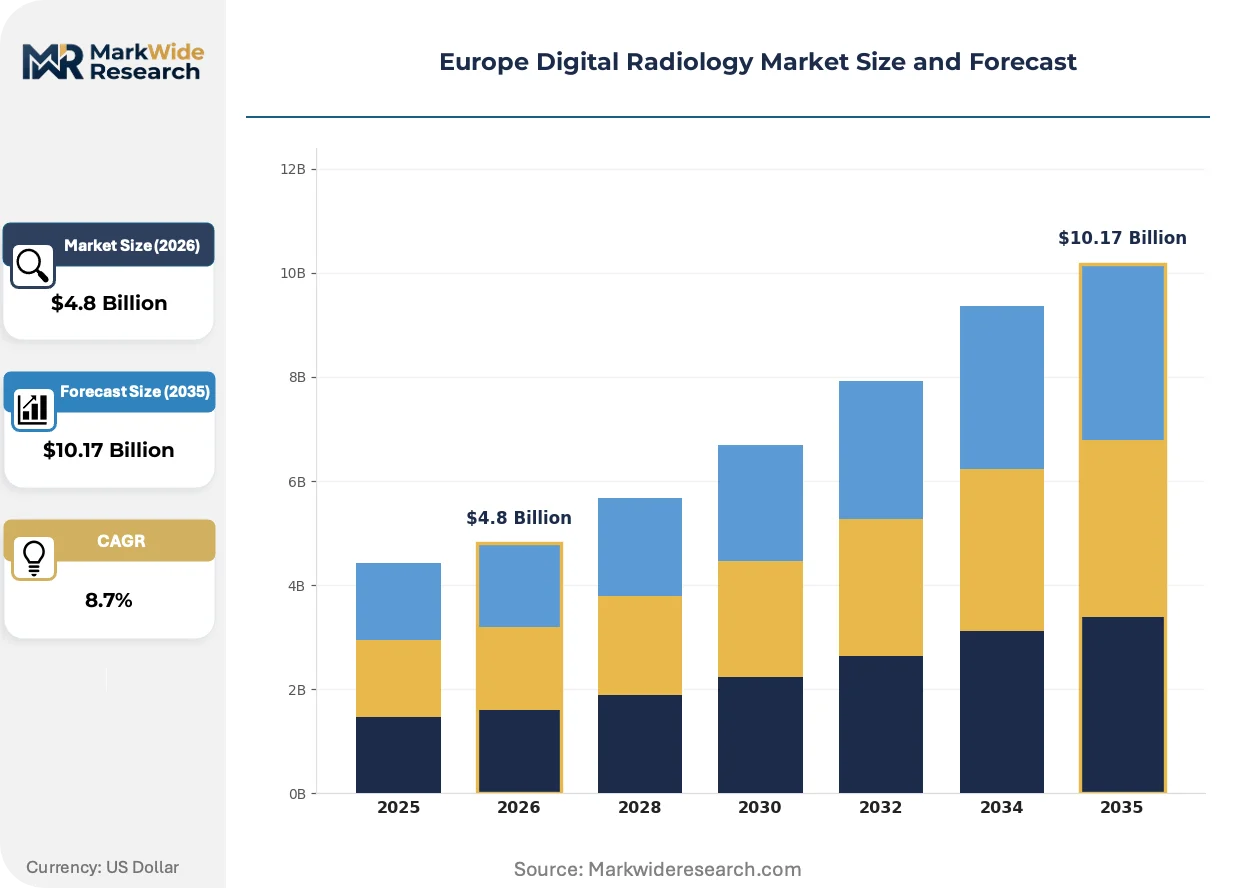
Market Dynamics
Hospital procurement consortia across Germany and France are consolidating purchasing power, compressing vendor margins while accelerating replacement cycles for AI-integrated imaging suites. The EU Medical Device Regulation tightens software classification pathways, forcing manufacturers to restructure conformity assessment timelines.
Growth Catalysts
- MDR Software Classification:The EU Medical Device Regulation creates structured pathways for AI-assisted detection algorithms, enabling faster market authorization for validated diagnostic tools across tertiary care networks.
- Helium Recovery Mandates:The F-Gas Regulation constrains conventional cooling systems, pushing manufacturers toward closed-loop helium recovery designs that reduce operational costs for MRI installations.
- Tertiary Care Consolidation:Western European university hospital networks are centralizing radiology infrastructure investments, creating volume concentration that justifies premium AI-integrated system deployments.
Market Restraints
- Notified Body Bottlenecks:CE marking review timelines for software-as-medical-device classifications have extended substantially under MDR implementation, delaying product launches.
- Flat-Panel Supply Concentration:Detector manufacturing capacity concentrates among limited specialized suppliers, creating input vulnerability for European OEMs dependent on external flat-panel sourcing.
- Seven-to-Ten Year Replacement Cycles:CT scan systems in high-throughput hospitals operate on extended depreciation schedules, compressing near-term revenue visibility for equipment vendors.
Strategic Opportunities
- Eastern European Imaging Centers:Poland and Romania present underpenetrated demand for cloud-based PACS infrastructure, offering first-mover positioning for off-premise storage solutions.
- Oncology Precision Staging:Multidisciplinary tumor boards command premium pricing for advanced visualization tools, creating high-margin application specialization.
- AI-DICOM Convergence:Machine learning algorithms integrated directly into DICOM workflows reduce radiologist reading times, enabling outcome-based service differentiation.
Industry Challenges
- Interoperability Fragmentation:Legacy PACS installations across European hospital networks resist seamless integration with cloud-native architectures, complicating system migrations.
- Radiologist Workflow Disruption:AI-assisted detection tools require substantial retraining investment, creating adoption friction among senior clinical staff accustomed to conventional reading protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Digital Radiology Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray, CT Scan, MRI, Ultrasound End User: Hospitals, Imaging Centers, Research Institutions, Clinics Technology: DICOM, PACS, Cloud-Based Solutions, AI Integration Application: Oncology, Orthopedics, Cardiology, Neurology |
| Companies Covered | Agfa HealthCare, Siemens Healthineers, Philips Healthcare, GE HealthCare, Canon Medical Systems, Fujifilm Europe, Konica Minolta Healthcare, Carestream Health, DRGEM Europe, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Digital Radiology Market Evolving Landscape
Artificial intelligence is embedding into diagnostic workflows at the acquisition layer, compressing the gap between image capture and actionable insight. Three developments are restructuring how imaging value flows through European healthcare systems.
Photon-counting CT detectors are integrating into next-generation scanner architectures, replacing energy-integrating detectors to enable spectral resolution at lower radiation doses. German university hospitals are piloting these systems for cardiac and pulmonary applications. The technology is integrating tissue characterization capabilities that previously required dual-energy protocols, collapsing diagnostic steps into single acquisition sequences.
The EU AI Act establishes risk-based classification for machine-learning diagnostic tools, mandating conformity assessments for high-risk applications before CE marking. Imaging software vendors must now document training data provenance and algorithmic transparency to satisfy notified body review. Oncology screening modules face the most stringent documentation requirements, driving consolidation among developers with established clinical validation libraries.
Centralized procurement consortia are unbundling equipment purchasing from long-term service agreements, forcing vendors to compete on discrete performance metrics rather than bundled relationships. French hospital networks pioneered this model, with German regional purchasing alliances now adopting similar structures. Radiology departments in the Benelux region are extending this unbundling to cloud storage contracts, separating image archiving from modality maintenance.
Europe Digital Radiology Market Segmentation
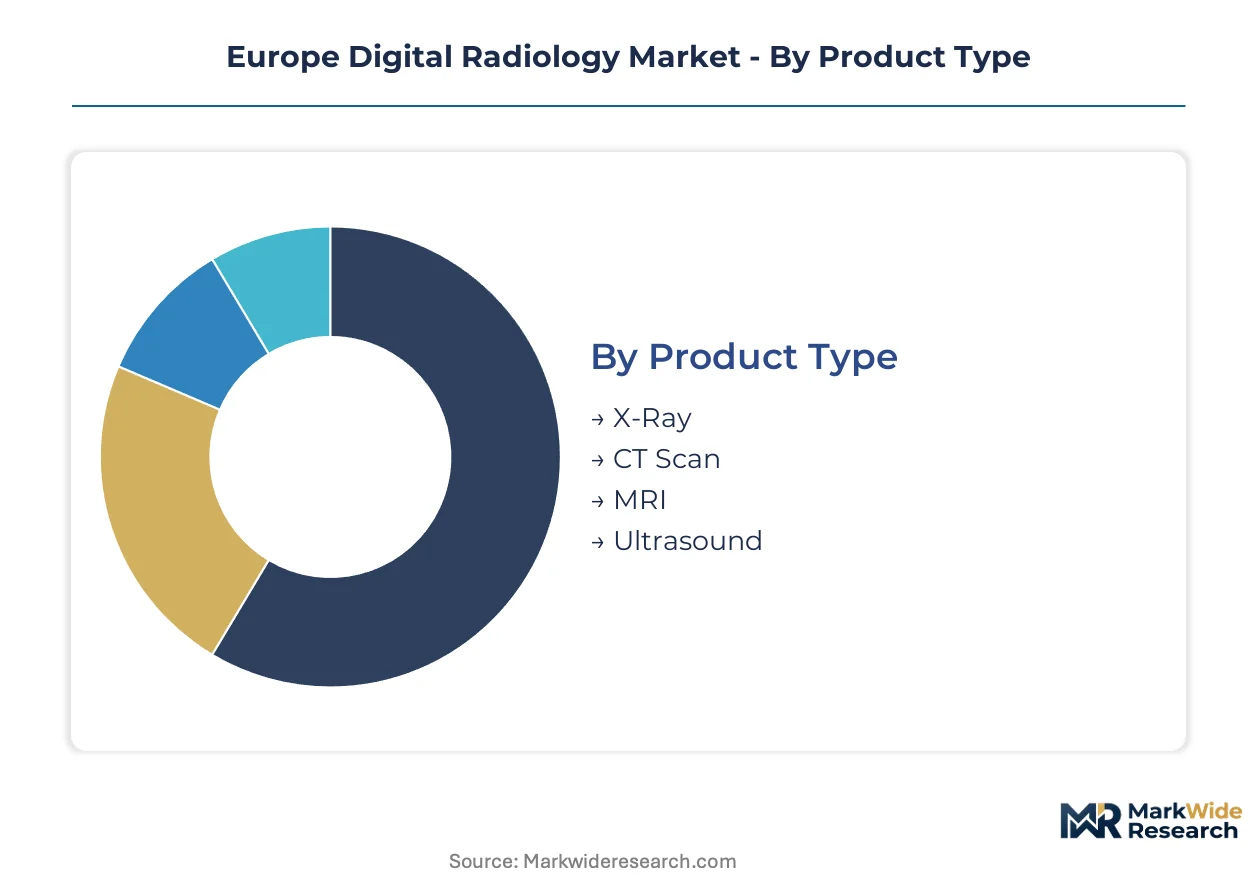
Segmentation in the Europe Digital Radiology Market reveals distinct investment profiles and regulatory exposure across equipment categories. Understanding these divisions enables vendors to align R&D budgets with procurement patterns and compliance requirements.
Product Type:
Capital intensity varies sharply across modalities, with infrastructure requirements dictating hospital budget allocation and replacement timelines.
- CT Scan:These systems integrate rotating X-ray tubes with multi-row detector arrays to generate cross-sectional volumetric data at sub-millimeter resolution. German and French university hospital networks are consolidating procurement of photon-counting CT architectures to reduce radiation exposure in cardiac protocols. CT scan systems absorb the bulk of installed capacity; cloud-based solutions are expanding most quickly.
- MRI:Superconducting magnets operating at 1.5 to 3 Tesla generate detailed soft-tissue contrast through radiofrequency pulse sequences. The F-Gas Regulation is pushing installations toward closed-loop helium recovery designs across tertiary care centers in the Benelux region.
- X-Ray:Flat-panel detectors capture projection radiographs with immediate digital output, serving high-throughput emergency departments.
- Ultrasound:Piezoelectric transducers emit acoustic waves for real-time imaging without ionizing radiation, dominating point-of-care diagnostics.
CT scan systems command the largest capital outlays per unit; MRI installations face steepest operational cost pressures from helium supply constraints.
End User:
Procurement authority concentrates differently across customer types, shaping contract structures and service bundling strategies.
- Hospitals:Acute care facilities operate comprehensive radiology departments with 24/7 coverage requirements and multidisciplinary tumor board integration. Centralized procurement consortia across Germany and France are unbundling equipment purchases from long-term service agreements.
- Imaging Centers:Dedicated outpatient facilities prioritize throughput optimization and PACS-DICOM workflow efficiency to maximize scanner utilization rates.
- Research Institutions:University hospitals and academic medical centers demand spectral imaging capabilities and AI validation environments for clinical trials.
- Clinics:Smaller outpatient settings favor compact digital X-ray systems with cloud archiving to minimize on-site infrastructure.
Hospital networks dominate installed base volume; imaging centers are climbing the fastest as independent operators consolidate across Eastern Europe.
Technology:
Technology layers stack from foundational data standards through intelligent analytics, each tier requiring distinct compliance pathways under EU MDR.
- AI Integration:Machine learning algorithms embedded at the acquisition layer enable automated detection and quantification of pathological findings. The EU AI Act mandates risk-based conformity assessments for oncology screening modules, extending notified body review timelines.
- Cloud-Based Solutions:Off-premise storage architectures transfer capital expenditure to operational models while enabling remote consultation networks. Polish and Romanian imaging centers present underpenetrated demand for these infrastructures.
- PACS:Picture archiving and communication systems manage image storage, retrieval, and distribution across hospital networks.
- DICOM:The standard protocol ensures interoperability between modalities and information systems, forming the backbone of digital workflow integration.
DICOM and PACS constitute the foundational installed base; AI integration is gaining share fastest as MDR pathways clarify for software-as-medical-device classifications.
Application:
Clinical specialization drives pricing differentiation through precision requirements and reimbursement intensity.
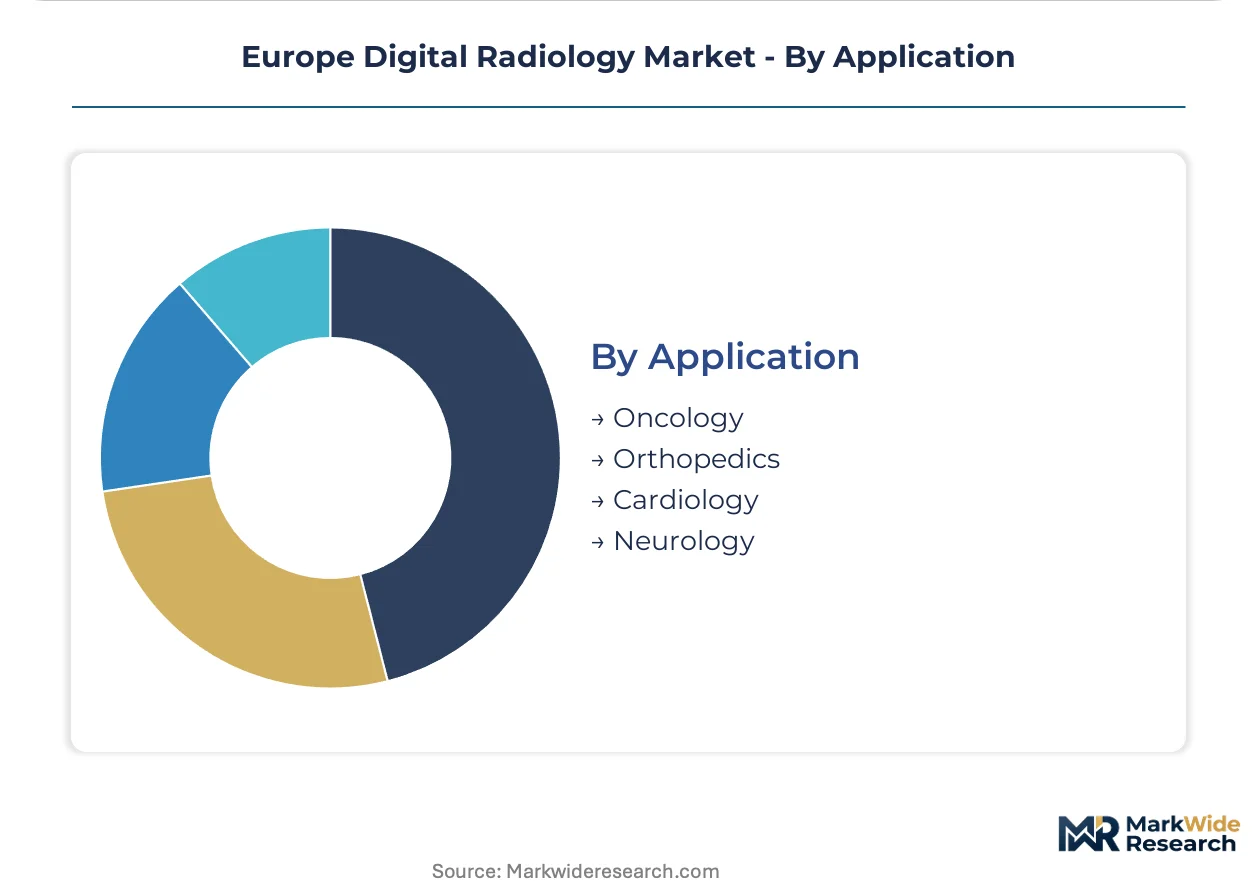
- Oncology:Multidisciplinary tumor boards demand advanced visualization tools for precision staging, with AI-assisted detection commanding premium pricing. The EU AI Act imposes stringent documentation requirements on screening algorithms, favoring developers with established clinical validation libraries.
- Cardiology:Cardiac CT and MRI protocols require temporal resolution sufficient to freeze coronary motion, driving adoption of photon-counting detector technology.
- Neurology:Brain imaging prioritizes soft-tissue contrast and functional mapping capabilities for stroke and neurodegenerative assessment.
- Orthopedics:Musculoskeletal applications emphasize weight-bearing imaging and 3D reconstruction for surgical planning.
Oncology captures the highest margin concentration; cardiology is expanding most quickly as photon-counting CT penetrates German pilot sites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Western European tertiary care networks consolidating procurement of AI-integrated imaging suites. Hospital consortia across Germany and France are unbundling equipment purchases from service agreements. Eastern European imaging centers present underpenetrated demand for cloud-based infrastructure.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia are piloting photon-counting CT systems for cardiac protocols. The F-Gas Regulation pushes MRI installations toward closed-loop helium recovery designs. Siemens Healthineers anchors its installed base across German university hospitals to sustain service revenue streams.
France
French hospital networks pioneered unbundling equipment procurement from long-term service contracts. The EU Medical Device Regulation tightens CE marking pathways for AI-assisted detection algorithms. Paris-based tertiary centers command premium pricing for oncology precision staging tools integrated into multidisciplinary tumor boards.
United Kingdom
NHS England is consolidating radiology infrastructure investments across regional imaging networks. The UK Medicines and Healthcare products Regulatory Agency aligns with EU MDR software classification frameworks post-Brexit. London and Greater Manchester clusters drive demand for PACS-DICOM workflow integration to reduce radiologist reading times.
Netherlands
Benelux radiology departments are extending procurement unbundling to cloud storage contracts separating image archiving from modality maintenance. The EU AI Act mandates risk-based conformity assessments for high-risk diagnostic applications. Eindhoven and Randstad regions concentrate imaging center consolidation for off-premise storage solutions.
Poland
Polish imaging centers present underpenetrated demand for cloud-based PACS infrastructure as independent operators consolidate. The EU Medical Device Regulation extends notified body review timelines for software-as-medical-device classifications. Warsaw and Krakow metropolitan areas anchor Eastern European expansion for remote consultation networks.
Europe Digital Radiology Market Competitive Landscape
German producers anchor one tier in detector manufacturing and integrated system architectures; Japanese and US specialists hold positions in flat-panel supply and AI-integrated workflows. The vendor base organizes around three strategic archetypes: diversified conglomerates with captive detector production, imaging specialists focused on PACS-DICOM convergence, and component suppliers controlling flat-panel supply for European OEMs. M&A activity concentrates on AI software acquisitions and strategic partnerships for cloud-native architectures.
Within the diversified conglomerate tier, Siemens Healthineers and Philips Healthcare exemplify integrated system providers leveraging installed base relationships across European hospital networks. GE HealthCare occupies a position among detector manufacturing specialists controlling significant flat-panel supply capacity for regional OEMs. These three anchors represent distinct competitive vectors: German-engineered hardware platforms, Dutch-integrated workflow solutions, and US-scale component supply.
| Leading Market Players |
|---|
| Agfa HealthCare |
| Siemens Healthineers |
| Philips Healthcare |
| GE HealthCare |
| Canon Medical Systems |
| Fujifilm Europe |
| Konica Minolta Healthcare |
| Carestream Health |
| DRGEM Europe |
| Others |
Value Network & Pricing Analysis
Specialized radiology software engineers concentrated in Germany and the Netherlands command compensation premiums that widen pricing spreads between AI-integrated suites and standard imaging systems. Labor-cost differentials between Western European development hubs and Eastern European service centers translate into three-tier pricing structures that segment buyers by digital maturity and compliance requirements.
Pricing Analysis
Volume concentrates in CT replacement cycles while margins accrue to AI-integrated oncology modules. Three-tier pricing structure across premium, standard, and economy levels separates photon-counting CT architectures with embedded detection algorithms from conventional detector arrays and refurbished legacy systems. Price differentiation hinges on CE marking tier under MDR software classifications and after-sales service bundling. Pricing pressure stems from centralized procurement consortia unbundling equipment from long-term maintenance contracts. Hospital networks in France and Germany exhibit lowest price sensitivity for precision staging tools; independent imaging centers in Poland and Romania demand economy-tier cloud archiving solutions.
Supply Chain Analysis
Dual-sourcing mandates from German university hospital networks require qualified suppliers for both flat-panel detectors and superconducting magnet components. Manufacturing concentrates in Germany, Japan, and the United States for detector arrays, helium recovery systems, and AI training infrastructure. Component dependencies include rare-earth elements for scintillator crystals, liquid helium for MRI cooling, and specialized ASICs for photon-counting signal processing. Single-source vulnerability concentrates in flat-panel detector supply for European OEMs lacking captive manufacturing. Distribution runs through authorized service networks with regional parts depots supporting 24-hour uptime commitments for tertiary care centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
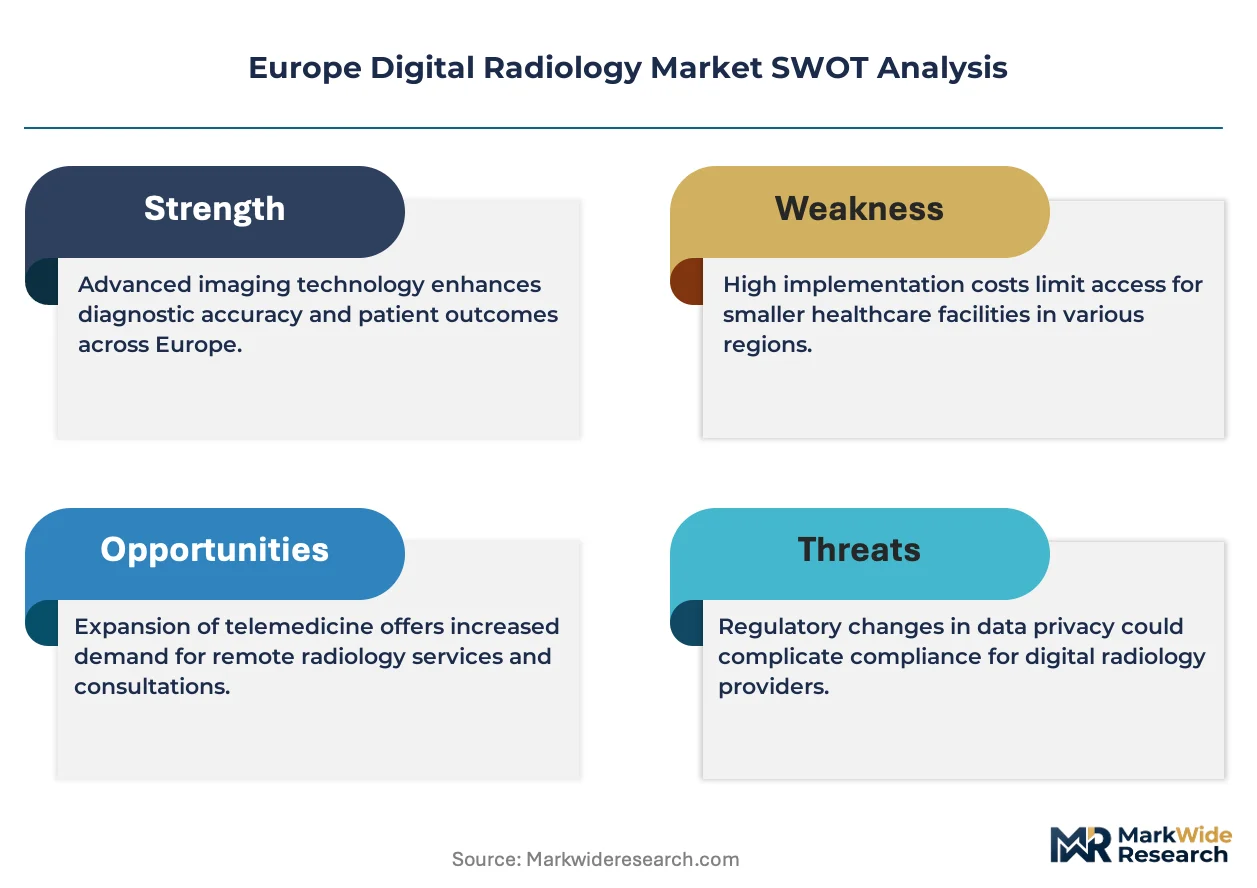
The Europe Digital Radiology Market functions as a cost-of-compliance arena where MDR software classification pathways erect barrier-to-entry moats favoring incumbents with established notified body relationships and clinical validation libraries.
For Market Incumbents: To counter margin compression from unbundled procurement contracts, deepen service revenue capture through predictive maintenance algorithms tied to detector performance monitoring. Anchor position by acquiring cloud-native PACS specialists to control workflow integration layers that resist displacement. For New Entrants and Emerging Players: Begin with cloud-based PACS infrastructure deployments in Polish and Romanian imaging centers where incumbent presence remains thin. Target independent operators consolidating across Eastern Europe with subscription pricing that converts capital expenditure to operational models. Pursue partnership routes with regional purchasing alliances rather than direct hospital sales. For Investors and Strategic Acquirers: The window for entry favors AI software developers with MDR-validated oncology screening modules and documented training data provenance. Mid-cap specialists with closed-loop helium recovery IP present acquisition appeal as F-Gas Regulation enforcement tightens. Watch notified body capacity expansion as the signal indicating authorization velocity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR software classification accelerates market authorization for validated diagnostic tools across tertiary networks. |
| Hospital System Partnership | Integrated PACS-DICOM workflows reduce radiologist reading times and lock in long-term service relationships. |
| Software Companion Development | AI algorithms embedded at acquisition layer compress diagnostic steps and command premium pricing in oncology. |
| Reimbursement Strategy | Precision staging alignment with multidisciplinary tumor boards secures favorable procurement decisions. |
| Strategic Partnership | Cloud-native architectures enable Eastern European imaging centers to offload storage infrastructure costs. |
Research Methodology
Multi-period observation of hospital procurement patterns, MDR implementation timelines, and AI algorithm authorization rates anchored the trend analysis, supplemented by interviews with radiology department heads, biomedical engineers, GPO contracts managers, and notified body technical assessors. Secondary validation drew from EMA guidance documents, EU Medical Device Coordination Group reports, hospital procurement databases, and F-Gas Regulation enforcement notices. Bottom-up equipment shipment tracking and top-down healthcare expenditure analysis were triangulated against vendor-reported installed base metrics.
Input-output matrices mapped modality-level demand drivers through technology adoption curves, regulatory compliance thresholds, and replacement cycle dynamics across the projection horizon. Segmentation dimensions modeled include product type, end-user facility scale, deployment architecture, and clinical application intensity. CAGRs were derived from curve-fitting approaches against historical replacement patterns and forward-looking procurement intention surveys. Forecast inputs incorporated helium supply constraints under F-Gas Regulation and AI Act risk-classification implementation pacing.
Underlying measurement precision varies by segment; CT scan and MRI equipment categories carry tighter precision than emerging cloud-based solutions due to established reporting channels. Forecasts reflect assumptions regarding notified body capacity expansion and tertiary care consolidation velocity. Deviation in MDR software classification guidance or AI Act enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Medical Imaging Workstation Market
Medical Imaging
Medical X-Ray Equipment and Imaging Software Market
Medical Imaging
India Digital Radiology Market
Medical Imaging
Cryo-Electron Microscopy Market
Medical Imaging
US Magnetic Resonance Angiography Market
Medical Imaging
Germany Digital Pathology Market
Medical Imaging
US Gadolinium-Based Contrast Media Market
Medical Imaging
South Korea Nuclear Imaging Market
Medical Imaging
Multiphoton Microscopy Market
Medical Imaging
Dental Diagnostic Imaging Equipment Market
Medical Imaging
Handheld Ultrasound Scanners Market
Medical Imaging
X-Ray Flat Panel Detectors Market
Medical Imaging
Refurbished Medical Imaging Devices Market
Medical Imaging
Australia Mammography Market
Medical Imaging
Europe Diagnostic Imaging Equipment Market
Medical Imaging
Medical Hyperspectral Imaging Market