
 China Nose Reconstruction Market | 2026-2036
China Nose Reconstruction Market Size, Share, and Industry Trends Forecast 2026-2036
China Nose Reconstruction Market Insights
The hospital end-use vertical is hardening as the dominant demand channel for nasal reconstruction across China's tier-one cities. Stryker Corporation leverages its orthopedic and craniomaxillofacial portfolio to sustain premium positioning in high-volume municipal hospitals. Allergan (AbbVie) anchors its presence through injectable filler lines that compete directly with domestic biologic substitutes. Surgiform Technology Ltd. specializes in porous polyethylene implant manufacturing, differentiating through cost structures that undercut imported alternatives.
Nose reconstruction encompasses surgical restoration of nasal form and function using autologous grafts, alloplastic implants, or injectable materials to correct congenital deformities, trauma defects, or aesthetic concerns. Polyetheretherketone and porous polyethylene implants withstand mechanical stress while permitting tissue ingrowth, making them standard for structural rib graft alternatives. Rhinoplasty implants and injectable fillers capture the deepest margin pools as recurring-consumable categories with shorter replacement cycles than capital equipment. Minimally invasive techniques and endoscopic surgery are expanding fastest among technology segments, driven by reduced recovery times and outpatient eligibility under China's DRG payment reforms.
China's NMPA regulates implantable medical devices under Class III registration requirements, while GB standards govern biocompatibility testing protocols that domestic manufacturers must satisfy. The country's dual carbon goals pressure hospital procurement committees to evaluate supply chain emissions from imported polymer implants against locally produced alternatives. Stakeholders must monitor how provincial centralized procurement expansions reshape pricing power for premium implant suppliers versus domestic challengers.
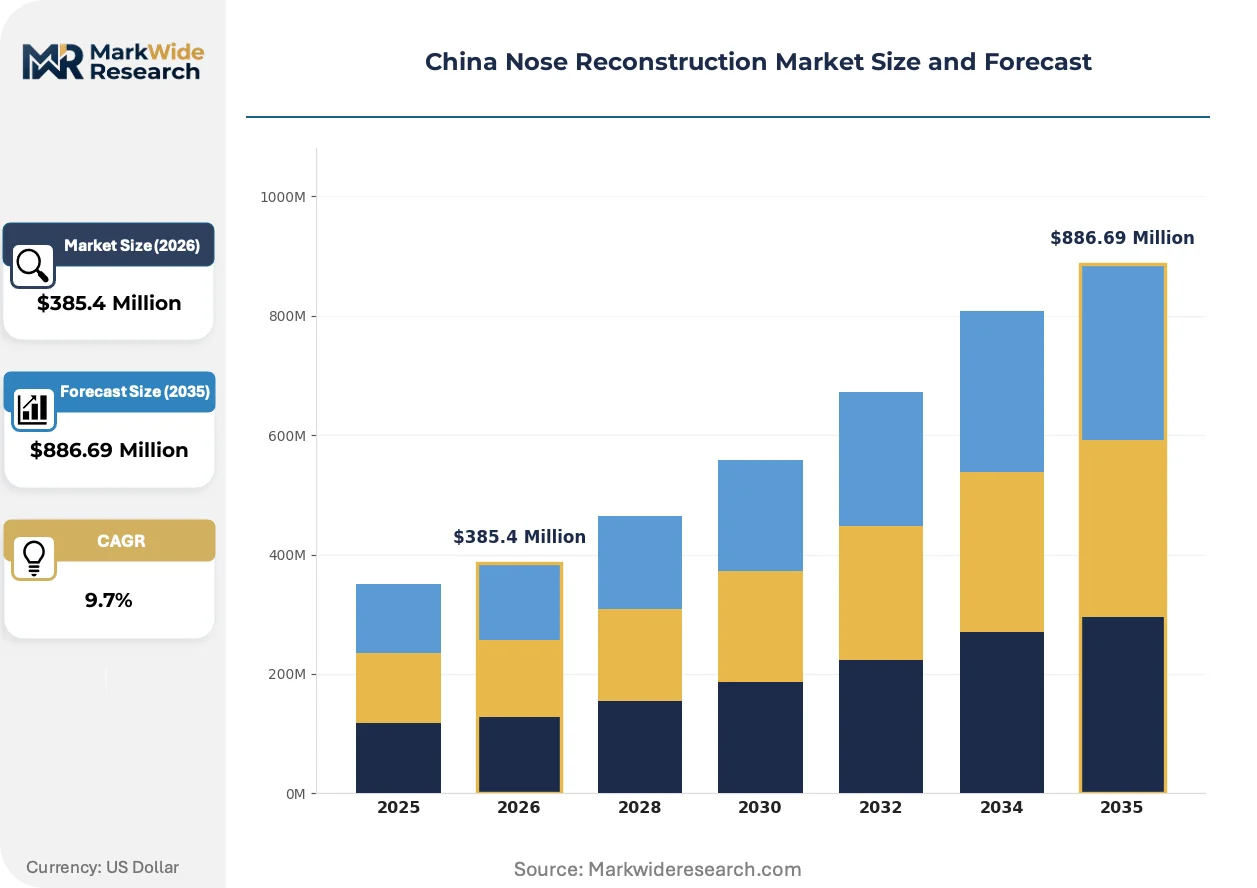
Market Dynamics
China's DRG payment reforms are compressing hospital reimbursement windows for nasal reconstruction procedures, forcing adoption of same-day discharge protocols and outpatient-compatible techniques across Shanghai and Beijing's tertiary centers.
Growth Catalysts
- Dual carbon goals:China's national emissions targets pressure municipal hospitals to favor domestically manufactured synthetic implants over carbon-intensive imported biologics.
- Minimally invasive endoscopic techniques:Reduced recovery timelines align with DRG cost containment, accelerating uptake in tier-one municipal hospitals.
- Shanghai cosmetic surgery corridors:Concentrated demand from high-income patient pools sustains premium procedure volumes despite pricing pressures elsewhere.
Market Restraints
- PEEK and porous polyethylene import dependency:Structural polymer supply concentrates among US and European specialty chemical producers, exposing domestic implant fabricators to raw material cost volatility.
- NMPA Class III registration timelines:Extended biocompatibility testing under GB standards delays market entry for novel implant geometries.
- Autologous rib graft persistence:Surgeon training pathways and patient preference for natural tissue substitutes constrain alloplastic implant penetration in reconstructive indications.
Strategic Opportunities
- Provincial centralized procurement expansion:Tier-two and tier-three city hospital networks remain underpenetrated for premium synthetic implants, creating volume opportunities for cost-optimized domestic suppliers.
- Injectable filler maintenance cycles:Recurring-consumable hyaluronic acid and calcium hydroxylapatite formulations offer annuity revenue streams absent from permanent implant categories.
- MEE environmental compliance incentives:Green manufacturing certifications for low-emission polymer processing unlock preferential procurement scoring in state-owned hospital systems.
Industry Challenges
- Craniomaxillofacial surgical specialization gaps:Fellowship-trained rhinoplasty surgeons concentrate in Beijing and Shanghai, limiting procedure standardization across provincial capitals.
- Legacy hospital information system integration:DRG coding and episode-based billing software requires costly upgrades to capture minimally invasive procedure complexity accurately.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Nose Reconstruction Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $886.69 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rhinoplasty Implants, Injectable Fillers, Surgical Instruments, Biologics Technology: 3D Printing, Minimally Invasive Techniques, Endoscopic Surgery, Augmented Reality End User: Clinics, Hospitals, Ambulatory Surgical Centers, Research Institutions Delivery Mode: Outpatient, Inpatient, Telemedicine, Hybrid Care |
| Companies Covered | Sihuan Pharmaceutical Holdings Group Ltd., Stryker Corporation, Allergan (AbbVie), NOUVAG, Koken, Surgiform Technology Ltd., ANTHONY PRODUCTS INC., Luminera, SATELEC (Actongroup), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Nose Reconstruction Market Trends and Innovations
Digital surgical planning and patient-specific implant design are reconfiguring competitive advantage away from standardized product catalogs toward software-integrated hardware ecosystems in China's nasal reconstruction sector.
Patient-specific porous polyethylene implants fabricated via CAD/CAM milling are consolidating structural rhinoplasty workflows around centralized manufacturing hubs. Tertiary hospitals in Beijing now mandate preoperative virtual surgical planning for complex revision cases. This consolidation is compressing lead times for custom implant production while raising capital barriers for smaller domestic fabricators lacking five-axis machining capacity.
NMPA's 2023 technical review guidelines for implantable medical devices now mandate extended biocompatibility testing for all new polymer formulations entering Class III registration. Domestic manufacturers face 18-24 month approval cycles versus 12-15 months for established materials. Porous polyethylene implant suppliers with grandfathered GB standard certifications are accelerating product line extensions ahead of anticipated testing requirement expansions.
Hospital procurement committees in Shanghai's municipal health bureau are unbundling implant supply from surgical service contracts, enabling direct vendor relationships previously intermediated by department chiefs. This disintermediation exposes price transparency across competing PEEK and silicone implant suppliers. The shift is most visible in high-volume cosmetic rhinoplasty centers where annual implant purchasing exceeds 500 units.
China Nose Reconstruction Market Segmentation
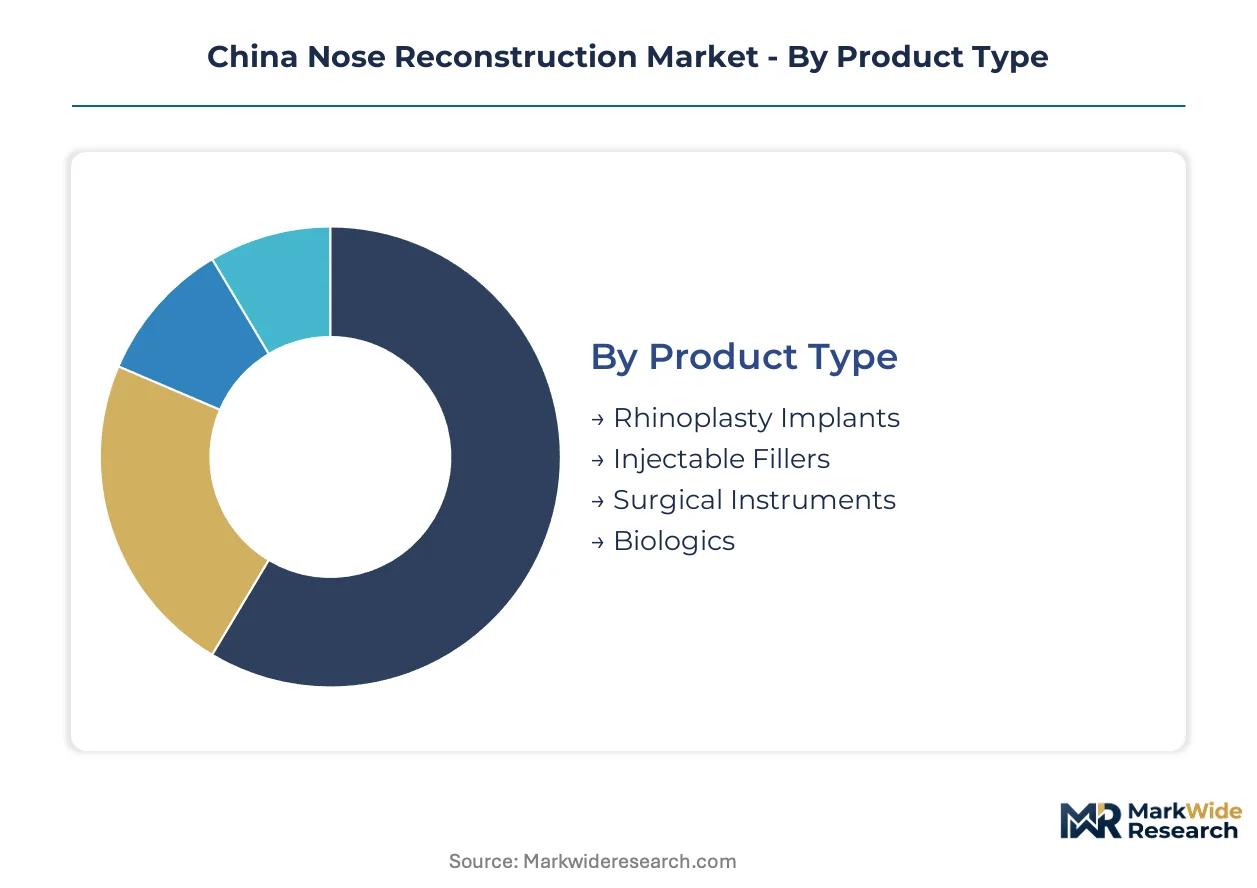
Segmentation in China's nasal reconstruction market reveals how procurement committees balance clinical outcomes against DRG reimbursement constraints. Each dimension exposes different pressure points where domestic suppliers can displace premium imports.
Product Type:
Hospital procurement committees prioritize consumable replenishment cycles and biocompatibility certification status when allocating budgets across implant categories.
- Rhinoplasty Implants:Structural porous polyethylene and PEEK constructs provide permanent dorsal augmentation and columellar support. Shanghai's tertiary cosmetic surgery corridors drive premium volumes for patient-specific CAD/CAM-milled geometries despite NMPA Class III registration burdens.
- Injectable Fillers:Hyaluronic acid and calcium hydroxylapatite formulations enable non-surgical nasal contouring with 12-18 month maintenance intervals. Beijing's outpatient aesthetic clinics capture recurring revenue streams absent from permanent implant categories.
- Surgical Instruments:Rhinoplasty-specific osteotomes, rasps, and nasal speculums constitute capital equipment with 5-7 year replacement cycles.
- Biologics:Allograft and xenograft-derived materials face tightening NMPA oversight, accelerating hospital shifts toward synthetic alternatives.
Rhinoplasty implants lead on scale; injectable fillers lead on momentum.
Technology:
Technology adoption correlates directly with surgeon training density and hospital capital expenditure approval thresholds.
- Minimally Invasive Techniques:Closed rhinoplasty and percutaneous filler injection protocols reduce operative time and enable same-day discharge. Municipal hospitals in tier-one cities accelerate uptake to align with DRG cost containment mandates.
- Endoscopic Surgery:Transnasal endoscopic visualization improves precision in revision cases and structural graft placement. Beijing's craniomaxillofacial centers mandate endoscopic assistance for complex septorhinoplasty procedures.
- 3D Printing:Titanium and PEEK powder-bed fusion enables patient-specific implant fabrication with porosity gradients matching native bone mechanics.
- Augmented Reality:Surgical navigation overlays project preoperative planning data onto live operative fields, requiring integration with legacy hospital information systems.
Endoscopic surgery anchors current procedural volume; augmented reality climbs the fastest as training infrastructure matures.
End User:
Facility type determines reimbursement pathway eligibility and implant procurement autonomy.
- Hospitals:Tertiary municipal centers in Shanghai and Beijing concentrate fellowship-trained rhinoplasty surgeons and maintain direct vendor relationships for high-volume implant purchasing. NMPA Class III device registrations and centralized procurement committee oversight govern supplier selection.
- Clinics:Private cosmetic surgery clinics in specialized urban corridors capture aesthetic rhinoplasty demand outside public hospital queues. Injectable fillers dominate product mix due to lower regulatory barriers and faster patient turnover.
- Ambulatory Surgical Centers:Same-day discharge protocols under DRG reforms expand eligibility for minimally invasive nasal procedures.
- Research Institutions:Academic medical centers pilot novel implant materials and surgical techniques under clinical trial frameworks.
Hospitals dominate absolute procedure volume; clinics gain share fastest as aesthetic demand outpaces reconstructive case growth.
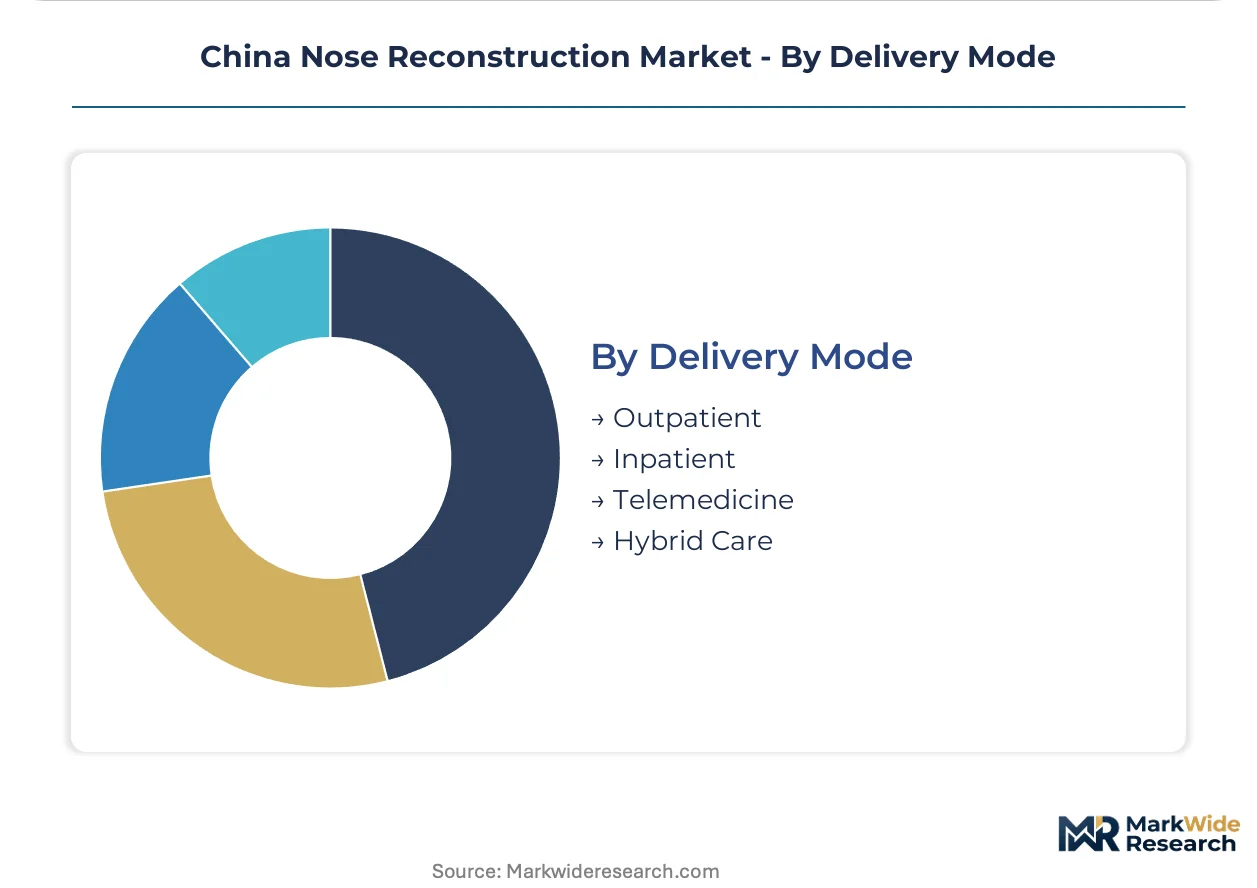
Delivery Mode:
Reimbursement classification and episode-based billing complexity shape channel preference.
- Outpatient:Injectable filler procedures and minor revision surgeries qualify for ambulatory reimbursement codes. Shanghai's municipal health bureau expanded outpatient eligibility for rhinoplasty procedures under DRG pilot programs.
- Inpatient:Complex reconstructive cases requiring rib graft harvest or alloplastic implant placement mandate overnight observation. Beijing's tertiary centers maintain inpatient capacity for revision rhinoplasty with structural complications.
- Telemedicine:Preoperative consultation and postoperative follow-up migrate to video platforms, reducing geographic access barriers for provincial patients.
- Hybrid Care:Virtual surgical planning combined with in-person operative execution consolidates expertise from centralized manufacturing hubs with distributed patient access.
Inpatient delivery retains structural case concentration; outpatient protocols expand most quickly as same-day discharge standardizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic implant fabricators exploit cost-of-compliance gaps as NMPA Class III registration timelines stretch approval cycles for novel materials. Manufacturing gravity shifts toward polymer-processing clusters with established GB standards certification infrastructure.
Beijing-Tianjin-Hebei
Craniomaxillofacial surgical specialization concentrates in Beijing's tertiary medical centers, driving demand for patient-specific CAD/CAM-milled implants. NMPA technical review guidelines mandate extended biocompatibility testing for new polymer formulations. Municipal health bureaus pilot DRG episode-based billing for outpatient rhinoplasty procedures.
Yangtze River Delta
Shanghai's cosmetic surgery corridors sustain premium procedure volumes through high-income patient pools seeking aesthetic nasal reconstruction. Centralized procurement committees unbundle implant supply from surgical service contracts, exposing price transparency. Porous polyethylene implant manufacturing clusters around Suzhou and Wuxi exploit established GB standards infrastructure.
Pearl River Delta
Guangzhou and Shenzhen private cosmetic surgery clinics capture aesthetic demand outside public hospital queues, favoring injectable filler protocols with faster patient turnover. Dual carbon goals pressure procurement committees to evaluate supply chain emissions from imported polymer implants. Dongguan polymer processing hubs supply domestic implant fabricators with PEEK and porous polyethylene raw materials.
Sichuan-Chongqing
Chengdu's expanding tertiary hospital network attracts fellowship-trained rhinoplasty surgeons from coastal provinces, expanding reconstructive case capacity. Provincial centralized procurement expansion creates volume opportunities for cost-optimized domestic suppliers. Chongqing's medical device manufacturing base develops captive polymer processing capabilities to reduce import dependency.
Shandong Peninsula
Qingdao and Jinan municipal hospitals adopt minimally invasive endoscopic techniques to align with DRG cost containment mandates. MEE environmental compliance incentives reward green manufacturing certifications for low-emission polymer processing. Regional implant fabricators leverage Shandong's chemical industry base to secure structural polymer supply chains.
China Nose Reconstruction Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium implant suppliers defending position through NMPA registration depth while domestic challengers exploit cost structures. Market structure tilts toward consolidation at the premium tier and fragmentation among regional fabricators. Three archetypes dominate: multinational orthopedic portfolios, domestic polymer specialists, and injectable filler platforms. Capacity expansion and strategic partnerships represent the dominant competitive moves as players navigate centralized procurement expansion.
Among multinational orthopedic and craniomaxillofacial portfolios, Stryker Corporation and Allergan (AbbVie) occupy positions exemplifying premium-tier positioning through established NMPA Class III registrations and direct hospital vendor relationships. Domestic specialists anchor the cost-optimized segment, with Surgiform Technology Ltd. representing the porous polyethylene implant fabrication archetype that undercuts imported alternatives through localized manufacturing. Sihuan Pharmaceutical Holdings Group Ltd. sits within the diversified healthcare conglomerate tier, leveraging cross-divisional regulatory expertise to navigate extended biocompatibility testing timelines.
| Leading Market Players |
|---|
| Sihuan Pharmaceutical Holdings Group Ltd. |
| Stryker Corporation |
| Allergan (AbbVie) |
| NOUVAG |
| Koken |
| Surgiform Technology Ltd. |
| ANTHONY PRODUCTS INC. |
| Luminera |
| SATELEC (Actongroup) |
| Others |
Pricing and Supply Chain Analysis
China's dual carbon goals gate qualified supply for premium-tier implant manufacturers while compressing procurement budgets across municipal hospital systems. NMPA Class III registration depth separates pricing power between established multinationals and domestic challengers facing extended biocompatibility testing timelines.
Pricing Analysis
Distributor margin layers concentrate in provincial centralized procurement committees that unbundle implant supply from surgical service contracts. Three-tier pricing structure across premium, standard, and economy levels stratifies by NMPA registration vintage and CAD/CAM customization capability. Cost compression in mid-tier porous polyethylene implants intensifies as Suzhou and Wuxi fabricators exploit localized polymer processing. Clinics in Guangzhou and Shenzhen exhibit highest price sensitivity due to filler-dominated product mixes, while Beijing's tertiary centers absorb premium patient-specific implant markups.
Supply Chain Analysis
Single-source vulnerability sits with US and European specialty chemical producers of medical-grade PEEK and porous polyethylene feedstock. Domestic implant fabricators draw from Dongguan polymer processing hubs and Shandong's chemical industry base, yet remain tethered to imported structural polymer supply. Tariff exposure runs through craniomaxillofacial device categories subject to trade policy friction. Distribution runs through direct vendor relationships with Shanghai and Beijing municipal hospital procurement committees, bypassing traditional department chief intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's nose reconstruction market compounds steadily through DRG payment reform tailwinds that standardize outpatient eligibility and consumable replenishment cycles.
For Market Incumbents: To counter domestic challenger cost structures, deepen NMPA Class III registration moats through extended biocompatibility testing investments and secure captive polymer supply via backward integration into Dongguan processing partnerships. Anchor direct procurement relationships with Shanghai municipal health bureau unbundling initiatives.
For New Entrants and Emerging Players: Enter via tier-two and tier-three city hospital networks underpenetrated for patient-specific CAD/CAM-milled implants, exploiting provincial centralized procurement expansion and MEE green manufacturing certification incentives. Target Chengdu and Chongqing reconstructive case growth as fellowship-trained surgeon migration accelerates.
For Investors and Strategic Acquirers: Roll-up economics work for domestic porous polyethylene specialists because NMPA registration timelines and five-axis machining capacity create acquisition currency for scale-challenged fabricators. Monitor surgeon training pipeline expansion into Sichuan-Chongqing and Shandong Peninsula as inflection signal for procedural volume migration.
| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Class III Registration Acceleration | Extended biocompatibility testing investments compress approval timelines against GB standards mandates. |
| Provincial Centralized Procurement Partnership | Direct vendor relationships with tier-two hospital networks displace department chief intermediation. |
| Green Manufacturing Certification | MEE environmental compliance unlocks preferential scoring in state-owned hospital procurement. |
| Patient-Specific CAD/CAM Capacity Expansion | Five-axis machining hubs consolidate complex revision case workflows around centralized manufacturing. |
| Injectable Filler Platform Integration | Recurring-consumable hyaluronic acid formulations capture annuity revenue absent from permanent implants. |
Research Methodology
Coverage spans Beijing-Tianjin-Hebei, Yangtze River Delta, Pearl River Delta, Sichuan-Chongqing, and Shandong Peninsula, with primary inputs from each. Conversations with hospital procurement committee directors, craniomaxillofacial surgeons, biomedical engineers, GPO contracts managers, and domestic implant fabricator executives combined with NMPA registration filings, hospital procurement databases, customs polymer trade data, and municipal health bureau DRG pilot disclosures. Bottom-up procedure volume estimates and top-down implant shipment data triangulate market sizing.
Rate-of-change decomposition separates volume growth from pricing dynamics across the analysis window. Segmentation dimensions modeled include product type, technology adoption tier, end-user facility category, and delivery mode reimbursement pathway. CAGRs derive from surgeon training pipeline trajectories, DRG expansion schedules, and NMPA regulatory timeline assumptions. Industry-specific inputs incorporate porous polyethylene raw material cost volatility and centralized procurement committee unbundling velocity.
Inputs from NMPA registration databases and municipal health bureau procurement disclosures were available through the study window; gaps in private clinic transaction data introduce uncertainty bands around aesthetic procedure estimates. Forecasts reflect documented assumptions regarding DRG pilot expansion and dual carbon goal enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Tetanus Treatment Market
Medical Treatment
Nasal Allergy Treatment Market
Medical Treatment
Hypercoagulability Treatment Market
Medical Treatment
Stereotactic Body Radiation Therapy Market
Medical Treatment
Vaginitis Treatment Drugs Market
Medical Treatment
Migraine Treatment Market
Medical Treatment
Anorectal Malformation Treatment Market
Medical Treatment
Systemic Sclerosis Treatment Market
Medical Treatment
Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
Seropositive Rheumatoid Arthritis Treatment Market
Medical Treatment
Hyperammonemia Treatment Market
Medical Treatment
Tendonitis Treatment Market
Medical Treatment
Sepsis Treatment Market
Medical Treatment
Lysosomal Acid Lipase (LAL) Deficiency Treatment Market
Medical Treatment
Radioimmunotherapy Treatment Market
Medical Treatment
Peri-Implantitis Treatment Market