
 Hand-Held X-Rays Market | 2026-2036
Hand-Held X-Rays Market Size, Share, and Industry Trends Forecast 2026-2036
Hand-Held X-Rays Market Foresight
High-resolution digital imaging is rotating the Hand-Held X-Rays Market toward premium-tier specifications that command stronger pricing. GE Healthcare leverages its installed base of hospital radiology departments to cross-sell portable units. Siemens Healthineers anchors its position through R&D intensity in wireless detector integration. Fujifilm Holdings Corporation specializes in battery-powered architectures that reduce thermal load during extended field use.
Hand-held x-rays are self-contained, battery-operated ionizing radiation devices that generate diagnostic images at tube voltages typically ranging from 50–90 kVp, employing solid-state detectors or imaging plates for immediate digital capture without fixed darkroom infrastructure. Their primary purpose is to deliver radiographic diagnostics at the point of care, eliminating patient transport to centralized radiology suites. Portable X-Ray Systems dominate current revenue as hospitals prioritize fleet standardization, while Digital X-Ray Devices represent the fastest-expanding segment due to immediate DICOM compatibility and elimination of chemical processing. Emergency Services as an end-user category commands disproportionate margin pools because military and disaster-response procurement tolerates premium pricing for ruggedized, NATO-compliant hardware.
FDA 21 CFR Part 1020 governs radiation safety and leakage limits for diagnostic x-ray equipment sold in the United States, directly shaping product design cycles and compliance costs for manufacturers seeking market access. The EU MDR and CE marking requirements impose parallel clinical evidence obligations that filter out undercapitalized competitors from European distribution channels. Stakeholders must monitor evolving cybersecurity mandates for networked imaging devices, as wireless connectivity becomes standard and exposes portable units to hospital IT governance frameworks that previously excluded mobile equipment.
Market Dynamics
The hand-held X-rays market is experiencing structural compression as solid-state detector technology collapses the cost-performance frontier, forcing manufacturers to recalibrate value capture around software integration and wireless workflow rather than hardware premiums alone.
Growth Catalysts
- Point-of-care imaging mandates:Ambulatory surgical centers in Germany are retrofitting mobile radiography suites to reduce patient transport delays. CMS reimbursement incentives in the United States reward same-site diagnostic completion.
- FDA 21 CFR Part 1020:Tightening shielding and dose requirements are accelerating replacement cycles for legacy fixed systems with compliant portable alternatives. Manufacturers redesign tube housings to meet leakage limits.
- Battery chemistry advances:Lithium-sulfur cell architectures are extending field operation windows without thermal degradation. Military procurement specifications now require NATO-compliant ruggedized hardware for disaster response deployment.
Market Restraints
- Scintillator material concentration:Cesium iodide and gadolinium oxysulfide supply chains cluster in East Asian processing facilities. Geopolitical friction threatens detector substrate availability.
- Radiation safety liability exposure:Malpractice insurers impose premium surcharges on operators lacking documented ALARA protocols. Small dental clinics face coverage gaps.
- Fixed-installation substitution:Ceiling-suspended DR systems retain cost advantages for high-throughput hospital radiology departments. Volume economics favor centralized suites for scheduled imaging.
Strategic Opportunities
- Veterinary dentistry expansion:Companion animal practices in Australia represent underpenetrated demand for intraoral radiography. Species-specific positioning accessories command margin premiums.
- EU MDR Article 10 clinical evidence pathways:Streamlined equivalence arguments for iterative hardware revisions reduce regulatory burden. Notified body capacity constraints filter undercapitalized competitors.
- Telemedicine integration:DICOM-compliant hand-held units with embedded 5G modems enable real-time specialist consultation. Rural health networks in Brazil leverage this for teleradiology coverage.
Industry Challenges
- Medical physics workforce scarcity:Qualified radiation safety officers are concentrated in metropolitan hospital systems. Exurban clinics struggle to staff required compliance oversight.
- Cybersecurity certification complexity:FDA premarket submission pathways for networked devices now require documented threat modeling. Small manufacturers lack in-house information security expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hand-Held X-Rays Market |
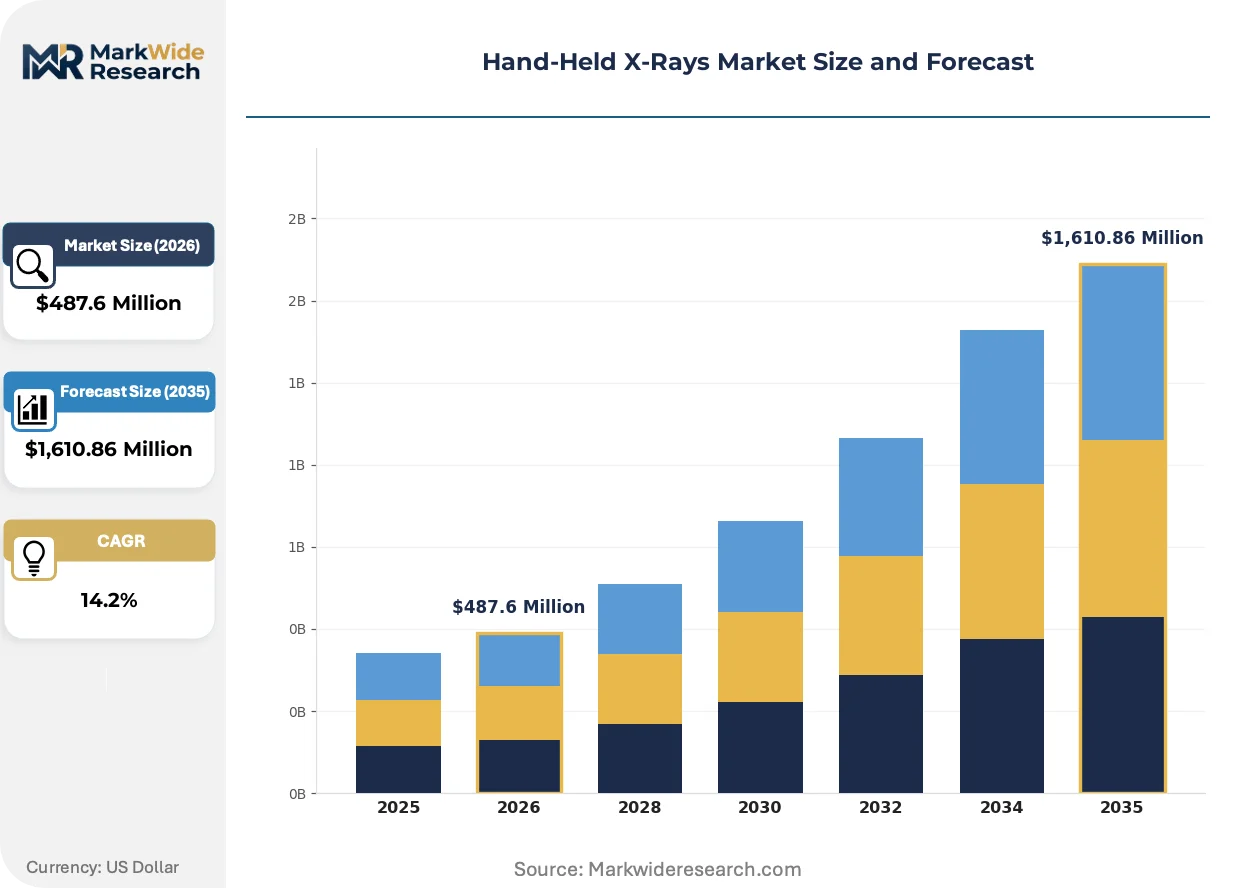
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,610.86 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable X-Ray Systems, Digital X-Ray Devices, Battery-Powered Units, Imaging Solutions End User: Dentists, Orthopedic Surgeons, Emergency Services, Veterinary Clinics Application: Bone Imaging, Dental Diagnostics, Emergency Assessment, On-Site Inspections Technology: Computed Radiography, Direct Radiography, Wireless Imaging, Image Processing |
| Companies Covered | GE Healthcare, Siemens Healthineers, Philips Healthcare, Carestream Health, Dental Imaging Technologies Corporation, Genoray, Fujifilm Holdings Corporation, Shimadzu Corporation, VATECH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hand-Held X-Rays Market Shifts & Advancements
Wireless detector integration is collapsing the distinction between portable and fixed radiography, while artificial intelligence inference at the edge redefines real-time image quality assurance. These shifts are compressing traditional equipment procurement cycles.
CMOS flat-panel detectors with direct deposition scintillator layers are supplanting amorphous silicon indirect-conversion architectures in premium hand-held configurations. Emergency medical services fleets in the United States are adopting these units for field trauma assessment. The structural consequence is collapsing price tiers between hospital-grade and point-of-care specifications.
EU MDR CE marking requirements now mandate post-market clinical follow-up for Class IIa diagnostic imaging devices. Manufacturers must maintain periodic safety update reports and vigilance data. German ambulatory care networks are consolidating procurement to suppliers with established notified body relationships.
After-sales service contracts are unbundling from hardware purchase agreements as buyers seek operational expenditure flexibility. Independent service organizations are capturing maintenance revenue from original equipment manufacturers. This pattern is most pronounced among mid-sized dental clinic chains in the United Kingdom negotiating multi-site fleet management agreements.
Hand-Held X-Rays Market Segmentation
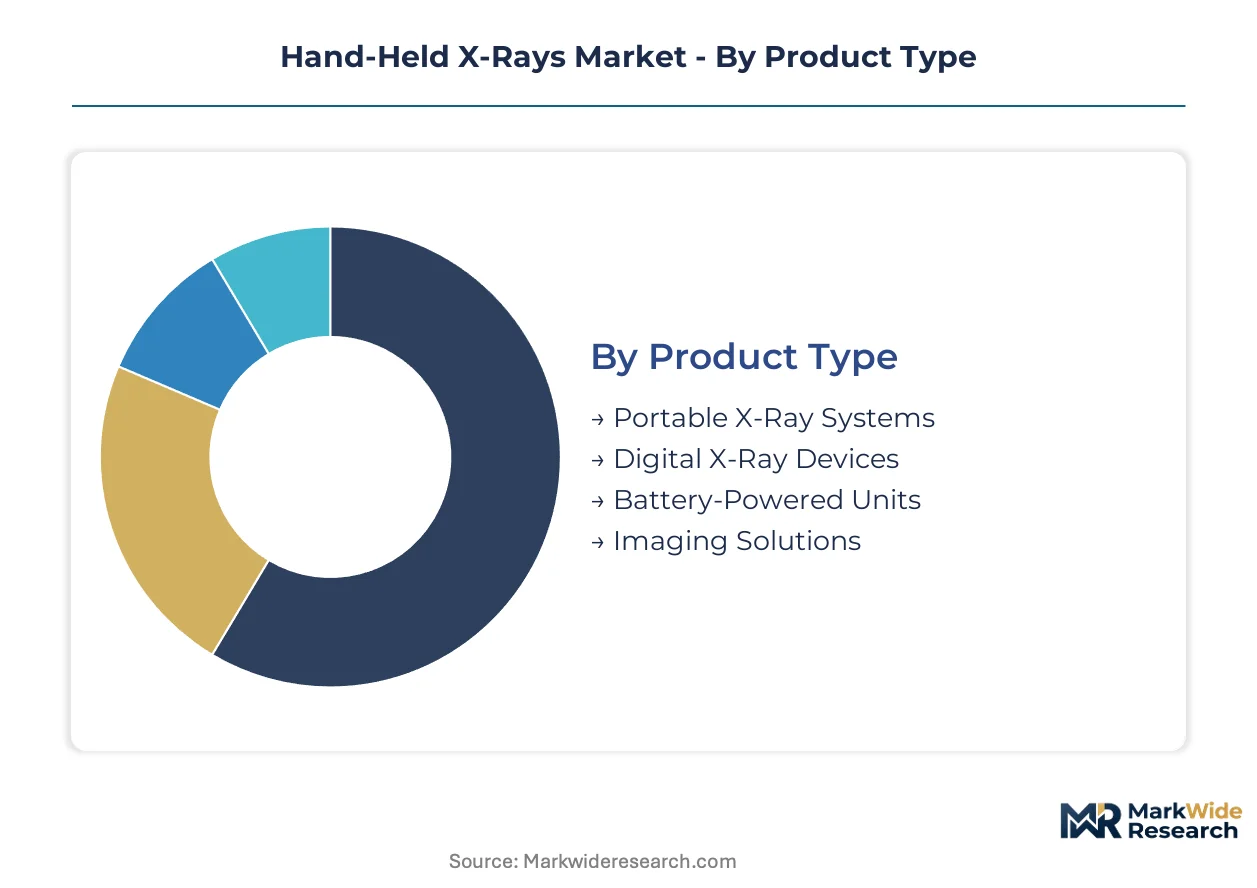
Segmentation in hand-held X-rays reveals divergent margin architectures across product tiers and end-use verticals. Procurement patterns vary sharply between institutional buyers optimizing fleet standardization and specialty practices seeking point-of-care autonomy.
Product Type:
Margin pools concentrate in configurations that eliminate infrastructure dependency and enable immediate digital workflow integration.
- Portable X-Ray Systems:Self-contained units with integrated high-voltage generators and collimator assemblies operate at 50–90 kVp without fixed electrical tethering. Hospital systems in the United States prioritize fleet standardization to reduce training overhead and spare parts proliferation. CMS reimbursement incentives reward same-site diagnostic completion, cementing institutional preference.
- Digital X-Ray Devices:Solid-state detector architectures with immediate DICOM compatibility eliminate chemical processing infrastructure. German ambulatory surgical centers are retrofitting mobile radiography suites with these units to compress patient throughput cycles. This segment is climbing the fastest as wireless workflow integration commands premium positioning.
- Battery-Powered Units:Lithium-sulfur cell architectures extend field operation windows without thermal degradation during extended trauma assessment.
- Imaging Solutions:Software-layer products encompassing acquisition protocols, post-processing algorithms, and PACS connectivity modules.
Portable X-Ray Systems hold installed capacity. Digital X-Ray Devices is rotating up the share rankings.
End User:
Customer-type stratification separates price-tolerant mission-critical procurement from cost-constrained private practice economics.
- Dentists:Intraoral radiography demand concentrates in expanding dental clinic chains across the United States seeking point-of-care imaging autonomy. ALARA protocol documentation requirements create compliance friction for smaller independent practices.
- Emergency Services:Military and disaster-response procurement tolerates premium pricing for ruggedized, NATO-compliant hardware with extended temperature operating ranges. Field trauma assessment protocols in United States EMS fleets are standardizing on CMOS flat-panel configurations.
- Orthopedic Surgeons:Ambulatory surgical center adoption in Germany targets intraoperative imaging without patient transport to centralized radiology suites.
- Veterinary Clinics:Companion animal practices in Australia represent underpenetrated demand for species-specific positioning accessories.
Emergency Services captures the steepest margin premiums. Dentists contributes the deepest volume base.
Application:
Use-case segmentation tracks the migration of imaging from scheduled centralized suites toward immediate diagnostic decision points.
- Bone Imaging:Extremity and trauma radiography at tube voltages optimized for cortical bone contrast. Orthopedic surgeons in ambulatory settings deploy hand-held units to eliminate patient transport delays.
- Emergency Assessment:Field trauma protocols requiring immediate image acquisition with wireless transmission to receiving hospitals. United States EMS fleet procurement specifications emphasize 5G modem integration for real-time specialist consultation.
- Dental Diagnostics:Intraoral bitewing and periapical imaging with reduced radiation exposure versus legacy film systems.
- On-Site Inspections:Industrial non-destructive testing and security screening applications outside medical regulated environments.
Bone Imaging anchors current procedure volume. Emergency Assessment is expanding most quickly as pre-hospital protocols mature.
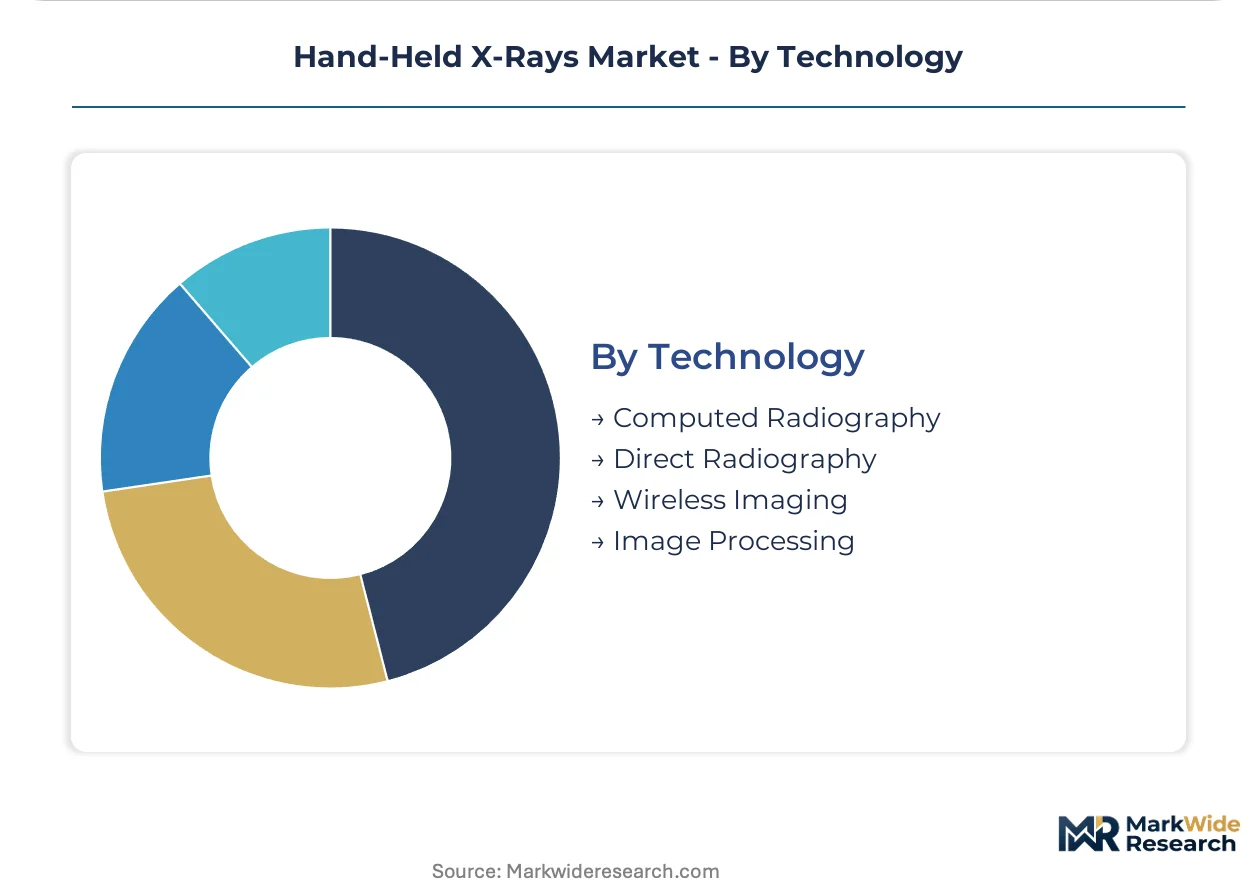
Technology:
Technology stratification reflects the displacement of analog intermediate steps by direct digital capture and wireless transmission architectures.
- Direct Radiography:CMOS and amorphous silicon flat-panel detectors with direct deposition scintillator layers achieve higher detective quantum efficiency than indirect-conversion alternatives. German ambulatory care networks are consolidating procurement toward suppliers with established EU MDR notified body relationships.
- Wireless Imaging:Embedded 5G and Wi-Fi 6E connectivity enables real-time DICOM transmission without physical detector tethering. Cybersecurity certification complexity under FDA premarket submission pathways filters smaller manufacturers lacking in-house information security expertise.
- Computed Radiography:Photostimulable phosphor plate systems requiring mechanical scanning infrastructure retain cost advantages in price-sensitive installations.
- Image Processing:Edge-based artificial intelligence inference for real-time quality assurance and automated exposure correction.
Direct Radiography commands technology premiums. Wireless Imaging is gaining share fastest as hospital IT governance frameworks expand to encompass mobile equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detector substrate processing clusters in East Asian facilities, yet ambulatory surgical center retrofitting and emergency response procurement drive demand across North America and Western Europe. Regulatory divergence between FDA 21 CFR Part 1020 and EU MDR compliance pathways shapes manufacturer market entry sequencing.
United States
Dental clinic chains expand point-of-care imaging autonomy to reduce patient referral leakage. FDA 21 CFR Part 1020 tightening of leakage limits accelerates replacement of legacy fixed systems in metropolitan hospital systems. Greater Boston medical device corridor hosts concentrated service contract negotiations for multi-site fleet standardization.
Germany
Ambulatory surgical centers retrofit mobile radiography suites to eliminate patient transport delays in orthopedic workflows. EU MDR Article 10 clinical evidence requirements filter undercapitalized competitors from distribution channels. Bavaria's medical technology cluster consolidates procurement toward suppliers with established notified body relationships.
Japan
Aging population demographics expand home healthcare imaging requirements for fracture assessment without hospital admission. PMDA regulatory pathways emphasize post-market surveillance for wireless-connected diagnostic devices. Kansai region manufacturing bases refine CMOS flat-panel detector architectures for premium hand-held configurations.
Australia
Companion animal veterinary practices drive underpenetrated demand for intraoral radiography with species-specific positioning accessories. TGA medical device regulations align with international harmonization frameworks for diagnostic imaging equipment. New South Wales metropolitan clinics negotiate multi-site fleet management agreements with independent service organizations.
Brazil
Rural health networks leverage 5G-enabled hand-held units for real-time teleradiology specialist consultation. ANVISA regulatory pathways require documented cybersecurity threat modeling for networked imaging devices. São Paulo state healthcare procurement aggregates demand for ruggedized emergency response hardware.
Hand-Held X-Rays Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics across the hand-held X-rays market. The vendor base separates into diversified medical imaging conglomerates, specialized dental radiography manufacturers, and regional equipment fabricators with price-competitive portfolios. Strategic archetypes include installed-base cross-sellers leveraging hospital radiology department relationships, wireless workflow specialists capturing ambulatory surgical center demand, and ruggedized hardware providers serving military and disaster-response procurement. Dominant competitive moves encompass strategic partnerships for detector technology licensing and geographic expansion through notified body relationship establishment in EU markets.
Within the diversified conglomerate tier, GE Healthcare and Siemens Healthineers exemplify players leveraging hospital radiology installed bases for portable unit cross-selling. Fujifilm Holdings Corporation occupies a position representing battery-powered architecture specialization. Among dedicated dental imaging specialists, Carestream Health and VATECH sit within the intraoral radiography segment. Genoray exemplifies the mid-tier specialist archetype serving price-sensitive clinic chains.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Philips Healthcare |
| Carestream Health |
| Dental Imaging Technologies Corporation |
| Genoray |
| Fujifilm Holdings Corporation |
| Shimadzu Corporation |
| VATECH |
| Others |
Supply & Pricing Matrix
Detector substrate fabrication scale in East Asian processing facilities anchors both cost floors and supplier pricing power across hand-held X-ray configurations. Capacity utilization at cesium iodide and gadolinium oxysulfide refineries directly determines component input costs that manufacturers either absorb or pass through to ambulatory surgical centers and dental clinic chains.
Pricing Analysis
FDA 21 CFR Part 1020 dictates the pricing tier structure across hand-held X-ray markets, with compliant tube housing and shielding architectures commanding premium positioning against legacy fixed-system alternatives. Three-tier pricing structure across premium, standard, and economy levels separates NATO-certified ruggedized units for military procurement from mid-tier wireless-enabled devices for hospital fleets and basic battery-powered configurations for independent dental practices. Cost compression in economy tiers is intensifying because CMOS flat-panel detector commoditization collapses hardware differentiation. Dental clinic chains exhibit highest price sensitivity due to malpractice insurance surcharge burdens, while emergency services procurement tolerates premium pricing for mission-critical field reliability.
Supply Chain Analysis
Strait of Malacca transit routes underpin critical cesium iodide crystal shipments from East Asian processing facilities to German detector assembly plants and United States OEM manufacturing corridors. Supply concentration clusters in Japan, South Korea, and China for scintillator substrate refining, with lithium-sulfur cell production anchored in South Korean battery chemistry facilities. Single-source vulnerability threatens detector substrate availability amid geopolitical friction over semiconductor-related export controls. Distribution runs through authorized medical device distributors with EU MDR notified body relationships, bypassing direct hospital procurement in consolidated European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hand-held X-rays represent high-growth medical device disruption as wireless detector integration and edge AI inference collapse the distinction between portable and fixed radiography, with FDA cybersecurity mandates for networked devices accelerating competitive filtering.
For Market Incumbents: Consolidate installed-base relationships through cross-selling portable units into hospital radiology departments already operating fixed DR systems, while deepening backward integration into CMOS flat-panel detector supply to offset scintillator material concentration risk from East Asian processors. Capture maintenance revenue from independent service organizations by unbundling after-sales contracts and offering operational expenditure flexibility to mid-sized dental clinic chains. For New Entrants and Emerging Players: Anchor in companion animal veterinary practices across Australia where intraoral radiography penetration remains underdeveloped and species-specific positioning accessories command margin premiums. Target rural health networks in Brazil leveraging 5G-enabled teleradiology integration as the most penetrable geography, with ANVISA cybersecurity documentation requirements creating barrier-to-entry advantages for prepared entrants. Pursue software-layer positioning through DICOM-compliant acquisition protocol licensing rather than capital-intensive hardware manufacturing. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among service-contract unbundlers capturing multi-site fleet management agreements from original equipment manufacturers. Long-term viability favors suppliers with established EU MDR notified body relationships and demonstrated post-market clinical follow-up capabilities for Class IIa diagnostic imaging devices. Monitor FDA premarket submission pathways for networked devices as the signal to watch for cybersecurity certification complexity filtering undercapitalized competitors.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR CE Marking Pathway | Streamlined equivalence arguments for iterative hardware revisions reduce regulatory burden for German ambulatory networks. |
| Hospital System Partnership | GE Healthcare leverages radiology department installed bases to cross-sell portable units with fleet standardization incentives. |
| Software Companion Development | Edge-based AI inference for real-time quality assurance differentiates premium-tier wireless detector configurations. |
| Backward Integration into Detectors | Captive supply of CMOS flat-panel architectures insulates against cesium iodide supply chain concentration risk. |
| Reimbursement Strategy | CMS same-site diagnostic completion incentives cement institutional preference for point-of-care imaging hardware. |
Research Methodology
The analysis maps portable X-ray systems, digital X-ray devices, battery-powered units, and imaging solutions software layers, each validated through biomedical engineers, hospital purchasing committee members, GPO contracts managers, and ambulatory surgical center procurement leads. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EU MDR notified body databases, CMS reimbursement schedules, and hospital procurement contract repositories. Bottom-up unit economics triangulate against top-down market sizing from installed base estimates and replacement cycle analysis.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation dimensions modeled include product type, end-user vertical, application use-case, and technology architecture with wireless connectivity tier. CAGRs derived from logistic adoption curves fitted to point-of-care imaging penetration rates, with forecast inputs incorporating battery chemistry advancement trajectories and regulatory compliance cost escalation for networked devices.
Decision-makers should treat outputs as directional under assumptions of continued FDA 21 CFR Part 1020 tightening and sustained EU MDR notified body capacity constraints; material deviation in scintillator material supply availability or cybersecurity certification timelines would warrant model refresh. Practitioners should keep alternative scenarios live as geopolitical friction over East Asian semiconductor processing evolves and lithium-sulfur cell commercialization timelines shift.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Medical X-Ray Films Market
Medical Imaging
Europe Nuclear Medicine Market
Medical Imaging
Cone Beam CT Scanner Market
Medical Imaging
Spain Mammography Market
Medical Imaging
Pre-Clinical Imaging System Market
Medical Imaging
Perfusion Radiology Market
Medical Imaging
Asia Pacific Computed Tomography (CT) Market
Medical Imaging
Global Mammography Systems Market
Medical Imaging
Wireless Ultrasound Scanner Market
Medical Imaging
Global Contrast Enhanced Digital Mammography (CEDM) Market
Medical Imaging
Germany Digital X-Ray Market
Medical Imaging
Latin America Medical Imaging Software Market
Medical Imaging
Asia-Pacific Digital Pathology Market
Medical Imaging
France Nuclear Imaging Market
Medical Imaging
Open System MRI Market
Medical Imaging
Japan Diagnostic Imaging Equipment Market