
 Italy Digital X-Ray Market | 2026-2036
Italy Digital X-Ray Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Digital X-Ray Market Foresight
Flat-panel detectors using cesium iodide scintillators is rebalancing cost structures against older amorphous selenium architectures. Siemens Healthineers leverages its installed base across Italian public hospitals to sustain service contract renewal rates. Villa Sistemi Medicali anchors its competitiveness through domestic manufacturing in Bologna, while Canon Medical Systems differentiates via specialized cardiovascular imaging configurations.
Italy digital x-ray equipment encompasses radiographic systems that convert x-ray photons into digital images through solid-state detector arrays, typically achieving spatial resolution between 2.5 and 5 line pairs per millimeter for diagnostic clarity. These systems eliminate chemical processing, enabling immediate image transmission to PACS networks for clinical decision support. Portable systems command expanding interest among outpatient clinics seeking point-of-care deployment flexibility, while direct radiography technology leads technology segment margins due to superior dose efficiency and throughput speed. Dental imaging applications represent the fastest-growing application niche, driven by private practice digitization mandates.
Italy's Ministry of Health enforces medical device registration through the national pharmaceutical regulator, while CE marking under the EU Medical Device Regulation governs market access for imported systems. Regional health authorities in Tuscany and Veneto layer additional procurement specifications that favor interoperable DICOM-compliant platforms. Stakeholders must monitor evolving AI-enabled diagnostic software classification rules that could reshape hardware-software bundling strategies and service revenue models.
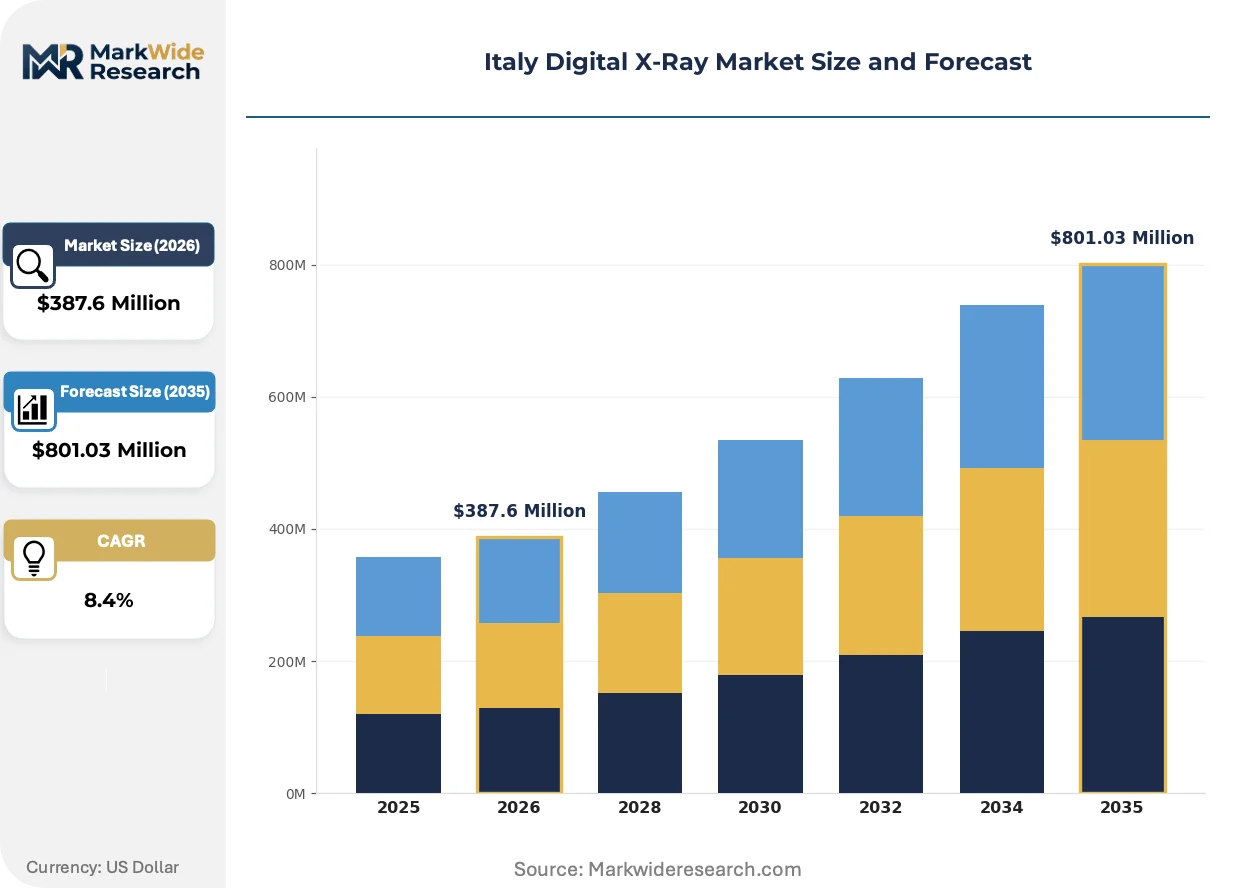
Market Dynamics
Italy's Ministry of Health reimbursement protocols are compressing analog-to-digital hybrid system margins while accelerating fully digital workflow adoption across hospital radiology departments and private diagnostic networks.
Growth Catalysts
- Reimbursement Protocol Realignment:Italy's Ministry of Health now favors fully digital workflows over analog-to-digital hybrid systems, redirecting capital allocation toward direct radiography platforms in hospital radiology departments.
- Private Diagnostic Network Expansion:Northern Italy's private diagnostic imaging center networks are consolidating procurement volumes, creating scale economies for flat-panel detector deployments.
- Cesium Iodide Scintillator Cost Rebalancing:Flat-panel detectors using cesium iodide scintillators are reducing per-exam operational costs against older amorphous selenium architectures, accelerating retrofit decisions in Lombardy and Piedmont facilities.
Market Restraints
- Detector Supply Concentration:Solid-state detector array manufacturing concentrates among East Asian component suppliers, exposing Italian system integrators to lead time volatility and currency fluctuation risk.
- CE Marking Compliance Burden:EU Medical Device Regulation technical documentation requirements extend product registration timelines by 8-14 months for imported direct radiography systems.
- Amorphous Selenium Stranded Assets:Facilities with recent amorphous selenium investments face accelerated obsolescence pressure as cesium iodide scintillator price-performance curves steepen.
Strategic Opportunities
- Outpatient Clinic Point-of-Care Deployment:Portable digital x-ray systems remain underpenetrated among Italy's independent outpatient clinics, particularly in Sicily and Calabria where fixed infrastructure investment lags northern regions.
- Dental Practice Digitization Mandates:Private dental practices across Veneto and Emilia-Romagna face regulatory digitization deadlines, creating concentrated demand for specialized intraoral and panoramic digital systems.
- AI-Enabled Diagnostic Software Convergence:Hardware-software bundling strategies around computer-aided detection algorithms present service revenue expansion paths beyond equipment sales.
Industry Challenges
- PACS Integration Complexity:Regional health authorities in Tuscany and Veneto impose additional DICOM interoperability specifications, forcing vendors to maintain multiple software configurations for Italian market access.
- Field Service Engineer Scarcity:Specialized training requirements for solid-state detector calibration and AI-software troubleshooting outpace technical workforce supply in southern Italy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Digital X-Ray Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $801.03 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary Systems, Portable Systems, Mobile Systems, Fluoroscopy Systems End User: Hospitals, Diagnostic Imaging Centers, Outpatient Clinics, Research Institutions Technology: Computed Radiography, Direct Radiography, Digital Tomosynthesis, 3D Imaging Application: Pediatric Imaging, Orthopedic Imaging, Cardiovascular Imaging, Dental Imaging |
| Companies Covered | Shimadzu Corporation, Villa Sistemi Medicali, Siemens Healthineers AG, Canon Medical Systems, Philips Healthcare, GE Healthcare, Carestream Health, Agfa-Gevaert Group, Fujifilm Holdings Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Digital X-Ray Market Shifts & Advancements
Workflow automation and detector material science are compressing examination throughput times while regulatory classification debates around AI-diagnostic software reshape hardware-software bundling economics.
Wireless flat-panel detector technology is unifying image acquisition and transmission functions previously requiring separate hardware components. Hospital radiology departments in Milan and Turin are adopting these systems to eliminate tethered workflow constraints. This unification is compressing capital equipment footprints and enabling mobile unit redeployment across multiple examination rooms within single facilities.
EU Medical Device Regulation Article 10 technical documentation requirements are extending conformity assessment timelines for systems incorporating AI-enabled diagnostic software. Italian notified bodies are interpreting software-as-medical-device classification rules inconsistently, creating registration pathway uncertainty. Vendors are responding by segregating hardware and software sales contracts to isolate regulatory risk exposure.
Diagnostic imaging centers are consolidating procurement decisions under centralized purchasing cooperatives, displacing individual hospital tender processes. These cooperatives negotiate multi-year service contracts bundling equipment, maintenance, and software updates. This concentration is most visible in Lombardy's private diagnostic network clusters, where three purchasing groups now control over sixty percent of annual digital x-ray system acquisitions.
Italy Digital X-Ray Market Segmentation
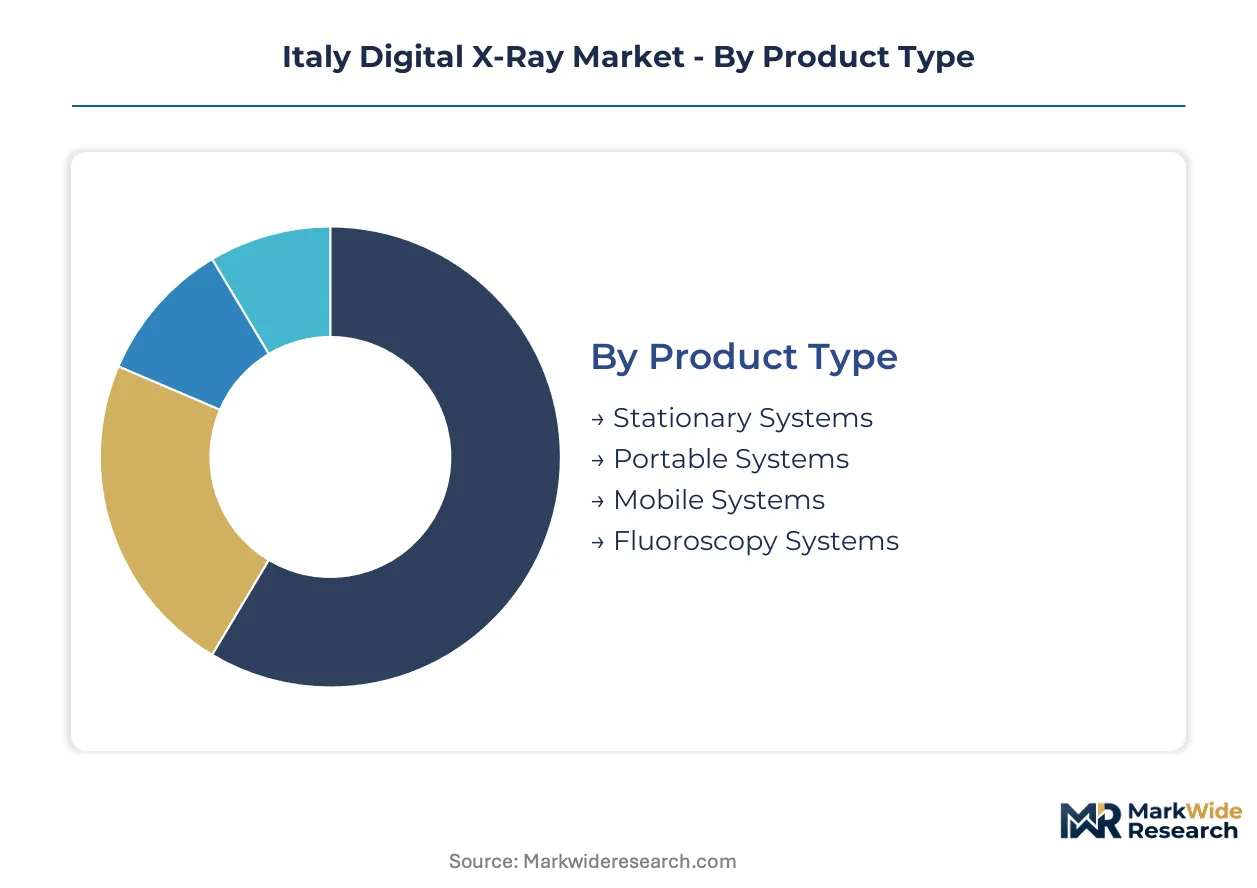
Segmentation reveals how Italy's reimbursement realignment and retrofit cycles concentrate demand across distinct equipment categories. Technology choices and end-user procurement patterns diverge sharply between northern consolidation hubs and southern expansion zones.
Product Type:
Replacement cycles across Lombardy and Piedmont hospitals favor systems that eliminate chemical processing entirely, compressing capital deployment timelines for fully digital architectures.
- Stationary Systems:Fixed-room installations using ceiling-suspended tube stands and integrated flat-panel detectors dominate high-throughput hospital radiology departments. Demand concentrates in Milan and Turin facilities replacing amorphous selenium units with cesium iodide scintillator configurations, driven by Ministry of Health reimbursement protocols that penalize hybrid workflows.
- Portable Systems:Battery-powered wireless detector units enable point-of-care deployment across multiple examination rooms. Northern Italy's private diagnostic networks in Lombardy are consolidating procurement through purchasing cooperatives for these systems, seeking operational flexibility without dedicated room infrastructure.
- Mobile Systems:Motorized column designs serve intensive care and emergency department integration.
- Fluoroscopy Systems:Real-time imaging platforms with pulsed exposure control support interventional procedures.
Stationary systems sit at the top of the volume ranking, with portable systems climbing the fastest as outpatient networks pursue deployment flexibility.
End User:
Procurement authority concentration varies dramatically by geography, with cooperative purchasing displacing individual tenders in northern regions while southern facilities retain decentralized decision-making.
- Hospitals:Public radiology departments across Tuscany and Veneto operate under regional authority specifications mandating DICOM-compliant PACS integration. These facilities drive bulk detector replacements as flat-panel technology reaches end-of-service life, constrained by CE marking documentation timelines that extend procurement cycles.
- Diagnostic Imaging Centers:Private networks in Lombardy and Piedmont consolidate equipment decisions under three major purchasing groups controlling majority acquisition volumes. These centers prioritize throughput speed and multi-modality interoperability to serve high patient volumes.
- Outpatient Clinics:Independent practices in Sicily and Calabria represent underpenetrated demand for point-of-care systems.
- Research Institutions:Academic medical centers in Bologna and Rome deploy specialized configurations for protocol development.
Diagnostic imaging centers command the largest procurement volumes, with outpatient clinics expanding most quickly as infrastructure investment reaches southern regions.
Technology:
Detector material cost curves are rebalancing competitive economics between established and emerging capture architectures across Italian retrofit decisions.
- Direct Radiography:Solid-state flat-panel detectors using thin-film transistor arrays deliver immediate digital readout without intermediate processing. Hospital radiology departments in Milan prioritize these systems for superior dose efficiency and examination throughput, aligning with Ministry of Health preferences for fully digital workflows.
- Computed Radiography:Photostimulable phosphor plate systems persist in cost-sensitive installations transitioning from analog.
- Digital Tomosynthesis:Limited-angle tomographic reconstruction enables depth-resolved imaging without full CT.
- 3D Imaging:Cone-beam acquisition geometries support specialized orthopedic and dental applications.
Direct radiography dominates current procurement value, with digital tomosynthesis gaining share fastest as reconstruction algorithms improve.
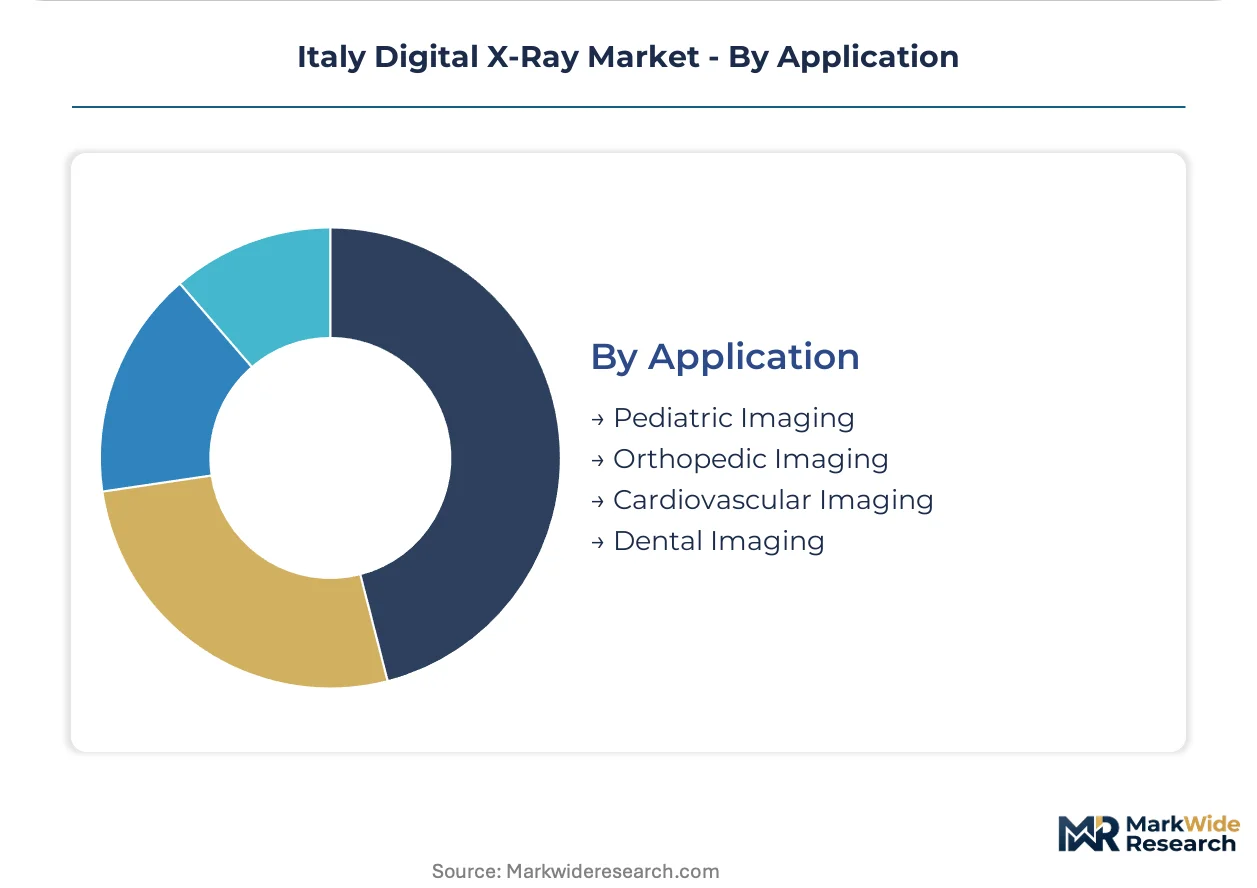
Application:
Regulatory digitization mandates and procedure-specific reimbursement rates concentrate investment in particular clinical domains.
- Dental Imaging:Intraoral sensors and panoramic units face mandatory digitization deadlines across Veneto and Emilia-Romagna private practices. These systems achieve the steepest expansion trajectory as regulatory compliance deadlines approach and equipment financing programs proliferate.
- Orthopedic Imaging:Weight-bearing extremity systems and long-length acquisition modes support trauma and arthroplasty planning.
- Cardiovascular Imaging:Specialized detector configurations with high frame rates serve catheterization laboratories.
- Pediatric Imaging:Low-dose protocols and child-appropriate positioning systems address radiation sensitivity requirements.
Orthopedic imaging leads by current installed base, with dental imaging climbing the fastest as practice digitization mandates take effect.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lombardy's diagnostic imaging cluster concentrates procurement volumes and shapes technology adoption patterns across northern Italy. Regional reimbursement protocols and purchasing cooperative structures create divergent investment climates between the industrial north and infrastructure-lagging south.
Lombardy
Private diagnostic networks in Milan and Brescia consolidate equipment acquisitions through three purchasing cooperatives controlling majority annual volumes. Regional health authority specifications mandate DICOM-compliant PACS integration for all new installations. Hospital radiology departments across the metropolitan Milan corridor are replacing amorphous selenium units with cesium iodide scintillator configurations.
Piedmont
Turin-based hospital systems drive retrofit cycles for direct radiography platforms as Ministry of Health protocols penalize hybrid analog-digital workflows. The national pharmaceutical regulator enforces CE marking documentation requirements that extend procurement timelines. Diagnostic imaging centers in the Turin-Alessandria axis prioritize throughput speed and multi-modality interoperability.
Veneto
Private dental practices across Verona and Padua face regulatory digitization deadlines for intraoral and panoramic imaging systems. Regional procurement specifications layer additional interoperability requirements atop EU Medical Device Regulation standards. The Verona-Bologna corridor hosts concentrated demand for specialized cardiovascular imaging configurations.
Emilia-Romagna
Bologna anchors domestic manufacturing capabilities for flat-panel detector systems serving national distribution networks. Villa Sistemi Medicali's production facilities supply regional hospital networks with reduced lead times versus imported alternatives. The Bologna-Modena industrial zone supports technical service infrastructure for solid-state detector calibration.
Sicily
Independent outpatient clinics in Palermo and Catania represent underpenetrated demand for portable point-of-care systems. Field service engineer scarcity constrains deployment speed for wireless detector units requiring specialized calibration protocols. Southern infrastructure investment lags northern regions, creating deployment flexibility advantages for mobile equipment configurations.
Italy Digital X-Ray Market Competitive Landscape
Service contract renewal dominance shapes the current landscape as vendors leverage installed base relationships to sustain recurring revenue streams. The market structure concentrates around multinational imaging conglomerates with established Italian hospital relationships, domestic manufacturing specialists, and East Asian component suppliers. Three strategic archetypes prevail: integrated diagnostic platform providers, regional manufacturing specialists, and detector technology licensors. Competitive moves center on hardware-software bundling strategies and purchasing cooperative penetration.
Among Japan-based conglomerates, Shimadzu Corporation and Fujifilm Holdings Corporation occupy positions emphasizing integrated diagnostic platforms with established service networks. Siemens Healthineers AG exemplifies the European multinational archetype leveraging public hospital installed bases. Villa Sistemi Medicali anchors the domestic specialist tier through Bologna-based manufacturing capabilities. Canon Medical Systems represents the diversified imaging technology vector with specialized configuration offerings.
| Leading Market Players |
|---|
| Shimadzu Corporation |
| Villa Sistemi Medicali |
| Siemens Healthineers AG |
| Canon Medical Systems |
| Philips Healthcare |
| GE Healthcare |
| Carestream Health |
| Agfa-Gevaert Group |
| Fujifilm Holdings Corporation |
| Others |
Supply & Pricing Matrix
Field service engineer scarcity across southern Italy widens pricing-tier spreads between premium service-bundled systems and economy configurations lacking calibration support. Labor-cost differentials between Bologna's technical hub and peripheral regions force vendors to stratify pricing across premium, standard, and economy levels based on geographic service coverage.
Pricing Analysis
Input-cost pass-through from cesium iodide scintillator supply volatility shapes pricing dynamics across detector tiers. Three-tier pricing structure across premium, standard, and economy levels separates systems with integrated AI software from hardware-only configurations. CE marking compliance costs for EU Medical Device Regulation documentation compress margins on imported economy-tier systems. Price differentiation hinges on after-sales service bundling, with private diagnostic networks in Lombardy showing lowest price sensitivity due to cooperative purchasing scale, while independent outpatient clinics in Sicily prioritize capital expenditure minimization.
Supply Chain Analysis
CE marking and EU Medical Device Regulation qualification gating extends procurement timelines for systems incorporating AI-enabled diagnostic software. Solid-state detector array manufacturing concentrates in South Korea, Japan, and Taiwan, exposing Italian system integrators to lead time volatility. Supply chains draw from East Asian thin-film transistor foundries, European precision mechanical component suppliers, and domestic Bologna-based final assembly operations. Single-source vulnerability concentrates in scintillator crystal growth capabilities. Distribution runs through regional purchasing cooperatives in northern Italy and direct hospital procurement channels in southern regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's Ministry of Health reimbursement protocol realignment compounds demand for fully digital workflows, creating a regulatory compounding effect that accelerates capital replacement cycles across hospital radiology departments.
For Market Incumbents: Anchor service contract renewal dominance by deepening calibration technician training programs in southern Italy, countering field engineer scarcity that threatens competitor deployment timelines. Fortify positions against emerging portable-system specialists by integrating AI-enabled diagnostic software into hardware-software bundles, isolating regulatory risk through segregated sales contracts. Prioritize backward integration into detector refurbishment capabilities to capture circular economy value from amorphous selenium stranded assets. For New Entrants and Emerging Players: EU Medical Device Regulation software-as-medical-device classification uncertainty in Italy opens a window for pure-hardware entrants to serve cost-sensitive outpatient clinics in Sicily and Calabria. Target underpenetrated point-of-care deployment in southern regions where fixed infrastructure investment lags northern consolidation hubs. Pursue dental practice digitization mandates across Veneto and Emilia-Romagna through equipment financing partnerships with regional banking networks. For Investors and Strategic Acquirers: Valuations sit cheapest among domestic manufacturing specialists with Bologna-based production capabilities and established regional service networks. Long-term viability centers on hardware-software convergence economics and recurring service revenue expansion. Monitor AI-diagnostic software classification rule harmonization across Italian notified bodies as the inflection signal for bundling strategy viability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU Medical Device Regulation documentation requirements extend registration timelines for AI-integrated systems. |
| Hospital System Partnership | Lombardy purchasing cooperatives consolidate procurement decisions under multi-year service contracts. |
| Software Companion Development | Computer-aided detection algorithms create service revenue expansion beyond equipment sales. |
| Reimbursement Strategy | Ministry of Health protocol alignment favors fully digital workflow configurations over hybrid systems. |
| Geographic Expansion | Southern Italy outpatient clinics represent underpenetrated demand for portable point-of-care systems. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down detector shipment tracking forms the analytical core of this study. Primary interviews with hospital biomedical engineers, GPO contracts managers, regional health authority procurement officers, and flat-panel detector calibration technicians combined with secondary validation from CE marking databases, Ministry of Health reimbursement protocols, and regional purchasing cooperative tender records. Triangulation across these sources ensures cross-verification of equipment deployment timelines and technology adoption patterns.
Historical trendline analysis of replacement cycles and retrofit decisions informs projection frameworks across the modeling period. Segmentation dimensions include product type, end user category, detector technology, and clinical application, with additional modeling of regional procurement authority concentration. CAGRs derive from equipment lifecycle analysis and reimbursement protocol impact assessment. Forecast inputs incorporate cesium iodide scintillator cost curve trajectories and AI-software regulatory classification evolution.
Revisions become necessary when Ministry of Health reimbursement protocols shift, EU Medical Device Regulation software classification rules harmonize, or East Asian detector component supply experiences disruption. Forecasts reflect documented assumptions regarding technology substitution rates and cooperative purchasing consolidation trajectories. A model refresh is warranted upon material change in AI-enabled diagnostic software regulatory treatment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Asia-Pacific Digital Radiology Market
Medical Imaging
Global Nuclear Imaging Equipment Market
Medical Imaging
Radiography-Fluoroscopy Combo System Market
Medical Imaging
France Diagnostic Imaging Equipment Market
Medical Imaging
Brazil Nuclear Imaging Market
Medical Imaging
Fluoroscopy Devices Market
Medical Imaging
Portable MRI Market
Medical Imaging
South America Portable X Ray Devices Market
Medical Imaging
Global Portable Magnetic Resonance Imaging Market
Medical Imaging
Teleradiology Services Market
Medical Imaging
Preclinical MRI Equipment Market
Medical Imaging
South Africa Nuclear Imaging Market
Medical Imaging
Point-Of-Care Medical Imaging Market
Medical Imaging
Europe Medical Imaging Market
Medical Imaging
France Magnetic Resonance Imaging Market
Medical Imaging
India Magnetic Resonance Imaging Market