
 Dental Imaging Market | 2026-2036
Dental Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Imaging Market Analysis
European sensor fabrication capacity is hardening as German and Finnish suppliers expand cleanroom operations for CMOS-based intraoral detectors. Planmeca Oy leverages its Helsinki manufacturing base to sustain vertical integration across sensor design and software calibration. Envista Holdings Corporation anchors its competitive position through dense distribution in North American dental service organizations. DENTSPLY SIRONA differentiates via proprietary tomographic reconstruction algorithms that reduce radiation exposure in implant planning workflows.
Dental imaging comprises the acquisition, processing, and visualization of oral and maxillofacial structures using ionizing radiation, optical coherence, or acoustic modalities, with spatial resolution typically ranging from 20 to 150 micrometers for intraoral sensors and sub-millimeter voxel dimensions for cone-beam computed tomography systems. Its primary purpose is to enable non-invasive diagnosis, treatment planning, and post-operative monitoring across restorative, orthodontic, periodontal, and surgical dental disciplines. Cone Beam CT systems command the highest capital investment per unit and generate recurring software maintenance revenue streams that deepen manufacturer-client relationships. Digital X-ray modalities occupy the broadest installed base across dental clinics globally, though price compression in phosphor plate systems is redirecting manufacturer R&D toward direct digital sensors. Intraoral cameras are expanding fastest in pediatric and cosmetic dentistry practices where patient communication and case documentation drive purchasing decisions.
The FDA regulates dental radiographic equipment under 21 CFR 1020.32 performance standards, while the EU Medical Device Regulation (MDR) reclassifies CBCT systems to Class IIb and imposes stricter clinical evidence requirements for software-aided diagnosis. ISO 11496 governs dental film and digital receptor dimensional stability, creating baseline interoperability that shapes procurement specifications for multi-vendor clinic networks. Stakeholders must monitor how AI-enabled diagnostic overlays trigger new regulatory scrutiny under the EU AI Act's high-risk system category and whether the FDA's predetermined change control plans for machine learning will accelerate or fragment software update pathways.
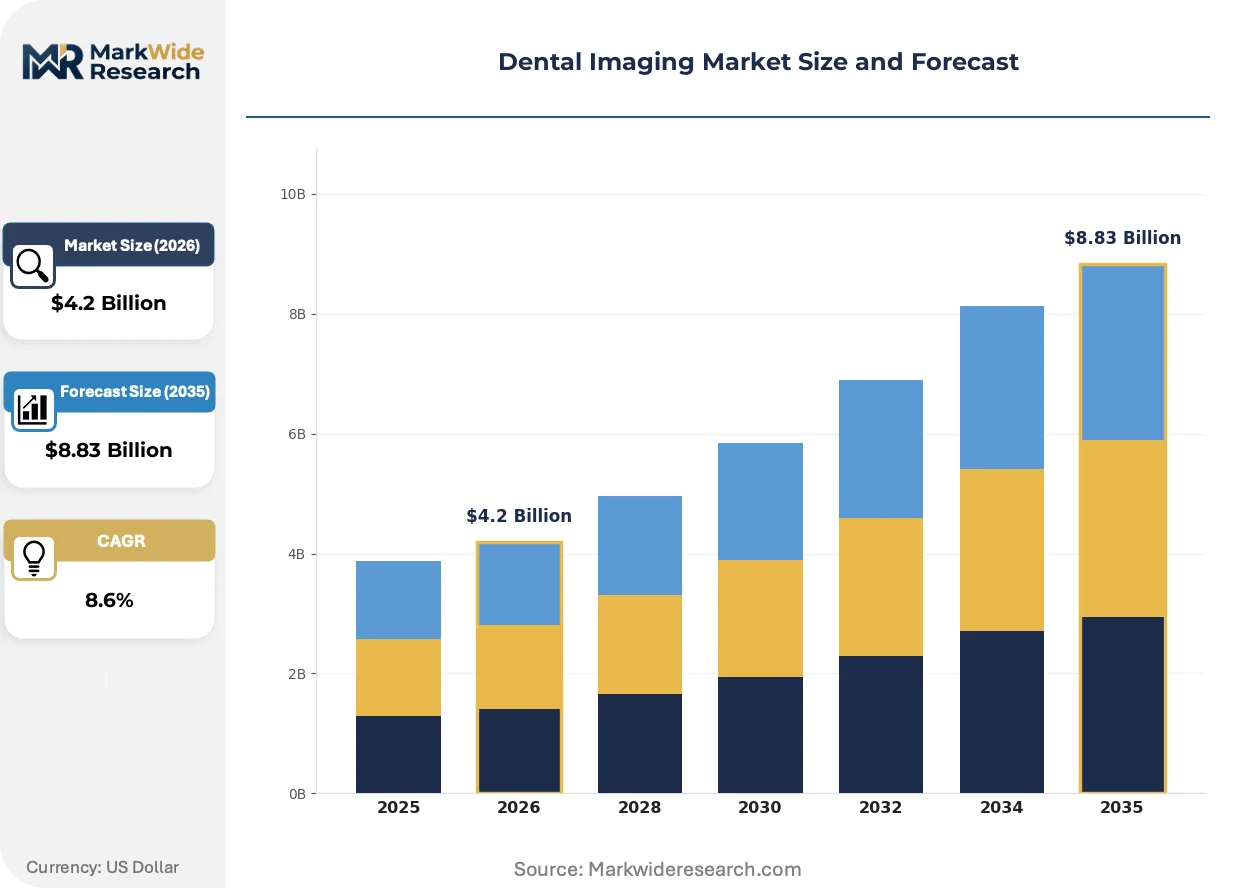
Market Dynamics
Digital radiography procurement by suburban and rural dental clinics is compressing equipment refresh cycles while the FDA's refinement of 510(k) pathways for AI-assisted diagnostics accelerates software development timelines.
Growth Catalysts
- Preventive oral health program scaling:Reimbursement structures in the United States, Germany, and South Korea now cover advanced imaging modalities, pulling capital investment into cone-beam computed tomography systems.
- FDA 510(k) pathway compression:Streamlined clearance processes for machine learning-enabled diagnostic overlays reduce time-to-market for algorithm developers serving dental service organizations.
- CMOS sensor fabrication expansion:German and Finnish cleanroom operations are hardening supply security for intraoral detectors, enabling procurement volume growth across multi-vendor clinic networks.
Market Restraints
- Capital intensity of CBCT systems:Per-unit investment thresholds exclude independent practices in lower-reimbursement catchments, concentrating ownership within dental service organizations.
- EU MDR Class IIb reclassification:Stricter clinical evidence requirements for software-aided diagnosis extend certification timelines and inflate regulatory compliance costs for CBCT manufacturers.
- Phosphor plate price compression:Margin erosion in computed radiography systems redirects manufacturer R&D budgets toward direct digital sensors, stranding existing installed bases.
Strategic Opportunities
- Pediatric and cosmetic dentistry verticals:Intraoral camera demand concentrates where patient communication and case documentation drive purchasing decisions, opening channel expansion for visualization specialists.
- EU AI Act high-risk system category:Early compliance with diagnostic overlay scrutiny requirements creates first-mover positioning for algorithm developers seeking CE marking under emerging frameworks.
- Software maintenance revenue unbundling:Tomographic reconstruction algorithm updates enable recurring revenue streams that deepen manufacturer-client relationships beyond hardware replacement cycles.
Industry Challenges
- ISO 11496 interoperability enforcement:Dimensional stability standards for digital receptors complicate multi-vendor procurement specifications, requiring calibration expertise that strains clinic technical staff.
- Predetermined change control plan execution:FDA machine learning update pathways fragment software version management across distributed dental networks, complicating IT governance.
- Radiation exposure optimization:Algorithm-driven dose reduction in implant planning workflows demands cross-functional collaboration between imaging physicists and surgical specialists that outpaces training pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Imaging Market |
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $8.83 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital X-ray, Intraoral Camera, Cone Beam CT, 3D Imaging End User: Dental Clinics, Hospitals, Research Institutions, Dental Laboratories Technology: X-ray Imaging, Optical Imaging, Ultrasound Imaging, Magnetic Resonance Imaging Application: Cavity Detection, Implant Planning, Orthodontic Evaluation, Periodontal Assessment |
| Companies Covered | Planmeca Oy, ACTEON, Envista Holdings Corporation, Owandy Radiology Inc., DÜRR DENTAL AG, DENTSPLY SIRONA, Carestream Dental LLC, Genoray Co., Ltd., VATECH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Imaging Market Emerging Trajectories
Artificial intelligence integration is restructuring diagnostic workflows across dental imaging modalities, compressing interpretation timelines while introducing new regulatory complexity for algorithm developers and clinic operators.
Direct digital intraoral sensors are overtaking phosphor plate systems in new equipment procurement across suburban and rural dental clinics. General practitioners facing patient volume pressure prioritize immediate image acquisition over cost savings from legacy computed radiography. This shift is compressing phosphor plate manufacturer margins and redirecting R&D investment toward CMOS-based detector architectures.
The EU AI Act's high-risk system classification for diagnostic overlays is imposing clinical evidence burdens on software developers that exceed prior CE marking requirements. Algorithm-assisted caries detection and periodontal assessment now face mandatory conformity assessment procedures that extend time-to-market. CBCT manufacturers with integrated diagnostic software are restructuring quality management systems to accommodate post-market performance monitoring obligations.
Subscription-based software licensing is displacing perpetual purchase models in cone-beam computed tomography system contracts. Dental service organizations in the United States are negotiating enterprise agreements that bundle tomographic reconstruction updates with hardware maintenance, unbundling traditional capital expenditure structures. Independent practices respond by extending equipment depreciation schedules or joining group purchasing organizations to access comparable pricing tiers.
Dental Imaging Market Segmentation
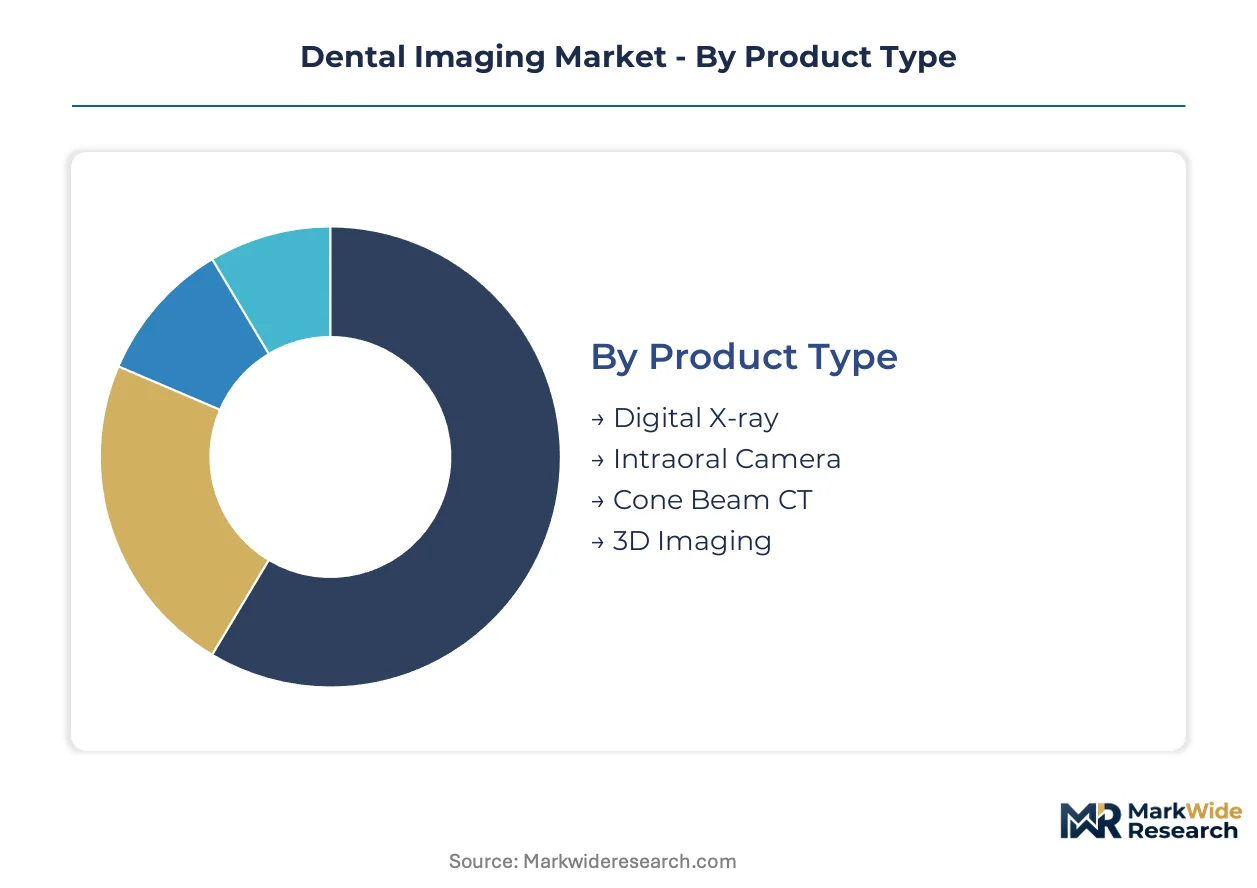
Dental imaging procurement patterns diverge sharply across equipment categories, with capital intensity and regulatory burden determining which segments penetrate suburban clinics versus hospital systems. Understanding these fault lines clarifies where manufacturers must align certification strategies with buyer budget cycles.
Product Type:
FDA 510(k) clearance timelines compress fastest for digital X-ray systems, while EU MDR Class IIb reclassification imposes heavier clinical evidence demands on cone beam CT platforms. CMOS sensor architectures face ISO 11496 dimensional stability testing that phosphor plate systems bypass.
- Digital X-ray:Direct digital sensors utilizing CMOS photodiode arrays deliver immediate image acquisition without chemical processing. Demand concentrates in United States suburban clinics where patient throughput pressure outweighs phosphor plate cost savings. FDA 510(k) pathway compression accelerates manufacturer refresh cycles.
- Cone Beam CT:Volumetric tomography systems reconstruct sub-millimeter voxel datasets for implant planning workflows. German and South Korean preventive oral health programs reimburse these modalities, pulling capital investment into dental service organizations. EU MDR Class IIb certification inflates compliance costs.
- Intraoral Camera:Optical visualization tools dominate pediatric and cosmetic dentistry practices where patient communication drives purchasing.
- 3D Imaging:Surface scanning and model reconstruction systems support orthodontic aligner fabrication and restorative workflows.
Leading the category by volume: Digital X-ray. Growing fastest: Intraoral camera.
End User:
Procurement authority clusters differently across customer types, with dental service organizations leveraging enterprise pricing while independent practices face capital constraints.
- Dental Clinics:General practitioner and specialty practices constitute the broadest installed base. United States suburban and rural catchments are expanding digital radiography procurement as reimbursement structures mature.
- Hospitals:Academic medical centers and integrated delivery networks command CBCT purchasing power. South Korean national health program scaling channels advanced imaging into hospital-based dental departments.
- Research Institutions:University dental schools and imaging centers drive algorithm validation for AI-assisted diagnostics.
- Dental Laboratories:Prosthetic fabrication facilities utilize 3D imaging for crown, bridge, and aligner model production.
Dental clinics anchor procurement volume. Research institutions are expanding most quickly as AI validation requirements intensify.
Technology:
Physics-based differentiation determines regulatory pathway complexity and reimbursement eligibility across modality categories.
- X-ray Imaging:Ionizing radiation modalities span intraoral sensors through panoramic and tomographic systems. German cleanroom operations harden CMOS detector supply security.
- Optical Imaging:Non-ionizing coherence and camera-based systems face lighter FDA scrutiny while satisfying pediatric dentistry demand for radiation-free alternatives.
- Ultrasound Imaging:Acoustic modalities remain niche for soft tissue assessment in periodontal applications.
- Magnetic Resonance Imaging:MRI protocols serve complex maxillofacial pathology and TMJ disorder evaluation in hospital settings.
X-ray imaging dominates installed value. Optical imaging gains share fastest as patient communication priorities reshape clinic investment.
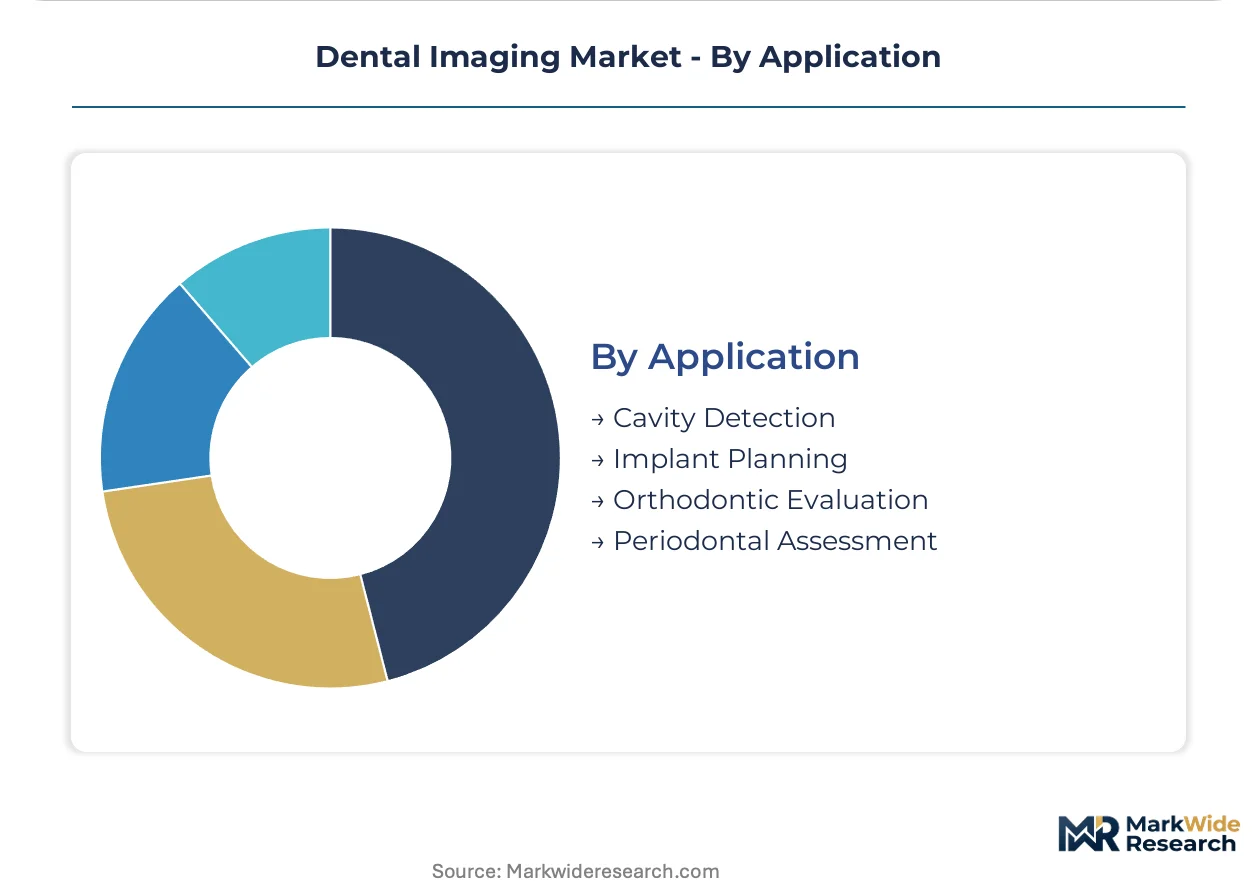
Application:
Clinical use case specificity determines software algorithm development priorities and maintenance revenue potential.
- Implant Planning:Three-dimensional surgical guidance commands premium software licensing fees. DENTSPLY SIRONA proprietary reconstruction algorithms reduce radiation exposure, deepening manufacturer-client relationships through recurring update subscriptions.
- Cavity Detection:Caries identification algorithms face EU AI Act high-risk system classification, extending conformity assessment timelines for diagnostic overlay developers.
- Orthodontic Evaluation:Cephalometric analysis and aligner planning workflows concentrate demand in adolescent patient demographics.
- Periodontal Assessment:Bone level monitoring and furcation detection applications support longitudinal treatment tracking.
Implant planning generates highest per-procedure software revenue. Cavity detection is climbing fastest as AI diagnostic overlays proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Finnish cleanroom operations anchor CMOS sensor fabrication for intraoral detectors, while reimbursement structures in the United States, Germany, and South Korea channel capital toward cone-beam computed tomography procurement.
United States
FDA 510(k) pathway compression accelerates machine learning-enabled diagnostic software timelines, while suburban and rural dental clinics expand digital radiography procurement. The agency's predetermined change control plans for algorithm updates reshape software governance across dental service organizations. Greater Boston hosts research institutions validating AI-assisted caries detection algorithms for regulatory submission.
Germany
Preventive oral health program scaling reimburses advanced CBCT modalities, pulling investment into implant planning workflows. EU MDR Class IIb reclassification imposes stricter clinical evidence requirements on software-aided diagnosis. Helsinki-Tallinn corridor suppliers expand cleanroom capacity for CMOS-based intraoral detector vertical integration.
South Korea
National health program expansion channels cone-beam CT procurement into hospital-based dental departments and specialty clinics. MFDS regulates radiographic equipment performance standards under medical device classification schemes. Seoul Capital Area concentrates manufacturing for panoramic and cephalometric imaging systems serving domestic and export markets.
Japan
PMDA oversight of dental radiographic equipment maintains stringent quality assurance protocols for ionizing radiation systems. Aging demographics drive periodontal assessment imaging demand across general practitioner networks. Osaka-Kobe industrial corridor houses precision optics fabrication for intraoral camera modules.
Finland
CMOS photodiode array production scales through Helsinki-region cleanroom investments, hardening supply security for direct digital sensor architectures. EU AI Act high-risk system classification for diagnostic overlays triggers conformity assessment restructuring for algorithm developers. Tampere imaging technology cluster advances tomographic reconstruction software for export markets.
Dental Imaging Market Vendor Landscape
Global majors compete with regional champions across sensor fabrication and software calibration capabilities, producing a tiered structure where capital-intensive CBCT platforms concentrate among multinational portfolios while intraoral detector supply fragments across specialized fabricators. Three archetypes dominate: vertically integrated imaging system houses, CMOS sensor specialists with software calibration expertise, and dental service organization-focused distributors with dense North American coverage. Competitive moves center on M&A for algorithm capabilities and cleanroom capacity expansion for CMOS detector supply security.
Within the vertically integrated tier, Planmeca Oy exemplifies Helsinki-based manufacturing control spanning sensor design through software calibration. Envista Holdings Corporation anchors distributor-centric positioning through North American dental service organization relationships. DENTSPLY SIRONA occupies a position defined by proprietary algorithm development for radiation dose optimization in surgical workflows.
| Leading Market Players |
|---|
| Planmeca Oy |
| ACTEON |
| Envista Holdings Corporation |
| Owandy Radiology Inc. |
| DÜRR DENTAL AG |
| DENTSPLY SIRONA |
| Carestream Dental LLC |
| Genoray Co., Ltd. |
| VATECH |
| Others |
Supply Flow & Price Mechanics
CMOS photodiode wafer costs from German and Finnish cleanroom operations cascade through three pricing tiers for intraoral sensors, with premium CMOS architectures commanding service-bundled premiums while phosphor plate systems face margin compression that redirects procurement toward direct digital alternatives.
Pricing Analysis
Warranty and software maintenance unbundling now separates capital expenditure from recurring revenue streams across cone-beam CT contracts. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) certification tier, volume scale through dental service organization enterprise agreements, and algorithm update frequency. Pricing pressure stems from phosphor plate price compression in computed radiography systems. Independent suburban practices exhibit highest price sensitivity, while hospital-based dental departments in South Korea demonstrate lowest sensitivity due to national health program reimbursement.
Supply Chain Analysis
Dual-sourcing requirements for CMOS sensors now mandate German and Finnish supplier qualification across multi-vendor clinic networks, hardening supply security. The chain draws from silicon wafer fabrication in the Helsinki-Tallinn corridor, precision optics from Osaka-Kobe, and tomographic reconstruction software development in Tampere. Single-source vulnerability concentrates in EU MDR Class IIb certification capacity for CBCT systems. Distribution runs through dental service organization procurement consortia in the United States and hospital supply chains in Germany and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
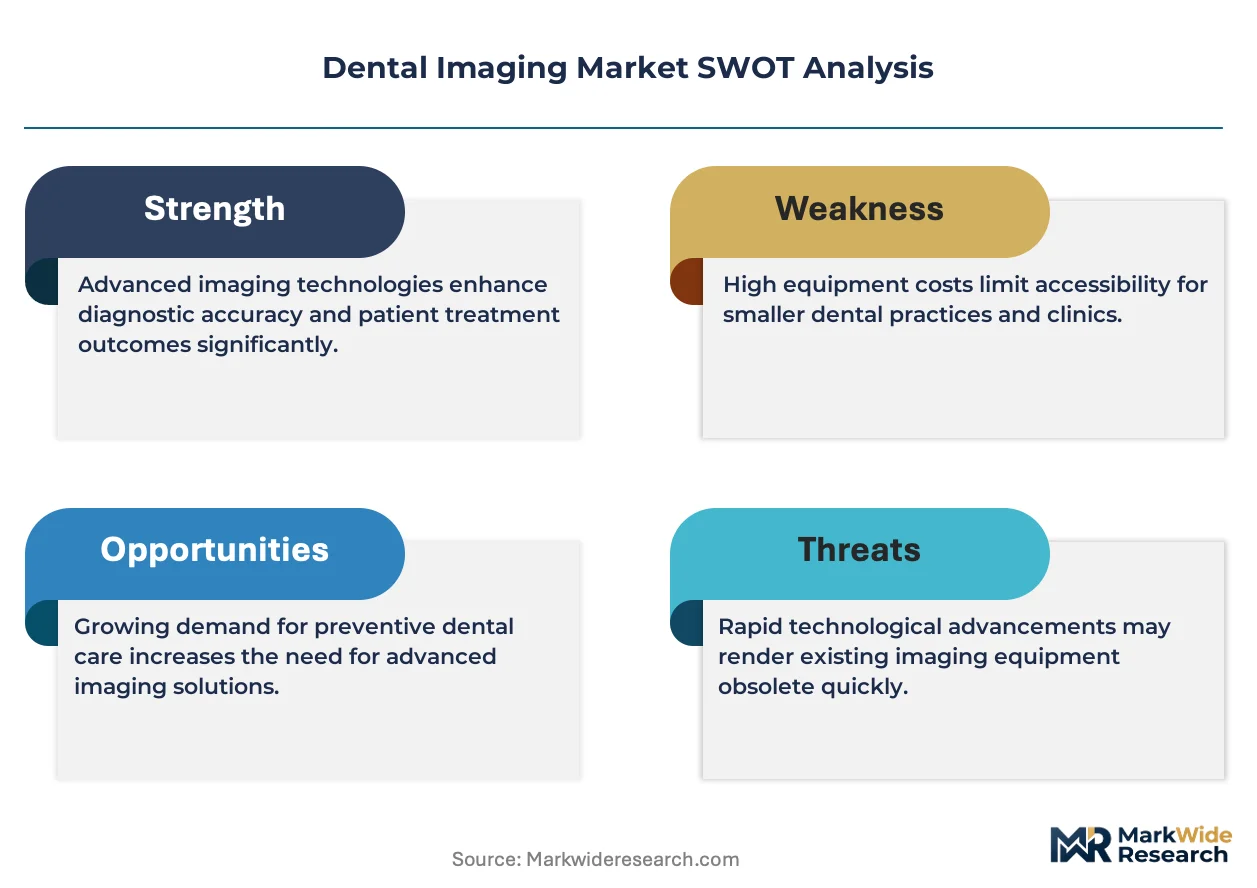
The EU MDR Class IIb reclassification erects a cost-of-compliance moat that favors incumbent CBCT manufacturers with established clinical evidence dossiers and quality management systems.
For Market Incumbents: Hedge against algorithm commoditization by deepening captive supply of CMOS sensor fabrication through Helsinki-region cleanroom expansion. Consolidate position by acquiring diagnostic overlay developers facing EU AI Act conformity assessment burdens that extend time-to-market for unresourced entrants.
For New Entrants and Emerging Players: Begin with intraoral camera penetration in United States pediatric and cosmetic dentistry practices where patient communication priorities override established brand loyalty. Target suburban dental clinics seeking immediate image acquisition without CBCT capital intensity. Deploy direct digital sensor bundling with visualization software to bypass phosphor plate installed bases.
For Investors and Strategic Acquirers: FDA predetermined change control plan adoption is the leading indicator that machine learning-enabled diagnostic software developers have achieved regulatory pathway maturity suitable for platform acquisition. Five-to-ten year viability centers on algorithm developers with CE marking progress under EU AI Act high-risk system frameworks. Watch for MFDS reimbursement expansion signals in South Korea as volume inflection triggers.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class IIb certification compresses competitive field to capitalized manufacturers. |
| Hospital System Partnership | South Korean national health program channels CBCT procurement into integrated delivery networks. |
| Software Companion Development | Tomographic reconstruction algorithm subscriptions deepen manufacturer-client relationships beyond hardware cycles. |
| FDA Submission | Predetermined change control plans accelerate machine learning diagnostic overlay approval timelines. |
| Reimbursement Strategy | German preventive oral health program scaling pulls capital investment into advanced imaging modalities. |
Methodological Framework
FDA 510(k) filings, EU MDR technical documentation, and MFDS medical device registration databases formed the secondary backbone for equipment approval timeline analysis. Primary interviews with dental service organization procurement directors, CBCT manufacturer regulatory affairs leads, and hospital biomedical engineering managers combined with secondary validation through ISO 11496 standard revision tracking and GPO contract database review. Bottom-up installed base estimates triangulated against top-down reimbursement structure analysis across the United States, Germany, and South Korea.
Historical trendline analysis of digital radiography replacement cycles and CBCT software maintenance renewal rates informed projection modeling across the analysis window. Segmentation dimensions spanned product type, end user archetype, technology physics, and application workflow with regulatory pathway complexity as an industry-specific overlay. CAGRs derived from equipment shipment volume trajectories and recurring revenue attachment rates. Forecast inputs incorporated AI diagnostic overlay penetration assumptions and CMOS sensor fabrication capacity expansion schedules.
Underlying measurement precision varies by segment; digital X-ray shipment volumes carry tighter precision than algorithm revenue attribution. Forecasts reflect documented assumptions regarding reimbursement expansion timelines and regulatory pathway efficiency. Deviation in EU AI Act enforcement intensity or FDA machine learning guidance revision would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global AI for Radiology Market
Medical Imaging
Europe Portable X-Ray Devices Market
Medical Imaging
Europe Digital X-Ray Market
Medical Imaging
Global Veterinary X-Ray Market
Medical Imaging
X-Ray Film Market
Medical Imaging
India Mammography Market
Medical Imaging
South America MRI Market
Medical Imaging
Saudi Arabia Digital Radiology Market
Medical Imaging
Non-Invasive Coronary Imaging Market
Medical Imaging
Global Medical Imaging Reagents Market
Medical Imaging
Breast Imaging Technologies Market
Medical Imaging
Wireless Ultrasound Scanner Market
Medical Imaging
Perfusion Radiology Market
Medical Imaging
MRI Ferromagnetic Detection Systems Market
Medical Imaging
Brazil Computed Tomography Market
Medical Imaging
Global Positron Emission Tomography [PET] Scanners Market