
 Business Transcription Market | 2026-2036
Business Transcription Market Size, Share, and Industry Trends Forecast 2026-2036
Business Transcription Market Analysis
The EU AI Act is pivoting vendor priorities toward algorithmic transparency and human-in-the-loop validation for automated transcription platforms. Verbit sustains competitive advantage through its hybrid AI-human workflow architecture optimized for legal and higher-education clients. Rev anchors its position with a crowdsourced freelancer model that controls cost scaling across enterprise accounts. TranscribeMe differentiates through specialized medical transcription expertise and HIPAA-compliant infrastructure.
Business transcription converts spoken audio from meetings, interviews, depositions, and broadcasts into searchable text formats, typically processing files at turnaround speeds ranging from one hour to several days depending on accuracy tier and audio complexity. The primary commercial purpose centers on creating auditable records, enabling content repurposing, and supporting accessibility compliance across enterprise, legal, and media workflows. Intelligent transcription services are capturing margin pools as natural language processing advances reduce post-editing labor, while manual transcription retains dominance in legal proceedings where verbatim certification carries evidentiary weight. AI-based solutions are expanding fastest in corporate end-use segments, though hybrid systems still lead in regulated industries requiring human verification.
The Federal Communications Commission enforces closed-captioning mandates for broadcast and streaming video that directly sustain demand for real-time transcription services in media applications. The European Medicines Agency and national health regulators across Germany, France, and Italy impose documentation standards on clinical trial proceedings that shape product requirements for medical transcription vendors. The Securities and Exchange Commission's recordkeeping rules for broker-dealer communications further tighten compliance specifications in financial services procurement. Stakeholders must monitor how divergent AI governance frameworks between the European Union and United States reshape cross-border service architectures and data residency requirements.
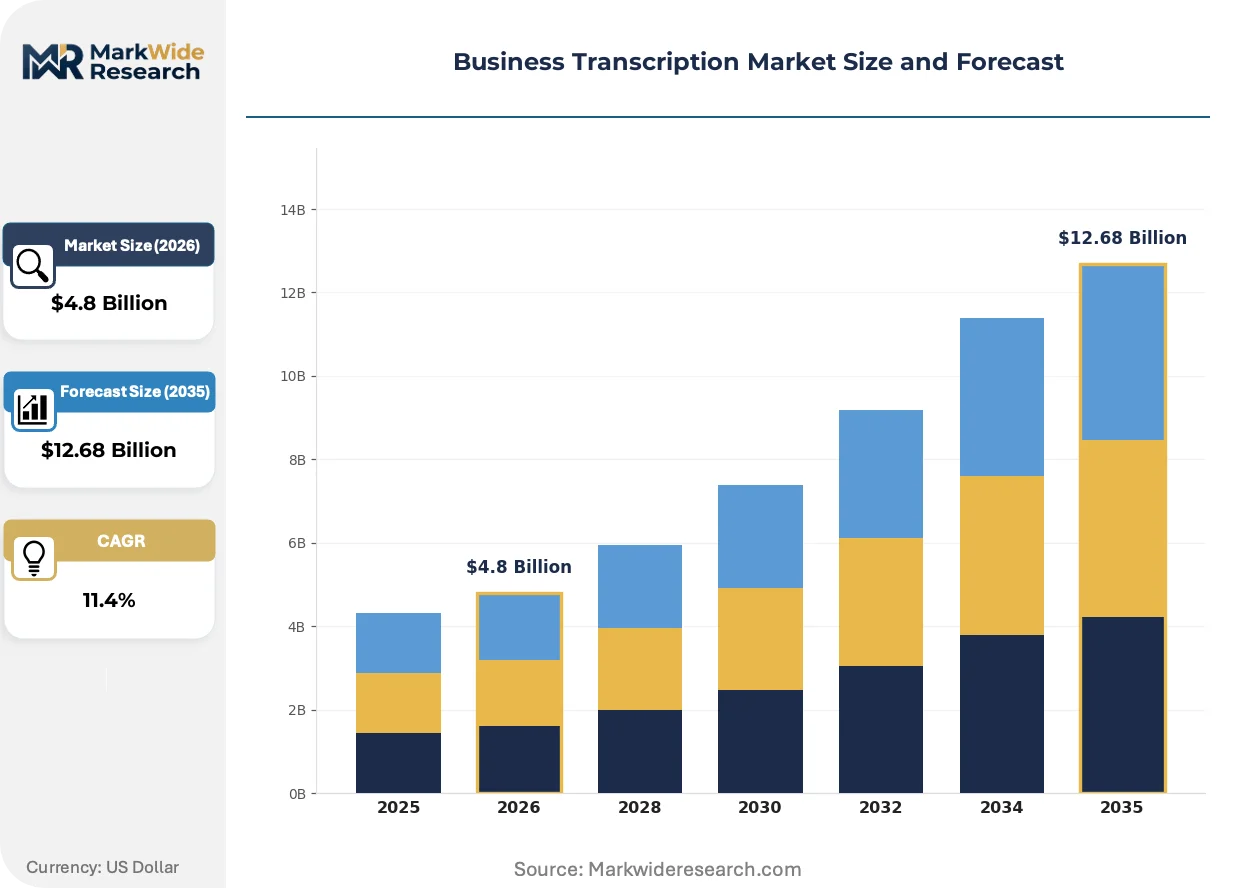
Market Dynamics
Natural language processing architectures are compressing post-editing labor requirements while regulatory mandates from the FCC and EU AI Act are hardening compliance specifications for verbatim certification and algorithmic transparency.
Growth Catalysts
- FCC closed-captioning mandates:Broadcast and streaming video requirements sustain real-time transcription demand in media workflows across the United States.
- Clinical trial documentation standards:The European Medicines Agency imposes verbatim recordkeeping on pharmaceutical proceedings, expanding specialized medical transcription procurement.
- SEC recordkeeping rules:Broker-dealer communication archiving requirements tighten specifications for financial services transcription vendors.
Market Restraints
- Human verification labor costs:Legal proceedings demand certified verbatim transcripts that resist full automation, anchoring cost structures to skilled transcriptionist wages.
- Cross-border data residency fragmentation:Divergent AI governance between the European Union and United States forces redundant infrastructure deployment.
- Audio complexity technical ceiling:Multi-speaker overlap, accented speech, and low-fidelity source material degrade automated speech recognition accuracy below evidentiary thresholds.
Strategic Opportunities
- Enterprise meeting intelligence:Fortune 500 compliance departments are accelerating procurement of real-time meeting transcription for auditable record creation.
- Higher-education accessibility mandates:Lecture captioning requirements under the Americans with Disabilities Act expand academic transcription contracts.
- Hybrid AI-human workflow convergence:Platforms combining automated draft generation with human quality assurance capture margin pools in regulated industries.
Industry Challenges
- Certified transcriptionist talent scarcity:Legal and medical domains require specialized expertise in stenography and domain terminology that outpaces training pipeline output.
- Legacy deposition software integration:Court reporting systems and case management platforms demand custom API development for seamless transcript ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business Transcription Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Verbatim, Edited, Intelligent, Medical End User: Corporate, Legal Firms, Educational Institutions, Media Technology: Speech Recognition, Manual Transcription, AI-Based Solutions, Hybrid Systems Delivery Mode: Online, Offline, Real-Time, Batch Processing |
| Companies Covered | GoTranscript, GMR Transcription, HappyScribe, Rev, SpeakWrite, TranscribeMe, Fellow, Verbit, Fathom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business Transcription Market Emerging Trajectories
Automated speech recognition is advancing through transformer-based architectures that reduce error rates in noisy environments while regulatory bodies on both sides of the Atlantic impose divergent compliance frameworks on vendor operations.
Speaker diarization and entity extraction capabilities are converging with core transcription engines to produce structured output that identifies participants, flags action items, and extracts contractual clauses without human preprocessing. Legal technology procurement teams are piloting these enhanced platforms for due diligence and discovery workflows. The structural consequence is converging with document automation and contract lifecycle management markets as transcription vendors expand into adjacent workflow software categories.
The EU AI Act's risk-based classification system is forcing automated transcription providers to implement human-in-the-loop validation for high-stakes legal and medical deployments. Vendors must document training data provenance and algorithmic decision pathways to maintain certification. European enterprise buyers are now screening supplier compliance documentation before procurement authorization, creating competitive differentiation for transparent architecture providers.
Enterprise buyers are unbundling transcription from bundled communication platforms and sourcing specialized vendors for compliance-critical applications. This fragmentation is displacing default procurement through unified communications suites in financial services and healthcare verticals. The United States exhibits the strongest unbundling momentum as SEC and HIPAA enforcement actions elevate recordkeeping quality above platform convenience.
Business Transcription Market Segmentation
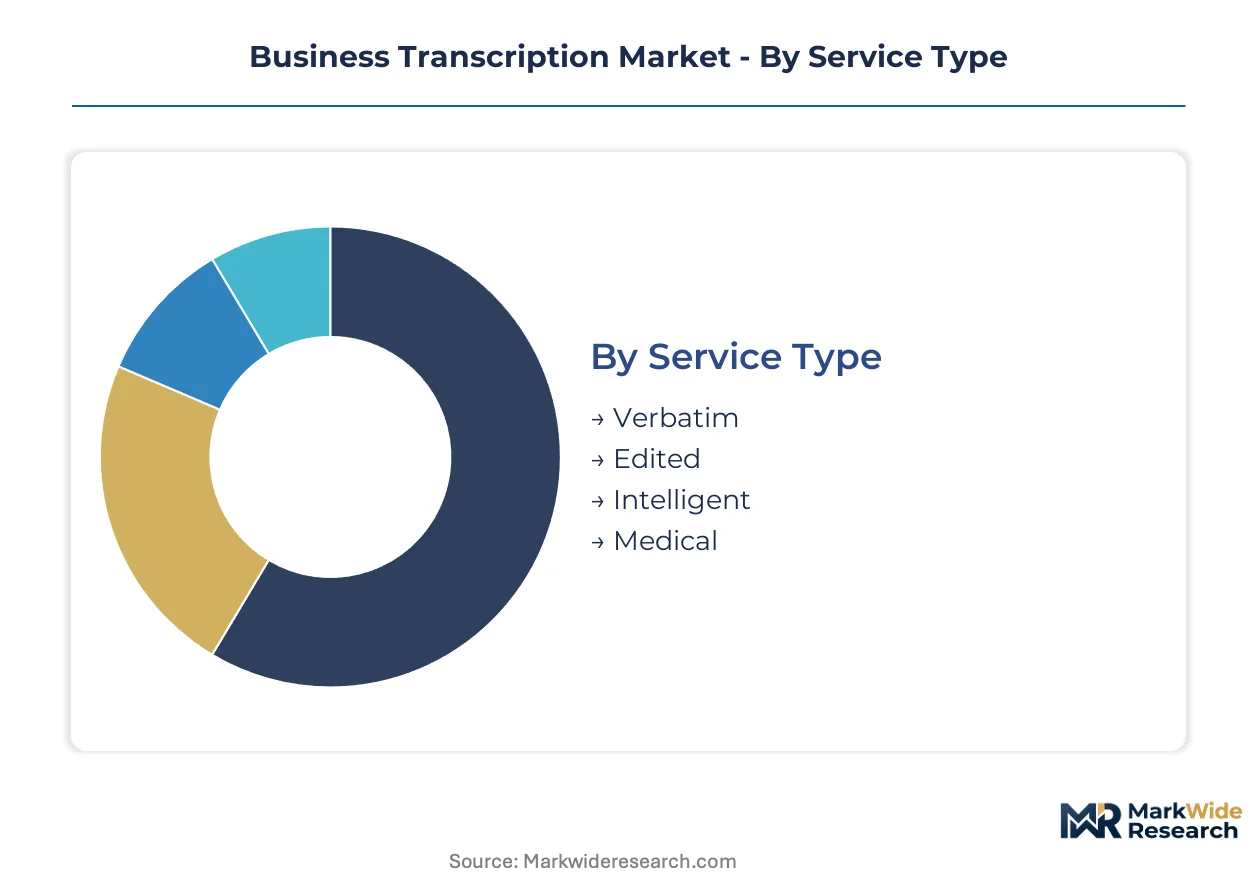
Business transcription segmentation reveals how service architectures align with compliance intensity and workflow integration depth. Procurement patterns diverge sharply between embedded enterprise platforms and specialized standalone services.
Service Type:
Standalone transcription services dominate legal and medical workflows where certification requirements resist platform embedding, while intelligent and edited formats increasingly integrate into corporate productivity suites.
- Verbatim:Captures every utterance including false starts, filler words, and non-verbal cues. Court reporters and deposition specialists in the United States drive demand as federal rules of evidence require word-for-word accuracy. Human stenographers remain essential where algorithmic transcription cannot meet certification standards.
- Intelligent:Applies natural language processing to extract action items, flag decisions, and structure meeting outputs. Fortune 500 compliance departments accelerate procurement for auditable record creation. The EU AI Act's risk classification pushes vendors toward human-in-the-loop validation architectures.
- Edited:Condenses spoken content into readable prose while preserving meaning. Corporate communications teams favor this format for internal documentation and executive briefing materials.
- Medical:Specialized for clinical terminology and HIPAA-compliant infrastructure. The European Medicines Agency's documentation standards shape procurement specifications for pharmaceutical trial proceedings.
Volume placements concentrate in Verbatim; the faster expansion belongs to Intelligent.
End User:
Cost tier segmentation separates compliance-critical buyers willing to pay premium rates for certified output from volume-sensitive corporate adopters prioritizing speed and scalability.
- Legal Firms:Discovery and deposition workflows demand certified transcripts with chain-of-custody documentation. The SEC's recordkeeping rules for broker-dealer communications tighten specifications for litigation support vendors. Specialized court reporting integrations require custom API development.
- Corporate:Enterprise meeting intelligence procurement accelerates across compliance departments seeking searchable archives. Real-time transcription unbundles from unified communications platforms as quality requirements escalate.
- Educational Institutions:Lecture captioning mandates under the Americans with Disabilities Act expand academic contracts. Hybrid AI-human workflows capture margin pools where accessibility compliance intersects with budget constraints.
- Media:FCC closed-captioning mandates sustain real-time demand for broadcast and streaming video. Live event transcription requires sub-second latency that tests technical architecture limits.
Revenue concentration sits with Legal Firms; Corporate is climbing the fastest.
Technology:
Technology segmentation tracks the automation frontier where transformer-based architectures compress labor costs while regulatory mandates preserve human verification requirements.
- Hybrid Systems:Combines automated draft generation with human quality assurance. Regulated industries in the United States and European Union favor this architecture for risk mitigation. The EU AI Act's algorithmic transparency requirements advantage vendors with documented human-in-the-loop workflows.
- AI-Based Solutions:End-to-end automated processing without human intervention. Corporate end-use segments adopt these for non-evidentiary applications where speed outweighs certification needs. Speaker diarization and entity extraction capabilities enhance output value.
- Manual Transcription:Human transcriptionists handle complex audio with multi-speaker overlap, accented speech, or low-fidelity source material. Legal proceedings retain this method where verbatim certification carries evidentiary weight.
- Speech Recognition:Core automated engine technology advancing through transformer architectures. Error rate improvements in noisy environments expand addressable audio quality ranges.
Deployment share clusters in Hybrid Systems; AI-Based Solutions show the steepest expansion trajectory.
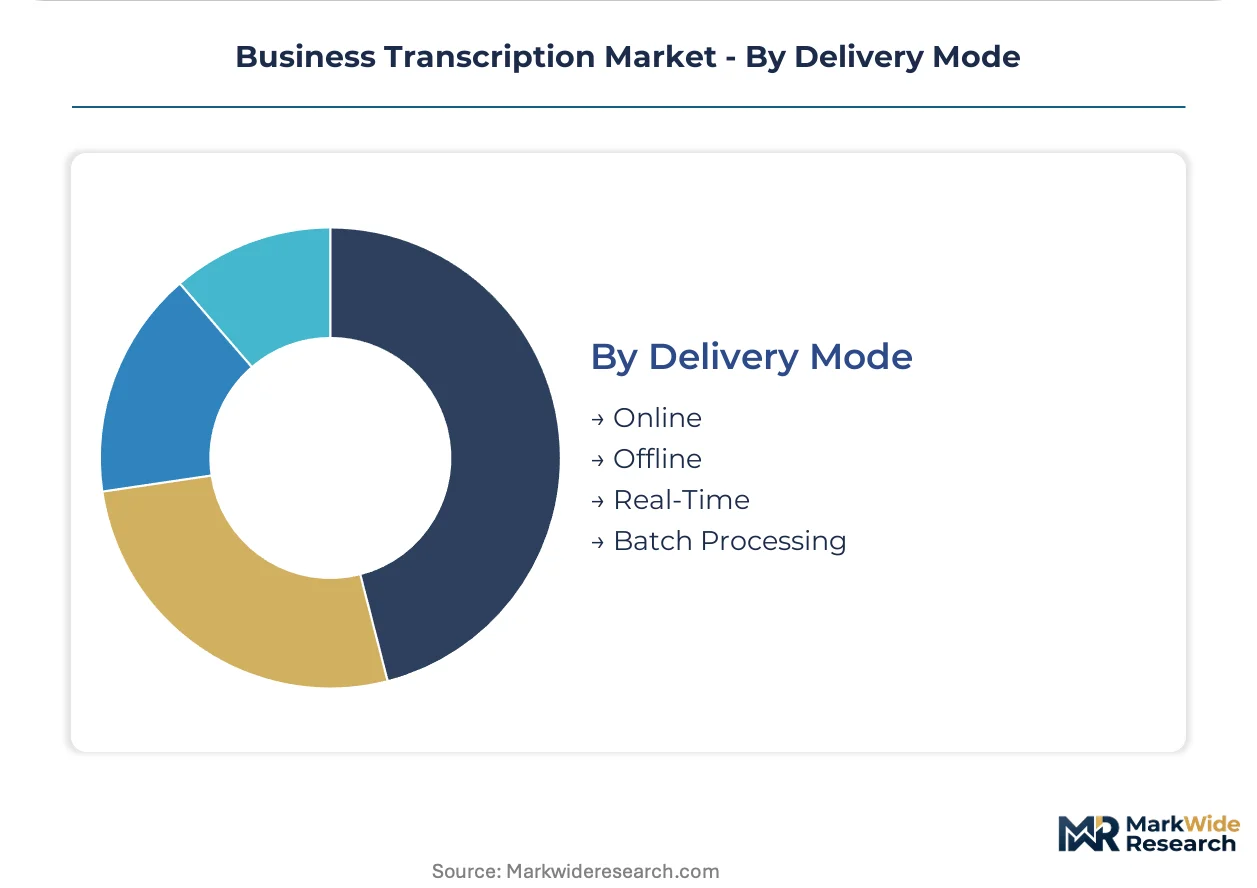
Delivery Mode:
Delivery segmentation maps latency requirements against infrastructure investment, separating synchronous real-time services from asynchronous batch processing.
- Real-Time:Sub-second transcription for live broadcasts, earnings calls, and judicial proceedings. The FCC's closed-captioning mandates sustain media demand. Technical complexity and infrastructure costs limit vendor participation.
- Batch Processing:File-based workflows with turnaround windows from hours to days. Legal discovery and corporate meeting archives favor this mode for cost efficiency at scale.
- Online:Cloud-hosted platforms enabling browser-based upload and retrieval. Enterprise procurement increasingly requires SOC 2 Type II certification and regional data residency options.
- Offline:Air-gapped or on-premise deployment for classified government or highly sensitive legal matters. Cross-border data residency fragmentation drives redundant infrastructure deployment.
Transaction volume pools in Batch Processing; Real-Time is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors enterprise transcription procurement as Fortune 500 compliance departments accelerate real-time meeting intelligence adoption. Legal technology clusters in New York and Washington DC sustain certified verbatim demand for deposition and discovery workflows.
United States
Enterprise meeting transcription procurement concentrates among Fortune 500 compliance departments seeking auditable records. The FCC enforces closed-captioning mandates for broadcast and streaming video that sustain real-time services demand. New York's legal technology corridor hosts specialized vendors serving litigation support and court reporting integration requirements.
United Kingdom
Financial services transcription procurement tightens around SEC recordkeeping compliance for broker-dealer communications archiving. The Information Commissioner's Office enforces data residency requirements that shape vendor infrastructure decisions. London's fintech and legal services clusters drive hybrid AI-human workflow adoption for risk-sensitive applications.
Germany
Pharmaceutical trial documentation standards expand specialized medical transcription procurement for clinical proceedings. The EU AI Act's risk-based classification system forces algorithmic transparency documentation for automated systems. Munich and Frankfurt host enterprise buyers screening supplier compliance before procurement authorization.
France
Higher-education accessibility mandates under national disability legislation expand academic transcription contracts. ANSM and CNIL impose documentation and data protection standards on medical and legal transcription deployments. Paris hosts enterprise procurement teams unbundling specialized services from unified communications platforms.
India
Corporate transcription adoption accelerates among business process outsourcing firms serving multinational compliance requirements. The country's national data protection framework shapes vendor infrastructure localization decisions. Bangalore and Hyderabad host technology development centers advancing speaker diarization and entity extraction capabilities.
Business Transcription Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification-grade and speed-tier dimensions in the business transcription market. The vendor base organizes around three strategic archetypes: hybrid AI-human workflow specialists, crowdsourced scale operators, and domain-certified niche providers. Consolidation pressure concentrates among scale players seeking geographic expansion, while technology licensing agreements proliferate between AI engine developers and compliance-focused service layers.
Within the hybrid workflow tier, Verbit and TranscribeMe exemplify architectures optimized for regulated industries requiring human verification. Rev occupies a position representing crowdsourced freelancer models that control cost scaling across enterprise accounts. These three entities anchor competitive positioning around the EU AI Act's human-in-the-loop validation requirements and divergent data residency mandates between the United States and European Union.
| Leading Market Players |
|---|
| GoTranscript |
| GMR Transcription |
| HappyScribe |
| Rev |
| SpeakWrite |
| TranscribeMe |
| Fellow |
| Verbit |
| Fathom |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between verbatim legal transcripts and automated corporate meeting outputs splits pricing power across entirely different supply configurations. Premium-tier vendors commanding certified deposition workflows anchor pricing to stenographer wage rates and court-reporting integration costs, while commodity AI transcription draws from cloud-compute pricing and API volume tiers.
Pricing Analysis
Outcome-based pricing tied to verbatim certification accuracy anchors premium tiers in legal and medical segments. Three-tier pricing structure across certified verbatim, intelligent edited, and automated draft levels reflects quality-grade differentiation and HIPAA or SEC compliance requirements. Pricing pressure stems from AI-based solutions compressing turnaround times in corporate non-evidentiary applications. Fortune 500 compliance departments show lowest price sensitivity for audit-ready documentation, while business process outsourcing firms in India exhibit highest sensitivity to per-minute transcription costs.
Supply Chain Analysis
Certification and qualification gating through court-reporting licensure and medical transcriptionist credentialing concentrates skilled labor supply in the United States, United Kingdom, and India. Raw material dependencies center on cloud infrastructure from AWS, Google Cloud, and Azure, proprietary speech recognition engines, and specialized legal or medical terminology datasets. Supply chain risk manifests in single-source vulnerability for transformer-based NLP models trained on limited high-quality annotated corpora. Distribution runs through direct enterprise sales teams for certified services and self-serve platforms for automated tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
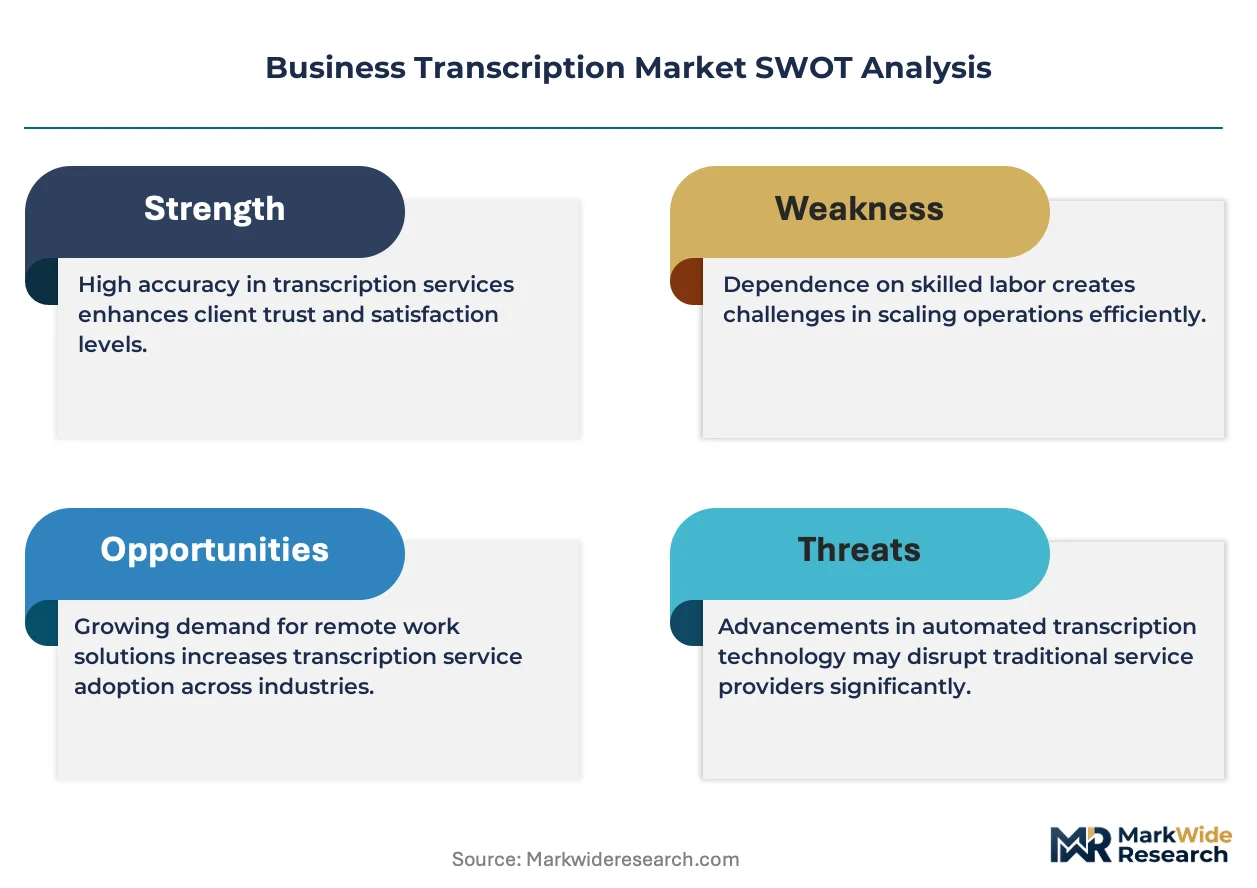
Certified transcriptionist talent scarcity props pricing across legal and medical workflows, constraining supply expansion regardless of AI automation advances. This bottleneck sustains margin pools for hybrid workflow vendors while limiting pure-play AI challengers.
For Market Incumbents: Deploy human-in-the-loop validation infrastructure to defend against pure AI entrants exploiting SEC and EU AI Act compliance documentation requirements. Deepen backward integration into specialized terminology training data and court-reporting software APIs. Consolidate position through acquisition of regional court reporting firms facing succession challenges from aging stenographer workforces.
For New Entrants and Emerging Players: Self-serve platform routes through direct-to-enterprise API sales offer lowest friction entry for automated meeting intelligence targeting mid-market corporate buyers. White-space concentrates in higher-education accessibility compliance where ADA mandates expand procurement but incumbent legal specialists lack pricing flexibility. Target university disability services offices with semester-based subscription models undercutting per-minute legal transcription rates.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by unified communications platforms seeking unbundled transcription capabilities for compliance verticals. Long-term viability favors hybrid workflow specialists with documented EU AI Act certification pathways and established HIPAA or SEC audit relationships. Watch FDA guidance on clinical trial documentation automation as inflection signal for medical transcription valuation compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid AI-Human Workflow Certification | EU AI Act compliance documentation creates competitive moat for transparent architecture vendors. |
| Vertical Integration into Training Data | Proprietary legal and medical corpora anchor model differentiation against generic speech engines. |
| Court Reporting Software API Partnership | Seamless transcript ingestion into case management platforms locks in litigation support workflows. |
| Real-Time Infrastructure Expansion | FCC closed-captioning mandates sustain demand for sub-second latency broadcast transcription services. |
| Higher-Education Accessibility Contracting | ADA lecture captioning requirements expand academic segment with predictable semester-based revenue. |
Methodological Framework
Multi-period observation of transcription procurement volumes, vendor pricing disclosures, and regulatory filing patterns anchored the trend analysis, supplemented by interviews with legal technology procurement officers, court reporting firm executives, university disability services directors, and pharmaceutical regulatory affairs specialists. Secondary validation drew from FCC enforcement records, SEC recordkeeping guidance documents, EU AI Act implementation drafts, and cloud infrastructure capex disclosures. Bottom-up triangulation across service-type segments converged with top-down market sizing from enterprise software procurement databases.
Segment-weighting across verbatim, intelligent, edited, and medical service types combined with end-user splits between legal, corporate, educational, and media buyers shaped the analytical framework. Deployment mode differentiation between real-time and batch processing, plus technology segmentation across hybrid, AI-based, manual, and speech recognition architectures, informed volume and value outputs across the projection horizon. CAGRs were derived from elasticity modeling against compliance mandate enforcement timelines and NLP accuracy improvement curves.
The model holds under sustained regulatory enforcement of SEC, FCC, and EU AI Act documentation requirements; deviation in algorithmic accuracy breakthroughs eliminating human verification needs would shift competitive dynamics toward pure automation. Forecasts reflect assumptions about certification standard persistence and cloud infrastructure cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Australia ICT Market
Digital Solutions
Mobile Campaign Management Market
Digital Solutions
Cognitive Supply Chain Market
Digital Solutions
Location Targeted Mobile Advertising Market
Digital Solutions
Data Pipeline Tools Market
Digital Solutions
Business Information Market
Digital Solutions
Advanced Drill Data Management Solutions Market
Digital Solutions
Desktop Virtualization in Manufacturing Market
Digital Solutions
End-User Computing (EUC) Market
Digital Solutions
North America 3D Rendering Services Market
Digital Solutions
Global Demand Side Platforms (DSP) for Programmatic Advertising Market
Digital Solutions
Ediscovery Market
Digital Solutions
Global Web Hosting Service Market
Digital Solutions
Hyperlocal Services Market
Digital Solutions
Interactive Kiosk Market
Digital Solutions
Remote Integration Solutions Market