
 Location Targeted Mobile Advertising Market | 2026-2036
Location Targeted Mobile Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Location Targeted Mobile Advertising Market Foresight
Quick-service restaurant chains and event organizers are redrawing the demand map for location targeted mobile advertising, pulling budget from traditional retail verticals into proximity-triggered engagement. Google LLC leverages its mapping and search data layers to dominate intent-based geotargeting at scale. Meta Platforms Inc. sustains competitive pressure through social graph density that amplifies local awareness campaigns. Foursquare anchors its position with first-party venue intelligence built on years of consumer check-in behavior.
Location targeted mobile advertising deploys GPS, geofencing, beacon technology, and Wi-Fi positioning to deliver promotional content to devices within defined geographic radii, typically measured in meters for beacon deployments and kilometers for geofenced zones. The system matches real-time spatial coordinates against advertiser-defined boundaries to trigger impressions, with latency requirements under 100 milliseconds for effective footfall attribution. Video ads and native ads are capturing expanding creative budgets as advertisers prioritize viewability and contextual relevance over standard banner formats. Managed services retain the largest revenue share among service types because mid-market advertisers lack in-house programmatic expertise and rely on agency partners for campaign orchestration.
The Federal Trade Commission scrutinizes location data brokers for deceptive collection practices, while the European Union's GDPR mandates explicit opt-in consent before geolocation processing, directly constraining audience pool sizes. Apple's App Tracking Transparency framework forces iOS applications to request permission for precise location access, reshaping addressable inventory on the dominant mobile operating system in North America. Stakeholders must monitor regulatory divergence between Brussels and Washington while calibrating first-party data strategies against platform-level privacy controls.
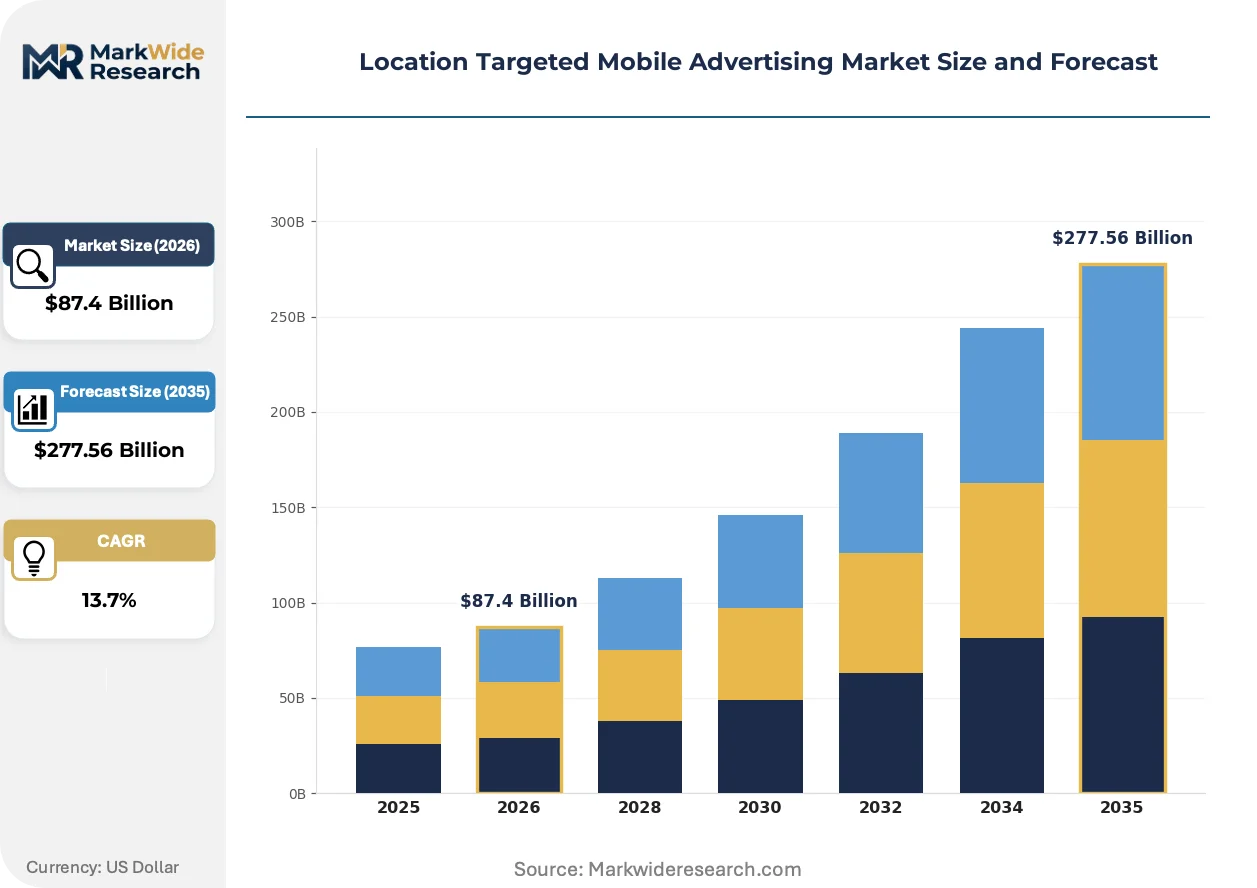
Market Dynamics
Apple's App Tracking Transparency framework has compressed addressable iOS inventory by forcing explicit opt-in for precise location access, forcing advertisers to rebuild targeting models around first-party data and contextual signals rather than device-level geolocation.
Growth Catalysts
- Geofenced QSR Promotions:Quick-service restaurant chains are expanding programmatic spend on proximity-triggered engagement, pulling budget from traditional retail verticals into meter-radius beacon deployments.
- India's Proximity-Sensor Buildout:Dense urban sensor networks in Mumbai, Delhi, and Bangalore are enabling real-time footfall attribution for advertisers seeking granular location intelligence.
- GDPR Consent Framework Maturation:Standardized explicit opt-in protocols across European markets have clarified compliant data collection pathways, reducing legal uncertainty for cross-border campaigns.
Market Restraints
- Input Cost Volatility:Precision GPS chipset supply concentrates among Taiwanese and South Korean fabricators, exposing campaign infrastructure to semiconductor foundry allocation shocks.
- Regulatory Friction:The FTC's scrutiny of location data brokers for deceptive collection practices has triggered inventory freezes among mid-tier aggregators lacking transparent consent chains.
- Technical Latency Floors:Sub-100 millisecond impression-to-attribution requirements demand edge-computing infrastructure that smaller DSPs cannot economically deploy.
Strategic Opportunities
- Underpenetrated Brazil:São Paulo and Rio de Janeiro lack dense beacon networks despite high mobile penetration, creating first-mover advantage for infrastructure investors.
- Regulatory Tailwind:India's Digital Personal Data Protection Act establishes lawful grounds for location processing that could unlock suppressed advertiser demand in the world's largest open mobile market.
- Wi-Fi Positioning Convergence:Fusion of Wi-Fi fingerprinting with 5G network slicing is enabling indoor vertical positioning accuracy previously achievable only through capital-intensive beacon deployments.
Industry Challenges
- Attribution Engineering Talent Gap:Campaign orchestration platforms lack sufficient data scientists capable of building privacy-preserving spatial models that satisfy differential privacy requirements.
- Legacy SSP Integration Friction:Supply-side platforms built on cookie-era architectures require substantial reconfiguration to ingest probabilistic location signals from SKAdNetwork and Privacy Sandbox.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Location Targeted Mobile Advertising Market |
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $277.56 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ad Format: Banner Ads, Video Ads, Native Ads, Interstitial Ads Technology: GPS, Geofencing, Beacon Technology, Wi-Fi Positioning Service Type: Managed Services, Professional Services, Cloud Services, Consulting Services End User: Retailers, Restaurants, Travel Services, Event Organizers |
| Companies Covered | Google LLC, Meta Platforms Inc., Apple Inc., Microsoft Corporation, IBM Corporation, GroundTruth, Foursquare, InMobi, PlaceIQ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Location Targeted Mobile Advertising Market Shifts & Advancements
Advertiser investment is rotating toward creative formats and measurement methodologies that function within privacy-preserving constraints, compressing traditional geotargeting into contextual proximity inference.
Beacon technology is supplanting GPS as the primary indoor positioning mechanism for retail and venue applications. Grocery chains and stadium operators are deploying Bluetooth Low Energy mesh networks at scale to enable sub-meter consumer journey mapping. This shift is compressing the addressable market for pure-play GPS attribution vendors while expanding managed service margins for full-stack proximity providers.
GDPR's Article 6 lawful-basis requirements have forced explicit purpose specification for geolocation processing across European campaigns. Advertisers now segment consent flows by specific use case rather than blanket location permissions. French and German markets show the steepest compliance-driven consolidation, with campaigns unable to demonstrate granular consent routing excluded from major publisher inventories.
Buyer procurement patterns are compressing campaign cycles from quarterly to always-on optimization. Quick-service restaurant marketers now demand real-time footfall attribution dashboards rather than post-campaign reports. This behavioral shift is most visible in the United States, where franchise-level operators bypass agency intermediaries to manage geofenced promotions through self-serve platforms.
Location Targeted Mobile Advertising Market Segmentation
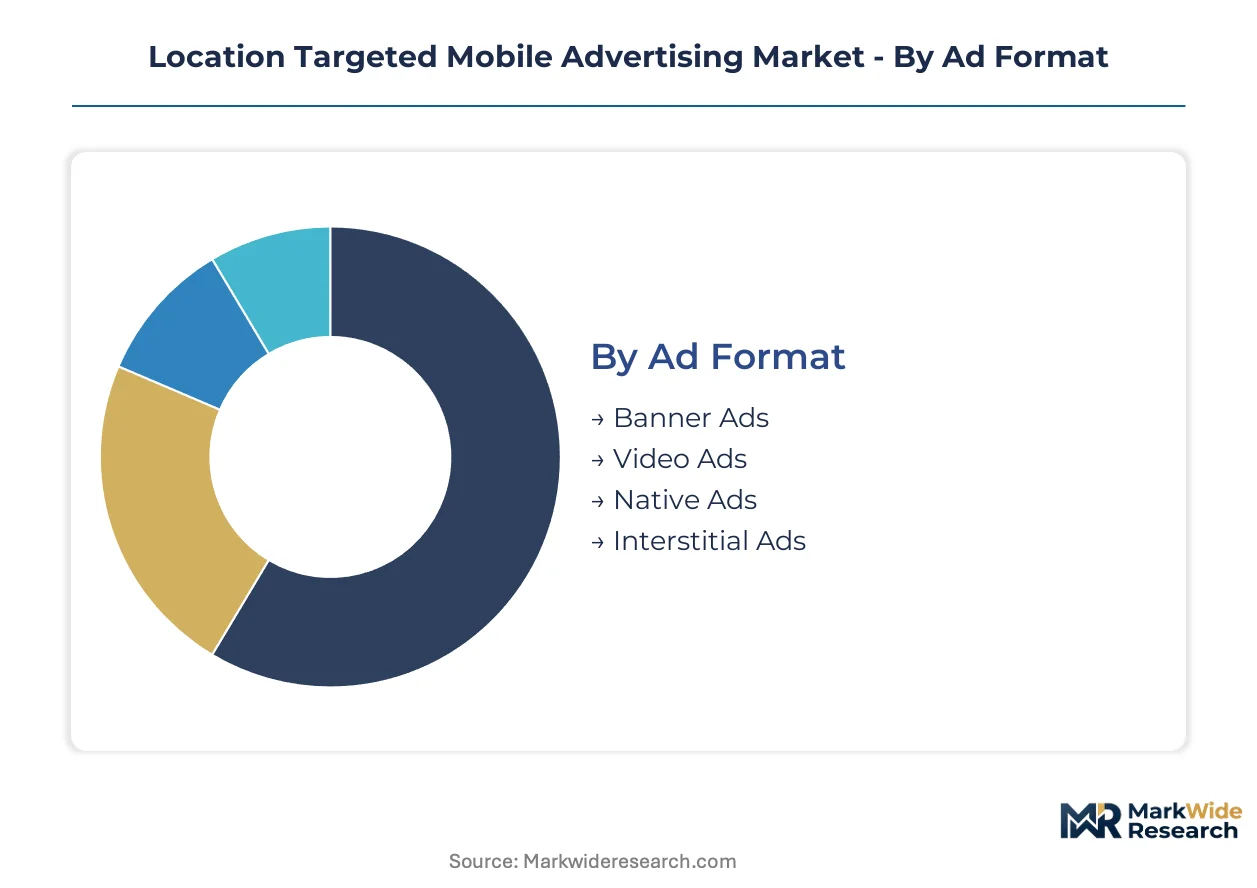
Channel mix determines how location-targeted inventory flows from proximity sensors through DSPs to end advertisers. Format and technology choices directly constrain which service layers capture margin and which end-use verticals access addressable audiences.
Ad Format:
Creative format selection channels through programmatic pipes differently, with viewability standards and latency tolerances filtering which formats reach which inventory pools.
- Video Ads:Vertical and rewarded video units command premium CPMs through in-app SDK integrations. Quick-service restaurant chains in the United States concentrate demand here, driven by completion-rate guarantees that banner inventory cannot match.
- Native Ads:Feed-integrated units leverage contextual signals rather than precise coordinates, making them resilient against Apple's App Tracking Transparency opt-in compression. Publishers in India favor this format for monetizing high-velocity urban traffic without triggering consent fatigue.
- Banner Ads:Standard display units retain volume leadership in remnant inventory clearing through open exchange auctions.
- Interstitial Ads:Full-screen transitions dominate gaming and utility app monetization where session breaks provide natural insertion points.
Video ads dominate installed base. Native ads are where expansion concentrates.
Technology:
Positioning infrastructure investment stratifies by accuracy requirements and capital intensity, with each technology locking into distinct venue types and attribution use cases.
- Geofencing:GPS-radius targeting enables kilometer-scale audience capture for regional retail campaigns. China's dense urban corridors concentrate deployment here, driven by municipal smart-city investments that subsidize boundary-drawing infrastructure.
- Beacon Technology:Bluetooth Low Energy mesh networks deliver sub-meter accuracy for indoor journey mapping. Stadium operators and grocery chains in the United States anchor demand, requiring capital-intensive hardware installation that excludes smaller venue operators.
- GPS:Satellite-based positioning remains the default for outdoor, vehicle-mounted, and rural inventory where beacon density is uneconomical.
- Wi-Fi Positioning:Fingerprinting techniques exploit existing access point density to bypass beacon hardware costs in multi-floor retail environments.
Geofencing dominates installed base. Beacon technology is where expansion concentrates.
Service Type:
Service layer selection tracks advertiser sophistication, with self-serve platforms capturing franchise-level operators while enterprise accounts retain agency intermediation.
- Managed Services:Full-stack campaign orchestration including creative adaptation, bid management, and footfall attribution. Mid-market advertisers lacking in-house programmatic expertise concentrate demand here, particularly in the United States where franchise operators bypass direct platform access.
- Professional Services:Custom integration and data science engagements for enterprise accounts with first-party location assets.
- Cloud Services:API-accessible infrastructure for publishers and large advertisers with internal trading desk capabilities.
- Consulting Services:Privacy compliance and consent architecture advisory, expanding fastest in European markets under GDPR Article 6 enforcement.
Managed services dominate installed base. Consulting services are climbing the fastest.
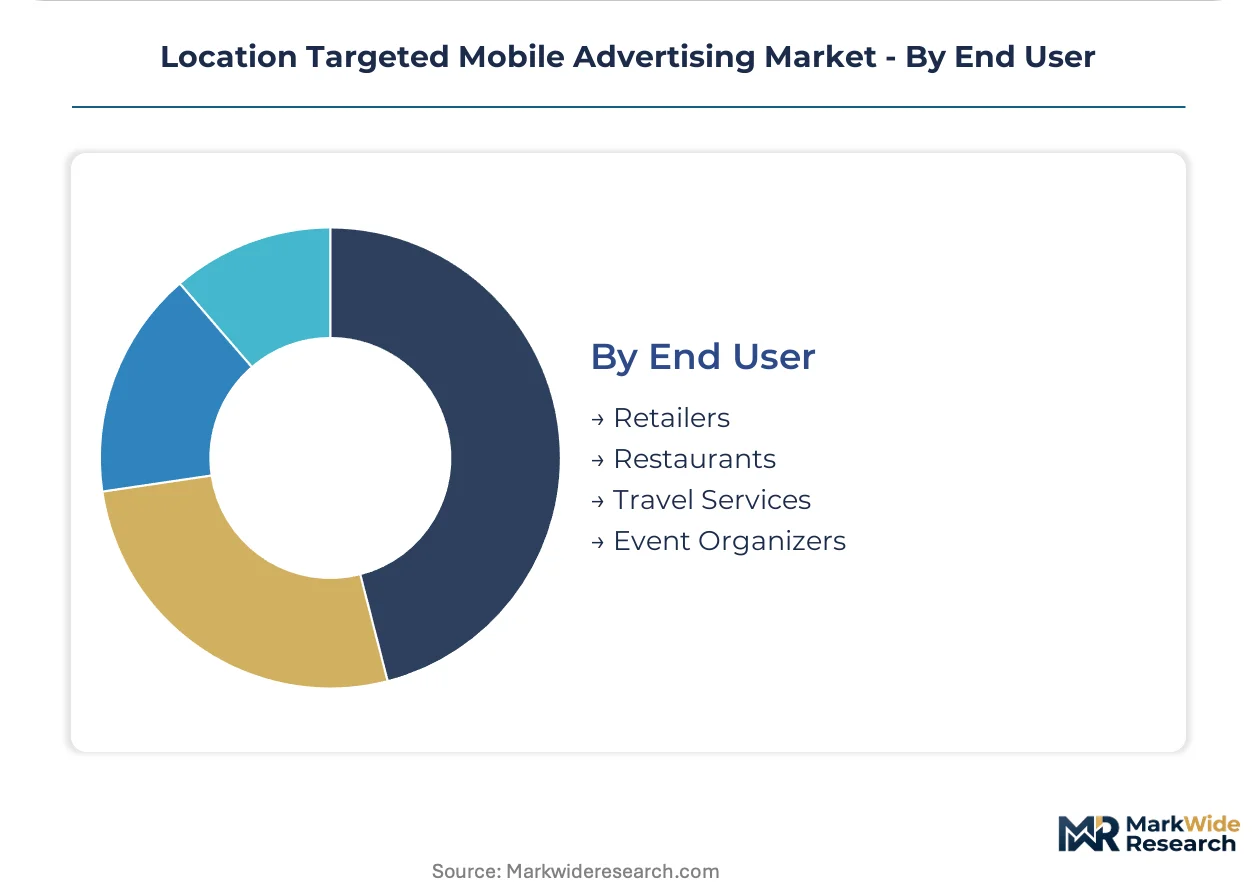
End User:
Vertical demand patterns diverge sharply by attribution requirements, with footfall-proximate sectors pulling budget from impression-based legacy categories.
- Restaurants:Quick-service chains deploy meter-radius beacon triggers for promotional redemption at point-of-sale. India's emerging proximity-sensor buildout in Mumbai and Delhi is unlocking suppressed demand from organized QSR networks seeking real-time attribution dashboards.
- Event Organizers:Temporary venue deployments require rapid geofence configuration and post-event audience extension. Music festivals and sporting venues in Brazil concentrate experimental spend here, despite sparse permanent beacon infrastructure.
- Retailers:Department stores and grocery chains balance indoor beacon networks against Wi-Fi positioning for cost-efficient floor-plan analytics.
- Travel Services:Airlines and hotel chains leverage airport and transit hub geofences for itinerary-triggered ancillary offers.
Restaurants dominate installed base. Event organizers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Submarine cable landing stations in Mumbai, Chennai, and Cochin anchor India's data throughput capacity for real-time programmatic bidding. Dense fiber backhaul from these coastal hubs enables sub-100 millisecond latency for location-triggered ad serving across the subcontinent's urban corridors.
United States
Quick-service restaurant chains concentrate programmatic spend on geofenced promotions, pulling budget from traditional retail verticals into meter-radius beacon deployments. The FTC scrutinizes location data brokers for deceptive collection practices, triggering inventory freezes among mid-tier aggregators. Franchise operators in Texas and Florida bypass agency intermediaries to manage campaigns through self-serve platforms.
China
Municipal smart-city investments in Shanghai, Beijing, and Shenzhen subsidize kilometer-scale geofence boundary-drawing infrastructure for regional retail campaigns. SAMR enforces data localization requirements that constrain cross-border audience extension. Dense urban corridors concentrate GPS-radius targeting deployment unmatched elsewhere in volume.
India
Organized QSR networks in Mumbai, Delhi, and Bangalore seek real-time attribution dashboards as proximity-sensor buildout accelerates. The Digital Personal Data Protection Act establishes lawful grounds for location processing that could unlock suppressed advertiser demand. Bengaluru's technology corridor hosts the highest density of DSP engineering talent for privacy-preserving spatial models.
Germany
GDPR Article 6 enforcement drives steepest compliance-driven consolidation among European markets. French and German publishers exclude campaigns unable to demonstrate granular consent routing. Berlin and Munich anchor demand for consulting services on privacy compliance and consent architecture advisory.
Brazil
São Paulo and Rio de Janeiro lack dense beacon networks despite high mobile penetration, creating first-mover advantage for infrastructure investors. Music festivals and sporting venues concentrate experimental spend on temporary geofence configuration. ANVISA's data protection framework remains less prescriptive than European counterparts, reducing legal friction for audience pool construction.
Location Targeted Mobile Advertising Market Competitive Landscape
Concentration sits with platform-scale technology providers that control mapping infrastructure, mobile operating systems, or social graph density. The vendor base stratifies across three tiers: hyperscale cloud platforms with proprietary location data layers, independent ad-tech specialists with first-party venue intelligence, and managed service agencies serving mid-market franchise operators. Strategic moves center on first-party data consolidation and privacy-preserving attribution engineering rather than capacity expansion.
Within the platform tier, Google LLC and Meta Platforms Inc. occupy positions defined by their control of intent signals and social graph density respectively. Foursquare exemplifies the specialist archetype, anchoring its competitive position on years of accumulated consumer check-in behavior. These three entities represent distinct strategic vectors: mapping-derived intent targeting, social amplification of local awareness, and venue-specific first-party intelligence.
| Leading Market Players |
|---|
| Google LLC |
| Meta Platforms Inc. |
| Apple Inc. |
| Microsoft Corporation |
| IBM Corporation |
| GroundTruth |
| Foursquare |
| InMobi |
| PlaceIQ |
| Others |
Supply & Pricing Matrix
Ninety-day inventory cycles for precision GPS chipsets concentrate pricing power among Taiwanese and South Korean fabricators, compressing margins for demand-side platforms that cannot secure long-term allocation agreements. This lead-time structure forces advertisers into annual subscription commitments with managed service providers to lock in beacon deployment capacity ahead of semiconductor foundry shocks.
Pricing Analysis
Volume-discount tiering separates enterprise self-serve platforms from mid-market managed service bundles and remnant inventory spot clearing. SaaS-tiered subscription models dominate, with price differentiation driven by attribution granularity and GDPR compliance certification tiers. Pricing pressure stems from Apple's App Tracking Transparency opt-in compression eroding addressable CPMs. Franchise operators exhibit highest price sensitivity, while enterprise advertisers with first-party data assets absorb premium tiers for differential privacy engineering.
Supply Chain Analysis
Inbound logistics costs through the Shanghai-Singapore trade lane fluctuate with container availability, exposing beacon hardware importers to port congestion surcharges. Component sourcing draws from Taiwan for GPS chipsets, South Korea for Bluetooth Low Energy modules, and China for sensor assembly. Single-source vulnerability concentrates in precision semiconductor fabrication. Distribution runs through hyperscale cloud platforms that bundle location intelligence with compute infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in location-targeted advertising hinge on interoperability between SKAdNetwork attribution and first-party data clean rooms, compressing competitive advantage into consent-architecture control points.
For Market Incumbents: Secure first-party venue intelligence through exclusive data partnerships with stadium operators and grocery chains before emerging DSPs replicate Foursquare's check-in archive model. Consolidate differential privacy engineering talent to defend against Apple's Privacy Sandbox displacement of device-level geolocation. Vertical integration into edge-computing infrastructure protects sub-100 millisecond latency guarantees.
For New Entrants and Emerging Players: Anchor in Brazil's São Paulo and Rio de Janeiro corridor where beacon infrastructure remains underpenetrated despite high mobile penetration. Target temporary event geofencing for music festivals and sporting venues as the fastest-validated entry point. Pursue Wi-Fi positioning convergence with 5G network slicing to bypass capital-intensive hardware deployment.
For Investors and Strategic Acquirers: Long-term, this sits as a data-utility play because location intelligence will consolidate into infrastructure layers analogous to mapping services. Acquisition targets should display first-party consent architecture and privacy-preserving attribution engineering capabilities. Watch India's Digital Personal Data Protection Act enforcement as the signal for regulatory tailwind unlocking suppressed advertiser demand.
| Strategic Initiative | Industry Significance |
|---|---|
| First-Party Data Partnership | Exclusive venue intelligence from stadium operators locks in competitive moats against replication. |
| Privacy-Preserving Attribution Engineering | Differential privacy capabilities satisfy GDPR Article 6 while maintaining campaign measurement accuracy. |
| Edge-Computing Infrastructure Deployment | Sub-100 millisecond latency guarantees secure footfall attribution contracts with QSR franchise networks. |
| SKAdNetwork Integration | Apple's attribution framework compatibility preserves iOS inventory access against platform exclusion. |
| Geographic Expansion into Brazil | São Paulo's sparse beacon density creates first-mover infrastructure advantage before competitor saturation. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, App Annie mobile intelligence, hyperscaler capex disclosures, and programmatic platform technical documentation. Interview inputs gathered from DSP engineering directors, QSR franchise marketing officers, privacy compliance consultants, and beacon hardware procurement leads. Bottom-up triangulation across ad format volumes and top-down validation against platform revenue disclosures anchor the analytical framework.
Segmentation dimensions modeled span ad format type, positioning technology, service layer, and end-use vertical across the projection horizon. CAGRs derive from installed base penetration curves and replacement cycle analysis for beacon hardware. Forecast inputs incorporate GDPR consent-rate trajectories and India's proximity-sensor deployment schedules.
Material uncertainties — regulatory divergence between Brussels and Washington, semiconductor foundry allocation shocks, iOS opt-in rate volatility — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as Apple's Privacy Sandbox and Google's Privacy Sandbox timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
IT Operations and Service Management (ITOSM) Market
Digital Solutions
Smart Card in Government Market
Digital Solutions
US Digital Twin Market
Digital Solutions
Big Data As a Service (Bdaas) Market
Digital Solutions
Docker Monitoring Market
Digital Solutions
Global B2B Buyer Intent Data Tools Market
Digital Solutions
Decision Management Applications Market
Digital Solutions
Mobile Engagement Market
Digital Solutions
Warranty Management System Market
Digital Solutions
Global Intelligent Platform Management Interface (IPMI) Market
Digital Solutions
Core Graphics Market
Digital Solutions
OTA Transmission Platform Market
Digital Solutions
France ICT Market
Digital Solutions
Cloud Field Service Management (FSM) Market
Digital Solutions
Location As a Service Market
Digital Solutions
Social Employee Recognition Systems Market