
 Hyperlocal Services Market | 2026-2036
Hyperlocal Services Market Size, Share, and Industry Trends Forecast 2026-2036
Hyperlocal Services Market Intelligence
ISO 9001 quality management certification is redrawing competitive boundaries in hyperlocal logistics, forcing smaller operators into costly compliance upgrades. Zepto leverages its dark-store network to sustain sub-15-minute delivery promises across Indian metros. Jugnoo anchors its position through auto-rickshaw fleet integration, competing on cost in tier-2 Indian cities. OneRail differentiates via multi-modal orchestration software, controlling dispatch across contracted courier pools in North American urban corridors.
Hyperlocal services denote geographically constrained fulfillment networks—typically sub-5-kilometer radii—coordinating inventory, labor, and delivery assets through real-time demand-matching algorithms. These systems rely on GPS-tagged fleet tracking, predictive inventory positioning, and dynamic surge pricing to compress delivery windows for perishable and time-sensitive goods. Food delivery commands the largest transaction volume among service types, though grocery delivery captures expanding basket sizes as dark-store density rises. Residential consumers dominate customer type flows, while corporate offices represent a maturing segment with contracted catering and supply replenishment cycles.
The EU's Platform Work Directive and India's PLI scheme for logistics technology are tightening labor classification rules and subsidizing automation investments respectively, reshaping cost structures for cross-border operators. The US Department of Labor's evolving independent contractor standards and OSHA last-mile safety guidelines further constrain fleet management flexibility. Stakeholders must monitor regulatory divergence between jurisdictions as compliance fragmentation threatens unit economics in multi-country expansion strategies.
Market Dynamics
Dark-store density and predictive inventory positioning are compressing delivery windows below 15 minutes, forcing operators to reconfigure fulfillment networks around sub-5-kilometer radii and real-time demand-matching algorithms.
Growth Catalysts
- India's PLI scheme for logistics technology:Subsidies for automation investments accelerate warehouse robotics deployment and fleet tracking systems across metropolitan corridors.
- Residential consumers in dense urban clusters:On-demand grocery delivery adoption concentrates in Mumbai and Bangalore, rewarding hyperlocal specialization with superior last-mile density.
- Dynamic surge pricing algorithms:Real-time labor-cost optimization enables operators to match perishable inventory volatility with elastic workforce deployment.
Market Restraints
- Labor reclassification costs:The EU's Platform Work Directive tightens contractor classification rules, inflating compliance overhead for cross-border operators.
- Dark-store real estate scarcity:Premium urban warehouse space in Indian metros commands escalating rents, squeezing unit economics for sub-15-minute delivery promises.
- Perishable inventory spoilage:Compressed fulfillment windows intensify cold-chain failure risks across unregulated last-mile handoffs.
Strategic Opportunities
- Tier-2 Indian city expansion:Auto-rickshaw fleet integration unlocks cost-efficient penetration where four-wheeler density remains insufficient.
- Corporate office catering contracts:Maturing B2B segments offer contracted replenishment cycles with predictable demand patterns and lower churn.
- ISO 9001 quality certification:Compliance differentiation creates procurement preference among institutional buyers seeking audited supply chain transparency.
Industry Challenges
- Multi-jurisdiction compliance fragmentation:Divergent OSHA last-mile safety guidelines, EU labor directives, and Indian automation subsidies force parallel legal frameworks.
- GPS-tagged fleet integration:Legacy dispatch systems require costly API overhauls to synchronize with predictive inventory positioning software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyperlocal Services Market |
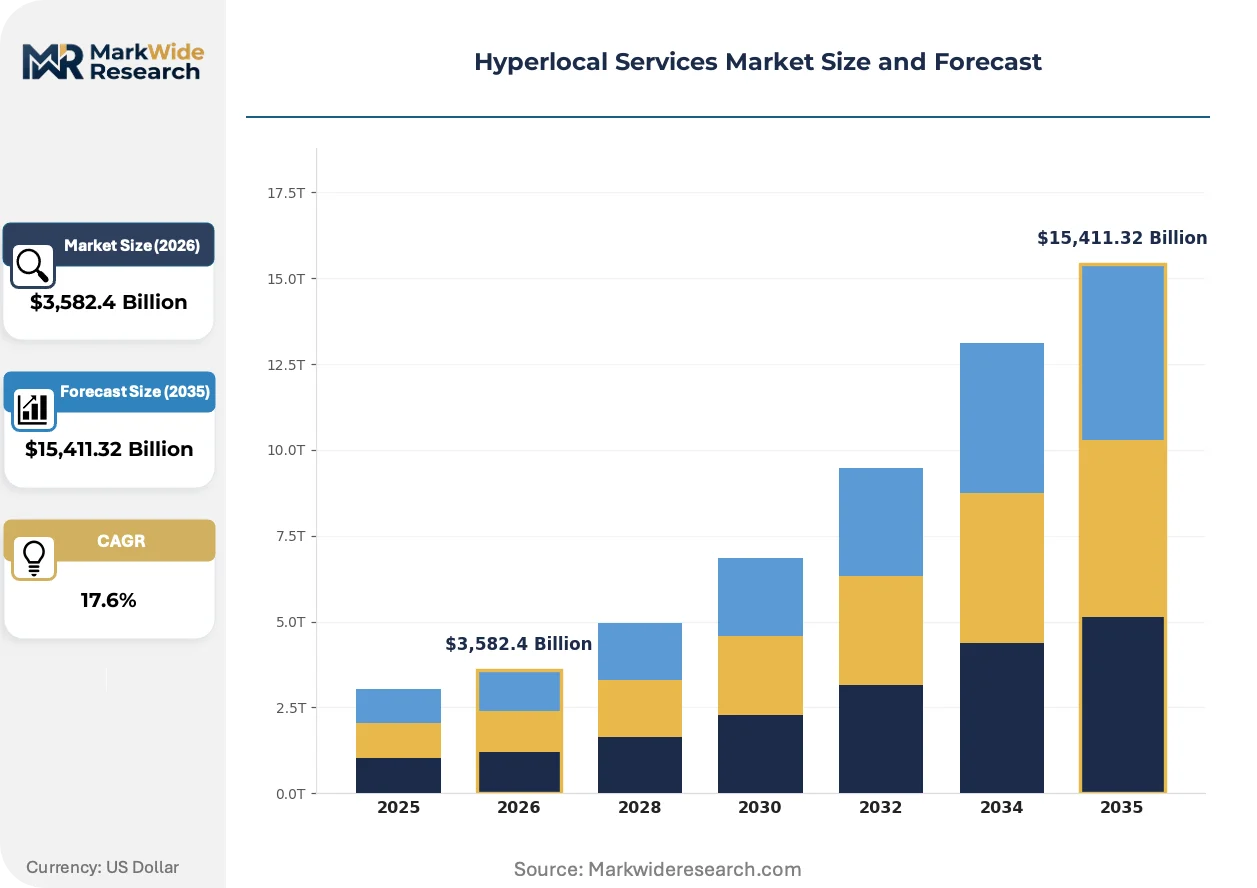
| Market Size in 2026 | $3,582.4 Billion |
| Market Size in 2035 | $15,411.32 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Food Delivery, Grocery Delivery, Home Services, Personal Care Customer Type: Residential Consumers, Small Businesses, Corporate Offices, Freelancers Technology: Mobile Apps, Web Platforms, Chatbots, Delivery Management End User: Households, Hospitality Sector, Retail Stores, Event Organizers |
| Companies Covered | Zepto, Jugnoo, OneRail, Handitova, Fetch.com, Jitsu, JOKR, Locus.sh, Arrivy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyperlocal Services Market Strategic Shifts & Innovations
Predictive analytics and automated dispatch systems are displacing manual coordination across hyperlocal fulfillment networks, compressing the gap between demand signal and inventory deployment.
Micro-fulfillment center technology is miniaturizing warehouse footprints to 2,000-5,000 square feet, embedding directly within residential neighborhoods. Quick-commerce operators in Indian metros deploy these facilities at 1-2 kilometer intervals. This density is miniaturizing the traditional 10-15 kilometer distribution radius into sub-5-kilometer catchments that sustain sub-15-minute delivery windows.
The EU's Platform Work Directive mandates algorithmic transparency and reclassified employment status for gig workers. Operators face payroll tax restructuring and benefits obligations previously externalized to contractors. Food delivery platforms in Germany and France accelerate automation investments to offset labor cost inflation.
Subscription-based replenishment models displace spontaneous ordering for household staples. Urban residential clusters in Bangalore and Mumbai pilot weekly grocery bundles with locked-in delivery slots. This behavioral shift reduces peak-hour surge dependency and improves fleet utilization for operators willing to sacrifice per-order premiums for volume predictability.
Hyperlocal Services Market Segmentation
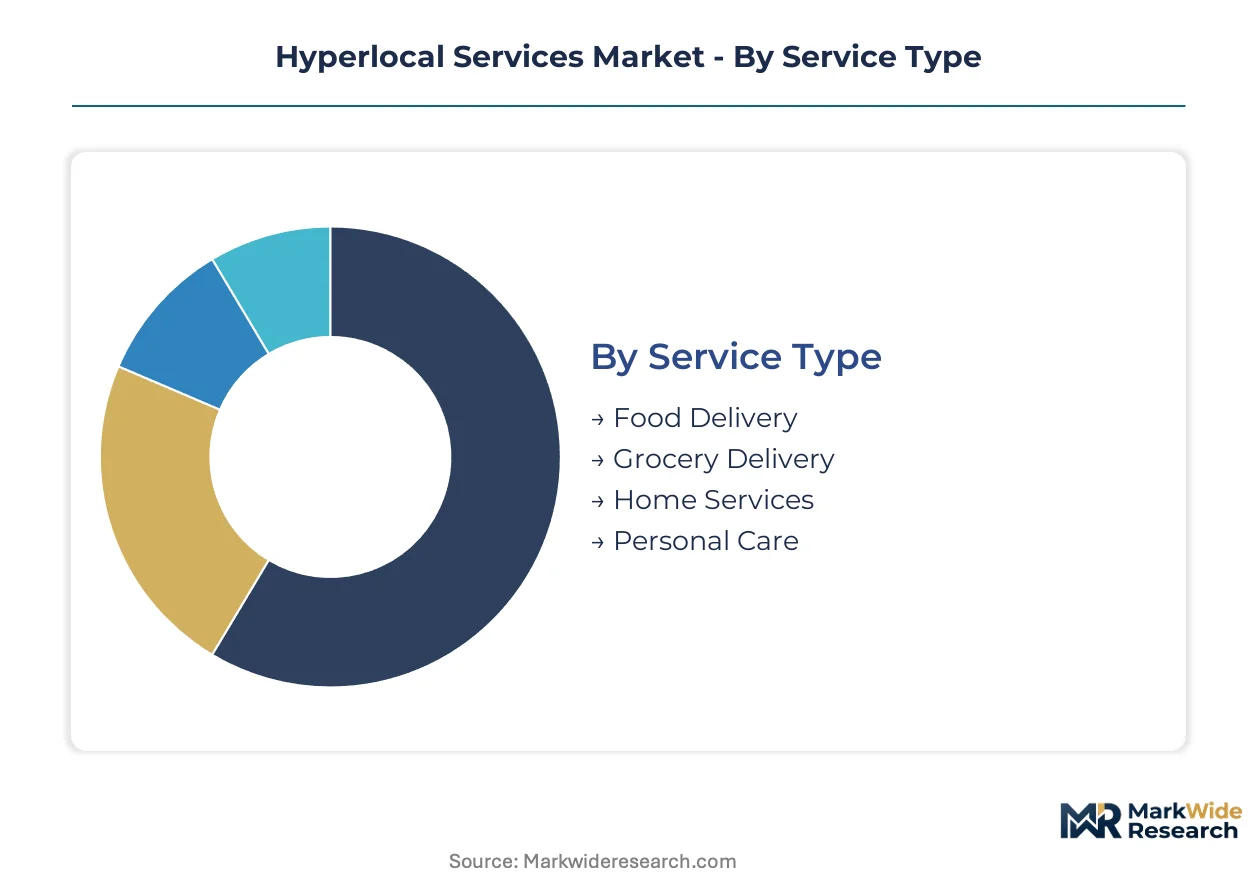
Hyperlocal operators configure fulfillment networks around precise service-type economics and customer-density patterns. Segmentation reveals where sub-15-minute delivery promises extract premium pricing versus where cost-efficient auto-rickshaw fleets sustain margins.
Service Type:
Margin pools concentrate in perishable categories where compression of delivery windows commands surge pricing tolerance.
- Food Delivery:Real-time demand-matching algorithms coordinate kitchen preparation with fleet dispatch across sub-5-kilometer radii. Mumbai and Bangalore residential clusters generate the highest transaction frequency, though per-order margins erode under promotional subsidy wars.
- Grocery Delivery:Dark-store density at 1-2 kilometer intervals enables sub-15-minute fulfillment for fresh produce and household staples. Predictive inventory positioning in Indian metros reduces stockout rates while cold-chain investments inflate fixed costs.
- Home Services:Skilled labor matching for repairs and maintenance operates on scheduled slots rather than instant dispatch. Unit economics favor tier-2 Indian cities where technician availability exceeds platform density.
- Personal Care:Appointment-based scheduling for beauty and wellness services relies on verified professional networks. Customer acquisition costs run higher than on-demand categories due to lower purchase frequency.
Food Delivery holds installed capacity. Grocery Delivery is rotating up the share rankings.
Customer Type:
Volume concentration follows residential density, though contracted B2B relationships deliver superior retention economics.
- Residential Consumers:Dense urban clusters in Indian metropolitan corridors generate recurring demand for convenience-driven replenishment. Subscription-based weekly bundles in Bangalore and Mumbai reduce peak-hour surge dependency.
- Corporate Offices:Contracted catering and supply replenishment cycles offer predictable demand patterns with lower churn than individual accounts. ISO 9001 certification unlocks procurement preference among institutional buyers.
- Small Businesses:Inventory restocking and administrative support services concentrate in commercial districts with sufficient order density to justify dedicated fleet allocation.
- Freelancers:Gig workers themselves constitute a distinct demand segment for equipment rental and workspace access, though transaction values remain below household and corporate tiers.
Residential Consumers anchor volume throughput. Corporate Offices are climbing the fastest toward margin contribution.
Technology:
Platform infrastructure investments differentiate operators capable of predictive positioning from those reliant on manual dispatch.
- Mobile Apps:GPS-tagged interfaces enable real-time tracking and dynamic surge pricing across Android and iOS ecosystems. India's PLI scheme for logistics technology subsidizes backend automation upgrades.
- Web Platforms:Browser-based ordering captures corporate procurement workflows requiring multi-user approval chains. Lower development costs than native apps attract capital-constrained entrants.
- Chatbots:Conversational interfaces handle routine order modifications and delivery rescheduling without human agent intervention. Natural language processing investments concentrate in English-Hindi bilingual markets.
- Delivery Management:Multi-modal orchestration software controls dispatch across contracted courier pools and owned fleet assets. API integration costs burden operators with legacy dispatch systems.
Mobile Apps dominate customer-facing investment. Delivery Management is gaining share fastest as fleet complexity escalates.
End User:
Demand fragmentation across end-use contexts forces modular fulfillment configurations.
- Households:Residential replenishment of perishables and convenience goods sustains the core transaction base. Dark-store miniaturization embeds fulfillment directly within neighborhood catchments.
- Hospitality Sector:Hotels and restaurants require just-in-time ingredient delivery with strict temperature compliance. Cold-chain failure risks intensify across unregulated last-mile handoffs.
- Retail Stores:Kirana shops and convenience stores leverage hyperlocal platforms for emergency stockouts and promotional inventory. Smaller basket sizes compress per-order profitability.
- Event Organizers:Time-bound catering and equipment logistics demand surge-capable fleet scaling. Seasonal demand concentration strains year-round asset utilization.
Households anchor installed demand. Hospitality Sector is rotating up the share rankings as B2B contracts mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for logistics technology subsidizes warehouse automation and fleet tracking systems, accelerating hyperlocal network deployment across metropolitan corridors. The EU's Platform Work Directive tightens labor classification rules, inflating compliance costs for cross-border operators. Divergent regulatory frameworks reshape capital allocation toward automation-heavy markets.
United States
OSHA last-mile safety guidelines constrain fleet management flexibility for independent contractor networks. The Department of Labor's evolving contractor standards force payroll restructuring across gig-based delivery platforms. New York and San Francisco metropolitan clusters concentrate dark-store real estate competition, squeezing unit economics for sub-15-minute delivery promises.
Germany
The EU's Platform Work Directive mandates algorithmic transparency and reclassified employment status for gig workers. Food delivery platforms accelerate automation investments to offset labor cost inflation. Berlin and Munich urban corridors witness consolidation of micro-fulfillment centers at 1-2 kilometer density intervals.
India
PLI scheme subsidies for logistics technology accelerate warehouse robotics deployment across metropolitan corridors. FSSAI cold-chain regulations intensify compliance requirements for perishable inventory handoffs. Mumbai and Bangalore residential clusters generate the highest transaction frequency for on-demand grocery delivery, rewarding hyperlocal specialization.
United Kingdom
GDPR data processing rules complicate GPS-tagged fleet tracking implementations across delivery management platforms. The national minimum wage framework for gig workers inflates operational overhead relative to contractor models. London's dense urban fabric sustains dark-store miniaturization at neighborhood-scale catchments.
China
SAMR antitrust enforcement limits platform exclusivity arrangements between merchants and delivery operators. MIIT data localization requirements constrain cross-border algorithmic training for demand-matching systems. Yangtze River Delta metropolitan clusters concentrate quick-commerce infrastructure investment at sub-5-kilometer radii.
Hyperlocal Services Market Key Industry Players
Player mix skews toward vertically integrated quick-commerce specialists and multi-modal orchestration platforms. The vendor base fragments across dark-store operators, auto-rickshaw fleet integrators, and enterprise delivery management software providers. Three archetypes dominate: sub-15-minute grocery specialists, cost-efficient tier-2 city penetrators, and B2B multi-modal orchestrators. Competitive moves concentrate on dark-store real estate acquisition and predictive inventory software licensing.
Within the quick-commerce specialist tier, Zepto anchors sub-15-minute delivery positioning through dark-store network density. Jugnoo exemplifies cost-efficient tier-2 penetration via auto-rickshaw fleet integration. OneRail occupies the multi-modal orchestration segment, controlling dispatch across contracted courier pools. These three represent divergent geographic and operational strategies within the broader competitive set.
| Leading Market Players |
|---|
| Zepto |
| Jugnoo |
| OneRail |
| Handitova |
| Fetch.com |
| Jitsu |
| JOKR |
| Locus.sh |
| Arrivy |
| Others |
Cost & Logistics Intelligence
Dark-store miniaturization replacing traditional distribution centers simultaneously compresses last-mile radii and inflates fixed-cost absorption, redrawing how operators price delivery speed against inventory positioning economics.
Pricing Analysis
Certification level creates the primary spread between ISO 9001-audited operators and uncertified competitors, with institutional buyers paying premiums for supply chain transparency. Three-tier pricing structure across premium, standard, and economy levels segments residential consumers by delivery window tolerance, while corporate accounts negotiate contracted rates. Pricing pressure stems from dark-store real estate scarcity in Mumbai and Bangalore, where escalating rents squeeze sub-15-minute promise margins. Price-sensitive residential consumers in tier-2 Indian cities favor auto-rickshaw fleet options, while ISO-certified operators command least sensitivity among institutional procurement committees.
Supply Chain Analysis
India anchors warehouse robotics deployment through PLI scheme subsidies, while Germany and the United States concentrate predictive inventory software development. Cold-chain infrastructure draws from specialized refrigeration component suppliers in China and South Korea, with fleet tracking hardware sourced from Taiwan semiconductor fabricators. Single-source vulnerability runs through unregulated last-mile handoffs where temperature compliance fails. Distribution runs through micro-fulfillment centers embedded at 1-2 kilometer density intervals within residential neighborhoods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU's Platform Work Directive and India's automation subsidies constitute a regulatory inflection accelerating capital flight from labor-heavy toward robotics-dependent fulfillment models.
For Market Incumbents: Fortify dark-store real estate positions in Mumbai and Bangalore through long-term lease lock-ins before premium warehouse scarcity intensifies. Deepen backward integration into predictive inventory software licensing to defend against multi-modal orchestration platforms eroding dispatch control. ISO 9001 certification investment anchors procurement preference among institutional buyers seeking audited transparency. For New Entrants and Emerging Players: Differentiate on auto-rickshaw fleet integration in tier-2 Indian cities where four-wheeler density remains insufficient and cost efficiency rewards hyperlocal specialization. Target corporate office catering contracts in Bangalore and Mumbai, where predictable replenishment cycles offer lower churn than individual residential accounts. Pursue chatbot-native customer acquisition in Hindi-English bilingual markets to reduce human agent overhead. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed quick-commerce specialists holding dark-store networks in Indian metropolitan corridors. Long-term viability hinges on automation-heavy unit economics surviving labor reclassification waves across European jurisdictions. Watch FSSAI cold-chain enforcement intensity as the signal indicating regulatory preference for capital-intensive compliance over lean operator models.| Strategic Initiative | Industry Significance |
|---|---|
| Dark-Store Network Densification | Embedding micro-fulfillment centers at 1-2 kilometer intervals sustains sub-15-minute delivery promises in Mumbai and Bangalore residential clusters. |
| Auto-Rickshaw Fleet Integration | Cost-efficient penetration of tier-2 Indian cities unlocks margin preservation where four-wheeler density cannot support unit economics. |
| ISO 9001 Certification Pathway | Audited quality management systems create procurement preference among institutional buyers seeking supply chain transparency. |
| Predictive Inventory Software Licensing | Real-time demand-matching algorithms reduce stockout rates while compressing the gap between demand signal and inventory deployment. |
| Corporate Catering Contract Acquisition | Predictable B2B replenishment cycles improve fleet utilization and reduce peak-hour surge dependency compared to residential spontaneity. |
Research Approach
Cross-validation between primary interviews with dark-store operators, fleet dispatch managers, and FSSAI compliance officers and secondary validation through customs automation equipment import records anchors the qualitative findings. Bottom-up triangulation incorporates India's PLI scheme subsidy disbursement data, EU Platform Work Directive implementation timelines, and OSHA last-mile safety guideline drafts. Top-down verification draws from warehouse robotics deployment permits and micro-fulfillment center real estate transaction databases across metropolitan corridors.
Sensitivity analysis across service type, customer type, technology platform, and end-use context shapes the analytical framework over the projection horizon. CAGRs derive from segment-level demand elasticity modeling against dark-store density thresholds and labor cost inflation scenarios. Modeled inputs include predictive inventory positioning adoption curves, auto-rickshaw fleet penetration rates in tier-2 cities, and ISO 9001 certification uptake among institutional procurement committees.
The analysis sits within stated boundaries; outcomes outside sustained PLI scheme funding or accelerated EU labor reclassification would require recalibration. Forecasts reflect documented assumptions about cold-chain infrastructure buildout and GPS-tagged fleet integration costs. Recalibration cycles align with material shifts in FSSAI enforcement intensity, dark-store real estate availability, and algorithmic transparency mandate implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Electronic Data Interchange (EDI) Market
Digital Solutions
Global Data Collection and Labeling Market
Digital Solutions
Product Prototyping Market
Digital Solutions
Manufacturing Execution System Market
Digital Solutions
Europe Online Dating Services Market
Digital Solutions
Service Fulfillment Market
Digital Solutions
Data Marketplace Platform Market
Digital Solutions
Context Rich Systems Market
Digital Solutions
IT Operations Management Market
Digital Solutions
Automatic Identification and Data Capture Market
Digital Solutions
United States ICT Market
Digital Solutions
Global BYOD and Enterprise Mobility Market
Digital Solutions
Global Photo Management Software Market
Digital Solutions
Landing Page Builders Market
Digital Solutions
Barcode Software Market
Digital Solutions
Bahrain ICT Market