
 Ediscovery Market | 2026-2036
Ediscovery Market Size, Share, and Industry Trends Forecast 2026-2036
Ediscovery Market Analysis
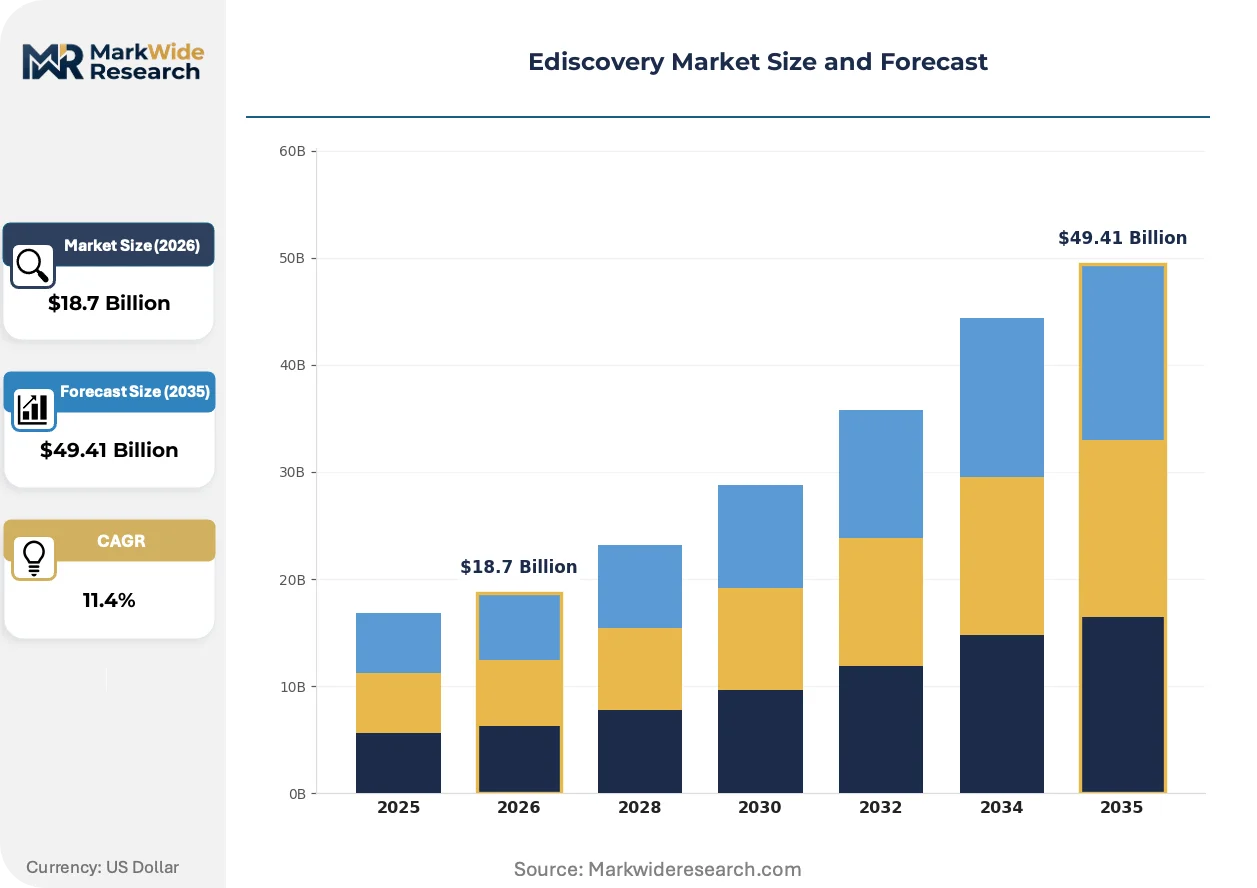
Forensic data analyst talent is collapsing across North America and Western Europe, forcing ediscovery vendors to automate review workflows or outsource to lower-cost jurisdictions. Relativity leverages its proprietary analytics engine to sustain platform stickiness among Am Law 200 firms. Microsoft Corporation anchors enterprise adoption by embedding Purview ediscovery tools within the Office 365 ecosystem. Nuix Limited differentiates through specialized processing of unstructured data formats at petabyte scale.
Ediscovery encompasses the identification, preservation, collection, processing, review, and production of electronically stored information for legal proceedings, typically requiring indexing speeds exceeding 100,000 documents per hour and native file format reconstruction capabilities. Cloud-based deployment leads segment growth as law firms and corporations migrate away from capital-intensive on-premise infrastructure, while managed services capture expanding margin pools by bundling technology with attorney review labor. The legal industry vertical dominates current revenue, though financial services shows accelerating adoption driven by SEC examination and enforcement workflows.
The Federal Rules of Civil Procedure, supplemented by state bar ethics opinions on technology competence, shape product standards by mandating defensible preservation and proportionality in discovery scope. The EU General Data Protection Regulation and emerging state privacy laws in California and Virginia constrain cross-border data transfer mechanisms, forcing vendors to architect region-specific hosting environments. Stakeholders must monitor evolving AI governance frameworks as automated document classification tools face judicial scrutiny over algorithmic transparency and bias.
Market Dynamics
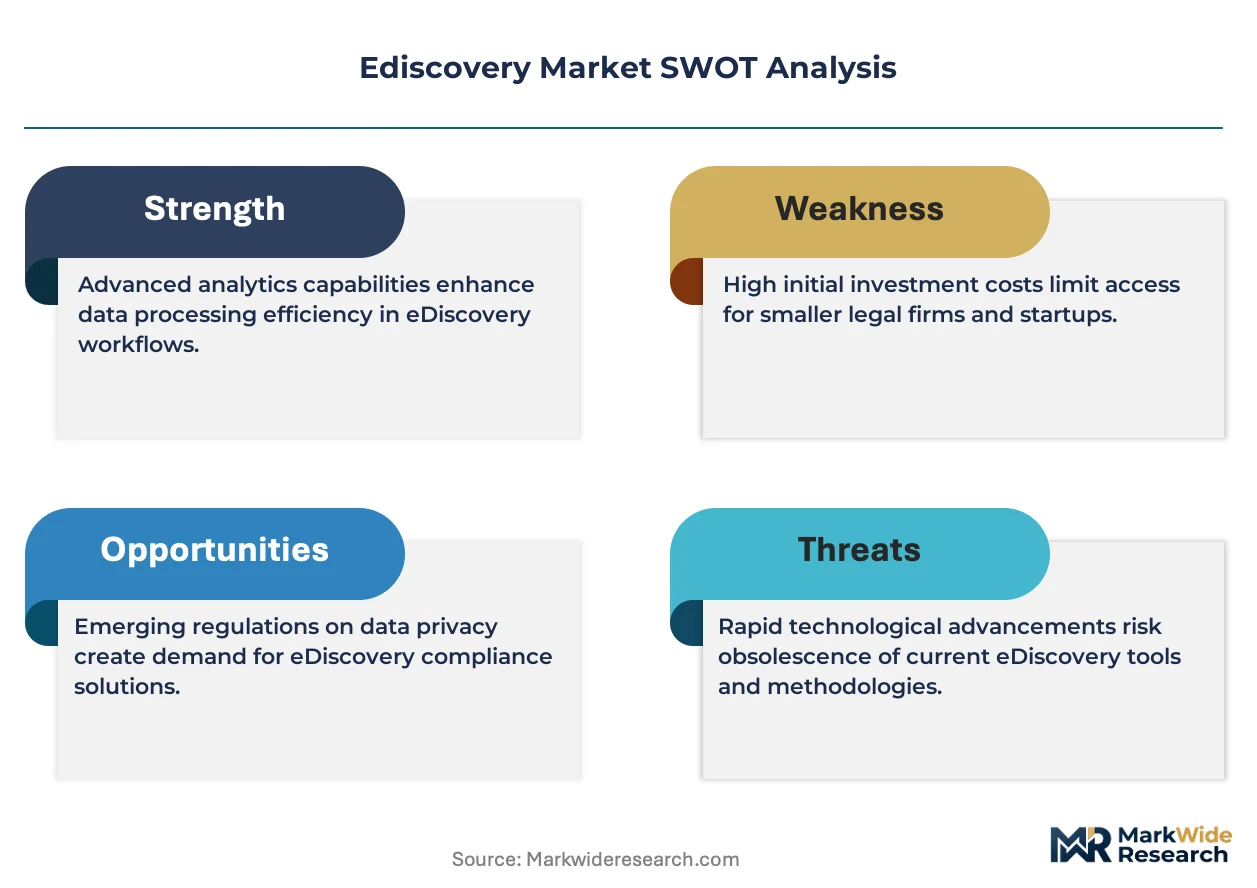
Cloud-native deployment architectures are collapsing the traditional on-premise infrastructure model across legal and corporate environments, compressing capital requirements while expanding elastic compute access for petabyte-scale document review.
Growth Catalysts
- FRCP ESI Amendments:Federal Rules of Civil Procedure mandates on electronically stored information compel defensible preservation protocols, expanding software procurement across US litigation practices.
- SEC Enforcement Workflows:Financial services regulators intensify examination scrutiny, requiring indexed document repositories with native format reconstruction for examination defense.
- Continuous Active Learning:Machine learning classification algorithms reduce attorney review hours by prioritizing relevance-ranked document queues.
Market Restraints
- Forensic Analyst Scarcity:Talent pipeline collapse across North America and Western Europe constrains vendor scaling and forces automation investment or jurisdictional arbitrage.
- Cross-Border Data Friction:EU GDPR and emerging US state privacy laws complicate transatlantic evidence transfer, requiring redundant regional hosting architectures.
- Algorithmic Transparency Scrutiny:Judicial skepticism toward opaque AI classification models creates admissibility risk and slows automated review adoption in high-stakes matters.
Strategic Opportunities
- Financial Services Expansion:Asset managers and broker-dealers face escalating regulatory examination volume, creating underserved demand for integrated preservation-to-production platforms.
- AI Governance Frameworks:Emerging judicial standards for automated document classification create first-mover advantage for vendors with interpretable model architectures.
- Managed Services Bundling:Technology-attorney hybrid offerings capture margin expansion by consolidating software licensing with contract review labor under single accountability.
Industry Challenges
- Legacy System Integration:Enterprise customers demand seamless connector architectures between cloud review platforms and existing document management systems, extending implementation timelines.
- Proportionality Defense:Counsel must document cost-benefit analyses for discovery scope, requiring platform-native budgeting tools that most vendors lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ediscovery Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services End User: Law Firms, Corporations, Government Agencies, Consulting Firms Solution: Software, Services, Consulting, Integration Industry Vertical: Legal, Healthcare, Financial Services, Energy |
| Companies Covered | Microsoft Corporation, Relativity, IBM Corporation, OpenText Corporation, CS DISCO, Nuix Limited, Epiq Systems, FTI Technology, KLDiscovery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ediscovery Market Emerging Trajectories
Generative AI capabilities are penetrating document review workflows, compressing timeline expectations while raising new questions about hallucination risk and authentication standards in legal proceedings.
Large language models are decomposing traditional linear review paradigms by enabling semantic search, conceptual clustering, and automated privilege identification. Am Law 100 firms pilot these tools for first-pass relevance screening, though most retain attorney eyes-on review for final production. The technology is decomposing billable-hour economics by collapsing document-throughput timelines from weeks to days.
EU AI Act classification requirements for high-risk applications are reshaping vendor development roadmaps, particularly for tools deployed in criminal and civil litigation contexts. The regulation mandates conformity assessments and human oversight protocols that increase compliance overhead. European corporate legal departments now prioritize vendors with established EU-hosted infrastructure and documented algorithmic accountability.
Corporate legal departments are consolidating vendor relationships from point-solution fragmentation toward integrated platform ecosystems, displacing best-of-breed toolchains. General counsel demand unified preservation, processing, review, and analytics under single vendor accountability. This concentration is most visible among Fortune 500 enterprises with multi-jurisdictional litigation portfolios and centralized legal operations functions.
Ediscovery Market Segmentation
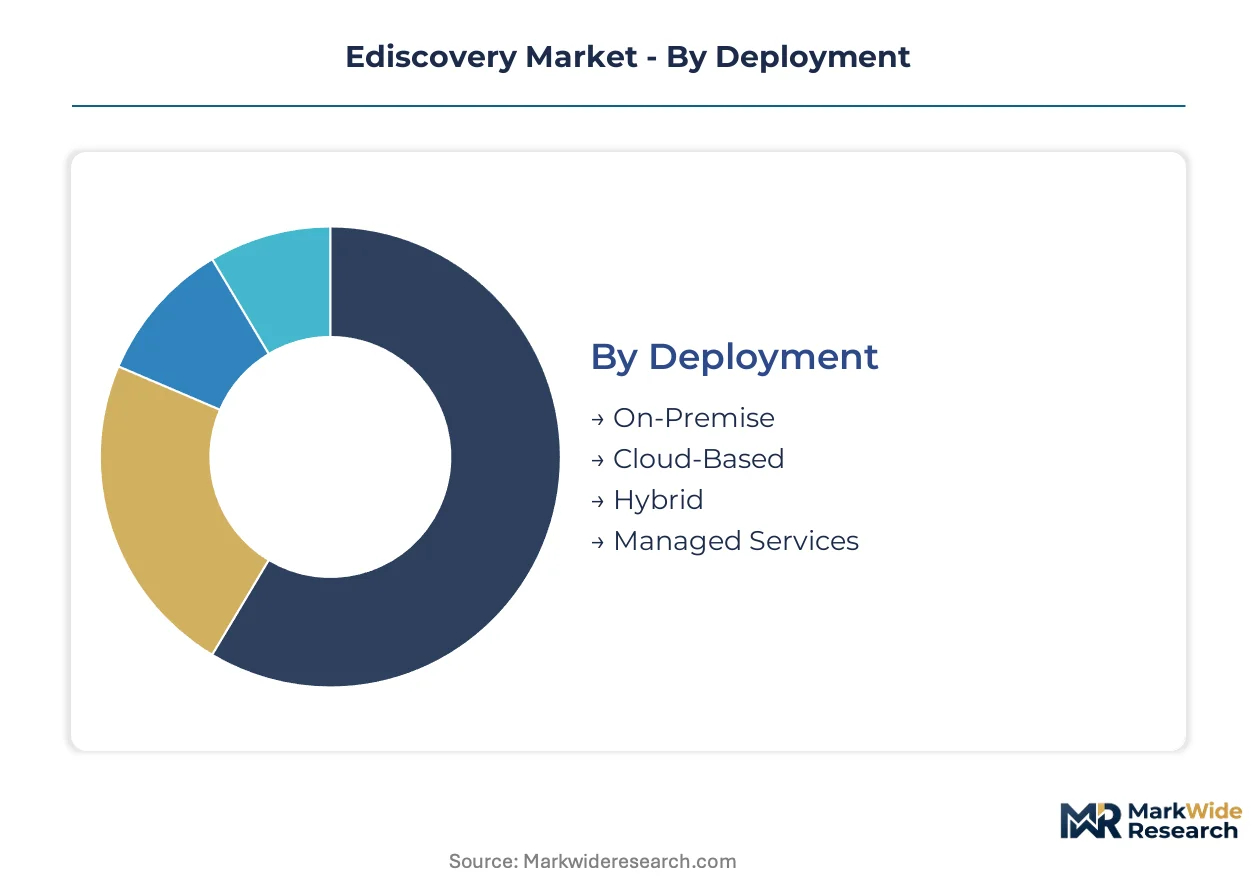
Ediscovery procurement patterns diverge sharply across deployment models and buyer types, with substitution pressure intensifying where capital constraints meet elastic scalability requirements. Segment boundaries blur as platform vendors bundle software with managed review labor, compressing standalone solution margins.
Deployment:
Substitution pressure concentrates where on-premise infrastructure faces cloud-native displacement, reshaping vendor economics and customer switching costs.
- On-Premise:Capital-intensive server and storage infrastructure deployed within client data centers, requiring dedicated IT maintenance and hardware refresh cycles. Demand persists among Am Law 50 firms with established security protocols and legacy document management investments, though procurement is decelerating as hybrid architectures gain favor.
- Cloud-Based:Elastic compute resources delivered via SaaS subscription, eliminating upfront infrastructure spend and enabling petabyte-scale review without hardware provisioning. US litigation practices and mid-market law firms drive adoption fastest, compelled by remote workforce requirements and OpEx budgeting preferences.
- Hybrid:Segregated architecture combining on-premise processing for sensitive data with cloud review tiers for lower-risk materials. Financial services institutions with SEC examination workflows favor this model to satisfy data residency requirements while accessing scalable analytics.
- Managed Services:Bundled technology and attorney review labor delivered under outcome-based contracts. Corporate legal departments with unpredictable litigation volume outsource entire discovery workflows to consolidate vendor accountability.
On-Premise deployments anchor the volume base while Cloud-Based solutions gain share at the steepest rate.
End User:
Cost tier stratification separates enterprise buyers with centralized procurement from fragmented professional services purchasing.
- Law Firms:Partnership-governed legal practices ranging from solo practitioners to global practices with multi-jurisdictional litigation portfolios. US-based Am Law 200 firms concentrate software spend on analytics-heavy platforms to defend billable-hour economics against alternative fee arrangements.
- Corporations:Enterprise legal departments and compliance functions managing regulatory examination and commercial litigation exposure. Fortune 500 manufacturers and technology companies build in-house discovery capabilities to reduce external counsel dependency.
- Government Agencies:Federal, state, and municipal legal departments with constrained procurement authority and heightened security clearance requirements. DOJ and SEC enforcement divisions maintain specialized discovery infrastructure for white-collar investigations.
- Consulting Firms:Advisory practices embedding ediscovery capabilities within broader risk management and forensic accounting offerings. Big Four accounting networks acquire boutique vendors to integrate document review with financial investigation services.
Law Firms generate the highest transaction velocity while Corporations expand their in-house capabilities most aggressively.
Solution:
Application complexity rises where standalone tools confront integrated platform consolidation, favoring vendors with unified workflow architectures.
- Software:Licensed platforms for data processing, analytics, review, and production with configurable workflow automation. Relativity and Microsoft Purview dominate enterprise procurement through API extensibility and Office 365 ecosystem integration.
- Services:Attorney-staffed document review, project management, and technical consulting delivered on a matter-specific basis. Managed review providers compete on speed-to-staff and foreign language capabilities.
- Consulting:Advisory engagements spanning information governance, preservation protocol design, and defensible deletion strategies. Demand concentrates among corporations preparing for SEC examination or complex antitrust litigation.
- Integration:Custom connector development and data migration services linking ediscovery platforms to enterprise content management systems. Implementation timelines extend where legacy document repositories lack standardized APIs.
Software licensing captures the largest revenue pool while Services margins compress under labor arbitrage pressure.
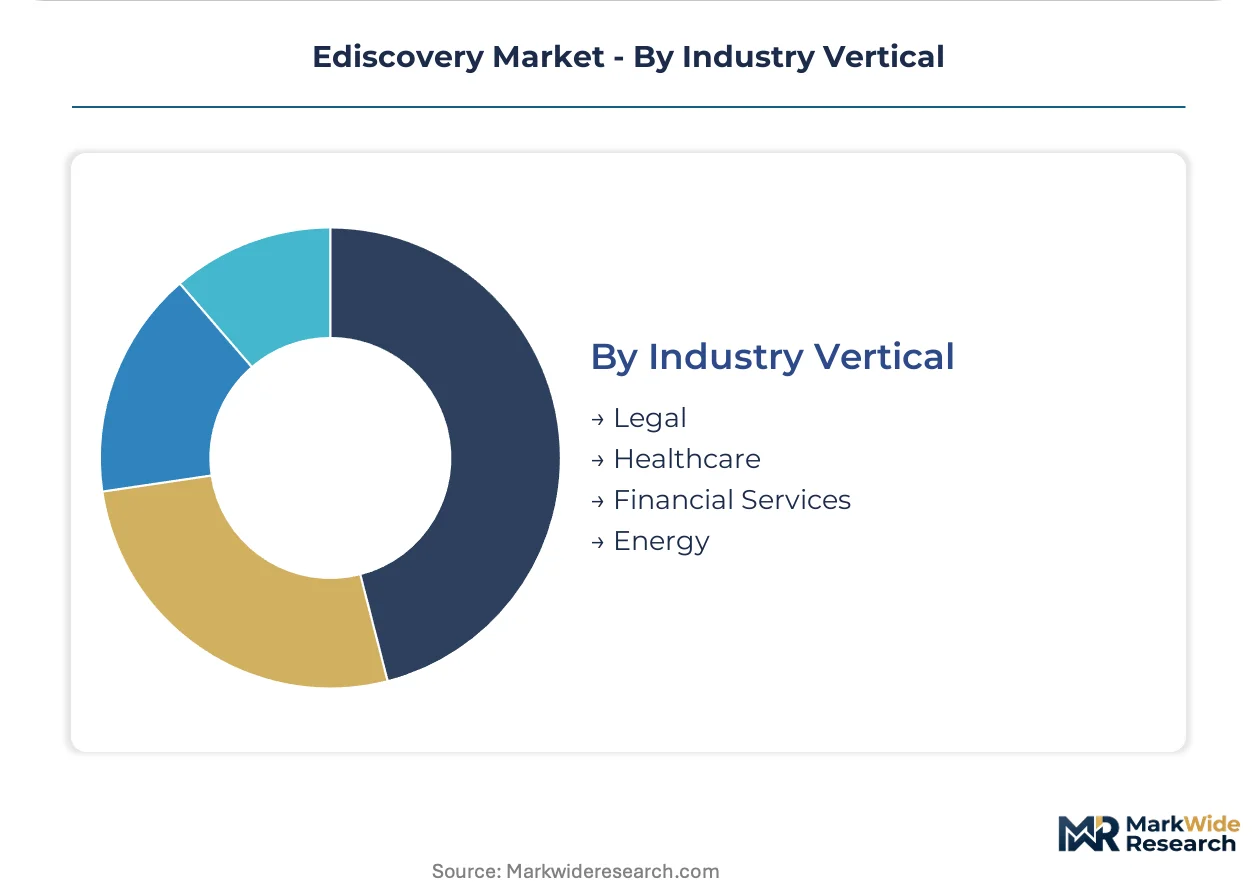
Industry Vertical:
Maturity gaps separate regulated sectors with established discovery protocols from emerging adopters facing first-matter learning curves.
- Legal:Law firms and legal service providers constituting the original ediscovery demand center with mature procurement processes and established vendor relationships. US litigation volume sustains platform subscription renewals despite pricing pressure.
- Healthcare:Hospital systems and pharmaceutical companies navigating HIPAA constraints while responding to malpractice and product liability discovery. OCR enforcement actions accelerate preservation protocol investments.
- Financial Services:Asset managers, broker-dealers, and insurers facing intensified SEC examination and enforcement workflows. FINRA arbitration and whistleblower investigations drive demand for indexed document repositories with native format reconstruction.
- Energy:Oil and gas producers, utilities, and renewable developers managing environmental litigation and FERC enforcement exposure. Complex operational data formats require specialized processing capabilities for SCADA logs and geological databases.
Legal verticals dominate current revenue while Financial Services expands most quickly under regulatory examination pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEC enforcement workflows anchor United States demand, while EU AI Act classification requirements reshape vendor development priorities across European jurisdictions. Litigation volume and regulatory examination intensity concentrate procurement in common law jurisdictions with mature discovery protocols.
United States
Am Law 200 firms and Fortune 500 corporate legal departments drive platform subscription growth, compelled by FRCP ESI amendments mandating defensible preservation protocols. SEC examination workflows require indexed document repositories with native format reconstruction capabilities. New York and Washington DC legal clusters concentrate vendor sales operations and attorney-staffed review centers.
United Kingdom
Magic Circle firms and Big Four advisory networks sustain demand for analytics-heavy platforms serving cross-border litigation and regulatory investigations. The UK GDPR and emerging AI governance frameworks constrain automated document classification deployment. London's legal technology corridor hosts regional headquarters for multiple platform vendors serving European corporate legal departments.
Germany
Automotive manufacturers and industrial conglomerates build in-house discovery capabilities to manage antitrust and product liability exposure. The EU AI Act mandates conformity assessments for high-risk litigation applications, increasing compliance overhead for deployed tools. Frankfurt's financial services cluster drives specialized demand for integrated preservation-to-production platforms serving BaFin examination workflows.
Australia
ASIC enforcement actions and class action litigation volume accelerate cloud-based platform adoption among corporate legal departments and mid-market law firms. The country's privacy regulator scrutinizes cross-border data transfers to US-hosted review environments. Sydney and Melbourne legal markets concentrate managed review provider operations and technical consulting capacity.
Canada
Provincial law societies' technology competence requirements shape procurement standards for litigation support platforms. Federal competition enforcement and white-collar criminal investigations sustain demand for specialized forensic processing capabilities. Toronto's financial district anchors enterprise adoption among asset managers and broker-dealers facing cross-border regulatory examination.
Ediscovery Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with platform stickiness and ecosystem integration determining competitive position. The market structure favors vendors bundling software licensing with attorney review labor under unified accountability. Three archetypes dominate: cloud-native platform providers, legacy enterprise software vendors with embedded discovery tools, and managed services specialists. Consolidation pressure intensifies as corporate legal departments reduce vendor fragmentation, while technology licensing partnerships extend platform reach into adjacent risk management workflows.
Within the integrated platform tier, Microsoft Corporation exemplifies ecosystem-anchored positioning through Office 365 integration, while Relativity occupies a position as analytics-focused independent vendor serving premium law firm segments. Nuix Limited represents specialized processing capability at petabyte scale. These three entities collectively illustrate the competitive spectrum from horizontal software integration to vertical workflow depth.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Relativity |
| IBM Corporation |
| OpenText Corporation |
| CS DISCO |
| Nuix Limited |
| Epiq Systems |
| FTI Technology |
| KLDiscovery |
| Others |
Supply Flow & Price Mechanics
Thirty-to-ninety-day implementation timelines for cloud-native deployments compress vendor cash conversion cycles and concentrate pricing power among platform providers with pre-configured connector libraries. This lead-time band tightens most acutely where enterprise customers demand seamless integration with existing document management infrastructure, forcing mid-tier vendors toward managed services bundling to defend margin pools.
Pricing Analysis
US-based platform subscriptions command 40-60% premiums over equivalent functionality deployed through EU-hosted environments, reflecting data residency compliance overhead and regional hosting infrastructure costs. The dominant pricing model is subscription-tiered SaaS licensing scaled by document volume and user seats, with price differentiation resting on analytics sophistication and API extensibility rather than base processing throughput. Cost compression in the mid-market tier intensifies as Microsoft Purview bundles ediscovery tooling within existing Office 365 commitments, eroding standalone vendor pricing power. Corporate legal departments exhibit the highest price sensitivity due to centralized procurement mandates, while Am Law 100 firms prioritize workflow efficiency over per-seat cost optimization.
Supply Chain Analysis
Inbound logistics costs for specialized forensic hardware and GPU-accelerated processing nodes spike during semiconductor supply constraints, particularly affecting on-premise deployment timelines for petabyte-scale installations. Software development talent concentrates in the United States, Ireland, and India, with cloud infrastructure provisioning drawing from hyperscaler data center footprints across Virginia, Frankfurt, and Singapore. The supply chain hinges on single-source vulnerability for advanced machine learning training clusters and specialized data processing accelerators. Distribution runs through direct enterprise sales teams for Fortune 500 accounts, supplemented by channel partnerships serving mid-market law firms and regional consulting networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed review services and ongoing analytics subscriptions expand faster than perpetual software licenses, positioning ediscovery as a service-attach opportunity where recurring revenue multiples exceed traditional licensing valuations.
For Market Incumbents: Compound platform stickiness through deeper Office 365 and Google Workspace integration, while acquiring boutique managed review providers to capture attorney-staffed labor margin pools. The threat of generative AI-native entrants with automated first-pass review capabilities demands accelerated investment in interpretable model architectures that satisfy judicial transparency requirements. Vertical integration into foreign-language document review capabilities in lower-cost jurisdictions defends against labor arbitrage pressure from emerging competitors. For New Entrants and Emerging Players: Lead with specialized processing capabilities for unstructured data formats—SCADA logs, geological databases, clinical trial records—where incumbent platforms lack native reconstruction tools. The most penetrable white space sits in financial services examination defense workflows, where SEC-mandated indexed repositories with native format reconstruction remain underserved by generalist vendors. A channel partnership strategy embedding ediscovery tooling within Big Four forensic accounting workflows accelerates credibility building without direct enterprise sales infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because corporate legal departments are reducing vendor fragmentation from point-solution toolchains toward unified platform ecosystems. The acquisition target archetype is regional managed services specialists with established attorney review centers and Fortune 500 referenceability. The signal to watch as an inflection indicator is judicial adoption of automated document classification protocols in high-stakes litigation, which would validate AI-native vendor architectures and compress traditional review economics.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding analytics engines within Microsoft 365 and Google Workspace ecosystems captures enterprise procurement workflows. |
| Acquisition of Specialist Firm | Consolidating boutique forensic processing vendors expands petabyte-scale unstructured data capabilities for energy and healthcare verticals. |
| Geographic Expansion | Establishing EU-hosted infrastructure satisfies GDPR data residency mandates and unlocks BaFin-regulated financial services demand. |
| Strategic Partnership | Alliances with Big Four advisory networks embed ediscovery capabilities within broader risk management and forensic accounting offerings. |
| Product Launch | Interpretable AI classification tools with documented algorithmic accountability address judicial skepticism and accelerate automated review adoption. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC enforcement action databases, FRCP amendment commentary, and vendor financial disclosures, combining structured interviews with ediscovery platform product managers, corporate legal operations directors, and federal magistrate judges with bottom-up and top-down triangulation across deployment model and vertical segmentation.
Segmentation dimensions modeled include deployment architecture, end-user type, solution category, and industry vertical across the analysis window, with CAGRs derived from elasticity-adjusted adoption curves and regulatory mandate timing. Forecast inputs incorporate FRCP ESI amendment compliance deadlines and SEC examination volume trajectories.
The analysis sits within stated boundaries; outcomes outside sustained judicial acceptance of automated document classification or abrupt shifts in cross-border data transfer regulations would require recalibration. Practitioners should keep alternative scenarios live as EU AI Act conformity assessment timelines and US state privacy law enforcement patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Experience Optimization Platforms Market
Digital Solutions
Asia-Pacific Smart Government Market
Digital Solutions
APAC Smart Office Market
Digital Solutions
Foot Traffic and Customer Location Intelligence Solution Market
Digital Solutions
Smart Recording Pen Market
Digital Solutions
Cloud Manufacturing Execution System (MES) Market
Digital Solutions
Model Based Enterprise Market
Digital Solutions
AI Infrastructure Solutions Market
Digital Solutions
Remote Control Duplicators Market
Digital Solutions
Stylus Pen for Education Market
Digital Solutions
Global Digital Business Card Market
Digital Solutions
Global Demand Side Platforms (DSP) for Programmatic Advertising Market
Digital Solutions
Digital User Experience Solutions Market
Digital Solutions
Global Assistive Technologies for Visually Impaired Market
Digital Solutions
Global Digital Experience Management Market
Digital Solutions
APAC Digital Signage Market