
 Australia ICT Market | 2026-2036
Australia ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Australia ICT Market Outlook
Modular service bundling is rebalancing how Australian enterprises procure technology, shifting from discrete hardware purchases toward integrated cloud and managed service packages. Accenture Australia leverages its consulting depth to anchor large-scale digital transformation programs across banking and federal agencies. Telco ICT competes through specialized network infrastructure deployments that dominate regional connectivity markets. ThoughtWorks differentiates via agile software delivery methodologies that sustain premium positioning among ASX-listed enterprises.
Information and communications technology in Australia encompasses hardware, software, telecommunications infrastructure, and networking equipment operating across fixed and wireless protocols with latency thresholds as low as one millisecond for enterprise fiber deployments. Its primary purpose is to enable data processing, storage, transmission, and secure exchange across commercial, government, and consumer domains. Cloud Services leads structural growth among service types as Australian organizations exit on-premises data centers for AWS, Azure, and domestic sovereign cloud alternatives. Hardware retains substantial revenue weight within product type segmentation, though margin pools have migrated toward software and managed services where recurring revenue models prevail.
The Australian Communications and Media Authority enforces carrier licensing and spectrum allocation rules that directly shape market entry for telecommunications providers, while the Australian Cyber Security Centre mandates Essential Eight compliance standards that redirect enterprise spending toward certified security vendors. The Privacy Act and Notifiable Data Breaches scheme impose liability frameworks that accelerate demand for managed security services and sovereign data residency solutions. Stakeholders must monitor evolving critical infrastructure designation rules that could expand regulatory coverage beyond energy and finance into cloud platforms and data center operations.
Market Dynamics
Australian federal agencies and ASX-listed enterprises are accelerating sovereign cloud migration under the Privacy Act's data residency mandates, compressing procurement cycles and redirecting capital from on-premises infrastructure toward managed service consumption models.
Growth Catalysts
- Critical Technologies Fund:Federal capital injections into artificial intelligence and quantum computing R&D are expanding domestic vendor capabilities and reducing reliance on offshore technology sourcing.
- Healthcare digitization:Hospital networks and primary care providers are deploying integrated electronic health record platforms, generating sustained demand for secure data exchange infrastructure.
- Sydney-Melbourne enterprise concentration:Corporate headquarters clusters in these cities concentrate procurement authority, enabling faster decision-making on large-scale transformation programs.
Market Restraints
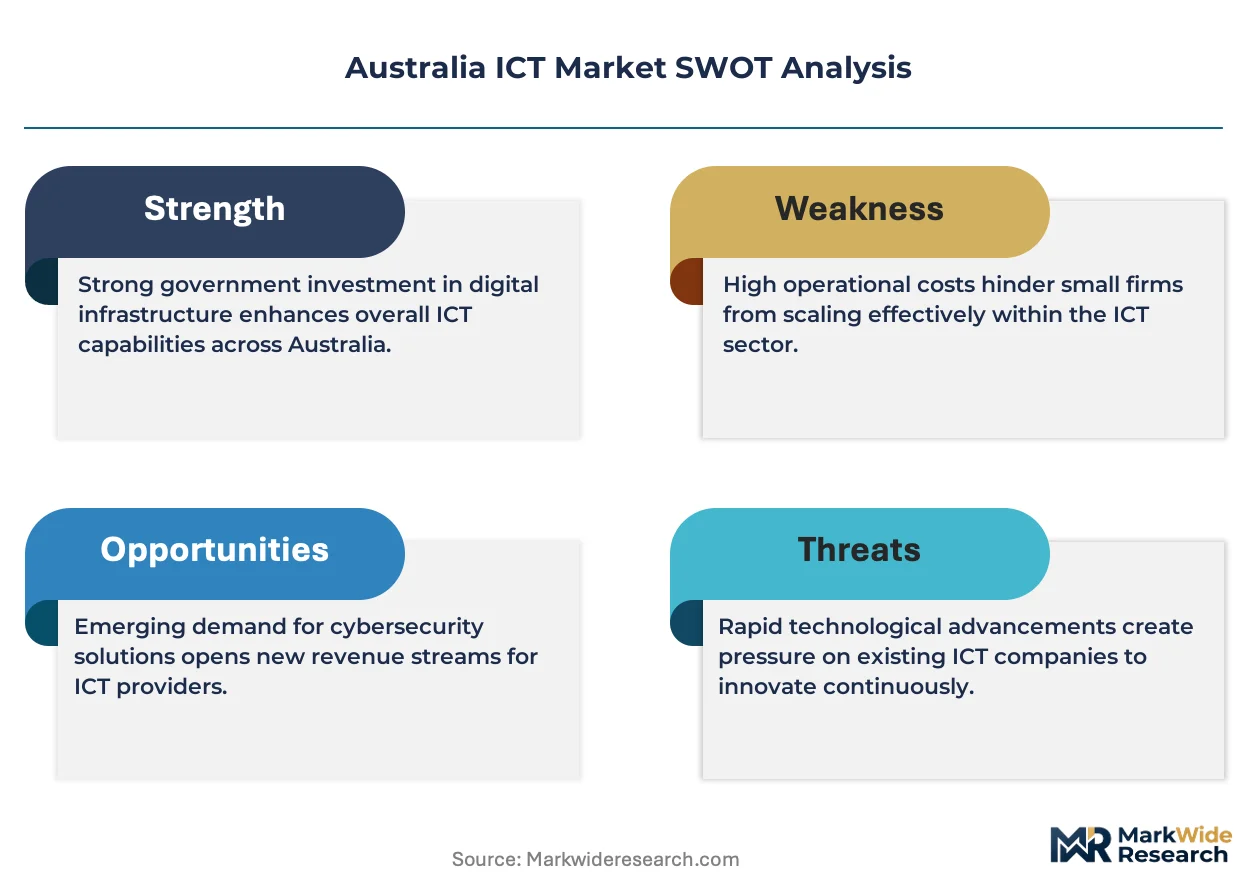
- Specialized talent scarcity:Domestic supply of cybersecurity architects and cloud engineers falls short of enterprise demand, inflating labor costs and extending implementation timelines.
- Submarine cable dependency:International data traffic routes through limited cable landing points, creating concentration risk for bandwidth-intensive applications.
- Essential Eight compliance burden:ACSC-mandated security controls impose certification overhead that disqualifies smaller vendors from federal procurement panels.
Strategic Opportunities
- Regional Queensland and Western Australia:Mining operations and agricultural processing facilities outside metropolitan centers remain underserved by high-bandwidth connectivity and edge computing infrastructure.
- AI-augmented managed services:Convergence of generative artificial intelligence with IT operations platforms is creating new service tiers for predictive infrastructure management.
- Sovereign cloud accreditation:Certified Cloud Services List expansion under the Digital Transformation Agency creates preferential market access for compliant domestic providers.
Industry Challenges
- Legacy system integration:Federal agencies operate decades-old mainframe environments that resist API-based connectivity with modern cloud architectures.
- Security clearance bottlenecks:Personnel vetting delays under the Australian Government Security Vetting Agency constrain staffing for classified infrastructure projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia ICT Market |
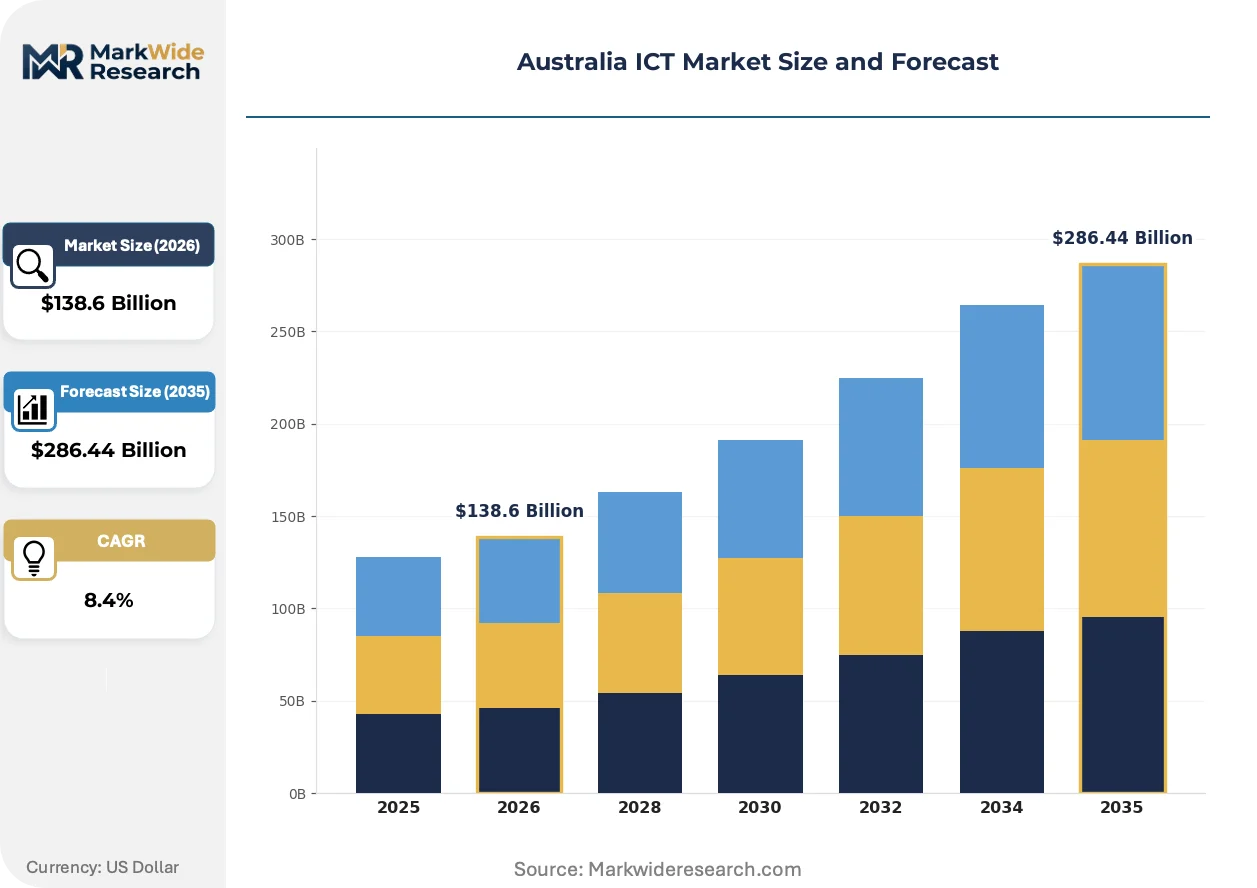
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $286.44 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Managed Services, Cloud Services, IT Consulting, Network Services Customer Type: Government, SMEs, Enterprises, Startups Product Type: Hardware, Software, Telecommunications, Networking Equipment Industry Vertical: Education, Healthcare, Finance, Retail |
| Companies Covered | XAM, Classic Informatics, Accenture Australia, SDLC Corp, Appinventiv, ThoughtWorks, Telco ICT, TechGropse, Codewave, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia ICT Market Strategic Shifts
Technology procurement patterns across Australian enterprises are fragmenting as hybrid work models persist and cyber threat sophistication escalates, forcing buyers toward integrated security-service bundles rather than point solutions.
Edge computing infrastructure is converging with private 5G network deployments to enable sub-10 millisecond latency for industrial automation use cases. Mining operators in Western Australia's Pilbara region are piloting these converged stacks for autonomous haulage coordination. The structural consequence is compression of traditional telecommunications vendor roles as system integrators capture broader solution margins.
The Notifiable Data Breaches scheme under the Privacy Act has hardened liability frameworks for data custodians, accelerating enterprise migration toward certified sovereign cloud environments. Financial services institutions now treat data residency as a board-level risk priority rather than procurement preference. This regulatory pressure is reshaping vendor qualification criteria across banking and insurance verticals.
Enterprise buyers are consolidating vendor relationships to reduce operational complexity, replacing multi-supplier hardware sourcing with single-accountability managed service agreements. Federal agencies and state health departments are leading this consolidation, favoring outcome-based contracts with penalty clauses for service degradation. Victoria's hospital networks have emerged as early adopters of this procurement model, bundling infrastructure, security, and application support under unified performance metrics.
Australia ICT Market Segmentation
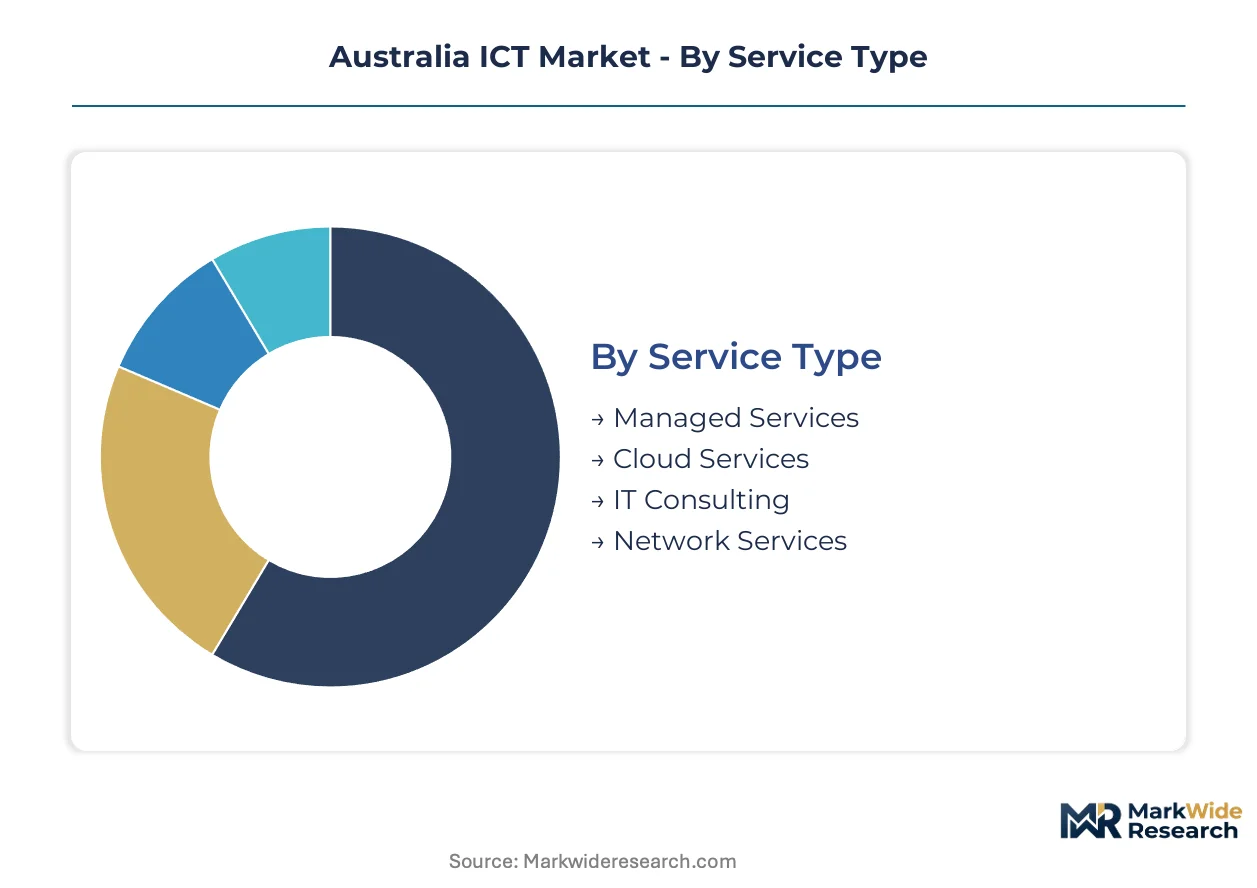
Australian ICT procurement patterns fragment sharply across customer scale and service maturity, with sovereign compliance requirements and legacy infrastructure debt creating divergent upgrade timelines between federal agencies and commercial enterprises.
Service Type:
Replacement cycles vary from 3-year hardware refreshes to perpetual managed service subscriptions, compressing capital planning horizons for cloud-first buyers.
- Cloud Services:Multi-tenant infrastructure delivered via AWS, Azure, and domestic sovereign cloud alternatives. ASX-listed enterprises in Sydney and Melbourne dominate consumption as Privacy Act data residency mandates accelerate migration from on-premises data centers.
- Managed Services:Outcome-based infrastructure and security operations with unified performance metrics. Federal agencies and Victoria's hospital networks lead adoption, favoring single-accountability contracts with penalty clauses over fragmented multi-vendor arrangements.
- IT Consulting:Advisory services anchoring large-scale digital transformation programs across banking and federal agencies.
- Network Services:Specialized connectivity deployments dominating regional markets outside metropolitan centers.
Volume placements concentrate in Managed Services; the faster expansion belongs to Cloud Services.
Customer Type:
Cost tiers separate compliance-heavy federal buyers from price-sensitive mid-market segments, with procurement authority clustering in distinct geographies.
- Government:Federal and state agencies with mandated Essential Eight compliance and security clearance requirements. ACSC certification overhead disqualifies smaller vendors, concentrating spending among accredited providers with cleared personnel.
- Enterprises:ASX-listed corporations with board-level data residency priorities and consolidated vendor strategies. Sydney-Melbourne headquarters clusters enable faster decision-making on transformation programs.
- SMEs:Mid-market commercial buyers with compressed IT budgets and hybrid work infrastructure demands.
- Startups:Early-stage ventures prioritizing scalable cloud consumption over capital-intensive infrastructure ownership.
Revenue gravity sits with Government contracts; Enterprises are climbing the fastest toward managed service consumption.
Product Type:
Margin pools have migrated from hardware toward software and recurring service models, though infrastructure retains substantial revenue weight.
- Hardware:Servers, storage arrays, and endpoint devices with shrinking margins as buyers shift toward as-a-service consumption. Replacement cycles extend where cloud migration defers on-premises refreshes.
- Software:Licensed and subscription applications with recurring revenue models prevailing over perpetual licenses. Healthcare digitization drives demand for integrated electronic health record platforms.
- Telecommunications:Fixed and wireless infrastructure operating across protocols with latency thresholds as low as one millisecond for enterprise fiber.
- Networking Equipment:Routing and switching hardware supporting API-based connectivity with modern cloud architectures.
Hardware still commands placement volume; Software is gaining share fastest as margin pools shift.
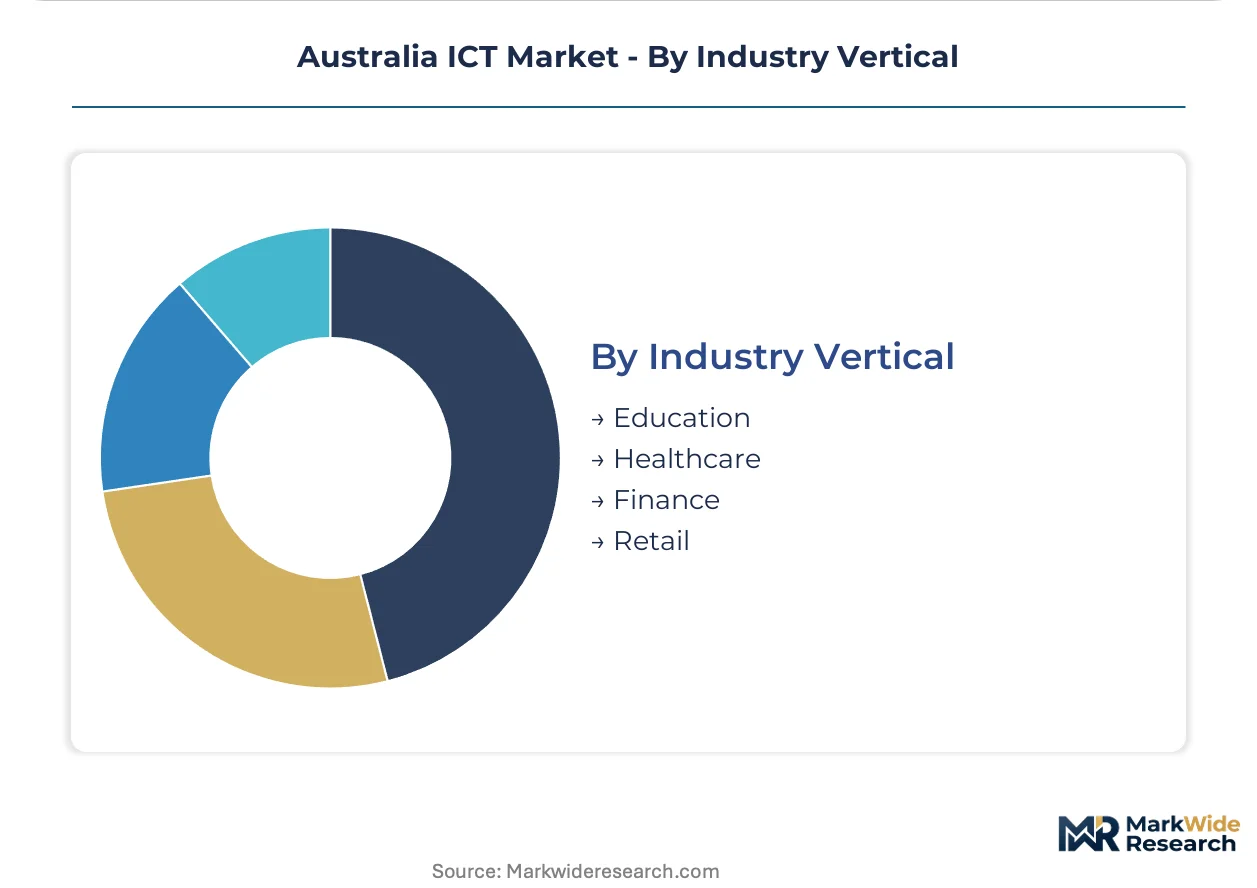
Industry Vertical:
Application-specific requirements reshape vendor qualification criteria, with regulatory pressure varying sharply across sectors.
- Healthcare:Hospital networks and primary care providers deploying secure data exchange infrastructure under Notifiable Data Breaches scheme liability frameworks. Victoria's health departments lead outcome-based procurement consolidation.
- Finance:Banking and insurance institutions treating data residency as board-level risk priority. The Privacy Act has hardened custodian liability, accelerating sovereign cloud migration.
- Education:Universities and vocational institutions with distributed campus connectivity and research computing demands.
- Retail:Consumer-facing operations with omnichannel infrastructure and edge computing requirements for inventory and customer analytics.
Finance verticals anchor current spending; Healthcare shows the steepest expansion trajectory as digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's ICT production concentrates in Sydney and Melbourne enterprise corridors while consumption spreads across state capitals and regional mining hubs. The geographic divide between solution development and end-use deployment shapes vendor qualification requirements and procurement timelines.
New South Wales
Enterprise cloud migration and cybersecurity spending dominate state-level IT budgets concentrated in Sydney's financial services corridor. The Digital Transformation Agency's Certified Cloud Services List redirects federal agency procurement toward accredited domestic providers. Macquarie Park technology precinct hosts major systems integrators serving both Commonwealth departments and ASX-listed corporations.
Victoria
Hospital networks and healthcare technology providers drive managed services demand across Melbourne's metropolitan region. The state's hospital procurement consolidation under outcome-based contracts with penalty clauses has emerged as a national template. Victorian health departments bundle infrastructure, security, and application support under unified performance metrics that compress vendor selection cycles.
Queensland
Mining operations and agricultural processing facilities outside Brisbane generate demand for high-bandwidth connectivity and edge computing infrastructure underserved by metropolitan-focused providers. The state's regional development programs subsidize telecommunications upgrades to resource extraction sites. Townsville and Cairns emerge as secondary procurement nodes for government and education sector technology spending.
Western Australia
Pilbara mining operators pilot converged edge computing and private 5G deployments for autonomous haulage coordination requiring sub-10 millisecond latency. Perth serves as the primary technology procurement hub for resources sector transformation programs. Submarine cable landing points at Fremantle create bandwidth concentration risks for international data traffic serving the state's isolated industrial zones.
Australia ICT Market Competitive Environment
The competitive structure tilts toward consulting-led transformation specialists anchoring large-scale federal and banking programs. Market concentration favors accredited providers with cleared personnel capable of meeting Australian Cyber Security Centre Essential Eight mandates. Three archetypes dominate: global consulting networks with domestic delivery arms, telecommunications carriers extending into managed infrastructure, and agile software delivery boutiques serving ASX-listed enterprises. Competitive moves center on outcome-based contract structures with penalty clauses and sovereign cloud accreditation under Digital Transformation Agency frameworks.
Among consulting-anchored integrators, Accenture Australia occupies a position exemplifying the large-scale program archetype across federal agencies and banking verticals. ThoughtWorks represents the agile methodology specialist tier sustaining premium positioning among listed enterprises. Telco ICT sits within the network infrastructure extension archetype dominating regional connectivity markets outside metropolitan centers.
| Leading Market Players |
|---|
| XAM |
| Classic Informatics |
| Accenture Australia |
| SDLC Corp |
| Appinventiv |
| ThoughtWorks |
| Telco ICT |
| TechGropse |
| Codewave |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up managed services specialists anchor pricing discipline across Australian ICT procurement, compressing margins for hardware resellers while enabling premium capture for sovereign-accredited cloud providers. This ownership concentration tightens supply-side coordination between Sydney-Melbourne distribution hubs and federal agency buying centers.
Pricing Analysis
Margin tightening in hardware tiers reflects accelerated cloud migration as buyers defer on-premises refreshes. Subscription-based managed services dominate, with three-tier pricing structure across premium, standard, and economy levels separating Essential Eight-certified providers from uncertified competitors. Pricing pressure stems from labor scarcity inflating implementation costs. SMEs exhibit highest price sensitivity; federal agencies prioritize compliance over cost.
Supply Chain Analysis
Regional distribution centers in Sydney and Melbourne operate hub-and-spoke patterns feeding state capitals and mining regions. Hardware sourcing concentrates in China, Taiwan, and USA for servers and networking equipment. Semiconductor components and fiber optic cable represent critical input dependencies. Single-source vulnerability persists for submarine cable landing points at Fremantle. Distribution runs through systems integrators with direct federal accreditation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia's ICT market operates as a vertical-integration race, with incumbents pursuing backward integration into sovereign cloud infrastructure to lock out offshore competitors.
For Market Incumbents: Deepen Essential Eight certification coverage across personnel pools to defend federal procurement panel access against emerging domestic specialists. Expand cleared workforce capacity through security vetting pipeline investments, as Australian Government Security Vetting Agency delays constrain staffing for classified infrastructure projects. Acquire regional Queensland and Western Australia connectivity assets to preempt edge computing entrants. For New Entrants and Emerging Players: Capture sovereign cloud accreditation gaps under Digital Transformation Agency frameworks, targeting mid-tier ASX-listed enterprises with data residency mandates. Regional mining operations in Pilbara and Bowen Basin present the most penetrable white-space for private 5G and edge computing bundles. Lead with outcome-based contracts featuring penalty clauses to mirror Victorian hospital procurement templates. For Investors and Strategic Acquirers: Distressed-cycle entries favor agile software delivery boutiques in Melbourne with established ASX relationships and recurring revenue bases. Long-term viability hinges on managed service transition completion and sovereign cloud certification maintenance. Watch Digital Transformation Agency Certified Cloud Services List expansion velocity as inflection indicator for domestic provider valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Accreditation | Digital Transformation Agency certification unlocks preferential federal procurement access under Privacy Act mandates. |
| Essential Eight Compliance Investment | Australian Cyber Security Centre certification overhead disqualifies smaller vendors from government panels. |
| Regional Edge Infrastructure Buildout | Pilbara mining operators pilot sub-10 millisecond latency stacks for autonomous haulage coordination. |
| Outcome-Based Contract Structuring | Victoria's hospital networks bundle infrastructure, security, and application support under unified performance metrics. |
| Managed Security Service Expansion | Notifiable Data Breaches scheme liability accelerates enterprise demand for certified data custodians. |
Study Parameters
Company filings, Australian Cyber Security Centre compliance registries, and Digital Transformation Agency procurement databases formed the secondary backbone for market sizing. Primary interviews with federal IT procurement officers, state health department technology directors, systems integrator account executives, and cloud platform engineers validated demand assumptions. Bottom-up segment builds triangulated against top-down federal budget appropriations and ASX technology spending disclosures.
Historical trendline analysis across service type, customer scale, and industry vertical dimensions established baseline growth trajectories. The analytical framework modeled deployment model, organization size, and sovereign compliance tier across the projection horizon. CAGRs derived from regression-adjusted technology budget growth rates, incorporating Critical Technologies Fund allocation trajectories and healthcare digitization pipeline visibility.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to submarine cable resilience and security clearance processing reforms. Outputs reflect documented assumptions around regulatory enforcement continuity and federal cloud migration timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Online Home Service Market
Digital Solutions
Ticketing Solution Market
Digital Solutions
Global Competitive Intelligence Tools Market
Digital Solutions
Global Remote Monitoring and Management (RMM) Tools Market
Digital Solutions
Telecom Site Management Software Market
Digital Solutions
Data Governance Market
Digital Solutions
Europe IT Asset Disposition Market
Digital Solutions
Computer Aided Engineering Market
Digital Solutions
Reverse Logistics Visibility and Disposition Optimization Platforms Market
Digital Solutions
Europe Warranty Management System Market
Digital Solutions
Account Based Marketing Market
Digital Solutions
North America IT Asset Disposition Market
Digital Solutions
Location As a Service Market
Digital Solutions
Enterprise Content Management (ECM) Market
Digital Solutions
Smart Set-Top Box and Dongle Market
Digital Solutions
Asia-Pacific Multichannel Order Management Market