
 Business Information Market | 2026-2036
Business Information Market Size, Share, and Industry Trends Forecast 2026-2036
Business Information Market Analysis
North American data infrastructure spending is broadening the addressable base for commercial intelligence providers. RELX PLC sustains dominant positions in legal and scientific information verticals through deep content archives. Bloomberg Finance L.P anchors fixed-income and trading workflows with proprietary terminal networks. S&P Global Inc. leverages integrated credit ratings, benchmarks, and analytics to cross-sell across risk functions.
Business information encompasses structured and unstructured datasets—credit histories, corporate registries, news archives, and predictive risk scores—processed through algorithmic models to support lending, procurement, and compliance decisions. The service type dimension segments into data analytics, market research, business intelligence, and consulting; data analytics commands the largest revenue share while business intelligence shows the fastest expansion as embedded dashboards proliferate across enterprise software. Client type splits across startups, SMEs, large enterprises, and government; large enterprises generate the deepest contract values, though SME adoption is accelerating through self-service subscription tiers.
The SEC mandates disclosure standards that directly shape the data fields and timeliness requirements for corporate intelligence products. The EU AI Act imposes algorithmic transparency obligations on automated credit scoring and risk assessment tools, forcing vendors to reengineer model documentation and audit trails. HIPAA constrains how healthcare-adjacent business information incorporates patient-linked datasets. Stakeholders must monitor how divergent regulatory timelines across Washington, Brussels, and Beijing fragment product roadmaps and compliance costs.
Market Dynamics
Financial services firms are accelerating real-time credit and risk data platform deployments. The EU AI Act's algorithmic transparency mandates are forcing vendors to reengineer model documentation and audit trails, reshaping competitive positioning across automated decision-making tools.
Growth Catalysts
- EU AI Act compliance mandates:Automated credit scoring and risk assessment tools face new transparency obligations, compelling enterprises to upgrade data infrastructure and expand vendor relationships.
- Real-time data infrastructure:Financial services firms demand instantaneous credit histories and predictive risk scores, pulling cloud-native analytics platforms into lending workflows.
- SME self-service adoption:Subscription tiers targeting smaller enterprises unlock new contract volumes as procurement barriers fall for business intelligence dashboards.
Market Restraints
- Algorithmic audit costs:Model documentation requirements under the EU AI Act inflate compliance spending, compressing margins for mid-tier analytics providers.
- Data source concentration:Proprietary credit registries and corporate archives concentrate in legacy information conglomerates, limiting new entrant access to foundational datasets.
- Cross-border regulatory fragmentation:Divergent disclosure timelines between Washington, Brussels, and Beijing fragment product roadmaps and multiply certification burdens.
Strategic Opportunities
- Healthcare-adjacent data services:HIPAA-constrained patient-linked datasets create specialized niches for compliant business information products in pharmaceutical supply chain monitoring.
- Embedded dashboard proliferation:Business intelligence modules are integrating directly into enterprise software platforms, bypassing standalone procurement cycles.
- India's digital public infrastructure:The country's expanding corporate registry digitization and credit bureau coverage open addressable markets for localized data analytics services.
Industry Challenges
- Explainable AI talent scarcity:Model interpretability requirements under the EU AI Act outpace available expertise in algorithmic auditing and documentation engineering.
- Legacy system integration friction:Real-time data streams encounter architectural bottlenecks when interfacing with on-premise risk management platforms at incumbent financial institutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business Information Market |
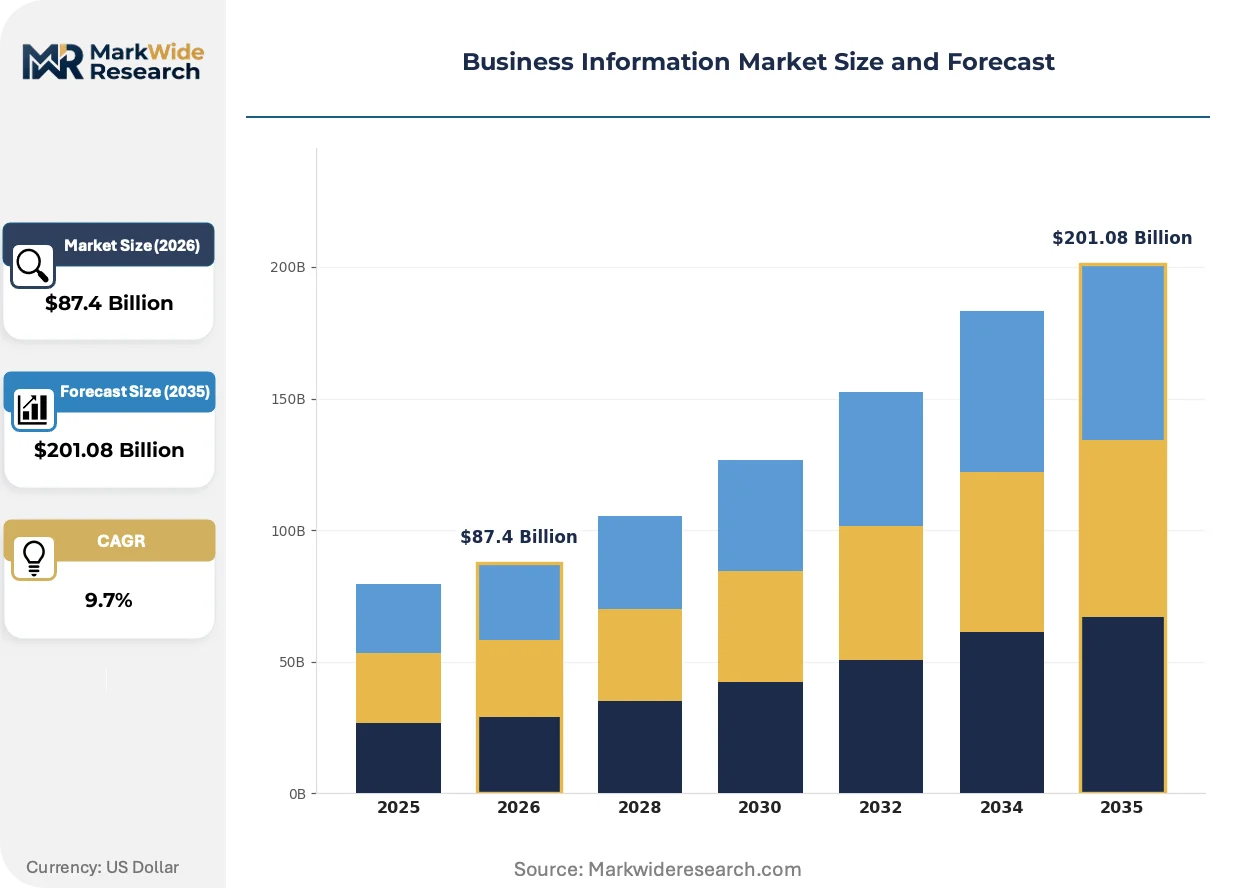
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $201.08 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Industry Vertical: Finance, Healthcare, Retail, Technology Service Type: Data Analytics, Market Research, Business Intelligence, Consulting Client Type: Startups, SMEs, Large Enterprises, Government Delivery Model: Subscription, Tiered Access, Pay-as-you-go, Customized Solutions |
| Companies Covered | Dun & Bradstreet Corporation, RELX PLC, Bloomberg Finance L.P, Verisk Analytics, Inc., Equifax Inc., Thomson Reuters Holdings Inc., Moody's Corporation, Morningstar, Inc., S&P Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business Information Market Emerging Trajectories
Generative AI is compressing the latency between raw data ingestion and actionable intelligence. Three distinct vectors are reshaping how business information products are architected, delivered, and monetized across enterprise segments.
Natural language processing engines are integrating directly into business intelligence workflows, translating unstructured news archives and regulatory filings into structured risk signals. Large enterprises in capital-intensive sectors are deploying these tools at scale, compressing analyst research cycles from days to hours. The technology is integrating predictive scoring models with conversational interfaces, collapsing the distinction between data platform and decision support system.
The EU AI Act's risk-based classification framework is mandating algorithmic impact assessments for automated credit decisions. Vendors must now maintain technical documentation, human oversight protocols, and bias monitoring systems for high-risk applications. European financial institutions are responding by segmenting procurement between compliant and non-compliant tool categories, creating a two-tier vendor landscape.
Enterprise buyers are consolidating vendor relationships around integrated data-analytics-consulting bundles, displacing point-solution subscriptions. Procurement teams at United States-based multinationals now prioritize single-contract relationships that span raw data feeds, benchmarking tools, and advisory services. This concentration is most visible in fixed-income trading workflows, where terminal networks anchor comprehensive intelligence subscriptions.
Business Information Market Segmentation
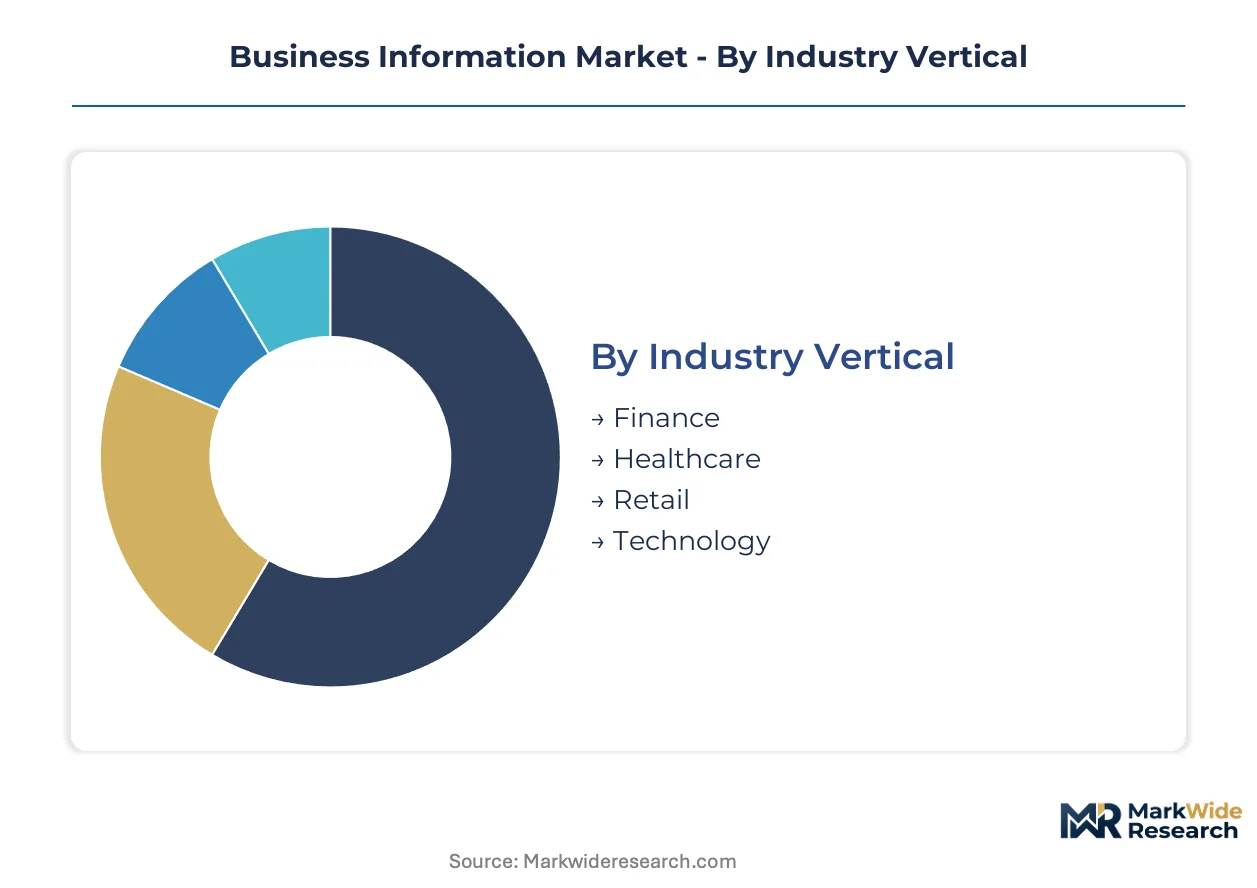
Business information vendors architect product portfolios around distinct buyer capabilities and workflow integration requirements. Segment boundaries determine pricing architecture, sales motion, and compliance obligations across regulatory jurisdictions.
Industry Vertical:
Supply concentration in financial data infrastructure anchors revenue concentration, with specialized registries and terminal networks creating high barriers to entry for adjacent verticals.
- Finance:Real-time credit histories and predictive risk scores flow through proprietary terminal networks and cloud-native analytics platforms. United States-based investment banks command the deepest procurement budgets for integrated fixed-income data workflows.
- Healthcare:HIPAA-constrained patient-linked datasets require specialized compliance architectures for pharmaceutical supply chain monitoring and clinical trial intelligence. The EU AI Act's algorithmic transparency mandates reshape automated diagnostic and risk-scoring tool procurement.
- Retail:Consumer transaction analytics and competitive pricing intelligence support inventory optimization and demand forecasting.
- Technology:Patent registries, venture capital databases, and developer ecosystem metrics enable competitive intelligence and investment screening.
Today's leader: Finance. Tomorrow's challenger: Healthcare.
Service Type:
Cost tier differentiation separates enterprise-grade bundled offerings from self-service subscriptions accessible to smaller buyers.
- Data Analytics:Algorithmic processing of structured and unstructured datasets—credit histories, corporate registries, news archives—generates predictive risk signals. Cloud-native platforms are pulling real-time streams into lending workflows at financial institutions.
- Business Intelligence:Embedded dashboards integrate directly into enterprise software platforms, bypassing standalone procurement cycles. SME adoption accelerates through self-service subscription tiers with reduced implementation friction.
- Market Research:Industry reports and competitive intelligence support strategic planning and market entry decisions.
- Consulting:Advisory services bundle with data subscriptions to support regulatory compliance and risk transformation programs.
Data analytics commands current revenue concentration. Business intelligence gains share fastest through embedded distribution.
Client Type:
Volume concentration in large enterprise contracts contrasts with expanding addressable base through lowered procurement barriers.
- Large Enterprises:Multi-year contracts spanning raw data feeds, benchmarking tools, and advisory services generate the deepest contract values. United States-based multinationals prioritize single-vendor relationships that consolidate procurement overhead.
- SMEs:Self-service subscription tiers with standardized dashboards and reduced implementation support unlock new contract volumes. India's expanding digital public infrastructure enables localized data analytics services for mid-market firms.
- Startups:Freemium tiers and API-based access lower entry barriers for early-stage companies building automated decision systems.
- Government:Procurement of corporate registry digitization and credit bureau infrastructure supports public policy objectives.
Large enterprises anchor current spending. SME segments expand addressable market fastest.
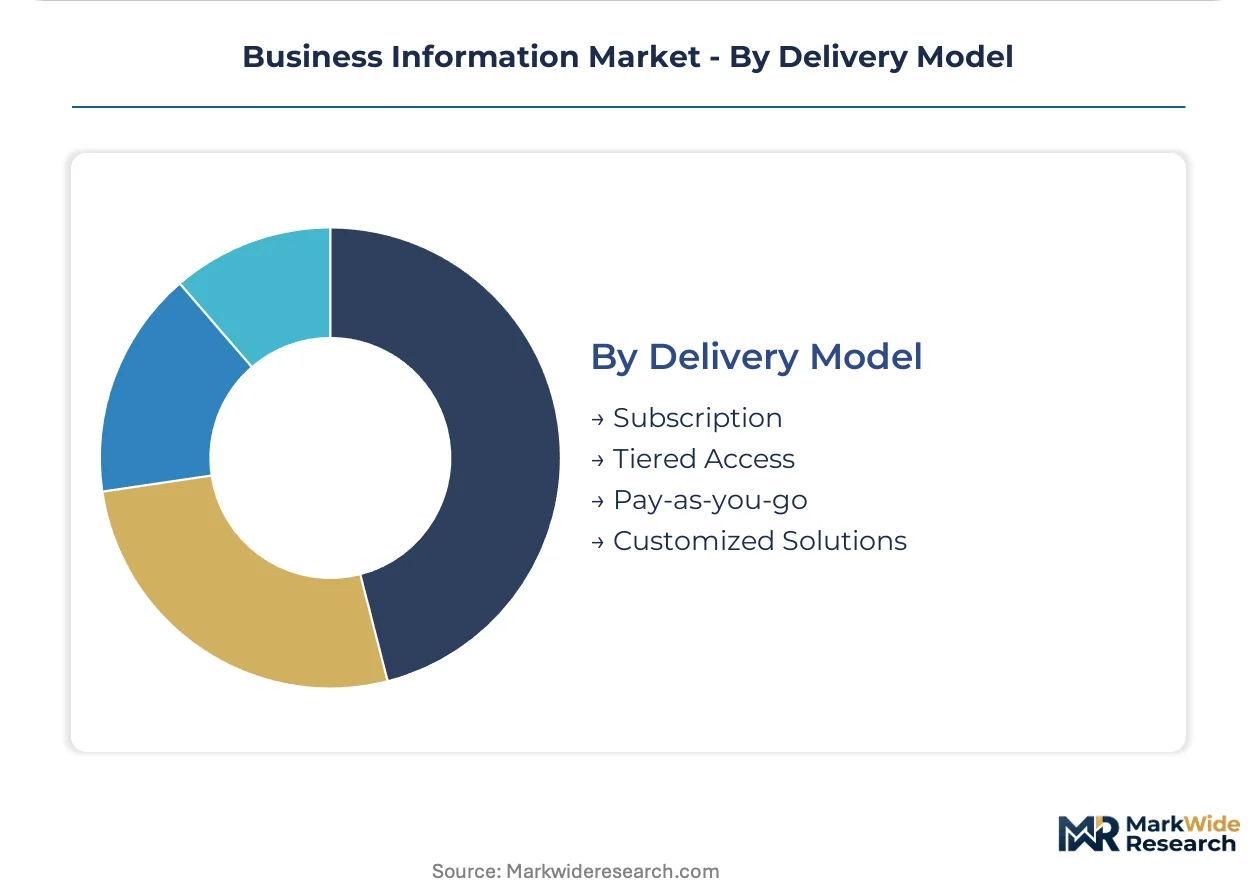
Delivery Model:
Margin structure varies with customization depth and usage predictability.
- Subscription:Recurring revenue models with standardized service levels dominate enterprise relationships.
- Tiered Access:Premium-mid-economy pricing differentiation matches feature depth to buyer sophistication and budget scale.
- Pay-as-you-go:Usage-based pricing aligns costs with transaction volume for intermittent or exploratory use cases.
- Customized Solutions:Bespoke data integration and advisory services command premium pricing for complex regulatory or operational requirements.
Subscription models secure predictable revenue. Tiered access structures expand market coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States enterprise buyers command procurement budgets that exceed German counterparts by substantial margins, yet India's digital public infrastructure is expanding credit bureau coverage faster than any comparable market.
United States
Financial services firms in New York and Chicago drive demand for real-time credit histories and predictive risk scores. The SEC mandates disclosure standards that shape data fields and timeliness requirements for corporate intelligence products. Silicon Valley clusters anchor cloud-native analytics platform development, pulling real-time streams into lending workflows at investment banks.
Germany
Industrial conglomerates in Frankfurt and Munich require integrated credit ratings and benchmarking tools for supply chain risk management. The EU AI Act imposes algorithmic transparency obligations on automated credit scoring systems, forcing vendors to reengineer model documentation. The Rhine-Ruhr metropolitan region concentrates procurement of compliance-ready business intelligence dashboards.
United Kingdom
London-based asset managers and insurers command deep contract values for fixed-income data workflows and terminal networks. The Financial Conduct Authority aligns with EU AI Act principles on automated decision-making transparency. The City of London cluster sustains demand for legal and scientific information verticals through deep content archives.
India
Mid-market firms in Mumbai and Bangalore accelerate adoption of self-service subscription tiers for business intelligence dashboards. The Reserve Bank of India and SEBI expand corporate registry digitization and credit bureau coverage through digital public infrastructure. The National Capital Region of Delhi emerges as a hub for localized data analytics services targeting SME procurement.
Japan
Tokyo-based trading houses and banks anchor demand for proprietary terminal networks and embedded risk analytics. METI guidelines on data governance intersect with emerging algorithmic accountability expectations. The Osaka-Kobe industrial corridor concentrates procurement of pharmaceutical supply chain monitoring tools constrained by patient data protections.
Business Information Market Vendor Landscape
United States-based conglomerates anchor the premium tier; European specialists hold differentiated positions in regulatory intelligence and scientific content. Market structure concentrates around legacy information conglomerates with proprietary credit registries and corporate archives, creating high barriers for new entrants. Three archetypes dominate: integrated data-analytics-consulting bundlers, vertical-specific terminal network operators, and compliance-focused risk scoring platforms. Competitive moves center on M&A to consolidate data archives and strategic partnerships to embed dashboards directly into enterprise software workflows.
Within the integrated bundler tier, RELX PLC and S&P Global Inc. exemplify archetypes that span raw data feeds through advisory services. Bloomberg Finance L.P anchors the terminal network specialist position, occupying a role defined by fixed-income workflow integration. These three entities represent the concentration of proprietary infrastructure that limits mid-tier provider expansion.
| Leading Market Players |
|---|
| Dun & Bradstreet Corporation |
| RELX PLC |
| Bloomberg Finance L.P |
| Verisk Analytics, Inc. |
| Equifax Inc. |
| Thomson Reuters Holdings Inc. |
| Moody's Corporation |
| Morningstar, Inc. |
| S&P Global Inc. |
| Others |
Supply Flow & Price Mechanics
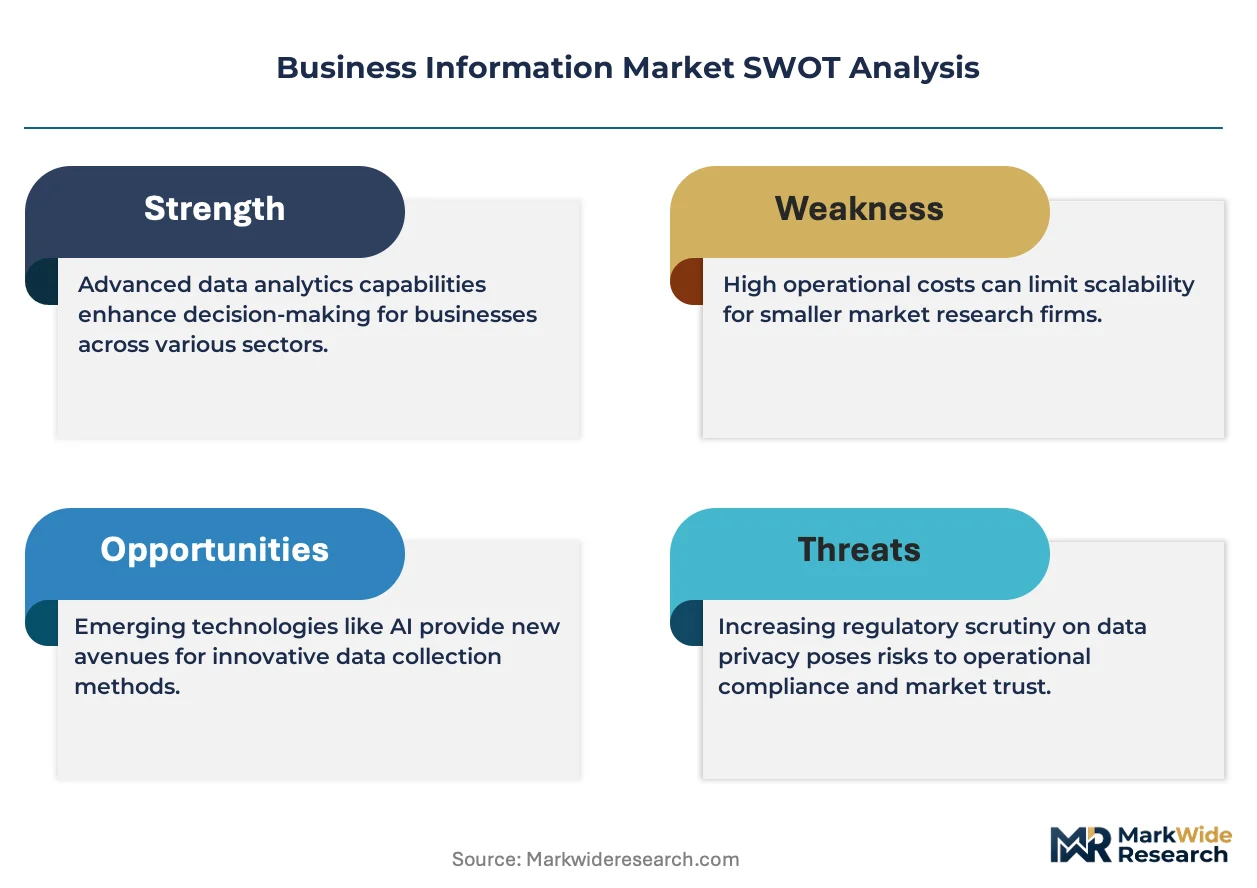
Vertical integration into proprietary credit registries and corporate archives anchors pricing power for legacy information conglomerates while compressing margins for mid-tier analytics providers dependent on licensed data feeds. United States-based enterprises command premium subscription tiers through integrated data-analytics-consulting bundles, whereas Indian SME segments unlock volume through self-service pricing tiers enabled by digital public infrastructure expansion.
Pricing Analysis
Capacity additions in India's digital public infrastructure are reshaping price floors for localized data analytics services targeting mid-market firms. Three-tier pricing structure across premium, standard, and economy levels segments enterprise buyers by workflow integration depth and compliance certification requirements. Price differentiation rests on EU AI Act algorithmic transparency documentation and real-time data infrastructure access. Cost compression in mid-tier analytics subscriptions is intensifying because algorithmic audit obligations inflate compliance spending. Government procurement segments exhibit highest price sensitivity; United States investment banks command lowest sensitivity through bundled terminal network contracts.
Supply Chain Analysis
Single-source vulnerability sits with proprietary credit registries concentrated in the United States and United Kingdom, where legacy archives create captive supply positions for incumbent vendors. Raw material dependencies encompass corporate registry digitization infrastructure, cloud-native analytics platforms, and unstructured news archive processing engines. Supply chain risk centers on regulatory restriction: divergent EU AI Act, SEC disclosure, and HIPAA compliance timelines fragment product roadmaps and multiply certification burdens. Distribution runs through embedded dashboard integrations directly into enterprise software platforms, bypassing standalone procurement cycles at financial institutions and industrial conglomerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate between United States premium-tier procurement budgets and India's expanding SME addressable base, where regulatory compliance costs diverge by factor of three to five across jurisdictions.
For Market Incumbents: Anticipate margin compression from algorithmic audit cost inflation by consolidating proprietary data archives through targeted acquisitions in European regulatory intelligence verticals. Deepen backward integration into cloud-native analytics infrastructure to defend position against real-time data platform entrants. Prioritize EU AI Act certification investment as competitive moat against non-compliant tool categories. For New Entrants and Emerging Players: API-first distribution routes into embedded enterprise software workflows bypass terminal network dominance and unlock SME procurement bypassing standalone sales cycles. Target India's mid-market firms through localized data analytics services leveraging Reserve Bank of India credit bureau expansion. Pursue healthcare-adjacent compliance niches constrained by HIPAA patient-linked dataset protections. For Investors and Strategic Acquirers: Roll-up economics work for vertical-specific terminal network operators because proprietary workflow integration creates high switching costs and recurring revenue predictability. Five-to-ten year viability hinges on generative AI integration compressing analyst research cycles. Watch EU AI Act enforcement granularity as inflection indicator for compliant versus non-compliant vendor tier separation.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Data Archives | Consolidates proprietary credit registry access and deepens content moats against cloud-native entrants. |
| Embedded Dashboard Integration | Bypasses standalone procurement cycles by integrating directly into SAP and Oracle enterprise workflows. |
| EU AI Act Compliance Certification | Creates vendor tier separation as European financial institutions segment procurement between compliant and non-compliant tools. |
| Real-Time Data Infrastructure Buildout | Pulls instantaneous credit streams into lending workflows at investment banks and trading houses. |
| Geographic Expansion into India | Captures SME contract volumes through self-service tiers enabled by RBI credit bureau digitization. |
Methodological Framework
Direct dialogue with chief data officers at financial institutions, regulatory compliance leads at pharmaceutical manufacturers, procurement directors at industrial conglomerates, and platform engineers at cloud-native analytics vendors grounded qualitative findings. Secondary validation drew from SEC disclosure filings, EU AI Act regulatory texts, Reserve Bank of India circulars on credit infrastructure, and corporate registry digitization progress reports. Bottom-up and top-down triangulation cross-referenced contract value estimates against infrastructure spending disclosures.
Bottom-up modeling segmented revenue by service type, client tier, and delivery model across the projection horizon, while top-down approaches validated against aggregate enterprise software spending patterns. Analytical dimensions encompassed industry vertical adoption curves, algorithmic transparency compliance tiers, and embedded versus standalone distribution channels. CAGRs derived from weighted average of historical trajectory and technology adoption S-curve positioning, with inputs from real-time data platform deployment rates and generative AI integration timelines.
The model assumes a particular technology adoption path; alternative pathways for generative AI natural language processing engines would alter the outlook for analyst research cycle compression. Forecasts reflect assumptions around EU AI Act enforcement intensity, HIPAA constraint evolution, and cloud infrastructure cost curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Consent Management Market
Digital Solutions
Software Defined Application and Infrastructure Market
Digital Solutions
Global Intelligent Platform Management Interface (IPMI) Market
Digital Solutions
Retail Warehouse Management Systems Market
Digital Solutions
Community Engagement Software Market
Digital Solutions
Online Classified Ad Platform Market
Digital Solutions
United States Contract Manufacturing Services Market
Digital Solutions
Online Voting System Market
Digital Solutions
Contactless Ticketing Solutions Market
Digital Solutions
Global Genealogy Products and Services Market
Digital Solutions
Legal Transcription Market
Digital Solutions
Online Dating Market
Digital Solutions
Global IT Asset Disposition (ITAD) Market
Digital Solutions
Brazil Digital Twin Market
Digital Solutions
Kazakhstan ICT Market
Digital Solutions
Agriculture Software Market