
 Global Business Process Outsourcing (BPO) Market | 2026-2036
Global Business Process Outsourcing (BPO) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Business Process Outsourcing (BPO) Market Analysis
Multi-source vendor consolidation is rebalancing contract structures across enterprise buyers. Accenture leverages its hybrid delivery footprint to capture complex transformation engagements. Tata Consultancy Services Limited anchors large-scale finance and accounting contracts through its India-centric delivery model. Cognizant competes aggressively in healthcare payer BPO with specialized domain expertise.
Business process outsourcing denotes the contractual delegation of operational functions—such as transaction processing, customer interaction management, and back-office administration—to third-party providers employing workflow automation, cloud-based delivery platforms, and labor arbitrage across geographies. Its commercial purpose centers on cost reduction, operational scalability, and access to specialized process expertise without fixed-capital expansion. Customer support services occupy the largest revenue pool within service type segmentation, reflecting perpetual enterprise demand for omnichannel engagement infrastructure. Offshore delivery models represent the fastest-expanding structural category, driven by wage differentials and maturing telecommunications infrastructure in South Asia. Finance and accounting services sustain premium margin pools due to compliance-sensitive process requirements and limited provider certification.
FDA data integrity requirements shape healthcare BPO contracting terms, mandating audit trails and validation protocols for outsourced clinical trial support functions. GDPR and the EU AI Act impose cross-border data handling restrictions and algorithmic transparency obligations on European customer support and automated decisioning workflows. India's Digital Personal Data Protection Act introduces localization mandates affecting offshore delivery architecture. Stakeholders must monitor evolving sovereignty frameworks as jurisdictions tighten extraterritorial data governance.
Market Dynamics
Generative AI deployment is compressing labor-intensive process tiers while regulatory fragmentation across data sovereignty regimes forces providers to re-architect delivery footprints. This structural tension between automation economics and compliance complexity defines current competitive positioning.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:European enterprises accelerate outsourcing of automated decision-audit functions to specialized providers with established validation protocols.
- Healthcare administrative complexity:FDA data integrity requirements for clinical trial documentation drive pharmaceutical sponsors toward certified BPO partners with compliant quality management systems.
- India's Digital Personal Data Protection Act:Localization requirements stimulate domestic capacity expansion in Bangalore and Hyderabad delivery clusters.
Market Restraints
- Wage arbitrage erosion:Rising talent costs in Indian tier-1 cities compress margin pools for transaction processing contracts.
- GDPR extraterritorial enforcement:Cross-border data transfer restrictions impose architectural costs on offshore delivery models serving European clients.
- Cloud infrastructure concentration:Dependency on hyperscale providers in limited jurisdictions creates systemic resilience exposure.
Strategic Opportunities
- Brazilian financial services modernization:PIX real-time payment infrastructure and open banking mandates generate demand for regulatory technology integration.
- Convergence of robotic process automation with large language models:Hybrid cognitive automation enables higher-value process transformation beyond rules-based task execution.
- Saudi Vision 2030 localization incentives:Government procurement preferences for in-country service delivery attract provider facility investment.
Industry Challenges
- GenAI prompt engineering talent scarcity:Shortage of practitioners capable of designing production-grade automated workflows limits deployment velocity.
- Multi-jurisdiction certification stacking:Providers must maintain parallel SOC 2, ISO 27001, HIPAA, and PCI-DSS attestations with divergent audit cycles.
- Technical debt in legacy ERP integration:Custom middleware requirements for SAP and Oracle system connectivity inflate implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Business Process Outsourcing (BPO) Market |
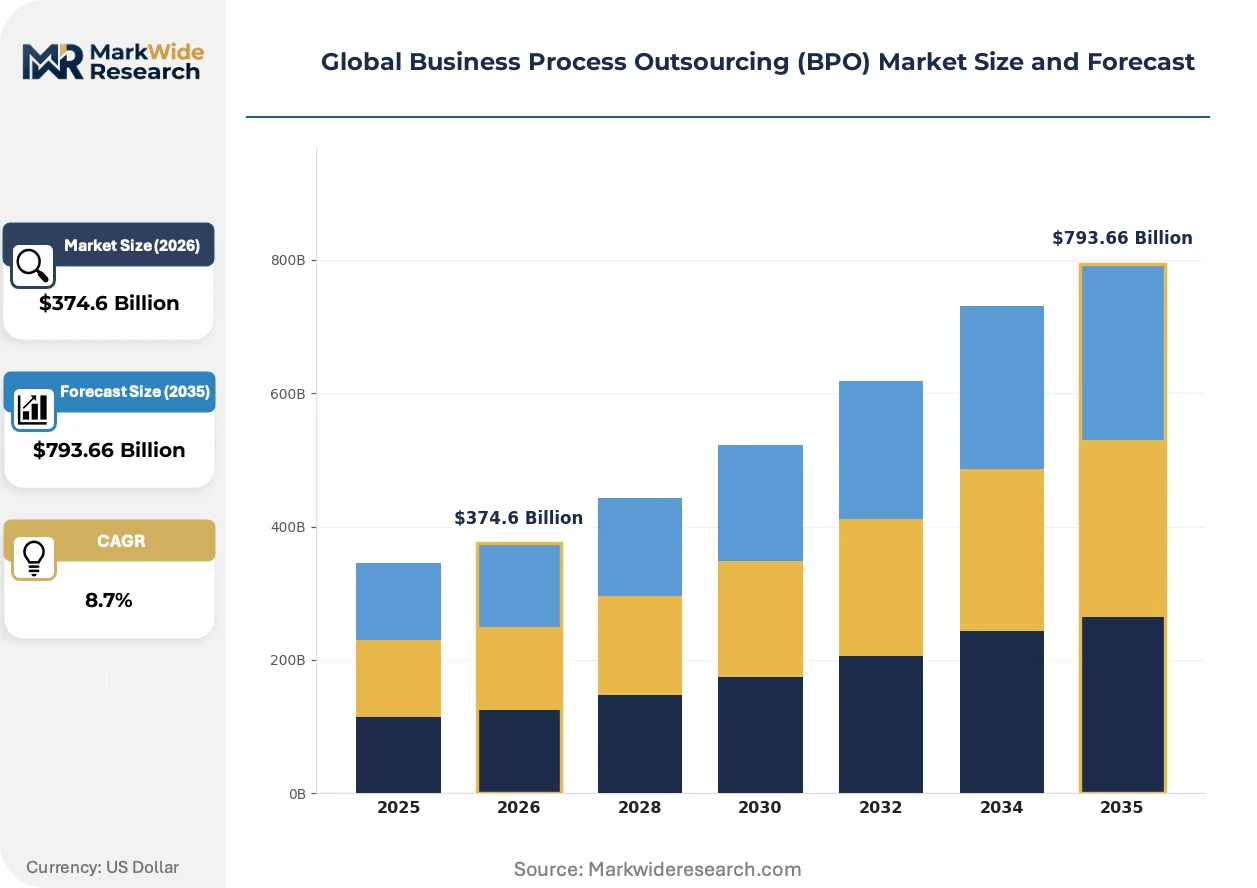
| Market Size in 2026 | $374.6 Billion |
| Market Size in 2035 | $793.66 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Finance & Accounting, Customer Support, Human Resources, IT Services Client Type: Small Businesses, Medium Enterprises, Large Corporations, Startups Industry Vertical: Healthcare, Telecommunications, Retail, Manufacturing Delivery Model: Onshore, Offshore, Nearshore, Hybrid |
| Companies Covered | Accenture, Tata Consultancy Services Limited, Teleperformance SE, Concentrix Corporation, Cognizant, Genpact Limited, Wipro, Capgemini, International Business Machines Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Business Process Outsourcing (BPO) Market Emerging Trajectories
Workflow orchestration platforms are embedding intelligence at process nodes, redefining how human and automated labor interleave. This evolution compresses traditional tiered service models and elevates technical architecture as a competitive differentiator.
Agentic AI systems capable of autonomous multi-step task execution are decentralizing process ownership from centralized operations centers to distributed decision nodes. Healthcare payers in the United States pilot these capabilities for claims adjudication, shifting from batch processing to exception-only human intervention. The structural consequence is collapsing headcount ratios per transaction processed.
The EU AI Act's risk-classification framework for automated customer interaction systems imposes conformity assessment obligations on European BPO contracts. Providers must document training data provenance and maintain human oversight mechanisms for high-risk applications. Financial services and public sector engagements face the steepest compliance ramp, with several large contracts now specifying algorithmic impact assessment deliverables.
Enterprise buyers are unbundling monolithic outsourcing agreements into modular, outcome-defined component contracts with discrete performance metrics. This procurement evolution displaces traditional full-time-equivalent pricing in favor of transaction-based or business-outcome fee structures. The shift is most pronounced in North American banking and insurance verticals, where procurement functions now mandate service-level agreements tied to measurable operational KPIs rather than input metrics.
Global Business Process Outsourcing (BPO) Market Segmentation
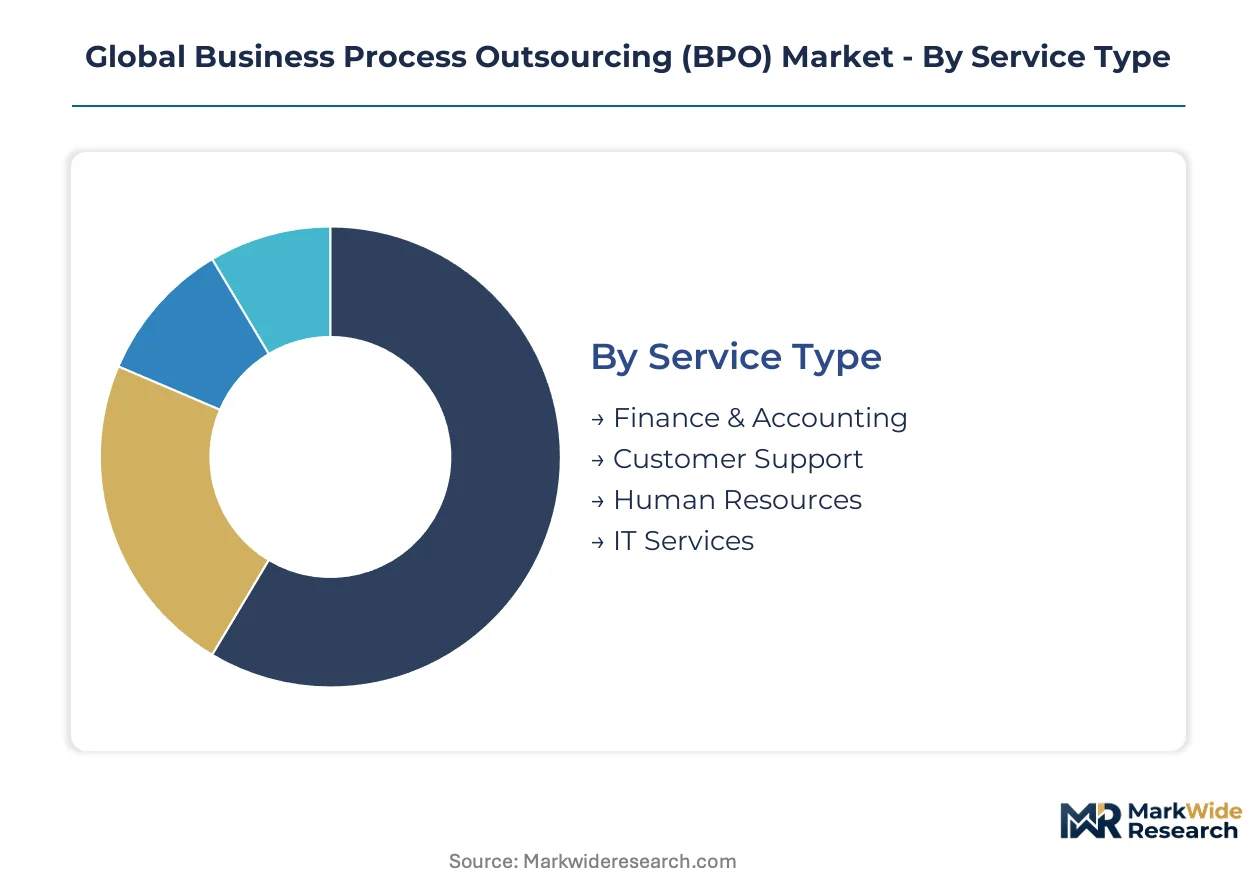
BPO procurement decisions hinge on matching process complexity to delivery architecture. Certification requirements, data sovereignty exposure, and labor arbitrage economics vary sharply across service categories and client profiles.
Service Type:
Finance & Accounting demands parallel SOC 1 Type II and ISO 27001 attestations. Customer Support contracts face EU AI Act algorithmic transparency obligations for automated interaction systems. Human Resources outsourcing requires GDPR-compliant payroll data handling protocols. IT Services contracts typically stack HIPAA, PCI-DSS, and FedRAMP certifications for healthcare and government verticals.
- Finance & Accounting:Encompasses accounts payable, receivable, general ledger management, and financial planning with embedded compliance controls. Pharmaceutical sponsors in the United States concentrate demand here as FDA data integrity mandates for clinical trial documentation drive outsourcing to certified quality management systems.
- Customer Support:Covers omnichannel engagement infrastructure including voice, chat, email, and social media interaction management. European enterprises accelerate contracting for this segment as EU AI Act risk-classification frameworks impose conformity assessment obligations on automated decision-audit functions.
- Human Resources:Payroll administration, benefits management, and talent acquisition process outsourcing with embedded regulatory compliance.
- IT Services:Application development, infrastructure management, and technical support desk operations with multi-jurisdiction certification requirements.
Leading the category by volume: Customer Support. Growing fastest: Finance & Accounting.
Client Type:
Contract structures diverge by scale. Large Corporations negotiate outcome-based pricing with embedded transformation roadmaps. Startups prioritize modular, consumption-aligned fee structures without capital lock-in.
- Large Corporations:Drive complex multi-function outsourcing with dedicated delivery centers and custom SLA architectures. These buyers in North American banking and insurance verticals now mandate transaction-based pricing tied to measurable operational KPIs rather than input metrics.
- Medium Enterprises:Represent the fastest-expanding client pool as cloud-native delivery platforms reduce minimum contract thresholds. Buyers across Indian tier-2 cities leverage standardized finance and accounting packages to bypass fixed-capital expansion.
- Small Businesses:Access standardized process packages through platformized delivery with limited customization scope.
- Startups:Prioritize variable-cost structures and rapid scaling capacity without long-term contractual commitments.
Volume concentration: Large Corporations. Steepest expansion trajectory: Medium Enterprises.
Industry Vertical:
Healthcare commands premium pricing due to FDA validation protocols and HIPAA security rule compliance. Telecommunications contracts emphasize real-time infrastructure resilience and FCC reporting alignment.
- Healthcare:Claims processing, clinical trial documentation, and revenue cycle management with stringent audit trail requirements. United States payers pilot agentic AI for claims adjudication, collapsing headcount ratios per transaction processed while maintaining HIPAA-compliant data handling.
- Telecommunications:Customer lifecycle management, billing operations, and network operations center support with 24/7 resilience mandates. Providers serving Brazilian carriers integrate PIX real-time payment infrastructure and open banking regulatory technology.
- Retail:Order management, returns processing, and customer loyalty program administration with seasonal elasticity requirements.
- Manufacturing:Supply chain coordination, procurement process outsourcing, and vendor management with embedded quality systems.
Dominant by contract value: Healthcare. Expanding most quickly: Telecommunications.
Delivery Model:
Architecture choices reflect wage differentials against data localization mandates. Offshore models face reconfiguration as India's Digital Personal Data Protection Act imposes storage requirements.
- Offshore:Leverages wage arbitrage across South Asian delivery clusters with maturing telecommunications infrastructure. Bangalore and Hyderabad anchor capacity expansion as localization requirements stimulate domestic facility investment.
- Hybrid:Combines onshore client proximity with offshore cost efficiency through intelligent workflow distribution. European buyers favor this model to satisfy GDPR extraterritorial enforcement while retaining labor economics.
- Onshore:Delivers client-proximate operations with minimal data transfer exposure and highest labor cost structures.
- Nearshore:Balances time-zone alignment with moderate cost advantages for North American and European buyers.
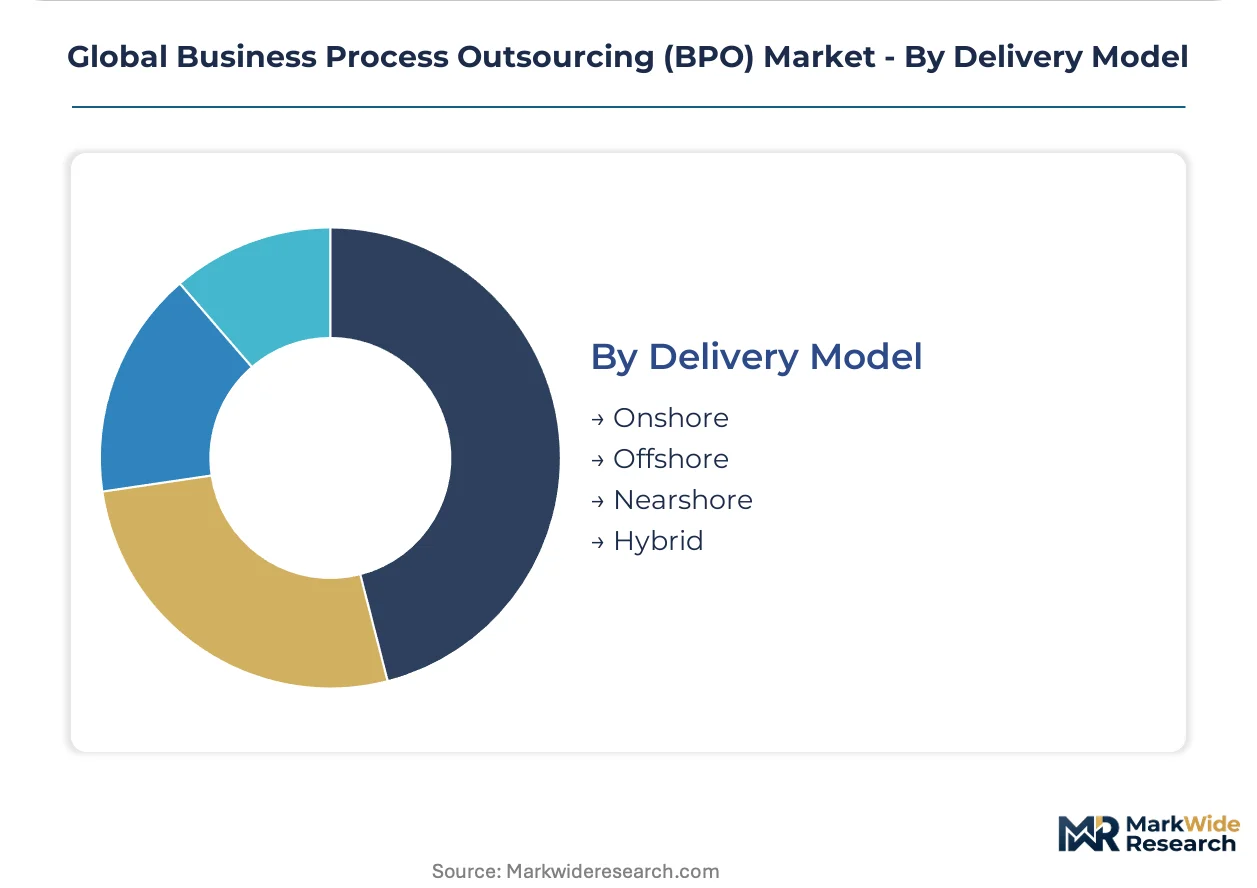
Current volume leader: Offshore. Gaining share fastest: Hybrid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise outsourcing demand concentrates in India, where Bangalore and Hyderabad delivery clusters anchor offshore capacity expansion. The United States drives premium healthcare BPO contracting. European compliance complexity reshapes delivery architecture across multiple jurisdictions.
United States
Healthcare payers and pharmaceutical sponsors dominate BPO procurement as FDA data integrity mandates for clinical trial documentation intensify outsourcing requirements. HIPAA security rule enforcement shapes vendor selection criteria for claims processing and revenue cycle management contracts. Dallas and Phoenix host expanding delivery centers serving domestic healthcare and financial services verticals.
India
The Digital Personal Data Protection Act imposes data localization requirements that stimulate domestic facility investment across finance and accounting service lines. Bangalore anchors specialized delivery clusters for complex transformation engagements, while Hyderabad expands capacity for healthcare payer administrative functions. Tier-1 city wage inflation compresses margins for transaction processing contracts.
Germany
Industrial manufacturing and automotive enterprises outsource supply chain coordination and procurement process administration to manage compliance-sensitive operations. GDPR extraterritorial enforcement restricts cross-border data transfers, favoring hybrid delivery models with European data residency. Frankfurt and Munich concentrate provider facilities serving DAX-listed corporations.
United Kingdom
Financial services modernization and open banking mandates generate demand for regulatory technology integration within BPO contracts. The Financial Conduct Authority's operational resilience requirements shape service-level agreement structures for banking and insurance outsourcing. London anchors premium-tier engagements, while regional centers in Manchester and Glasgow capture mid-market volume.
Brazil
PIX real-time payment infrastructure and Central Bank open banking regulations create demand for payment processing and customer lifecycle management outsourcing. Telecommunications carriers modernize billing operations to align with regulatory technology requirements. São Paulo and Rio de Janeiro concentrate provider investment serving Latin American financial services expansion.
Global Business Process Outsourcing (BPO) Market Vendor Landscape
Strategic partnerships and hybrid delivery footprint expansion dominate the current landscape as providers reposition for compliance-complexity premiums. The vendor base organizes into three tiers: integrated consultancies with transformation capabilities, India-centric scale operators, and specialized vertical players. Competitive positioning hinges on multi-jurisdiction certification maintenance and generative AI deployment velocity. M&A activity concentrates on acquiring niche healthcare and financial services domain expertise.
Within the integrated consultancy tier, Accenture occupies a position exemplifying hybrid delivery architecture spanning onshore client proximity and offshore cost efficiency. Among India-centric scale operators, Tata Consultancy Services Limited and Wipro represent archetypes of large-scale finance and accounting contract anchoring through domestic delivery concentration. Cognizant sits within the specialized vertical player category, occupying a position tied to healthcare payer domain expertise.
| Leading Market Players |
|---|
| Accenture |
| Tata Consultancy Services Limited |
| Teleperformance SE |
| Concentrix Corporation |
| Cognizant |
| Genpact Limited |
| Wipro |
| Capgemini |
| International Business Machines Corporation |
| Others |
Supply Flow & Price Mechanics
Large corporation procurement functions in North American banking and insurance verticals mandate transaction-based pricing tied to measurable operational KPIs rather than input metrics, compressing traditional full-time-equivalent models and reshaping provider cost structures across delivery tiers.
Pricing Analysis
Service-level agreement bundling separates comprehensive transformation engagements with embedded compliance protocols from unbundled modular contracts with discrete performance metrics. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth—SOC 2 Type II and ISO 27001 attestation tiers command substantial premiums over baseline quality management systems. Cost compression in transaction processing contracts intensifies because tier-1 Indian city wage inflation erodes legacy labor arbitrage economics. Startups exhibit highest price sensitivity due to variable-cost structure requirements, while healthcare payers demonstrate lowest sensitivity given FDA validation protocol mandates.
Supply Chain Analysis
Prompt engineering talent availability in Bangalore, Hyderabad, and Dallas delivery clusters constrains generative AI deployment velocity across transformation engagements. Provider capacity draws from specialized delivery infrastructure, cloud hyperscale dependencies, and certified quality management systems anchored in India and the United States. Single-source vulnerability in hyperscale cloud infrastructure creates systemic resilience exposure for offshore delivery architectures. Distribution runs through direct enterprise sales teams, strategic advisory partnerships, and platform-enabled self-service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The BPO market functions as a cost-of-compliance story where EU AI Act algorithmic transparency mandates erect barrier-to-entry moats favoring providers with established validation protocols and multi-jurisdiction certification maintenance.
For Market Incumbents: Anchor defensive positioning through accelerated generative AI deployment velocity and expanded hybrid delivery footprint investment in GDPR-compliant European data residency. Consolidation of niche healthcare domain expertise through targeted capability acquisition counters emerging specialized vertical players. Certification stacking in parallel SOC 2, ISO 27001, HIPAA, and PCI-DSS attestations with convergent audit cycles preserves margin premiums against low-cost challengers. For New Entrants and Emerging Players: Cloud-native platform routes offer lowest-friction entry into medium enterprise finance and accounting outsourcing across Indian tier-2 cities, where standardized packages bypass fixed-capital expansion requirements. Brazilian regulatory technology integration for PIX real-time payment infrastructure presents underexposed white-space in financial services modernization. Saudi Vision 2030 localization incentives for in-country service delivery attract facility investment with government procurement preference tailwinds. For Investors and Strategic Acquirers: The window for entry favors vertically integrated consultancies with hybrid delivery architecture spanning onshore client proximity and offshore cost efficiency. Long-term viability centers on providers demonstrating production-grade agentic AI workflow deployment and healthcare payer domain depth. Watch EU AI Act enforcement velocity as inflection indicator for compliance-complexity premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Delivery Footprint Expansion | GDPR-compliant European data residency satisfies extraterritorial enforcement while retaining Indian labor economics. |
| Generative AI Workflow Integration | Agentic AI deployment for claims adjudication collapses headcount ratios per transaction processed. |
| Healthcare Domain Acquisition | FDA-certified quality management systems capture pharmaceutical sponsor clinical trial documentation outsourcing. |
| Regulatory Technology Partnership | Brazilian open banking mandates generate payment processing modernization demand for telecommunications carriers. |
| Certification Convergence Program | Parallel SOC 2, ISO 27001, HIPAA, and PCI-DSS attestations with aligned audit cycles reduce compliance overhead. |
Methodological Framework
Independent corroboration across BPO operations executives, healthcare payer procurement directors, regulatory compliance officers, and cloud infrastructure specialists underwrites the qualitative findings in this study. Primary fieldwork with enterprise buyers in North American banking and insurance verticals, India-centric delivery center managers, and EU AI Act implementation consultants combined with secondary validation from SEC filings, customs and trade data, FDA warning letters, and EMA regulatory guidance databases. Bottom-up contract value aggregation and top-down macroeconomic adjustment anchor the analytical framework.
Comparable-period anchoring to historical delivery model evolution and automation technology adoption curves structured the projection methodology across the analysis window. Segmentation dimensions modeled include service type complexity, client scale tier, industry vertical regulatory intensity, and delivery model architecture. CAGRs derived from regression analysis against labor cost indices, certification penetration rates, and generative AI deployment velocity inputs. Workforce availability constraints in Indian tier-1 cities and EU AI Act compliance cost assumptions inform the forecast trajectory.
The model holds under stable regulatory enforcement timelines and sustained wage differential economics; deviation in data sovereignty mandate acceleration or hyperscale infrastructure concentration failure would shift capacity expansion assumptions. Forecasts reflect documented assumptions regarding automation substitution rates and certification maintenance costs. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Global Contact and Call Center Outsourcing Market
Business Process Outsourcing (BPO)
Business Processing Outsourcing Market
Business Process Outsourcing (BPO)
Middleoffice BPO Services Market
Business Process Outsourcing (BPO)
Recruitment Process Outsourcing (RPO) Services Market
Business Process Outsourcing (BPO)
United States IT Outsourcing Market
Business Process Outsourcing (BPO)
Life Sciences BPO Market
Business Process Outsourcing (BPO)
Business Process As a Service (Bpaas) Market
Business Process Outsourcing (BPO)
Global Application Outsourcing Market
Business Process Outsourcing (BPO)
United States Healthcare BPO Market
Business Process Outsourcing (BPO)
US Managed Print Services Market
Business Process Outsourcing (BPO)
Middle East and Africa Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Global Insurance Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Indonesia Business Process Outsourcing Services Market
Business Process Outsourcing (BPO)
Healthcare BPO Market
Business Process Outsourcing (BPO)
North America Business Process-As-A-Service (Bpaas) Market
Business Process Outsourcing (BPO)
Europe Business Process Outsourcing (BPO) Market