
 Mobile Campaign Management Market | 2026-2036
Mobile Campaign Management Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Campaign Management Market Foresight
Asset-light SaaS subscription models and usage-based billing is fragmenting competitive barriers in mobile campaign management, allowing mid-tier vendors to challenge incumbents without heavy infrastructure investments. Salesforce Marketing Cloud leverages its CRM data backbone to anchor enterprise retention strategies. Braze differentiates through real-time streaming architecture that supports sub-second personalization triggers. CleverTap specializes in emerging-market localization with tiered pricing that accommodates smaller retailer budgets.
Mobile campaign management encompasses software platforms that orchestrate, execute, and measure marketing communications across smartphone channels including push notifications, in-app messaging, SMS, and mobile web, typically operating through cloud-native architectures with API-driven interoperability and sub-100-millisecond latency requirements for real-time engagement triggering. The primary commercial purpose centers on converting fragmented mobile touchpoints into coordinated revenue-generating interactions while maintaining subscriber consent state across channels. Cloud-based and SaaS deployment models now dominate new procurement as enterprises prioritize elastic scaling over fixed infrastructure commitments, while messaging solutions capture disproportionate attention due to their direct line to consumer lock screens and superior conversion attribution. Analytics platforms represent a maturing margin pool where differentiation has shifted from dashboard visualization to predictive churn modeling and automated creative optimization.
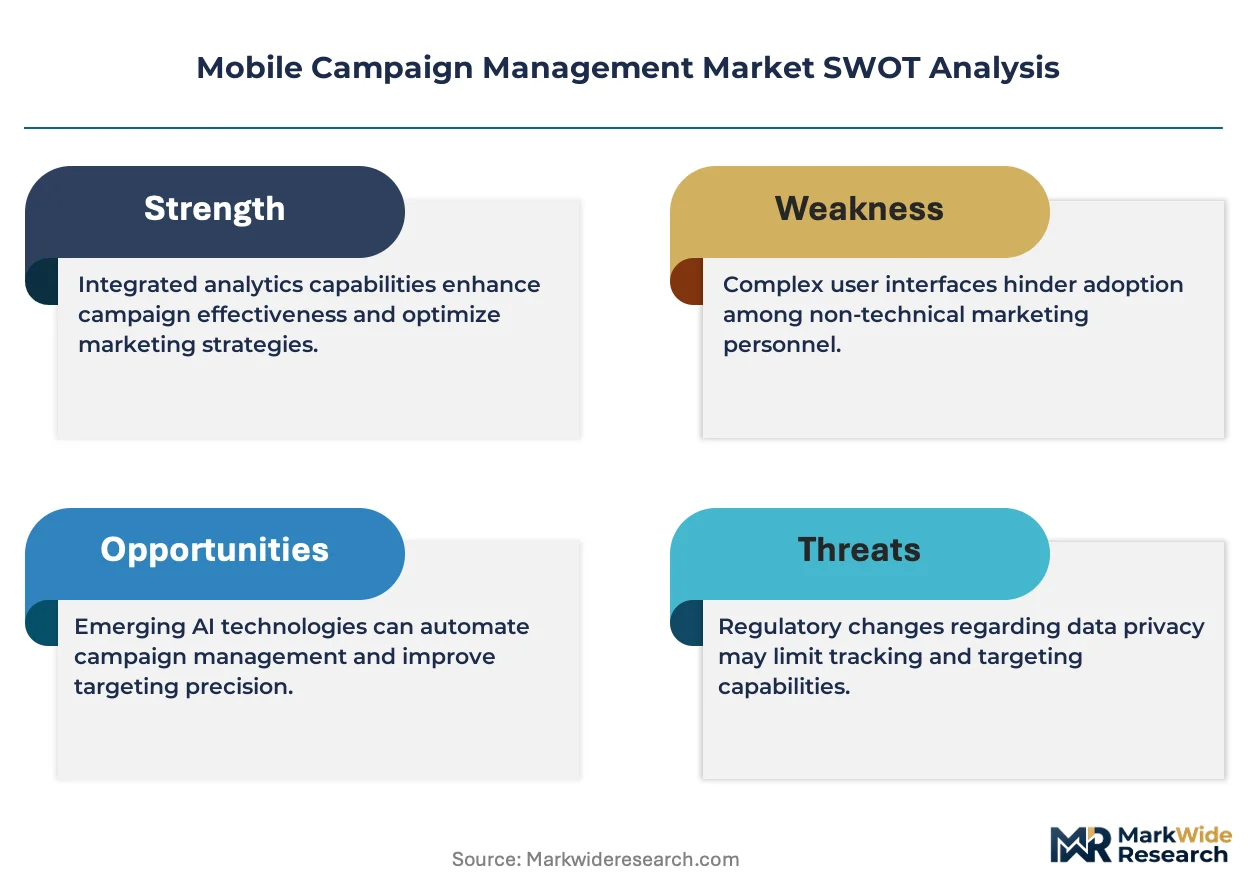
The EU AI Act and GDPR impose algorithmic accountability mandates on automated campaign targeting, while the US FCC enforces TCPA restrictions that shape opt-in architecture and message frequency caps for SMS-based programs. India's TRAI guidelines on commercial communications add another compliance layer for vendors serving its expanding digital advertiser base. Stakeholders must weigh regulatory velocity against platform modernization timelines, as consent-framework fragmentation across jurisdictions threatens to outpace standardized product roadmaps.
Market Dynamics
The EU AI Act's algorithmic accountability mandates are compressing platform upgrade timelines, forcing vendors to rebuild consent frameworks and explainability layers while retailers demand uninterrupted campaign orchestration.
Growth Catalysts
- India's PLI scheme for digital infrastructure:Government incentives accelerate enterprise software procurement among domestic retailers seeking mobile-first customer engagement stacks.
- Real-time streaming architecture:Sub-100-millisecond latency requirements push adoption of edge-compute personalization engines that trigger contextual messaging based on in-app behavioral signals.
- GDPR consent-state synchronization:Cross-channel subscriber preference management creates recurring SaaS revenue pools as brands mandate unified consent repositories across push, SMS, and mobile web touchpoints.
Market Restraints
- Cross-jurisdictional compliance fragmentation:India's TRAI guidelines, EU AI Act transparency rules, and US FCC TCPA restrictions create incompatible technical specifications that fragment product roadmaps.
- Cloud infrastructure cost volatility:Elastic scaling dependencies expose mid-tier vendors to hyperscaler pricing swings that compress margins on usage-based billing contracts.
- Legacy CRM data silos:Enterprise retention of on-premise customer databases slows API-driven interoperability with modern campaign orchestration layers.
Strategic Opportunities
- Indonesia's mobile-first merchant base:Underpenetrated mid-market retailers lack localized tiered pricing options for automated messaging solutions.
- Predictive churn modeling convergence:Machine learning pipelines integrating transaction history with engagement telemetry create differentiated analytics offerings.
- Outcome-based creative optimization:Automated A/B testing of message variants tied to conversion attribution reshapes vendor-client contracting structures.
Industry Challenges
- ML engineering talent scarcity:Real-time personalization algorithm development requires specialized data science capabilities concentrated in competitive labor markets.
- ISO 27001 certification timelines:Enterprise procurement mandates for information security management systems delay vendor onboarding by quarters.
- Legacy SMS gateway integration:Decades-old telecommunications protocols create friction in unified campaign orchestration architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Campaign Management Market |
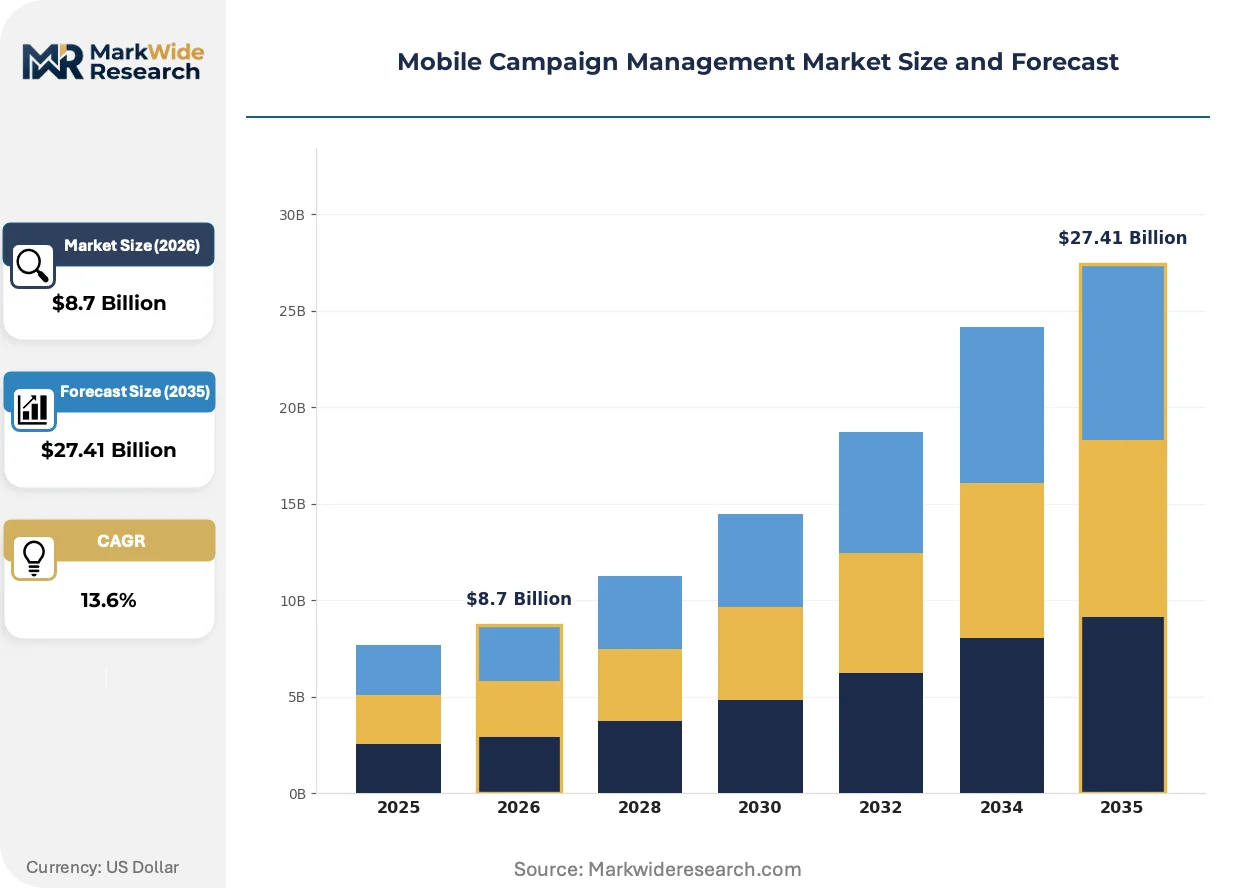
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $27.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Automation Tools, Analytics Platforms, Content Management, Messaging Solutions Deployment Model: On-Premises, Cloud-Based, Hybrid Solutions, SaaS Models End User: Retailers, Brands, Agencies, Publishers Integration Level: API Integration, CRM Integration, E-commerce Platforms, Social Media Integration |
| Companies Covered | Braze, Salesforce Marketing Cloud, Adobe Campaign, CleverTap, Customer.io, Vibes, Moburst, Attentive, Zoomd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Campaign Management Market Shifts & Advancements
Automated campaign targeting is undergoing fundamental reconstruction as algorithmic transparency mandates collide with real-time personalization requirements, reshaping vendor technical architectures and buyer evaluation criteria simultaneously.
Edge-deployed inference engines are migrating from centralized cloud batch processing to localized decision nodes that execute personalization logic within 50 milliseconds of behavioral triggers. Tier-one retailers in Germany and France are piloting these architectures to satisfy EU AI Act explainability requirements without sacrificing engagement velocity. This migration from cloud-concentrated compute is compressing vendor infrastructure strategies toward hybrid deployment models.
The EU AI Act's risk-based classification system for automated decision-making imposes documentation and human-oversight obligations on campaign targeting algorithms that profile consumer behavior. Platform vendors must now embed audit trails and counterfactual explanation modules into production pipelines. Retail and financial services verticals face the steepest compliance curves, with German insurers already mandating algorithmic impact assessments for customer segmentation models.
Subscription contracting for campaign management is pivoting from seat-based licensing to event-volume tiers that align vendor revenue with client message throughput. Mid-market retailers in India and Brazil prefer this structure as it defers fixed costs until scale validates platform investment. This behavioral shift is most pronounced among direct-to-consumer brands operating on thin working capital cycles, where cash flow predictability outweighs long-term cost optimization.
Mobile Campaign Management Market Segmentation
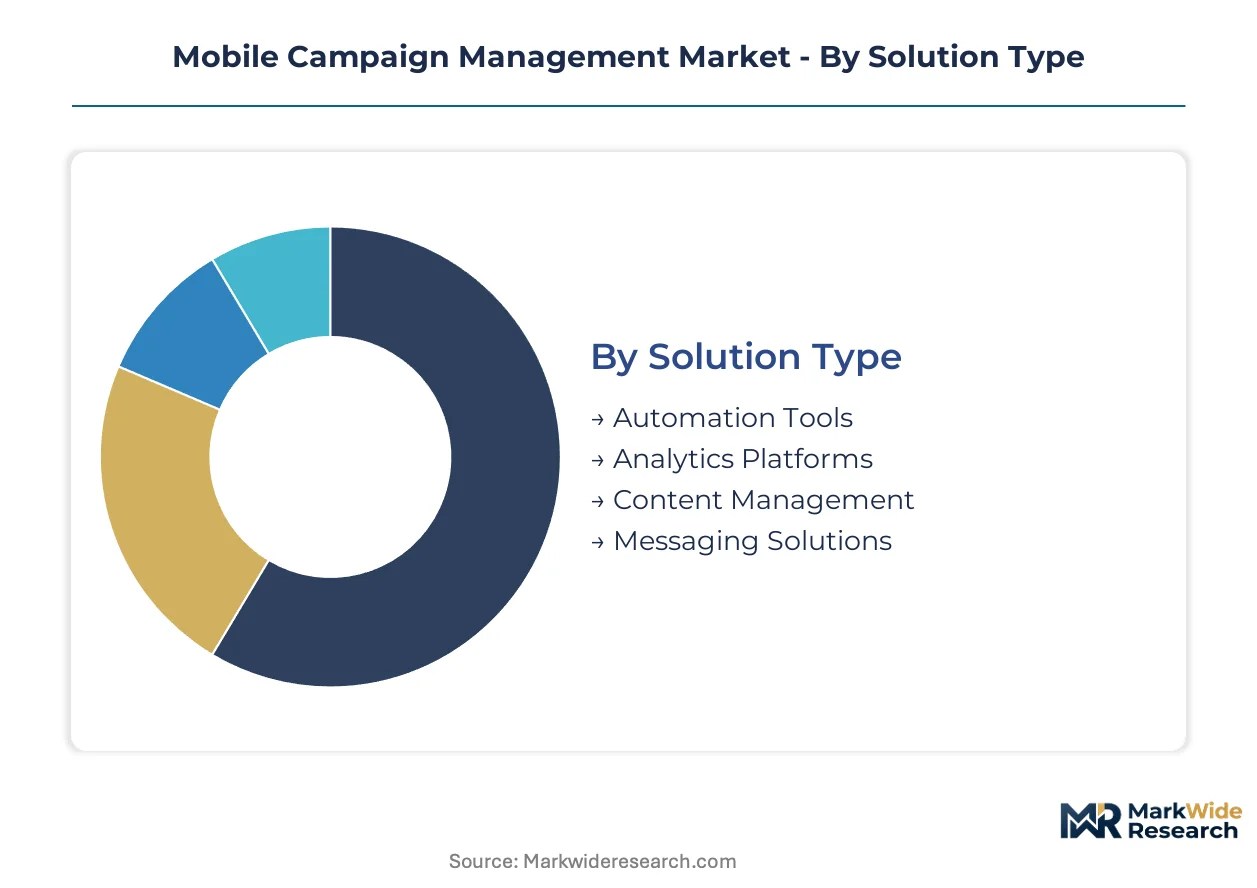
Segmentation in mobile campaign management reveals how vendor capabilities align with divergent client technical maturity and compliance burdens. Deployment preferences and integration architectures now outweigh feature breadth in procurement decisions, particularly as EU AI Act mandates reshape platform evaluation criteria.
Solution Type:
Cost tier separates basic orchestration utilities from premium predictive engines that command recurring revenue multiples.
- Automation Tools:Workflow engines that sequence multi-channel message delivery based on behavioral triggers and time-delay rules. Indian retailers under PLI scheme incentives are consolidating procurement around these tools to reduce manual campaign operations. Demand concentrates among mid-market direct-to-consumer brands seeking to compress campaign production cycles without expanding headcount.
- Analytics Platforms:Telemetry aggregation systems that correlate engagement signals with transaction outcomes to calculate channel-level attribution. German insurers and French retailers are mandating these platforms to satisfy EU AI Act algorithmic impact assessment requirements for customer segmentation models. The installed base skews toward enterprises with dedicated data science functions.
- Content Management:Asset repositories with variant generation capabilities for A/B testing message creative.
- Messaging Solutions:Specialized infrastructure for push notification, SMS, and in-app delivery with sub-100-millisecond latency guarantees.
Automation Tools holds installed capacity. Analytics Platforms is rotating up the share rankings.
Deployment Model:
Application criticality determines whether clients absorb infrastructure ownership or delegate operational risk to vendor-managed environments.
- Cloud-Based:Hyperscaler-hosted architectures offering elastic compute scaling without capital expenditure commitment. Brazilian and Indian mid-market retailers prefer this model to align platform costs with message volume rather than fixed licensing. The structure accommodates seasonal demand spikes without procurement friction.
- SaaS Models:Subscription contracting with usage-based tiers that defer costs until scale validates platform investment. Direct-to-consumer brands operating on thin working capital cycles in Indonesia and Brazil are driving adoption of event-volume pricing structures. This model fragments competitive barriers by reducing upfront procurement thresholds.
- On-Premises:Client-controlled infrastructure for regulated sectors with data residency mandates.
- Hybrid Solutions:Split architectures that retain sensitive processing on-premise while leveraging cloud burst capacity.
SaaS Models captures new logo acquisition. Cloud-Based is expanding most quickly among migrating legacy installations.
End User:
Customer type dictates feature prioritization, with retailers demanding real-time personalization and agencies requiring multi-tenant orchestration capabilities.
- Retailers:Direct merchants operating owned digital properties who require unified consent management across push, SMS, and mobile web touchpoints. EU-based retailers face the steepest compliance curves as GDPR and AI Act obligations converge on subscriber preference repositories. These buyers prioritize edge-deployed inference engines that satisfy explainability requirements without sacrificing engagement velocity.
- Agencies:Service providers managing campaigns across multiple client accounts with segregated data environments. The segment demands API-driven interoperability to ingest CRM data from disparate client systems without normalization overhead. Procurement concentrates among holding companies consolidating point solutions into unified stacks.
- Brands:Product manufacturers without direct retail operations seeking performance marketing attribution.
- Publishers:Content platforms monetizing audience attention through programmatic messaging inventory.
Retailers anchor current revenue concentration. Agencies are gaining share fastest as vendor land-and-expand strategies target service provider intermediation.
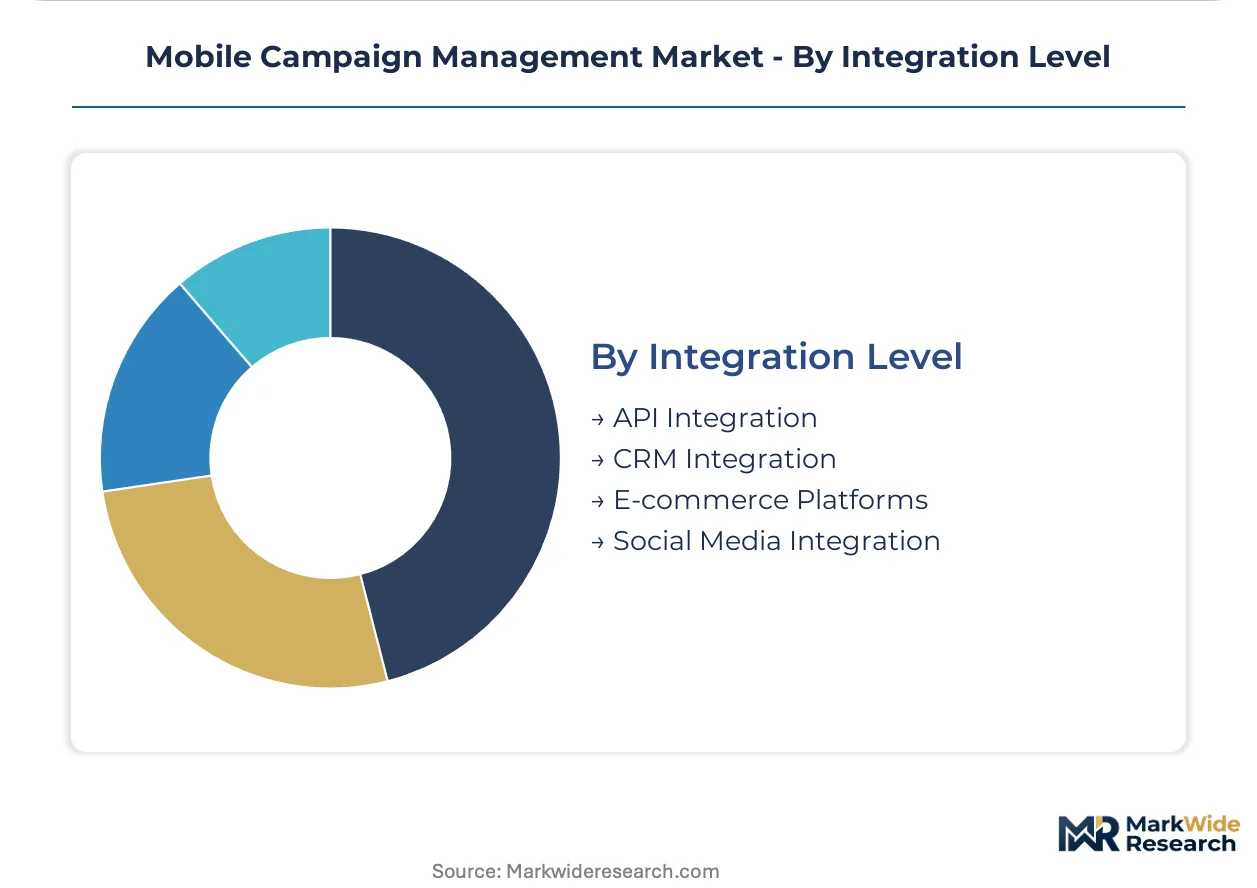
Integration Level:
Supply concentration among legacy data repositories forces vendors to accommodate heterogeneous client system architectures rather than mandating greenfield replacement.
- CRM Integration:Bidirectional data synchronization with customer record systems to anchor personalization on transaction history and service interactions. Salesforce Marketing Cloud leverages this integration pattern as its core competitive moat. Enterprise retention of on-premise databases slows API-driven interoperability, creating implementation friction that extends sales cycles.
- API Integration:Open protocol connectivity enabling custom data flows between campaign orchestration layers and adjacent martech systems. Mid-tier vendors use this flexibility to challenge incumbents without requiring clients to abandon existing infrastructure investments. The pattern accommodates fragmented best-of-breed architectures common among growth-stage retailers.
- E-commerce Platforms:Native connectors to transaction engines for abandoned cart recovery and purchase-triggered messaging.
- Social Media Integration:Audience synchronization and lookalike modeling with advertising platforms.
CRM Integration holds installed capacity. API Integration is rotating up the share rankings as interoperability demands outpace single-vendor consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade in mobile campaign management software tilts toward import-dependent markets in emerging economies, while the United States and Western Europe remain net exporters of SaaS platforms and cloud infrastructure services. Cross-border data flows increasingly determine competitive positioning as vendors localize hosting to satisfy data residency mandates.
United States
Enterprise retailers and direct-to-consumer brands drive platform procurement, with demand concentrating among digitally native merchants seeking real-time personalization capabilities. The FCC enforces TCPA restrictions that shape opt-in architecture and message frequency caps for SMS-based programs. San Francisco and Seattle anchor vendor headquarters clusters where edge-compute personalization engines are being developed for sub-100-millisecond latency requirements.
Germany
Automotive manufacturers and financial services firms mandate algorithmic impact assessments for customer segmentation models, creating specialized demand for explainable AI features. The KBA and BfDI coordinate oversight of automated decision-making systems alongside EU AI Act implementation timelines. Berlin and Munich host pilot deployments of edge-deployed inference engines that satisfy transparency requirements without sacrificing engagement velocity.
India
Domestic retailers under the PLI scheme for digital infrastructure are consolidating procurement around automation tools to reduce manual campaign operations. TRAI guidelines on commercial communications add compliance layers for vendors serving the expanding digital advertiser base. Bengaluru and Mumbai concentrate vendor development centers and enterprise sales operations targeting mid-market direct-to-consumer brands.
United Kingdom
Agency holding companies and publisher networks demand API-driven interoperability to ingest CRM data from disparate client systems without normalization overhead. The Information Commissioner's Office enforces GDPR-aligned consent frameworks that synchronize subscriber preferences across push, SMS, and mobile web touchpoints. London anchors the European headquarters of several global vendors, with Manchester emerging as a secondary hub for customer success operations.
Brazil
Mid-market retailers prefer event-volume pricing structures that defer fixed costs until scale validates platform investment, reflecting thin working capital cycles among direct-to-consumer brands. ANVISA and the national data protection authority impose sector-specific obligations on health and wellness marketers using automated messaging. São Paulo concentrates both vendor sales operations and the headquarters of domestic e-commerce platforms expanding their in-house campaign management capabilities.
Mobile Campaign Management Market Competitive Landscape
On the supply side, the industry is structured around three distinct tiers: hyperscaler-backed suites with CRM integration depth, real-time streaming specialists with sub-second latency architectures, and emerging-market localization experts with tiered pricing flexibility. Strategic archetypes include data backbone consolidators, edge-compute personalization engine builders, and compliance-first platform modernizers. Competitive moves concentrate on API-driven interoperability investments and geographic expansion through localized hosting partnerships.
Within the real-time streaming tier, Braze exemplifies architecture-first positioning through its sub-second personalization trigger capabilities. Salesforce Marketing Cloud occupies the data backbone consolidation archetype, leveraging CRM integration depth as a competitive moat. CleverTap represents emerging-market localization expertise, with tiered pricing structures designed for smaller retailer budgets in high-growth economies. These three anchors illustrate how technical differentiation and geographic focus stratify competitive positioning across procurement segments.
| Leading Market Players |
|---|
| Braze |
| Salesforce Marketing Cloud |
| Adobe Campaign |
| CleverTap |
| Customer.io |
| Vibes |
| Moburst |
| Attentive |
| Zoomd |
| Others |
Supply & Pricing Matrix
EU AI Act compliance costs are compressing vendor margins while fragmenting product roadmaps across incompatible jurisdictional requirements, forcing pricing stratification between explainability-enabled premium tiers and basic orchestration utilities while supply chains reorganize around localized hosting partnerships for data residency mandates.
Pricing Analysis
Mid-market direct-to-consumer brands anchor SaaS event-volume pricing structures that defer fixed costs until message throughput validates platform investment. Three-tier pricing separates enterprise-grade predictive churn engines from standard automation tools and economy-tier basic messaging utilities, with certification against ISO 27001 and GDPR-compliant consent frameworks commanding substantial premiums. Pricing pressure stems from hyperscaler infrastructure cost volatility exposing vendors to margin compression on elastic scaling contracts. Indian and Brazilian retailers exhibit highest price sensitivity due to thin working capital cycles, while German automotive and financial services buyers prioritize algorithmic transparency over cost optimization.
Supply Chain Analysis
AWS, Google Cloud, and Microsoft Azure concentrate hyperscaler capacity for campaign orchestration platforms, with secondary hosting partnerships in Germany, India, and Singapore satisfying data residency requirements. Core infrastructure draws from semiconductor fabrication in Taiwan and South Korea for edge-compute inference engines, while telecommunications hardware for SMS gateway integration sources from Chinese and Finnish equipment manufacturers. Single-source vulnerability concentrates in hyperscaler pricing power over mid-tier vendors locked into usage-based billing contracts. Distribution runs through direct enterprise sales teams in North America and Europe, with channel partnerships and localized reseller networks penetrating mid-market segments in India, Brazil, and Indonesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's algorithmic accountability mandates are disrupting competitive positioning by forcing fundamental platform reconstructions, creating asymmetric opportunities for vendors with pre-built explainability architectures.
For Market Incumbents: Entrench CRM data backbone advantages by deepening API interoperability with legacy enterprise databases while accelerating edge-compute personalization engine deployments to satisfy sub-100-millisecond latency requirements without sacrificing EU AI Act compliance. Counter emerging-market localization specialists through tiered pricing structures that match event-volume flexibility. Prioritize ISO 27001 certification investments to compress enterprise procurement timelines currently extending sales cycles by quarters. For New Entrants and Emerging Players: Mid-market retailers in Indonesia lacking localized tiered pricing options represent the most penetrable entry point, with underpenetrated automation tool demand among mobile-first merchant bases offering immediate revenue traction. Brazilian direct-to-consumer brands operating on thin working capital cycles present secondary white-space for usage-based SaaS contracting. Pursue API-first go-to-market positioning that accommodates fragmented best-of-breed martech architectures without demanding client infrastructure replacement. For Investors and Strategic Acquirers: Real-time streaming architecture specialists with sub-second personalization capabilities and pre-built EU AI Act compliance modules constitute the highest-conviction acquisition archetype for long-term viability across the 5-10 year window. Monitor TRAI guideline enforcement intensity in India and corresponding vendor localization investments as early signals of geographic share capture. Track edge-compute inference engine pilot deployments in Germany and France as indicators of technical differentiation sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-driven interoperability with Salesforce and Adobe ecosystems anchors enterprise retention against point solution fragmentation. |
| Geographic Expansion | Localized hosting partnerships in Mumbai and São Paulo satisfy TRAI and ANVISA data residency mandates for mid-market penetration. |
| Acquisition of Specialist Firm | Edge-compute personalization engine builders in Berlin and Munich address EU AI Act explainability requirements without latency sacrifice. |
| Product Launch | Predictive churn modeling pipelines integrating transaction history with engagement telemetry differentiate analytics platform offerings. |
| Strategic Partnership | SMS gateway modernization alliances with telecommunications infrastructure vendors resolve legacy protocol friction in unified orchestration. |
Research Methodology
A standing panel of mobile marketing platform CTOs, enterprise IT procurement officers, CRM integration specialists, and data privacy compliance leads provided ongoing calibration across the study period. Primary interview insights combined with secondary validation from SEC filings of publicly traded martech vendors, TRAI commercial communications reports, EU AI Act implementation guidance documents, and hyperscaler capex disclosures. Bottom-up triangulation across vendor revenue disclosures and top-down cross-checks against enterprise software spending patterns anchored market size estimates.
Scenario-bracketing framed analytical approaches across the projection horizon, with sensitivity testing against regulatory implementation delays and infrastructure cost volatility. Segmentation dimensions modeled include deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs derived from logistic diffusion curves fitted to historical enterprise software procurement patterns, with inputs from PLI scheme disbursement timelines in India and EU AI Act enforcement phase-ins.
Practitioners should monitor GDPR consent-framework fragmentation and hyperscaler pricing announcement cadence for early signals requiring forecast revision. Quarterly review of EU AI Act algorithmic impact assessment mandate enforcement and Indian PLI scheme beneficiary lists is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Cultivation Management Software Market
Digital Solutions
Europe Digital Marketing Software Market
Digital Solutions
Smart and Connected Offices Market
Digital Solutions
Enterprise Content Management (ECM) Market
Digital Solutions
Physical-Digital Integration Market
Digital Solutions
Industrial Operational Intelligence Solution Market
Digital Solutions
Virtual Closet Market
Digital Solutions
Social Networking App Market
Digital Solutions
Component (Document) Content Management System Market
Digital Solutions
Asia-Pacific Data Monetization Market
Digital Solutions
Global Sharing Economy Market
Digital Solutions
Social Employee Recognition Systems Market
Digital Solutions
Middle East and Africa Digital Signage Market
Digital Solutions
Intelligent Virtual Store Design Solution Market
Digital Solutions
India Engineering Research and Development (ER&D) Services Market
Digital Solutions
Enterprise Mobility Market