
 Advanced Drill Data Management Solutions Market | 2026-2036
Advanced Drill Data Management Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Drill Data Management Solutions Market Outlook
The EU Green Deal is repositioning procurement priorities across European drilling contractors, forcing investment in emissions-linked data capture and verification tools. Schlumberger leverages its digital subsurface platform to anchor cloud-based drilling optimization contracts with North Sea operators. Halliburton competes through integrated well construction workflows that combine real-time telemetry with predictive analytics. Baker Hughes differentiates via turbine-powered drilling systems that feed continuous performance data into proprietary data lakes.
Advanced drill data management solutions encompass software platforms, edge computing architectures, and communication infrastructure that aggregate, process, and visualize real-time drilling parameters including weight on bit, torque, standpipe pressure, and gamma ray measurements. These systems enable remote decision-making, automated well control responses, and post-well forensic analysis to improve drilling economics and safety outcomes. Cloud-based deployment leads in new installations among supermajors seeking centralized reservoir-to-rig data integration, while IoT-enabled technology represents the fastest-expanding category as sensor miniaturization and 5G field networks mature. Workflow automation commands premium pricing where labor scarcity drives demand for autonomous tripping and connection procedures.
The EPA enforces methane monitoring requirements under the Inflation Reduction Act that mandate granular emissions reporting from drilling operations, compelling operators to upgrade data infrastructure. BSEE oversees offshore safety case regimes that require documented real-time kick detection and well control verification, shaping product certification standards. OSHA drilling safety directives further specify logging and retention protocols for operational parameters. Stakeholders must weigh the capital intensity of hybrid cloud-field architectures against the operational risk of fragmented legacy systems that lack interoperability with emerging regulatory dashboards.
Market Dynamics
Cloud-native drilling command centers are compressing decision cycles from days to minutes, forcing legacy on-premise data historians into rapid obsolescence across shale and offshore basins alike.
Growth Catalysts
- EPA methane monitoring mandates:The Inflation Reduction Act's granular emissions reporting requirements compel operators to deploy continuous sensor networks and automated compliance dashboards across drilling fleets.
- Edge computing architectures:Real-time wellbore stability algorithms processed at the rig site eliminate latency from satellite uplinks, enabling autonomous kick detection responses within seconds.
- Permian Basin operator consolidation:Supermajors operating multi-rig programs demand unified data lakes that aggregate telemetry from diverse service providers into single-pane visualization.
Market Restraints
- Proprietary data formats:Schlumberger, Halliburton, and Baker Hughes lock drilling parameters into incompatible silos, forcing operators into expensive middleware development or single-vendor dependency.
- High-grade sensor supply concentration:MEMS-based downhole pressure transducers rely on semiconductor fabrication concentrated in Taiwan and South Korea, exposing lead times to geopolitical friction.
- Subsea fiber latency:North Sea and Gulf of Mexico deepwater rigs face inherent bandwidth constraints that throttle real-time analytics deployment despite satellite backup redundancy.
Strategic Opportunities
- EU Green Deal verification protocols:European drilling contractors must purchase emissions-attested data management packages to satisfy CSRD-linked sustainability reporting and secure project finance.
- Geothermal drilling crossover:Oilfield data platforms repurpose for high-temperature geothermal wells, opening addressable market among utilities pursuing baseload renewable generation.
- 5G private networks:Mid-band spectrum deployments at West Texas and North Dakota well pads enable sensor densities and refresh rates impossible under legacy 4G or Wi-Fi mesh topologies.
Industry Challenges
- Petrotechnical talent scarcity:Drilling engineers fluent in both subsurface geomechanics and Python-based machine learning pipelines command premium compensation that strains operator budgets.
- Hybrid cloud integration complexity:Stitched-together architectures spanning AWS GovCloud, Azure Energy, and field-hardened edge nodes create cybersecurity attack surfaces that BSEE safety case regimes scrutinize intensely.
- Legacy SCADA migration timelines:Decades-old distributed control systems in mature basins resist API-standard connectivity, delaying real-time analytics ROI by 18-24 months per rig retrofit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Drill Data Management Solutions Market |
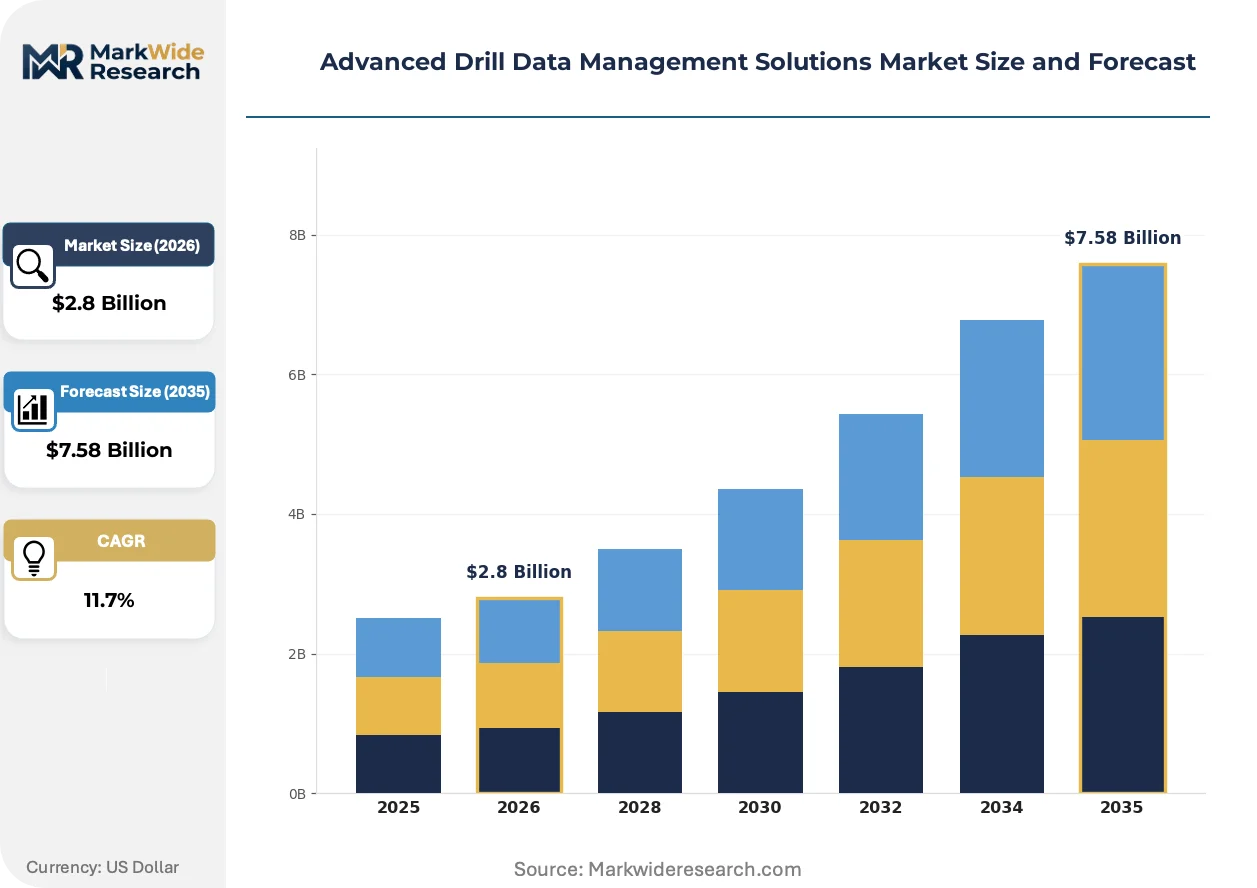
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Data Analytics, Data Visualization, Workflow Automation, System Integration Technology: Cloud-Based, On-Premise, Hybrid, IoT-Enabled End User: Mining Companies, Oil & Gas Operators, Environmental Agencies, Drilling Contractors Deployment: Field Operations, Centralized Data Hubs, Remote Monitoring, Consulting Services |
| Companies Covered | Honeywell International Inc., Pason Systems Inc., Schlumberger, Weatherford International Inc., Infosys Limited, Halliburton Company, National-Oilwell Varco, Inc., Siemens AG, Baker Hughes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Drill Data Management Solutions Market Strategic Shifts
Artificial intelligence is penetrating drilling operations through three distinct vectors: autonomous downhole responses, emissions-linked compliance automation, and reconstituted procurement relationships between operators and digital service vendors.
Digital twin technology is automating well construction planning by simulating thousands of bit-rock interaction scenarios before spudding. Supermajors in the Permian Basin deploy these virtual environments to optimize rate of penetration trajectories and reduce non-productive time from stuck pipe incidents. The technology is automating geosteering decisions that previously required continuous human intervention from remote operations centers.
The EU Green Deal's methane emissions monitoring mandates are forcing North Sea operators to retrofit legacy rigs with IoT-enabled sensor networks and blockchain-verified data logging. These requirements compress equipment procurement cycles and elevate data governance to board-level oversight. Offshore contractors now specify automated compliance reporting as a contractual deliverable separate from drilling performance metrics.
Integrated service contracts are displacing discrete software licensing as the dominant commercial model. Shale operators in the United States negotiate outcome-based arrangements where data platform vendors share drilling efficiency gains rather than charging per-seat subscriptions. This restructuring concentrates vendor risk and accelerates technology refresh cycles beyond traditional five-year enterprise software horizons.
Advanced Drill Data Management Solutions Market Segmentation
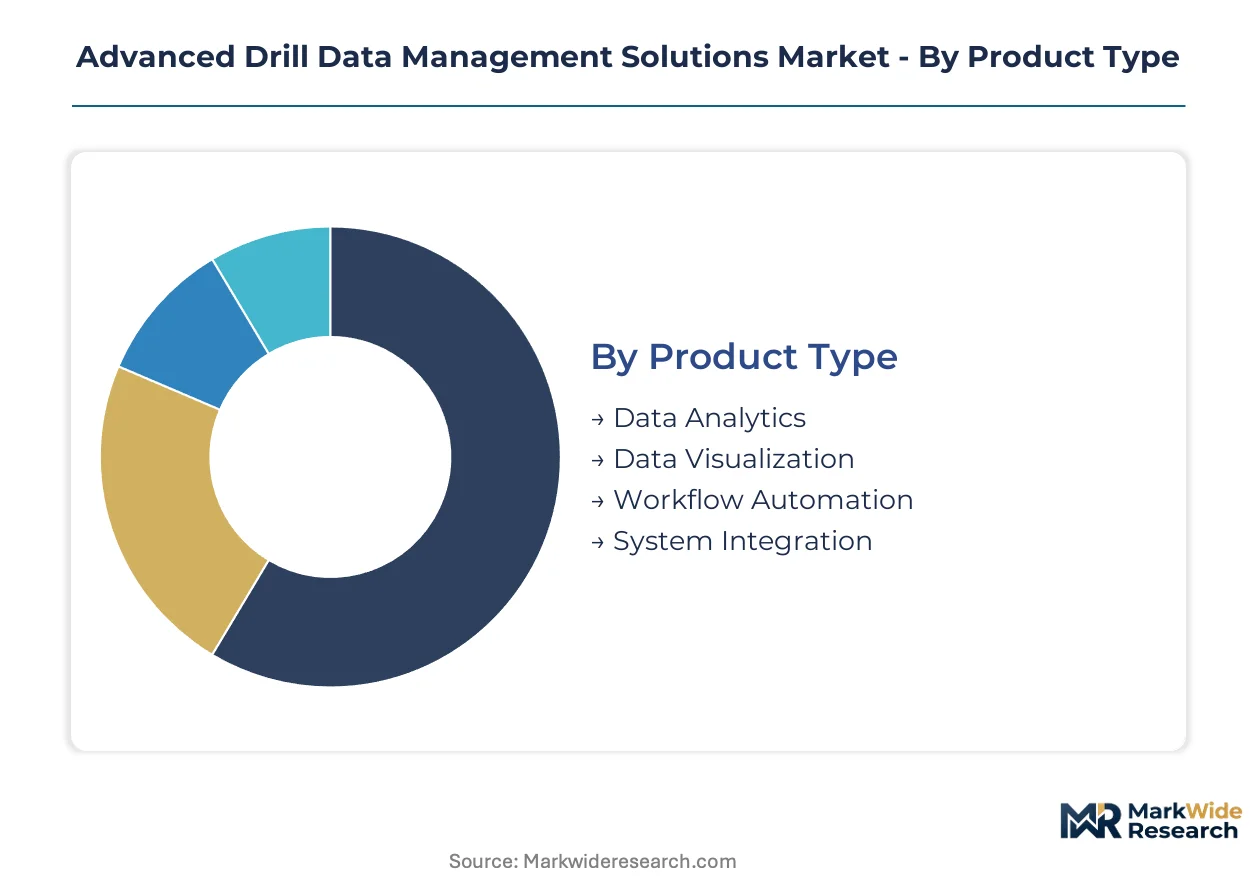
Drill data management procurement fractures across four distinct axes, each commanding separate vendor specializations and integration protocols. Product functionality, infrastructure topology, buyer organizational type, and operational deployment mode create overlapping segment boundaries that complicate platform standardization across drilling fleets.
Product Type:
Supply concentration in data analytics software tilts toward established energy technology vendors with proprietary algorithm libraries.
- Data Analytics:Machine learning pipelines process real-time drilling parameters including weight on bit, torque, and gamma ray measurements to predict stuck pipe incidents. Permian Basin supermajors deploy these platforms to optimize rate of penetration across multi-rig programs, though proprietary data formats from Schlumberger, Halliburton, and Baker Hughes force expensive middleware development.
- Workflow Automation:Autonomous tripping and connection procedures reduce labor dependency where petrotechnical talent scarcity strains operator budgets. North Sea drilling contractors specify automated compliance reporting as a contractual deliverable separate from performance metrics under EU Green Deal mandates.
- Data Visualization:Single-pane dashboards aggregate telemetry from diverse service providers into unified command centers.
- System Integration:API-standard connectivity bridges legacy SCADA systems with cloud-native architectures, though retrofit timelines delay ROI by 18-24 months per rig.
Today's leader: Data Analytics. Tomorrow's challenger: Workflow Automation.
Technology:
Cost tier stratification separates premium cloud-native deployments from economy on-premise installations in mature basins.
- Cloud-Based:Centralized reservoir-to-rig data integration enables remote decision-making across dispersed drilling assets. Supermajors operating West Texas shale programs favor these architectures for unified data lakes, though hybrid cloud-field configurations create cybersecurity attack surfaces that BSEE safety case regimes scrutinize intensely.
- IoT-Enabled:Miniaturized sensors and 5G field networks deliver refresh rates impossible under legacy 4G or Wi-Fi mesh topologies. EPA methane monitoring mandates under the Inflation Reduction Act compel continuous sensor network deployment across drilling fleets.
- Hybrid:Split processing architectures balance latency-sensitive wellbore stability algorithms at the rig site with archival analytics in cloud environments.
- On-Premise:Legacy data historians resist obsolescence in bandwidth-constrained offshore environments where subsea fiber latency throttles real-time deployment.
Cloud-Based commands current procurement volume. IoT-Enabled tracks steepest expansion trajectory as emissions-linked verification requirements harden.
End User:
Application urgency varies sharply across buyer types, with regulatory compliance driving environmental agency procurement while efficiency metrics dominate oil and gas operator selection.
- Oil & Gas Operators:Shale producers and offshore supermajors negotiate outcome-based contracts where vendors share drilling efficiency gains rather than charging per-seat subscriptions. These arrangements concentrate vendor risk and accelerate technology refresh cycles.
- Drilling Contractors:Equipment procurement cycles compress as EU Green Deal methane mandates elevate data governance to board-level oversight.
- Mining Companies:Geothermal drilling crossover applications repurpose oilfield platforms for high-temperature well construction.
- Environmental Agencies:Automated compliance dashboards satisfy granular emissions reporting requirements with blockchain-verified data logging.
Oil & Gas Operators anchor current demand. Environmental Agencies represent the fastest-climbing segment as verification protocols proliferate.
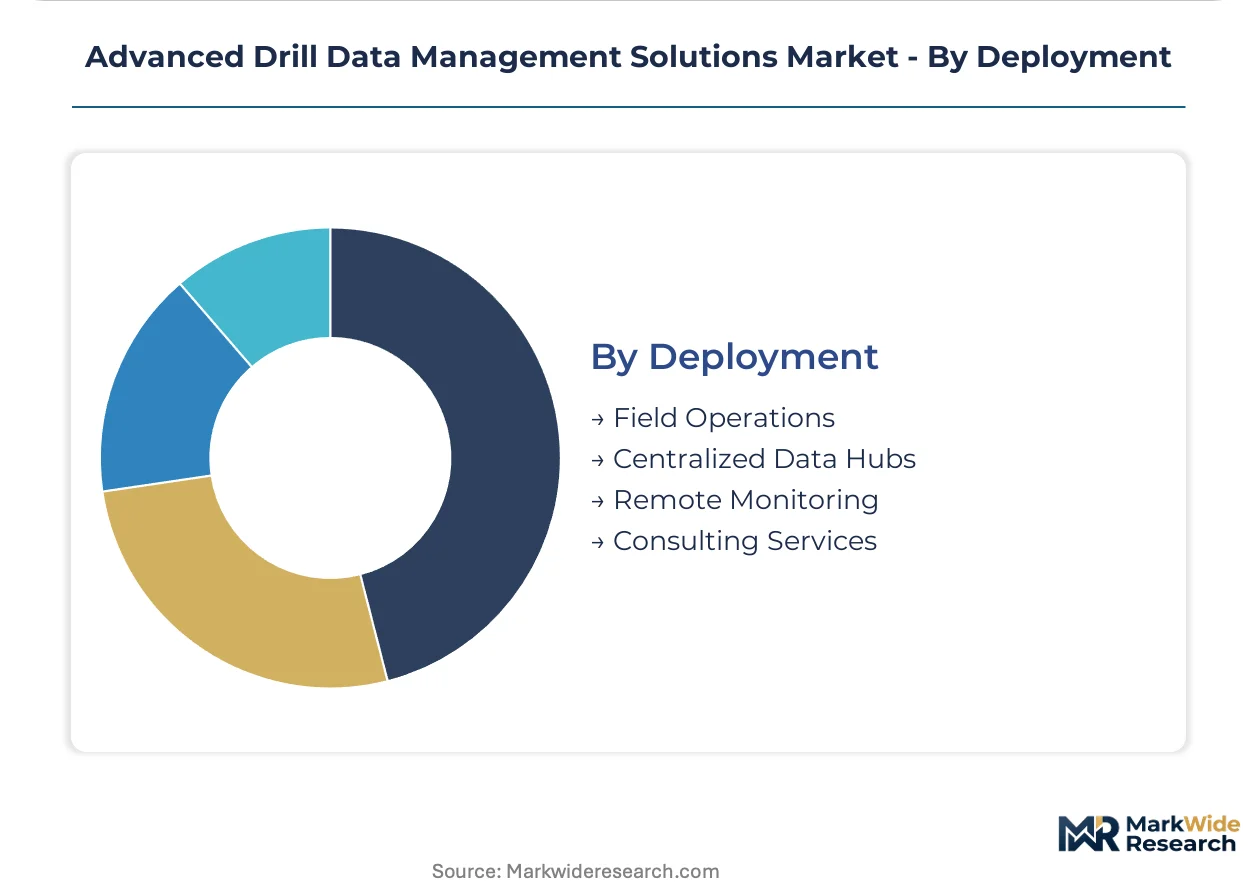
Deployment:
Customer type and operational maturity dictate deployment mode selection, with field-hardened operations commanding premium integration services.
- Field Operations:Edge computing architectures process kick detection algorithms within seconds, eliminating satellite uplink latency. These deployments require field-hardened hardware rated for hazardous area classifications.
- Centralized Data Hubs:Cloud-based command centers compress decision cycles from days to minutes across multi-basin portfolios.
- Remote Monitoring:Remote operations centers automate geosteering decisions previously requiring continuous human intervention.
- Consulting Services:Integration specialists bridge API connectivity gaps between decades-old distributed control systems and modern analytics platforms.
Field Operations dominates capital allocation. Centralized Data Hubs gain share as operator consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Real-time drilling telemetry first achieved commercial scale in North Sea offshore operations during the 1990s, establishing the technical foundations that now propagate across shale basins and geothermal frontiers worldwide. The Permian Basin subsequently emerged as the dominant proving ground for cloud-native data architectures. Today's procurement patterns reflect this bifurcated heritage: mature offshore regimes upgrade legacy infrastructure while unconventional onshore operators build greenfield digital stacks.
United States
EPA methane monitoring mandates under the Inflation Reduction Act compel shale operators to deploy continuous sensor networks across multi-rig programs. Supermajors operating in the Permian Basin negotiate outcome-based contracts where vendors share drilling efficiency gains. West Texas well pads now host 5G private networks enabling sensor densities impossible under legacy 4G topologies.
Norway
North Sea drilling contractors retrofit legacy rigs with IoT-enabled sensor networks to satisfy EU Green Deal verification protocols. The country's petroleum regulator enforces safety case regimes requiring documented real-time kick detection and well control verification. Stavanger anchors Europe's largest concentration of digital drilling command centers serving offshore supermajors.
United Kingdom
North Sea operators face compressed equipment procurement cycles as CSRD-linked sustainability reporting elevates data governance to board-level oversight. The Oil and Gas Authority mandates granular emissions reporting that forces investment in blockchain-verified data logging infrastructure. Aberdeen's remote operations centers automate geosteering decisions previously requiring continuous human intervention.
Saudi Arabia
Aramco's drilling programs drive demand for unified data lakes aggregating telemetry from diverse service providers into single-pane visualization. The kingdom's industrial development initiatives prioritize captive production of high-grade downhole sensors to reduce import dependency. Dhahran's technology clusters host regional headquarters for major energy technology vendors.
China
Shale gas development in Sichuan-Chongqing basin accelerates adoption of edge computing architectures processing wellbore stability algorithms at the rig site. The Ministry of Ecology and Environment enforces dual carbon goals that tighten methane emissions monitoring requirements across drilling fleets. Chengdu anchors domestic manufacturing of MEMS-based pressure transducers for downhole deployment.
Advanced Drill Data Management Solutions Market Competitive Environment
Capital-heavy integrated service providers compete with asset-light software specialists for drilling data management contracts across shale and offshore basins. The vendor base stratifies into three tiers: supermajors anchoring cloud-native platform ecosystems, mid-cap specialists delivering workflow automation, and regional integrators bridging legacy SCADA with modern analytics. Consolidation pressure intensifies as outcome-based commercial models concentrate risk onto fewer platform vendors. Strategic moves center on API standardization initiatives and hybrid cloud-field architecture certifications satisfying BSEE safety case regimes.
Within the integrated service tier, Schlumberger, Halliburton, and Baker Hughes exemplify contrasting approaches to data platform architecture. Schlumberger occupies a position emphasizing proprietary subsurface digital twins. Halliburton represents the integrated well construction workflow archetype combining telemetry with predictive modules. Baker Hughes anchors the turbine-powered drilling systems segment feeding continuous performance data into proprietary data lakes. Among technology conglomerates, Honeywell International Inc. and Siemens AG sit within the industrial automation tier repurposing process control expertise for hazardous area drilling environments.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Pason Systems Inc. |
| Schlumberger |
| Weatherford International Inc. |
| Infosys Limited |
| Halliburton Company |
| National-Oilwell Varco, Inc. |
| Siemens AG |
| Baker Hughes |
| Others |
Value Chain & Pricing Dynamics
Captive sensor production in Taiwan and South Korea anchors both supply security and pricing power for MEMS-based downhole pressure transducers, forcing operators to accept premium pricing or face extended lead times from concentrated semiconductor fabrication.
Pricing Analysis
Outcome-based commercial models dominate procurement, where vendors share drilling efficiency gains rather than charging per-seat subscriptions. Price differentiation hinges on certification grade for BSEE safety case compliance and the depth of after-sales integration services bundled with platform deployment. Cost compression in standard cloud-native tiers is intensifying because supermajors consolidate vendor relationships across multi-rig programs. Shale operators in the Permian Basin exhibit highest price sensitivity, while North Sea offshore contractors prioritize compliance-grade specifications regardless of cost.
Supply Chain Analysis
Dual-sourcing requirements from BSEE and EPA-mandated operators force qualification of multiple MEMS foundries across Taiwan, South Korea, and Japan for critical downhole pressure transducers. Component dependencies center on semiconductor-grade silicon wafers, high-temperature packaging ceramics, and subsea fiber-optic cable assemblies. Single-source vulnerability concentrates in Taiwan-based MEMS fabrication exposed to geopolitical friction. Distribution runs through integrated service providers who bundle hardware procurement with software platform deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as EU Green Deal methane verification protocols shift procurement toward emissions-attested data management packages with blockchain-verified logging.
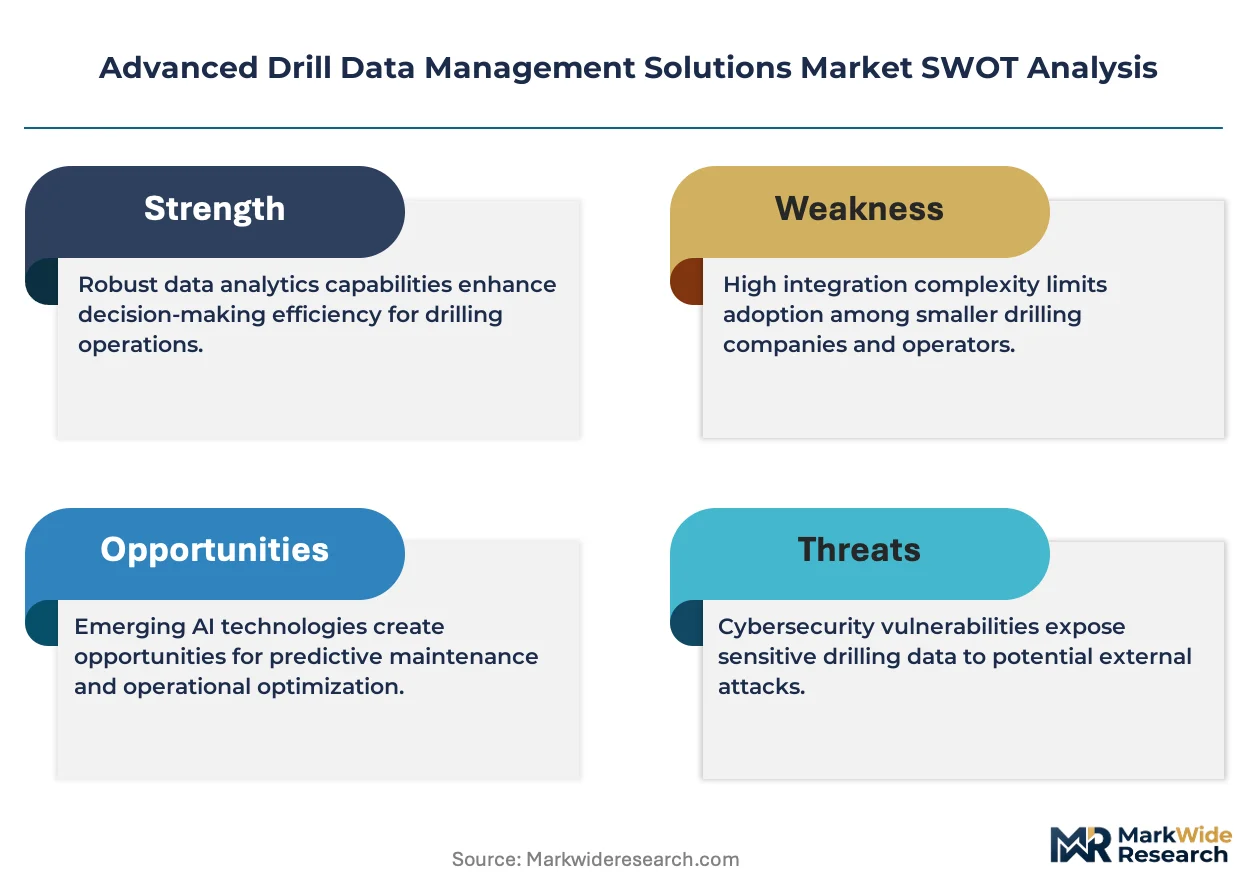
For Market Incumbents: Anchor cloud-native platform ecosystems through API standardization initiatives that neutralize proprietary data format lock-in from Schlumberger, Halliburton, and Baker Hughes. Pursue backward integration into MEMS sensor fabrication to secure supply continuity against Taiwan concentration risk. Defend position by certifying hybrid cloud-field architectures for BSEE safety case regimes ahead of regulatory deadlines. For New Entrants and Emerging Players: Regional integrators represent the most penetrable channel partner type for bridging legacy SCADA with modern analytics in mature North Sea and Gulf of Mexico basins. Target workflow automation for autonomous tripping and connection procedures where petrotechnical talent scarcity strains operator budgets. Pursue geothermal drilling crossover applications as utilities repurpose oilfield platforms for high-temperature well construction. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap workflow automation specialists because outcome-based contracting concentrates vendor risk onto fewer platform providers. Long-term viability favors vendors with proven hybrid cloud-field deployments across the analysis window. Acquisition targets should demonstrate EPA compliance dashboard certification. The signal to watch is 5G private network deployment velocity at West Texas well pads as inflection indicator for IoT-enabled sensor density expansion.| Strategic Initiative | Industry Significance |
|---|---|
| API Standardization Program | Neutralizes proprietary data silos from Schlumberger, Halliburton, and Baker Hughes to enable multi-vendor integration. |
| Backward Integration into MEMS Fabrication | Secures captive supply of downhole pressure transducers against Taiwan semiconductor concentration risk. |
| Hybrid Cloud-Field Certification | Satisfies BSEE safety case regimes for cybersecurity scrutiny of stitched AWS GovCloud and Azure Energy architectures. |
| Geothermal Platform Repurposing | Opens addressable market among utilities pursuing baseload renewable generation with existing oilfield data infrastructure. |
| 5G Private Network Deployment | Enables sensor densities and refresh rates impossible under legacy 4G topologies at West Texas well pads. |
Study Parameters
Coverage spans the United States, Norway, United Kingdom, Saudi Arabia, and China, with primary inputs from each market through structured interviews with drilling engineers, remote operations center managers, petroleum regulators, EPC contractors, and digital platform procurement officers. Secondary validation draws from EPA enforcement actions, BSEE safety case filings, EU Green Deal implementation directives, Aramco technology disclosure documents, and Ministry of Ecology and Environment emissions standards. Bottom-up rig-level deployment estimates triangulate against top-down vendor revenue attribution.
Rate-of-change decomposition separates volume expansion from value migration across cloud-based, IoT-enabled, hybrid, and on-premise technology segments, with additional modeling by product type, end user archetype, and deployment mode. CAGRs derive from regression against historical rig count trajectories, regulatory mandate implementation timelines, and sensor cost curves. Industry-specific forecast inputs include Permian Basin operator consolidation patterns and EU CSRD-linked sustainability reporting adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MEMS semiconductor supply disruption, 5G spectrum allocation delays, and EPA methane enforcement intensity variation. Deviation in Taiwan geopolitical stability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Asset Tracking and Inventory Management Solutions Market
Digital Solutions
Search Engine Optimization Services Market
Digital Solutions
Global Digital Asset Management Software Market
Digital Solutions
Global Logistics Software Market
Digital Solutions
Data Labeling Solution and Services Market
Digital Solutions
Product Lifecycle Management Consumer Packaged Goods and Retail (PLM Cpandr) Market
Digital Solutions
Cheque Scanner Market
Digital Solutions
UAE Digital Twin Market
Digital Solutions
Kenya ICT Market
Digital Solutions
Predictive Maintenance Software Market
Digital Solutions
Europe Electronic Contract Manufacturing and Design Services Market
Digital Solutions
Product Data Management Market
Digital Solutions
US Supply Chain Management Software Market
Digital Solutions
Interactive Kiosk Market
Digital Solutions
Service Fulfillment Market
Digital Solutions
Change and Configuration Management Market