
 North America 3D Rendering Services Market | 2026-2036
North America 3D Rendering Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America 3D Rendering Services Market Insights
GPU silicon is restructuring economics across 3D rendering services as NVIDIA Corp's proprietary CUDA cores displace CPU-bound workflows in high-resolution production pipelines. Autodesk Inc leverages its Revit-to-Arnold integration to anchor architectural visualization contracts with North American design-build firms. Adobe Inc competes through Substance 3D subscriptions that extend creative cloud lock-in into material authoring and environment rendering. Chaos Software Ltd specializes in V-Ray's dominance across film and automotive visualization, sustaining premium pricing through photorealistic light-simulation accuracy.
3D rendering services encompass the computational generation of two-dimensional images from three-dimensional digital models, typically executed on clusters of GPUs processing ray-traced light paths at resolutions exceeding 4K for client deliverables. These services translate architectural CAD files, product prototypes, and entertainment assets into photorealistic or stylized imagery for marketing, design validation, and pre-visualization purposes. Architectural visualization leads service-type revenue in North America, reflecting sustained commercial real estate development cycles across the United States and Canada. Cloud rendering represents the fastest-expanding technology segment, as elastic compute access reduces capital barriers for mid-size studios in Vancouver and Austin. Real-time rendering gains traction in game development and virtual production, displacing offline batch workflows for iterative creative review.
The Federal Trade Commission enforces truth-in-advertising standards that classify photorealistic architectural renderings as deceptive when indistinguishable from photography without disclosure, shaping liability frameworks for real estate marketing deliverables. Health Canada's radiation-emitting device regulations govern laser-scanning hardware used in reality-capture workflows that feed rendering pipelines, while the Federal Communications Commission's broadband infrastructure programs indirectly expand cloud-rendering accessibility for rural Canadian and US studios. Stakeholders must monitor evolving synthetic-media disclosure mandates and assess whether edge-compute investments or hyperscaler partnerships better align with client latency requirements and data-sovereignty expectations.
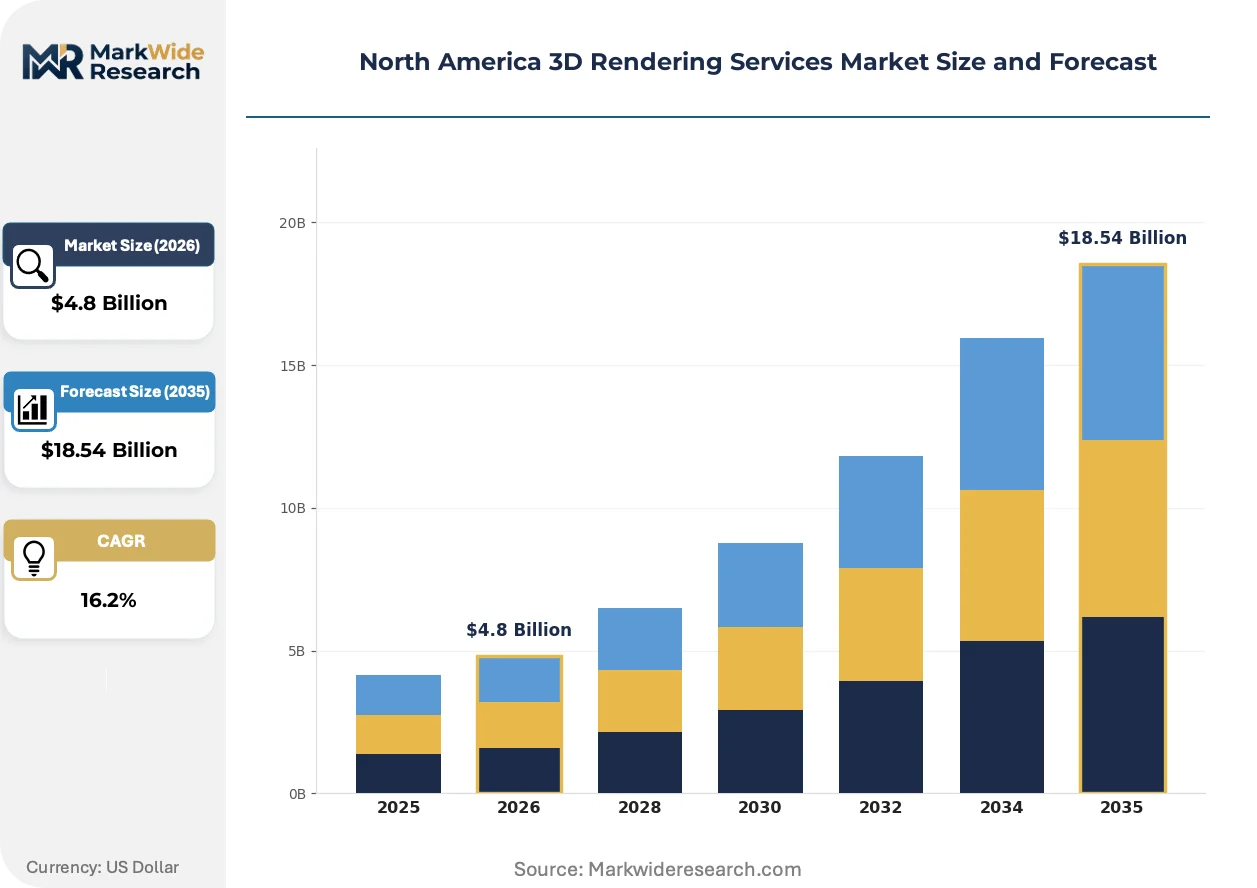
Market Dynamics
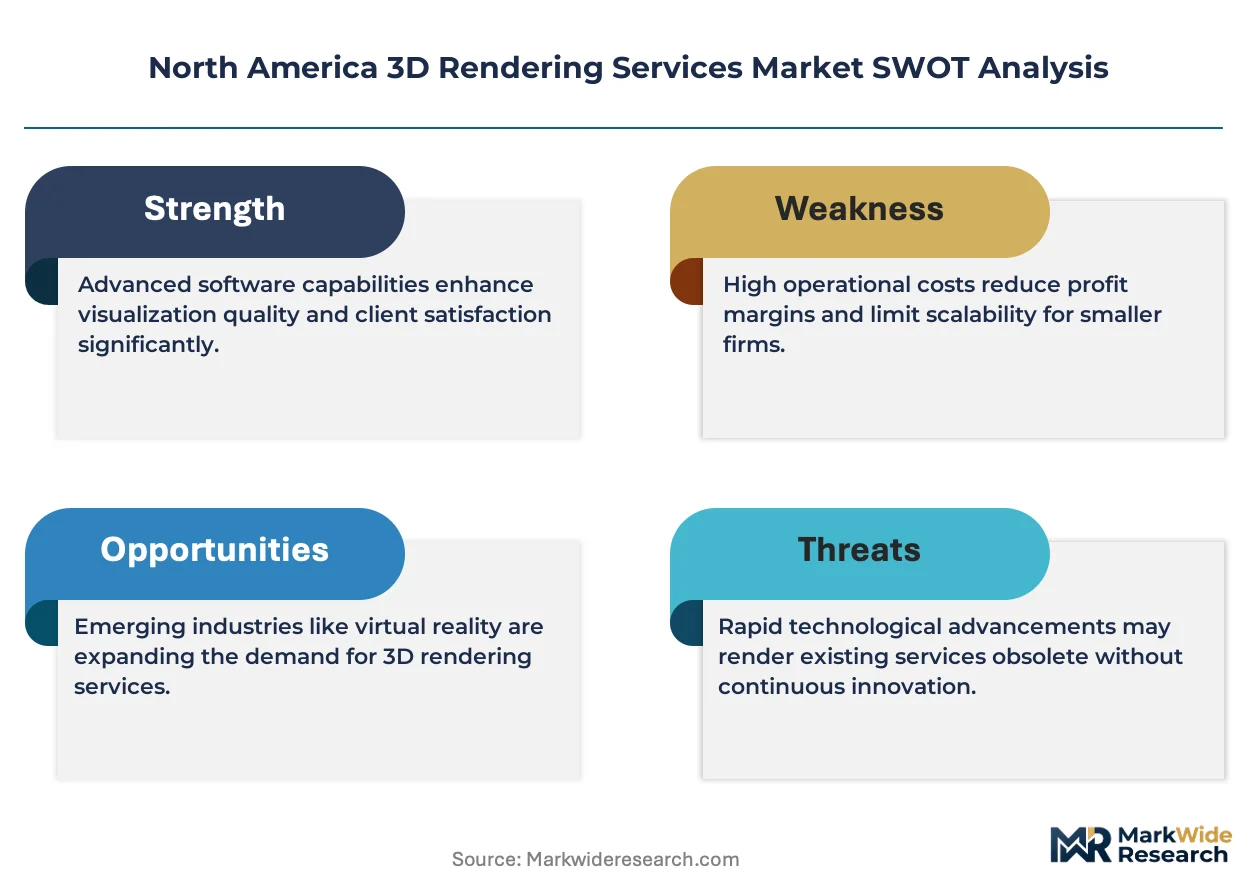
GPU silicon shortages and FTC disclosure mandates are squeezing North American rendering studios into capital-intensive infrastructure bets while compressing turnaround times for photorealistic deliverables.
Growth Catalysts
- FTC truth-in-advertising enforcement:Mandatory disclosure rules for synthetic imagery are creating certified-origin premiums that differentiate compliant studios in US real estate marketing.
- Cloud rendering elasticity:Hyperscaler GPU clusters are eliminating capex barriers for mid-size studios in Vancouver and Austin, expanding addressable production capacity.
- Virtual production pipelines:LED volume stages in Los Angeles and Toronto are consuming real-time rendered environments, displacing physical set construction.
Market Restraints
- NVIDIA CUDA dependency:Proprietary GPU architecture concentration creates single-supplier risk for compute-bound ray-tracing workflows.
- Health Canada laser-scanning compliance:Radiation-emitting device regulations add certification friction to reality-capture hardware procurement for cross-border projects.
- CPU-to-GPU workflow abandonment costs:Legacy render farm investments face accelerated obsolescence as studios migrate to tensor-core pipelines.
Strategic Opportunities
- FCC rural broadband expansion:Infrastructure subsidies are extending cloud-rendering accessibility to underserved US studios beyond coastal metro corridors.
- AI-assisted denoising convergence:Neural network inference on RTX cores is compressing render iteration cycles, enabling fixed-bid pricing models.
- Texas edge-compute investments:Low-latency GPU nodes in Dallas-Fort Worth are capturing virtual production workloads from latency-sensitive entertainment clients.
Industry Challenges
- USD pipeline integration complexity:Universal Scene Description adoption requires retraining technical directors and rebuilding asset management systems.
- Cross-border data sovereignty:Canadian studios serving US clients face jurisdictional friction over render asset storage and transfer compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America 3D Rendering Services Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $18.54 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Architectural Visualization, Animation Services, Virtual Reality, Product Rendering End User: Real Estate, Advertising, Entertainment, Manufacturing Technology: Cloud Rendering, Real-Time Rendering, Ray Tracing, Rasterization Application: Interior Design, Game Development, Marketing, Film Production |
| Companies Covered | Autodesk Inc, Adobe Inc, NVIDIA Corp, Dassault Systemes SE, Chaos Software Ltd, Unity Technologies, Maxon Computer, SideFX, Foundry Visionmongers Limited, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America 3D Rendering Services Market Trends and Innovations
Neural rendering and real-time pipelines are collapsing the traditional boundary between pre-visualization and final-pixel delivery across North American production workflows.
Neural radiance fields (NeRF) are rewriting location scouting economics for architectural visualization studios. California real estate marketers now capture sparse photogrammetry and generate explorable 3D environments without full LiDAR surveys. The technology is compressing site documentation costs while expanding revision flexibility for developers.
The FTC's updated advertising disclosure framework is reclassifying photorealistic architectural renderings as regulated synthetic media. Studios must now maintain provenance documentation and disclosure workflows for marketing deliverables. California and New York real estate marketing agencies are building compliance infrastructure ahead of anticipated state-level amplification.
Consumption patterns among enterprise buyers are fragmenting across subscription, per-frame, and dedicated-instance models. Mid-market architectural firms in Chicago and Denver are abandoning perpetual licenses for elastic cloud rendering access. The shift is visible most acutely in commercial real estate marketing, where project-based budgeting favors operational expenditure structures over capital deployment.
North America 3D Rendering Services Market Segmentation
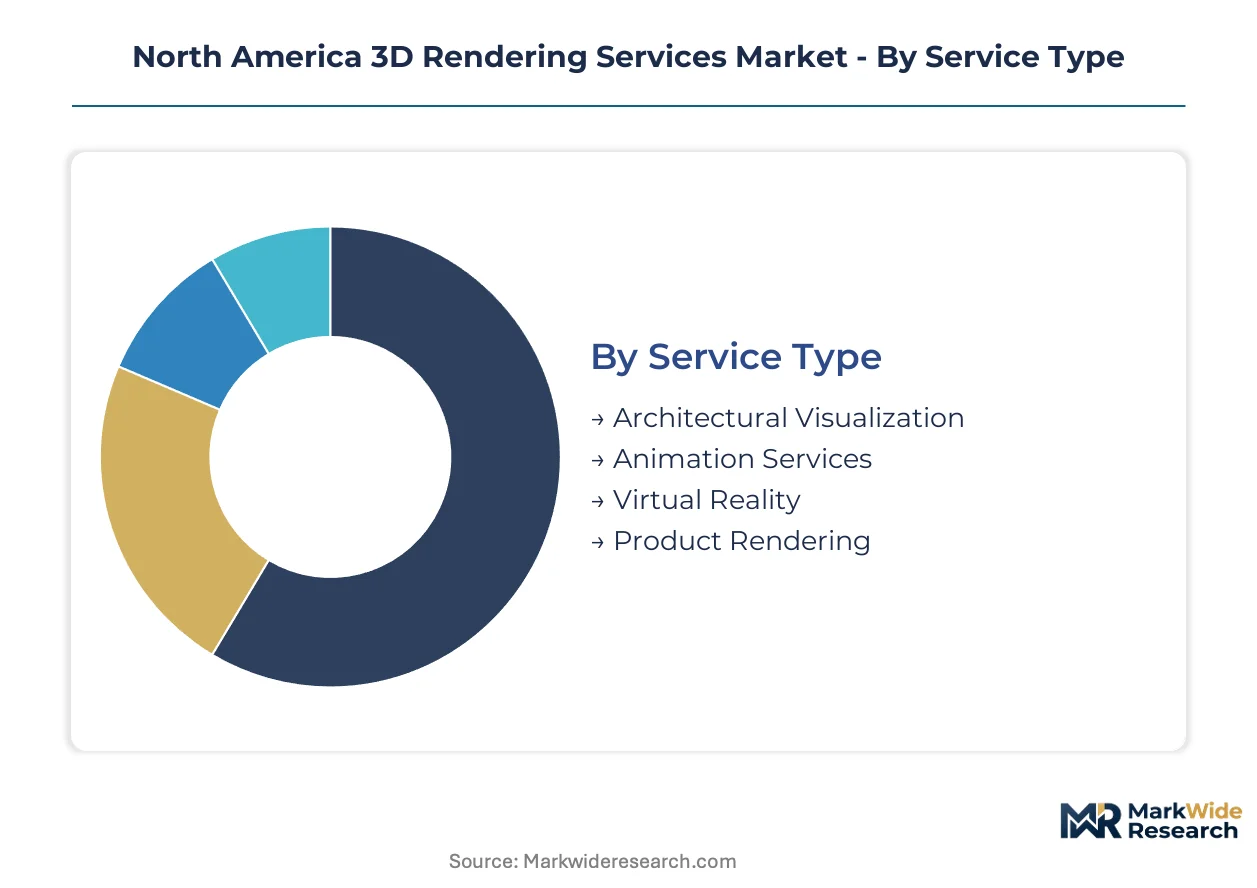
Service providers in North America price and deliver 3D rendering through distinct capability bundles that match client technical requirements and project velocity needs. Segmentation reveals where GPU infrastructure investments concentrate and which buyer workflows command premium rates.
Service Type:
Buyers differentiate primarily by deliverable fidelity requirements and revision cycle tolerance, separating photorealistic still imagery from immersive interactive experiences.
- Architectural Visualization:Static and walkthrough imagery derived from CAD files dominates commercial real estate marketing in California and New York. FTC disclosure mandates for synthetic imagery are forcing studios to maintain provenance documentation and certified-origin workflows.
- Animation Services:Motion sequences for product launches and architectural flythroughs require render farm orchestration across hundreds of GPU-hours. Toronto visual effects clusters leverage elastic cloud capacity to handle episodic television workloads without permanent infrastructure.
- Virtual Reality:Stereoscopic 360-degree environments and interactive spatial experiences for property tours and training simulations.
- Product Rendering:Isolated product visualization for e-commerce catalogs and automotive configurators, optimized for web and mobile delivery.
Architectural visualization leads volumes today; virtual reality is gaining share fastest.
End User:
Client procurement sophistication varies sharply across sectors, with entertainment buyers demanding real-time iteration while manufacturing prioritizes cost-per-image efficiency.
- Real Estate:Developers and brokerages commission pre-construction marketing imagery across California's multifamily housing corridor and Toronto's condominium market. FTC truth-in-advertising enforcement now classifies undisclosed photorealistic renderings as deceptive trade practices.
- Entertainment:Los Angeles and Vancouver production facilities consume real-time rendered environments for LED volume stages, displacing physical set construction.
- Advertising:Campaign imagery for consumer brands and automotive launches, balancing speed-to-market against creative iteration demands.
- Manufacturing:Design validation and technical documentation for industrial equipment and consumer products prior to physical prototyping.
Real estate anchors current revenue; entertainment production shows the steepest expansion trajectory.
Technology:
Infrastructure deployment choices separate capital-intensive studio ownership from operational expenditure models favoring elasticity.
- Cloud Rendering:Hyperscaler GPU clusters eliminate capital barriers for mid-size studios in Austin and Vancouver, enabling per-project scaling without permanent farm investment.
- Real-Time Rendering:Game engine pipelines using Unreal Engine and Unity deliver iterative environments for virtual production and architectural review.
- Ray Tracing:Physically accurate light simulation for premium film and automotive visualization, sustaining premium pricing through photorealistic accuracy.
- Rasterization:Traditional polygon-based rendering for mobile and web-optimized deliverables where computational efficiency outweighs fidelity.
Cloud rendering dominates new capacity deployment; real-time rendering is climbing the fastest among production pipelines.
Application:
Workflow integration depth determines whether rendering operates as a discrete service or embedded production stage.
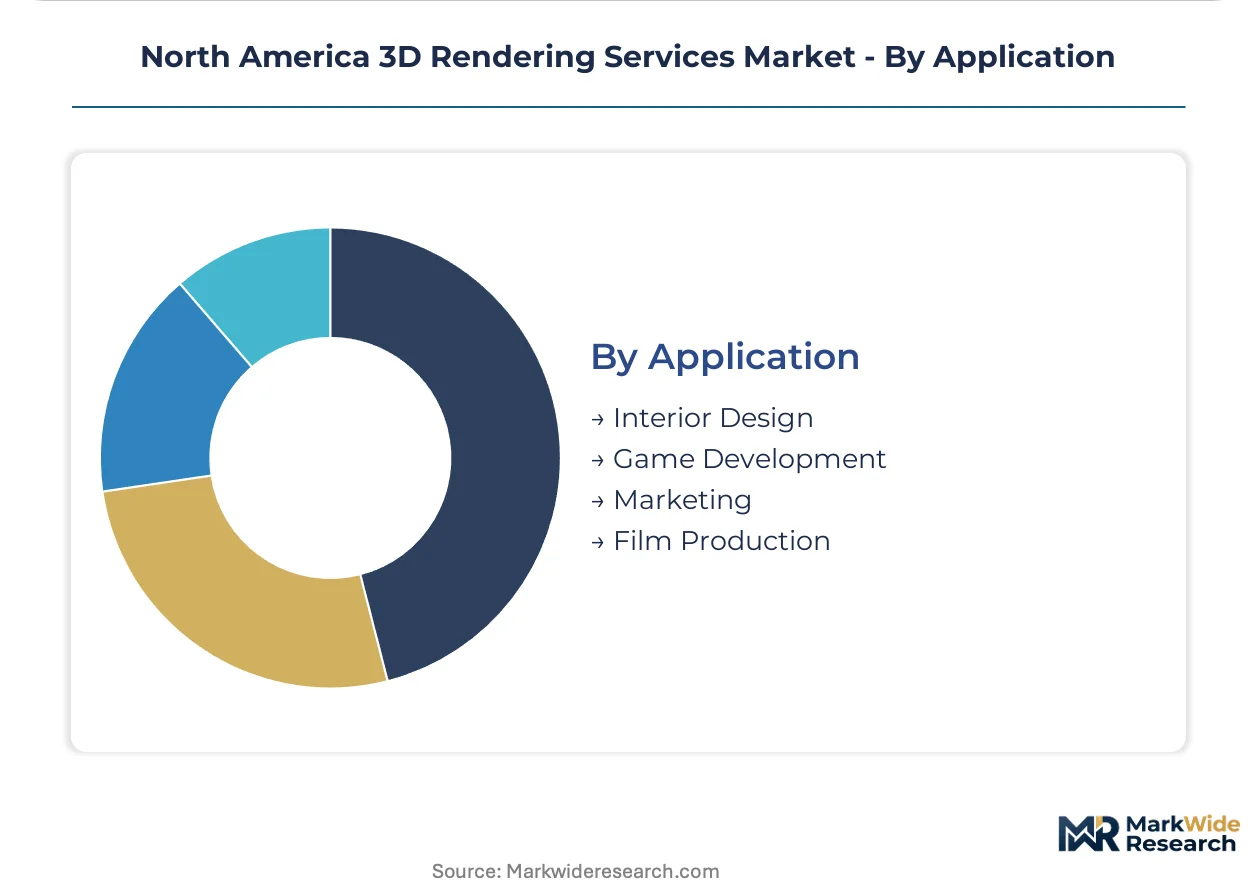
- Marketing:Final-pixel imagery for print, digital, and out-of-home campaigns across real estate and consumer brands.
- Film Production:Pre-visualization, virtual production environments, and final compositing elements for theatrical and streaming content.
- Interior Design:Spatial visualization for residential and commercial fit-out decisions, accelerating client approval cycles.
- Game Development:Environment and character asset creation for interactive entertainment, bridging offline cinematic quality with runtime performance constraints.
Marketing applications command the largest current spend; film production integration is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's entertainment production corridor generates substantial demand for real-time rendered environments across LED volume stages and virtual production workflows. Toronto's visual effects cluster anchors Canadian capacity for episodic television and feature film rendering. Regulatory frameworks in both countries increasingly shape service provider compliance obligations and infrastructure investment patterns.
United States
Commercial real estate marketing in California and New York drives architectural visualization volumes, with multifamily housing developers commissioning pre-construction imagery. The FTC enforces truth-in-advertising standards that classify undisclosed photorealistic renderings as deceptive trade practices, mandating provenance documentation. Los Angeles production facilities consume real-time rendered environments for LED volume stages, displacing physical set construction across streaming content pipelines.
Canada
Toronto's visual effects cluster leverages elastic cloud capacity to handle episodic television workloads without permanent infrastructure investment. Health Canada's radiation-emitting device regulations govern laser-scanning hardware used in reality-capture workflows that feed rendering pipelines. Vancouver studios serve cross-border entertainment clients while navigating data sovereignty friction over render asset storage and transfer compliance.
Mexico
Guadalajara's emerging technology corridor attracts nearshore animation and architectural visualization outsourcing from US real estate developers. The country's federal consumer protection agency applies advertising standards to synthetic imagery used in cross-border property marketing campaigns. Mexico City studios increasingly integrate into North American production pipelines for mid-market architectural firms seeking cost-efficient render farm access.
North America 3D Rendering Services Market Competitive Landscape
Global majors compete with regional champions across software platform dominance and specialized service delivery in the North America 3D rendering services market. The vendor base clusters around three strategic archetypes: GPU hardware suppliers anchoring compute infrastructure, software platform vendors controlling creative workflow integration, and specialized service studios executing client-facing production. Competitive positioning crystallizes through technology licensing agreements, strategic cloud infrastructure partnerships, and vertical capability expansion into adjacent visualization segments.
Within the software platform tier, Autodesk Inc and Adobe Inc exemplify creative workflow integration strategies, while NVIDIA Corp anchors GPU compute infrastructure supply. Chaos Software Ltd occupies a specialist position in photorealistic light-simulation accuracy for premium film and automotive visualization. These three companies represent distinct competitive vectors: design-to-render pipeline ownership, subscription-based creative ecosystem lock-in, and hardware-bound compute performance differentiation.
| Leading Market Players |
|---|
| Autodesk Inc |
| Adobe Inc |
| NVIDIA Corp |
| Dassault Systemes SE |
| Chaos Software Ltd |
| Unity Technologies |
| Maxon Computer |
| SideFX |
| Foundry Visionmongers Limited |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up architectural visualization specialists in California and New York have consolidated fragmented studio networks, concentrating GPU procurement leverage while enforcing standardized pricing discipline across project portfolios. This ownership pattern feeds directly into supply chain behavior: centralized infrastructure teams negotiate hyperscaler contracts at volume, then cascade preferred-provider status to acquired studios, compressing vendor diversity while stabilizing margin structures.
Pricing Analysis
Input-cost pass-through from NVIDIA's CUDA-core GPU pricing dominates service rate adjustments, with studios indexing per-frame cloud rendering quotes to hyperscaler compute tariffs. Three-tier pricing structure across premium, standard, and economy levels separates photorealistic ray-traced deliverables from real-time game-engine outputs and basic rasterized web assets. Price differentiation hinges on FTC disclosure certification and turnaround velocity, with compliant studios commanding premiums in California real estate marketing. Cost compression in mid-market architectural visualization is intensifying because elastic cloud access eliminates capital barriers for new entrants. Manufacturing buyers exhibit highest price sensitivity, prioritizing cost-per-image efficiency; entertainment clients show lowest sensitivity, accepting premium rates for latency-sensitive virtual production environments.
Supply Chain Analysis
Warehouse-distribution layer concentration in Dallas-Fort Worth and Ashburn, Virginia anchors GPU cluster proximity for low-latency virtual production workflows serving Los Angeles and Toronto clients. Geographic supply concentration centers on Taiwan for advanced GPU silicon, the United States for hyperscaler cloud infrastructure, and China for mid-tier rendering hardware components. Raw material dependencies span high-bandwidth memory modules, liquid cooling systems, and fiber-optic interconnects. Single-source vulnerability from NVIDIA's CUDA architecture dominance creates structural risk for compute-bound ray-tracing pipelines. Distribution runs through direct hyperscaler partnerships for enterprise studios, with regional resellers and managed service providers handling mid-market architectural firm accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America 3D rendering services market operates as a regulatory compounder, with FTC truth-in-advertising enforcement creating certified-origin premiums that reshape competitive positioning and justify compliance infrastructure investments.
For Market Incumbents: Anticipate margin compression from AI-assisted denoising tools that compress render iteration cycles and enable fixed-bid pricing by mid-size competitors. Defensive moves require deepening backward integration into proprietary GPU farm ownership in Texas edge-compute nodes to escape hyperscaler tariff exposure, while accelerating FTC disclosure workflow certification to capture real estate marketing premiums before state-level amplification. For New Entrants and Emerging Players: Cloud-native SaaS platforms represent the most penetrable entry vector, targeting mid-market architectural firms in Chicago and Denver that have abandoned perpetual licenses for elastic operational expenditure models. White-space concentrates in AI-assisted pre-visualization services for multifamily housing developers, and in cross-border data-sovereignty-compliant rendering for Canadian studios serving US entertainment clients. Go-to-market should anchor on consumption-based pricing with embedded compliance tooling. For Investors and Strategic Acquirers: Valuations sit cheapest among regional architectural visualization studios lacking FTC certification infrastructure but holding established developer relationships in California and New York. Long-term viability favors targets with hybrid cloud-edge capacity and proven virtual production pipelines for LED volume stages. The signal to watch is state-level synthetic-media disclosure legislation adoption, which would amplify federal compliance premiums and accelerate consolidation among uncertified mid-cap players.| Strategic Initiative | Industry Significance |
|---|---|
| GPU Farm Ownership | Captures margin from hyperscaler tariffs while securing capacity for latency-sensitive entertainment clients. |
| FTC Certification Program | Unlocks premium pricing in California and New York real estate marketing through compliant disclosure workflows. |
| AI-Assisted Denoising Integration | Compresses render iteration cycles and enables fixed-bid pricing models for mid-market architectural firms. |
| Cross-Border Data Sovereignty Compliance | Captures Canadian studio demand serving US entertainment clients facing jurisdictional storage friction. |
| Virtual Production Pipeline Expansion | Positions for LED volume stage growth in Los Angeles and Toronto displacing physical set construction. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with visualization studio technical directors, real estate marketing procurement leads, hyperscaler cloud solution architects, and entertainment production facility operations managers with secondary validation against SEC filings from Autodesk and Adobe, hyperscaler capex disclosures, FTC enforcement action records, and Health Canada radiation-emitting device regulatory databases. Bottom-up service-provider capacity estimates and top-down end-user demand projections were triangulated for consistency.
Segment-weighting across service type, end user, technology, and application dimensions shaped the analytical framework, with architectural visualization, entertainment production, and cloud rendering receiving distinct growth trajectory assumptions over the projection horizon. CAGRs derived from elasticity modeling of GPU compute pricing, regulatory compliance cost absorption rates, and virtual production adoption curves across Los Angeles and Toronto production clusters.
The model assumes a particular technology adoption path; alternative pathways for neural radiance fields displacing traditional LiDAR-based reality capture would alter the outlook for site documentation cost structures and revision flexibility premiums. Forecasts reflect documented assumptions regarding hyperscaler pricing stability, FTC enforcement intensity, and NVIDIA architecture dominance. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Electronic Data Interchange (EDI) Market
Digital Solutions
Computer Aided Engineering Market
Digital Solutions
Ediscovery Market
Digital Solutions
Global User Experience (UX) Market
Digital Solutions
Search Engine Optimization Services Market
Digital Solutions
OSS/BSS Market
Digital Solutions
Data Marketplace Platform Market
Digital Solutions
Kenya ICT Market
Digital Solutions
Predictive Maintenance Software Market
Digital Solutions
Cloud Service Assurance Market
Digital Solutions
Location Targeted Mobile Advertising Market
Digital Solutions
Global Autonomous Data Platform Market
Digital Solutions
Mobile Marketing Market
Digital Solutions
Global Metadata Management Tools Market
Digital Solutions
Cloud-Based Product Lifecycle Management (PLM) Market
Digital Solutions
Transport Management System Market