
 Automotive Business Process Management Market | 2026-2036
Automotive Business Process Management Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Business Process Management Market Outlook
Germany's industrial software ecosystem is reconfiguring how automotive manufacturers orchestrate cross-border production networks. SAP leverages deep ERP-BPM integration to anchor enterprise accounts across Stuttgart and Wolfsburg manufacturing clusters. Plex Systems competes through cloud-native shop-floor connectivity that sustains real-time visibility for tiered suppliers. Oracle NetSuite differentiates via modular financial workflow tools that extend from procurement through warranty management.
Automotive Business Process Management comprises integrated software platforms that digitize, automate, and optimize operational workflows across vehicle design, production, distribution, and aftersales service, typically deployed through multi-tenant cloud architectures with API-driven interoperability across MES and ERP layers. Its primary commercial purpose is to compress process cycle times, enforce compliance traceability, and unify data flows across fragmented automotive value chains. Workflow Automation commands the largest installed base among product types, though Cloud-Based deployment is expanding fastest as OEMs retire legacy on-premise infrastructure. Among end users, Tier-1 Suppliers represent the most contested segment, where margin pools concentrate around supplier quality management and PPAP documentation automation.
Germany's KBA enforces type-approval documentation standards that compel BPM investment for audit readiness, while REACH and EU Green Deal reporting obligations through ECHA mandate granular supply-chain traceability that only integrated process platforms can deliver cost-effectively. The US NHTSA's evolving defect-recall data requirements similarly pressure North American operations toward centralized case-management systems. Stakeholders must evaluate whether their current BPM stack can absorb pending battery-passport regulations and embedded carbon-accounting rules without wholesale replacement.
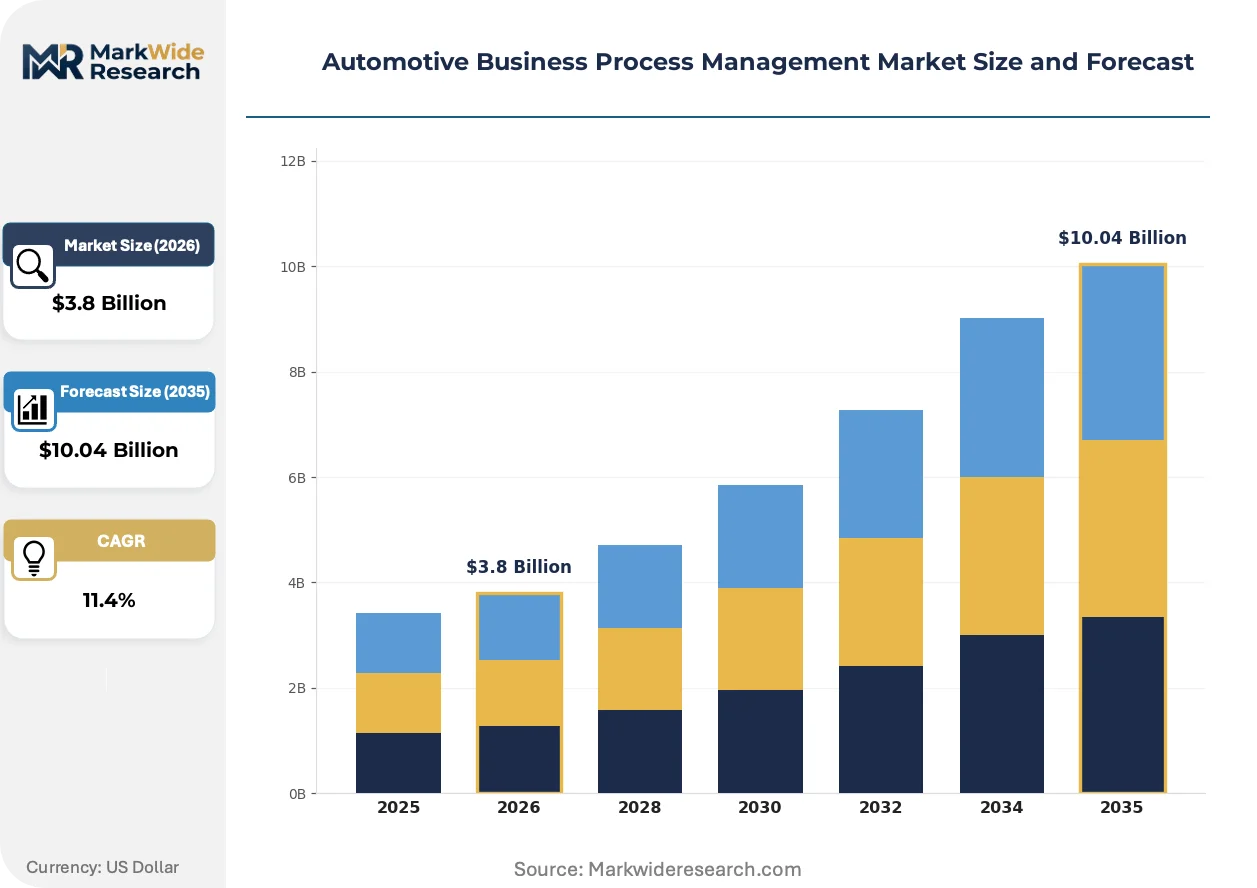
Market Dynamics
AI-embedded workflow engines are compressing decision cycles across automotive engineering and manufacturing operations, forcing incumbent BPM platforms to rearchitect for real-time inference at the process edge.
Growth Catalysts
- EU CSRD Mandate:Sustainability reporting obligations through the Corporate Sustainability Reporting Directive compel tiered suppliers to deploy traceable process documentation systems that BPM platforms uniquely consolidate.
- Battery Passport Architecture:Pending EU regulations for embedded carbon-accounting and full lifecycle traceability of electric vehicle batteries demand granular supply-chain visibility that integrated BPM-ERP stacks deliver.
- Germany's KBA Type-Approval Standards:The Federal Motor Transport Authority enforces rigorous documentation protocols that drive BPM adoption among Stuttgart and Wolfsburg manufacturing clusters for audit readiness.
Market Restraints
- Legacy System Entrenchment:Decades of on-premise ERP-MES investments at major OEMs create technical debt that slows cloud-native BPM migration and extends replacement cycles.
- Specialized Talent Scarcity:Shortages of process engineers fluent in both automotive PPAP protocols and modern API-driven platform architecture constrain implementation velocity.
- REACH Compliance Cost Burden:The European Chemicals Agency's substance registration requirements impose documentation overhead that squeezes margins for mid-tier BPM vendors serving supplier networks.
Strategic Opportunities
- India's PLI-Linked Auto Component Sector:Production-linked incentive schemes for advanced automotive technology manufacturing are spawning BPM demand for supplier quality management and export documentation automation.
- Digital Twin Convergence:Integration between BPM workflow engines and physics-based manufacturing simulations enables predictive process optimization that OEMs increasingly specify in RFPs.
- Aftersales Service Unbundling:Warranty management and predictive maintenance workflows represent underpenetrated BPM applications as vehicle electrification shifts service revenue models.
Industry Challenges
- Multi-Tier Data Sovereignty:Cross-border production networks face conflicting data localization requirements between EU GDPR, China's PIPL, and US state privacy laws that complicate unified BPM deployment.
- PPAP Documentation Velocity:Production Part Approval Process cycles for EV platform launches have compressed from months to weeks, straining BPM systems to maintain quality gate traceability at speed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Business Process Management Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Document Management, Workflow Automation, Performance Management, Compliance Management End User: OEMs, Tier-1 Suppliers, Dealerships, Aftermarket Providers Deployment: On-Premise, Cloud-Based, Hybrid, SaaS Application: Sales & Marketing, Supply Chain Management, Quality Assurance, Financial Services |
| Companies Covered | Epicor, Plex Systems, SAP, Acumatica, QAD, Microsoft Dynamics, Infor, Godlan, Oracle NetSuite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Business Process Management Market Strategic Shifts
Workflow automation architectures are fragmenting across edge-compute, cloud-native, and hybrid deployments as automotive manufacturers balance latency requirements against centralization imperatives for compliance reporting.
Process mining technology is hybridizing with conventional BPM suites to expose hidden inefficiencies in multi-tier supplier coordination. Tier-1 suppliers in Germany's automotive corridor are deploying these tools to compress PPAP cycle times by identifying approval bottlenecks across distributed engineering teams. The structural consequence is a shift from reactive workflow management toward predictive process intervention that reduces warranty exposure.
The EU's CSRD and associated EFRAG standards are mandating granular sustainability disclosure that extends deep into tiered supply chains. Automotive OEMs must now collect and verify Scope 3 emissions data from hundreds of suppliers, a requirement that only integrated BPM platforms with embedded carbon calculators can satisfy at scale. Germany-based manufacturers are responding fastest, embedding ESG data collection directly into procurement workflow templates.
Service contracting for BPM capabilities is rotating from perpetual license models toward consumption-based pricing indexed to transaction volumes or process outcomes. Tier-1 suppliers facing margin pressure from EV transition costs prefer this structure for quality management and warranty administration workflows. This shift is most visible in North American operations where CFOs are pushing operational technology spending toward variable cost structures aligned with production volatility.
Automotive Business Process Management Market Segmentation
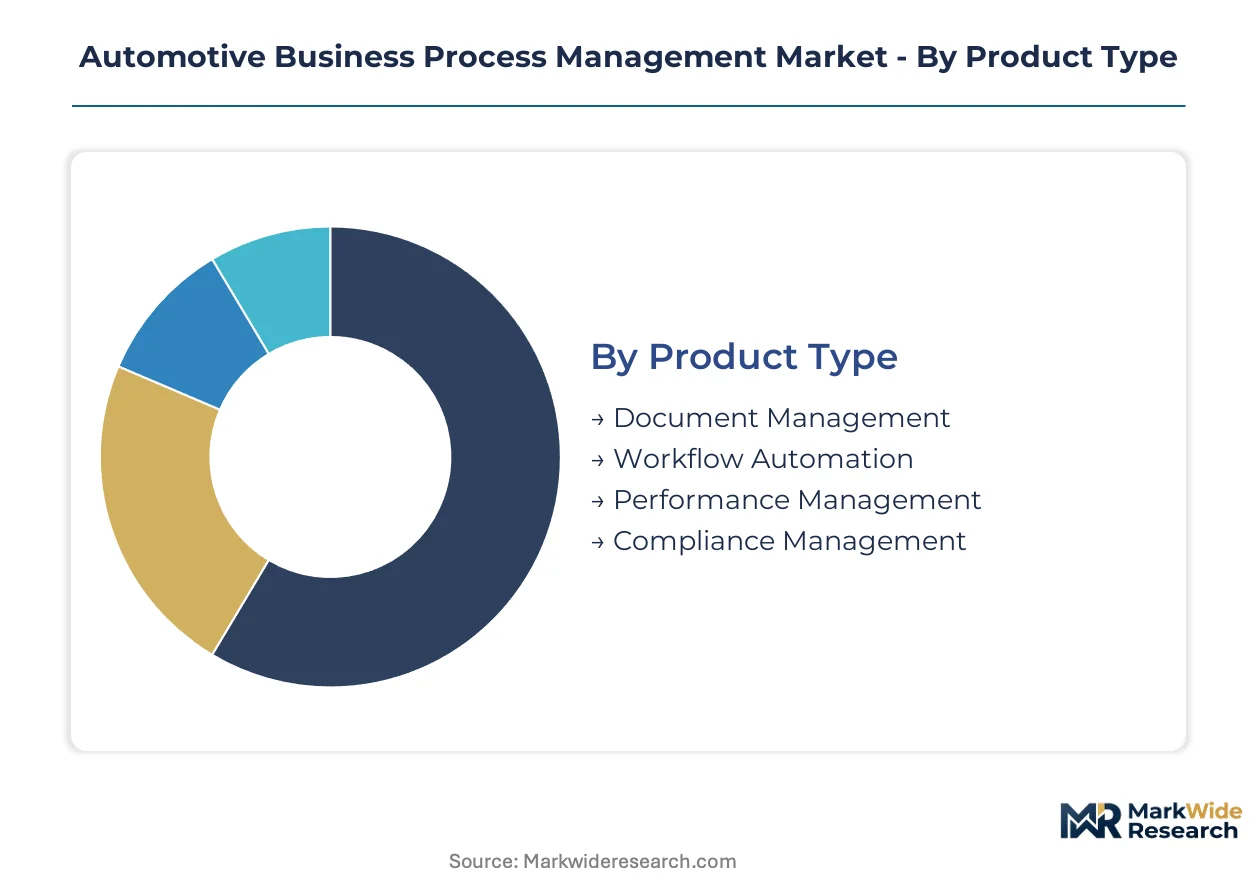
Automotive BPM segmentation reveals how procurement priorities diverge across deployment maturity and regulatory exposure. Tier-1 suppliers select platforms based on PPAP documentation velocity, while OEMs prioritize ERP integration depth for multi-plant coordination.
Product Type:
Cost tier determines platform selection, with premium workflow engines commanding larger implementation budgets than compliance modules.
- Workflow Automation:Embedded AI inference engines compress approval cycles for engineering change orders and supplier quality gates. Stuttgart and Wolfsburg manufacturing clusters deploy these tools most intensively for PPAP acceleration under KBA audit protocols. Cloud-native architectures are displacing legacy on-premise installations as margin pressure forces variable-cost structures.
- Compliance Management:Integrated traceability modules embed ECHA REACH substance tracking and CSRD carbon-accounting directly into procurement workflows. EU-based Tier-1 suppliers treat this as non-negotiable infrastructure for battery passport readiness. Platform vendors compete on pre-certified template libraries that reduce implementation timelines.
- Document Management:Centralized repositories with version-controlled access govern type-approval submissions across distributed engineering teams.
- Performance Management:Real-time dashboards aggregate MES and ERP data for OEE visibility at plant level.
Workflow Automation holds installed capacity. Compliance Management is rotating up the share rankings.
End User:
Customer type shapes functional requirements, with each tier demanding different depth of supplier network visibility.
- Tier-1 Suppliers:Margin compression from EV platform launches forces investment in automated PPAP documentation and warranty traceability. These stakeholders specify API-first architectures that interoperate with OEM ERP systems without custom integration costs. India's PLI-linked component manufacturers represent emerging demand concentration for export compliance automation.
- OEMs:Multi-brand corporations require centralized process orchestration across heterogeneous plant infrastructures accumulated through decades of acquisition. SAP-embedded BPM stacks dominate Stuttgart and Wolfsburg headquarters for ERP-BPM integration depth. Battery passport regulations are accelerating replacement of legacy on-premise installations.
- Dealerships:Franchise networks prioritize warranty administration and parts inventory optimization over manufacturing-oriented capabilities.
- Aftermarket Providers:Independent service chains seek modular subscription tools for predictive maintenance workflow digitization.
Tier-1 Suppliers anchor current revenue concentration. OEMs are climbing the fastest as battery passport mandates force platform consolidation.
Deployment:
Maturity stage dictates infrastructure decisions, with early adopters now optimizing hybrid architectures while laggards skip to cloud-native.
- Cloud-Based:Multi-tenant SaaS architectures eliminate capital expenditure for Tier-1 suppliers facing EV transition margin pressure. Plex Systems and comparable vendors compete on shop-floor connectivity that sustains real-time visibility without on-premise middleware. Consumption-based pricing models align operational technology spending with production volatility.
- SaaS:Pre-configured automotive templates for PPAP and supplier quality management reduce implementation risk for mid-tier suppliers. Oracle NetSuite differentiates through modular financial workflow extensions from procurement through warranty administration. North American CFOs prefer this structure for operational expenditure treatment.
- On-Premise:Legacy ERP-BPM stacks persist at major OEMs with decades of technical debt and customized integration layers.
- Hybrid:Edge-compute process engines handle latency-sensitive shop-floor decisions while centralizing compliance reporting in cloud repositories.
On-Premise retains legacy installed base. Cloud-Based is gaining share fastest as retirement cycles accelerate.
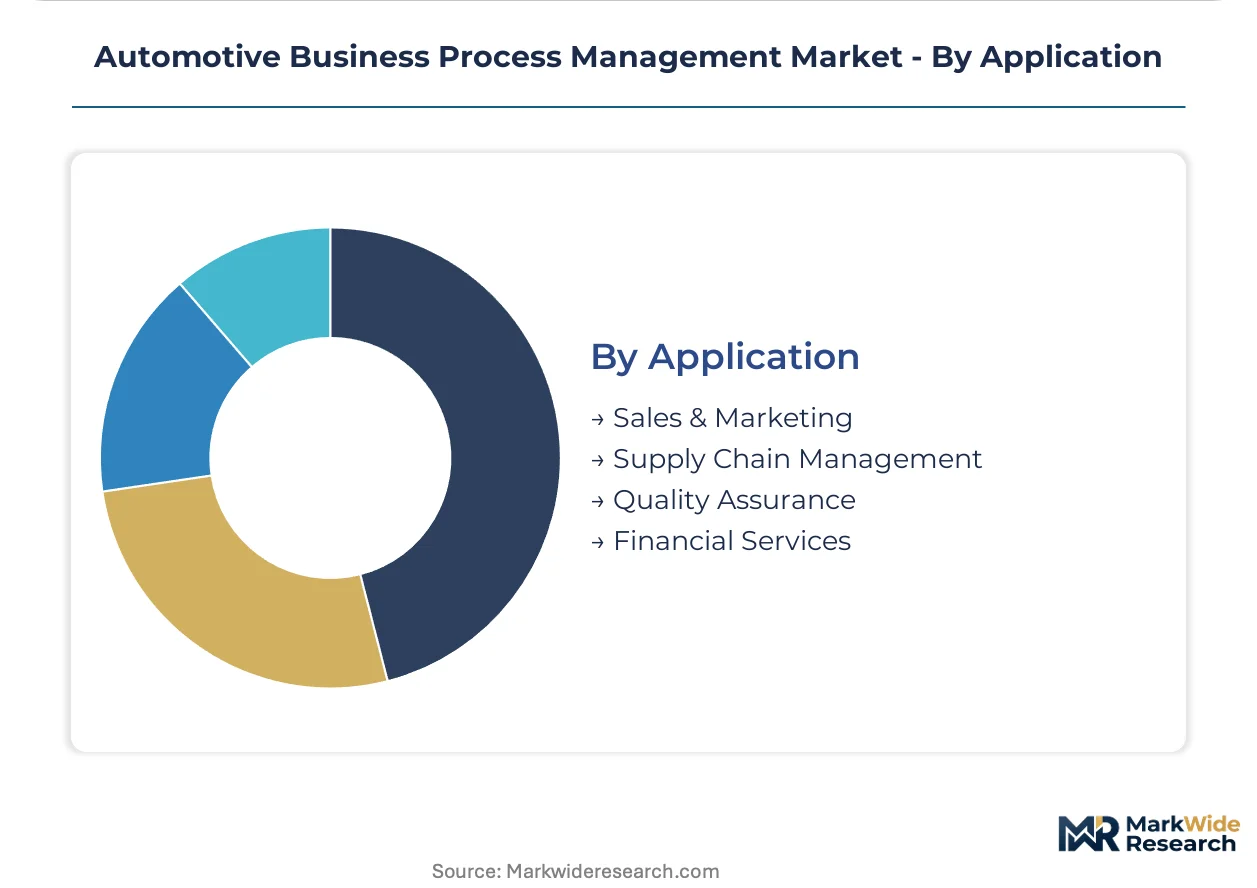
Application:
Functional domain determines integration complexity, with supply chain modules requiring deepest multi-tier data orchestration.
- Supply Chain Management:Granular visibility from raw material sourcing through final assembly supports EU Green Deal carbon-accounting and battery passport traceability. ECHA REACH compliance mandates substance documentation that only integrated BPM-ERP stacks can deliver at tiered supplier scale. Germany-based manufacturers embed ESG data collection directly into procurement workflow templates.
- Quality Assurance:Automated PPAP gate management compresses approval cycles from months to weeks for EV platform launches. Process mining tools expose bottlenecks across distributed engineering teams in Germany's automotive corridor. Predictive intervention capabilities reduce warranty exposure through early defect pattern recognition.
- Sales & Marketing:Configure-price-quote automation and dealer incentive management attract mid-market investment.
- Financial Services:Warranty reserve calculation and lease-end residual value workflows serve captive finance operations.
Supply Chain Management holds installed capacity. Quality Assurance is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform vendors concentrate engineering resources in automotive manufacturing corridors where regulatory density and supplier network complexity converge. Germany's KBA documentation mandates and the EU's CSRD sustainability reporting framework create concentrated demand for integrated BPM-ERP stacks across three continents.
Germany
KBA type-approval standards and ECHA REACH substance tracking compel Stuttgart and Wolfsburg manufacturing clusters to maintain audit-ready process documentation. The EU Green Deal's embedded carbon-accounting rules accelerate retirement of legacy on-premise installations. SAP-anchored ERP-BPM integration dominates headquarters operations across Baden-Württemberg and Lower Saxony industrial zones.
United States
NHTSA defect-recall data requirements pressure Detroit and Southeast automotive corridors toward centralized case-management systems. Tier-1 suppliers facing EV transition margin compression specify API-first architectures for warranty traceability. Cloud-native deployments expand fastest among Michigan and Tennessee manufacturing networks seeking variable-cost operational technology structures.
China
MIIT intelligent manufacturing directives and dual carbon goals drive BPM adoption across Yangtze River Delta EV production hubs. Battery passport traceability requirements for EU export markets demand granular supply-chain visibility. Shanghai and Shenzhen automotive clusters deploy edge-compute process engines to balance latency requirements against centralized compliance reporting.
India
PLI-linked auto component incentives spawn BPM demand for supplier quality management and DGFT export documentation automation. Tamil Nadu and Gujarat manufacturing corridors attract tier-1 suppliers establishing export-oriented production. Mid-tier component manufacturers specify pre-configured PPAP templates to reduce implementation risk.
Japan
METI Society 5.0 digitalization targets and JIS quality standards sustain BPM investment across Aichi Prefecture automotive engineering networks. Toyota City and Nagoya manufacturing clusters emphasize predictive process intervention through digital twin convergence. Hybrid deployment architectures dominate as incumbents balance latency-sensitive shop-floor decisions against cloud-based compliance repositories.
Automotive Business Process Management Market Competitive Environment
ERP-native platforms and cloud-native specialists split the market along integration depth versus deployment velocity axes. Incumbent vendors leverage decades of automotive customer relationships and customized middleware layers. Challenger platforms compete through multi-tenant SaaS architectures and consumption-based pricing aligned with production volatility. Consolidation pressure intensifies as battery passport regulations force wholesale replacement of fragmented legacy installations.
Among ERP-integrated incumbents, SAP exemplifies the deep-integration archetype through Stuttgart and Wolfsburg enterprise account concentration. Plex Systems occupies the cloud-native connectivity position with real-time shop-floor visibility offerings. Oracle NetSuite represents the modular financial workflow specialization extending from procurement through warranty administration. These three anchors illustrate how vendor selection bifurcates between headquarters ERP consolidation and supplier network agility.
| Leading Market Players |
|---|
| Epicor |
| Plex Systems |
| SAP |
| Acumatica |
| QAD |
| Microsoft Dynamics |
| Infor |
| Godlan |
| Oracle NetSuite |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Frankfurt rail freight corridors transmit cost volatility from German manufacturing clusters to BPM platform pricing, compressing margins for cloud-native vendors while amplifying differentiation premiums for ERP-integrated incumbents serving KBA audit-ready documentation requirements.
Pricing Analysis
The EU CSRD dictates the pricing tier structure across automotive BPM platforms, separating premium ERP-embedded stacks from mid-tier SaaS offerings and economy compliance modules. Three-tier pricing stratifies across enterprise-grade workflow automation, modular departmental tools, and template-based entry solutions. Price differentiation rests on certification depth for ECHA REACH traceability and KBA type-approval readiness. Cost compression in mid-tier SaaS intensifies as Tier-1 suppliers facing EV transition margin pressure demand consumption-based structures. OEM headquarters show least price sensitivity, prioritizing ERP integration depth over licensing cost.
Supply Chain Analysis
Extended payment terms from Stuttgart and Wolfsburg OEMs cascade through supplier networks, forcing BPM vendors to absorb working capital strain or cede position to ERP-native competitors with balance sheet depth. Component concentration centers on Germany, the United States, and India for platform development and implementation services. Raw material dependencies include cloud infrastructure from hyperscale providers, specialized process engineering talent, and pre-certified regulatory template libraries. Single-source vulnerability runs through SAP-anchored middleware layers that dominate Baden-Württemberg industrial zones. Distribution runs through direct enterprise sales for OEM accounts and channel partners for mid-tier supplier penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive BPM exhibits defensive moat characteristics rooted in regulatory entrenchment—KBA documentation mandates and CSRD traceability requirements create switching costs that cement incumbent positions across multi-year replacement cycles.
For Market Incumbents: Harden ERP-BPM integration layers at Stuttgart and Wolfsburg headquarters to capture battery passport-driven replacement cycles. Deepen vertical control over process engineering talent pipelines to counter specialized scarcity constraining implementation velocity. Extend pre-certified template libraries for ECHA REACH and EU Green Deal compliance to compress competitor implementation timelines. For New Entrants and Emerging Players: India's PLI-linked auto component corridors offer underpenetrated white-space for export documentation automation and supplier quality management tools. Target mid-tier component manufacturers in Tamil Nadu and Gujarat with pre-configured PPAP templates that reduce implementation risk. Lead with API-first architectures that interoperate with OEM ERP systems without custom integration costs. For Investors and Strategic Acquirers: Cloud-native specialists with shop-floor connectivity capabilities represent the priority acquisition archetype as battery passport regulations force wholesale legacy replacement. Long-term viability hinges on consumption-based pricing alignment with production volatility and embedded AI inference engines. Watch for PPAP documentation velocity benchmarks as the inflection signal—platforms compressing approval cycles from months to weeks will capture Tier-1 supplier expansion budgets.| Strategic Initiative | Industry Significance |
|---|---|
| ERP-BPM Integration Deepening | SAP-anchored stacks capture Stuttgart and Wolfsburg battery passport replacement cycles. |
| Cloud-Native Shop-Floor Connectivity | Plex Systems architectures sustain real-time visibility without on-premise middleware. |
| Consumption-Based Pricing Pivot | Variable-cost structures align operational technology spending with EV transition volatility. |
| Pre-Certified Compliance Templates | ECHA REACH and CSRD-ready libraries compress implementation timelines for EU suppliers. |
| Process Mining Hybridization | Tier-1 suppliers deploy bottleneck identification tools across distributed engineering teams. |
Study Parameters
Initial hypotheses were tested against primary input from OEM platform engineers, Tier-1 supplier procurement directors, aftermarket distributors, and dealership operations managers, then refined through secondary validation. Primary fieldwork combined structured interviews with process architects at Stuttgart and Wolfsburg manufacturing clusters and implementation specialists serving India's PLI-linked component sector. Secondary sources included vehicle production databases, IHS Markit registration data, KBA type-approval filings, and ECHA REACH substance tracking disclosures. Bottom-up segment sizing triangulated against top-down market consolidation analysis.
Demand-supply balance framing anchored the forecast framework, modeling deployment mode, organization tier, integration complexity, regional regulatory cluster, and application domain across the projection horizon. CAGRs derived from segment-level growth trajectory analysis weighted by battery passport implementation timelines and CSRD compliance deadlines. Industry-specific inputs included PPAP documentation velocity benchmarks and cloud infrastructure hyperscaler capex disclosures.
The forecast holds incumbent behavior within observed patterns; aggressive platform consolidation moves by ERP-native vendors or rapid AI-embedded workflow engine deployment by challengers would shift outcomes. Macroeconomic deviation, regulatory acceleration, or breakthrough process automation technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Desktop Outsourcing Market
Business Process Outsourcing (BPO)
Procurement Outsourcing Services Market
Business Process Outsourcing (BPO)
Global Knowledge Process Outsourcing Market
Business Process Outsourcing (BPO)
Global Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Business Process Re-Engineering Market
Business Process Outsourcing (BPO)
Global Document Outsourcing Market
Business Process Outsourcing (BPO)
Back Office Outsourcing Market
Business Process Outsourcing (BPO)
IT Outsourcing Market
Business Process Outsourcing (BPO)
Global Software Outsourcing Market
Business Process Outsourcing (BPO)
Global Supply Chain Management BPO Market
Business Process Outsourcing (BPO)
United States IT Outsourcing Market
Business Process Outsourcing (BPO)
Europe Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Business Process As a Service (Bpaas) Market
Business Process Outsourcing (BPO)
Labor Outsourcing Service Market
Business Process Outsourcing (BPO)
United States Healthcare BPO Market
Business Process Outsourcing (BPO)
Asia-Pacific Business Process Outsourcing (BPO) Market