
 Desktop Virtualization in Manufacturing Market | 2026-2036
Desktop Virtualization in Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Desktop Virtualization in Manufacturing Market Insights
Multi-source virtualization licensing is recalibrating procurement patterns across manufacturing IT departments. Citrix Systems anchors enterprise-grade application virtualization through deep channel partnerships with industrial systems integrators. VMware differentiates via GPU virtualization capabilities that support CAD/CAM workloads on thin-client factory floors. Microsoft Corporation extends its position through Azure Virtual Desktop bundling with existing manufacturing ERP subscriptions.
Desktop virtualization in manufacturing delivers centrally managed computing environments where operating systems, applications, and data reside on servers rather than local devices, enabling real-time patch management and reducing endpoint attack surfaces through zero-trust access protocols. Its primary industrial purpose secures intellectual property by preventing CAD files and process parameters from persisting on shop-floor hardware. Cloud-based deployment models capture the fastest expansion as manufacturers retire aging on-premises data centers, while application virtualization commands premium margins where specialized engineering software requires isolated runtime environments. Hypervisor-based technology leads in mature automotive assembly operations, though container-based approaches gain traction for lightweight kiosk and HMI virtualization.
FDA 21 CFR Part 11 shapes validated virtual desktop requirements in pharmaceutical and medical device manufacturing, mandating audit trails and electronic signature integrity. NIST cybersecurity frameworks drive zero-trust architecture adoption across US defense suppliers, while EU GDPR and emerging CSRD disclosures pressure European manufacturers toward sovereign cloud desktop deployments. Stakeholders must weigh data residency obligations against the operational flexibility of cross-border virtual workspace orchestration.
Market Dynamics
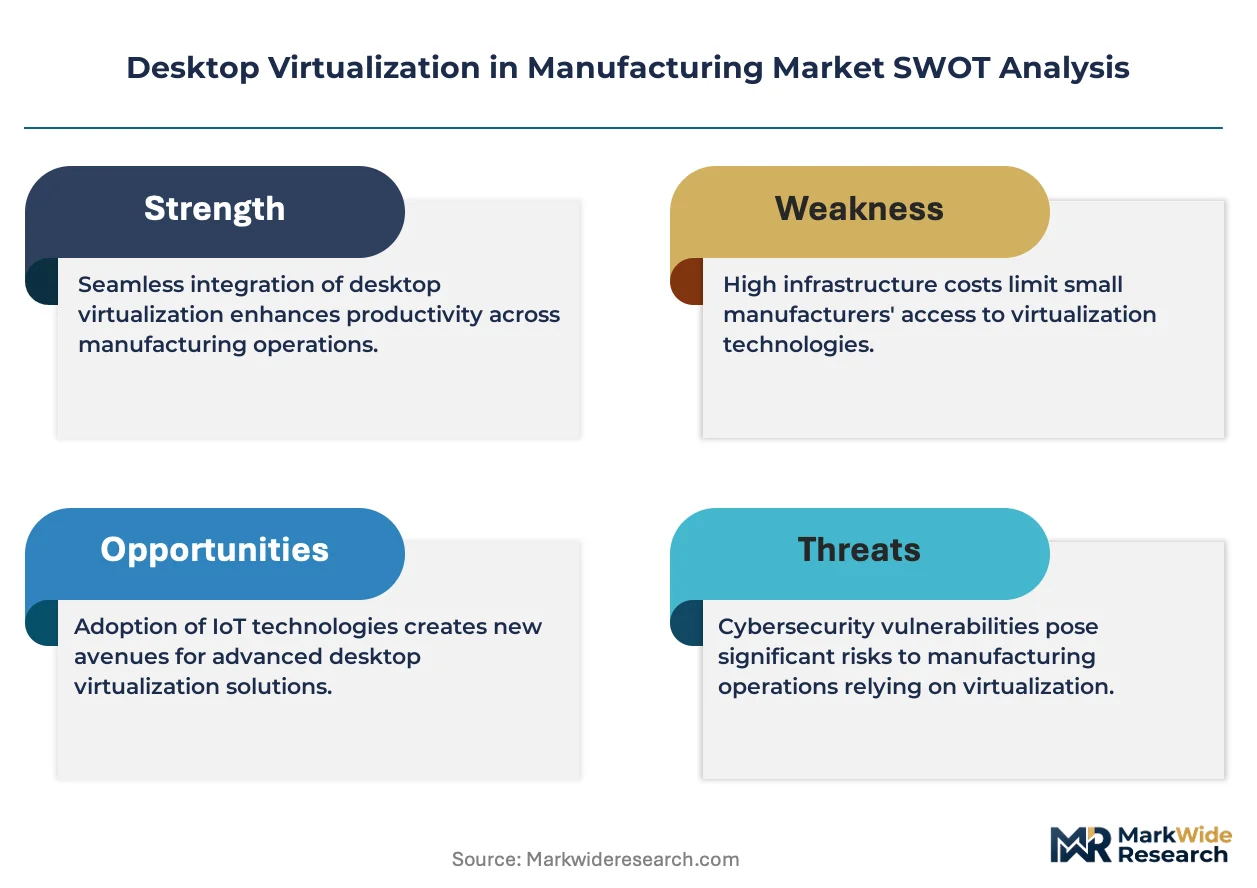
Hybrid cloud-desktop architectures are forcing manufacturing IT departments to rearchitect endpoint security models around zero-trust access protocols, compressing traditional hardware refresh cycles while elevating sovereign data requirements.
Growth Catalysts
- NIST Cybersecurity Frameworks:US defense suppliers mandate zero-trust virtual desktop infrastructure for controlled unclassified information handling, accelerating validated deployment templates across tier-1 aerospace contractors.
- Automotive CAD/CAM virtualization:Multi-site OEM production networks deploy GPU-accelerated virtual workstations to synchronize design iterations across dispersed engineering teams without file persistence on local devices.
- FDA 21 CFR Part 11:Pharmaceutical and medical device manufacturers invest in audit-trail-compliant virtual desktops to satisfy electronic signature integrity requirements for batch records and quality documentation.
Market Restraints
- GPU supply concentration:NVIDIA's dominance in datacenter graphics acceleration creates procurement bottlenecks for manufacturers scaling virtual CAD workstations across multiple facilities.
- EU GDPR data residency:Cross-border virtual workspace orchestration faces friction from emerging CSRD disclosure requirements and sovereign cloud mandates in Germany, France, and the Netherlands.
- Legacy SCADA integration:Brownfield manufacturing sites struggle to bridge air-gapped industrial control systems with modern virtual desktop networks without compromising operational technology security boundaries.
Strategic Opportunities
- India's PLI scheme manufacturing expansion:Electronics and automotive component producers building greenfield facilities represent underpenetrated demand for cloud-native desktop virtualization without legacy technical debt.
- Edge-container convergence:Lightweight container-based virtualization for factory-floor kiosks and HMI terminals enables real-time rendering with lower infrastructure overhead than traditional hypervisor approaches.
- ISO 27001 certification tailwinds:Information security management system mandates from European automotive OEMs are pushing tier-2 and tier-3 suppliers toward certified managed desktop service providers.
Industry Challenges
- OT-IT convergence expertise:Manufacturing organizations face acute shortages of professionals capable of securing virtual desktop deployments that interface with operational technology networks without disrupting production continuity.
- Validation documentation burden:FDA-regulated environments require extensive qualification protocols for virtual desktop infrastructure changes, extending deployment timelines and elevating compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Desktop Virtualization in Manufacturing Market |
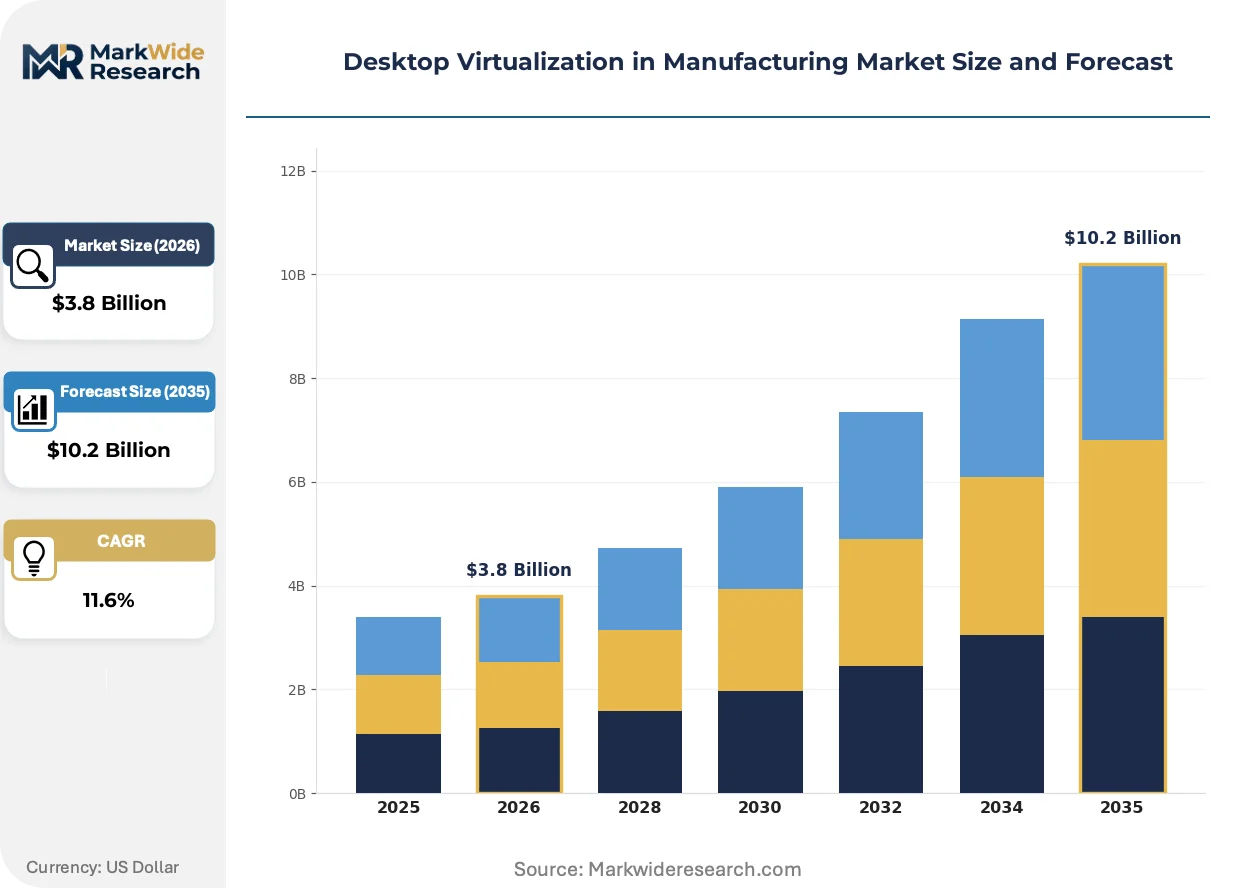
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, Virtual Desktop Infrastructure Solution Type: Application Virtualization, Desktop as a Service, Remote Desktop Services, User Environment Management End User: OEMs, Tier-1 Suppliers, Manufacturing Plants, Assembly Lines Technology: Hypervisor-Based, Container-Based, GPU Virtualization, Security Protocols |
| Companies Covered | Citrix Systems, VMware, Microsoft Corporation, Cisco Systems, Amazon Web Services, IBM Corporation, Huawei Technologies, Hewlett Packard Enterprise, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Desktop Virtualization in Manufacturing Market Trends and Innovations
GPU virtualization technology is absorbing rendering workloads previously tethered to high-end engineering workstations, compressing capital requirements for design-intensive manufacturing operations.
Container-based desktop virtualization is absorbing lightweight application delivery scenarios on factory floors, enabling automotive suppliers in Stuttgart and Wolfsburg to deploy ephemeral virtual environments for temporary quality inspection stations without persistent endpoint configuration.
EU CSRD sustainability disclosure requirements are compelling German industrial manufacturers to document energy consumption of their desktop virtualization infrastructure, driving procurement preference toward cloud providers with verified renewable energy matching and carbon accounting transparency.
Subscription-based managed desktop services are displacing perpetual license procurement in mid-sized Mittelstand manufacturers, with industrial systems integrators in Bavaria and Baden-Württemberg bundling virtual workspace provisioning with existing maintenance contracts to capture recurring revenue streams.
Desktop Virtualization in Manufacturing Market Segmentation
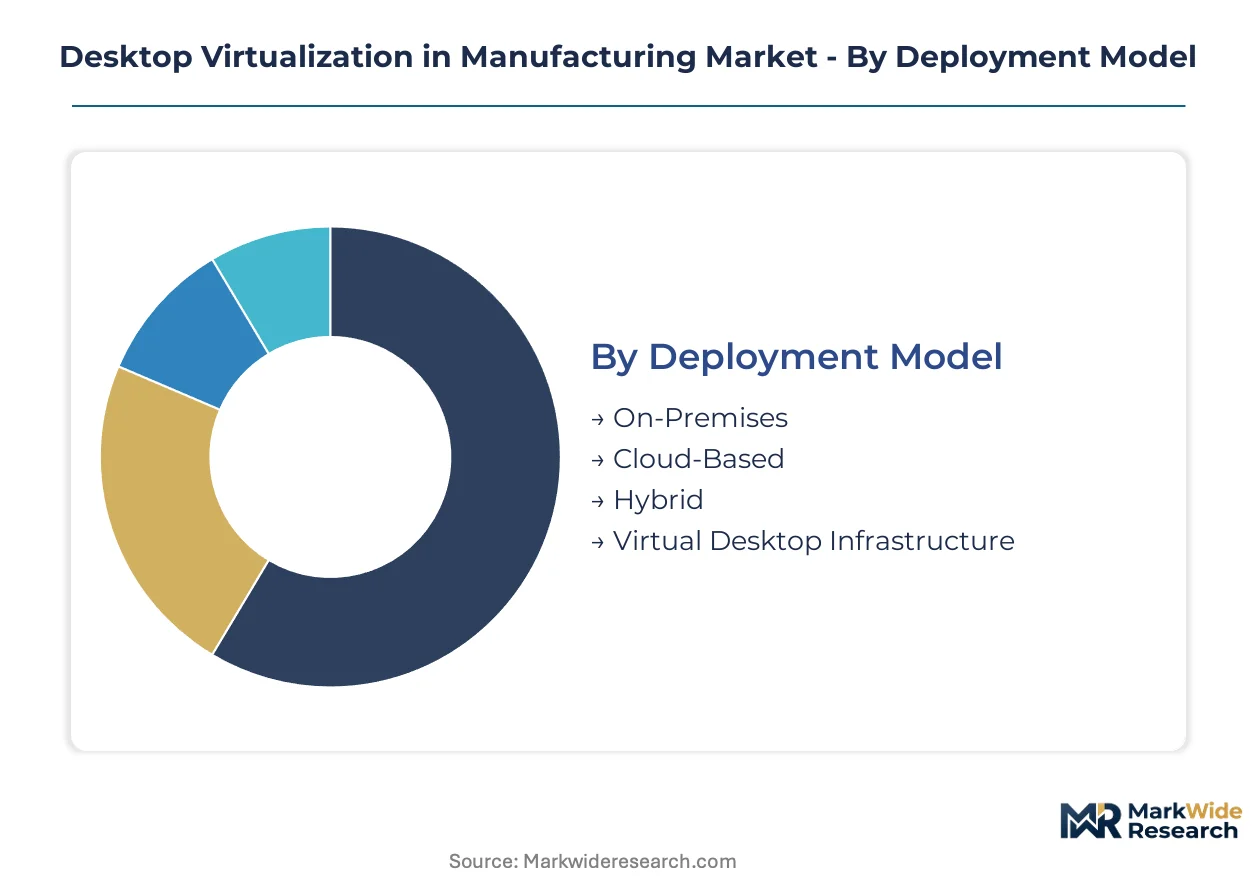
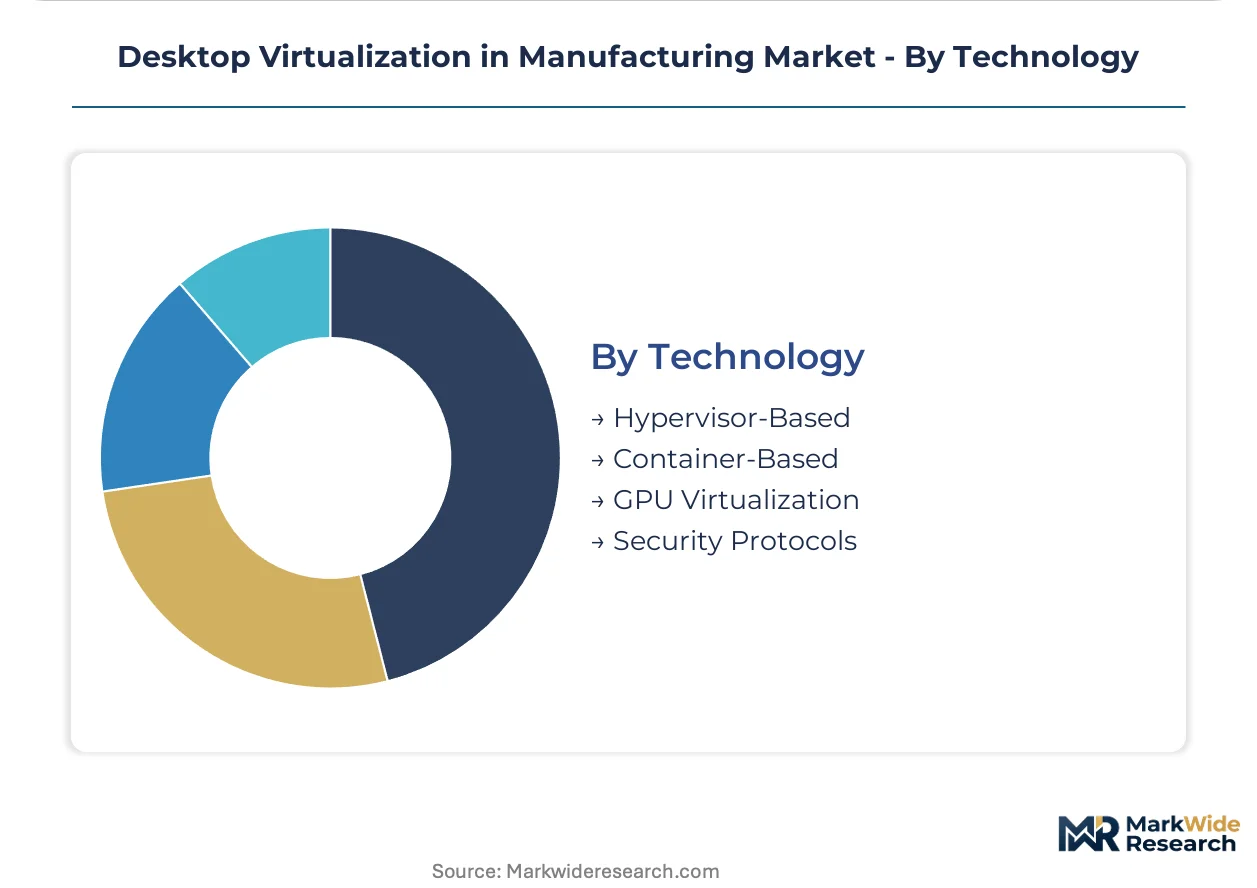
Desktop virtualization in manufacturing fragments across four structural dimensions that determine capital allocation, compliance burden, and operational flexibility. Each segmentation axis carries distinct procurement patterns, technology requirements, and vendor selection criteria that shape deployment outcomes across industrial environments.
Deployment Model:
Capital intensity varies sharply across deployment architectures, with upfront infrastructure commitments ranging from fully depreciated legacy data centers to greenfield cloud-native provisioning.
- Cloud-Based:Manufacturers lease virtual desktop capacity from hyperscale providers, eliminating server procurement cycles and shifting expenditure to operational budgets. Automotive OEMs in Stuttgart and Wolfsburg favor this model for temporary engineering workstations during product launch windows. Cloud-based deployments absorb the bulk of installed capacity; hybrid architectures are expanding most quickly.
- On-Premises:Enterprises retain full hardware ownership within facility data centers, prioritizing air-gapped security for defense suppliers handling controlled unclassified information. German Mittelstand manufacturers maintain these deployments to satisfy BSI IT-Grundschutz data sovereignty requirements.
- Hybrid:Split workloads between local infrastructure and cloud resources, enabling burst capacity for seasonal production ramps without permanent overprovisioning. Tier-1 aerospace contractors in Toulouse and Hamburg use hybrid models to balance ITAR compliance with engineering collaboration demands.
- Virtual Desktop Infrastructure:Purpose-built server farms deliver persistent virtual machines to endpoint devices, requiring substantial datacenter investment but offering maximum customization for specialized CAD/CAM toolchains.
Cloud-based models dominate new procurement decisions; hybrid configurations command the steepest expansion trajectory among manufacturers with mixed legacy-modernization requirements.
Solution Type:
Application isolation requirements drive solution selection, with engineering software licensing models and FDA validation obligations creating divergent procurement paths.
- Application Virtualization:Isolates individual software packages from host operating systems, enabling concurrent runtime of conflicting CAD versions without workstation reconfiguration. Medical device manufacturers in Ireland and Minnesota deploy this approach to maintain validated environments for FDA 21 CFR Part 11 compliance. Application virtualization captures the largest revenue share; Desktop as a Service is climbing the fastest among mid-sized suppliers.
- Desktop as a Service:Fully managed subscription offerings bundle infrastructure, licensing, and support into per-user monthly fees. Bavarian automotive suppliers adopt DaaS to outsource endpoint management and redirect internal IT resources toward OT-IT integration projects.
- Remote Desktop Services:Session-based virtualization multiplexes multiple users onto shared server instances, minimizing per-seat costs for task workers accessing standardized ERP interfaces.
- User Environment Management:Profile and policy orchestration tools personalize virtual sessions without persistent virtual machines, reducing storage overhead in large-scale deployments.
Application virtualization retains primacy in regulated manufacturing; Desktop as a Service gains share fastest where IT staffing constraints bite hardest.
End User:
Organizational scale and technical sophistication determine feature requirements, with OEMs demanding GPU acceleration that assembly line deployments rarely need.
- OEMs:Original equipment manufacturers operate the most complex virtual desktop estates, synchronizing design data across multi-site engineering centers while enforcing strict IP egress controls. German automotive OEMs mandate ISO 27001 certification from all virtualization providers.
- Tier-1 Suppliers:Direct component providers balance OEM compliance requirements with leaner IT organizations, often purchasing managed desktop services through industrial systems integrators. Suppliers in Baden-Württemberg increasingly bundle virtualization with existing maintenance contracts.
- Manufacturing Plants:Single-facility deployments emphasize shop-floor durability and offline resilience, with thin-client endpoints replacing aging PCs in dusty production environments.
- Assembly Lines:Station-specific kiosks and HMI terminals require only lightweight application delivery, making container-based virtualization economically viable for high-node-count deployments.
OEMs anchor solution development roadmaps; Tier-1 suppliers represent the fastest-growing customer category as outsourcing pressures intensify.
Technology:
Virtualization substrate selection hinges on workload characteristics, with graphics-intensive engineering applications demanding hardware acceleration that administrative tasks do not require.
- GPU Virtualization:NVIDIA vGPU and AMD MxGPU technologies partition datacenter graphics cards across multiple virtual workstations, enabling real-time 3D rendering without dedicated engineering PCs. Automotive design studios in Munich and Detroit rely on GPU virtualization to compress hardware refresh cycles. GPU virtualization leads technology investment; container-based approaches are gaining share fastest at the network edge.
- Hypervisor-Based:VMware ESXi and Microsoft Hyper-V dominate mature manufacturing IT environments, offering proven stability for business-critical ERP and PLM systems.
- Container-Based:Lightweight runtime isolation enables rapid provisioning of ephemeral desktops for temporary quality inspection stations and seasonal workforce scaling. Stuttgart automotive suppliers deploy containerized kiosks with sub-minute startup times.
- Security Protocols:Zero-trust access frameworks, multi-factor authentication, and encrypted display protocols form mandatory overlays regardless of underlying virtualization technology, with NIST 800-207 guidance shaping implementation choices among US defense contractors.
Hypervisor-based deployments retain the largest installed base; container-based virtualization is expanding most quickly for factory-floor edge scenarios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial automation corridors anchor demand for sovereign desktop virtualization architectures, while US defense manufacturing clusters drive zero-trust compliance investments. India's greenfield electronics production facilities represent the fastest-expanding frontier for cloud-native deployments.
United States
NIST cybersecurity frameworks mandate zero-trust virtual desktop infrastructure for defense suppliers handling controlled unclassified information. FDA 21 CFR Part 11 requirements shape validated deployments across pharmaceutical manufacturing in New Jersey and North Carolina. Aerospace contractors in Seattle and Los Angeles integrate GPU-accelerated virtual workstations for multi-site engineering collaboration.
Germany
Mittelstand manufacturers pursue hybrid cloud-desktop architectures to balance BSI IT-Grundschutz data sovereignty requirements with operational agility. EU CSRD sustainability disclosure rules pressure industrial firms toward renewable-energy-matched cloud providers. Automotive OEMs in Stuttgart and Wolfsburg mandate ISO 27001 certification from all virtualization vendors serving their supplier networks.
India
PLI scheme incentives for electronics and automotive component manufacturing create greenfield demand without legacy technical debt. CDSCO digital record requirements for medical device manufacturing accelerate validated virtual desktop adoption in Hyderabad and Bengaluru. Contract manufacturers in Tamil Nadu and Gujarat deploy cloud-native DaaS to avoid capital-intensive data center construction.
China
MIIT cybersecurity classifications restrict cross-border data flows, favoring domestic cloud providers for manufacturing virtual desktop deployments. Dual carbon goals drive energy efficiency scrutiny for datacenter-powered virtualization infrastructure in Yangtze River Delta industrial zones. State-owned automotive groups in Shanghai and Wuhan consolidate engineering workstations onto centralized GPU virtualization platforms.
Japan
METI digital manufacturing initiatives promote virtual desktop standardization across keiretsu supplier networks. JIS information security standards shape procurement criteria for tier-1 automotive and electronics manufacturers. Precision equipment producers in Nagoya and Osaka deploy container-based virtualization for factory-floor HMI terminals requiring sub-minute provisioning.
Desktop Virtualization in Manufacturing Market Competitive Landscape
Global majors compete with regional champions across virtualization substrate technologies, creating a tiered structure where hyperscale cloud providers, enterprise software incumbents, and specialized GPU acceleration vendors occupy distinct competitive positions. The vendor landscape segments into three strategic archetypes: full-stack platform providers bundling infrastructure with productivity suites, GPU virtualization specialists serving design-intensive manufacturing workloads, and managed service providers capturing mid-market outsourcing demand. Dominant competitive moves include strategic partnerships with industrial systems integrators and vertical integration into sovereign cloud infrastructure to satisfy data residency requirements.
Among enterprise software incumbents, Citrix Systems, VMware, and Microsoft Corporation exemplify distinct positioning vectors within manufacturing virtualization. Citrix represents the application virtualization archetype through channel-intensive industrial partnerships. VMware anchors GPU-accelerated workstation virtualization for automotive and aerospace engineering environments. Microsoft occupies the bundled cloud productivity position, leveraging Azure Virtual Desktop integration with existing manufacturing ERP subscriptions to compress procurement friction.
| Leading Market Players |
|---|
| Citrix Systems |
| VMware |
| Microsoft Corporation |
| Cisco Systems |
| Amazon Web Services |
| IBM Corporation |
| Huawei Technologies |
| Hewlett Packard Enterprise |
| Oracle Corporation |
| Others |
Pricing and Supply Chain Analysis
Captive integration into NVIDIA's datacenter GPU supply anchors pricing power for virtual workstation deployments, with automotive OEMs in Stuttgart and Wolfsburg absorbing premium costs to secure vGPU allocation for CAD/CAM workloads. This vertical control over graphics acceleration hardware concentrates procurement leverage among hyperscale cloud providers, compressing margins for mid-sized Mittelstand manufacturers lacking direct allocation agreements.
Pricing Analysis
Managed service bundling separates validated FDA 21 CFR Part 11 environments from standard virtual desktop tiers, with compliance documentation and audit-trail infrastructure driving premium positioning. Three-tier pricing structure across premium GPU-accelerated, standard business productivity, and economy kiosk-terminal levels reflects workload intensity differentiation. Cost compression in standard tiers is intensifying because Microsoft Azure Virtual Desktop bundles erode standalone licensing value. Tier-1 automotive suppliers exhibit highest price sensitivity due to OEM cost-down mandates, while pharmaceutical manufacturers show lowest sensitivity given validation replacement costs.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Amsterdam, and Singapore anchor hub-and-spoke delivery of thin-client endpoints to manufacturing facilities. GPU silicon supply concentrates in Taiwan and South Korea, with final assembly of virtualization servers distributed across China, Mexico, and Germany. Raw material dependencies span NVIDIA A100/H100 accelerators, enterprise SSD storage arrays, and zero-trust security modules. Single-source vulnerability in NVIDIA's datacenter graphics stack exposes procurement timelines to allocation rationing. Distribution runs through industrial systems integrators in Bavaria and Baden-Württemberg serving Mittelstand accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container-based virtualization is displacing hypervisor architectures for factory-floor edge deployments, compressing infrastructure overhead while demanding new orchestration expertise from manufacturing IT organizations.
For Market Incumbents: Hedge against GPU supply concentration by cultivating AMD MxGPU alternatives and ARM-based edge virtualization partnerships. Secure channel control through exclusive industrial systems integrator agreements in Germany's automation corridor. Invest in ISO 27001 certification maintenance to defend against emerging sovereign cloud competitors.
For New Entrants and Emerging Players: Tier-3 automotive suppliers in India's PLI scheme corridors represent underpenetrated demand for cloud-native DaaS without legacy SCADA integration burdens. Target medical device contract manufacturers in Hyderabad seeking CDSCO-compliant validated environments. Pursue OEM-direct partnerships bypassing established integrator networks.
For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscaler acquisition of container-based virtualization specialists with manufacturing vertical expertise. Long-term viability favors platforms demonstrating OT-IT convergence capabilities across multi-site deployments. Watch for FDA 21 CFR Part 11 audit enforcement intensity as inflection signal for compliance-service premium expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| GPU Virtualization Partnership | NVIDIA vGPU alliances with automotive OEMs secure multi-year allocation commitments for design workstation workloads. |
| Sovereign Cloud Certification | BSI IT-Grundschutz compliance enables German Mittelstand procurement against GDPR data residency mandates. |
| Container-Based Edge Deployment | Lightweight runtime isolation reduces infrastructure overhead for Stuttgart automotive suppliers' temporary inspection stations. |
| FDA Validation Service Bundling | Audit-trail documentation packages capture premium pricing from pharmaceutical manufacturers in New Jersey. |
| Industrial Systems Integrator Acquisition | Channel control in Bavaria accelerates recurring revenue capture from maintenance contract bundling. |
Research Methodology
Multi-period observation of hyperscaler capex disclosures, GPU allocation patterns, and manufacturing IT procurement cycles anchored the trend analysis, supplemented by interviews with virtualization platform engineers, industrial systems integrators, manufacturing CIOs, and regulatory compliance officers at FDA-regulated facilities. Secondary validation drew from SEC 10-K filings, BSI IT-Grundschutz certification databases, CDSCO medical device registration records, and cloud provider sustainability disclosures. Bottom-up deployment counts across automotive, pharmaceutical, and electronics manufacturing segments were triangulated against top-down infrastructure spending estimates.
Input-output matrices mapped virtual desktop instance provisioning to end-user workload requirements across deployment model, solution type, organizational scale, and technology substrate dimensions. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion across the analysis window. Forecast inputs incorporated GPU supply elasticity assumptions, NIST cybersecurity framework adoption trajectories, and PLI scheme facility construction timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to sovereign cloud mandate enforcement, NVIDIA manufacturing capacity expansion, and OT-IT convergence skill availability. Outputs reflect documented assumptions regarding regulatory compliance cost trajectories and hyperscaler pricing discipline. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Data As a Service (Daas) Market
Digital Solutions
North America IT Asset Disposition Market
Digital Solutions
Email Deliverability Tools Market
Digital Solutions
GCC and Africa ICT Market
Digital Solutions
Change and Configuration Management Market
Digital Solutions
Business Transcription Market
Digital Solutions
Japan E-Invoicing Market
Digital Solutions
Procure-To-Pay Solutions Market
Digital Solutions
Global Assistive Technologies for Visually Impaired Market
Digital Solutions
Global Application Container Market
Digital Solutions
Europe Data Virtualization Market
Digital Solutions
Digital Signage Systems Market
Digital Solutions
Workspace As a Service Market
Digital Solutions
Smart Dictation Systems Market
Digital Solutions
Real-Time (Graphics and Video) Rendering Solutions Market
Digital Solutions
Mexico Digital Twin Market