
 End-User Computing (EUC) Market | 2026-2036
End-User Computing (EUC) Market Size, Share, and Industry Trends Forecast 2026-2036
End-User Computing (EUC) Market Analysis
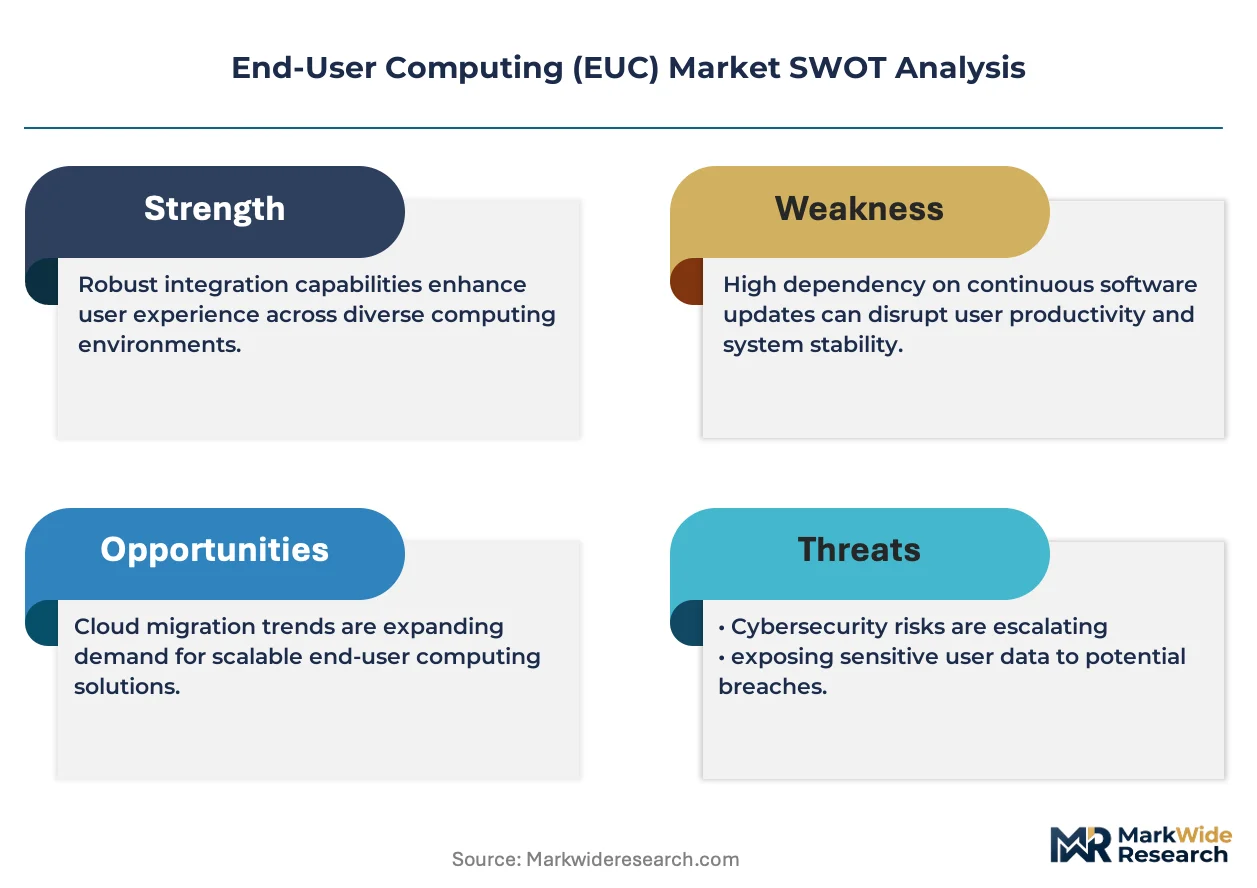
ISO/IEC 27001 certification is redrawing competitive boundaries in the EUC landscape. Microsoft Corporation leverages its Azure Virtual Desktop ecosystem to anchor enterprise cloud migration strategies. Citrix Systems specializes in high-performance application virtualization for regulated industries. VMware competes through its cross-cloud workspace platform that unifies endpoint management across heterogeneous environments.
End-User Computing encompasses the technologies, platforms, and services that deliver desktop environments, applications, and data to individual workers across distributed locations, typically relying on centralized server infrastructure with client-side rendering protocols such as HDX, PCoIP, or RDP to maintain sub-50ms latency thresholds. Cloud-based deployment models now capture the fastest expansion as enterprises retire legacy on-premises data centers, while thin client hardware maintains steady replacement cycles in manufacturing floor environments where thermal tolerance and fanless operation matter. Managed services within the service type dimension concentrate margin pools, since multi-tenant monitoring and patch orchestration generate recurring revenue with lower customer acquisition costs than perpetual license models.
FDA 21 CFR Part 11 requirements shape product validation protocols for EUC systems deployed in pharmaceutical quality assurance labs, while HIPAA security rules govern endpoint encryption standards for healthcare virtual desktop pools. NIST SP 800-207 zero-trust architecture guidance is forcing vendors to redesign session brokers around continuous device posture verification rather than perimeter-based network access. Stakeholders must evaluate whether their current endpoint management stack can satisfy emerging supply chain attestation requirements without fragmenting user experience across operating system types.
Market Dynamics
NIST SP 800-207 zero-trust mandates are compressing legacy perimeter-based architectures into continuous verification models, forcing vendors to rebuild session brokers around device posture signals rather than network location.
Growth Catalysts
- HIPAA Security Rule:Healthcare providers in the United States are expanding virtual desktop pools to encrypt endpoints for remote clinical access.
- Remote clinical workflows:Hospital systems deploy centralized infrastructure to support distributed diagnostic teams accessing imaging workstations.
- Thin client hardware:Manufacturing floors in Germany adopt fanless thermal-tolerant devices for production line operator stations.
Market Restraints
- GPU supply concentration:Graphics processing unit allocation for VDI acceleration remains constrained by Taiwan foundry capacity.
- Latency thresholds:Sub-50ms rendering protocols require fiber proximity that rural infrastructure cannot guarantee.
- FDA 21 CFR Part 11:Pharmaceutical validation protocols extend deployment timelines for quality assurance lab environments.
Strategic Opportunities
- India enterprise modernization:Distributed workforce technology upgrades in Mumbai and Bangalore create greenfield VDI installations.
- ISO/IEC 27001 convergence:Certification-driven procurement favors vendors with unified endpoint management across heterogeneous environments.
- Cloud-native session brokers:Continuous device posture verification architectures displace legacy gateway appliances in financial services.
Industry Challenges
- HDX/PCoIP/RDP protocol integration:IT teams struggle to unify monitoring across mixed rendering stacks without fragmenting user experience.
- Multi-tenant patch orchestration:Managed service providers face operational complexity coordinating updates across client environments with divergent compliance calendars.
- Supply chain attestation:Hardware vendors must document component provenance for federal procurement without disclosing proprietary supplier relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | End-User Computing (EUC) Market |
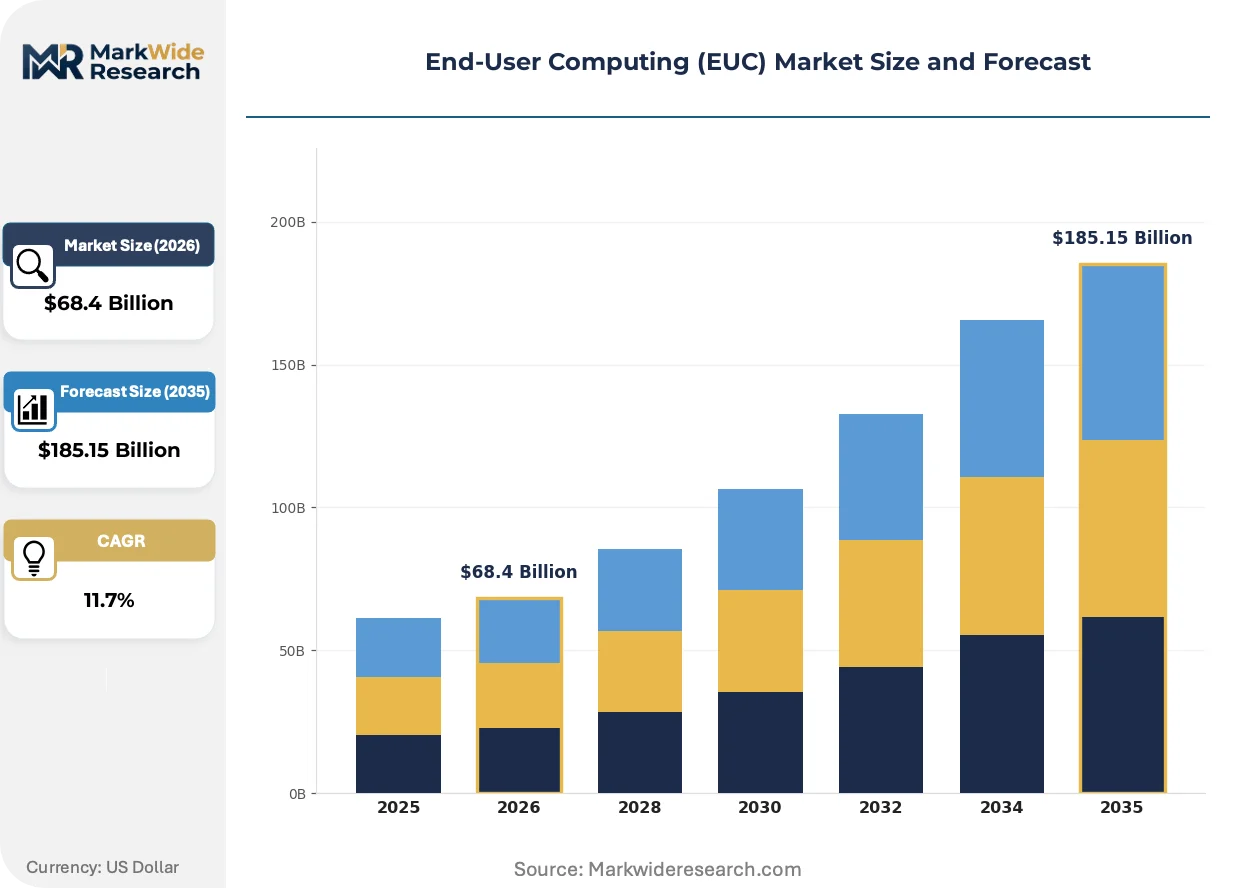
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $185.15 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktops, Laptops, Tablets, Thin Clients Deployment Model: On-Premises, Cloud-Based, Hybrid, Virtual Industry Vertical: Education, Healthcare, BFSI, Manufacturing Service Type: Managed Services, Consulting, Support Services, Training |
| Companies Covered | VMware, Citrix Systems, Microsoft Corporation, Amazon Web Services, IBM Corporation, Dell Technologies, Cisco Systems, Oracle Corporation, Nutanix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
End-User Computing (EUC) Market Emerging Trajectories
Protocol abstraction layers are dissolving traditional boundaries between on-premises data centers and edge rendering nodes, enabling workload portability that redefines where compute cycles execute.
GPU virtualization is fragmenting the high-performance workstation market by allowing engineering teams to access CAD and simulation tools through browser-based streams rather than dedicated local hardware. Automotive design studios in Stuttgart and aerospace firms in Toulouse now provision rendering capacity on demand. This compression of capital expenditure into operational spending is fragmenting the traditional workstation vendor ecosystem.
GDPR data residency requirements are compelling European enterprises to maintain session broker infrastructure within EU sovereign cloud regions. Germany's BSI IT-Grundschutz certification now governs federal procurement of virtual desktop services. Financial institutions in Frankfurt are retrofitting existing deployments to satisfy these mandates ahead of contract renewals.
Consumption-based licensing models are replacing perpetual seat agreements as enterprise buyers demand elasticity for seasonal workforce fluctuations. Channel partners in the United States are unbundling professional services from software subscriptions to capture margin from implementation complexity. This reconfiguration is most visible among healthcare systems expanding telemedicine infrastructure post-pandemic.
End-User Computing (EUC) Market Segmentation
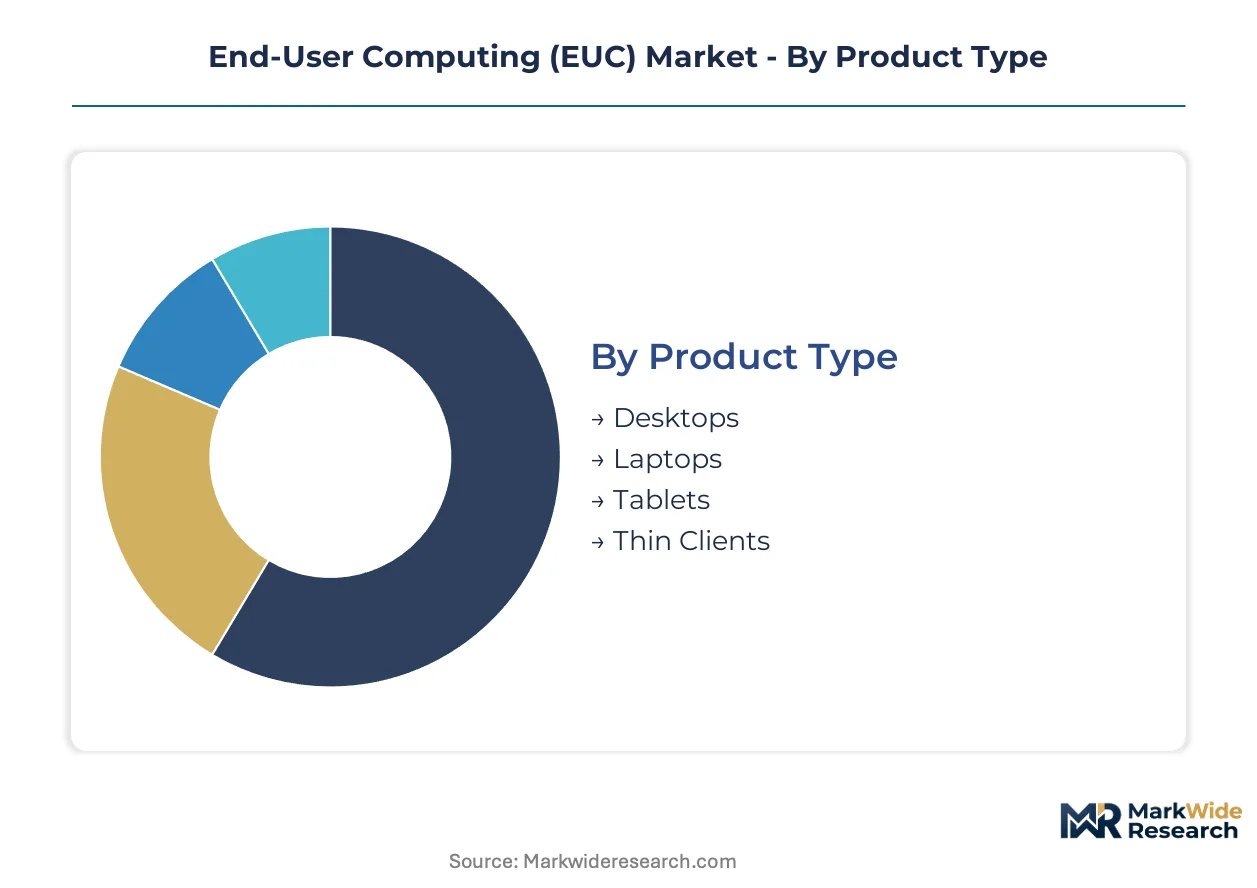
End-User Computing segmentation reveals how deployment choices, hardware form factors, and service wrappers fragment procurement decisions across regulated industries. Buyers optimize around latency requirements, compliance calendars, and workforce mobility patterns rather than uniform technology stacks.
Product Type:
Domestic manufacturing concentration in Taiwan and China shapes supply availability, while German and Indian assembly plants serve regional demand with customized thermal specifications.
- Desktops:Tower and small-form-factor units persist in financial trading floors and engineering workstations where local GPU acceleration outperforms remote rendering. Demand concentrates in United States banking hubs and Stuttgart automotive design centers constrained by sub-50ms latency requirements for real-time simulation.
- Laptops:Enterprise-grade mobile endpoints with hardware-rooted security modules dominate hybrid workforce procurement. Healthcare systems in Germany and BFSI firms in Mumbai prioritize these for clinical and trading floor mobility where NIST zero-trust mandates require continuous device attestation.
- Tablets:Ruggedized field-service devices with stylus digitizers serve inspection and inventory workflows in manufacturing environments across India and Germany.
- Thin Clients:Fanless thermal-tolerant hardware anchors production line operator stations in German automotive plants and Indian electronics assembly floors where dust and vibration exclude rotating media.
Desktops hold the largest share; momentum sits with thin clients as manufacturing automation accelerates.
Deployment Model:
Cost tier stratification separates capital-intensive on-premises builds from operational expenditure models favored by seasonal workforce planners.
- On-Premises:Legacy data center installations retain traction in pharmaceutical quality labs and defense contractors where FDA 21 CFR Part 11 validation and air-gapped security override cloud economics. German chemical manufacturers maintain these for process control continuity.
- Cloud-Based:Azure Virtual Desktop and competitive platforms capture fastest expansion as United States healthcare systems retire aging Citrix farms. HIPAA encryption requirements and NIST SP 800-207 zero-trust architectures drive broker redesigns around continuous verification rather than perimeter gates.
- Hybrid:Split workloads between local rendering and burst capacity to sovereign cloud regions satisfy GDPR residency mandates for Frankfurt financial institutions.
- Virtual:Pure browser-delivered sessions abstract protocol dependencies, enabling India-based IT services firms to standardize delivery across heterogeneous client estates.
On-premises retains the largest installed base; cloud-based deployments are gaining share fastest among regulated industries.
Industry Vertical:
Application-specific compliance calendars and endpoint durability requirements reshape vendor qualification criteria across buyer categories.
- Healthcare:Virtual desktop pools encrypt diagnostic imaging access for distributed radiology teams in United States hospital systems. HIPAA Security Rule mandates and remote clinical workflow expansion drive centralized infrastructure investment.
- BFSI:Trading floors in Mumbai and Frankfurt require sub-50ms rendering protocols for real-time market data visualization, favoring low-latency on-premises or edge deployments over distant cloud regions.
- Manufacturing:Stuttgart automotive plants and Indian electronics assembly floors deploy fanless thin clients to production lines where thermal tolerance and vibration resistance outweigh compute density.
- Education:Seasonal enrollment fluctuations favor consumption-based licensing for student device fleets, with German vocational institutes and Indian technical universities leading modernization cycles.
Healthcare holds the largest share; manufacturing is climbing the fastest as industrial automation deepens endpoint deployment.
Service Type:
Customer-type stratification separates recurring-revenue managed services from project-based consulting engagements with divergent margin profiles.
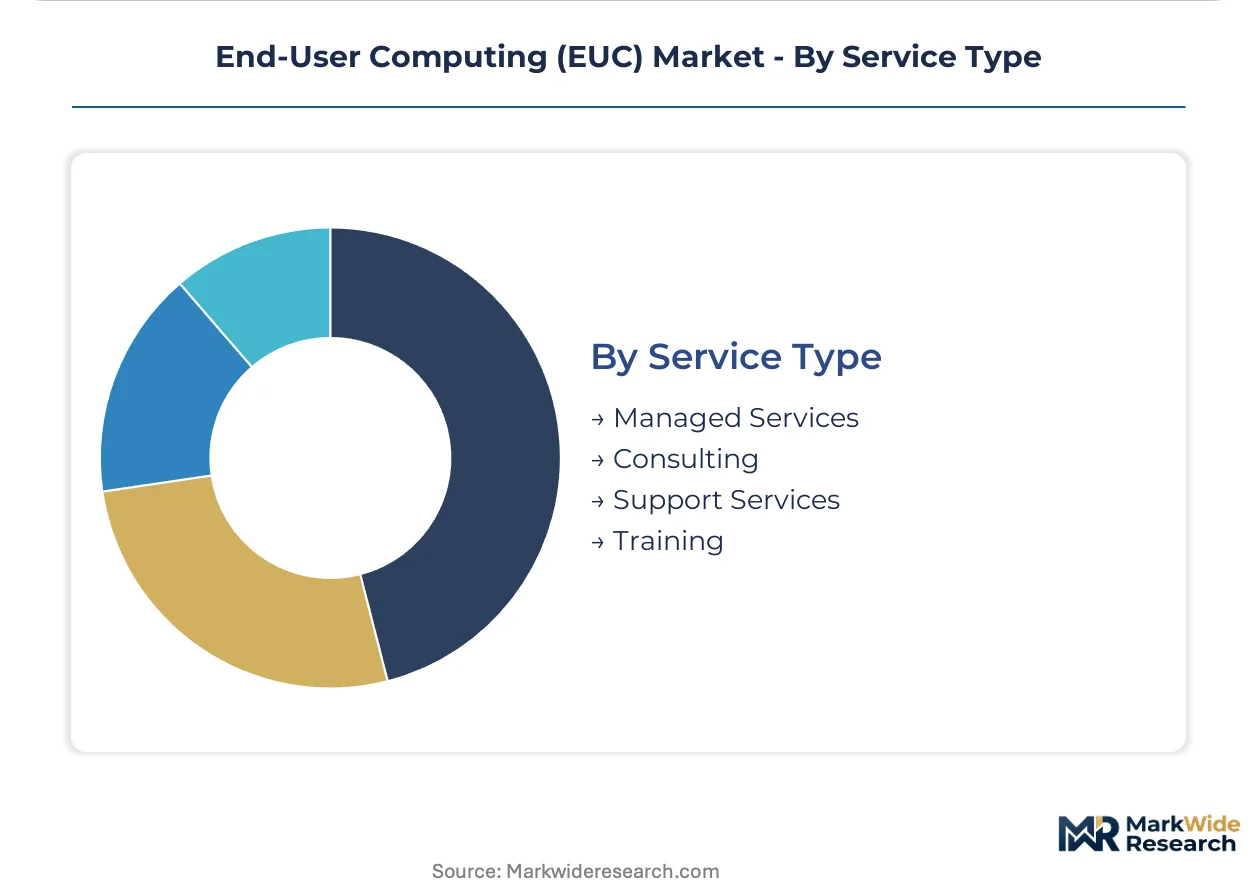
- Managed Services:Multi-tenant monitoring and patch orchestration generate recurring revenue with lower customer acquisition costs than perpetual licenses. United States healthcare systems and German manufacturing conglomerates outsource endpoint lifecycle management to capture operational predictability.
- Consulting:Migration architecture and compliance gap assessments command premium day rates for NIST zero-trust redesigns and FDA validation protocol development in pharmaceutical environments.
- Support Services:Tiered response commitments with geographic escalation paths serve distributed workforces across India and Germany where local language support contracts influence renewal decisions.
- Training:Certification programs for IT administrators on hybrid cloud broker administration expand addressable market for channel partners in United States and Indian markets.
Managed services holds the largest share; consulting is expanding most quickly as zero-trust mandates force architectural redesigns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NIST SP 800-207 zero-trust mandates and HIPAA Security Rule enforcement are accelerating cloud migration decisions across enterprise buyers. Healthcare providers and financial institutions in multiple jurisdictions are modernizing distributed workforce infrastructure to satisfy regulatory compliance deadlines.
United States
Hospital systems deploy virtual desktop pools to encrypt endpoints for remote radiology teams accessing diagnostic imaging. HIPAA Security Rule mandates and FDA 21 CFR Part 11 validation protocols govern pharmaceutical quality lab deployments. Healthcare concentration in Boston and Minneapolis drives centralized infrastructure investment for clinical workflow virtualization.
Germany
Automotive manufacturers adopt fanless thin clients for production line operator stations where thermal tolerance and vibration resistance matter. BSI IT-Grundschutz certification now governs federal procurement of virtual desktop services. Stuttgart design studios provision GPU virtualization on demand for CAD and simulation workloads.
India
BFSI firms in Mumbai and IT services companies in Bangalore prioritize enterprise-grade mobile endpoints with hardware-rooted security modules. RBI cybersecurity guidelines and SEBI data localization requirements shape broker architecture decisions. Greenfield VDI installations concentrate in Hyderabad and Pune as distributed workforce technology upgrades accelerate.
United Kingdom
Financial institutions in London retrofit existing deployments to satisfy GDPR data residency mandates ahead of contract renewals. FCA operational resilience requirements pressure trading floors to maintain sub-50ms rendering protocols. Edinburgh and Manchester emerge as secondary hubs for managed service provider delivery centers.
Japan
Manufacturing conglomerates in Nagoya and Osaka maintain hybrid deployments splitting workloads between local rendering and burst capacity. METI cybersecurity frameworks and JIS standards govern industrial endpoint specifications. Tokyo financial institutions evaluate cloud-native session brokers for continuous device posture verification.
End-User Computing (EUC) Market Vendor Landscape
Listed leaders compete with private specialists across deployment architecture and compliance certification dimensions. The vendor base organizes around three tiers: hyperscale cloud platforms with integrated virtual desktop stacks, independent software vendors specializing in high-performance application virtualization, and hardware-integrated systems providers. Strategic archetypes include protocol-agnostic brokers, sovereign cloud specialists, and managed service aggregators. Dominant competitive moves encompass M&A to acquire zero-trust orchestration capabilities and geographic expansion into India and Germany to capture modernization cycles.
Within the hyperscale platform tier, Microsoft Corporation and Amazon Web Services exemplify cloud-native delivery models that displace legacy on-premises farms. VMware occupies a position representing cross-cloud workspace unification across heterogeneous environments. Citrix Systems sits within the high-performance virtualization specialist archetype, serving regulated industries with latency-sensitive workloads. These three anchors demonstrate how certification-driven procurement and protocol abstraction are reshaping vendor qualification criteria across healthcare, BFSI, and manufacturing verticals.
| Leading Market Players |
|---|
| VMware |
| Citrix Systems |
| Microsoft Corporation |
| Amazon Web Services |
| IBM Corporation |
| Dell Technologies |
| Cisco Systems |
| Oracle Corporation |
| Nutanix |
| Others |
Supply Flow & Price Mechanics
Thin client hardware substitution for traditional desktop towers redraws procurement economics across German automotive floors and Indian electronics assembly lines, compressing capital expenditure into operational spending while shifting supply geography toward Taiwan semiconductor packaging and Chinese fanless enclosure manufacturing.
Pricing Analysis
Certification level (ISO/IEC 27001 versus BSI IT-Grundschutz versus FDA 21 CFR Part 11) creates the primary spread between premium and standard tiers, with validated pharmaceutical lab environments commanding substantial premiums over general enterprise deployments. Consumption-based SaaS licensing now dominates cloud-based virtual desktop procurement, displacing perpetual seat agreements as United States healthcare systems demand elasticity for seasonal telemedicine fluctuations. Price erosion runs through thin client hardware tiers due to Taiwanese foundry capacity constraints and competing GPU virtualization alternatives. Healthcare providers exhibit highest price sensitivity among regulated buyers, while defense contractors accepting air-gapped on-premises builds demonstrate lowest elasticity.
Supply Chain Analysis
Just-in-time component flows predominate for standardized thin client assembly, whereas strategic stockpiling of GPU accelerators and secure enclave chips characterizes defense and pharmaceutical buyer procurement. Manufacturing concentration spans Taiwan (semiconductor packaging), China (fanless thermal enclosures), and Germany (customized industrial-grade assembly). Raw material dependencies center on advanced node GPUs, hardware security modules, and rare-earth magnet supply for fanless thermal management. Single-source vulnerability in Taiwan foundry capacity for VDI acceleration chips presents structural risk. Distribution runs through direct OEM relationships for large healthcare systems and tier-one automotive manufacturers, with channel partners serving mid-market education and BFSI segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where NIST zero-trust mandates and FDA validation protocols create switching costs that cement incumbent positions across healthcare and pharmaceutical verticals.
For Market Incumbents: Shield installed base through ISO/IEC 27001 certification maintenance and continuous device posture verification architecture upgrades that align with NIST SP 800-207 mandates. Deepen backward integration into secure enclave chip sourcing to mitigate Taiwan foundry concentration risk. Channel control through managed service provider certification programs captures recurring revenue pools as healthcare systems outsource endpoint lifecycle management. For New Entrants and Emerging Players: Differentiate on sovereign cloud specialization for GDPR-bound European financial institutions in Frankfurt and London retrofitting existing deployments. Target greenfield VDI installations in Hyderabad and Pune where RBI cybersecurity guidelines and SEBI data localization requirements create procurement windows for compliant newcomers. Go-to-market through IT services firm partnerships leverages existing Bangalore channel relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed managed service providers holding multi-tenant monitoring platforms and patch orchestration capabilities across United States healthcare systems. Long-term viability hinges on cloud-native session broker architectures displacing legacy gateway appliances. Watch cloud migration acceleration among pharmaceutical quality labs as FDA 21 CFR Part 11 validation protocol modernization signals inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Trust Architecture Migration | NIST SP 800-207 compliance repositions session brokers for United States federal healthcare procurement. |
| GPU Virtualization Platform Launch | Browser-based CAD streaming fragments Stuttgart automotive design studio workstation vendor ecosystems. |
| Sovereign Cloud Partnership | EU data residency capabilities capture Frankfurt financial institution contract renewal cycles. |
| Managed Service Provider Acquisition | Multi-tenant patch orchestration assets generate recurring revenue with lower customer acquisition costs. |
| Fanless Thin Client Manufacturing Scale-Up | Thermal-tolerant production line deployments deepen penetration across German automotive floors. |
Methodological Framework
A standing panel of virtual desktop infrastructure architects, healthcare IT procurement officers, pharmaceutical quality systems managers, and thin client hardware procurement leads provided ongoing calibration across the study period. Primary interview data combined with secondary validation from SEC 10-K filings, hyperscaler capex disclosures, FDA 483 inspection records, and BSI certification databases. Bottom-up deployment sizing and top-down market aggregation triangulated segment-level estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled deployment model, industry vertical, service type, and protocol abstraction maturity as core segmentation dimensions. CAGRs derived from regression analysis of historical adoption curves and regulatory compliance deadline clustering. GPU supply constraints and zero-trust mandate implementation timelines served as industry-specific forecast inputs.
Material uncertainties — Taiwan foundry capacity allocation shifts, NIST guidance revisions, and HIPAA enforcement intensity changes — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory compliance calendar adherence and enterprise cloud migration velocity. Practitioners should keep alternative scenarios live as sovereign data residency requirements and supply chain attestation protocols evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Utility Cases Market
Digital Solutions
Software Defined Application and Infrastructure Market
Digital Solutions
Master Data Management Market
Digital Solutions
UAE Digital Twin Market
Digital Solutions
Thin Client Market
Digital Solutions
Interactive Response Technology Market
Digital Solutions
Assortment and Space Optimization (ASO) Market
Digital Solutions
Manufacturing Operations Management Solutions Market
Digital Solutions
IT Service Management Market
Digital Solutions
Cloud Based Manufacturing Market
Digital Solutions
Global Interactive Whiteboard (IWB) Market
Digital Solutions
Canada Digital Twin Market
Digital Solutions
Global Workflow Orchestration Market
Digital Solutions
Legal Transcription Market
Digital Solutions
Graphical Situational Display Market
Digital Solutions
Reverse Logistics Visibility and Disposition Optimization Platforms Market