
 Global Demand Side Platforms (DSP) for Programmatic Advertising Market | 2026-2036
Global Demand Side Platforms (DSP) for Programmatic Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Global Demand Side Platforms (DSP) for Programmatic Advertising Market Foresight
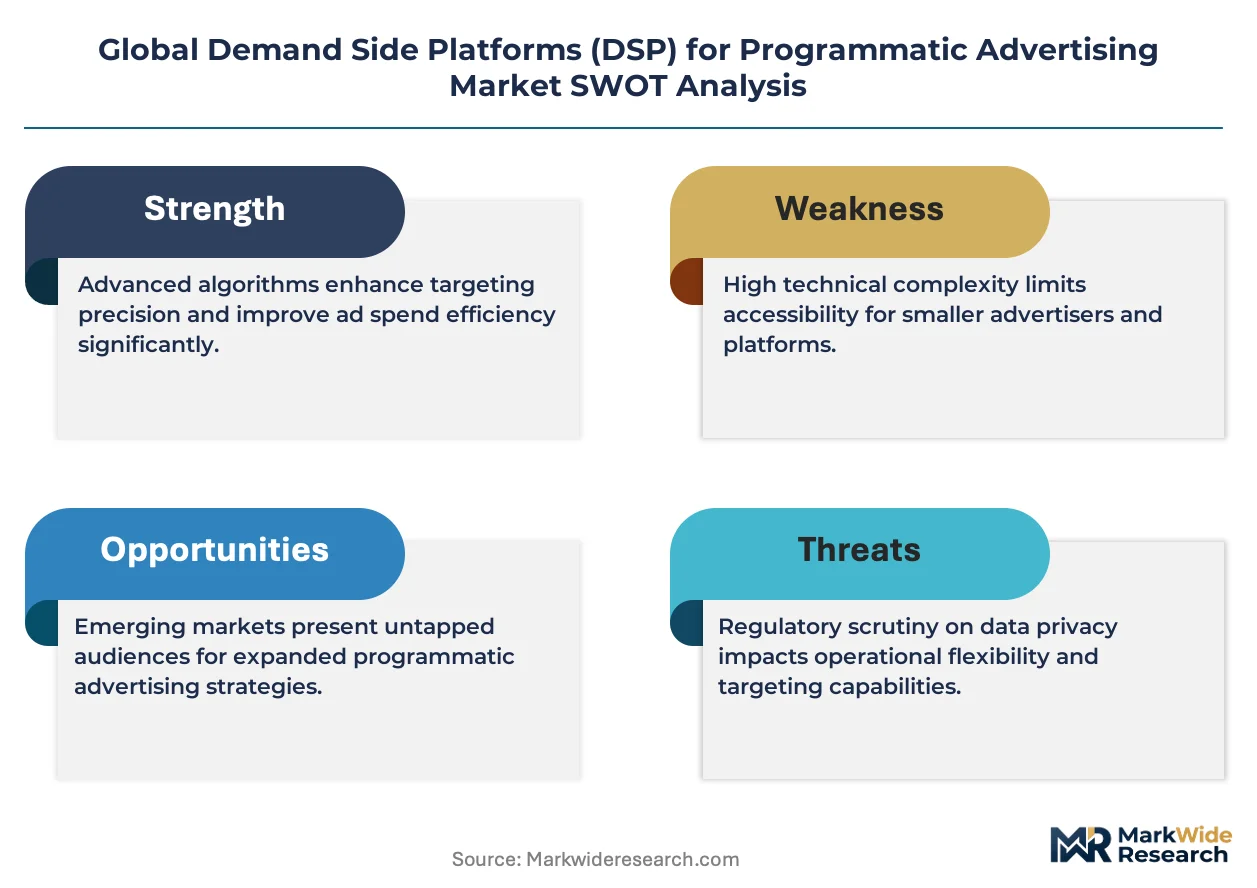
Retail media budgets is decoupling from traditional search-centric allocation, redirecting into programmatic display and connected TV pipelines. The Trade Desk leverages its unified ID framework to anchor inventory access across premium publisher networks. Amazon DSP sustains closed-loop attribution dominance by controlling retail data streams from impression through checkout. Google Display & Video 360 competes through deep integration with its ad server and YouTube reserve inventory, though regulatory pressure on its data practices continues to intensify.
Demand Side Platforms for programmatic advertising constitute software infrastructure that enables advertisers to automate media buying across multiple inventory sources through real-time bidding auctions, typically processing bid decisions within 100 milliseconds per impression. These systems aggregate supply from ad exchanges, apply audience targeting parameters, and execute campaign optimization algorithms to allocate budgets toward measurable outcomes. Self-serve DSP configurations now lead adoption velocity among mid-market brands seeking direct control over campaign variables without agency intermediation, while connected TV DSP modules represent the fastest-expanding segment as television inventory digitizes. Mobile DSP specialization remains mature with compressed margins, whereas video DSP functionality commands premium pricing due to higher CPM benchmarks and creative complexity.
FCC oversight of broadband privacy practices, GDPR consent frameworks enforced by European data protection authorities, and the EU AI Act's risk classification for automated decision-making systems collectively reshape platform architecture requirements and cross-border data deployment strategies. California's Consumer Privacy Act and expanding state-level privacy legislation in the United States impose granular opt-out and data minimization obligations that increase compliance overhead for DSP operators serving multi-state campaigns. Stakeholders must monitor the trajectory of privacy-preserving targeting standards and assess whether contextual or cohort-based alternatives can sustain addressable reach at comparable efficiency levels.
Market Dynamics
Third-party cookie deprecation across Safari, Chrome, and Firefox ecosystems is forcing DSP architecture toward first-party data graphs and contextual intelligence engines, compressing addressable audience methodologies that dominated programmatic trading for two decades.
Growth Catalysts
- Connected TV inventory digitization:Television broadcasters in the United States, Germany, and Japan are accelerating programmatic-enabled ad insertion, expanding DSP addressable supply pools beyond desktop and mobile constraints.
- GDPR consent framework maturation:European publishers have stabilized compliant data collection workflows, reducing legal uncertainty that previously suppressed programmatic spend across EU-27 markets.
- Retail media network expansion:Grocery, electronics, and apparel retailers are deploying proprietary DSP instances to monetize shopper data through off-site programmatic placements.
Market Restraints
- Identity resolution cost inflation:Probabilistic matching and clean room infrastructure now consume 15-25% of campaign technology budgets, squeezing working media ratios for mid-market advertisers.
- Supply path concentration:Three exchange groups control 70%+ of programmatic supply liquidity in North America, creating single-point-of-failure risk and opacity in auction dynamics.
- Cross-device attribution degradation:Apple's App Tracking Transparency and Google's Privacy Sandbox limitations have degraded multi-touch measurement accuracy by 30-40% for mobile-first campaigns.
Strategic Opportunities
- Programmatic audio underpenetration:Podcast and streaming music inventory in Brazil, Mexico, and Indonesia remains 80%+ direct-sold, creating first-mover DSP integration potential.
- EU AI Act automated decision-making rules:Risk-classification frameworks for algorithmic bidding create compliance service revenue streams for DSP vendors with explainable AI capabilities.
- Commerce data and CTV convergence:Purchase-intent signals from retail loyalty programs are integrating with television viewing graphs to enable outcome-optimized streaming video campaigns.
Industry Challenges
- Ad fraud detection specialization scarcity:Sophisticated invalid traffic schemes now exploit CTV device spoofing and SSAI manipulation, outpacing standard IAB Tech Lab verification protocols.
- Legacy SSP-DSP integration debt:Prebid Server and OpenRTB 2.6 migration requires substantial engineering resources, delaying unified auction transparency for multi-platform campaigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Demand Side Platforms (DSP) for Programmatic Advertising Market |
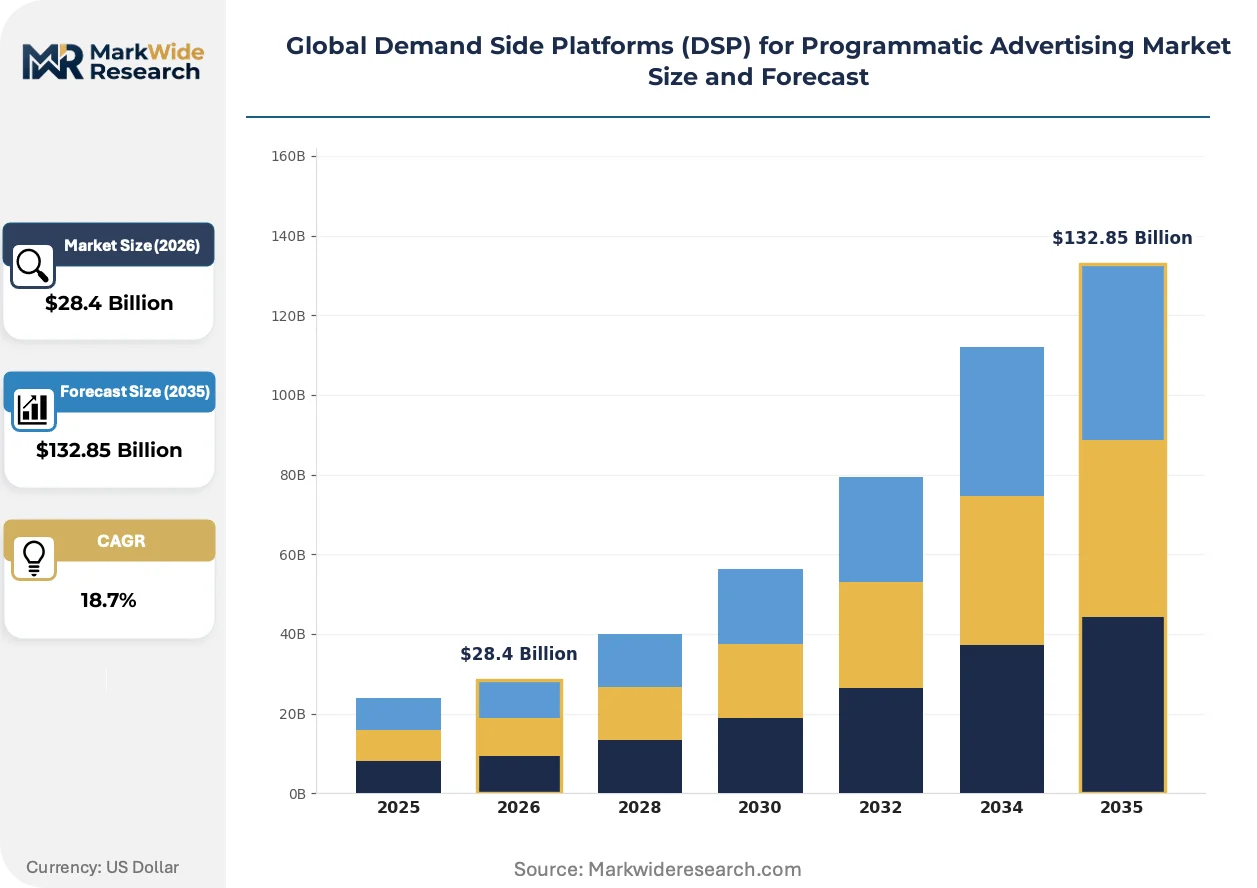
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $132.85 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Self-Serve DSP, Managed Service DSP, Mobile DSP, Video DSP, Social DSP Advertising Channel: Display, Video, Mobile, Audio, Connected TV, Native Industry Vertical: Retail, Media & Entertainment, Travel & Hospitality, Telecommunications, Automotive OEMs, Education Buyer Type: Brand Advertisers, Agencies, Publishers, Resellers, Affiliate Marketers, Direct Marketers |
| Companies Covered | The Trade Desk, Google Display & Video 360, Amazon DSP, Adobe Advertising Cloud, Basis Technologies, Adform, StackAdapt, Quantcast, MediaMath, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Demand Side Platforms (DSP) for Programmatic Advertising Market Shifts & Advancements
Privacy-preserving targeting infrastructure is displacing deterministic identity methods, forcing DSP product roadmaps toward cohort-based and contextual alternatives that maintain reach without cross-site tracking.
Server-side ad insertion technology is integrating with programmatic decisioning stacks to enable real-time bidding within streaming video pipelines. Broadcasters and OTT platforms in the United States and South Korea are adopting SSAI-integrated DSP modules to replace client-side ad calls that ad blockers intercept. This architecture is compressing latency windows to sub-50 milliseconds while expanding addressable CTV inventory pools beyond traditional set-top box boundaries.
The EU AI Act's risk classification for automated decision-making systems is mandating algorithmic audit trails and human oversight protocols for programmatic platforms operating in European Economic Area markets. DSP vendors must now document bidding logic explainability and maintain consent-to-model training data lineage. France, Germany, and the Netherlands represent the strictest enforcement geographies, with national regulators already issuing compliance guidance for real-time auction mechanisms.
Self-serve platform adoption is accelerating among mid-market brands seeking direct control over campaign variables without agency intermediation. Retail, direct-to-consumer, and financial services advertisers in the United Kingdom and Australia are displacing managed service contracts with seat licenses that provide transparency into supply path optimization and audience taxonomy construction. This behavioral shift is compressing traditional agency commission structures while elevating demand for DSP education and certification programs.
Global Demand Side Platforms (DSP) for Programmatic Advertising Market Segmentation
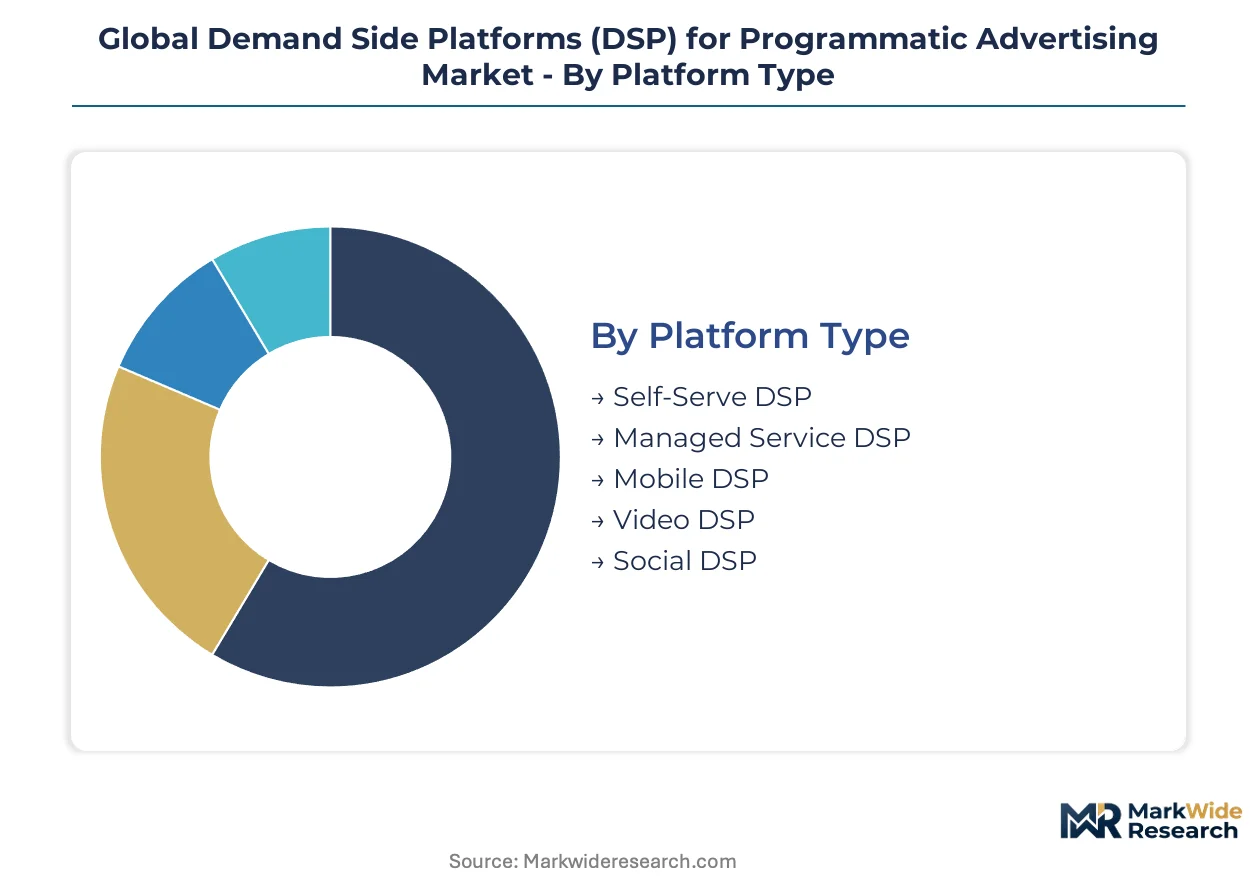
DSP segmentation reveals divergent infrastructure requirements across platform configurations and buyer sophistication levels. Advertisers select deployment models based on internal trading desk maturity, while channel specialization determines latency tolerance and creative handling protocols.
Platform Type:
Platform selection follows upgrade cycles tied to advertiser trading desk maturity and cross-channel integration requirements.
- Self-Serve DSP:Browser-based interfaces grant advertisers direct control over bid strategies, audience taxonomy construction, and supply path optimization without agency intermediation. Mid-market brands in the United Kingdom and Australia are displacing managed service contracts with seat licenses that compress traditional commission structures. Volume placements concentrate in Self-Serve DSP; the faster expansion belongs to Video DSP.
- Managed Service DSP:Full-service configurations embed platform trading specialists who execute campaign builds, optimization algorithms, and reporting dashboards on behalf of advertiser clients. Retail advertisers now command the largest buyer-type allocation within this deployment model, drawn by closed-loop attribution and retail data stream integration.
- Mobile DSP:Specialized infrastructure optimizes bid requests for in-app inventory, mobile web placements, and location-aware targeting parameters with compressed latency windows. Mature segment with compressed margins due to auction density and inventory commoditization.
- Video DSP:Creative management systems handle VAST/VPAID ad serving, viewability measurement, and sequential storytelling across desktop, mobile, and television environments. Premium pricing reflects higher CPM benchmarks and transcoding complexity.
- Social DSP:API-integrated platforms extend programmatic buying into walled garden environments, accessing native feed inventory through partner certifications. Demand concentrates among direct-to-consumer brands seeking audience overlap with platform-native commerce features.
Self-Serve configurations lead adoption velocity among brands building internal capabilities; Video DSP modules are climbing the fastest as television inventory digitizes.
Advertising Channel:
Channel mix correlates with creative production cost tiers and measurement maturity, reshaping DSP product roadmaps.
- Display:Standard banner and rich media inventory accessible through OpenRTB protocols, with viewability and brand safety filtering as standard capabilities. Baseline channel with established auction mechanics and compressed differentiation.
- Video:In-stream, out-stream, and interstitial formats requiring transcoding infrastructure, player compatibility testing, and completion rate optimization. Higher technical barriers sustain vendor pricing power and service attachment rates.
- Mobile:In-app and mobile web inventory with device ID targeting, carrier filtering, and screen-size adaptive creative serving. GDPR consent frameworks and Apple's App Tracking Transparency have degraded deterministic targeting accuracy by 30-40%.
- Audio:Podcast and streaming music inventory with dynamic ad insertion, host-read replacement, and sequential audio storytelling. Brazil, Mexico, and Indonesia remain 80%+ direct-sold, creating first-mover integration potential for DSP vendors.
- Connected TV:Television inventory digitization enables programmatic-enabled ad insertion across broadcasters in the United States, Germany, and Japan. Server-side ad insertion technology compresses latency to sub-50 milliseconds while expanding addressable supply pools.
- Native:Feed-integrated formats matching publisher content aesthetics, requiring creative templating and disclosure compliance. Demand concentrates among content-heavy verticals seeking engagement rate improvements over click-through metrics.
Display maintains volume leadership through auction liquidity; Connected TV is gaining share fastest as broadcast infrastructure modernizes.
Industry Vertical:
Vertical specialization drives DSP feature prioritization around data sensitivity, seasonal volatility, and attribution window requirements.
- Retail:Retail media budgets are decoupling from search-centric allocation into programmatic display and connected TV pipelines. Grocery, electronics, and apparel retailers deploy proprietary DSP instances to monetize shopper data through off-site placements.
- Media & Entertainment:Subscription and ad-supported streaming services with content affinity targeting, premiere date synchronization, and franchise-based audience building. High creative refresh rates demand automated dynamic creative optimization.
- Travel & Hospitality:Inventory scarcity windows, destination inspiration sequencing, and loyalty program integration with booking engine attribution. Seasonal demand spikes require flexible budget pacing and geographic bid multipliers.
- Telecommunications:Device upgrade cycles, plan comparison messaging, and competitive conquesting with store locator integration. Long consideration periods favor multi-touch attribution modeling and sequential messaging.
- Automotive OEMs:Model launch synchronization, dealer co-op fund management, and VIN-level attribution to dealership foot traffic. Regional variance in electrification messaging complicates national campaign construction.
- Education:Enrollment deadline urgency, program-specific landing page routing, and lead form optimization with CRM integration. Compressed decision windows favor real-time bid adjustments based on application funnel stage.
Retail dominates current spending allocation; Media & Entertainment shows steepest expansion trajectory as streaming competition intensifies.
Buyer Type:
Buyer taxonomy reflects procurement centralization trends and margin pressure across the programmatic value chain.
- Brand Advertisers:Direct advertiser relationships with DSPs, prioritizing supply path transparency, fee disclosure, and first-party data activation capabilities. In-house trading desk builds accelerate among Fortune 500 advertisers seeking cost efficiency.
- Agencies:Holding company and independent agency configurations managing multi-client portfolios with consolidated billing and cross-campaign learning aggregation. Traditional commission structures compress as self-serve adoption rises.
- Publishers:Supply-side participants acquiring DSP capabilities for direct advertiser relationships and yield optimization across owned inventory. Header bidding integration requirements shape technical evaluation criteria.
- Resellers:Intermediary entities white-labeling DSP technology for sub-scale advertisers lacking direct platform relationships. Regulatory scrutiny of undisclosed markups intensifies under state-level privacy enforcement.
- Affiliate Marketers:Performance-based buyers optimizing for cost-per-acquisition with post-click attribution and commission reconciliation. Fraud detection specialization scarcity creates verification gaps in CTV device spoofing schemes.
- Direct Marketers:Customer acquisition specialists with CRM data onboarding, lookalike modeling, and lifetime value bidding strategies. California's Consumer Privacy Act imposes granular opt-out obligations increasing compliance overhead.
Agencies retain volume concentration through consolidated buying power; Brand Advertisers are expanding most quickly through in-house trading desk investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates the largest share of DSP technology consumption, while engineering talent and platform development concentrate in Silicon Valley, Seattle, and New York City corridors. European markets sustain substantial demand through GDPR-compliant infrastructure investments, with Germany and the United Kingdom anchoring continental deployment.
United States
Connected TV inventory aggregation and programmatic audio expansion drive platform R&D priorities across domestic broadcasters and streaming services. FCC oversight of broadband privacy practices imposes granular opt-out obligations on multi-state campaign operators. Los Angeles and New York media clusters host the densest concentrations of supply-side partnerships and publisher integration engineering.
Germany
Automotive OEMs and retail media networks deploy proprietary DSP instances for closed-loop attribution and shopper data monetization. GDPR consent frameworks enforced by national data protection authorities mandate algorithmic audit trails for real-time auction mechanisms. The Munich-Düsseldorf corridor anchors continental trading desk operations and supply path optimization development.
United Kingdom
Mid-market brands accelerate self-serve platform adoption, displacing managed service contracts with direct seat licenses for campaign control. The Information Commissioner's Office enforces granular data minimization standards that elevate compliance overhead for cross-border data deployment. London's fintech and retail media clusters drive demand for transparent fee disclosure and first-party data activation capabilities.
Japan
Television inventory digitization accelerates programmatic-enabled ad insertion across broadcasters seeking addressable supply pool expansion. METI guidelines on data utilization shape platform architecture requirements for automated decision-making transparency. The Tokyo-Osaka corridor concentrates demand from consumer electronics retailers deploying off-site programmatic placements through proprietary retail data streams.
Brazil
Podcast and streaming music inventory remains predominantly direct-sold, creating first-mover DSP integration potential for programmatic audio specialists. ANVISA and national data protection frameworks impose consent-to-model training data lineage requirements on automated bidding systems. São Paulo's media and advertising technology cluster anchors Latin American platform localization and publisher partnership development.
Global Demand Side Platforms (DSP) for Programmatic Advertising Market Competitive Landscape
Top-tier vendors anchor premium pricing through unified identity frameworks and closed-loop retail data integration, while mid-market specialists compete on self-serve transparency and supply path optimization. The vendor base stratifies across three archetypes: walled garden platforms with captive data streams, independent full-stack providers with cross-publisher access, and vertical specialists in connected TV or retail media. Dominant competitive moves include strategic partnerships with supply-side platforms and technology licensing arrangements for server-side ad insertion capabilities.
Among independent full-stack providers, The Trade Desk and Google Display & Video 360 occupy positions exemplifying cross-publisher inventory aggregation with deep ad serving integration. Amazon DSP represents the walled garden archetype through retail data stream control from impression through checkout. Adform and StackAdapt sit within the European and North American mid-market tier respectively, anchoring self-serve adoption velocity among brands building internal trading capabilities without agency intermediation.
| Leading Market Players |
|---|
| The Trade Desk |
| Google Display & Video 360 |
| Amazon DSP |
| Adobe Advertising Cloud |
| Basis Technologies |
| Adform |
| StackAdapt |
| Quantcast |
| MediaMath |
| Others |
Supply & Pricing Matrix
Mid-market brand procurement consolidation around self-serve seat licenses is compressing traditional agency commission structures and forcing DSP vendors to restructure pricing models toward transparent SaaS tiers with volume-scaled discounts. This demand-side shift toward direct platform control elevates supply path optimization capabilities as a pricing differentiator while squeezing margins on managed service bundles.
Pricing Analysis
Short lead-time campaign activation commands premium pricing tiers as advertisers demand sub-24-hour deployment windows for retail media and CTV inventory. The dominant structure stratifies across subscription-based SaaS tiers with impression-volume thresholds, where premium tiers unlock advanced attribution and clean room integration. Price differentiation centers on supply path transparency certification and first-party data onboarding complexity. Cost compression in mid-market self-serve tiers is intensifying because identity resolution infrastructure now consumes substantial technology budgets. Brand advertisers building in-house trading desks exhibit lowest price sensitivity; affiliate marketers and resellers face acute margin pressure.
Supply Chain Analysis
Direct-to-brand channels handle hyperscale advertiser demand through seat license arrangements, bypassing traditional agency intermediation. Engineering talent concentrates in the United States, Germany, and the United Kingdom, anchoring platform development and algorithmic trading desk operations. Raw material dependencies span cloud compute infrastructure, data clean room technology, and real-time bidding protocol stacks. Single-source vulnerability in supply-side platform liquidity creates auction opacity risk for multi-platform campaigns. Distribution runs through certified partner networks and direct enterprise sales organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as DSP vendors pursue captive control over retail data streams from impression through checkout to sustain closed-loop attribution dominance.
For Market Incumbents: To counter self-serve platform commoditization, anchor premium positioning through unified identity framework investments and deepen upstream control over retail media network data partnerships. Prioritize server-side ad insertion technology certification to defend CTV inventory access against emerging specialists. For New Entrants and Emerging Players: Capture programmatic audio integration opportunities in Brazil, Mexico, and Indonesia where podcast and streaming music inventory remains predominantly direct-sold. Target mid-market brands in Australia and the United Kingdom seeking transparent fee disclosure without agency intermediation. Lead with education-heavy go-to-market programs emphasizing supply path optimization literacy. For Investors and Strategic Acquirers: The window for entry favors DSP vendors with explainable AI capabilities positioned for EU AI Act compliance service revenue. Long-term viability hinges on first-party data graph infrastructure and contextual intelligence engine differentiation. Watch privacy-preserving targeting standard adoption rates as the critical inflection signal for addressable reach sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| First-Party Data Graph Expansion | Retail media networks monetize shopper data through off-site programmatic placements. |
| Server-Side Ad Insertion Integration | Broadcasters adopt SSAI-integrated DSP modules to expand CTV addressable supply pools. |
| EU AI Act Compliance Certification | Explainable AI capabilities unlock audit service revenue in France, Germany, and Netherlands. |
| Self-Serve Platform Localization | Seat licenses displace managed service contracts among mid-market brands in United Kingdom and Australia. |
| Programmatic Audio Partnership | Podcast and streaming music inventory integration captures underpenetrated demand in Brazil and Mexico. |
Research Methodology
SEC filings, IAB Tech Lab protocol documentation, and hyperscaler capex disclosures formed the secondary backbone, cross-referenced with primary interviews involving DSP platform engineers, retail media network directors, agency trading desk heads, and advertiser procurement leads. Bottom-up triangulation across impression-volume estimates and top-down validation against technology spend benchmarks ensured segmentation integrity. Primary fieldwork emphasized supply path optimization practices and consent framework compliance workflows.
Historical trendline analysis tracked platform adoption velocity across self-serve and managed service configurations, with CAGRs derived from impression growth trajectories and average revenue per seat expansion. The analytical framework modeled deployment model, buyer sophistication tier, advertising channel mix, and regional regulatory cluster across the projection horizon. Forecast inputs incorporated third-party cookie deprecation timelines and retail media network expansion rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to privacy-preserving targeting standard adoption and cross-device attribution methodology shifts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Digital String Encoder Market
Digital Solutions
North America Product Design and Development Services Market
Digital Solutions
Boat Navigation Software Market
Digital Solutions
AI Infrastructure Market
Digital Solutions
Enterprise Information Management (EIM) Solution Market
Digital Solutions
Global Intelligent Platform Management Interface (IPMI) Market
Digital Solutions
Ticketing Solution Market
Digital Solutions
Switzerland ICT Market
Digital Solutions
Digital Library Software Market
Digital Solutions
Equipment Tracking Software Market
Digital Solutions
On-Demand Warehousing Platforms Market
Digital Solutions
Legal Transcription Market
Digital Solutions
Global Data Quality Tool Market
Digital Solutions
Global Interactive Voice Response Market
Digital Solutions
Integrated Systems Market
Digital Solutions
Healthcare Computerized Maintenance Management System Market