
 Remote Integration Solutions Market | 2026-2036
Remote Integration Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Remote Integration Solutions Market Analytics
Modular service bundling is recalibrating how enterprises procure integration capabilities. MuleSoft leverages its API-led connectivity approach to anchor enterprise-grade deployments across Fortune 500 accounts. Workato competes through low-code automation templates that reduce implementation timelines for mid-market buyers. Zapier dominates the self-serve segment with pre-built connectors that extend platform reach without dedicated engineering resources.
Remote integration solutions encompass software architectures that enable disparate systems to exchange data and execute workflows across distributed environments, typically employing RESTful APIs, event-driven messaging protocols, and containerized middleware with sub-second latency thresholds. These configurations serve industrial and commercial purposes by eliminating manual data reconciliation and enabling real-time operational visibility across supply chains. Cloud Integration services lead the service type dimension as enterprises migrate legacy ETL pipelines to elastic infrastructure, while API Management captures disproportionate margin pools due to governance complexity and security certification requirements. The deployment landscape tilts toward Hybrid configurations as regulated industries retain sensitive processing on-premises while bursting transactional workloads to SaaS layers.
FDA 21 CFR Part 11 guidelines shape validation requirements for healthcare integrations, while HIPAA mandates encryption standards for protected health information traversing remote nodes. The EU AI Act imposes risk-classification obligations on automated decision-making workflows, compelling European enterprises to audit integration chains for algorithmic transparency. Stakeholders must monitor how NIST cybersecurity frameworks evolve to mandate zero-trust architecture in federal procurement, as this will reshape vendor qualification criteria and deployment patterns across government-facing segments.
Market Dynamics
Hybrid deployment architectures are fragmenting vendor control over integration pipelines as enterprises bifurcate sensitive workloads between sovereign on-premises infrastructure and elastic cloud bursts. This structural split is reconfiguring procurement patterns, margin pools, and compliance obligations across the competitive landscape.
Growth Catalysts
- EU AI Act risk-classification mandates:Automated decision-making workflows in European enterprises now require auditable integration chains, compelling investment in governance-ready middleware and API management layers.
- Automotive supply chain real-time connectivity:German industrial clusters demand sub-second latency for supplier coordination, driving deployment of event-driven messaging protocols across tiered manufacturing networks.
- Cloud-native ETL migration:Healthcare providers are accelerating replacement of legacy batch pipelines with elastic containerized infrastructure to support FHIR-based data exchange.
Market Restraints
- Specialized engineering talent scarcity:Shortage of architects proficient in zero-trust security frameworks and Kubernetes-native integration patterns inflates implementation timelines and service costs.
- Cross-border data localization requirements:Divergent sovereignty rules across national jurisdictions fragment platform architectures and complicate unified vendor offerings.
- Legacy system entrenchment:Decades-old on-premises ERP investments in regulated industries create technical debt that resists API abstraction without costly middleware layers.
Strategic Opportunities
- Sovereign cloud adoption in France:CNIL guidance and national cloud certification programs create protected market segments for EU-headquartered integration vendors.
- Edge-to-cloud orchestration convergence:Manufacturing facilities are deploying containerized integration runtimes at plant level, synchronizing with central platforms through event mesh architectures.
- Subscription-based API marketplace models:Pre-built connector ecosystems are displacing custom development engagements, opening mid-market access previously blocked by professional services dependency.
Industry Challenges
- FDA 21 CFR Part 11 validation complexity:Healthcare integrations require documented audit trails and electronic signature compliance, extending deployment cycles by 40-60 percent for regulated workloads.
- Interoperability standard fragmentation:Competing protocols across HL7 FHIR, DICOM, and proprietary health data formats force vendors to maintain multiple adapter stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remote Integration Solutions Market |
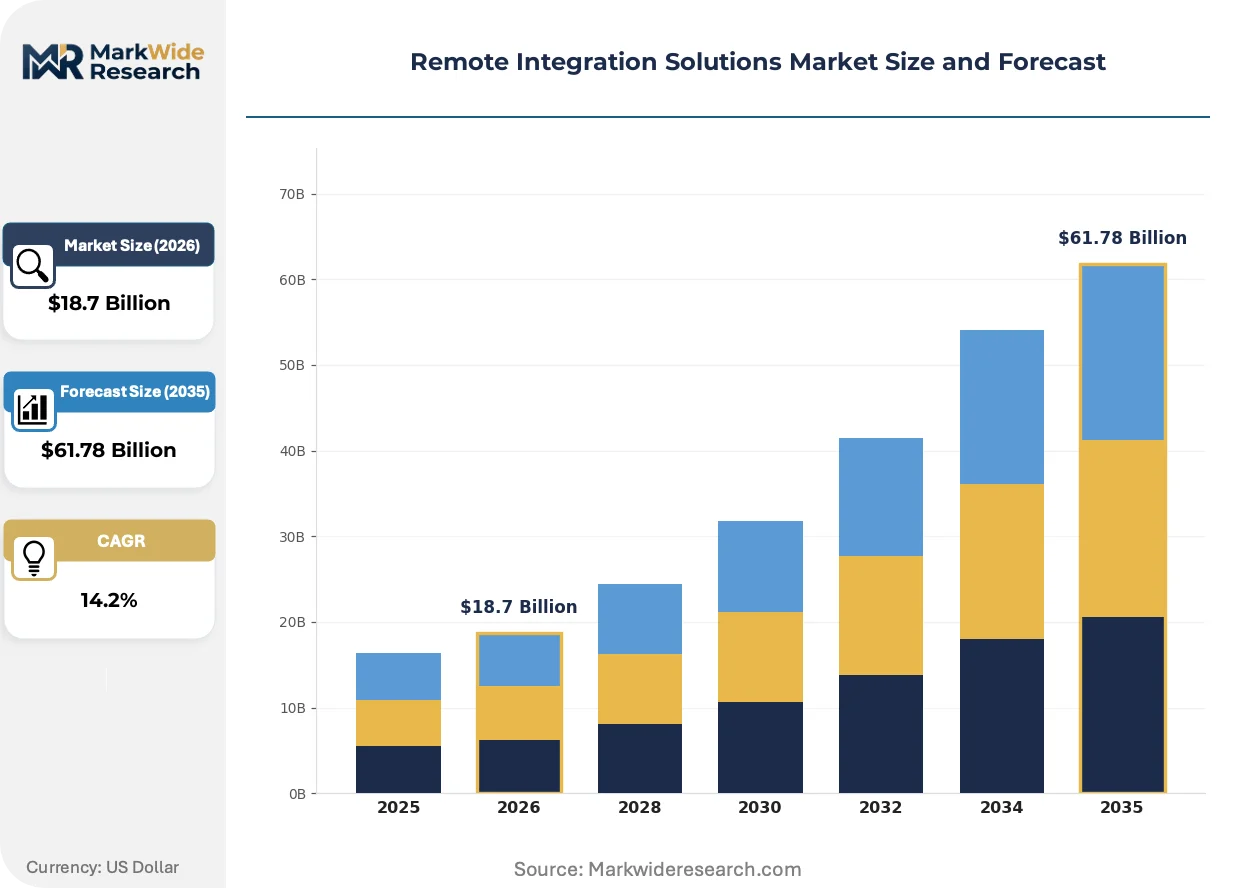
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Integration, API Management, Data Synchronization, Remote Monitoring Deployment: Hybrid, On-Premises, SaaS, PaaS End User: SMEs, Large Enterprises, Government Agencies, Healthcare Providers Solution: Integration Platform as a Service, Middleware, Custom Solutions, Automation Tools |
| Companies Covered | MuleSoft, Microsoft Azure Logic Apps, Zapier, HashiCorp, GitLab, Workato, SnapLogic, Informatica, Dell Boomi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remote Integration Solutions Market Evolving Landscape
Event-driven architecture patterns are displacing request-response paradigms as the dominant integration modality. This shift compresses latency thresholds and enables real-time operational visibility across distributed supply chains.
Event mesh technology is decentralizing integration control planes by enabling peer-to-peer event routing between distributed nodes without centralized broker dependency. Automotive manufacturers in Germany are deploying these architectures to synchronize supplier production schedules with assembly line velocity. The technology is decentralizing vendor lock-in risks while demanding new skills in stream processing and schema governance.
GDPR Article 32 security requirements and the EU AI Act's risk-management obligations are mandating algorithmic transparency in automated workflows. European enterprises must now maintain integration chain documentation for audit purposes. Financial services and healthcare sectors are responding by embedding compliance checkpoints directly into CI/CD pipelines.
Self-service integration platforms are compressing buyer-vendor engagement models from multi-quarter professional services cycles to credit-card-activated deployments. Mid-market procurement teams now evaluate solutions through free-tier experimentation rather than RFP processes. This behavioral shift is most pronounced in North American SaaS-native enterprises and is forcing incumbent vendors to unbundle implementation services.
Remote Integration Solutions Market Segmentation
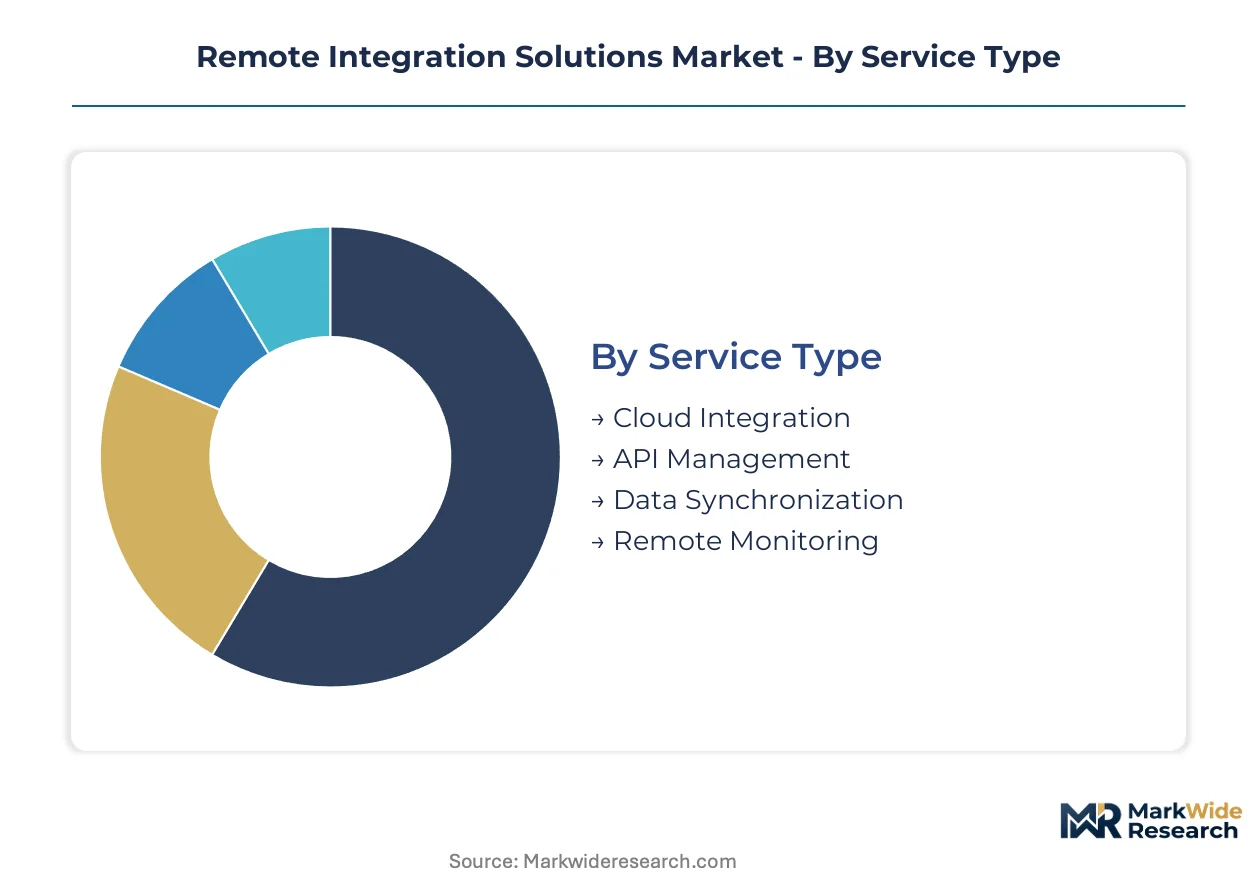
Segmentation in remote integration solutions reveals how procurement patterns bifurcate between standalone platforms and embedded infrastructure. Understanding these divides exposes where margin pools concentrate and which architectures enterprises prioritize for specific workload types.
Service Type:
Cloud Integration anchors enterprise deployments requiring elastic scalability, while API Management commands premium pricing for governance complexity. Data Synchronization and Remote Monitoring serve embedded use cases within broader operational technology stacks.
- Cloud Integration:Containerized middleware architectures enable workload bursting between sovereign on-premises nodes and hyperscaler infrastructure. Healthcare providers in Germany and France are migrating legacy ETL pipelines to these elastic configurations to support FHIR-based data exchange requirements.
- API Management:Governance layers enforce authentication protocols, rate limiting, and schema validation across distributed endpoints. Financial services institutions in the United Kingdom and the Netherlands are prioritizing these capabilities to satisfy EBA operational resilience mandates and GDPR Article 32 security requirements.
- Data Synchronization:Real-time consistency engines maintain state coherence across geographically dispersed databases.
- Remote Monitoring:Telemetry collection and alerting systems track integration pipeline health and performance thresholds.
Cloud Integration leads volumes today; API Management is gaining share fastest.
Deployment:
Cost tiers separate regulated industries retaining capital-intensive on-premises infrastructure from SaaS-native buyers seeking operational expenditure flexibility. Hybrid configurations capture mid-tier spend by bifurcating sensitive and transactional workloads.
- Hybrid:Architectures partition sensitive processing on sovereign infrastructure while bursting transactional workloads to elastic cloud layers. Automotive manufacturers in Germany deploy these configurations to maintain supplier data within national jurisdiction while leveraging cloud analytics for demand forecasting.
- SaaS:Fully managed multi-tenant platforms eliminate infrastructure ownership and accelerate procurement cycles for mid-market buyers.
- On-Premises:Self-hosted integration runtimes retain complete data sovereignty and customization control.
- PaaS:Developer-centric environments provide managed Kubernetes and serverless compute for custom integration logic.
Hybrid deployments dominate regulated verticals; SaaS is climbing the fastest among North American technology firms.
End User:
Customer type determines implementation complexity and sales cycle duration. Large enterprises demand professional services and custom engineering; SMEs favor self-service activation and pre-built templates.
- Large Enterprises:Global manufacturers and financial institutions require multi-region orchestration, dedicated support tiers, and compliance certification packages. These buyers in Germany, France, and the United Kingdom generate the highest professional services attach rates.
- SMEs:Mid-market buyers prioritize low-code interfaces and credit-card-activated deployments over lengthy procurement processes.
- Government Agencies:Public sector buyers mandate FedRAMP, ISO 27001, and national security certifications for vendor qualification.
- Healthcare Providers:Hospitals and clinic networks require HIPAA, GDPR, and FDA 21 CFR Part 11 validation for patient data integrations.
Large Enterprises anchor revenue today; SMEs are expanding most quickly as self-service platforms mature.
Solution:
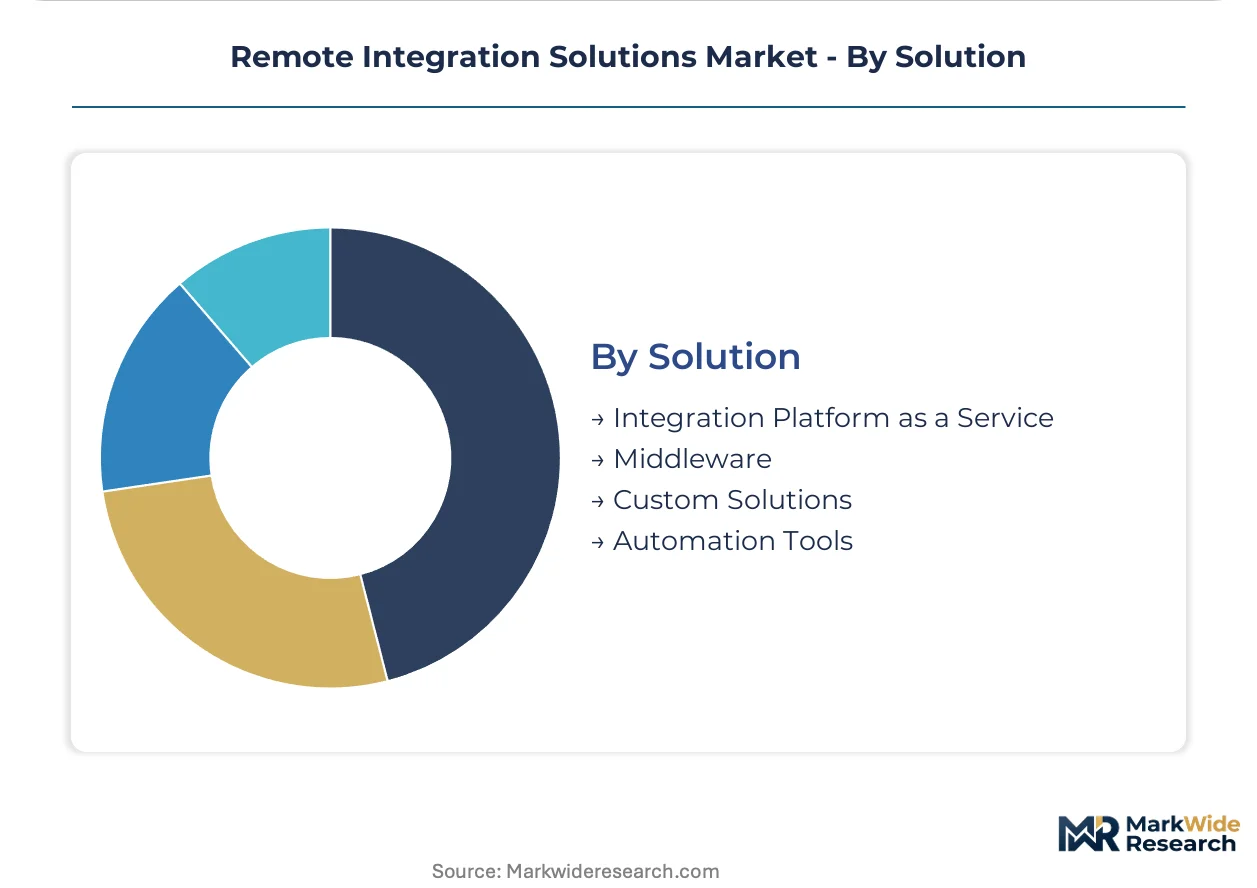
Technology maturity separates established Integration Platform as a Service offerings from emerging automation-native alternatives. Custom solutions persist where legacy system entrenchment resists standardization.
- Integration Platform as a Service:Cloud-native middleware delivers pre-built connectors, visual workflow designers, and elastic scaling without infrastructure management. These platforms capture the majority of new logo acquisitions in France and Germany as enterprises consolidate point-to-point integrations.
- Automation Tools:Robotic process automation and low-code workflow engines extend integration capabilities to business users without engineering resources.
- Middleware:Traditional enterprise service buses and message-oriented middleware persist in on-premises environments with heavy legacy investment.
- Custom Solutions:Bespoke engineering engagements address unique protocol requirements or specialized compliance scenarios.
Integration Platform as a Service leads volumes today; Automation Tools are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise software integration first achieved industrial scale in the United States during the 1990s client-server era, with middleware vendors clustering around Silicon Valley and Route 128. That foundational concentration established architectural patterns now diffusing through European manufacturing hubs and Asian financial centers.
United States
Healthcare systems and SaaS-native enterprises drive cloud integration procurement, with HIPAA-mandated encryption standards shaping vendor selection. FDA 21 CFR Part 11 validation requirements extend deployment cycles for regulated workloads. The San Francisco Bay Area and Seattle metropolitan corridors host dense concentrations of platform engineering talent and venture-backed integration startups.
Germany
Automotive and industrial manufacturing clusters demand sub-second latency for supplier coordination through event-driven messaging protocols. KBA vehicle data regulations and EU AI Act risk-classification mandates compel sovereign data architectures. Stuttgart and Munich anchor tiered supplier networks deploying edge-to-cloud orchestration for real-time production scheduling.
United Kingdom
Financial services institutions prioritize API management capabilities to satisfy EBA operational resilience mandates and GDPR Article 32 security requirements. The City of London and Edinburgh fintech corridors concentrate demand for governance-ready middleware with audit trail documentation.
France
CNIL guidance and national cloud certification programs create protected market segments for EU-headquartered integration vendors. Healthcare providers migrate legacy ETL pipelines to elastic configurations supporting FHIR-based data exchange. The Paris-Saclay cluster and Lyon metropolitan area concentrate public-sector and pharmaceutical integration procurement.
Japan
Manufacturing conglomerates deploy containerized integration runtimes at plant level, synchronizing with central platforms through event mesh architectures. METI digital transformation incentives accelerate replacement of legacy enterprise service buses. The Tokyo-Osaka industrial corridor concentrates demand for hybrid deployment configurations.
Remote Integration Solutions Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the API management and governance layer, while self-serve automation tools compete on volume and activation speed. The vendor landscape fragments across three tiers: enterprise-grade platforms with professional services dependencies, mid-market low-code offerings, and developer-centric infrastructure tools. Strategic archetypes include API-first connectivity specialists, automation-native challengers, and infrastructure-anchored incumbents. Competitive moves concentrate on connector ecosystem expansion and hybrid deployment certification programs.
Within the enterprise platform tier, MuleSoft and Informatica occupy positions anchored to Fortune 500 professional services relationships. Workato exemplifies the mid-market automation-native archetype competing through template-driven deployment velocity. Among infrastructure-anchored players, HashiCorp represents the developer-centric approach emphasizing programmable integration runtimes and Kubernetes-native patterns.
| Leading Market Players |
|---|
| MuleSoft |
| Microsoft Azure Logic Apps |
| Zapier |
| HashiCorp |
| GitLab |
| Workato |
| SnapLogic |
| Informatica |
| Dell Boomi |
| Others |
Value Network & Pricing Analysis
Healthcare provider migration to FHIR-based data exchange is compressing implementation timelines and forcing vendors to absorb validation costs upfront, which in turn stratifies pricing across certified and uncertified deployment tiers. This demand-side pressure reshapes how integration platforms recover margin through subscription structures versus professional services.
Pricing Analysis
Three-tier pricing structure across enterprise, professional, and developer levels dominates the remote integration solutions landscape, with differentiation anchored in API call volume thresholds, compliance certification grade, and dedicated support tier. Enterprise buyers in Germany's automotive sector demonstrate lowest price sensitivity due to operational resilience mandates, while North American mid-market SaaS adopters drive cost compression through self-service procurement and template-driven deployment. Pricing pressure stems from low-code automation platforms commoditizing connector development and collapsing implementation service attach rates.
Supply Chain Analysis
Single-source vulnerability sits with hyperscaler infrastructure concentrated in the United States, Ireland, and Singapore, where AWS, Azure, and GCP regions anchor elastic compute capacity for integration runtimes. The vendor ecosystem draws from Kubernetes distribution layers, API gateway software stacks, and identity management protocols, with tariff exposure on semiconductor-dependent edge hardware creating downstream cost uncertainty. Distribution runs through direct enterprise sales organizations for regulated verticals and self-service digital marketplaces for mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The remote integration solutions market functions as a stable compounder, with enterprise software consolidation and regulatory compliance mandates providing durable recurring revenue foundations across economic cycles.
For Market Incumbents: Deepen hybrid deployment certification programs to defend against cloud-native challengers, while expanding connector ecosystems for automotive and healthcare protocols to lock in switching costs. Prioritize zero-trust architecture investments as NIST frameworks reshape federal procurement qualification criteria. For New Entrants and Emerging Players: Event mesh technology for manufacturing edge-to-cloud orchestration offers the most penetrable wedge, particularly among German tiered supplier networks seeking sub-second latency without centralized broker dependency. Target France's sovereign cloud segments through CNIL-aligned compliance positioning and API marketplace subscription models that displace custom development engagements. For Investors and Strategic Acquirers: Asymmetric upside sits with automation-native platforms serving mid-market buyers through credit-card-activated deployments, where self-service adoption curves outpace traditional enterprise sales cycles. Monitor FDA 21 CFR Part 11 validation timeline compression as the signal indicating healthcare procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Deployment Certification | Enables regulated German manufacturers to partition sensitive workloads while bursting analytics to cloud layers. |
| API Marketplace Expansion | Pre-built connector ecosystems displace custom development and open mid-market access previously blocked by services dependency. |
| Event Mesh Architecture Development | Decentralizes vendor lock-in for automotive suppliers synchronizing production schedules with assembly velocity. |
| Zero-Trust Security Integration | Aligns platform offerings with evolving NIST frameworks reshaping federal vendor qualification criteria. |
| FHIR Compliance Acceleration | Positions vendors for healthcare provider migration from legacy ETL pipelines to elastic containerized infrastructure. |
Research Methodology
Direct dialogue with platform engineering directors, healthcare IT procurement officers, automotive supply chain architects, and API product managers anchored qualitative insights, cross-referenced against hyperscaler capex disclosures, SEC filings from publicly traded integration vendors, EU regulatory guidance documents, and hospital procurement database records. Bottom-up and top-down triangulation validated segment-level assumptions across deployment models and end-user categories.
Bottom-up modeling aggregated individual customer archetype adoption curves, while top-down analysis calibrated aggregate market expansion against enterprise software spend ratios across the analysis window. Segmentation dimensions included service type, deployment configuration, organization size tier, vertical industry, and geographic regulatory cluster. CAGRs derived from elasticity-adjusted pricing trajectories and connector ecosystem maturity curves, with healthcare FHIR adoption velocity and automotive event-driven protocol penetration serving as industry-specific forecast inputs.
The model holds under stable regulatory enforcement and continued hyperscaler infrastructure availability; deviation in EU AI Act risk-classification implementation timelines or cross-border data localization fragmentation would shift trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Docker Monitoring Market
Digital Solutions
Kubernetes Solutions Market
Digital Solutions
Global Remote Monitoring and Management (RMM) Tools Market
Digital Solutions
US Digital Market
Digital Solutions
Self Service Technology Market
Digital Solutions
Supply Chain Digital Twin Market
Digital Solutions
Smart Government Market
Digital Solutions
Europe Digital Pen Market
Digital Solutions
Online Advocacy Platform Market
Digital Solutions
Track and Trace Solutions Market
Digital Solutions
Global Application Container Market
Digital Solutions
Global Service Integration and Management Market
Digital Solutions
North America Managed Mobility Service Market
Digital Solutions
Utility App Market
Digital Solutions
Cloud-Based Product Lifecycle Management (PLM) Market
Digital Solutions
Smart Connected Assets and Operations Market