
 Data Pipeline Tools Market | 2026-2036
Data Pipeline Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Data Pipeline Tools Market Intelligence
Data engineering talent scarcity is redrawing competitive boundaries across the data pipeline tools sector. Databricks sustains technology leadership through its unified lakehouse architecture that collapses storage and compute layers. Microsoft anchors enterprise penetration by embedding pipeline capabilities within Azure Synapse and Power Platform ecosystems. Google competes on price-performance for streaming workloads through BigQuery and Dataflow integration.
Data pipeline tools are software systems that automate the extraction, transformation, and loading of data across distributed sources, typically orchestrating workflows through DAG-based schedulers with sub-second latency SLAs for streaming paths. Their primary purpose is to ensure reliable, governed data movement for downstream analytics and operational decision systems. Cloud deployment dominates current spending as enterprises retire on-premises Hadoop clusters, while stream processing technology captures the fastest expansion as event-driven architectures replace overnight batch windows. The ETL application segment retains the largest installed base, though real-time processing commands premium pricing due to infrastructure complexity.
FDA guidelines on data integrity for pharmaceutical submissions, SEC audit-trail requirements for broker-dealers, and GDPR cross-border transfer mechanisms collectively shape product roadmaps around lineage tracking and encryption standards. HIPAA compliance obligations in healthcare further harden requirements for access controls and audit logging within pipeline orchestration layers. Stakeholders must weigh vendor lock-in risks against the operational agility promised by managed serverless offerings.
Market Dynamics
Serverless computing architectures are collapsing traditional infrastructure procurement cycles, forcing vendors to reprice managed offerings around consumption granularity rather than provisioned capacity blocks.
Growth Catalysts
- Event-Driven Architecture Mandates:Financial services firms in the United States deploy sub-second latency pipelines for algorithmic trading execution, creating sustained demand for stream-processing infrastructure.
- GDPR Cross-Border Mechanisms:European enterprises invest in lineage-tracking capabilities to satisfy data residency requirements, expanding the addressable market for governance-integrated pipeline tools.
- Healthcare Interoperability Rules:HIPAA compliance obligations harden requirements for encrypted data movement between clinical systems, driving replacement of legacy batch infrastructure.
Market Restraints
- Cloud Concentration Risk:Three hyperscalers control the underlying compute substrate for managed pipeline services, creating vendor lock-in exposure for enterprise buyers.
- Specialized Talent Scarcity:Shortages of Apache Kafka and Spark engineers in San Francisco and Seattle metropolitan clusters inflate implementation costs and extend deployment timelines.
- Legacy Technical Debt:On-premises Hadoop clusters persist in heavily regulated industries, constraining migration velocity despite cloud-native performance advantages.
Strategic Opportunities
- Edge Computing Convergence:Manufacturing and logistics operators combine 5G connectivity with lightweight pipeline agents to process telemetry at plant-floor locations.
- India Digital Infrastructure:RBI data localization mandates and the PLI scheme for IT hardware create demand for sovereign cloud pipeline deployments.
- AI/ML Feature Engineering:Automated feature stores integrated with pipeline orchestration reduce model deployment friction for data science teams.
Industry Challenges
- Schema Evolution Complexity:Data contract enforcement between upstream producers and downstream consumers requires governance tooling that most organizations lack.
- Multi-Cloud Interoperability:Portable pipeline definitions across Azure, AWS, and Google Cloud remain technically immature, complicating disaster recovery architectures.
- Observability Integration:Unified monitoring across streaming and batch paths demands specialized tooling that fragments procurement budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Pipeline Tools Market |
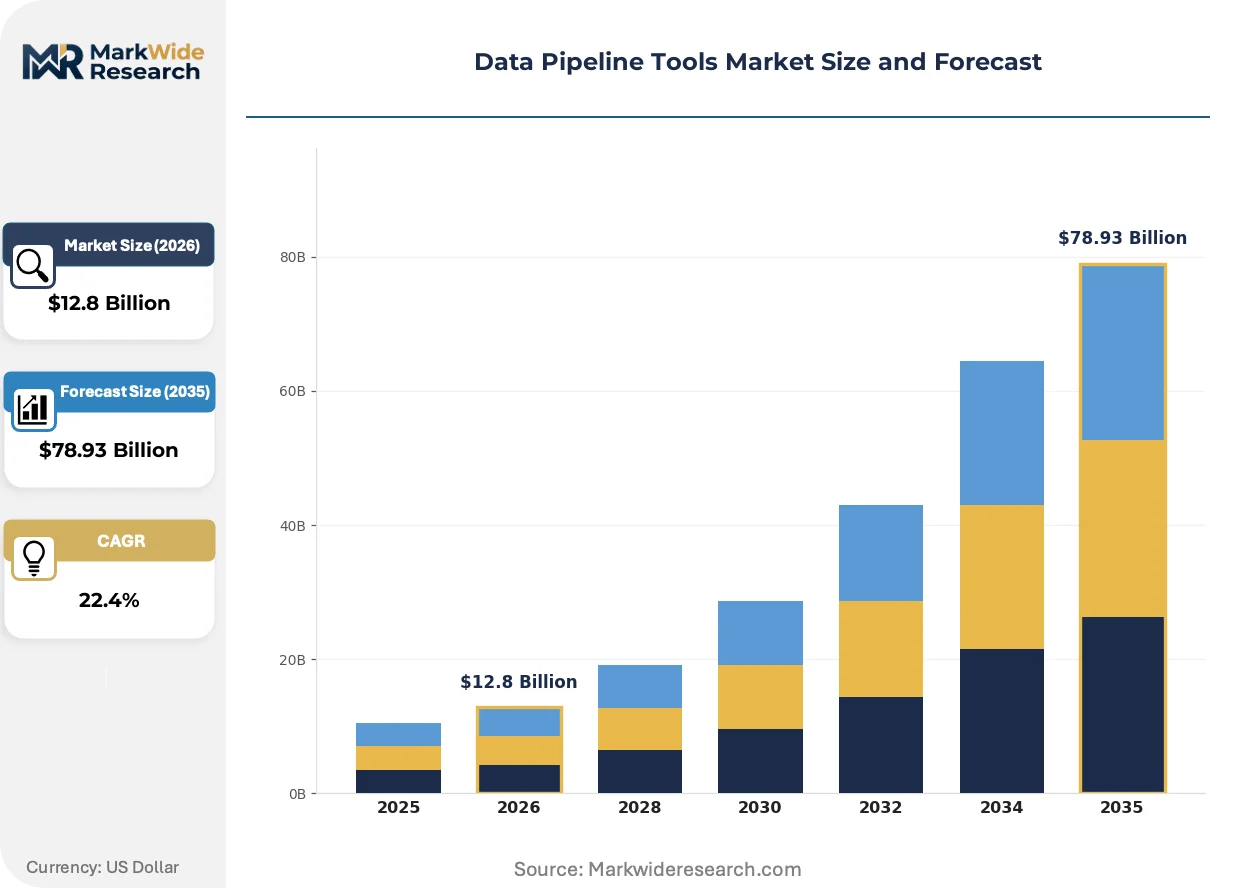
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $78.93 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud, On-Premises, Hybrid, Managed Technology: Batch Processing, Stream Processing, Microservices, Serverless End User: Data Scientists, Developers, Business Analysts, IT Administrators Application: Data Integration, Analytics, Real-Time Processing, ETL |
| Companies Covered | Fivetran, Hevo Data, Matillion, Databricks, Apache Airflow, RudderStack, Amazon Web Services, Google, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Pipeline Tools Market Strategic Shifts & Innovations
Data pipeline architectures are fragmenting into specialized paths optimized for latency-critical versus cost-sensitive workloads, with vendor portfolios expanding to cover both extremes.
Apache Flink and Kafka Streams are bifurcating the stream-processing layer into operational and analytical paths. Capital markets firms adopt Flink for millisecond-latency fraud detection while retail analytics teams favor Kafka Streams for customer journey aggregation. This technical split is bifurcating vendor roadmaps and pricing models.
EU AI Act risk classification requirements are forcing pipeline vendors to embed provenance logging for training data flows. High-risk AI system deployers must demonstrate data lineage from ingestion through model versioning. Healthcare and financial services verticals in Germany and France are accelerating procurement of compliant tooling ahead of enforcement deadlines.
Consumption-based pricing for managed pipeline services is displacing annual licensing contracts in the SaaS sector. Seattle and San Francisco enterprise buyers negotiate spend-commitment tiers with burst allowance rather than fixed-capacity provisioning. This purchasing shift compresses vendor revenue recognition cycles and intensifies competitive pressure on per-record processing rates.
Data Pipeline Tools Market Segmentation
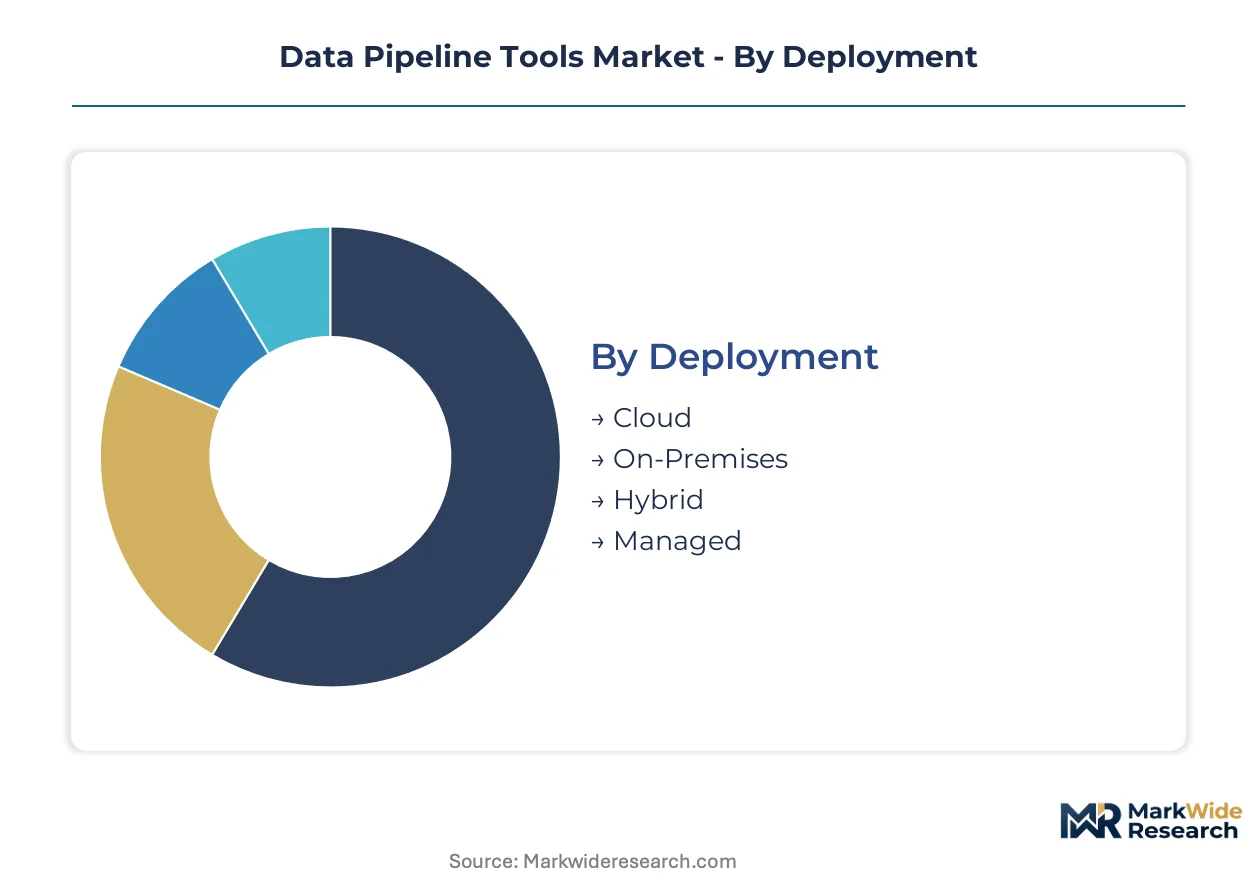
Segmentation in data pipeline tools reflects divergent infrastructure strategies across enterprise maturity levels. Cloud-native deployment patterns now command procurement priority as organizations dismantle legacy Hadoop estates. Technology choices increasingly bifurcate between latency-sensitive streaming architectures and cost-optimized batch systems.
Deployment:
Substitution pressure runs highest against on-premises installations as consumption-based cloud models collapse capital expenditure requirements.
- Cloud:Fully managed infrastructure delivered through hyperscaler marketplaces eliminates provisioning overhead. Financial services firms in the United States dominate procurement, driven by SEC audit-trail mandates requiring elastic compute for regulatory reporting spikes.
- On-Premises:Self-managed hardware and software stacks retained in defense, intelligence, and heavily regulated pharmaceutical operations. FDA data integrity guidelines for drug submission systems sustain residual demand despite migration headwinds.
- Hybrid:Split architectures preserving sensitive data on local infrastructure while bursting analytics workloads to cloud substrates. GDPR cross-border transfer mechanisms drive European enterprise adoption for sovereignty-compliant processing.
- Managed:Vendor-operated pipeline services with SLA-backed operations. Healthcare interoperability rules accelerate procurement as HIPAA-covered entities seek encrypted movement between clinical systems without internal engineering overhead.
Cloud deployments anchor the volume base while managed services gain share at the steepest rate.
Technology:
Cost tier differentiation separates high-performance streaming infrastructure from commodity batch processing.
- Batch Processing:Scheduled execution of data transformations across accumulated datasets. Legacy ETL workloads in retail and manufacturing persist here, though migration to microservices architectures is accelerating replacement cycles.
- Stream Processing:Continuous computation on event streams with sub-second latency guarantees. Capital markets firms deploy Flink and Kafka Streams for algorithmic trading execution, creating sustained infrastructure investment.
- Microservices:Containerized pipeline components orchestrated through Kubernetes. SaaS enterprises in Seattle and San Francisco metropolitan clusters favor this pattern for independent scaling of ingestion versus transformation stages.
- Serverless:Function-as-a-service execution models with per-invocation billing. Event-driven architecture mandates in financial services drive adoption despite cold-start latency constraints for sporadic workloads.
Batch processing retains the largest installed base while stream processing climbs the fastest as real-time decision systems displace overnight windows.
End User:
Application depth varies sharply by technical sophistication and governance requirements across user types.
- Data Scientists:Pipeline consumers requiring clean feature stores and model training datasets. Automated feature engineering integrations reduce deployment friction for ML workflows in technology and healthcare verticals.
- Developers:Engineers building custom data products and application backends. API-first pipeline tools with infrastructure-as-code definitions dominate procurement for this segment.
- Business Analysts:Self-service users demanding visual workflow designers and pre-built connectors. Low-code interfaces expand addressable market beyond traditional data engineering teams.
- IT Administrators:Governance and operations personnel managing access controls, encryption standards, and lineage tracking. HIPAA, GDPR, and SEC requirements concentrate demand for audit-capable orchestration layers.
Developers anchor the volume base while data scientists gain share at the steepest rate as AI/ML investment accelerates.
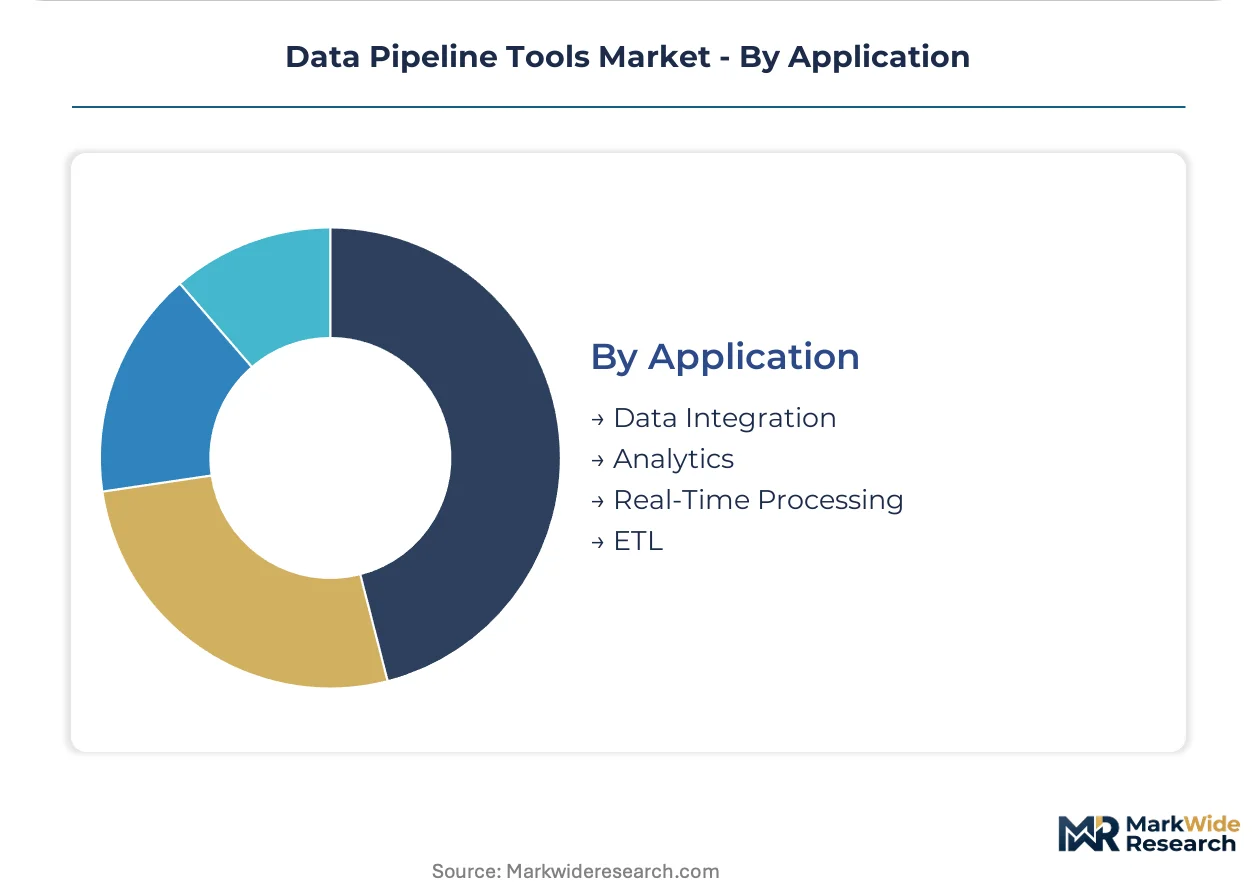
Application:
Maturity stages separate established data integration from emerging real-time processing use cases.
- Data Integration:Consolidation of disparate sources into unified analytical repositories. Enterprise data warehouse modernization projects sustain demand despite architectural shifts toward lakehouse patterns.
- Analytics:Pipeline outputs feeding business intelligence dashboards and exploratory analysis. Power Platform and Tableau ecosystem integrations drive vendor selection criteria.
- Real-Time Processing:Immediate transformation and delivery for operational decision systems. Fraud detection in financial services and telemetry processing in logistics create infrastructure premiums for millisecond-latency paths.
- ETL:Traditional extract-transform-load workflows with scheduled execution windows. The largest historical installed base now faces displacement by ELT patterns that push transformation to query engines.
ETL anchors the volume base while real-time processing expands most quickly as event-driven architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with US financial services demanding sub-second latency streaming while European enterprises prioritize GDPR-compliant lineage tracking and Asian markets emphasize sovereign cloud deployments under data localization mandates.
United States
Financial services firms in Manhattan and Chicago deploy real-time pipelines for algorithmic trading execution and fraud detection. SEC audit-trail requirements for broker-dealers mandate elastic compute infrastructure for regulatory reporting spikes. Seattle and San Francisco metropolitan clusters concentrate SaaS enterprise procurement of serverless pipeline architectures.
Germany
Automotive manufacturers in Stuttgart and Munich integrate streaming pipelines for connected vehicle telemetry and predictive maintenance systems. EU AI Act risk classification requirements force provenance logging for training data flows in high-risk AI deployments. Frankfurt's financial district drives demand for GDPR-compliant cross-border transfer mechanisms with encrypted lineage tracking.
India
RBI data localization mandates and the PLI scheme for IT hardware create demand for sovereign cloud pipeline deployments in Mumbai and Bangalore. Healthcare interoperability rules accelerate procurement of HIPAA-equivalent encrypted data movement between clinical systems. Hyderabad and Pune technology clusters favor microservices architectures for independent scaling of ingestion versus transformation stages.
United Kingdom
London's capital markets adopt Flink-based stream processing for millisecond-latency trading infrastructure. FCA operational resilience requirements shape vendor selection around SLA-backed managed services. Cambridge and Oxford research corridors drive automated feature store integration with pipeline orchestration for AI/ML workflows.
Japan
Manufacturing conglomerates in Nagoya and Osaka combine 5G connectivity with lightweight pipeline agents for plant-floor telemetry processing. METI digital transformation incentives accelerate replacement of legacy batch infrastructure. Tokyo's financial district sustains investment in hybrid architectures preserving sensitive data on local infrastructure while bursting analytics workloads to cloud substrates.
Data Pipeline Tools Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with hyperscalers anchoring enterprise penetration through embedded ecosystem capabilities while pure-play vendors compete on streaming performance and consumption-based pricing granularity. Three strategic archetypes dominate: cloud-native platform providers with unified lakehouse architectures, open-source orchestration specialists monetizing support and managed services, and vertical-integrated hyperscalers bundling pipeline tools with compute infrastructure. Competitive intensity concentrates around M&A activity targeting feature engineering automation and strategic partnerships securing 5G edge computing integration.
Within the open-source orchestration tier, Apache Airflow exemplifies community-driven standardization for DAG-based workflow scheduling. Among hyperscaler-integrated providers, Amazon Web Services and Microsoft occupy positions anchoring enterprise procurement through Synapse and Power Platform ecosystem lock-in. Google sits within the price-performance vector for streaming workloads through BigQuery and Dataflow integration. Databricks represents the unified architecture archetype collapsing storage and compute layers for lakehouse deployments.
| Leading Market Players |
|---|
| Fivetran |
| Hevo Data |
| Matillion |
| Databricks |
| Apache Airflow |
| RudderStack |
| Amazon Web Services |
| Microsoft |
| Others |
Cost & Logistics Intelligence
Capacity reservation contracts with hyperscalers lock in compute substrate access while capping per-record processing exposure for enterprise buyers navigating consumption-based billing volatility.
Pricing Analysis
Long-term offtake agreements with AWS, Azure, and Google Cloud dominate enterprise procurement, though spot consumption for burst workloads introduces price variability. Three-tier pricing structure across premium streaming, standard batch, and economy serverless tiers differentiates by latency SLA and encryption certification. Pricing pressure stems from Apache Airflow's open-source orchestration commoditizing core workflow scheduling. SaaS enterprises in Seattle and San Francisco exhibit highest price sensitivity, while financial services firms accept premium rates for sub-second latency guarantees.
Supply Chain Analysis
The United States and India anchor managed pipeline service delivery, with Ireland and Singapore supporting GDPR-compliant and Asia-Pacific data residency requirements. Infrastructure draws from specialized silicon for stream-processing acceleration, encrypted storage arrays, and API gateway middleware. Single-source vulnerability concentrates in hyperscaler control planes, constraining multi-cloud portability. Distribution runs through hyperscaler marketplaces and direct vendor sales teams serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in data pipeline tools hinge on lakehouse architecture consolidation collapsing storage-compute boundaries, with interoperability emerging as the decisive moat.
For Market Incumbents: Compound ecosystem lock-in through deeper Power Platform and Synapse integration while embedding EU AI Act provenance logging ahead of enforcement deadlines. Defend against open-source orchestration erosion by certifying managed Airflow variants for HIPAA and SEC audit-trail requirements. For New Entrants and Emerging Players: Anchor in edge computing convergence for manufacturing telemetry processing, where 5G pipeline agents remain underpenetrated. Target India sovereign cloud deployments under RBI localization mandates with microservices architectures bypassing hyperscaler dependency. For Investors and Strategic Acquirers: Capital is best deployed toward feature engineering automation specialists bridging pipeline orchestration and ML model deployment. Watch for inflection in automated data contract enforcement tooling addressing schema evolution complexity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Lakehouse architecture consolidation collapses storage-compute layers for unified analytics. |
| Acquisition of Specialist Firm | Feature engineering automation reduces model deployment friction for data science teams. |
| Strategic Partnership | 5G edge computing integration enables plant-floor telemetry processing for manufacturing clients. |
| Geographic Expansion | Sovereign cloud deployments satisfy RBI data localization mandates in Mumbai and Bangalore. |
| Product Launch | Serverless pipeline services with per-invocation billing displace annual licensing contracts. |
Research Approach
Findings reconcile primary fieldwork against secondary review of hyperscaler capex disclosures, SEC filings, and healthcare interoperability rulemakings. Data platform engineers, cloud procurement officers, regulatory compliance leads, and ML infrastructure architects provided structured input. Bottom-up deployment estimates triangulate against top-down spending analysis across cloud-native and legacy migration cohorts.
Segmentation dimensions modeled include deployment architecture, processing latency tier, end-user technical sophistication, and application maturity stage. CAGRs derive from elasticity-adjusted adoption curves and infrastructure retirement timelines across the projection horizon. Forecast inputs incorporate HIPAA encryption mandate compliance costs and EU AI Act provenance logging requirements.
Material uncertainties — hyperscaler pricing volatility, Kafka engineer scarcity inflation, and legacy Hadoop technical debt persistence — sit outside the modeled envelope. Recalibration cycles align with material shifts in regulatory enforcement schedules and sovereign cloud procurement acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Application Performance Management Market
Digital Solutions
UK High Performance Computing Market
Digital Solutions
Real-Time Temperature and Location Monitoring Platforms for Cold Chain Market
Digital Solutions
Global Process Orchestration Market
Digital Solutions
Global Ad Tech Software Market
Digital Solutions
Global Content Recommendation Engine Market
Digital Solutions
Control Room Solutions Market
Digital Solutions
US Digital Twin Market
Digital Solutions
Smart Process Application (SPA) Market
Digital Solutions
Web Performance Market
Digital Solutions
Cloud E-Signature Tools Market
Digital Solutions
Web Based E-Detailing Market
Digital Solutions
AQI App Market
Digital Solutions
North America Digital Pen Market
Digital Solutions
Construction Design App Market
Digital Solutions
New Zealand ICT Market