
 Global Automated Liquid Handling System Market | 2026-2036
Global Automated Liquid Handling System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automated Liquid Handling System Market Foresight
ISO 13485 certification for in vitro diagnostic device manufacturing is bifurcating the competitive landscape into qualified and non-qualified suppliers. Thermo Fisher Scientific leverages its vertically integrated consumables portfolio to sustain recurring revenue streams alongside instrument placements. Hamilton Company anchors its position through precision syringe pump technology that dominates high-throughput screening workflows. Tecan Group differentiates via modular platform architectures that allow pharmaceutical laboratories to scale throughput without full system replacement.
Automated liquid handling systems are electromechanical platforms that transfer measured volumes of liquid between vessels with accuracies typically ranging from sub-microliter to milliliter scales, serving as foundational infrastructure for reproducible assay execution in life sciences research and clinical diagnostics. Multi-channel systems command the largest installed base due to their throughput efficiency in plate-based workflows, while acoustic liquid handling represents the fastest-growing technology segment as drug discovery programs miniaturize reaction volumes to reduce reagent costs. Benchtop liquid handlers concentrate margin pools in academic and mid-tier contract research organization settings where capital budgets favor compact footprints over enterprise-scale robotics.
FDA 21 CFR Part 11 electronic records requirements shape software validation investments for US pharmaceutical laboratories, while EMA's MDR and IVDR frameworks tighten performance documentation obligations for diagnostic applications across European Union member states. EPA Good Automated Laboratory Practices influence environmental testing protocols that demand traceable liquid handling audit trails. Stakeholders must weigh regulatory compliance roadmaps against modular upgrade pathways when committing to platform architectures with decade-long depreciation cycles.
Market Dynamics
EMA's Annex 1 sterile manufacturing revisions are forcing pharmaceutical laboratories across Germany, France, and Switzerland to accelerate robotic liquid handler deployments, compressing validation timelines and redrawing competitive boundaries between qualified and non-qualified equipment suppliers.
Growth Catalysts
- Multi-channel throughput efficiency:US biotechnology firms rebuilding domestic screening capacity are prioritizing 96- and 384-channel systems that compress assay preparation cycles.
- EMA sterile manufacturing mandates:European pharmaceutical regulators now require closed-system liquid handling for aseptic processing, eliminating manual intervention in fill-finish workflows.
- Acoustic dispensing miniaturization:Drug discovery programs are shrinking reaction volumes below 100 nanoliters to cut reagent expenditure, pulling investment toward non-contact transfer technologies.
Market Restraints
- Precision component supply concentration:Ceramic piston pumps and optical encoders for sub-microliter accuracy concentrate among German and Swiss precision engineering suppliers, exposing buyers to extended lead times.
- ISO 13485 certification barriers:In vitro diagnostic device manufacturers face 18-24 month qualification timelines that freeze out non-certified system vendors from clinical diagnostic procurement pools.
- Acoustic technology cost premiums:Transducer arrays and piezoelectric positioning stages carry 3-4x capital cost multiples versus traditional pipetting, limiting adoption to well-capitalized discovery operations.
Strategic Opportunities
- India contract research expansion:CDSCO's streamlined medical device rules and PLI scheme incentives are drawing multinational pharmaceutical sponsors to establish automated screening infrastructure in Hyderabad and Bangalore clusters.
- Cell therapy manufacturing integration:Closed-system liquid handlers capable of aseptic cell culture manipulation address GMP requirements for CAR-T and iPSC workflows.
- Cloud-connected predictive maintenance:Instrument OEMs are unbundling service contracts into subscription-based uptime guarantees, shifting revenue from episodic repairs to recurring software-enabled monitoring.
Industry Challenges
- Multi-disciplinary field service engineering:Maintenance of electromechanical liquid handlers demands simultaneous competence in fluid dynamics, robotics kinematics, and 21 CFR Part 11 software validation.
- Legacy LIMS integration complexity:Pharmaceutical laboratories running decade-old laboratory information management systems face middleware development costs that erode automation ROI projections.
- Cross-platform consumable standardization:Proprietary tip and plate geometries lock users into single-vendor ecosystems, complicating multi-site standardization initiatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automated Liquid Handling System Market |
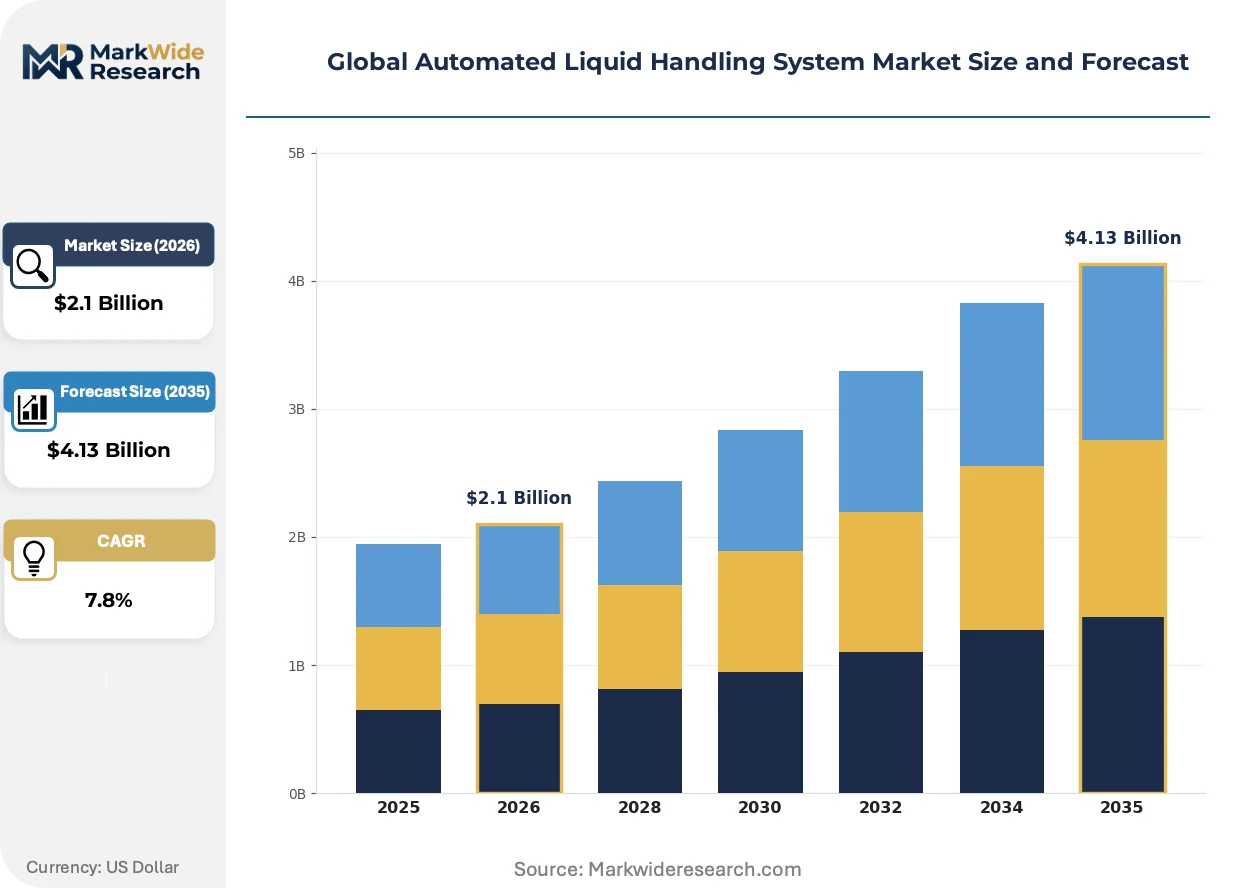
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Channel Systems, Multi-Channel Systems, Modular Automated Systems, Robotic Liquid Handlers, Benchtop Liquid Handlers Technology: Gripper-Based, Conveyor-Based, Arm-Based, Acoustic Liquid Handling, Pipetting Robots, Microfluidic Handling Application: Genomics, Drug Discovery, Proteomics, Diagnostics, Food Testing, Environmental Analysis End User: Pharmaceutical Laboratories, Biotechnology Firms, Contract Research Organizations, Academic Institutions, Forensic Laboratories |
| Companies Covered | Thermo Fisher Scientific, Hamilton Company, Tecan Group, Agilent Technologies, PerkinElmer, Danaher, Eppendorf, Mettler-Toledo International, Sartorius, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automated Liquid Handling System Market Shifts & Advancements
Modular platform architectures are fragmenting the traditional monolithic liquid handler market, allowing end-users to reconfigure throughput and functionality without full system replacement, while regulatory pressure on data integrity accelerates software validation investment cycles.
Acoustic liquid handling is decomposing the conventional pipetting paradigm by eliminating physical contact between transducer and sample. High-throughput screening groups at major pharmaceutical headquarters are adopting the technology for compound management and assay miniaturization. This displacement is compressing reagent budgets and enabling 1,536-well plate formats that were mechanically inaccessible to traditional pipetting systems.
REACH restrictions on per- and polyfluoroalkyl substances are forcing European liquid handler manufacturers to reformulate sealing materials and lubricants used in precision syringe pumps. The industrial consequence is a 12-18 month materials qualification cycle that delays new product introductions. Diagnostic instrument divisions with pre-validated alternative chemistries are capturing market share from competitors caught in regulatory recertification.
Consolidated procurement by US-based contract research organizations is compressing vendor rosters to three approved liquid handling platforms per therapeutic area. Mid-tier CROs are displacing point solutions with enterprise framework agreements that bundle instruments, consumables, and validation support. This concentration is most visible in Boston and San Diego biotechnology corridors, where purchasing departments now mandate cross-site equipment standardization to simplify technician training and method transfer.
Global Automated Liquid Handling System Market Segmentation
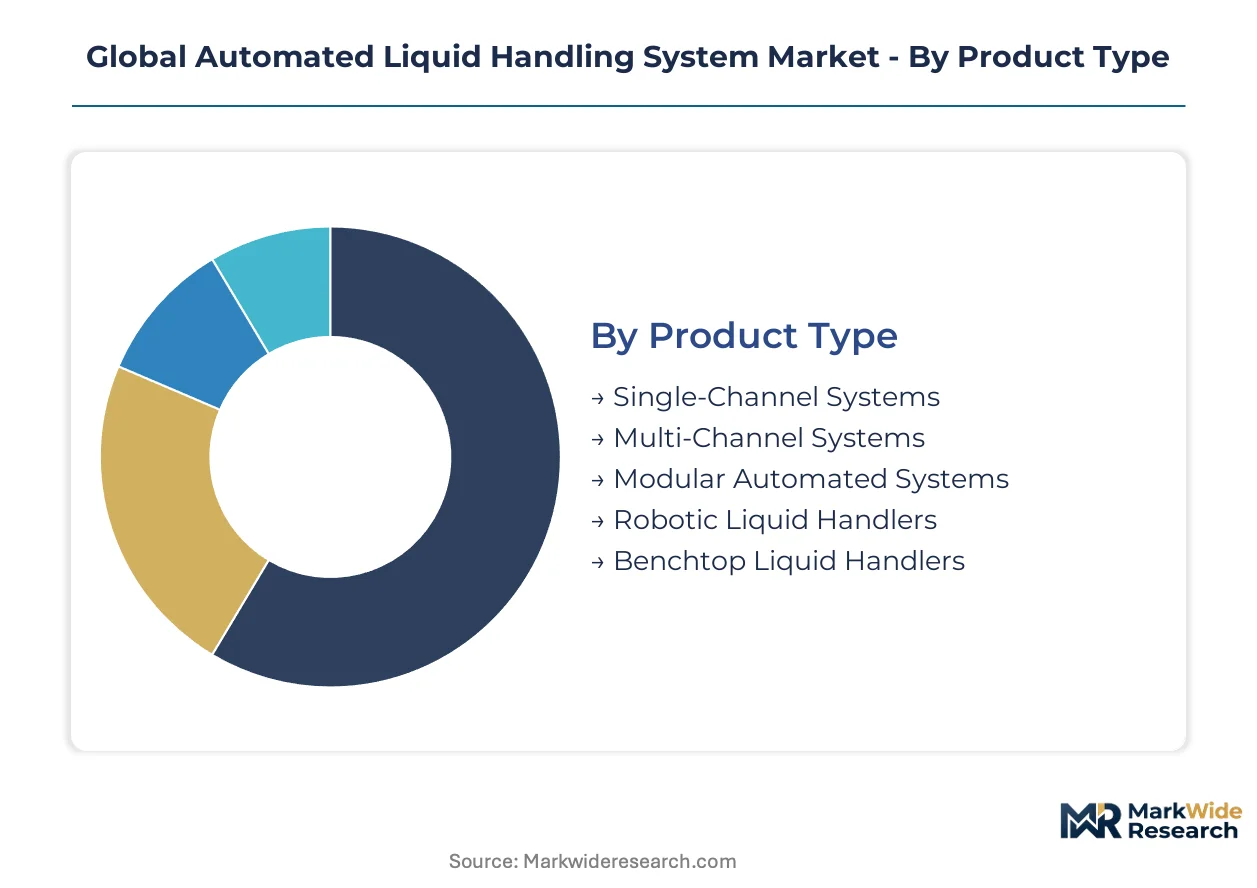
Liquid handling system purchasing decisions bifurcate sharply between throughput-intensive drug discovery operations and compliance-driven clinical diagnostics, with each segment demanding incompatible performance specifications. Procurement committees weigh capital efficiency against regulatory qualification burdens when mapping segment priorities to facility roadmaps.
Product Type:
Multi-channel architectures face acute substitution pressure from acoustic dispensing in high-throughput screening, while benchtop units confront manual pipetting persistence in budget-constrained settings.
- Multi-Channel Systems:These platforms deploy 96- or 384-channel pipetting heads that compress plate replication cycles to minutes. US biotechnology firms rebuilding domestic screening infrastructure in Boston and San Diego corridors prioritize these systems for compound library management.
- Benchtop Liquid Handlers:Compact footprints under 60 centimeters accommodate academic core facilities and mid-tier contract research organizations where capital budgets favor modular expansion over enterprise robotics. German pharmaceutical laboratories deploy these for method development prior to scale-up validation.
- Single-Channel Systems:Precision syringe pump architectures dominate cell therapy manufacturing workflows requiring sterile closed-system manipulation.
- Modular Automated Systems:Reconfigurable deck layouts allow pharmaceutical laboratories to adapt throughput without full instrument replacement.
- Robotic Liquid Handlers:Integrated kinematic platforms with enclosed environments address EMA Annex 1 sterile manufacturing mandates for aseptic processing.
Multi-channel systems retain volume leadership; acoustic-ready modular platforms hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium non-contact technologies from commodity electromechanical systems, with price multiples of 3-4x governing adoption feasibility.
- Acoustic Liquid Handling:Transducer arrays eject nanoliter droplets without physical probe contact, eliminating cross-contamination risk. Major pharmaceutical headquarters in Switzerland and the United Kingdom adopt this for 1,536-well assay miniaturization that slashes reagent expenditure.
- Pipetting Robots:Servo-driven pipetting arms with disposable tip handling constitute the installed base majority across European diagnostic laboratories subject to IVDR performance documentation obligations.
- Gripper-Based:Parallel-jaw and vacuum gripper mechanisms transfer microplates between processing stations in integrated screening lines.
- Conveyor-Based:Belt-driven transport systems enable continuous-flow processing in high-volume environmental testing laboratories.
- Arm-Based:Articulated robotic arms with six or more degrees of freedom access irregular vessel geometries in cell culture applications.
- Microfluidic Handling:Channel-based fluid manipulation enables picoliter precision for single-cell genomics workflows.
Pipetting robots dominate installed value; acoustic liquid handling is climbing the fastest as discovery programs miniaturize reaction volumes.
Application:
Customer type concentration varies sharply, with pharmaceutical-funded applications commanding premium pricing and public-sector testing operating on compressed procurement cycles.
- Drug Discovery:High-throughput screening, lead optimization, and compound management workflows demand 24-hour unattended operation with error rates below 0.1 percent. Biotechnology firms in the United States prioritize acoustic dispensing integration for fragment-based screening campaigns.
- Diagnostics:Clinical laboratories require ISO 13485-certified systems with full audit trails for FDA 21 CFR Part 11 compliance. European Union member states enforce additional IVDR technical documentation that extends validation timelines.
- Genomics:Next-generation sequencing library preparation drives demand for 96-channel normalization and pooling capabilities.
- Proteomics:Mass spectrometry sample preparation requires precise buffer exchange and digestion protocols.
- Food Testing:Pathogen detection workflows in commercial laboratories favor closed-system designs that prevent sample cross-contamination.
- Environmental Analysis:EPA Good Automated Laboratory Practices mandate traceable liquid handling for water and soil contaminant testing protocols.
Drug discovery commands the largest procurement budgets; diagnostics applications are expanding most quickly under regulatory documentation pressure.
End User:
Supply concentration among precision component vendors in Germany and Switzerland shapes delivery reliability across end-user categories with differing urgency tolerance.
- Pharmaceutical Laboratories:GMP-compliant facilities in Germany, France, and Switzerland deploy closed-system robotic handlers to meet EMA sterile manufacturing revisions. These installations require 18-24 month validation cycles that freeze out non-qualified equipment suppliers.
- Contract Research Organizations:Consolidated procurement by US-based CROs compresses approved vendor rosters to three platforms per therapeutic area, mandating cross-site standardization in Boston and San Diego biotechnology corridors.
- Biotechnology Firms:Venture-funded discovery operations prioritize modular architectures that scale with pipeline progression.
- Academic Institutions:Shared core facilities balance capital cost against multi-user accessibility requirements.
- Forensic Laboratories:Chain-of-custody documentation drives investment in integrated barcode tracking and audit trail capabilities.
Pharmaceutical laboratories retain the highest per-site spending; contract research organizations are gaining share fastest through consolidated framework agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain infrastructure underwrites European pharmaceutical distribution networks that depend on temperature-controlled liquid handler logistics. Germany's Rhine-Main corridor connects precision engineering suppliers in Baden-Württemberg to pharmaceutical manufacturing clusters in Hesse and Bavaria.
United States
Boston and San Diego biotechnology corridors drive multi-channel system procurement as venture-funded firms rebuild domestic screening capacity. FDA 21 CFR Part 11 electronic records requirements shape software validation investments across pharmaceutical laboratories. The Research Triangle Park in North Carolina anchors contract research organization consolidation with framework agreements mandating cross-site equipment standardization.
Germany
Pharmaceutical laboratories in Frankfurt and Munich scale robotic liquid handler deployments to meet EMA's Annex 1 sterile manufacturing revisions. The country's precision engineering base in the Black Forest region supplies ceramic piston pumps and optical encoders for sub-microliter accuracy. Heidelberg and Cologne clusters concentrate on ISO 13485-certified diagnostic instrument manufacturing for IVDR compliance.
Switzerland
Basel's pharmaceutical headquarters demand acoustic liquid handling for 1,536-well assay miniaturization that slashes reagent expenditure. Swissmedic's stringent device oversight compresses validation timelines for closed-system robotic handlers. The Zurich-Lausanne corridor integrates precision mechanics expertise with biotechnology discovery operations requiring GMP-compliant aseptic processing.
India
Hyderabad and Bangalore contract research clusters expand automated screening infrastructure under CDSCO's streamlined medical device rules and PLI scheme incentives. The country's national pharmaceutical regulator enforces performance documentation obligations that align with European MDR frameworks. Gujarat's industrial corridor attracts multinational sponsors establishing high-throughput compound management facilities.
United Kingdom
Cambridge and Oxford life science parks adopt modular platform architectures that scale throughput without full system replacement. The Medicines and Healthcare products Regulatory Agency's post-Brexit device oversight maintains alignment with EMA sterile manufacturing standards. London's diagnostic laboratory networks prioritize IVDR-compliant audit trail capabilities for clinical testing workflows.
Global Automated Liquid Handling System Market Competitive Landscape
Listed leaders compete with private specialists across instrument manufacturing and consumables supply, creating a tiered structure where scale advantages clash with customization depth. The market consolidates around three strategic archetypes: vertically integrated conglomerates controlling captive consumables streams, precision engineering specialists dominating high-accuracy syringe pump architectures, and modular platform architects enabling pharmaceutical scalability. Dominant competitive moves include backward integration into precision component manufacturing and subscription-based service contract unbundling.
Within the precision engineering tier, Hamilton Company and Tecan Group exemplify contrasting approaches to liquid handling architecture. Thermo Fisher Scientific anchors the integrated conglomerate archetype through its consumables portfolio leverage. These three entities occupy positions that span the competitive spectrum from component-level specialization to full-stack laboratory infrastructure provision.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Hamilton Company |
| Tecan Group |
| Agilent Technologies |
| PerkinElmer |
| Danaher |
| Eppendorf |
| Mettler-Toledo International |
| Sartorius |
| Others |
Supply & Pricing Matrix
Capacity utilization at precision component foundries in Germany and Switzerland sets price floors for sub-microliter accuracy systems, concentrating margin capture among vertically integrated instrument OEMs while forcing mid-tier vendors toward modular architectures with lower entry points. Pharmaceutical procurement committees exploit this concentration through multi-year framework agreements that lock in consumables pricing alongside capital equipment.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs automated liquid handling procurement, with acoustic dispensing platforms commanding premium positioning due to transducer array complexity while benchtop electromechanical systems compete on capital efficiency. Price differentiation hinges on ISO 13485 certification status and after-sales service bundling, with qualified suppliers extracting 15-25 percent premiums over non-certified competitors. Cost compression in the standard tier intensifies because CRO consolidated procurement mandates cross-site standardization. Academic core facilities exhibit highest price sensitivity, while GMP-compliant pharmaceutical laboratories prioritize qualification timelines over capital expenditure.
Supply Chain Analysis
Strategic stockpiling of ceramic piston pumps and optical encoders dominates inventory strategy among German and Swiss precision engineering suppliers, insulating pharmaceutical instrument manufacturers from spot-market volatility. Manufacturing concentration in Baden-Württemberg, the Zurich-Lausanne corridor, and Boston-San Diego biotechnology clusters draws from captive machining capacity for syringe pump architectures. Single-source vulnerability concentrates in piezoelectric positioning stages sourced from Japanese component specialists. Distribution runs through authorized service networks that bundle installation qualification with field validation support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automated liquid handling sector sits in early-cycle expansion as EMA sterile manufacturing mandates and US domestic screening rebuilds accelerate replacement demand ahead of traditional depreciation schedules.
For Market Incumbents: Shield installed base margins by deepening captive consumables penetration through tip and plate geometry lock-in, while accelerating ISO 13485 recertification investments to exploit 18-24 month qualification barriers that freeze out emerging competitors. Prioritize backward integration into ceramic piston pump manufacturing to reduce dependency on Black Forest precision engineering suppliers. For New Entrants and Emerging Players: Differentiate on acoustic-ready modular architectures that enable pharmaceutical laboratories to scale throughput without full system replacement, targeting mid-tier CROs in India contract research clusters where CDSCO streamlined rules lower regulatory entry barriers. Pursue cloud-connected predictive maintenance subscriptions as a go-to-market angle that shifts revenue from episodic repairs to recurring software-enabled monitoring. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated instrument OEMs with captive consumables streams, positioning these archetypes for superior cash flow quality across the analysis window. Acquisition targets should display pre-validated alternative chemistries for REACH-compliant sealing materials. Watch for inflection when EMA Annex 1 enforcement timelines compress validation capacity at incumbent service organizations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Components | Ceramic piston pump in-house production reduces lead time exposure to German suppliers. |
| Cloud-Connected Predictive Maintenance Launch | Subscription uptime guarantees shift revenue from episodic repairs to recurring monitoring. |
| ISO 13485 Certification Investment | Diagnostic instrument qualification opens IVDR-compliant procurement pools in EU member states. |
| Modular Platform Architecture Expansion | Reconfigurable deck layouts enable pharmaceutical scale-up without full instrument replacement. |
| India Contract Research Infrastructure Buildout | Hyderabad and Bangalore clusters leverage CDSCO streamlined rules and PLI incentives. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA device registrations, and ISO 13485 certification databases, combining structured interviews with laboratory automation directors, GMP compliance officers, and diagnostic instrument procurement managers at pharmaceutical headquarters and contract research organizations. Bottom-up instrument shipment data triangulates against top-down capital expenditure disclosures from biotechnology firms and academic core facilities.
Segmentation dimensions modeled span product type, technology architecture, application workflow, and end-user category across the projection horizon, with CAGRs derived from regression analysis of historical placement velocity and forward-looking procurement pipeline visibility. Forecast inputs incorporate EMA Annex 1 implementation timelines and US biotechnology corridor expansion announcements.
Material uncertainties — regulatory recertification delays, precision component supply disruptions, and acoustic technology cost curve trajectories — sit outside the modeled envelope. Revision becomes warranted when EMA enforcement intensity or REACH substitution timelines cross thresholds that alter qualification economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Computer Numerical Control Market
Automation
Middle East and Africa Workforce Management Market
Automation
Italy Marketing Automation Software Market
Automation
Escalator Control Systems Market
Automation
Dropshipping Automation Software Market
Automation
Global Direct Mail Automation Software Market
Automation
Global Process Automation and Instrumentation Market
Automation
Micro Fulfillment Market
Automation
Europe Marketing Automation Software Market
Automation
US Workload Scheduling and Automation Market
Automation
Playout Automation Market
Automation
Helpdesk Automation Market
Automation
Lab Automation Market
Automation
APAC Water Automation and Instrumentation Market
Automation
Database Automation Market
Automation
CNC Controller Market