
 Global Online Book Services Market | 2026-2036
Global Online Book Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Online Book Services Market Foresight
India's digital publishing infrastructure is narrowing the accessibility gap between metropolitan and tier-two city readers. Amazon.com, Inc. leverages its Kindle ecosystem and self-publishing platform to dominate English-language digital distribution. Rakuten Kobo Inc. competes through hardware-software integration and localized store operations across multiple continents. Scribd Inc. differentiates via subscription bundling that extends beyond books into documents and audiobooks.
Global Online Book Services encompass digital content platforms that deliver textual and audio narrative works through internet-connected interfaces, typically employing DRM encryption, adaptive bitrate streaming, and cloud-synced library management to enable cross-device consumption. The primary commercial purpose centers on disintermediating traditional physical retail while capturing recurring revenue through access-based models rather than unit sales. Audiobook streaming commands expanding share as commute-time consumption and smart speaker penetration deepen listener habits. Subscription services concentrate margin pools through predictable recurring revenue and reduced customer acquisition costs per incremental title. eBook rental occupies a mature position with slower growth but retains utility among price-sensitive student segments.
The EU Digital Services Act and GDPR impose transparency and data governance requirements that reshape how platforms curate recommendations and manage user reading data across Europe. The US FCC maintains oversight of net neutrality principles that affect streaming delivery costs and quality-of-service tiers for bandwidth-intensive audiobook content. India's TRAI broadband pricing regulations influence affordable access thresholds for mobile-first book consumption. Stakeholders must monitor evolving platform liability frameworks and interoperability mandates that could unlock or restrict captive content ecosystems.
Market Dynamics
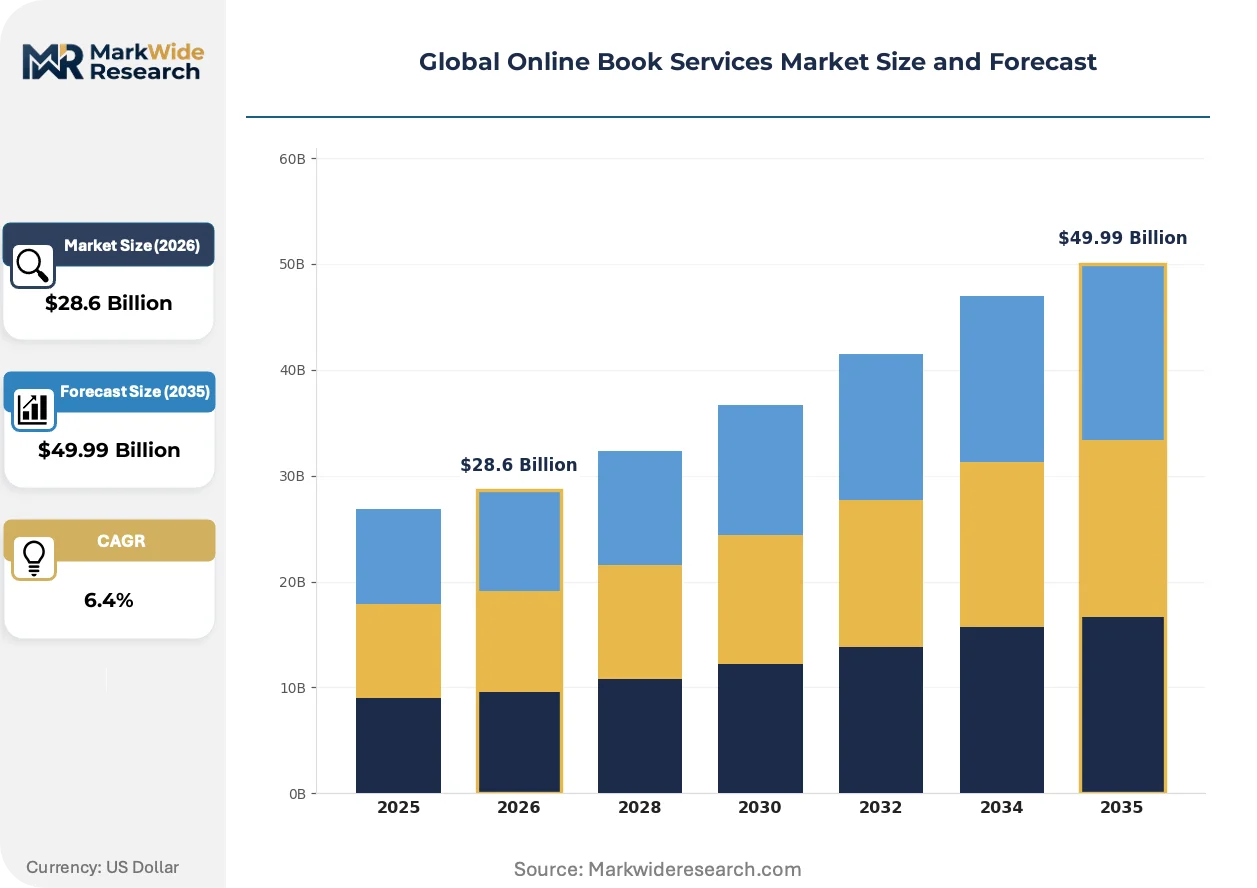
Subscription bundling is compressing unit economics while DRM interoperability battles between Amazon, Apple, and independent retailers force publishers into multi-platform licensing complexity. This structural tension between access-based revenue models and platform captivity defines competitive positioning.
Growth Catalysts
- EU Digital Services Act transparency mandates:Platforms must disclose recommendation algorithms, creating openings for smaller publishers to audit discoverability bias.
- India TRAI broadband pricing reforms:Affordable data plans in tier-two cities unlock mobile-first audiobook consumption among price-sensitive readers.
- Academic digital curriculum mandates:Universities are replacing physical coursepacks with licensed e-textbook platforms, generating institutional recurring revenue.
Market Restraints
- Cloud infrastructure cost concentration:AWS and Azure pricing power squeezes margin for independent streaming platforms serving bandwidth-intensive audiobook content.
- GDPR data portability friction:Reader history and annotation exports face technical barriers that reinforce platform stickiness and suppress multi-platform usage.
- Print-to-digital licensing gaps:Backlist titles often lack cleared digital rights, constraining catalog depth for subscription services.
Strategic Opportunities
- Brazil ANVISA regulatory clarity:Emerging frameworks for digital health content create pathways for medical and wellness audiobook verticals.
- Generative AI narration convergence:Synthetic voice synthesis paired with human editing is opening mid-tier audiobook production at compressed cost structures.
- Indonesia's underpenetrated archipelago:Fragmented physical retail and rising smartphone penetration position the country for mobile-only platform launches.
Industry Challenges
- Metadata standardization delays:ONIX 3.0 adoption gaps between publishers and retailers cause listing errors and discoverability loss.
- Cross-border royalty accounting complexity:VAT variations across EU member states and withholding tax treaties create reconciliation overhead for global platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Online Book Services Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: eBook Rental, Print Book Delivery, Audiobook Streaming, Subscription Service, Personalized Recommendations Customer Type: Students, Educators, Research Professionals, Casual Readers, Book Collectors Platform Technology: Web Browsers, Mobile Apps, Dedicated eReaders, Smart Speakers, Tablet Interfaces Distribution Channel: Direct Website, Affiliate Networks, Social Media, Mobile Marketplaces, Third-Party Retailers |
| Companies Covered | Amazon.com, Inc., Apple Inc., Rakuten Kobo Inc., Barnes & Noble Booksellers, Inc., Google, Scribd Inc., Audible, HarperCollins Publishers, Smashwords, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Online Book Services Market Shifts & Advancements
Adaptive streaming protocols and AI-generated narration are collapsing production timelines while regulatory pressure on algorithmic transparency forces platforms to expose curation mechanics. These forces are reshaping how content reaches readers.
Generative voice synthesis is collapsing the cost barrier for audiobook production. Mid-list titles and backlist catalogs previously uneconomical for human narration now reach audio format. Publishers are adopting hybrid workflows pairing synthetic base narration with human quality control, compressing per-title investment from weeks to days.
GDPR algorithmic accountability provisions are forcing recommendation engine disclosures. Platforms must explain why specific titles surface for individual users, exposing competitive curation logic. French CNIL enforcement actions against opaque profiling are prompting EU-wide audits of reading-history monetization practices.
Library patron-driven acquisition models are disrupting traditional institutional sales. Academic and public libraries now license access pools where user selections trigger automatic purchases, shifting inventory risk from librarian curation to platform algorithms. This pattern concentrates most visibly in US and Canadian university systems with strained acquisition budgets.
Global Online Book Services Market Segmentation
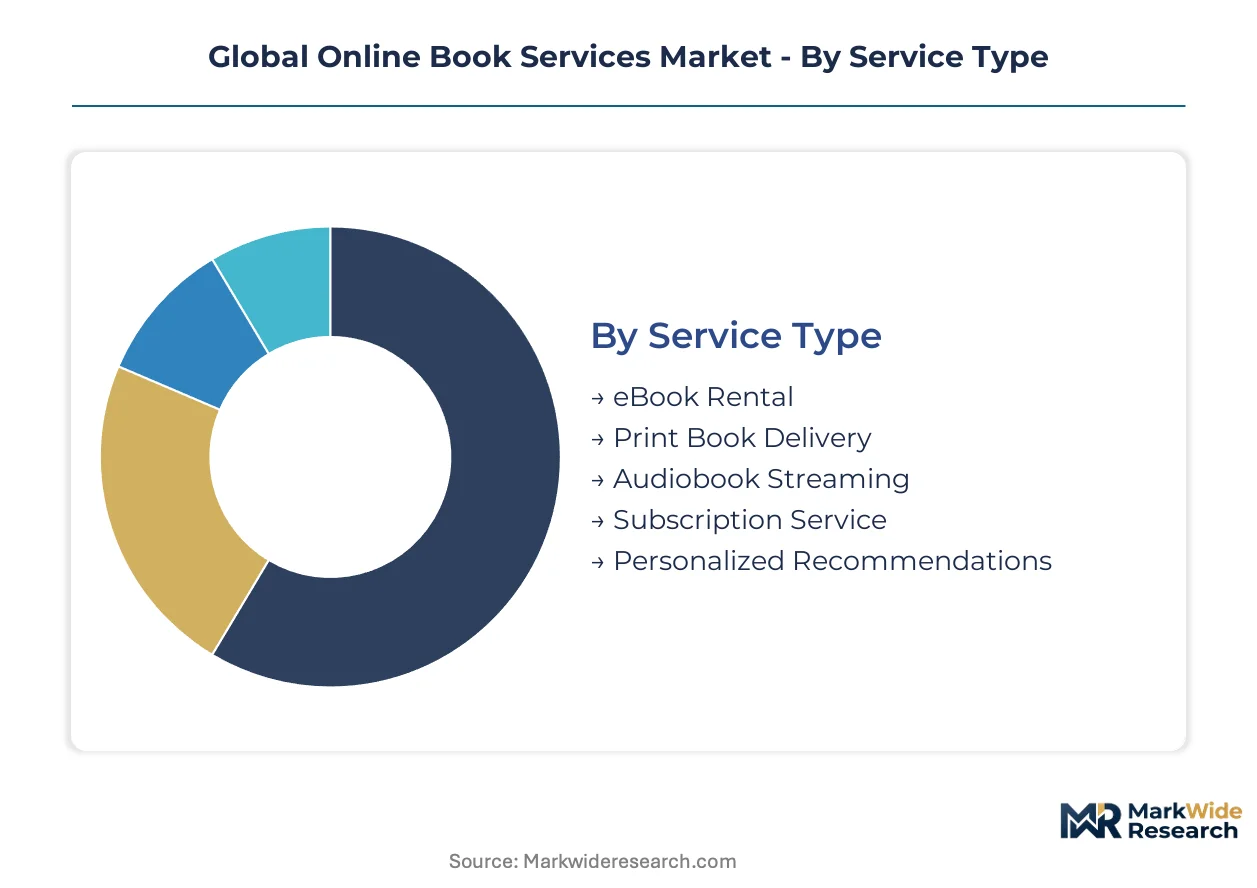
Segmentation in online book services reveals how platform economics fragment across consumption modes, user sophistication levels, and hardware dependencies. Each dimension exposes distinct margin structures, churn patterns, and regulatory exposure that shape competitive strategy.
Service Type:
Cost tier differentiation separates transactional rentals from recurring subscriptions and algorithmic value-adds.
- Subscription Service:Bundled access models generate predictable recurring revenue through unlimited consumption ceilings. Academic institutions in India and price-sensitive casual readers in tier-two cities drive concentration as mobile data costs fall under TRAI pricing reforms.
- Audiobook Streaming:Adaptive bitrate protocols deliver spoken-word content across commute contexts and smart speaker environments. Commute-time consumption in São Paulo and Jakarta deepens listener habits where physical retail penetration remains fragmented.
- eBook Rental:Time-limited access at compressed price points serves student segments with predictable course-driven demand cycles.
- Print Book Delivery:Hybrid logistics integrating digital discovery with physical fulfillment retains collectors and gift purchasers resistant to screen-based reading.
- Personalized Recommendations:Algorithmic curation layers monetize reading history through improved conversion and extended session duration.
Subscription Service holds installed capacity. Audiobook Streaming is rotating up the share rankings.
Customer Type:
Application context determines pricing power, with institutional buyers commanding volume discounts and individual readers showing divergent willingness-to-pay.
- Students:Curriculum-mandated adoption through university licensing agreements generates concentrated institutional recurring revenue. EU Digital Services Act transparency requirements reshape how platforms curate required reading lists for this segment.
- Casual Readers:Discretionary consumption patterns exhibit high churn sensitivity to subscription pricing and catalog breadth. Mobile-first consumption in Indonesian archipelago markets expands addressable base as smartphone penetration crosses critical thresholds.
- Educators:Course design authority creates gatekeeper influence over institutional procurement decisions and platform selection.
- Research Professionals:Deep search functionality and annotation export requirements prioritize technical capabilities over price in vendor selection.
- Book Collectors:Ownership preference and edition specificity sustain demand for print-digital hybrid fulfillment models.
Students anchor institutional contract value. Casual Readers are climbing the fastest in absolute user additions.
Platform Technology:
Hardware-software integration intensity varies from commodity browsers to proprietary eReaders with captive content ecosystems.
- Mobile Apps:Native smartphone clients dominate session volume through push notification re-engagement and offline sync capabilities. India's tier-two cities and Brazil's urban peripheries concentrate demand as affordable Android devices proliferate.
- Dedicated eReaders:E-ink display technology and extended battery life create differentiated reading hardware with platform-specific DRM lock-in. Enthusiast segments in Germany and Japan sustain premium pricing for single-purpose devices.
- Web Browsers:Zero-install access lowers friction for occasional users and institutional account sharing scenarios.
- Smart Speakers:Voice-first interaction design enables hands-free audiobook consumption during household multitasking and commute contexts.
- Tablet Interfaces:Larger screen real estate supports illustrated content and parallel annotation workflows for academic use cases.
Mobile Apps command session frequency leadership. Dedicated eReaders are gaining share fastest among high-value customer cohorts.
Distribution Channel:
Customer acquisition economics diverge sharply between owned properties and intermediated traffic sources.
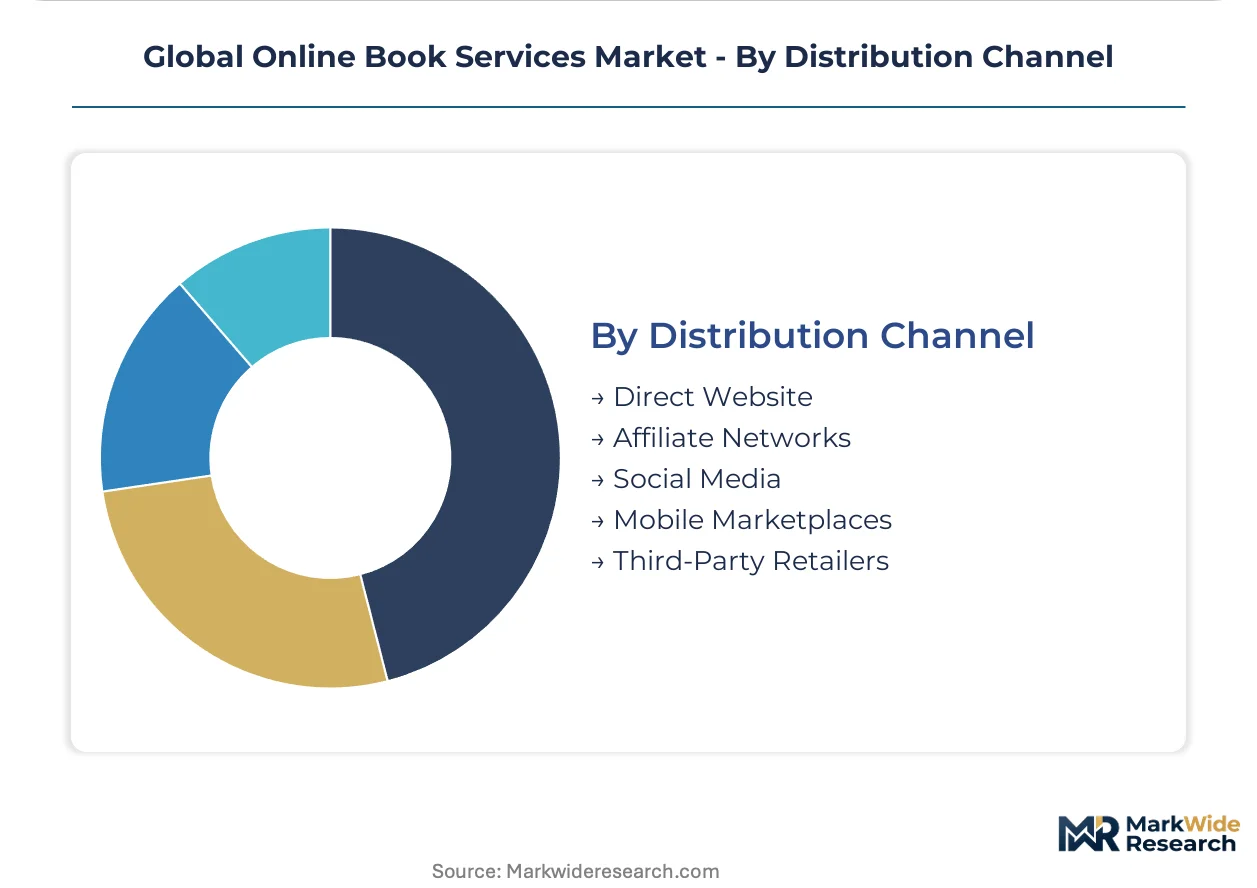
- Direct Website:First-party relationships capture full margin and reading behavior data without intermediary attribution costs. GDPR-compliant consent flows and algorithmic transparency disclosures under EU Digital Services Act reshape European direct acquisition strategies.
- Mobile Marketplaces:App store distribution exposes platforms to 15-30% revenue share obligations and review-driven discoverability algorithms. Google's Play Store and Apple's App Store operate as unavoidable gatekeepers for smartphone-native customer segments.
- Affiliate Networks:Performance-based acquisition scales reach through content publisher partnerships with cost-per-action economics.
- Social Media:Algorithmic feed distribution enables viral content discovery though engagement rates vary sharply by platform demographic alignment.
- Third-Party Retailers:E-commerce marketplace listings extend reach into established purchase journeys though margin compression and brand dilution follow.
Direct Website retains highest lifetime value concentration. Mobile Marketplaces are expanding fastest in emerging market user acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform infrastructure investment clusters in jurisdictions with favorable data governance frameworks and expanding broadband penetration. Content licensing operations concentrate where copyright enforcement mechanisms support subscription economics. Cloud delivery nodes follow demand density into metropolitan corridors with reliable connectivity.
United States
Academic institutional procurement and public library patron-driven acquisition models sustain platform revenue concentration. FCC net neutrality oversight shapes streaming quality-of-service tiers for bandwidth-intensive audiobook delivery. Greater Boston and Seattle-Tacoma corridors host technical operations centers supporting recommendation engine development.
Germany
Enthusiast demand for dedicated eReader hardware sustains premium single-purpose device markets. EU Digital Services Act transparency mandates force algorithmic disclosure for recommendation curation logic. Berlin-Brandenburg and Munich clusters concentrate localization operations for multilingual European content distribution.
India
Mobile-first consumption in tier-two cities accelerates as TRAI broadband pricing reforms compress data costs. BIS technical standards for digital content interoperability reduce platform switching friction. Bengaluru and Hyderabad corridors attract venture deployment for vernacular language platform development.
Brazil
Fragmented physical retail penetration in urban peripheries positions mobile-only platforms for audiobook adoption. ANVISA regulatory frameworks for digital health content create vertical pathways for medical and wellness narration. São Paulo metropolitan concentration anchors Portuguese-language production and distribution operations.
Indonesia
Archipelago geography and rising smartphone penetration enable mobile-native platform launches bypassing traditional retail. Central bank digital payment infrastructure expansion reduces friction for micro-transaction subscription models. Jakarta and Surabaya clusters concentrate content localization for diverse regional language markets.
Global Online Book Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in content production and DRM licensing. The vendor structure organizes around three archetypes: ecosystem-locked hardware-software bundlers, subscription aggregators with cross-content bundling, and self-publishing infrastructure providers. Consolidation pressure concentrates among mid-tier aggregators facing cloud infrastructure cost escalation. Competitive moves center on geographic licensing expansion and synthetic narration technology partnerships.
Within the ecosystem-locked tier, Amazon.com, Inc. and Apple Inc. anchor platform captivity through proprietary DRM and device integration. Rakuten Kobo Inc. represents the hardware-software bundler archetype with localized store operations spanning multiple continents. Scribd Inc. occupies the subscription aggregator position, exemplifying cross-content bundling that extends beyond books into documents and audiobooks.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| Apple Inc. |
| Rakuten Kobo Inc. |
| Barnes & Noble Booksellers, Inc. |
| Scribd Inc. |
| Audible |
| HarperCollins Publishers |
| Smashwords, Inc. |
| Others |
Supply & Pricing Matrix
Overcapacity in cloud audiobook streaming infrastructure across North American data centers is compressing marginal delivery costs while intensifying price competition for subscription tier differentiation. This utilization slack enables platforms to absorb TRAI-mandated data cost reductions in India without margin erosion, yet simultaneously pressures independent aggregators facing AWS and Azure pricing power concentration.
Pricing Analysis
The EU Digital Services Act dictates the pricing tier structure through algorithmic transparency mandates that increase compliance overhead for personalized recommendation layers. Three-tier pricing structure across premium, standard, and economy levels segments by catalog depth and device sync limits, with academic institutional buyers commanding volume discounts through curriculum-mandated licensing. Price differentiation hinges on DRM interoperability certification and geographic content licensing scope. Pricing pressure stems from generative AI narration collapsing audiobook production costs in the mid-list segment. Students exhibit highest price sensitivity through eBook rental demand cycles, while research professionals prioritize annotation export functionality over subscription cost.
Supply Chain Analysis
Upstream content production feeds from synthetic voice synthesis laboratories in the United States, human narration studios in the United Kingdom, and generative AI training data providers in Canada. Cloud infrastructure provisioning draws from hyperscaler concentration in the United States, Ireland, and Singapore, with edge delivery nodes following metropolitan demand density. Supply chain risk centers on single-source vulnerability for DRM encryption licensing from proprietary ecosystem providers. Distribution runs through direct website relationships capturing first-party data, mobile marketplace gatekeepers extracting 15-30% revenue share, and institutional procurement channels with extended sales cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative AI narration convergence is disrupting production economics faster than platform pricing structures can adapt, creating asymmetric opportunity for technology-integrated entrants against legacy human-narration dependent catalogs.
For Market Incumbents: Insulate proprietary DRM ecosystems through hardware-software bundling investments in dedicated eReader development, while accelerating synthetic narration quality control workflows to compress backlist audio conversion timelines. Cloud infrastructure cost concentration from AWS and Azure pricing power demands backward integration into owned delivery node deployment. Academic institutional licensing agreements with curriculum-mandated adoption provide defensive recurring revenue anchors against casual reader churn sensitivity. For New Entrants and Emerging Players: Pursue vernacular language content gaps in Indian tier-two cities and Indonesian archipelago markets where mobile-first consumption outpaces established platform localization investment. Fragmented physical retail penetration in Brazilian urban peripheries enables mobile-only audiobook platform launches bypassing traditional distribution. Direct website acquisition with GDPR-compliant consent flows captures higher lifetime value than marketplace-dependent customer relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across synthetic narration technology deployment, reducing barrier-to-entry for mid-tier content aggregators with hybrid human-AI production workflows. Long-term viability favors platforms controlling proprietary recommendation algorithms with transparency-compliant curation logic. Acquisition target archetype: regional vernacular specialists with institutional licensing traction and owned narration production capacity. Signal to watch: BIS interoperability standard adoption rates unlocking platform switching friction reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Narration Technology Partnership | Generative AI voice synthesis compresses mid-list audiobook production timelines from weeks to days. |
| Vernacular Language Platform Launch | TRAI broadband pricing reforms unlock mobile-first consumption in Indian tier-two city markets. |
| Academic Institutional Licensing Expansion | Curriculum-mandated e-textbook adoption generates predictable recurring revenue through university procurement. |
| DRM Interoperability Certification Investment | BIS technical standards compliance reduces platform switching friction for price-sensitive reader segments. |
| Direct Website Acquisition Channel Buildout | First-party relationships capture full margin and reading behavior data without app store revenue share. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with platform product managers, publishing house digital strategy leads, university procurement officers, and audiobook production studio heads. Secondary validation incorporated EU Digital Services Act regulatory filings, TRAI broadband pricing orders, BIS technical standard documentation, and cloud hyperscaler infrastructure capex disclosures. Bottom-up triangulation across service type, customer segment, and platform technology dimensions converged with top-down macroeconomic calibration.
Calibration against historical subscription adoption curves and institutional licensing penetration rates anchored the analytical framework across the analysis window. Segmentation modeling incorporated service type differentiation, customer application context, hardware-software integration intensity, and distribution channel economics. CAGRs were derived from fitted growth curves adjusted for regulatory inflection timing and technology adoption S-curve positioning. Forecast inputs included mobile data cost elasticity parameters and synthetic narration quality improvement trajectories.
Sensitivities concentrate around GDPR algorithmic accountability enforcement intensity and generative AI narration quality threshold crossing timing. Forecasts reflect assumptions regarding institutional procurement budget stability and cloud infrastructure pricing power persistence. Cross-checking against App Annie mobile session data and university library patron-driven acquisition reporting is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
US Social Commerce Market
E-Commerce Solutions
Second-Hand E-Commerce Market
E-Commerce Solutions
IT Consumer Electronics E-Commerce Market
E-Commerce Solutions
Middle East and Africa E-Commerce Market
E-Commerce Solutions
Social Commerce Market
E-Commerce Solutions
Australia E-Commerce Market
E-Commerce Solutions
China Online Trading Platform Market
E-Commerce Solutions
China E-Commerce Market
E-Commerce Solutions
China Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
North Macedonia E-Commerce Market
E-Commerce Solutions
Slovak Republic E-Commerce Market
E-Commerce Solutions
Italy E-Commerce Market
E-Commerce Solutions
Indonesia E-Commerce Market
E-Commerce Solutions
Malta E-Commerce Market
E-Commerce Solutions
North America Dropshipping Market
E-Commerce Solutions
India Alcohol E-Commerce Market