
 Asia-Pacific E-Commerce Apparel Market | 2026-2036
Asia-Pacific E-Commerce Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific E-Commerce Apparel Market Insights
China's GB standards for textile labeling and safety is restructuring the cost-of-entry calculus for cross-border sellers entering the mainland. Alibaba Group leverages its Cainiao logistics backbone to control last-mile delivery costs across tiered city networks. JD.com sustains inventory depth through captive warehousing and same-day fulfillment infrastructure. Shopee navigates fragmented Southeast Asian customs regimes by anchoring distribution in Singapore and Indonesia.
Asia-Pacific E-Commerce Apparel encompasses digitally distributed garments sold through web-based platforms and native mobile applications, with technical specifications governed by fiber content disclosure, flammability ratings, and size-standardization protocols that vary by destination country. The category serves both discretionary fashion consumption and functional wardrobe replacement cycles across climates ranging from tropical to temperate. Activewear leads product type momentum as gym culture and remote-work casualization converge across South Korean and Australian buyer bases. Mobile Apps capture the fastest-growing distribution channel share where super-app ecosystems integrate payment, discovery, and delivery in single interfaces. Premium price tiers concentrate margin pools in Japan and South Korea where brand heritage commands sustained willingness-to-pay.
India's BIS textile certification requirements and Australia's ACCC consumer guarantee enforcement create dual compliance burdens for pan-regional operators. Japan's METI guides circular economy pilots that mandate fiber recycling disclosures on platform listings. South Korea's MFDS-aligned textile safety alerts shape product recall protocols for infant and skin-contact categories. Stakeholders must monitor evolving data-localization mandates that could fragment customer-analytics capabilities across national jurisdictions.
Market Dynamics
Live-stream commerce infrastructure is compressing purchase cycles across China's tier-two cities while fragmenting inventory control for cross-border sellers adapting to GB textile labeling mandates.
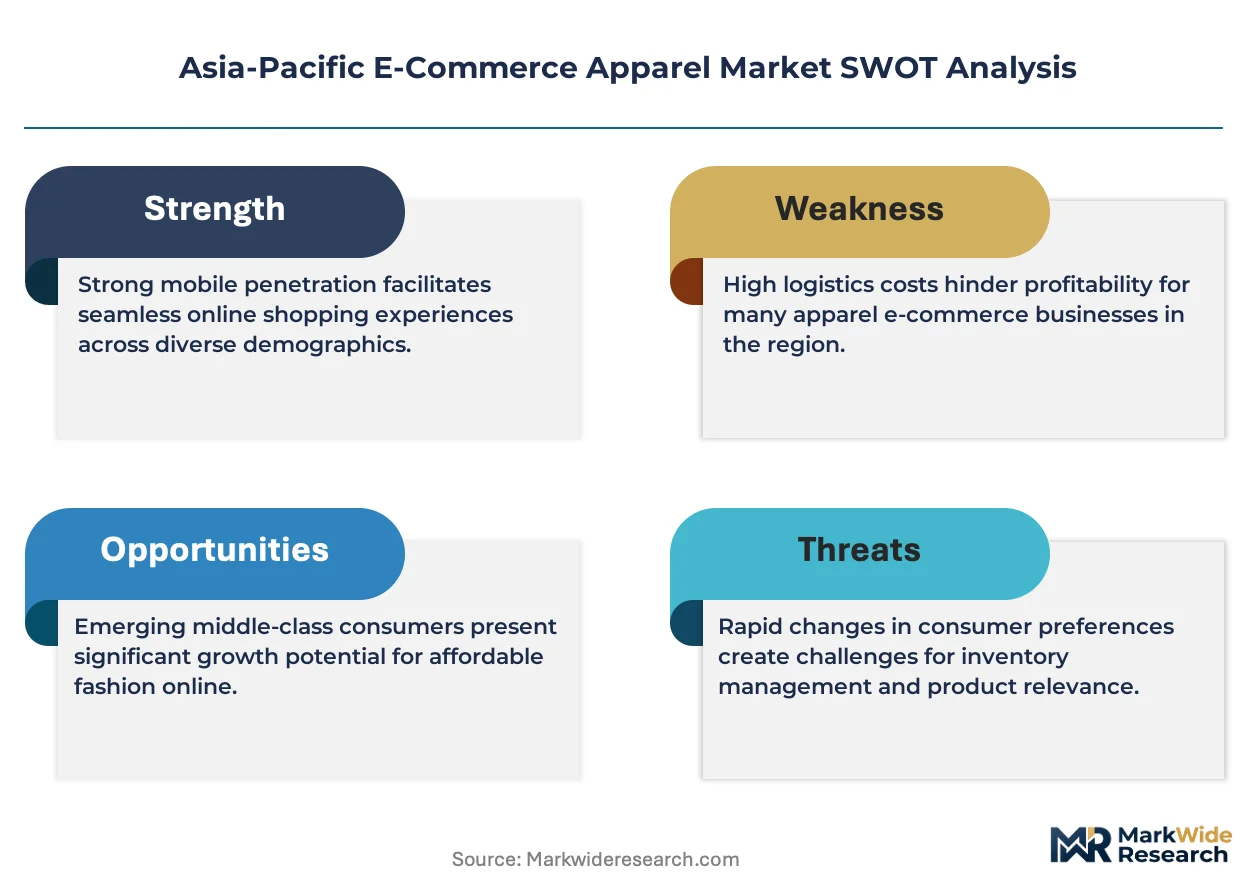
Growth Catalysts
- India's PLI scheme:Production-linked incentives for textile manufacturing are pulling garment production away from coastal China toward Gujarat and Tamil Nadu clusters. Domestic fulfillment costs drop as origin-to-consumer distance shrinks.
- Mobile-first purchasing habits:Young urban professionals in Jakarta, Bangkok, and Ho Chi Minh City complete transactions entirely within super-app ecosystems integrating discovery, payment, and delivery tracking.
- Activewear demand convergence:Gym culture normalization and remote-work casualization across South Korea and Australia are expanding SKU velocity in moisture-wicking and compression categories.
Market Restraints
- Cotton price volatility:Input cost swings tied to Pakistani and Indian monsoon patterns compress margin predictability for mid-market private-label operators.
- Supply concentration risk:Zhejiang and Guangdong provinces still control over 60% of woven garment finishing capacity, creating single-geography exposure for platform-dependent brands.
- Technical limitation:Size-standardization protocols remain incompatible between Japan's JIS measurements and Australia's AS sizing, forcing redundant inventory splits.
Strategic Opportunities
- Vietnam's underpenetrated tier-two cities:Da Nang and Can Tho show rising disposable income without saturated platform competition, opening first-mover positioning for curated vertical brands.
- Japan's METI circular economy pilots:Mandatory fiber recycling disclosures on platform listings create premium positioning for brands with verified closed-loop supply chains.
- AI-driven virtual try-on convergence:Computer vision and AR rendering technologies are reducing return rates in fit-critical categories like denim and tailored outerwear.
Industry Challenges
- BIS certification timelines:India's Bureau of Indian Standards textile testing backlog stretches 14-18 weeks, delaying product launches for pan-regional catalogs.
- Legacy ERP integration:Southeast Asian marketplace sellers struggle to reconcile Shopee and Lazada API data formats with existing inventory management systems.
- Cross-border data localization:Australia's ACCC consumer guarantee enforcement requires transaction data storage within national jurisdiction, fragmenting customer-analytics capabilities.
Report Scope
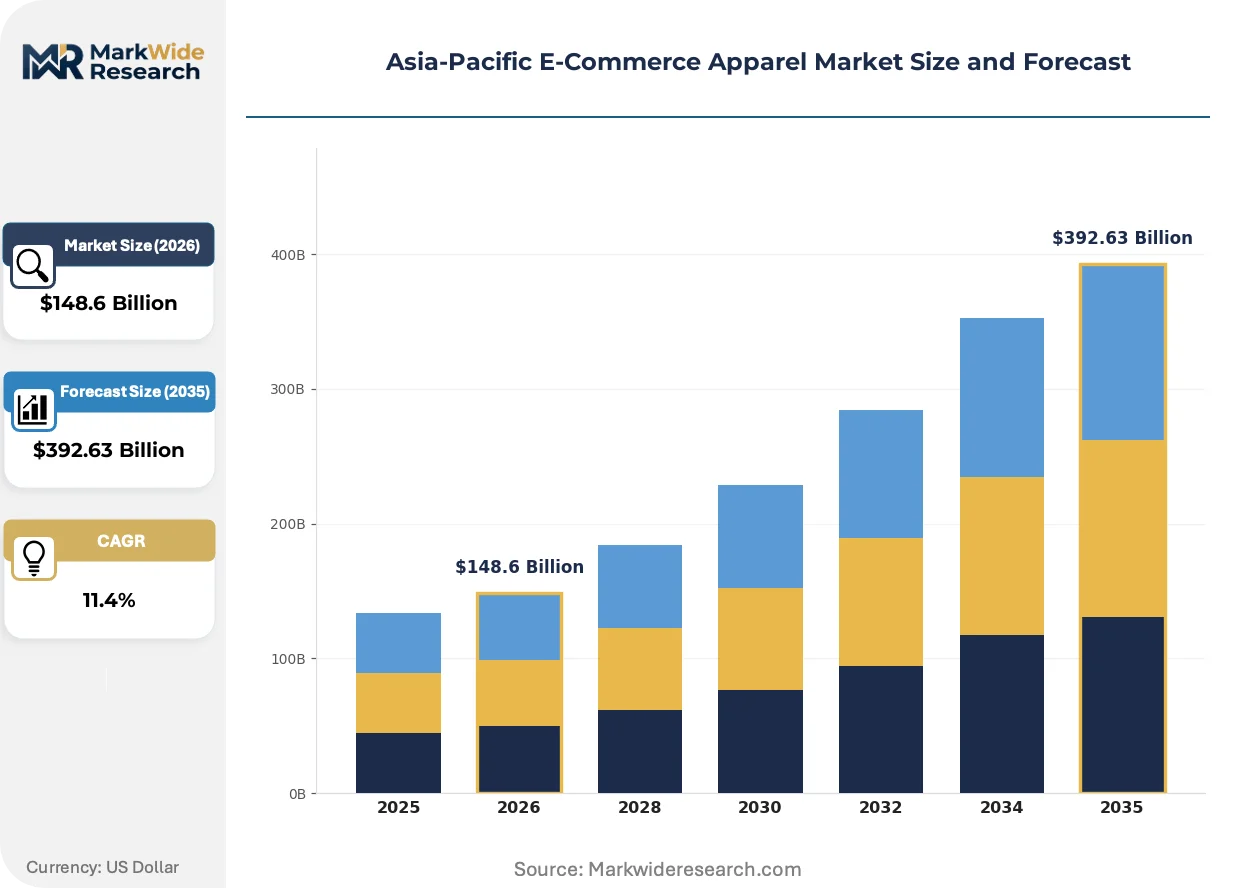
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific E-Commerce Apparel Market |
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $392.63 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: T-Shirts, Dresses, Jeans, Activewear Customer Type: Men, Women, Children, Unisex Distribution Channel: Online Marketplaces, Brand Websites, Social Media, Mobile Apps Price Tier: Premium, Mid-Range, Budget, Discounted |
| Companies Covered | Ajio, Inditex, Alibaba Group, Shopee, Hennes & Mauritz AB, JD.com, Fast Retailing Co., Ltd., Coupang, Myntra, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific E-Commerce Apparel Market Trends and Innovations
Digitally native supply chains are collapsing traditional wholesale-to-retail timelines while embedding compliance checkpoints earlier in product development workflows.
Blockchain-based fiber provenance tracking is electrifying transparency expectations among premium buyers in Japan and South Korea. Luxury consignment platforms now require chain-of-custody documentation for cashmere and silk categories. This technology is compressing authentication costs while opening secondary-market revenue streams for original manufacturers.
China's GB 18401 national textile safety standard is forcing reformulation of dye chemistry across cross-border seller portfolios. The standard's formaldehyde and pH limits exceed previous industry baselines, triggering lab retesting cycles. Infant and skin-contact apparel categories face the steepest compliance ramps, with some sellers exiting those SKUs entirely.
Social commerce discovery patterns are displacing search-based purchasing in Southeast Asian markets. Young buyers in Indonesia and the Philippines encounter products through influencer live streams rather than category browsing, shifting marketing spend toward commission-based creator partnerships. This behavioral pivot concentrates demand spikes around campaign windows, straining just-in-time inventory systems.
Asia-Pacific E-Commerce Apparel Market Segmentation
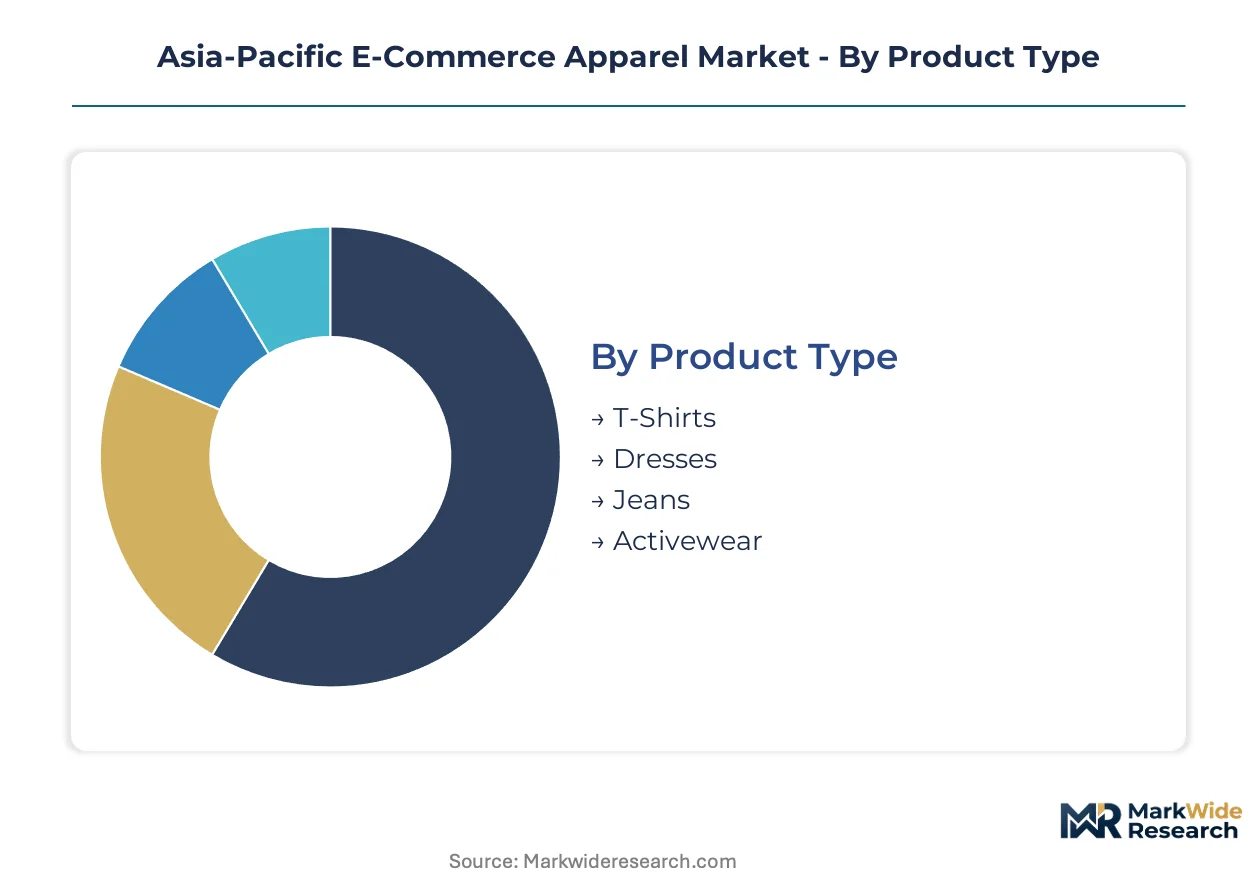
Segmentation in Asia-Pacific E-Commerce Apparel reveals how purchasing behavior fragments across platform interfaces, demographic cohorts, and price sensitivity thresholds. Each dimension carries distinct compliance burdens and logistics requirements that reshape margin structures for cross-border operators.
Product Type:
Garment categories diverge sharply in return rates, size-standardization complexity, and fiber certification requirements across destination markets.
- Activewear:Compression fabrics and moisture-wicking synthetics dominate South Korean and Australian buyer baskets as gym culture normalizes. Technical specifications around stretch recovery and breathability ratings command premium positioning in these markets.
- T-Shirts:Cotton-jersey basics generate the highest transaction velocity across Southeast Asian mobile commerce, though India's BIS fiber-content labeling mandates extend testing timelines for imported inventory. Volume concentrates in repeat-purchase wardrobe replenishment cycles.
- Dresses:Fit-critical silhouettes drive elevated return rates in markets lacking standardized sizing protocols, straining reverse-logistics networks.
- Jeans:Denim's weight-to-value ratio compresses cross-border shipping economics, favoring regional fulfillment nodes over direct-from-origin models.
Volume sits with T-Shirts; growth tilts toward Activewear.
Customer Type:
Age-gender cohorts exhibit divergent platform preferences and privacy-posture tolerances that reshape data-capture strategies.
- Women:Apparel purchases integrate with lifestyle content consumption across Indonesian and Philippine social commerce streams, concentrating demand around influencer campaign windows. Category breadth spans professional, casual, and occasion-wear with distinct fit expectations.
- Men:Transaction cycles compress in China's tier-two cities where live-stream commerce reduces consideration phases for standard-fit categories. Repeat-purchase loyalty concentrates in basic replenishment SKUs.
- Children:Infant and skin-contact categories face the steepest compliance ramps under China's GB 18401 safety standards, with some cross-border sellers exiting these SKUs entirely.
- Unisex:Gender-neutral sizing reduces inventory fragmentation for private-label operators, though Japan's JIS measurement protocols still require localized grading.
Revenue concentrates in Women; Unisex is climbing the fastest as casualization erodes traditional gendered merchandising.
Distribution Channel:
Platform choice determines payment integration depth, logistics control, and customer data ownership for apparel sellers.
- Mobile Apps:Super-app ecosystems in Jakarta, Bangkok, and Ho Chi Minh City embed discovery, payment, and delivery tracking in single interfaces. Young urban professionals complete entire purchase journeys without platform switching.
- Online Marketplaces:Alibaba and JD.com control inventory depth through captive warehousing, while Shopee navigates fragmented Southeast Asian customs regimes via Singapore and Indonesia distribution anchors.
- Social Media:Influencer-driven discovery displaces search-based purchasing in Indonesia and the Philippines, shifting marketing spend toward commission-based creator partnerships.
- Brand Websites:Direct-to-consumer models retain customer-analytics capabilities but face Australia's ACCC-mandated data-localization requirements that fragment cross-border analytics.
Transaction volume flows through Online Marketplaces; Mobile Apps are gaining share fastest as super-app penetration deepens.
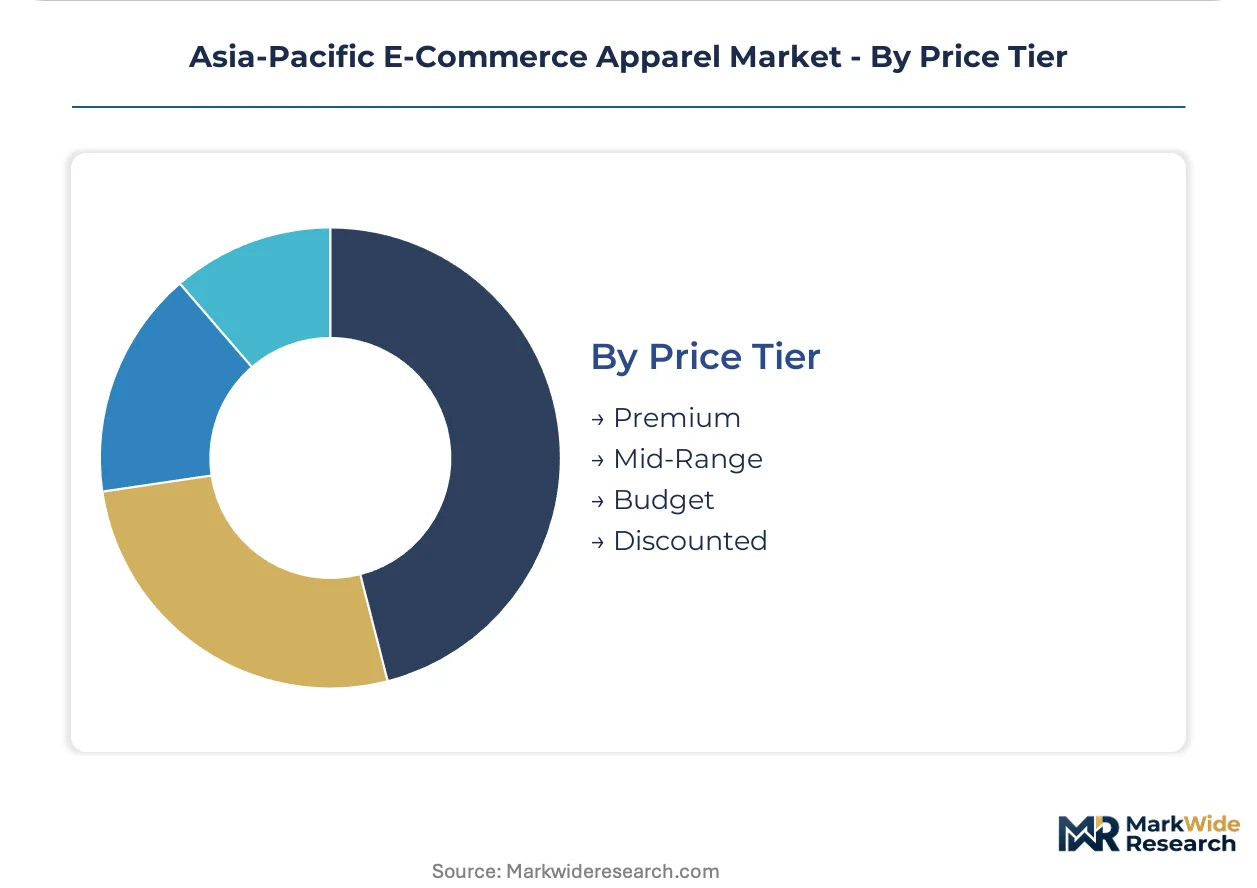
Price Tier:
Willingness-to-pay stratifies across brand heritage recognition, certification transparency, and circular-economy credentials.
- Premium:Verified fiber provenance and closed-loop supply chains command sustained pricing power in Japan and South Korea. Blockchain-based chain-of-custody documentation now gates entry to luxury consignment platforms.
- Mid-Range:Private-label operators in this band face compressed margins from cotton price volatility tied to Pakistani and Indian monsoon patterns.
- Budget:Domestic fulfillment cost advantages from India's PLI textile manufacturing incentives enable competitive positioning against coastal China origin models.
- Discounted:Flash-sale mechanics concentrate demand spikes that strain just-in-time inventory systems, particularly in social-commerce campaign windows.
Margin pools concentrate in Premium; Budget tier is expanding most quickly as India's manufacturing incentives restructure regional cost curves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's SEZ framework for textile manufacturing under the PLI scheme is concentrating garment production in Gujarat and Tamil Nadu clusters, shortening fulfillment distances to domestic consumers.
China
Live-stream commerce penetration in tier-two cities like Chengdu and Xi'an compresses purchase cycles for standard-fit categories. GB 18401 textile safety standards force dye chemistry reformulation across cross-border seller portfolios. Zhejiang and Guangdong provinces retain over 60% of woven garment finishing capacity, creating single-geography exposure for platform-dependent brands.
India
BIS certification requirements for fiber-content labeling extend testing timelines to 14-18 weeks, delaying product launches for pan-regional catalogs. The PLI scheme for textile manufacturing pulls production toward Gujarat and Tamil Nadu, shrinking origin-to-consumer distances. Domestic fulfillment cost advantages enable competitive positioning against coastal China origin models.
Japan
METI circular economy pilots mandate fiber recycling disclosures on platform listings, creating premium positioning for verified closed-loop supply chains. JIS measurement protocols require localized grading that fragments inventory for unisex categories. Tokyo and Osaka concentrate demand for heritage-brand apparel with sustained willingness-to-pay.
South Korea
MFDS-aligned textile safety alerts shape product recall protocols for infant and skin-contact categories. Gym culture normalization drives compression fabric and moisture-wicking synthetic demand in Seoul and Busan. Blockchain-based fiber provenance documentation gates entry to luxury consignment platforms for cashmere and silk.
Vietnam
Da Nang and Can Tho show rising disposable income without saturated platform competition, opening first-mover positioning for curated vertical brands. Shopee navigates fragmented customs regimes via Singapore and Indonesia distribution anchors. Young urban professionals in Ho Chi Minh City complete transactions entirely within super-app ecosystems.
Asia-Pacific E-Commerce Apparel Market Competitive Landscape
China-based platforms anchor one tier; Southeast Asian specialists hold the mobile-first interface layer. The vendor base splits between inventory-heavy captive warehousing operators and asset-light marketplace facilitators. Three archetypes dominate: super-app ecosystems integrating payment and logistics, vertically integrated retailers controlling end-to-end supply chains, and social commerce enablers monetizing creator-driven discovery. Competitive moves concentrate on M&A for logistics assets and strategic partnerships for customs-clearance capabilities.
Among China-based platforms, Alibaba Group and JD.com exemplify the captive warehousing archetype through Cainiao backbone control and same-day fulfillment infrastructure. Shopee occupies a position bridging Southeast Asian marketplace fragmentation with Singapore-anchored distribution. Fast Retailing Co., Ltd. represents heritage-brand positioning with sustained pricing power in Japan and South Korea premium tiers.
| Leading Market Players |
|---|
| Ajio |
| Inditex |
| Alibaba Group |
| Shopee |
| Hennes & Mauritz AB |
| JD.com |
| Fast Retailing Co., Ltd. |
| Coupang |
| Myntra |
| Others |
Pricing and Supply Chain Analysis
Japan's METI circular economy pilots gate qualified supply access and premium-tier pricing power by mandating fiber recycling disclosures that only verified closed-loop manufacturers can satisfy. Buyers in Tokyo and Osaka pay sustained premiums for blockchain-documented provenance while sellers lacking certification face margin compression in mid-market tiers.
Pricing Analysis
Lead-time-driven pricing stratifies across fulfillment speed tiers, with same-day delivery in China's tier-two cities commanding 15-25% premiums over standard shipping windows. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification depth and brand heritage recognition. Pricing pressure stems from India's PLI manufacturing incentives compressing origin costs for budget-tier operators. Budget buyers in Southeast Asian mobile commerce show highest price sensitivity, while Japanese heritage-brand purchasers demonstrate lowest elasticity.
Supply Chain Analysis
India's PLI scheme for textile manufacturing is reshaping sourcing patterns by pulling garment production toward Gujarat and Tamil Nadu clusters with domestic-content advantages. Raw material flows draw from Pakistani cotton, Vietnamese synthetic fiber, and Chinese dye chemistry. Single-geography exposure concentrates in Zhejiang and Guangdong provinces, where over 60% of woven garment finishing capacity creates vulnerability to regional disruption. Distribution runs through captive warehousing nodes in Singapore and Indonesia that anchor Southeast Asian marketplace fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computer vision and AR rendering technologies are displacing legacy size-standardization protocols, compressing return rates in fit-critical categories and reshaping competitive requirements across the forecast horizon.
For Market Incumbents: Cement control over last-mile logistics infrastructure in tier-two Chinese cities where live-stream commerce penetration deepens. Invest in captive warehousing capacity across Vietnam's underpenetrated Da Nang and Can Tho markets. Threat of AI-native virtual try-on specialists eroding fit-based brand loyalty makes logistics speed the priority defensive lever. For New Entrants and Emerging Players: India's BIS certification backlog opens a window for domestic-origin brands with pre-certified inventory to capture delayed cross-border demand. Target Vietnam's rising disposable income corridors before platform saturation sets in. Launch through super-app ecosystems in Ho Chi Minh City to embed discovery-to-delivery in single interfaces. For Investors and Strategic Acquirers: Shopee's Singapore-anchored distribution network consolidation is the leading indicator that Southeast Asian logistics assets are entering scarcity pricing. Five-to-ten year viability favors operators with customs-clearance capabilities and multi-country warehousing footprints. Watch for India's PLI scheme maturation as the signal that domestic-origin cost advantages have stabilized.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Fiber Provenance Integration | Japan's METI mandates now require chain-of-custody documentation for premium tier access. |
| Super-App Ecosystem Partnership | Indonesian and Philippine creator commerce embeds payment and logistics in single interfaces. |
| Vietnam Tier-Two City Distribution Anchor | Da Nang and Can Tho rising income lacks saturated platform competition for first-mover positioning. |
| GB 18401 Compliance Lab Investment | China's textile safety standards force dye chemistry reformulation for cross-border sellers. |
| India PLI-Aligned Manufacturing Scale-Up | Gujarat and Tamil Nadu clusters shrink origin-to-consumer distances for domestic fulfillment advantage. |
Research Methodology
Independent corroboration across platform operations executives, logistics infrastructure directors, textile compliance officers, and Southeast Asian marketplace sellers underwrites the qualitative findings in this study. Primary fieldwork combined with secondary validation from customs trade records, BIS certification databases, GB standard filings, and ACCC enforcement actions established demand and supply parameters. Bottom-up transaction volume estimates and top-down macroeconomic triangulation anchored the analytical framework.
Rate-of-change decomposition across the analysis window modeled volume and value trajectories through product type, customer cohort, distribution channel, and price tier segmentation. CAGRs derived from historical trajectory analysis and driver elasticity modeling incorporated mobile commerce penetration curves, live-stream commerce adoption patterns, and manufacturing incentive program maturation timelines as industry-specific inputs.
Caveats apply where cotton price volatility tied to monsoon patterns, BIS certification timeline extensions, or cross-border data localization mandates could materially shift the outlook. Forecasts reflect documented assumptions about regulatory enforcement consistency and infrastructure buildout pacing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
ASEAN E-Commerce Logistics Market
E-Commerce Solutions
UAE Ecommerce Market
E-Commerce Solutions
E-Commerce Lockers Market
E-Commerce Solutions
France E-Commerce Market
E-Commerce Solutions
T-Commerce Market
E-Commerce Solutions
South Africa E-Commerce Market
E-Commerce Solutions
Global B2B E-Commerce Market
E-Commerce Solutions
South Korea Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
E-Commerce Buy Now Pay Later Market
E-Commerce Solutions
Asia Pacific B2B E-Commerce Market
E-Commerce Solutions
FMCG B2B E-Commerce Market
E-Commerce Solutions
China E-Commerce Market
E-Commerce Solutions
Shopping Application Market
E-Commerce Solutions
Retail E-Commerce Market
E-Commerce Solutions
Slovakia E-Commerce Market
E-Commerce Solutions
E-Commerce Logistics Market