
 Saudi Arabia Delivery Apps Market | 2026-2036
Saudi Arabia Delivery Apps Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Delivery Apps Market Insights
The gap between premium full-service restaurant delivery and commodity quick-service tiers is realigning as commission structures and customer acquisition costs diverge sharply. Talabat leverages its cross-border logistics network to sustain delivery density across the Gulf corridor. HungerStation anchors its position through exclusive partnerships with national fast-food chains. Jahez competes aggressively on rider fleet scale in dense urban zones.
Saudi Arabia delivery apps constitute digital intermediaries connecting consumers with merchants through algorithmic order matching, GPS-enabled dispatch, and integrated payment settlement, typically processing transactions within fifteen-minute fulfillment windows for food and thirty-minute windows for grocery. The primary commercial purpose is reducing merchant customer acquisition cost while capturing recurring commission revenue from order flow. Food delivery dominates transaction volume but grocery delivery is expanding fastest as supermarket chains deploy dedicated dark stores. Mobile apps lead technology adoption while API integration is emerging as the margin pool where enterprise restaurant chains demand direct POS connectivity. Real-time tracking has matured into a baseline expectation rather than a differentiator.
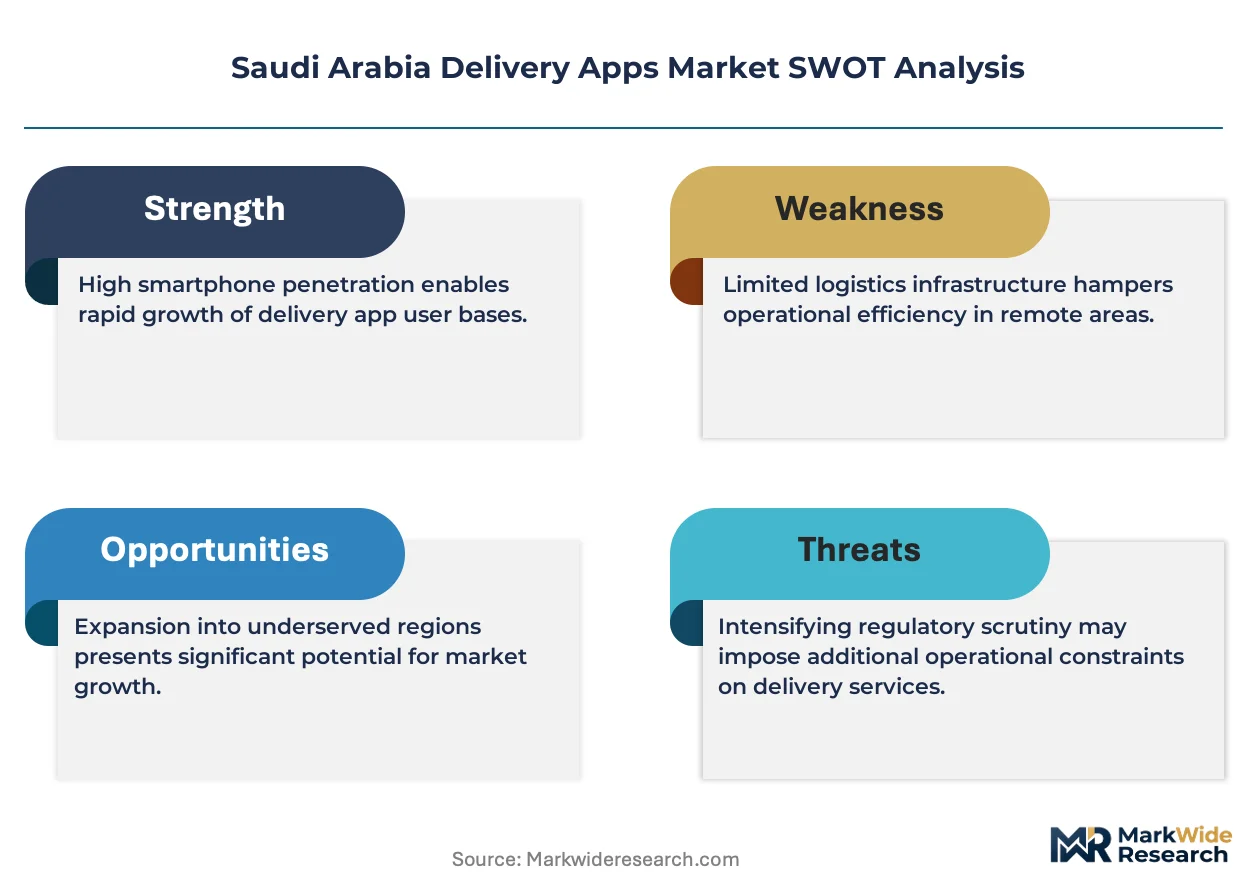
SFDA oversees food safety standards for cloud kitchens and delivery packaging, while SAMR monitors platform pricing transparency and merchant contract terms under competition law. The Communications and Information Technology Commission regulates data localization requirements for consumer transaction records. Stakeholders must monitor how SFDA's evolving hygiene certification rules for delivery-only kitchens reshape merchant onboarding costs and platform liability exposure.
Market Dynamics
The Saudi Food and Drug Authority's cloud kitchen licensing framework is compressing merchant onboarding timelines while concentrating operational compliance costs among smaller delivery-only operators, reshaping platform liability structures.
Growth Catalysts
- SFDA Cloud Kitchen Framework:The licensing regime accelerates formalization of delivery-only kitchens, reducing regulatory friction for platform-integrated merchants and expanding addressable supply.
- Riyadh Central Business District Demand Density:Corporate corridor concentration creates natural fulfillment clustering, reducing per-order logistics costs and improving rider utilization rates.
- Dark Store Grocery Infrastructure:Supermarket chains deploying dedicated fulfillment centers expand non-food transaction volume, diversifying platform revenue beyond restaurant commissions.
Market Restraints
- Rider Fleet Cost Inflation:Wage pressure in dense urban zones compresses per-delivery margins, particularly for platforms competing on fulfillment speed rather than exclusive merchant access.
- Merchant Commission Compression:National fast-food chains leverage exclusive partnership negotiations to reduce platform take rates, constraining revenue per transaction.
- Data Localization Compliance:Communications and Information Technology Commission requirements for consumer transaction record storage increase infrastructure capex for platform operators.
Strategic Opportunities
- Jeddah and Dammam Corridor Expansion:Secondary metropolitan areas show underpenetrated delivery density relative to Riyadh, offering first-mover logistics optimization advantages.
- API-First Enterprise Integration:Direct POS connectivity for mid-market restaurant chains creates margin pools outside standard commission structures.
- SAMR Pricing Transparency Enforcement:Competition law monitoring of merchant contract terms creates regulatory tailwind for platforms with standardized, auditable fee structures.
Industry Challenges
- SFDA Hygiene Certification Timelines:Evolving delivery-only kitchen standards create compliance backlogs, delaying merchant activation and increasing platform quality assurance overhead.
- Legacy POS Integration Complexity:Fragmented restaurant technology stacks require custom API development, extending enterprise sales cycles and implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Delivery Apps Market |
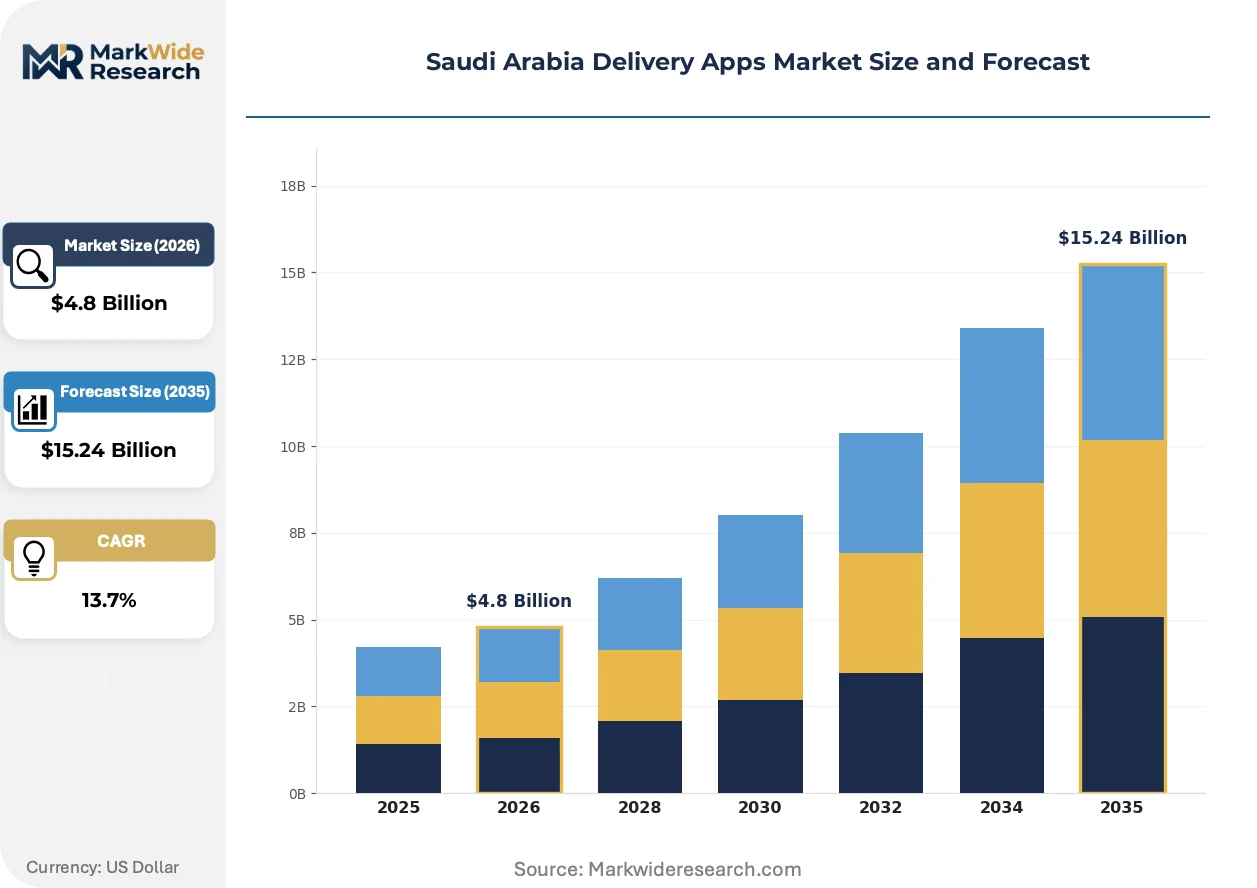
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Food Delivery, Grocery Delivery, Parcel Delivery, Alcohol Delivery Customer Type: Individuals, Businesses, Restaurants, Retailers Technology: Mobile Apps, Web Platforms, API Integration, Real-Time Tracking Payment Mode: Credit Card, Debit Card, Mobile Wallets, Cash |
| Companies Covered | Talabat, Keeta, HungerStation, ToYou, Ninja, Jahez, Careem, Matajer Central Co, Mrsool, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Delivery Apps Market Trends and Innovations
Algorithmic dispatch and real-time tracking have matured into baseline infrastructure, shifting competitive differentiation toward merchant exclusivity and fulfillment network density.
Artificial intelligence-driven demand forecasting is integrating historical order patterns with traffic and weather data to optimize rider positioning. Quick-service restaurant chains deploy predictive prep-time algorithms to reduce handoff delays. This compression of fulfillment variance is integrating delivery speed as a standardized service expectation rather than a premium tier.
SFDA's evolving packaging and hygiene certification requirements for cloud kitchens mandate temperature-controlled container standards and traceable sourcing documentation. The industrial consequence is elevated capital requirements for delivery-only kitchen fit-out. Smaller merchant operators in Riyadh's peripheral zones face the steepest compliance cost absorption.
Subscription-based delivery memberships are displacing per-order fee structures among frequent users. Urban professional segments in Riyadh's central business district now expect bundled fulfillment as a default utility. This behavioral shift is most visible in grocery delivery, where dark store operators compete on annual membership penetration rather than transaction margins.
Saudi Arabia Delivery Apps Market Segmentation
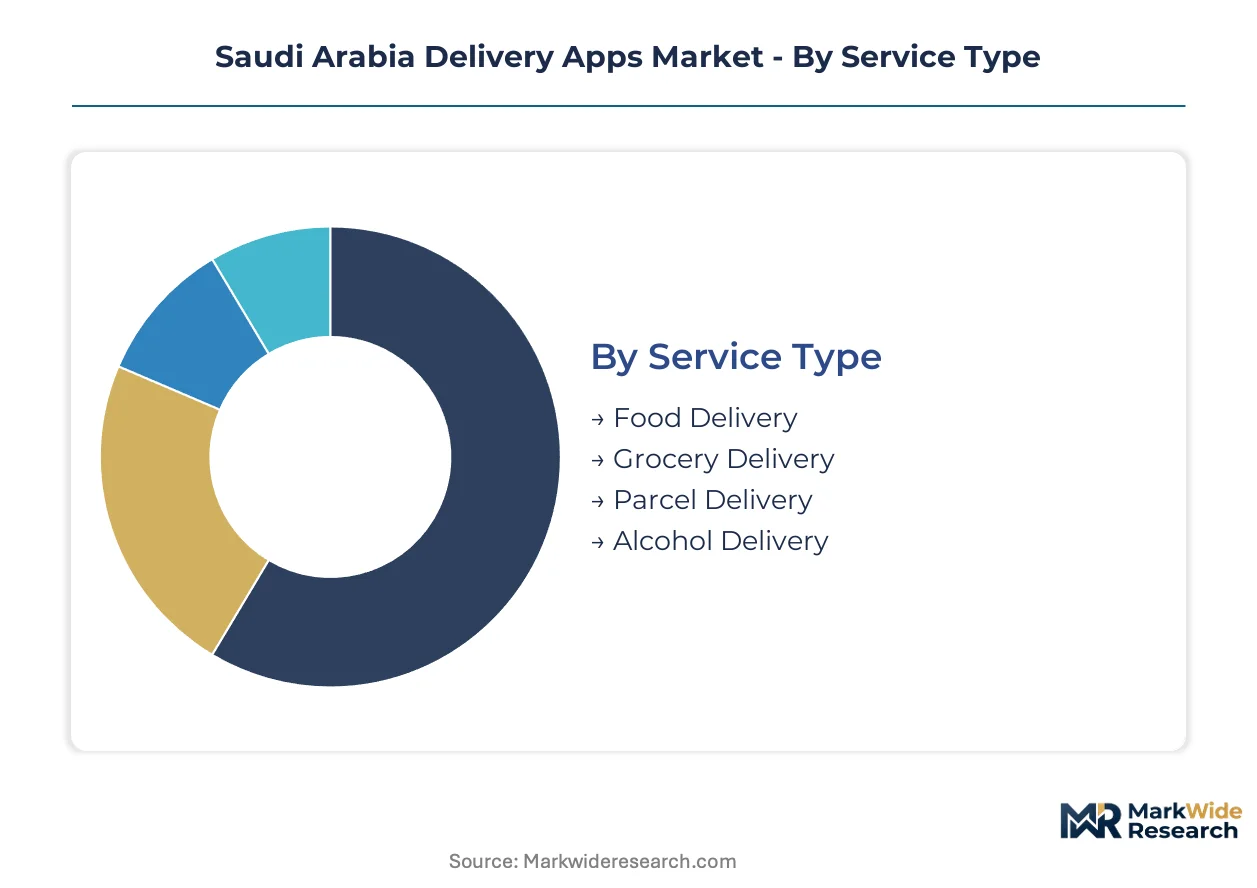
Delivery app monetization in Saudi Arabia diverges sharply across service types and customer profiles, with commission structures and fulfillment economics varying by order density and payment infrastructure. Understanding these segment boundaries clarifies where platform operators can extract margin versus where cost-to-serve erodes profitability.
Service Type:
Order frequency and basket composition determine platform revenue per user, with food commanding highest transaction volume but grocery expanding fulfillment network utilization.
- Food Delivery:Quick-service restaurant chains generate the densest order flow, with Riyadh's central business district corridor concentrating lunchtime demand into sub-fifteen-minute fulfillment windows. Commission rates here face downward pressure from national chain exclusivity negotiations.
- Grocery Delivery:Dark store infrastructure deployed by supermarket chains is displacing traditional store-pick models, with annual subscription memberships now default expectations among urban professional segments. This segment climbs fastest as fulfillment variance compresses toward standardized thirty-minute windows.
- Parcel Delivery:Cross-border logistics integration through Gulf corridor networks sustains delivery density for document and small-package flows.
- Alcohol Delivery:Regulatory constraints limit addressable geography to licensed zones, constraining merchant onboarding velocity.
Food delivery leads on scale; grocery delivery leads on momentum.
Customer Type:
Contract structure and order predictability separate recurring revenue pools from transactional acquisition costs.
- Individuals:Mobile app dominance among Saudi consumers creates direct-to-user acquisition channels, with subscription memberships displacing per-order fees for frequent users in dense urban zones.
- Restaurants:Enterprise chains demand API-first POS integration, creating margin pools outside standard commission structures through direct connectivity fees.
- Businesses:Corporate catering contracts in Riyadh's central business district generate batch order flows with predictable fulfillment windows and lower per-dispatch marketing spend.
- Retailers:Supermarket chains deploying dedicated dark stores require custom logistics integration, extending sales cycles but locking in volume commitments.
Restaurants anchor platform revenue; individuals drive volume expansion.
Technology:
Interface choice shapes customer acquisition cost and merchant integration complexity.
- Mobile Apps:Primary consumer interface with algorithmic order matching and GPS-enabled dispatch now baseline infrastructure rather than differentiation.
- API Integration:Direct POS connectivity for mid-market chains creates the steepest margin expansion opportunity as enterprise restaurant technology demands consolidate.
- Web Platforms:Secondary channel for corporate procurement workflows and merchant back-office order management.
- Real-Time Tracking:Matured into standardized expectation, with predictive prep-time algorithms now reducing handoff delays at quick-service locations.
Mobile apps dominate user acquisition; API integration captures enterprise margin.
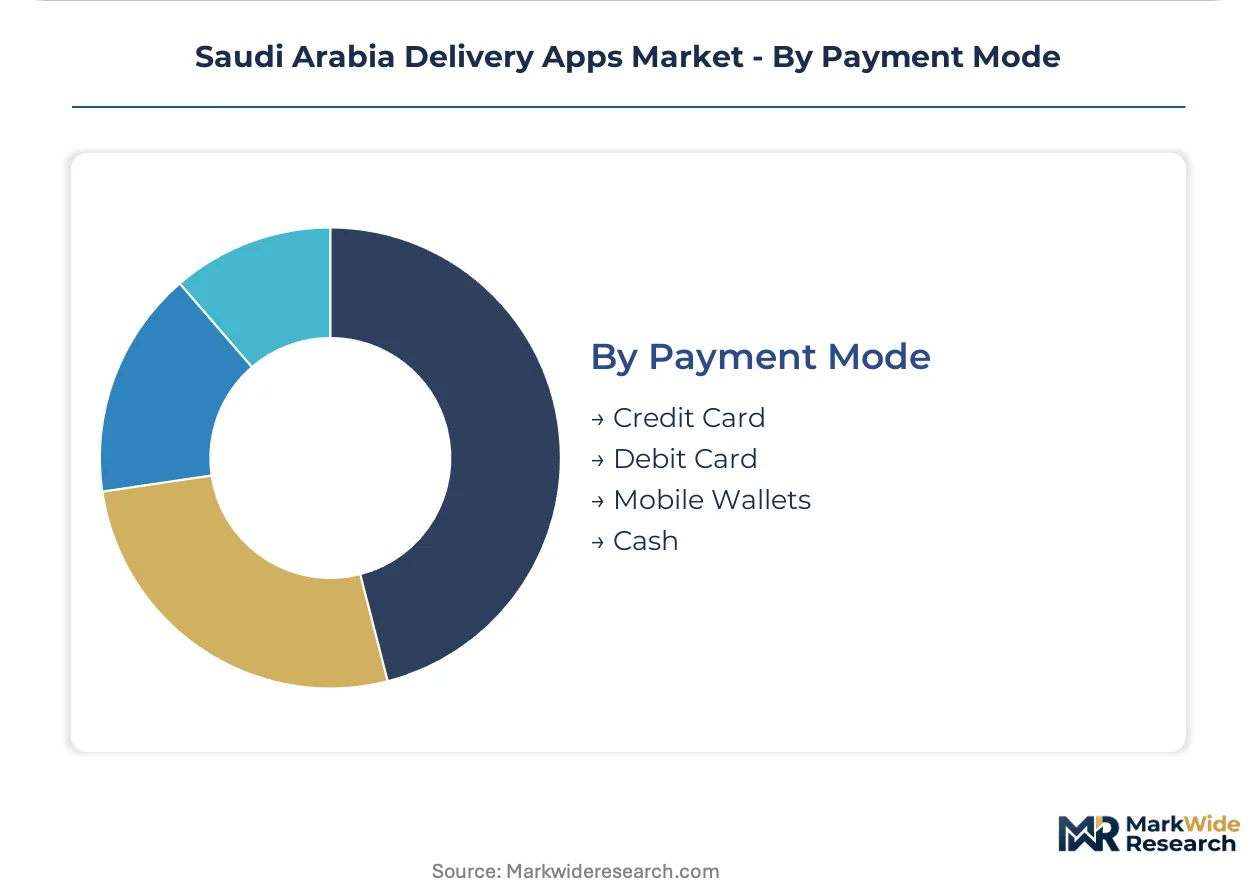
Payment Mode:
Settlement infrastructure affects platform working capital and fraud exposure.
- Mobile Wallets:Mada Pay and STC Pay integration accelerates checkout completion rates among Saudi consumers, reducing cart abandonment versus card entry flows.
- Credit Card:Corporate expense account integration supports business customer acquisition with automated receipt documentation.
- Debit Card:Dominant retail payment rail with lower interchange costs than credit products.
- Cash:Persistent preference in peripheral Riyadh zones and among unbanked segments, elevating rider handling costs and reconciliation overhead.
Mobile wallets gain share fastest; cash retains peripheral penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rider workforce density in Riyadh's central business district anchors national fulfillment capacity, while secondary metros build out logistics networks to capture spillover demand.
Riyadh
Corporate corridor concentration generates sub-fifteen-minute fulfillment windows for quick-service lunch orders. SAMR monitors platform-merchant contract terms under competition law enforcement. The King Abdullah Financial District drives subscription membership penetration among urban professionals.
Eastern Province
Industrial zone catering contracts create predictable batch order flows with lower per-dispatch marketing spend. SFDA cloud kitchen licensing accelerates formalization of delivery-only operations in Dammam. The Dammam-Khobar corridor attracts dark store grocery deployment from supermarket chains.
Western Region
Pilgrimage-season demand spikes strain rider fleet utilization around religious calendars. The Communications and Information Technology Commission enforces data localization for consumer transaction records. Jeddah's commercial districts concentrate quick-service restaurant chain exclusivity negotiations.
NEOM Northwest
Greenfield smart city infrastructure enables predictive logistics integration without legacy POS fragmentation. SFDA hygiene certification timelines for delivery-only kitchens compress under streamlined regulatory frameworks. The linear city development tests autonomous dispatch algorithms in controlled deployment zones.
Saudi Arabia Delivery Apps Market Competitive Landscape
Top-tier vendors anchor cross-border logistics networks, while mid-scale platforms compete on rider fleet density in urban zones. The vendor base stratifies around three strategic archetypes: Gulf corridor integrators leveraging regional fulfillment density, national exclusivity holders locking in fast-food chain partnerships, and urban specialists optimizing dispatch algorithms for dense metropolitan grids. Competitive moves concentrate on merchant exclusivity negotiations and dark store infrastructure deployment.
Among Gulf-integrated platforms, Talabat leverages cross-border logistics networks to sustain delivery density across regional corridors. HungerStation exemplifies the national exclusivity archetype through partnerships with established quick-service chains. Jahez anchors the urban specialist tier, competing on rider fleet scale in dense metropolitan zones like Riyadh's central business district.
| Leading Market Players |
|---|
| Talabat |
| Keeta |
| HungerStation |
| ToYou |
| Ninja |
| Jahez |
| Careem |
| Matajer Central Co |
| Mrsool |
| Others |
Pricing and Supply Chain Analysis
Dark store grocery infrastructure simultaneously compresses fulfillment unit economics and concentrates supplier bargaining power among Saudi supermarket chains operating dedicated fulfillment centers. API-first POS integration for enterprise restaurant chains creates parallel margin pools that decouple platform revenue from standard commission structures.
Pricing Analysis
Bundled subscription memberships versus per-order transaction fees split the pricing architecture across user frequency tiers. Three-tier pricing structure across premium, standard, and economy levels differentiates by fulfillment speed and merchant exclusivity, with corporate catering contracts commanding lowest per-dispatch rates due to batch order predictability. Pricing pressure stems from national fast-food chains leveraging exclusive partnership negotiations to compress platform take rates. Quick-service restaurant chains show lowest price sensitivity due to volume guarantees, while peripheral zone individual users exhibit highest sensitivity to delivery fees.
Supply Chain Analysis
Single-source vulnerability sits with concentrated cloud kitchen equipment suppliers and temperature-controlled packaging manufacturers serving Riyadh's delivery-only operators. Geographic supply concentration draws from China for GPS-enabled dispatch hardware, India for rider fleet management software, and Germany for cold-chain logistics components. Raw material dependencies include lithium-ion batteries for electric motorbikes, food-grade insulated containers, and algorithmic routing software licenses. Supply chain risk centers on tariff exposure for imported rider fleet hardware. Distribution runs through platform-operated dark stores and merchant-integrated cloud kitchens with direct-to-consumer last-mile dispatch.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Saudi Arabia delivery apps rests on subscription membership penetration compressing customer acquisition costs and API integration fees capturing enterprise restaurant technology spend.
For Market Incumbents: Hedge against merchant commission compression by deepening API-first POS connectivity for mid-market restaurant chains, locking in direct connectivity fees outside standard commission structures. Expand rider fleet scale in Riyadh's central business district to sustain sub-fifteen-minute fulfillment windows as a defensive moat against urban specialists. Counter national fast-food chain exclusivity negotiations with predictive prep-time algorithm investments that reduce handoff delays. For New Entrants and Emerging Players: Direct-to-merchant SaaS integration offers the lowest customer acquisition cost route for capturing mid-market restaurant chains frustrated by legacy POS fragmentation. Target Jeddah and Dammam corridor expansion where delivery density remains underpenetrated relative to Riyadh, offering first-mover logistics optimization advantages. Lead with SFDA hygiene certification compliance tooling as a go-to-market angle to accelerate merchant onboarding timelines for smaller delivery-only operators. For Investors and Strategic Acquirers: Valuations sit cheapest among urban specialist platforms with dense rider fleets but limited cross-border logistics integration, presenting acquisition targets for Gulf corridor integrators seeking metropolitan scale. Long-term viability favors platforms with diversified revenue beyond food delivery into grocery dark store infrastructure and parcel logistics. Watch SAMR pricing transparency enforcement actions as the inflection indicator for standardized fee structure advantages.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Enterprise Integration | Direct POS connectivity for Jahez and HungerStation captures margin pools outside standard commission structures. |
| Dark Store Infrastructure Deployment | Talabat's grocery fulfillment center expansion diversifies platform revenue beyond restaurant commissions. |
| Rider Fleet Scale Expansion | Jahez competes on dispatch density in Riyadh's central business district corridor. |
| Cross-Border Logistics Integration | Talabat leverages Gulf corridor networks to sustain delivery density across regional markets. |
| SFDA Compliance Technology Investment | Platforms reducing hygiene certification timelines for cloud kitchens accelerate merchant activation velocity. |
Research Methodology
Coverage spans Riyadh, Jeddah, Dammam, and the Eastern Province corridor, with primary inputs from each metropolitan cluster. The approach combines structured interviews with platform operations directors, restaurant technology procurement leads, cloud kitchen operators, and SFDA compliance officers with secondary validation from CITC regulatory filings, SAMR competition law disclosures, and supermarket chain capex announcements. SEC filings of Gulf-integrated platform parents, delivery app user analytics, and dark store deployment databases provided additional triangulation. Bottom-up merchant onboarding velocity models and top-down addressable supply calculations were reconciled.
Granularity-level modeling disaggregated the analysis window by service type, customer archetype, technology interface, and payment mode, with additional dimensioning by metropolitan zone density tier. CAGRs were derived from logistic cost curves, commission rate trajectories, and subscription membership penetration assumptions across the projection horizon. Forecast inputs included SFDA cloud kitchen licensing velocity, rider wage inflation indices, and Mada Pay integration adoption curves.
The model assumes a particular technology adoption path; alternative pathways for autonomous dispatch algorithms or drone logistics would alter the outlook. Forecasts reflect assumptions about SFDA hygiene certification timeline compression and SAMR pricing transparency enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Global Healthcare E-Commerce Market
E-Commerce Solutions
China E-Commerce Market
E-Commerce Solutions
Indonesia Ecommerce Logistics Market
E-Commerce Solutions
Europe FMCG B2B E-Commerce Market
E-Commerce Solutions
UAE Q-Commerce Industry Market
E-Commerce Solutions
Europe Automotive E-Commerce Market
E-Commerce Solutions
Canada E-Commerce Market
E-Commerce Solutions
Pharma E-Commerce Market
E-Commerce Solutions
Denmark E-Commerce Market
E-Commerce Solutions
Quiet Commerce Market
E-Commerce Solutions
Asia-Pacific E-Commerce Apparel Market
E-Commerce Solutions
Nigeria Alcohol E-Commerce Market
E-Commerce Solutions
Serbia E-Commerce Market
E-Commerce Solutions
E-Commerce in Luxembourg Market
E-Commerce Solutions
Spain E-Commerce Market
E-Commerce Solutions
UK Ecommerce Market