
 Global Corporate Wellness Software Market | 2026-2036
Global Corporate Wellness Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Corporate Wellness Software Market Foresight
Cloud infrastructure is rebalancing the cost structure of wellness platform delivery as on-premises legacy systems face displacement. Virgin Pulse leverages extensive behavioral data architecture to sustain engagement rates across large employer populations. ComPsych anchors its competitive position through integrated employee assistance programming that extends beyond software into clinical service layers. Provant Health Solutions specializes in biometric screening coordination, differentiating through occupational health workflow depth rather than pure digital scale.
Corporate wellness software encompasses digital platforms that aggregate health risk assessments, fitness tracking telemetry, and mental wellbeing interventions through configurable dashboards and API-connected wearable ecosystems. These systems process physiological data streams, apply algorithmic nudge protocols, and generate population-level analytics to reduce employer insurance outlays and absenteeism. Cloud-Based deployment dominates current procurement patterns among technology firms seeking rapid implementation without capital infrastructure commitment, while Mental Wellbeing solution offerings represent the fastest-expanding segment as post-pandemic employer liability frameworks evolve. Stress Management applications retain mature, high-volume status across financial institutions where regulatory pressure on trader and analyst working conditions intensifies.
FDA oversight of software-as-medical-device classifications shapes how wellness platforms incorporate diagnostic-adjacent features without triggering premarket submission requirements. The EU AI Act imposes risk-tiered conformity obligations on algorithmic health coaching outputs, compelling vendors to reengineer recommendation engines for European deployment. OSHA workplace health standards and HIPAA privacy guardrails collectively determine data architecture choices and third-party integration boundaries across US employer implementations. Stakeholders must monitor whether emerging FDA guidance on mental health software will reclassify certain cognitive behavioral tools as regulated medical devices, forcing platform redesign or market exit.
Market Dynamics
The EU AI Act's risk-tiered conformity obligations are forcing algorithmic health coaching vendors to reengineer recommendation engines before European deployment, compressing product development timelines while expanding compliance budgets.
Growth Catalysts
- Self-insured employer procurement:Large US employers with captive insurance arrangements are consolidating wellness platform spending into single-vendor contracts that bundle biometric screening with mental health modules.
- OSHA workplace health standards:Regulatory pressure on financial institutions to document trader stress management protocols is mandating software-based intervention tracking.
- API-connected wearable ecosystems:Real-time physiological data streams from consumer devices are enabling algorithmic nudge protocols that drive sustained user engagement.
Market Restraints
- FDA software-as-medical-device classification:Diagnostic-adjacent features risk triggering premarket submission requirements that stall product roadmaps.
- Cloud infrastructure concentration:Reliance on hyperscaler compute creates vendor lock-in and exposes margins to egress pricing volatility.
- HIPAA privacy guardrails:Third-party integration boundaries constrain data architecture choices and limit cross-platform analytics.
Strategic Opportunities
- India's PLI scheme for digital health:Production-linked incentives for software development centers are attracting wellness platform R&D investment.
- EMA medical device regulation convergence:Alignment pathways between wellness software and regulated digital therapeutics create premium pricing tiers.
- Biometric screening + mental health convergence:Integrated platforms that correlate physiological markers with psychological state data command enterprise procurement preference.
Industry Challenges
- Algorithmic bias audit capabilities:Shortage of data scientists with health equity certification is delaying EU AI Act compliance submissions.
- Legacy on-premises system integration:Occupational health departments with decades-old HRIS infrastructure resist API-first platform migration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Corporate Wellness Software Market |
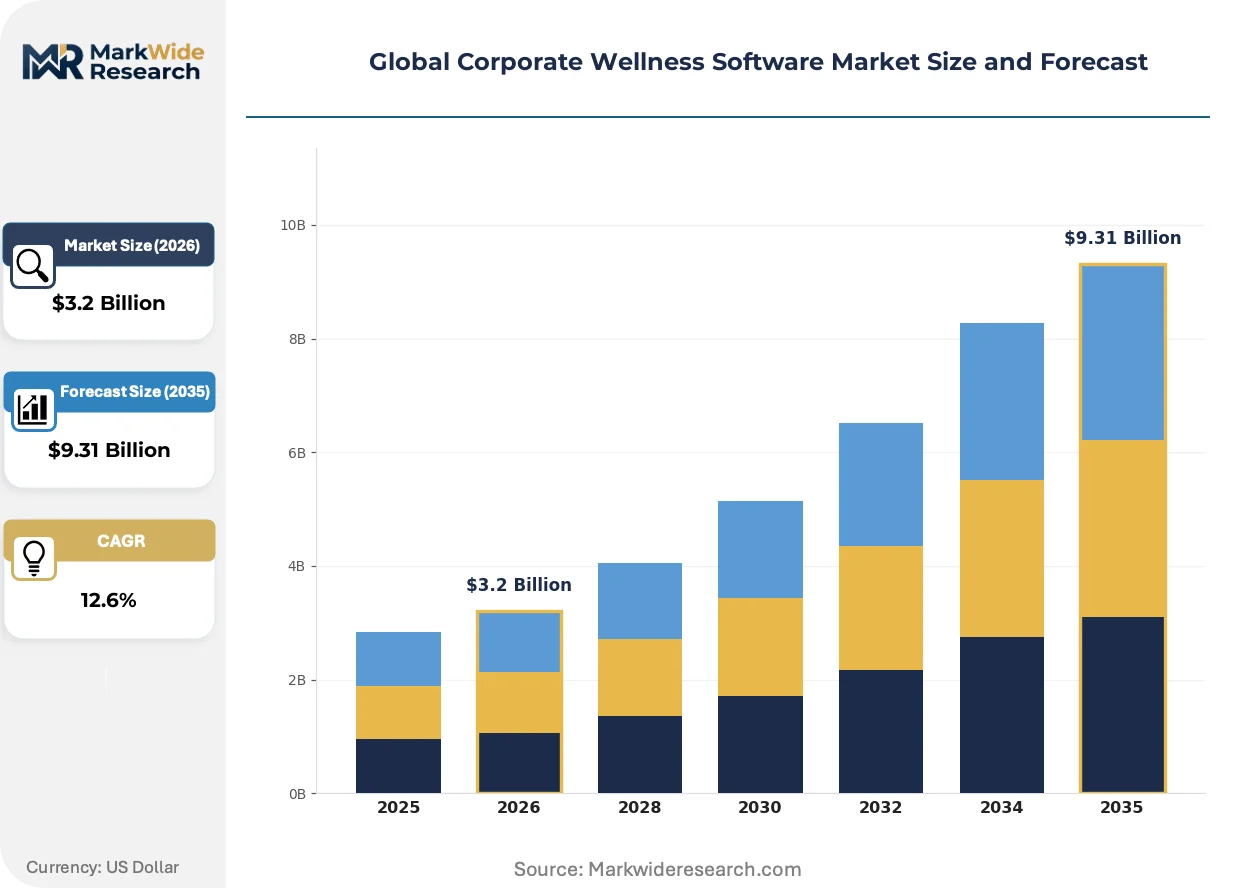
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $9.31 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS, Managed Hosting Solution Offering: Health Risk Assessment, Fitness Tracking, Mental Wellbeing, Nutrition Management, Employee Engagement Application: Stress Management, Chronic Disease Prevention, Lifestyle Management, Occupational Health, Work-Life Balance End User Industry: Technology Firms, Financial Institutions, Manufacturing Units, Educational Services, Government Agencies |
| Companies Covered | ComPsych, Wellness Corporate Solutions, Virgin Pulse, Provant Health Solutions, EXOS, Marino Wellness, Privia Health, Vitality Group, Wellsource, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Corporate Wellness Software Market Shifts & Advancements
Generative AI is compressing content personalization cycles while regulatory fragmentation across the EU AI Act and FDA guidance is bifurcating product development tracks. Behavioral data architecture is overtaking pure clinical metrics as the engagement currency.
Large language model-powered coaching interfaces are overtaking rule-based chatbot systems in enterprise wellness deployments. Technology firms with rapid implementation mandates are adopting these tools within six-month procurement windows. The shift is overtaking traditional vendor evaluation criteria that prioritized clinical validation over engagement velocity.
The EU AI Act imposes risk-tiered conformity obligations on algorithmic health coaching outputs. Vendors must document training data provenance and implement human oversight protocols for high-risk applications. European financial institutions are responding by demanding third-party algorithmic audits before contract execution.
Self-insured employers are consolidating vendor relationships into multi-year platform agreements that bundle biometric screening with mental health interventions. Benefits consultants are displacing direct software procurement as the primary channel. This concentration is most visible in the United States where enterprise employers exceed five thousand covered lives.
Global Corporate Wellness Software Market Segmentation
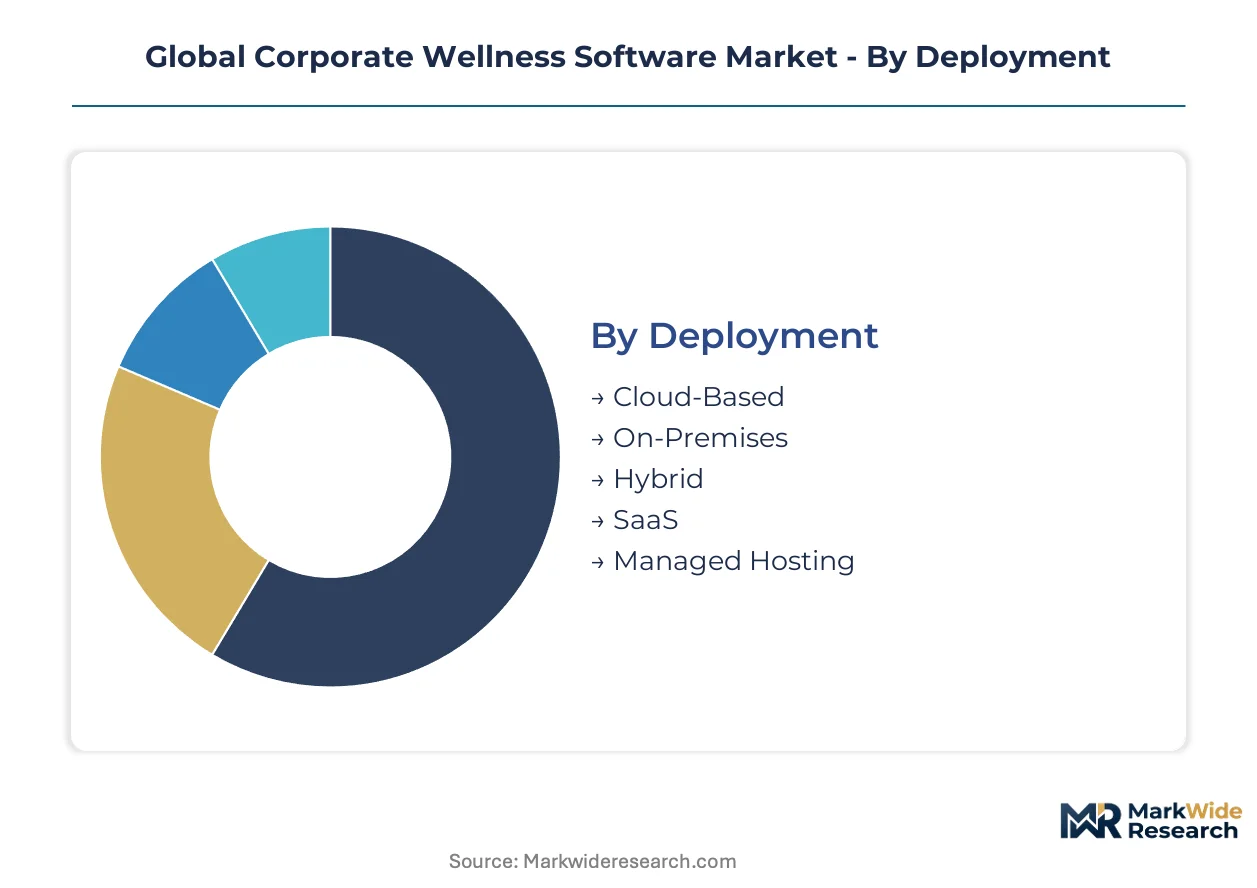
Corporate wellness software procurement patterns diverge sharply across deployment architectures, solution bundles, and employer risk profiles. Buyers prioritize configurability, integration depth, and regulatory alignment differently depending on organizational scale and captive insurance arrangements.
Deployment:
Technology firms with rapid implementation mandates favor subscription economics over capital infrastructure commitment.
- Cloud-Based:Multi-tenant architectures with API-first design enable wearable ecosystem integration without on-site server maintenance. Demand concentrates among United States technology firms seeking six-month procurement windows and automatic feature updates.
- SaaS:Pre-configured modules with per-employee-per-month pricing reduce procurement friction for mid-market employers. Financial institutions in Germany and France are adopting these deployments to satisfy EU AI Act documentation requirements through vendor-managed compliance layers.
- On-Premises:Air-gapped data environments serving defense contractors and classified government facilities.
- Hybrid:Split architectures with sensitive biometric data on-site and engagement layers in cloud.
- Managed Hosting:Single-tenant cloud with dedicated infrastructure for large self-insured employers.
Volume sits with Cloud-Based; growth tilts toward SaaS.
Solution Offering:
Employer liability frameworks post-pandemic are reweighting budget allocation toward psychological interventions over pure physical health metrics.
- Mental Wellbeing:Algorithmic nudge protocols and cognitive behavioral toolkits address trader stress management mandates from OSHA and emerging FDA guidance on software-as-medical-device classifications. Financial institutions in New York and London are expanding procurement fastest.
- Health Risk Assessment:Biometric screening coordination with predictive analytics for insurance premium optimization. Large self-insured employers in the United States bundle these with captive insurance arrangements.
- Fitness Tracking:Wearable telemetry aggregation with gamified engagement mechanics.
- Nutrition Management:Meal logging and metabolic marker correlation for chronic condition populations.
- Employee Engagement:Pulse surveys and recognition systems with wellness program tie-ins.
Revenue concentrates in Health Risk Assessment; Mental Wellbeing climbs the fastest.
Application:
Regulatory pressure on workplace conditions is hardening software requirements in high-stakes occupational environments.
- Stress Management:Real-time physiological monitoring with intervention escalation protocols for trading floors and emergency response teams. United Kingdom and Singapore financial regulators now mandate documented stress management systems.
- Chronic Disease Prevention:Diabetes and cardiovascular risk stratification with care coordination handoffs. United States self-insured employers with five thousand plus covered lives drive procurement.
- Lifestyle Management:Sleep, hydration, and activity optimization for general workforce populations.
- Occupational Health:Injury prevention and return-to-work coordination for manufacturing and logistics employers.
- Work-Life Balance:Boundary-setting tools and burnout early warning systems.
Installed base favors Stress Management; Chronic Disease Prevention gains share fastest.
End User Industry:
Industry-specific regulatory exposure and insurance cost structures determine platform sophistication requirements.
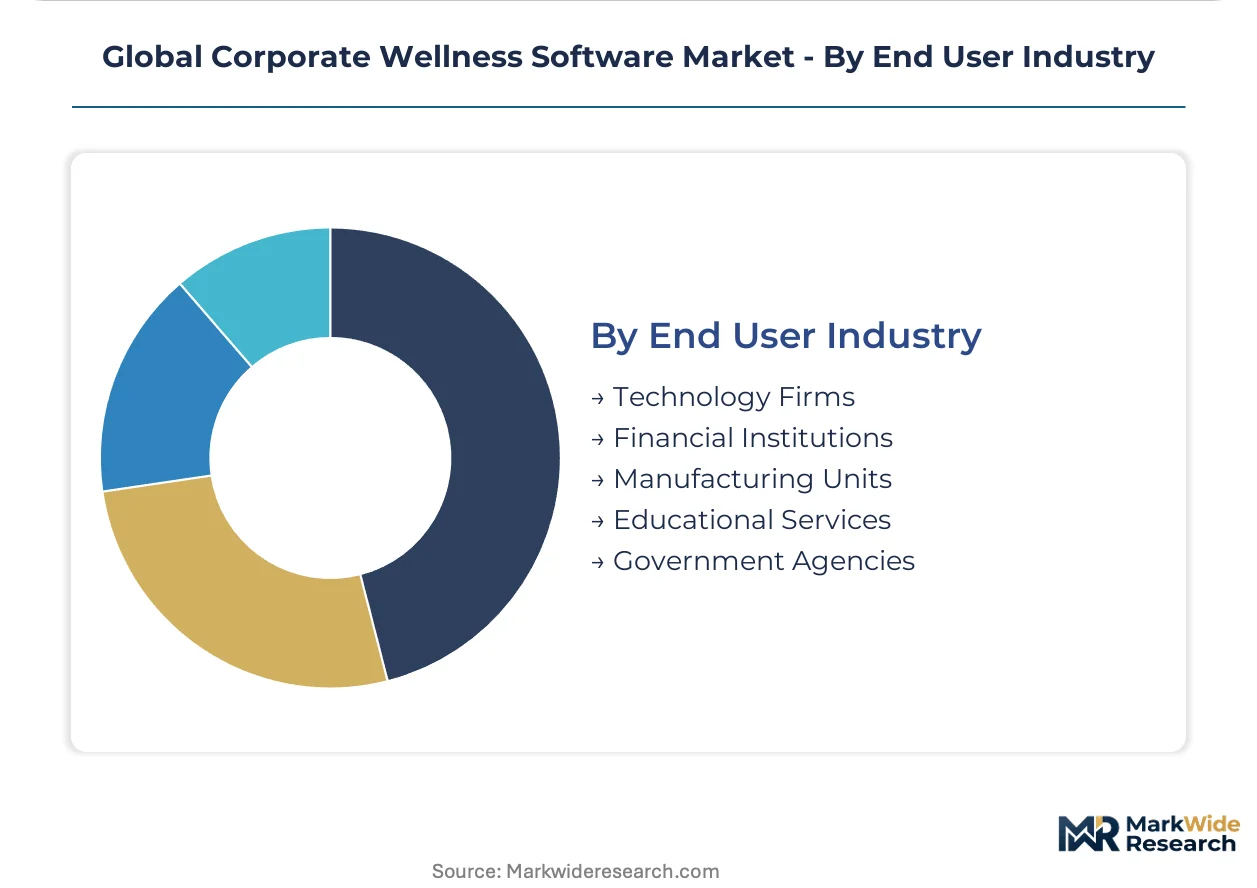
- Financial Institutions:Algorithmic coaching with audit trails for regulatory examination. European banks face EU AI Act conformity obligations on recommendation engine outputs.
- Technology Firms:Rapid deployment with Slack and Microsoft Teams integration. Bay Area and Bangalore campuses prioritize engagement velocity over clinical validation.
- Manufacturing Units:Occupational health modules with OSHA injury tracking and biometric screening for physical role assignments.
- Educational Services:Student-facing wellness platforms with FERPA-compliant data architecture.
- Government Agencies:FedRAMP-authorized cloud deployments with veteran and civilian workforce segmentation.
Procurement volume centers on Technology Firms; Financial Institutions show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for digital health production concentrates wellness platform R&D investment in Bangalore and Hyderabad special economic zones. Software development centers in these zones attract multinational vendors seeking cost-efficient engineering capacity.
United States
Enterprise self-insured employers with five thousand plus covered lives drive platform procurement through benefits consultant channels. OSHA workplace health standards mandate documented stress management protocols for financial institutions in New York and Chicago. Silicon Valley technology firms prioritize six-month cloud deployment windows over clinical validation depth.
Germany
Financial institutions in Frankfurt and Munich expand algorithmic coaching procurement to satisfy EU AI Act conformity obligations on recommendation engine outputs. The country's national data protection regulator enforces strict documentation requirements for algorithmic health tools. Berlin-based mid-market employers favor SaaS deployments with vendor-managed compliance layers.
United Kingdom
London financial regulators now mandate documented stress management systems for trading floors and asset management operations. The Financial Conduct Authority examines algorithmic audit trails during routine supervisory reviews. Edinburgh and Manchester occupational health departments resist API-first platform migration from legacy HRIS infrastructure.
Singapore
Monetary Authority of Singapore guidelines on trader conduct drive demand for real-time physiological monitoring with intervention escalation protocols. The country's national technology regulator promotes sandbox testing for AI-enabled wellness applications. Marina Bay financial district employers consolidate biometric screening with mental health modules into single-vendor contracts.
India
Production-linked incentives for software development centers attract wellness platform engineering investment from multinational vendors. The country's national pharmaceutical regulator monitors diagnostic-adjacent features that risk medical device classification. Bangalore technology campuses and Hyderabad special economic zones concentrate cloud infrastructure talent pools.
Global Corporate Wellness Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pure-play software vendors holding engagement velocity advantages while integrated service providers capture clinical workflow depth. The vendor base clusters around three strategic archetypes: behavioral data architecture specialists, integrated employee assistance programming providers, and biometric screening coordinators. Capacity expansion through cloud infrastructure partnerships and strategic acquisitions of occupational health service layers represent the dominant competitive moves reshaping positioning.
Within the integrated service tier, ComPsych and Provant Health Solutions exemplify providers that extend beyond software into clinical service delivery. Virgin Pulse occupies a position among behavioral data architecture specialists leveraging engagement rate optimization across large employer populations. These three companies represent the primary competitive anchors in a market where differentiation increasingly depends on correlating physiological markers with psychological state data rather than pure digital scale.
| Leading Market Players |
|---|
| ComPsych |
| Wellness Corporate Solutions |
| Virgin Pulse |
| Provant Health Solutions |
| EXOS |
| Marino Wellness |
| Privia Health |
| Vitality Group |
| Wellsource |
| Others |
Supply & Pricing Matrix
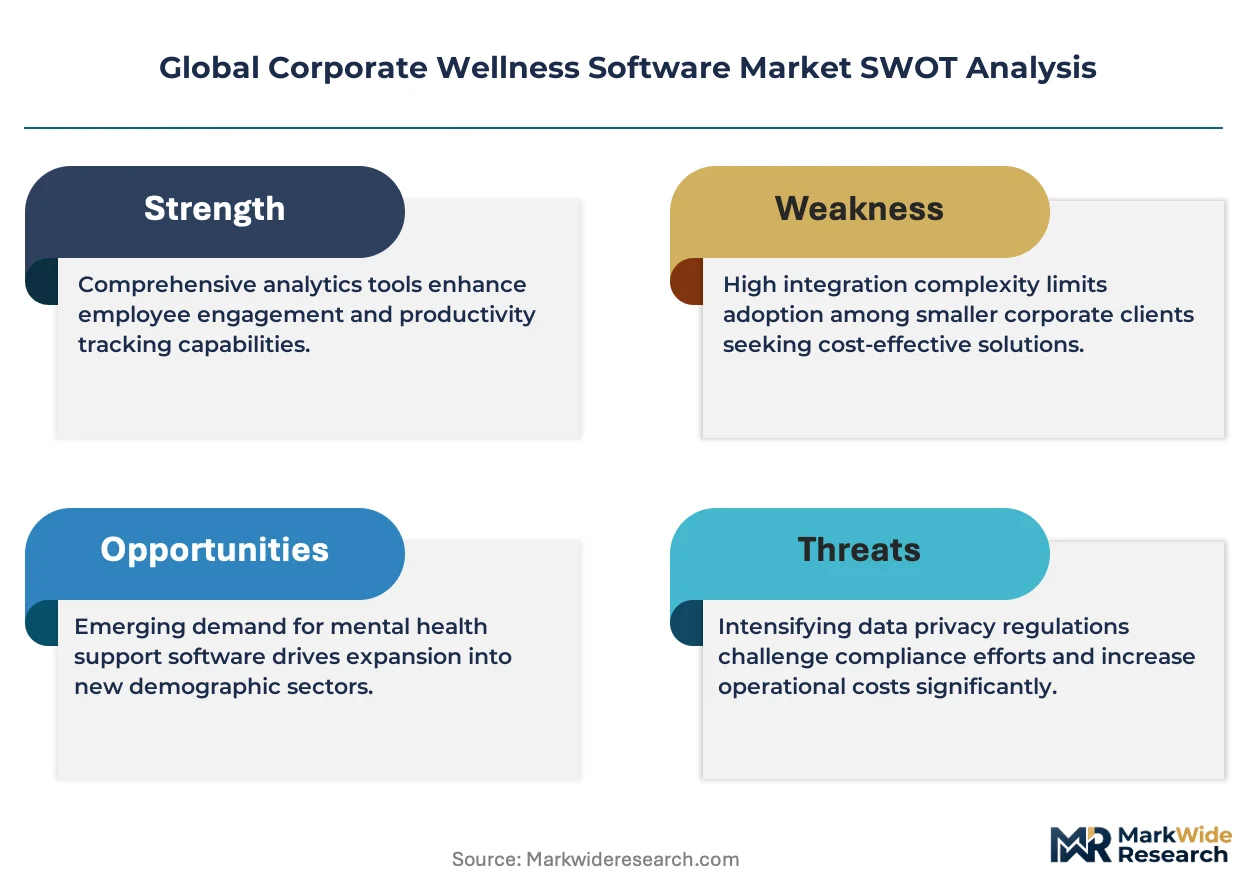
Private-equity-rolled-up wellness platform specialists anchor supply-side consolidation while enforcing subscription pricing discipline across cloud infrastructure tiers. Their portfolio aggregation strategies compress vendor diversity and standardize per-employee-per-month rate cards.
Pricing Analysis
Short lead-time deployments command SaaS-tiered premiums as benefits consultants accelerate procurement cycles for self-insured employers. Three-tier pricing structure across premium, standard, and economy levels segments by integration complexity and compliance certification depth. Cost compression in economy tiers intensifies because hyperscaler egress fees erode vendor margins. Mid-market employers exhibit highest price sensitivity; financial institutions with regulatory mandates show lowest.
Supply Chain Analysis
Reverse-logistics flows for wearable device refurbishment and biometric hardware returns create secondary supply channels for occupational health deployments. Engineering talent concentrates in India, Ireland, and Poland as software development centers cluster near multinational R&D facilities. Raw material dependencies span semiconductor chips for wearable sensors, cloud compute capacity from hyperscalers, and licensed clinical content libraries. Single-source vulnerability sits with AWS and Azure concentration for core infrastructure. Distribution runs through benefits consultant intermediaries rather than direct enterprise sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative AI coaching interfaces are displacing rule-based chatbot systems as the dominant engagement technology, compressing legacy platform replacement cycles.
For Market Incumbents: Deepen algorithmic audit capabilities to preempt EU AI Act conformity rejections. Fortify behavioral data architecture through API-first wearable ecosystem expansion. Consolidate occupational health service layers via acquisition to match ComPsych's integrated clinical delivery model.
For New Entrants and Emerging Players: Mid-market German and French employers with vendor-managed compliance needs represent the most penetrable buyer archetype. Target SaaS deployments with pre-configured EU AI Act documentation modules. Pursue channel partnerships with Berlin and Munich-based benefits consultants rather than direct sales buildout.
For Investors and Strategic Acquirers: FDA guidance publication on mental health software reclassification is the leading indicator that platform redesign requirements will trigger distressed asset opportunities. Five-to-ten year viability favors vendors correlating physiological markers with psychological state data. Monitor OSHA enforcement actions on financial institution stress management documentation as demand signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Audit Certification | EU AI Act conformity documentation enables European financial institution contract execution. |
| Biometric-Mental Health Convergence | Integrated platforms command premium pricing from self-insured employers with captive arrangements. |
| Hyperscaler Partnership Expansion | AWS and Azure co-selling agreements accelerate six-month procurement windows for technology firms. |
| Occupational Health Service Layer Acquisition | Clinical workflow depth differentiates against pure-play engagement velocity competitors. |
| India PLI Zone Development | Bangalore and Hyderabad engineering capacity reduces R&D cost structure for algorithmic coaching tools. |
Research Methodology
Multi-period observation of vendor contract structures, regulatory filing patterns, and employer procurement timelines anchored the trend analysis, supplemented by interviews with benefits consultants, enterprise HR technology officers, platform engineering leads, and occupational health directors. Secondary validation drew from SEC 10-K disclosures, EU AI Act implementation guidance, OSHA enforcement databases, and hyperscaler partnership announcements. Bottom-up deployment modeling and top-down employer spending estimates were cross-triangulated.
Segment-weighting across deployment architectures, solution bundles, and end-user industries distributed growth assumptions throughout the forecast period. CAGRs derived from employer headcount projections, insurance premium optimization incentives, and regulatory mandate implementation schedules. Integration complexity tiers and regional adoption patterns provided additional granularity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA mental health software reclassification timing and EU AI Act enforcement consistency. Practitioners should monitor OSHA workplace health standard revisions and EMA medical device regulation convergence announcements for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
HR Saas Market
Software & Services
Software Release Management Tools Market
Software & Services
Paraphrasing Tools Market
Software & Services
Design Collaboration Software Market
Software & Services
Global Knowledge Management Software Market
Software & Services
Waterway Transportation Software Solutions Market
Software & Services
Global App Store Optimization Software Market
Software & Services
Global Continuous Testing Market
Software & Services
Middle East HR Payroll Software Market
Software & Services
Europe Pharmacy POS Software Market
Software & Services
Global Cloud-Based Call Center Software Market
Software & Services
Time and Attendance Software Market
Software & Services
India Software Services Export Market
Software & Services
US Digital Marketing Software Market
Software & Services
Pharmacy Billing Software Market
Software & Services
Full Screen Website Screenshot Software Market