
 North America E-Commerce Market | 2026-2036
North America E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
North America E-Commerce Market Analytics
Recycled corrugated fiberboard is decoupling last-mile packaging economics from virgin pulp price volatility across North American fulfillment networks. Amazon leverages captive air cargo capacity and regional sortation centers to sustain delivery speed advantages. Walmart anchors its e-commerce growth through store-based fulfillment, converting thousands of locations into hybrid retail-distribution nodes. Shopify competes by extending software infrastructure to independent merchants, reducing platform dependency.
North America E-Commerce denotes digitally mediated transactions for goods and services conducted over internet-connected devices, relying on encrypted payment gateways, distributed order management systems, and algorithmic inventory allocation across multi-node fulfillment architectures. Its primary commercial purpose is to match heterogeneous consumer demand with distributed supply while minimizing friction in discovery, payment, and reverse logistics. Electronics and fashion command the dominant transaction volumes, though home goods generates superior per-unit margins due to lower return rates and bundled shipping economics. Marketplace channels concentrate liquidity and advertising revenue, while direct-to-consumer models capture first-party data and repeat purchase loyalty.
The FTC enforces Section 5 of the FTC Act against platform self-preferencing, reshaping how Amazon structures its Buy Box algorithms and seller fee disclosures. State-level privacy statutes, including California's CCPA and Virginia's CDPA, fragment compliance obligations for cross-border data flows and targeted advertising. The Payment Card Industry Data Security Standard governs tokenized transaction architecture, elevating infrastructure costs for smaller merchants. Stakeholders must monitor whether emerging state sales tax nexus expansions override marketplace facilitator laws, as this determines liability allocation between platforms and third-party sellers.
Market Dynamics
The FTC's intensifying antitrust scrutiny of marketplace dominance is forcing structural recalibration of platform fee architectures and seller access policies across North American fulfillment networks.
Growth Catalysts
- State Privacy Statutes:California's CCPA and Virginia's CDPA are fragmenting compliance obligations and accelerating investment in first-party data infrastructure among direct-to-consumer merchants.
- Suburban Online Grocery Adoption:Household penetration in Texas exurbs is accelerating cold-chain fulfillment network expansion through Dallas-Fort Worth and Austin logistics clusters.
- Recycled Corrugated Fiberboard:Decoupling last-mile packaging economics from virgin pulp price volatility is stabilizing margin structures across regional sortation centers.
Market Restraints
- Virgin Pulp Price Volatility:Input cost swings in packaging substrates compress margin predictability for mid-market fulfillment operators lacking long-term supply contracts.
- Platform Fee Opacity:Non-disclosed algorithmic adjustments to Buy Box rankings create working capital uncertainty for third-party sellers dependent on marketplace liquidity.
- State Sales Tax Nexus Expansion:Emerging nexus rules overriding marketplace facilitator laws are reallocating liability exposure toward smaller merchants with limited compliance infrastructure.
Strategic Opportunities
- Store-Based Fulfillment Convergence:Hybrid retail-distribution nodes in suburban Texas and Florida markets enable same-day delivery without dedicated warehouse capex.
- Independent Merchant Infrastructure:Software-as-a-service order management systems reduce platform dependency for direct-to-consumer brands seeking first-party data capture.
- Captive Air Cargo Networks:Dedicated freight capacity between regional sortation hubs insulates delivery speed commitments from commercial carrier rate volatility.
Industry Challenges
- Distributed Order Management Integration:Legacy ERP architectures require substantial middleware development to synchronize real-time inventory visibility across multi-node fulfillment networks.
- PCI-DSS Compliance Talent Scarcity:Tokenized transaction architecture expertise concentrates among payment processors, elevating recruitment costs for merchant in-house security teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America E-Commerce Market |
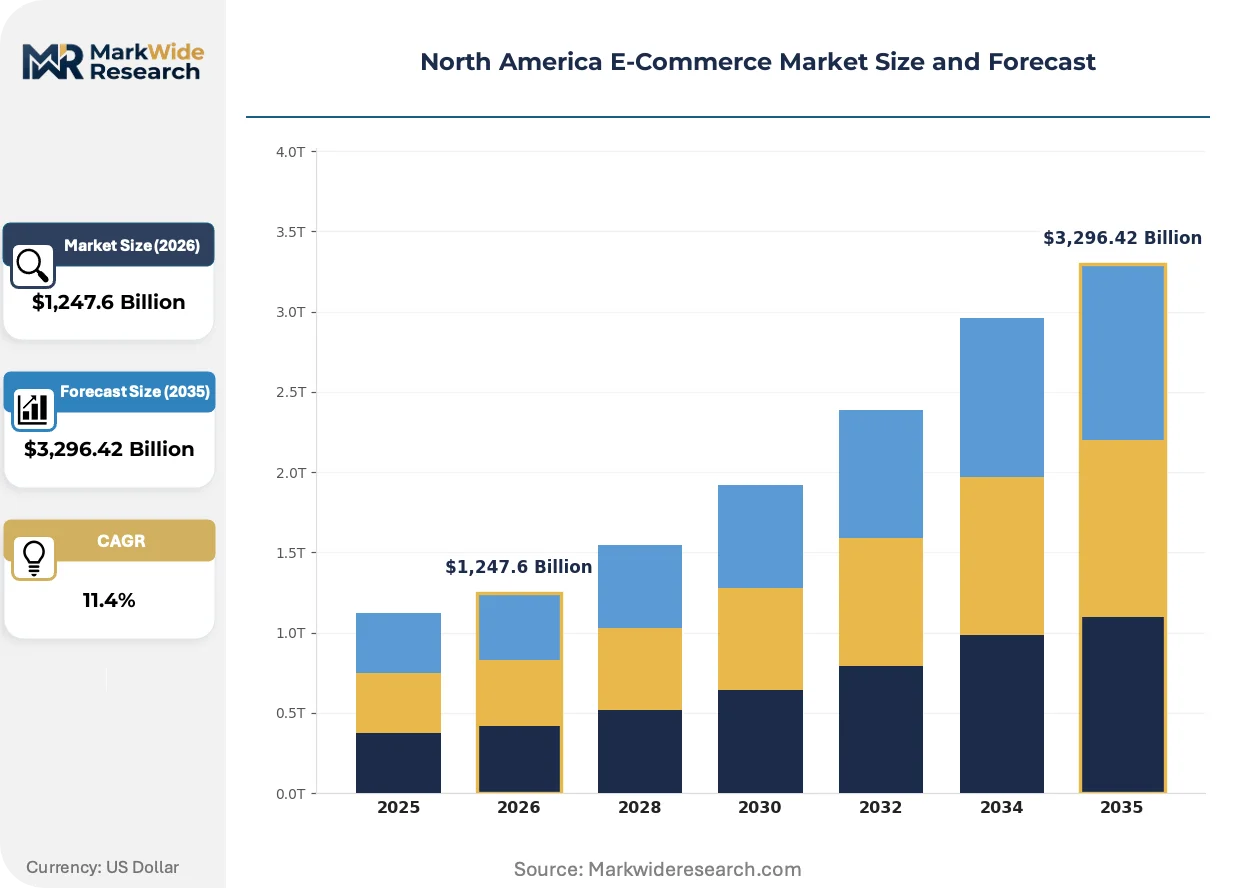
| Market Size in 2026 | $1,247.6 Billion |
| Market Size in 2035 | $3,296.42 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Electronics, Fashion, Home Goods, Beauty Sales Channel: Direct-to-Consumer, Marketplace, Subscription, Social Commerce Customer Type: Individuals, Small Businesses, Corporations, Non-Profits Payment Method: Credit Card, PayPal, Digital Wallets, Bank Transfer |
| Companies Covered | Amazon, Walmart, eBay, Apple, Shopify, Home Depot, Target, Best Buy, Etsy, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America E-Commerce Market Evolving Landscape
Algorithmic inventory allocation and encrypted payment gateway evolution are compressing friction points in discovery, payment, and reverse logistics across North American digital commerce infrastructure.
Warehouse robotics integration is automating pick-and-pack operations in regional sortation centers. Mid-market fulfillment operators are deploying autonomous mobile robots at accelerating pace to offset labor availability constraints in Texas and Florida logistics corridors. This technology is automating throughput scaling without proportional headcount expansion.
The FTC's Section 5 enforcement against platform self-preferencing is reshaping how marketplace algorithms rank seller offers. Industrial consequence includes mandatory fee disclosure requirements and audit rights for Buy Box placement criteria. Third-party seller segments in California and New York are responding through collective bargaining arrangements and direct-to-consumer pivot strategies.
Buyer concentration among suburban households is compressing switching cycles between grocery and general merchandise platforms. Store-based fulfillment models are displacing pure-play warehouse delivery for routine replenishment categories. This pattern is most visible in Dallas-Fort Worth and Austin exurbs where hybrid retail nodes anchor last-mile density.
North America E-Commerce Market Segmentation
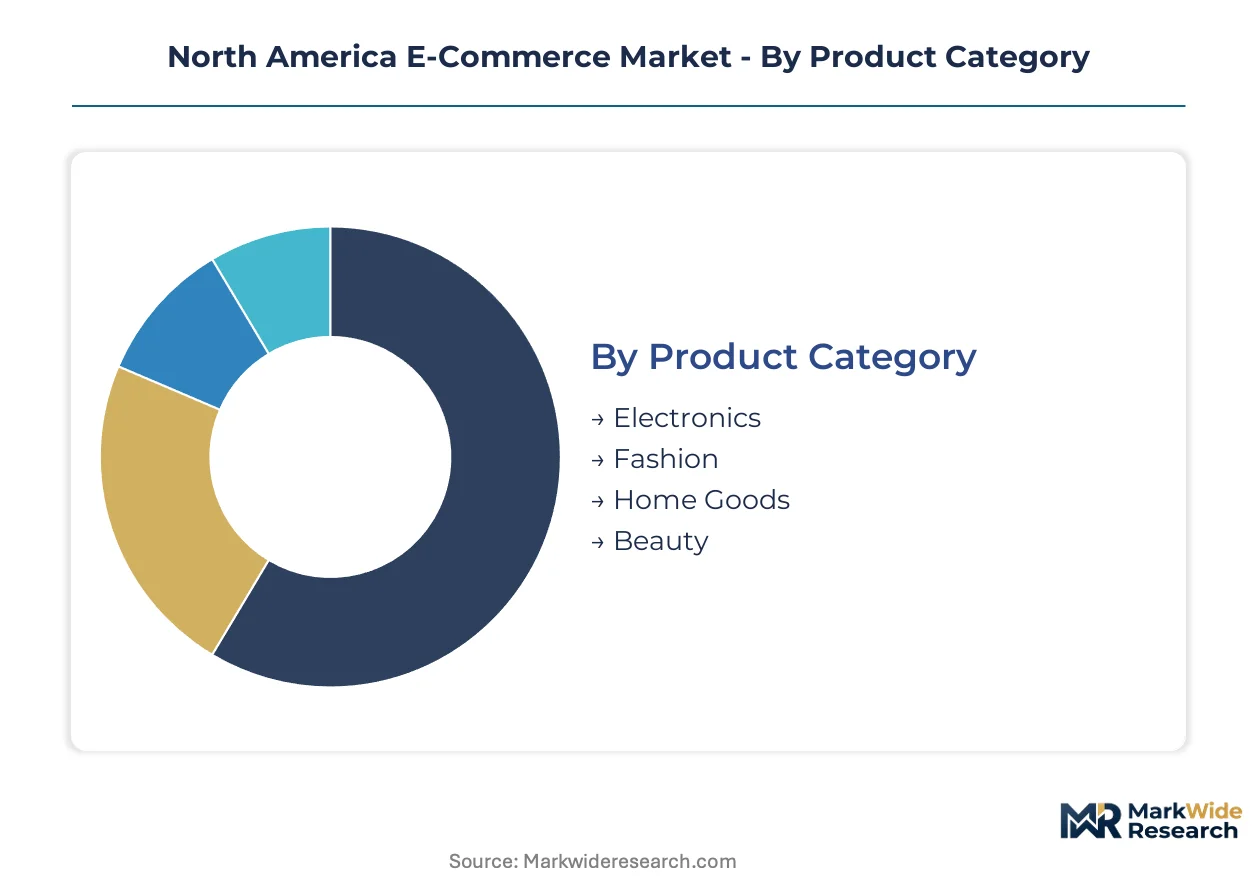
Segmentation in North American e-commerce reveals how fulfillment infrastructure, regulatory exposure, and margin structures vary across transaction types. Understanding these partitions helps stakeholders allocate capital toward channels with defensible economics and lighter compliance burdens.
Product Category:
Supply concentration in electronics fulfillment centers on Texas and California logistics clusters, where specialized handling infrastructure for high-value items commands premium lease rates.
- Electronics:High-value SKUs requiring tamper-evident packaging and serialized inventory tracking. Demand concentrates in suburban Texas households upgrading home office setups, constrained by FTC warranty disclosure enforcement on marketplace listings.
- Fashion:Apparel with elevated return rates demanding reverse logistics capacity. Demand concentrates in California and New York metro areas, where CCPA data restrictions complicate size-preference targeting and repeat purchase algorithms.
- Home Goods:Bulky items with superior per-unit margins due to lower return frequency and bundled shipping economics.
- Beauty:Temperature-sensitive products requiring cold-chain segments in fulfillment networks, with FDA labeling compliance adding regulatory overhead.
Today's leader: Electronics. Tomorrow's challenger: Home Goods.
Sales Channel:
Channel economics diverge sharply based on who owns customer data and who bears sales tax compliance liability.
- Direct-to-Consumer:Merchant-controlled storefronts capturing first-party purchase histories and email relationships. Demand concentrates among California-based independent brands seeking CCPA-compliant data strategies outside platform surveillance.
- Marketplace:Aggregated liquidity with algorithmic search ranking determining seller visibility. Demand concentrates among Texas and Florida third-party sellers, where Buy Box placement volatility creates working capital uncertainty.
- Subscription:Recurring revenue models with predictable fulfillment scheduling reducing peak-season labor spikes.
- Social Commerce:Influencer-mediated discovery with abbreviated purchase funnels, expanding fastest among younger demographics in urban California and New York markets.
Direct-to-Consumer commands loyalty economics. Social Commerce climbs fastest on discovery innovation.
Customer Type:
Procurement scale determines whether buyers access negotiated shipping rates and volume-tiered platform fee structures.
- Individuals:Single-unit purchases with highest per-transaction fulfillment cost ratios.
- Small Businesses:B2B procurement with irregular order patterns, concentrated in Texas manufacturing corridors seeking bulk supply chain inputs.
- Corporations:Volume-contracted purchasing with dedicated account management and custom API integrations for procurement system compatibility.
- Non-Profits:Tax-exempt transactions requiring specialized checkout flows and documentation verification, gaining share fastest in California and New York donor networks.
Corporations anchor revenue stability. Non-Profits gain share fastest on mission-aligned purchasing platforms.
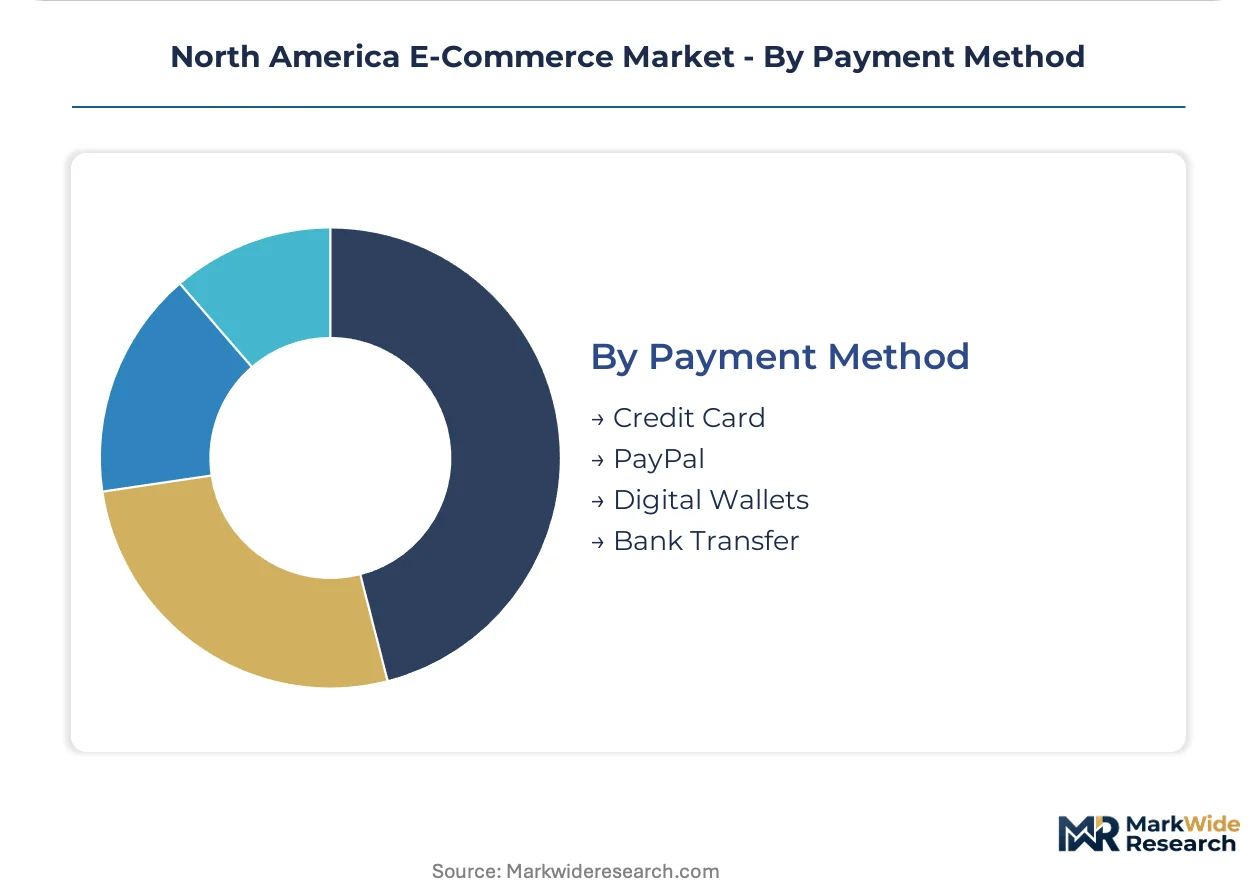
Payment Method:
Transaction architecture choices cascade through fraud liability allocation and PCI-DSS compliance scope.
- Credit Card:Dominant rails with established chargeback dispute frameworks and interchange fee transparency.
- PayPal:Wallet-based checkout reducing merchant PCI exposure, concentrated among small California merchants seeking simplified compliance.
- Digital Wallets:Apple Pay and Google Pay tokenization shifting fraud liability toward issuers, expanding fastest in iPhone-dense suburban Texas markets.
- Bank Transfer:ACH-based settlement with lower processing fees but delayed confirmation timing, preferred by B2B buyers in corporate procurement workflows.
Credit Cards hold transaction volume leadership. Digital Wallets show steepest expansion trajectory on mobile-first checkout optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dallas-Fort Worth anchors North American e-commerce infrastructure investment through cold-chain fulfillment expansion and suburban grocery adoption corridors.
United States
Texas exurbs and California metro areas drive warehouse absorption, with Austin and Los Angeles logistics clusters commanding premium lease rates for last-mile nodes. The FTC enforces Section 5 of the FTC Act against platform self-preferencing, reshaping Buy Box algorithms and seller fee disclosure requirements. Dallas-Fort Worth and Austin logistics corridors absorb disproportionate investment as suburban households accelerate online grocery penetration.
Canada
Ontario and Quebec manufacturing corridors generate B2B procurement demand for bulk supply chain inputs through digital channels. Health Canada regulates temperature-sensitive product labeling for cross-border beauty and pharmaceutical shipments, adding compliance overhead for fulfillment operators. Toronto and Vancouver anchor last-mile density through hybrid retail-distribution nodes converting existing store footprints.
Mexico
Nuevo León and Jalisco manufacturing hubs create cross-border fulfillment demand for component inputs and finished goods bound for US markets. The country's national consumer protection agency monitors marketplace fee transparency and seller dispute resolution frameworks. Mexico City Metro logistics clusters expand air cargo connectivity to regional sortation hubs in Texas and California.
North America E-Commerce Market Competitive Landscape
Global majors compete with regional champions across fulfillment infrastructure and seller ecosystem dimensions. The market structure concentrates around vertically integrated platform operators and specialized software infrastructure providers. Three archetypes dominate: captive logistics networks, store-based fulfillment converters, and independent merchant enablers. Competitive moves center on warehouse robotics deployment and first-party data infrastructure acquisition.
Within the captive logistics tier, Amazon and Walmart exemplify divergent fulfillment strategies—air cargo networks versus store-based nodes. Shopify occupies a position as the independent merchant infrastructure archetype, reducing platform dependency through SaaS order management. These three anchors represent the spectrum from integrated ecosystem control to merchant autonomy.
| Leading Market Players |
|---|
| Amazon |
| Walmart |
| eBay |
| Apple |
| Shopify |
| Home Depot |
| Target |
| Best Buy |
| Etsy |
| Others |
Value Network & Pricing Analysis
Warehouse robotics deployment across Texas and Florida fulfillment corridors simultaneously compresses per-unit labor costs and concentrates sorting capacity among operators with capital access. This technological shift widens the efficiency gap between scaled regional networks and mid-market fulfillment operators lacking automation budgets.
Pricing Analysis
Input-cost pass-through from virgin pulp volatility runs through corrugated packaging tiers, with recycled fiberboard commanding premium positioning against conventional substrates. Three-tier pricing structure separates automated fulfillment nodes from semi-automated and manual operations based on throughput guarantees. Pricing pressure stems from FTC-mandated fee disclosure requirements compressing marketplace commission opacity. Small business procurement segments exhibit highest price sensitivity, while corporate volume contracts anchor rate stability.
Supply Chain Analysis
Reverse logistics flows for fashion and electronics returns concentrate refurbishment capacity in Dallas-Fort Worth and Los Angeles metro areas. Domestic supply draws from Texas cold-chain infrastructure, California high-value handling facilities, and Ontario cross-border distribution nodes. Dependencies rest on lithium-ion battery cells, tamper-evident packaging substrates, and cloud-based order management licensing. Single-source vulnerability sits with concentrated cloud infrastructure providers. Distribution runs through hybrid retail-distribution nodes converting existing store footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
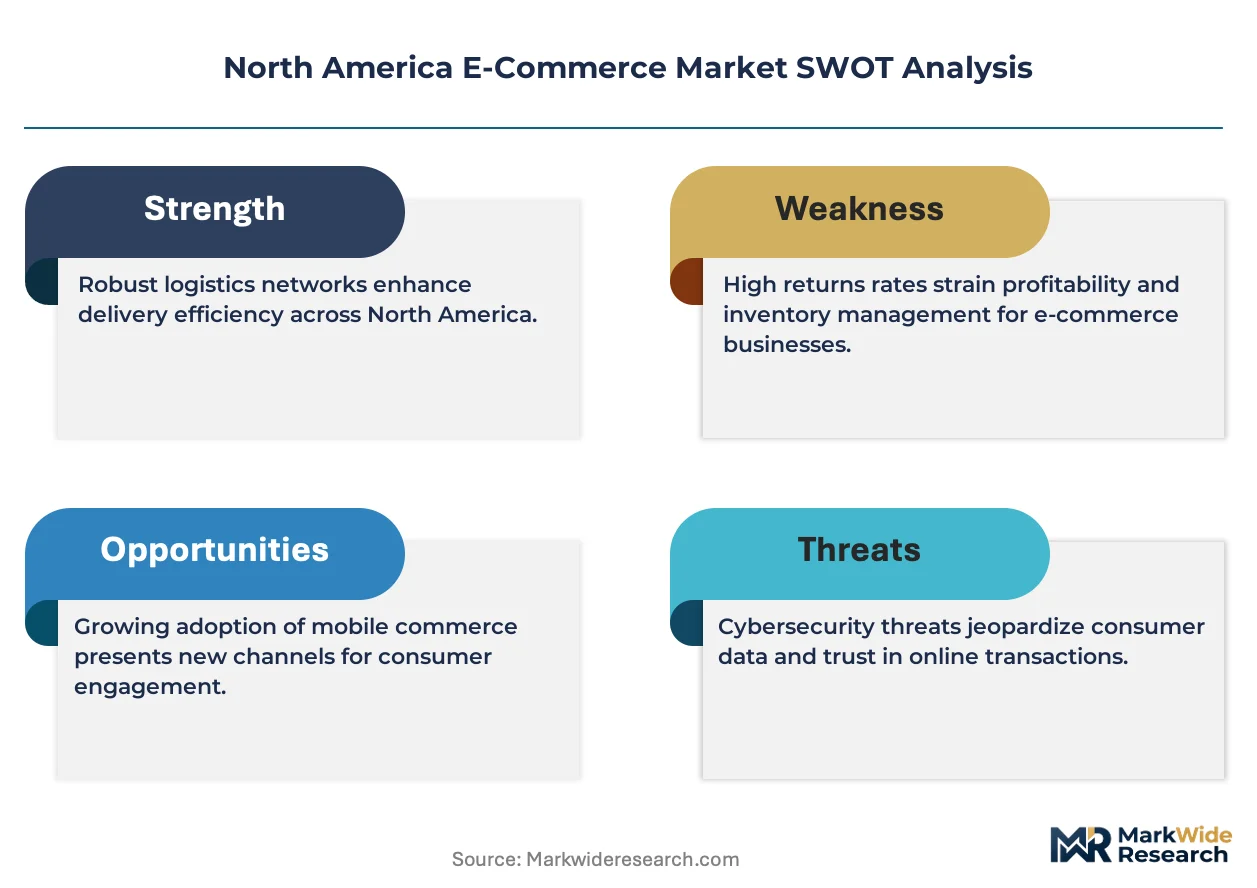
Margin expansion in North American e-commerce rests on warehouse robotics depreciation curves and premium-tier same-day delivery pricing. Recycled packaging adoption and captive air cargo networks compress cost structures while supporting service premiums.
For Market Incumbents: Acquire last-mile robotics fleets to offset labor availability constraints in Texas and Florida logistics corridors. Consolidate cold-chain certification assets to defend against emerging regional fulfillment specialists. FTC algorithmic audit requirements threaten Buy Box revenue opacity; invest in first-party data infrastructure to reduce platform dependency. For New Entrants and Emerging Players: Suburban Texas exurbs present underserved buyer concentration for specialized grocery and home goods fulfillment. Texas manufacturing corridors generate B2B procurement demand with irregular order patterns vulnerable to disruption. Penetrate through software-as-a-service order management systems reducing merchant platform dependency. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-market fulfillment operators lacking automation scale but holding regional density in Austin and Dallas-Fort Worth corridors. Long-term viability favors automated networks with captive air cargo capacity and first-party data infrastructure. Monitor FTC enforcement intensity against platform self-preferencing as regulatory inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Warehouse Robotics Deployment | Autonomous mobile robots in Texas sortation centers offset labor constraints without proportional headcount expansion. |
| Captive Air Cargo Network Expansion | Dedicated freight capacity between Dallas-Fort Worth and California hubs insulates delivery commitments from carrier rate volatility. |
| Store-Based Fulfillment Conversion | Hybrid retail-distribution nodes in suburban Texas and Florida enable same-day delivery without dedicated warehouse capex. |
| First-Party Data Infrastructure Investment | CCPA-compliant customer relationship platforms reduce merchant dependency on marketplace surveillance economics. |
| Recycled Packaging Supply Contracting | Long-term corrugated fiberboard agreements decouple margin structures from virgin pulp price swings. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national logistics corridor. Fulfillment center operators, marketplace seller account managers, and supply chain procurement directors provided operational data. Secondary validation drew from FTC enforcement filings, SEC 10-K disclosures, customs trade records, and commercial real estate lease databases. Bottom-up facility capacity estimates triangulated against top-down transaction volume projections.
Rate-of-change decomposition anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product category, sales channel, customer type, and payment method, cross-referenced against regional logistics cluster density. CAGRs derived from facility investment pipelines, warehouse absorption rates, and platform seller growth metrics. Forecast inputs incorporated FTC regulatory trajectory and suburban household penetration curves for online grocery.
Inputs from fulfillment operator interviews and commercial lease databases were available through the study window; gaps in private marketplace fee structures introduce uncertainty bands around seller economics projections. Forecasts reflect documented assumptions on regulatory enforcement intensity and automation adoption curves. Practitioners should monitor FTC Section 5 case progression and state sales tax nexus rulemaking for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Italy Dropshipping Market
E-Commerce Solutions
Finland E-Commerce Market
E-Commerce Solutions
United States Same-Day Delivery Market
E-Commerce Solutions
Norway E-Commerce Market
E-Commerce Solutions
Indonesia Ecommerce Logistics Market
E-Commerce Solutions
Spain E-Commerce Logistics Market
E-Commerce Solutions
China Online Trading Platform Market
E-Commerce Solutions
Europe FMCG B2B E-Commerce Market
E-Commerce Solutions
Bahrain E-Commerce Market
E-Commerce Solutions
Asia-Pacific Automotive E-Commerce Market
E-Commerce Solutions
Online Apparel Retailing Market
E-Commerce Solutions
Global Subscription E Commerce Market
E-Commerce Solutions
China Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
Global Ecommerce Platform Market
E-Commerce Solutions
Chile E-Commerce Market
E-Commerce Solutions
Ireland E-Commerce Market