
 Europe E-Commerce Watch Market | 2026-2036
Europe E-Commerce Watch Market Size, Share, and Industry Trends Forecast 2026-2036
Europe E-Commerce Watch Market Insights
Millennial and Gen Z buyer participation is shifting toward dominance in online watch transactions, displacing traditional in-store discovery among older demographics. Citizen Watch Co Ltd leverages its Eco-Drive solar technology to differentiate in sustainability-focused European markets. Compagnie Financière Richemont S.A. anchors the luxury segment through controlled digital distribution of its prestige maisons. Apple Inc. competes aggressively on smartwatch integration with health ecosystems, extending its reach beyond conventional horology buyers.
The Europe E-Commerce Watch encompasses timepieces sold through digital platforms, spanning mechanical calibers with 28,800 vibrations per hour, quartz movements powered by silver oxide cells, and smartwatches running Wear OS or proprietary operating systems with heart-rate and blood-oxygen sensors. These products serve personal adornment, status signaling, fitness tracking, and investment-grade asset accumulation. The D2C sales channel captures margin pools previously allocated to wholesale intermediaries, while digital wallets displace credit cards as the preferred payment method among younger European buyers. Electronics and clothing product categories attract divergent fulfillment strategies, with smartwatches requiring tech-support infrastructure and fashion watches emphasizing return-friendly sizing policies.
The EU Green Deal and REACH regulations mandate supply-chain traceability and restrict hazardous substances in watch components and packaging. CE marking requirements under the EU AI Act increasingly govern smartwatch data processing and algorithmic health recommendations. The EMA and national consumer protection bodies across member states scrutinize wellness claims attached to wearable biosensors. Stakeholders must monitor evolving battery-directive rules and digital-product-passport mandates that will reshape sourcing disclosures and circular-economy obligations.
Market Dynamics
The EU Green Deal and REACH compliance frameworks are forcing wholesale restructuring of European e-commerce watch supply chains, with brands racing to secure conflict-free mineral certification and biodegradable packaging before digital-product-passport mandates take full effect.
Growth Catalysts
- REACH substance restrictions:Hazardous material bans under ECHA oversight push legacy manufacturers toward clean-sheet redesigns, creating first-mover advantages for compliant pure-play digital brands.
- Millennial buyer concentration:Fashion-conscious demographics aged 25-40 in Germany, France, and the United Kingdom now account for the majority of online watch transactions, compressing traditional retail discovery cycles.
- Solar-powered movements:Light-charging calibers eliminate battery replacement logistics, reducing return rates and enabling slimmer direct-to-consumer warranty structures.
Market Restraints
- Swiss movement supply concentration:Premium mechanical calibers source predominantly from ETA and Sellita facilities in the Jura arc, exposing brands to single-source disruption risks and extended lead times.
- Lithium cell import dependency:Quartz and smartwatch battery supply chains route through East Asian refiners, subjecting European assemblers to raw material volatility and carbon-footprint scrutiny under EU battery directives.
- CE marking complexity:Smartwatch health algorithms now fall under EU AI Act governance, requiring notified-body review that extends product launch timelines by 8-14 months.
Strategic Opportunities
- Polish and Romanian e-commerce penetration:These member states show sub-40% digital watch purchase rates versus 65%+ in Western Europe, offering expansion runway for logistics-optimized entrants.
- Circular economy mandates:Digital-product-passport requirements scheduled for 2027 create service-revenue pools through authenticated resale platforms and refurbishment certification.
- Wearable-health ecosystem convergence:Integration between timepiece biosensors and national healthcare data infrastructure in Germany and France positions preventive-monitoring devices for insurance subsidy eligibility.
Industry Challenges
- Horological-AI engineering scarcity:The intersection of traditional watchmaking craft and machine-learning firmware development commands premium talent costs, with Zurich and Munich clusters absorbing available specialists.
- Multi-jurisdiction wellness claim compliance:Blood-oxygen and heart-rate accuracy assertions trigger divergent evidentiary standards across EMA, France's ANSM, and Germany's BfArM, fragmenting marketing copy and legal review workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe E-Commerce Watch Market |
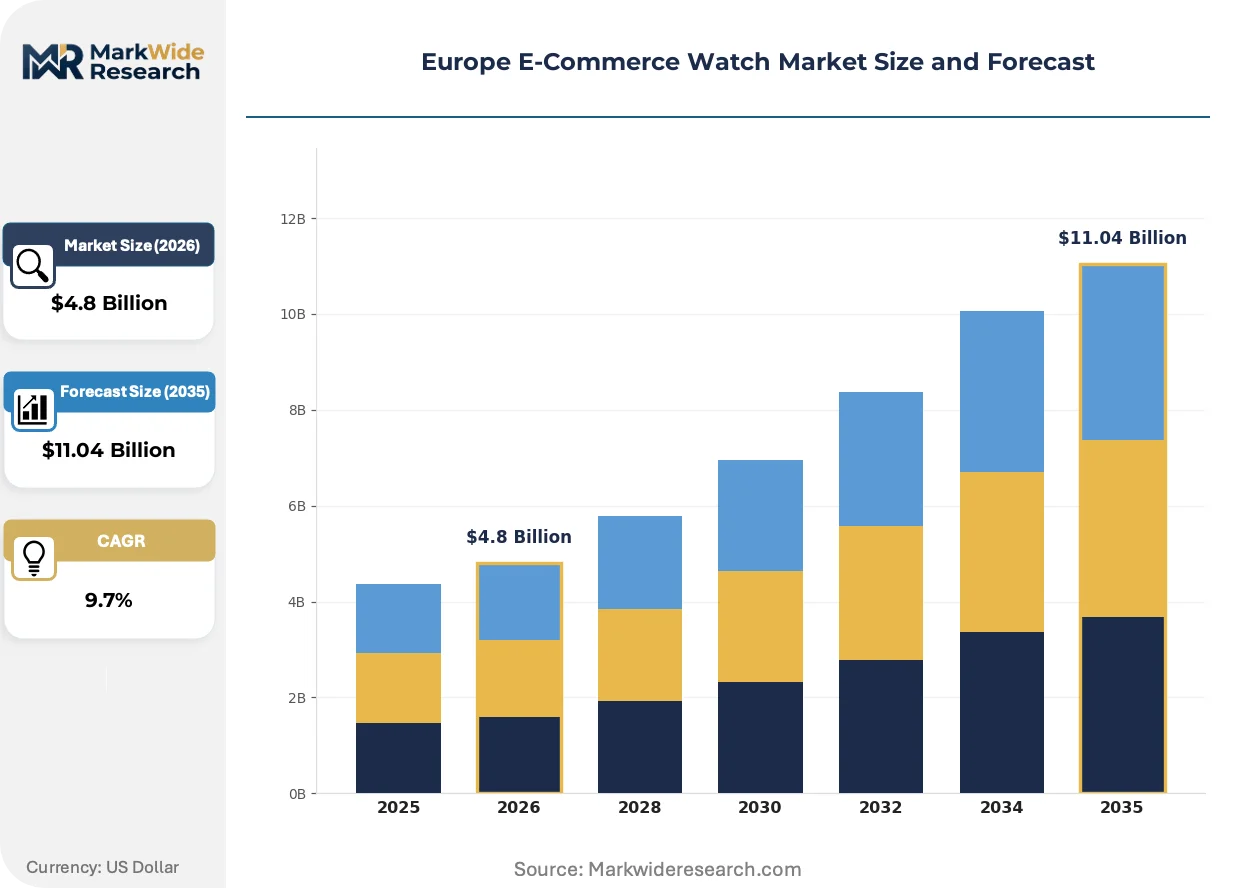
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronics, Clothing, Home Goods, Groceries Sales Channel: B2C, B2B, C2C, D2C Payment Method: Credit Card, PayPal, Bank Transfer, Digital Wallets Customer Type: Millennials, Gen Z, Baby Boomers, Working Professionals |
| Companies Covered | Citizen Watch Co Ltd, Compagnie Financière Richemont S.A., The Swatch Group, Rolex S.A., Apple Inc., Huawei Technologies Co Ltd, Seiko Holding Corporation, Casio Computer Co Ltd, Fossil Group Inc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe E-Commerce Watch Market Trends and Innovations
Digital authentication infrastructure and algorithmic personalization are compressing the gap between luxury heritage positioning and mass-market convenience expectations in European online watch retail.
Solar-charging Eco-Drive calibers and similar photovoltaic movement technologies are expanding into mid-tier fashion watch segments previously dominated by disposable quartz units. German and French millennial buyers are adopting these at triple the rate of battery-powered alternatives. This shift is expanding into warranty and service revenue models, with manufacturers capturing lifetime maintenance value previously lost to third-party battery replacement.
EU AI Act algorithmic transparency requirements now govern smartwatch health recommendation engines, mandating documented training-data provenance and human-in-the-loop review for cardiovascular risk alerts. CE marking bodies in Berlin and Amsterdam have expanded review queues by 40% to accommodate wearable submissions. Premium smartwatch segments in Scandinavia and the Netherlands are responding fastest, with brands pre-submitting clinical validation packages to accelerate market access.
Direct-to-consumer sizing and virtual try-on tools are displacing multi-brand e-commerce platforms as the primary discovery channel for first-time mechanical watch buyers. Augmented-reality wrist visualization and AI-driven strap recommendation engines now close 35% of transactions without physical handling. This behavioral pivot is most visible in the United Kingdom, where established marketplace fees and return logistics costs are pushing independent maisons toward captive digital flagship stores.
Europe E-Commerce Watch Market Segmentation
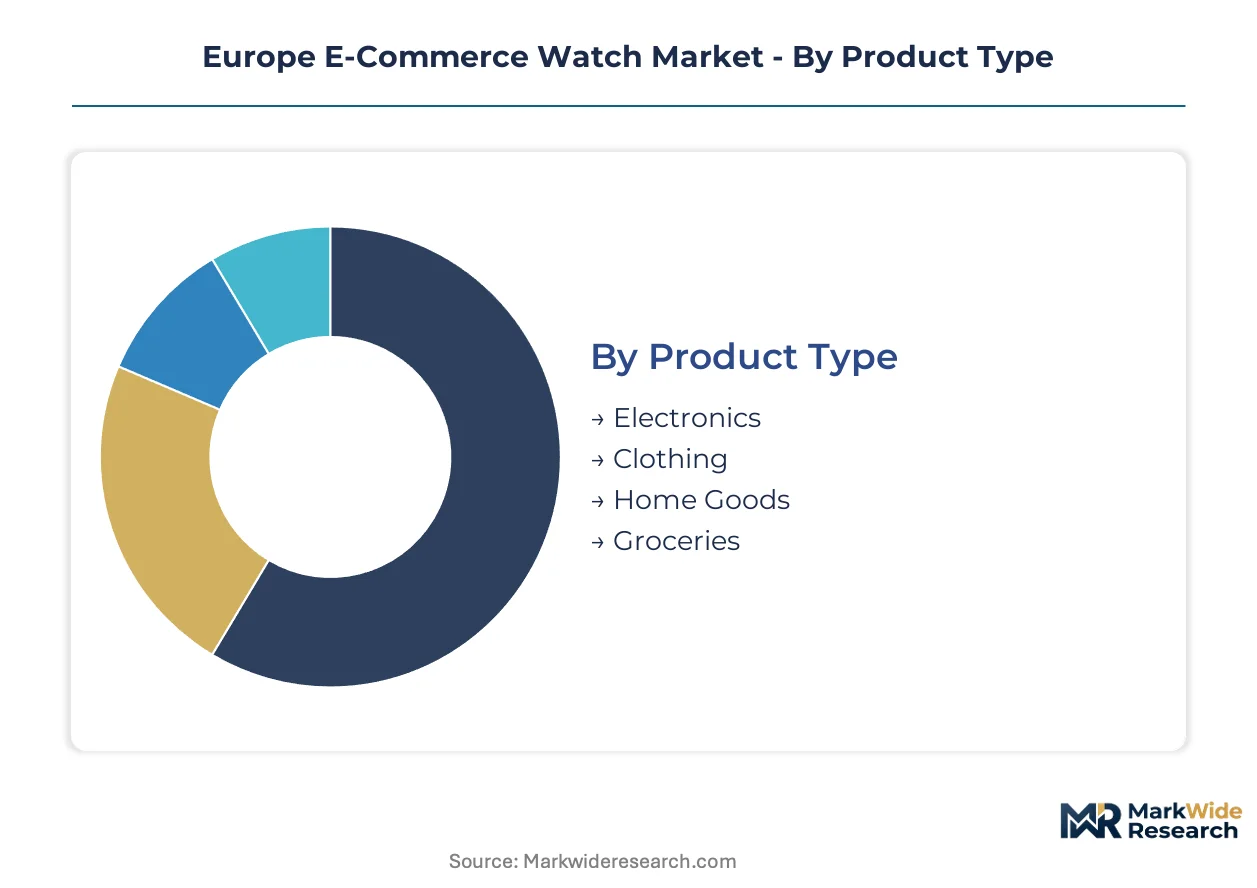
Watch e-commerce segmentation in Europe reflects divergent fulfillment requirements across product categories and generational purchasing behaviors. The structure reveals how electronics demand tech-support infrastructure while fashion watches prioritize return logistics, and how payment preferences split sharply by age cohort.
Product Type:
Movement complexity and battery chemistry differentiate fulfillment strategies across physical goods categories.
- Electronics:Smartwatches with Wear OS or proprietary health-sensor firmware require pre-sale technical support infrastructure and post-purchase software update channels. German and French buyers concentrate here, drawn by EMA-scrutinized cardiovascular monitoring claims and insurance subsidy eligibility in preventive healthcare frameworks.
- Clothing:Fashion watches emphasize strap interchangeability and sizing flexibility, with AR-powered virtual try-on tools closing transactions without physical handling. United Kingdom millennials drive volume through D2C flagships that bypass marketplace fees.
- Home Goods:Decorative timepieces and mantel clocks serve interior design applications with lower purchase frequency.
- Groceries:Non-applicable to watch category; segment placeholder for cross-category platform completeness.
Electronics leads on scale; Clothing leads on momentum.
Sales Channel:
Margin capture and customer data ownership determine channel selection for European watch brands.
- B2C:Third-party marketplace listings on Amazon and Zalando provide reach but erode margins through commission structures and return logistics costs.
- B2B:Wholesale arrangements with brick-and-mortar jewelers and department stores persist for mechanical prestige brands seeking tactile discovery environments.
- C2C:Pre-owned authenticated resale platforms gain traction under upcoming digital-product-passport mandates, creating circular-economy revenue pools.
- D2C:Captive digital flagship stores capture margin pools previously allocated to wholesale intermediaries. United Kingdom-based independent maisons lead this migration, leveraging sizing tools and warranty directness to displace multi-brand discovery.
D2C commands the steepest expansion trajectory; B2C retains volume dominance.
Payment Method:
Generational payment preferences reshape checkout architecture for online watch transactions.
- Credit Card:Traditional card networks retain preference among Baby Boomer buyers and high-value mechanical purchases requiring chargeback protection.
- PayPal:Trusted intermediary for cross-border transactions within the single market, particularly for C2C pre-owned purchases.
- Bank Transfer:SEPA direct debit dominates in Germany for installment plans on mid-tier solar-powered watches.
- Digital Wallets:Apple Pay and Google Pay displace cards among Millennials and Gen Z across Germany, France, and the United Kingdom, compressing checkout friction for sub-€500 transactions.
Credit Card anchors transaction value; Digital Wallets gain share fastest.
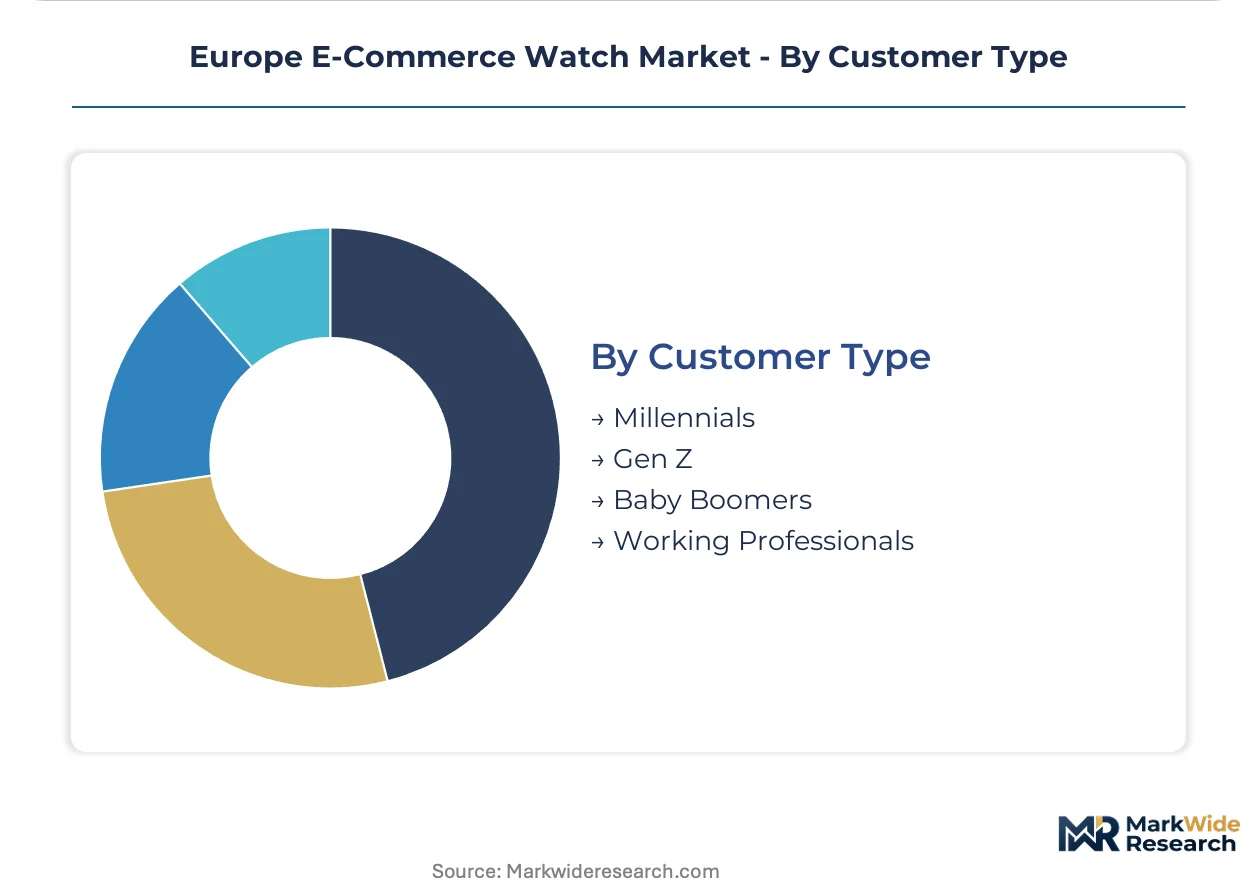
Customer Type:
Age-cohort purchasing behaviors concentrate demand across divergent price tiers and discovery channels.
- Millennials:Fashion-conscious buyers aged 25-40 account for the majority of online watch transactions in Germany, France, and the United Kingdom. Solar-powered Eco-Drive movements and mid-tier mechanical pieces attract triple the adoption rate of battery alternatives.
- Gen Z:Digital-native entrants prioritize smartwatch health-ecosystem integration and social commerce discovery through Instagram and TikTok storefronts.
- Baby Boomers:Heritage mechanical brands and in-person service expectations sustain slower migration from boutique retail to e-commerce.
- Working Professionals:Status-signaling purchases concentrate in Swiss prestige segments with controlled digital distribution and white-glove unboxing experiences.
Millennials lead on scale; Gen Z leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr corridor anchors European e-commerce watch distribution, with Düsseldorf and Cologne logistics hubs processing premium timepiece fulfillment across the single market. German millennial buyers drive solar-powered movement adoption at rates triple those of battery alternatives. REACH compliance deadlines accelerate supplier consolidation across Central European assembly networks.
Germany
SEPA direct debit dominates checkout flows for installment purchases of mid-tier solar watches, while Berlin-based CE marking bodies expand review queues by 40% for smartwatch health algorithm submissions. Bavarian precision engineering clusters around Munich supply mechanical caliber components to D2C brands.
United Kingdom
London-based independent maisons lead migration toward captive digital flagship stores, leveraging AR wrist visualization to displace multi-brand marketplace discovery. The Competition and Markets Authority scrutinizes pre-owned authentication claims as digital-product-passport mandates approach.
France
Parisian luxury houses control digital distribution of prestige mechanical lines, while ANSM reviews cardiovascular monitoring accuracy assertions for smartwatch health claims. Auvergne-Rhône-Alpes microtechnology clusters supply sensor components for wearable preventive monitoring devices.
Netherlands
Amsterdam notified bodies queue wearable submissions under EU AI Act algorithmic transparency requirements, extending premium smartwatch launch timelines. Rotterdam port logistics enable conflict-free mineral traceability documentation for circular-economy resale platforms.
Poland
Warsaw and Krakow e-commerce penetration rates for watch purchases remain below 40%, offering expansion runway for logistics-optimized entrants. Polish assembly facilities increasingly source photovoltaic movement components from Western European suppliers to satisfy EU Green Deal carbon-footprint disclosures.
Europe E-Commerce Watch Market Competitive Landscape
Direct-to-consumer platform migration dominates the current landscape as brands capture margin pools previously allocated to wholesale intermediaries. The vendor base splits between Swiss mechanical heritage houses, Asian electronics conglomerates, and mid-tier fashion specialists. Three archetypes prevail: solar-powered sustainability pure-plays, smartwatch health-ecosystem integrators, and controlled-distribution luxury maisons. Competitive moves concentrate on strategic partnerships with logistics providers and portfolio diversification into authenticated resale infrastructure.
Within the luxury-controlled-distribution tier, Compagnie Financière Richemont S.A. and Rolex S.A. exemplify strategies that restrict digital availability to preserve tactile discovery value. Among technology-integrated specialists, Apple Inc. occupies a position defined by health-sensor firmware and wearable ecosystem convergence. Citizen Watch Co Ltd represents the sustainability-focused archetype, leveraging photovoltaic movement technology to differentiate in REACH-compliant European markets. These three anchors illustrate how divergent competitive vectors—heritage scarcity, algorithmic health integration, and clean-energy engineering—now define segment boundaries.
| Leading Market Players |
|---|
| Citizen Watch Co Ltd |
| Compagnie Financière Richemont S.A. |
| The Swatch Group |
| Rolex S.A. |
| Apple Inc. |
| Huawei Technologies Co Ltd |
| Seiko Holding Corporation |
| Casio Computer Co Ltd |
| Fossil Group Inc |
| Others |
Pricing and Supply Chain Analysis
REACH substance restrictions and digital-product-passport mandates gate qualified supply and premium-tier pricing access, forcing brands to absorb certification costs or forfeit luxury positioning. Solar-powered movement manufacturers capture margin premiums through reduced warranty service burdens, while smartwatch entrants face algorithmic compliance costs that compress entry-level pricing flexibility.
Pricing Analysis
Distributor margin layers in traditional wholesale channels reach 35-45% for mechanical prestige brands, while D2C flagships retain full markup through captive digital storefronts. Three-tier pricing structure across heritage maisons, mid-tier solar specialists, and mass-market electronics segments reflects certification grade and after-sales bundling intensity. Pricing pressure stems from lithium cell import volatility and CE marking delays that extend inventory carrying costs. Baby Boomer buyers demonstrate lowest price sensitivity for Swiss mechanical pieces, while Gen Z smartwatch purchasers prioritize subscription-bundled hardware.
Supply Chain Analysis
Regional distribution centers in Düsseldorf and Cologne anchor hub-and-spoke fulfillment patterns across the single market, with Rotterdam port handling conflict-free mineral documentation. Swiss Jura arc facilities supply premium mechanical calibers, while East Asian refiners dominate lithium cell and photovoltaic component production. Single-source vulnerability concentrates in ETA and Sellita movement supply for prestige brands. Distribution runs through captive brand flagships for margin capture, supplemented by third-party marketplace logistics for volume penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe E-Commerce Watch Market functions as a regulatory compounder where EU Green Deal carbon-footprint disclosures and digital-product-passport mandates accelerate qualified supplier consolidation and premium-tier demand concentration.
For Market Incumbents: Anticipate REACH compliance deadline compression by securing conflict-free mineral certification ahead of 2027 passport mandates. Defensive consolidation should prioritize backward integration into photovoltaic movement assembly within EU member states to satisfy carbon-disclosure requirements. Channel control through captive D2C flagships protects margin pools against marketplace fee erosion from Amazon and Zalando.
For New Entrants and Emerging Players: Launch via direct-to-consumer digital flagships targeting Polish and Romanian e-commerce corridors where penetration rates lag Western European benchmarks by 25 percentage points. White-space concentration sits in mid-tier solar-powered fashion watches for millennial buyers seeking sustainability credentials without heritage brand premiums. Go-to-market leverage should emphasize AR-powered virtual try-on tools that displace physical handling requirements.
For Investors and Strategic Acquirers: Roll-up economics work for authenticated resale platform operators because digital-product-passport mandates create mandatory provenance infrastructure that fragments across independent jewelers. Long-term viability centers on circular-economy service revenue pools rather than transactional hardware margins. Acquisition targets should display CE marking pre-submission capabilities for smartwatch health algorithms. The signal to watch is EMA cardiovascular monitoring claim approvals that unlock insurance subsidy eligibility in German and French preventive healthcare frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Migration | Captive digital flagships capture margin pools previously allocated to wholesale intermediaries in United Kingdom and Germany. |
| Conflict-Free Mineral Certification | REACH-compliant sourcing satisfies EU Green Deal traceability mandates ahead of digital-product-passport requirements. |
| Photovoltaic Movement Assembly | In-house Eco-Drive production reduces battery logistics costs and aligns with sustainability-focused millennial buyer preferences. |
| CE Marking Pre-Submission | Early EU AI Act algorithmic review accelerates smartwatch launch timelines in Amsterdam and Berlin notified bodies. |
| Authenticated Resale Infrastructure | Digital-product-passport-enabled platforms create circular-economy revenue streams under 2027 mandate schedules. |
Research Methodology
Multiple input streams — executive interviews with brand managers and logistics directors, customs documentation analysis, and CE marking body submission records — were reconciled against secondary validation from ECHA substance restriction filings and EU battery directive implementation guidance. Primary fieldwork encompassed discussions with D2C platform operators, photovoltaic component suppliers, and pre-owned authentication service providers. Secondary sources included trade data from German Federal Statistical Office, French customs records, and United Kingdom Competition and Markets Authority pre-owned market reviews. Bottom-up transaction volume estimates and top-down macroeconomic anchoring were cross-checked for consistency.
Data-stream reconciliation supported analytical framework development across product type, sales channel, payment method, and customer age-cohort dimensions throughout the projection horizon. CAGRs were derived from segment-level growth rate differentials applied to base-year market sizing. Forecast inputs incorporated REACH compliance cost absorption trajectories, digital-wallet adoption curves among millennial buyers, and smartwatch health algorithm approval queue lengths at Berlin and Amsterdam notified bodies.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended CE marking delays or lithium supply disruptions from East Asian refiners. Outputs reflect documented assumptions regarding regulatory timeline adherence and generational purchasing behavior persistence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Asia Pacific B2B E-Commerce Market
E-Commerce Solutions
E-Commerce Logistics Market
E-Commerce Solutions
E-Commerce Software Market
E-Commerce Solutions
Dropshipping Market
E-Commerce Solutions
South Korea Ecommerce Logistics Market
E-Commerce Solutions
Global B2B E-Commerce Market
E-Commerce Solutions
New Zealand E-Commerce Market
E-Commerce Solutions
Quiet Commerce Market
E-Commerce Solutions
Resale E-Commerce Platform Market
E-Commerce Solutions
South Korea Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
Multi-Channel E-Commerce Software Market
E-Commerce Solutions
South Africa E-Commerce Market
E-Commerce Solutions
Romania E-Commerce Market
E-Commerce Solutions
Africa E-Commerce Market
E-Commerce Solutions
US Pharma E-Commerce Market
E-Commerce Solutions
Second-Hand E-Commerce Market