
 E-Commerce Market | 2026-2036
E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
E-Commerce Market Intelligence
Digital logistics talent scarcity is bifurcating fulfillment capabilities between operators with captive last-mile networks and those dependent on third-party providers. Amazon.com Inc. leverages its proprietary warehouse robotics and delivery infrastructure to sustain next-day reliability across dense metropolitan zones. JD.com Inc. anchors its competitive edge through in-house supply chain control spanning procurement to doorstep delivery in tier-one Chinese cities. MercadoLibre Inc. competes by integrating fintech and logistics within Latin American markets where banking penetration remains uneven.
E-commerce encompasses digitally mediated transactions for goods and services executed through web-based storefronts, mobile applications, and API-connected procurement platforms, typically requiring encrypted payment gateways, inventory management systems, and real-time order tracking protocols to enable remote commercial exchange. Fashion and electronics currently occupy the largest product type revenue pools, though home goods is accelerating as augmented reality visualization tools reduce return rates for furniture and fixture purchases. B2C sales channel dominance persists in volume terms, yet B2B digital procurement is deepening as enterprise buyers migrate indirect spend categories onto platform-based purchasing workflows.
The US Federal Trade Commission scrutinizes marketplace fee structures and seller data usage, while the EU Digital Services Act imposes transparency obligations on algorithmic product ranking and consumer profiling across European operations. India's ONDC framework and data localization requirements under its digital commerce policies are fragmenting platform economics and compelling foreign operators to establish domestic infrastructure. Stakeholders must monitor how divergent regulatory architectures for data sovereignty, antitrust enforcement, and seller protection reshape cost structures and market entry feasibility across jurisdictions.
Market Dynamics
India's ONDC protocol is fragmenting platform economics and forcing foreign operators to build domestic fulfillment infrastructure, while Southeast Asian mobile-first adoption deepens competitive access rules across Jakarta, Ho Chi Minh City, and Manila.
Growth Catalysts
- India's DPI infrastructure:The ONDC framework enables interoperable transactions between fragmented seller networks and payment systems, lowering entry barriers for regional merchants.
- Grocery and fresh food delivery:Urban consumers in dense metropolitan zones are shifting weekly purchasing online, compressing delivery windows and expanding addressable market scope.
- Mobile-first commerce penetration:Indonesia, Vietnam, and the Philippines exhibit deepening smartphone-based transaction habits, particularly among unbanked populations accessing digital marketplaces.
Market Restraints
- Last-mile logistics cost concentration:Dense urban zones require captive delivery networks or third-party provider dependency, bifurcating fulfillment economics between scaled and unscaled operators.
- Data localization mandates:India's digital commerce policies compel foreign platforms to store transaction data within domestic boundaries, raising infrastructure capital requirements.
- Fresh inventory spoilage rates:Temperature-controlled supply chains for grocery and perishable categories impose working capital intensity that pure general merchandise platforms avoid.
Strategic Opportunities
- B2B digital procurement workflows:Enterprise buyers migrating indirect spend categories onto platform-based purchasing systems represent underpenetrated volume expansion.
- Augmented reality visualization:Furniture and fixture purchases benefit from AR tools that reduce return rates, opening home goods category acceleration.
- Fintech-logistics integration:Latin American markets with uneven banking penetration reward operators embedding payment and credit services within commerce platforms.
Industry Challenges
- Digital logistics talent scarcity:Fulfillment network design and warehouse robotics programming skills concentrate among operators with captive technical training pipelines.
- Algorithmic transparency compliance:The EU Digital Services Act imposes disclosure obligations on product ranking systems, requiring engineering resources for audit-ready documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Commerce Market |
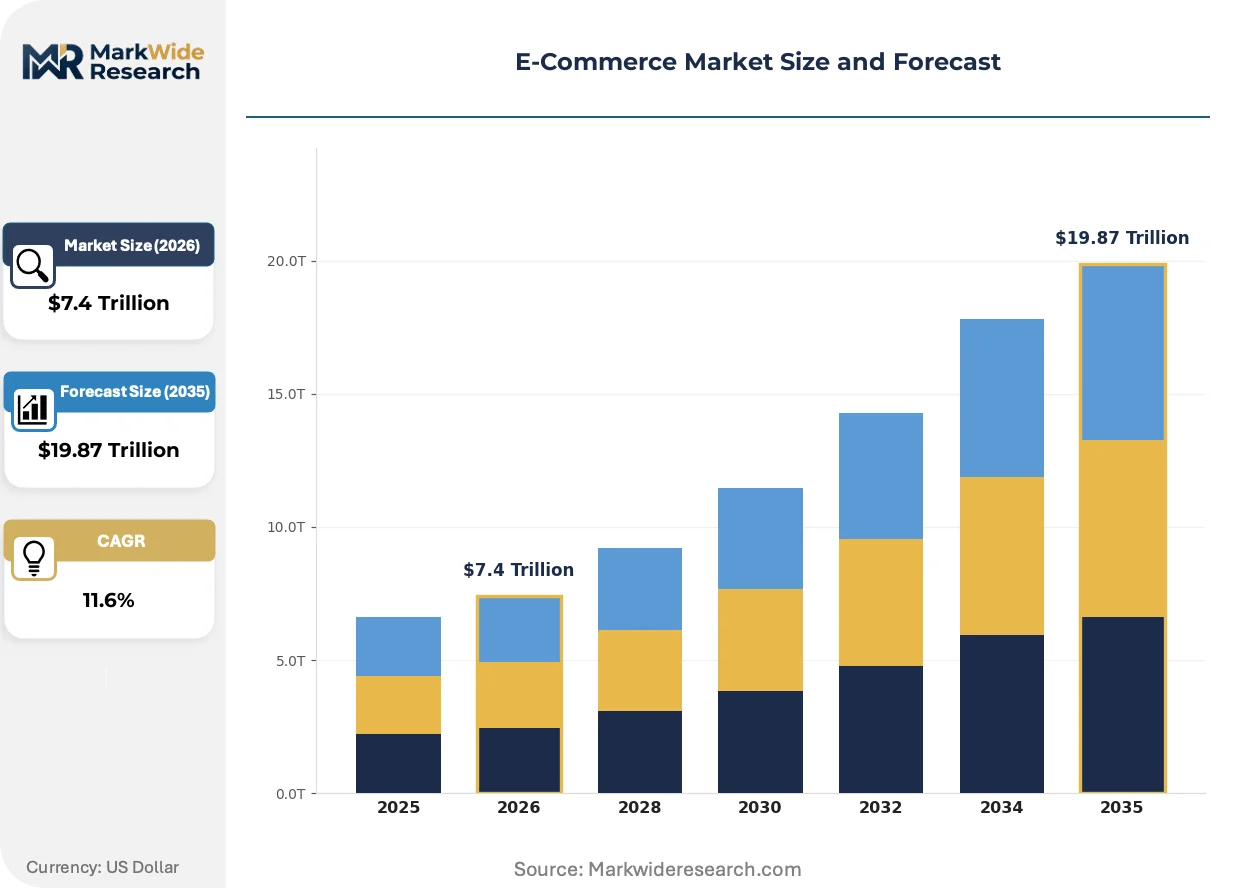
| Market Size in 2026 | $7.4 Trillion |
| Market Size in 2035 | $19.87 Trillion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fashion, Electronics, Home Goods, Beauty Sales Channel: B2C, C2C, B2B, Direct-to-Consumer Customer Type: Millennials, Gen Z, Baby Boomers, Professionals Payment Method: Credit Card, Digital Wallet, Bank Transfer, Cash on Delivery |
| Companies Covered | Amazon.com Inc., Alibaba Group Holding Limited, JD.com Inc., Walmart Inc., Shopify Inc., eBay Inc., PDD Holdings, MercadoLibre Inc., Rakuten Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Commerce Market Strategic Shifts & Innovations
Warehouse robotics and automated sortation systems are compressing order-to-dispatch intervals, while regulatory pressure on marketplace data usage intensifies technical investment requirements across operational jurisdictions.
Autonomous mobile robots with vision-guided picking capabilities are supplanting manual warehouse labor in high-SKU-density facilities. Fashion and electronics retailers with next-day delivery commitments deploy these systems most aggressively. The technology is supplanting traditional conveyor-based infrastructure and enabling smaller-footprint fulfillment centers in expensive urban real estate.
The EU Digital Services Act mandates algorithmic transparency for product ranking and consumer profiling across European operations. Marketplace operators must document how recommendation engines prioritize listings and explain variable fee structures to sellers. Fashion and electronics categories face heightened scrutiny given their volume concentration and seller complaint frequency.
Enterprise procurement departments are consolidating indirect spend onto API-connected purchasing platforms, displacing traditional distributor relationships. Manufacturing and healthcare verticals lead this migration, seeking spend visibility and compliance automation. Germany and France exhibit the deepest B2B platform adoption within European markets.
E-Commerce Market Segmentation
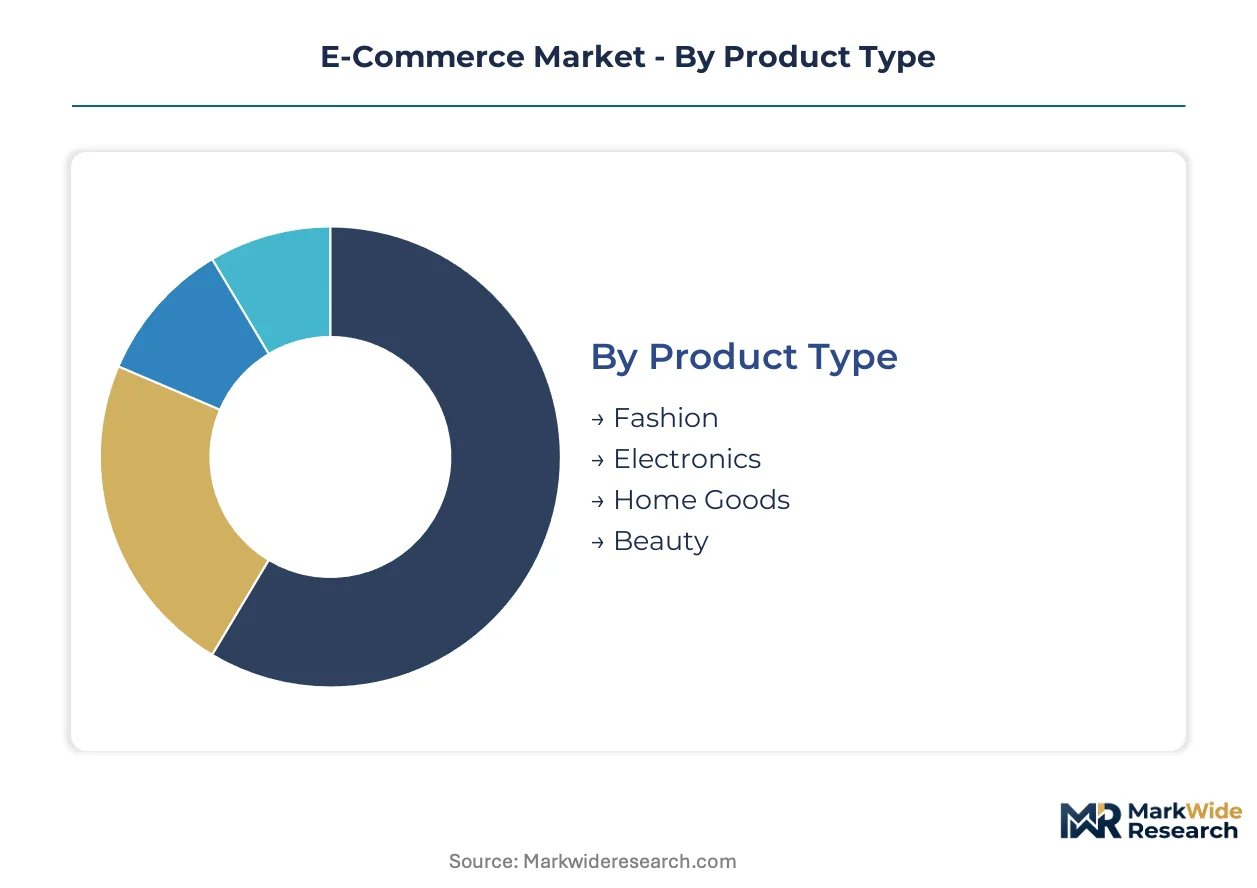
Segmentation in e-commerce reveals where capital allocation and technical investment concentrate. Product type and sales channel dimensions determine fulfillment infrastructure requirements, while customer cohorts and payment preferences shape platform interface design and trust architecture.
Product Type:
Margin pools concentrate in categories with high return frequency and visual merchandising complexity.
- Fashion:Apparel and accessories dominate transaction volumes with size-variant complexity and seasonal inventory turnover. Demand concentrates in urban Indian and Southeast Asian markets where mobile-first discovery drives impulse purchasing through influencer-curated feeds.
- Electronics:Smartphones, laptops, and peripherals carry higher average order values with warranty and authentication requirements. Chinese tier-one cities and metropolitan India anchor volume, with JD.com and Amazon maintaining captive distribution networks for next-day reliability commitments.
- Home Goods:Furniture and fixtures benefit from augmented reality visualization tools that reduce return rates. Compact urban apartments in Jakarta and Ho Chi Minh City drive demand for space-efficient designs.
- Beauty:Skincare and cosmetics leverage subscription models and sample-driven discovery. Korean and Japanese regulatory frameworks for ingredient disclosure shape cross-border purchasing patterns.
Fashion holds installed capacity. Home Goods is rotating up the share rankings.
Sales Channel:
Channel economics diverge sharply based on inventory ownership and seller relationship structures.
- B2C:First-party and third-party marketplace models with platform-controlled fulfillment. Volume concentrates in Amazon's North American operations and JD.com's Chinese infrastructure, where warehouse robotics compress dispatch intervals.
- B2B:Enterprise procurement platforms consolidating indirect spend categories. Manufacturing and healthcare verticals in Germany and France drive deepest adoption through API-connected purchasing workflows.
- C2C:Peer-to-peer marketplaces with minimal platform inventory risk. MercadoLibre anchors Latin American volume through integrated fintech services addressing uneven banking penetration.
- Direct-to-Consumer:Brand-owned storefronts bypassing marketplace fee structures. US and European specialty retailers deploy this channel to capture first-party customer data for personalization.
B2C captures dominant transaction volume. B2B is expanding most quickly as enterprise buyers migrate spend onto platform-based systems.
Customer Type:
Cohort-specific interface design and payment trust architectures determine conversion optimization priorities.
- Gen Z:Digital-native consumers with social commerce discovery habits and buy-now-pay-later preferences. Southeast Asian markets exhibit highest concentration, with TikTok Shop and Shopee capturing engagement through live-stream purchasing.
- Millennials:Subscription-oriented buyers with established platform loyalty and sustainability filtering. Urban Indian professionals drive premium grocery and fresh food delivery adoption through Blinkit and Zepto.
- Professionals:Time-constrained purchasers prioritizing convenience and delivery reliability. Dense metropolitan zones in São Paulo and Mexico City reward operators with captive last-mile networks.
- Baby Boomers:Security-focused shoppers requiring simplified interfaces and human customer service. Japanese and European markets show strongest representation, with Rakuten and Zalando investing in voice-assisted navigation.
Millennials hold established purchasing power. Gen Z is climbing the fastest in addressable lifetime value projections.
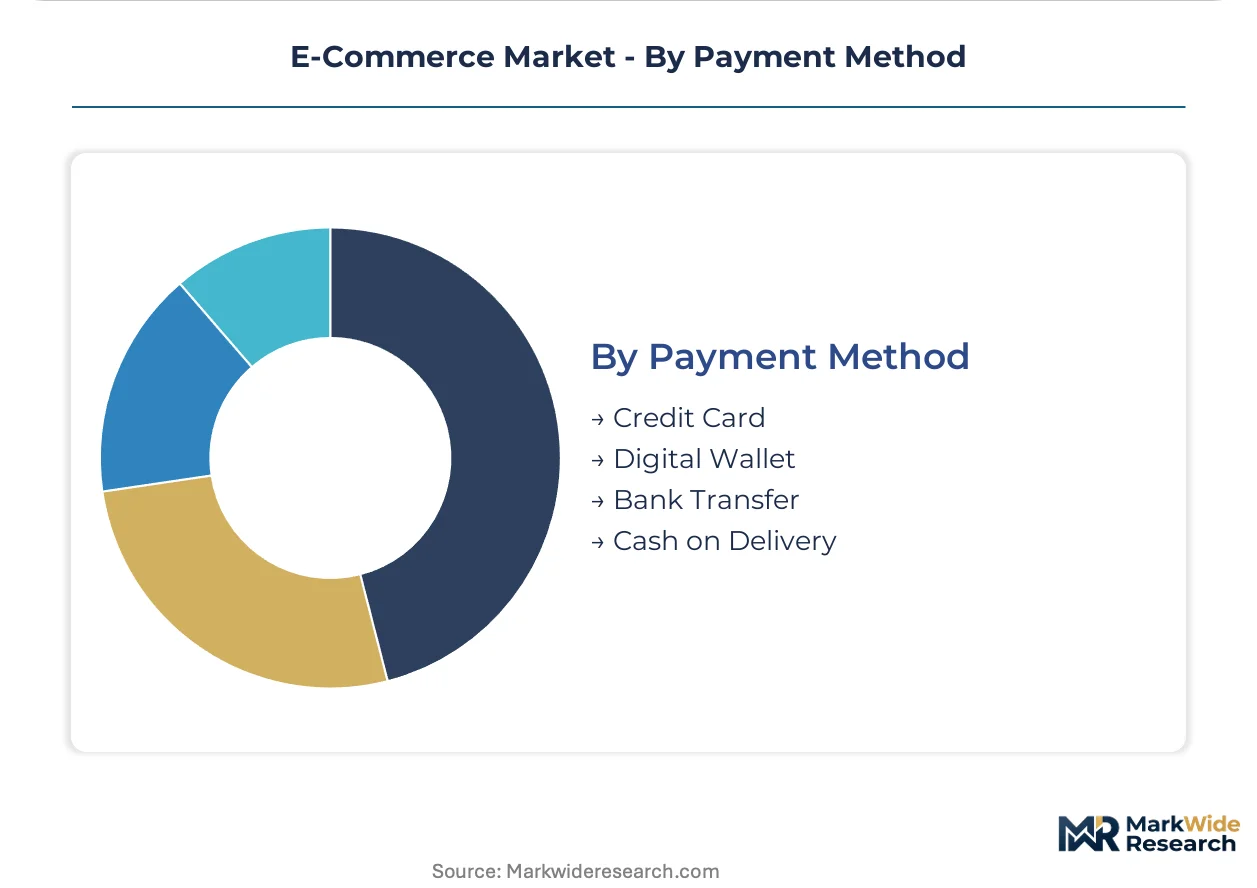
Payment Method:
Payment infrastructure determines market access depth for unbanked populations and cross-border transaction feasibility.
- Digital Wallet:Mobile-first payment systems with embedded loyalty and credit services. Indonesia, Vietnam, and the Philippines exhibit deepest penetration through GoTo Financial and Momo, displacing traditional banking relationships.
- Credit Card:Established instrument in North American and European markets with chargeback protection and rewards programs. US FTC scrutiny of data usage shapes issuer-platform partnership terms.
- Cash on Delivery:Trust-building mechanism in markets with low card penetration and fraud concerns. Indian e-commerce retains significant COD share despite UPI growth, particularly in tier-two and tier-three cities.
- Bank Transfer:Preferred for high-value B2B transactions and German-speaking European markets. SEPA infrastructure enables low-cost settlement, though reconciliation complexity exceeds card networks.
Digital Wallet holds installed capacity. Bank Transfer is gaining share fastest in B2B procurement workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FTC enforces marketplace fee transparency and seller data protection rules that shape operator economics across the United States, while divergent regulatory architectures in India, China, and Southeast Asia fragment platform strategies across jurisdictions.
United States
Amazon's proprietary fulfillment network and Walmart's omnichannel infrastructure dominate transaction volumes. The FTC scrutinizes algorithmic ranking systems and seller contract terms under antitrust mandates. New York and Los Angeles anchor dense last-mile delivery zones where warehouse robotics compress dispatch intervals.
China
JD.com's in-house supply chain control and PDD Holdings' social commerce model capture divergent consumer segments. SAMR enforces data localization and anti-monopoly provisions that constrain cross-border data flows. Shanghai and Beijing concentrate fulfillment automation investments for next-day reliability commitments.
India
ONDC protocol adoption enables interoperable transactions between fragmented seller networks and UPI payment systems. RBI and DPI infrastructure mandates compel foreign operators to establish domestic data storage and fulfillment assets. Mumbai and Bengaluru anchor grocery and fresh food delivery expansion as urban consumers shift weekly purchasing online.
Indonesia
Mobile-first commerce penetration deepens through GoTo Financial's embedded payment and logistics integration. The central bank's digital wallet regulations shape fintech-commerce convergence. Jakarta and Surabaya drive demand for compact home goods as augmented reality visualization tools reduce return rates for furniture purchases.
Germany
B2B digital procurement workflows consolidate indirect enterprise spend onto API-connected purchasing platforms. The EU Digital Services Act imposes algorithmic transparency obligations on product ranking systems. Berlin and Munich exhibit deepest manufacturing and healthcare vertical adoption for platform-based purchasing automation.
E-Commerce Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the e-commerce landscape. The market structures around three tiers: integrated operators with captive logistics networks, platform-as-a-service enablers, and specialized regional marketplaces. Strategic differentiation concentrates fulfillment reliability, fintech integration, and seller ecosystem density. Dominant competitive moves include backward integration into warehouse robotics and geographic expansion through localized fulfillment infrastructure.
Within the integrated logistics tier, Amazon.com Inc. and JD.com Inc. exemplify operators with end-to-end supply chain control from procurement to doorstep delivery. MercadoLibre Inc. occupies a distinct position embedding payment and credit services within commerce platforms for markets with uneven banking penetration. Alibaba Group Holding Limited anchors the platform-as-a-service archetype enabling third-party merchant ecosystems at scale.
| Leading Market Players |
|---|
| Amazon.com Inc. |
| Alibaba Group Holding Limited |
| JD.com Inc. |
| Walmart Inc. |
| Shopify Inc. |
| eBay Inc. |
| PDD Holdings |
| MercadoLibre Inc. |
| Rakuten Group Inc. |
| Others |
Cost & Logistics Intelligence
Warehouse robotics substitution for manual fulfillment labor simultaneously reshapes supply geography toward expensive urban real estate and compresses pricing economics for next-day delivery commitments. Operators deploying autonomous mobile robots in high-SKU-density facilities offset real estate premiums through smaller-footprint fulfillment centers, while third-party-dependent competitors absorb margin erosion from logistics provider rate inflation.
Pricing Analysis
Metropolitan delivery zones in Mumbai and Jakarta exhibit 40-60% fulfillment cost premiums over tier-two cities, forcing three-tier pricing structure across premium, standard, and economy delivery windows. Price differentiation rests on delivery speed guarantees and inventory ownership models, with first-party logistics commanding subscription premiums and marketplace sellers absorbing platform fee compression. Cost compression in standard-tier fulfillment is intensifying because warehouse robotics deployment concentrates among scaled operators. Small and medium marketplace sellers demonstrate highest price sensitivity, while enterprise procurement buyers prioritize compliance automation over unit economics.
Supply Chain Analysis
Last-mile logistics chokepoints in dense Southeast Asian urban corridors constrain fulfillment reliability for operators without captive delivery networks. Supply concentration centers on China for warehouse robotics hardware, India for software development talent, and Vietnam for electronics assembly supporting fulfillment automation. Raw material dependencies span lithium-ion batteries for delivery fleet electrification, rare earth elements for robotic motor systems, and temperature-controlled packaging for grocery segments. Single-source vulnerability in Chinese robotics component supply threatens fulfillment automation timelines. Distribution runs through hub-and-spoke fulfillment networks anchored in tier-one metropolitan zones with satellite sortation facilities in secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The e-commerce market sits in a cyclical recovery phase driven by enterprise procurement digitization, as manufacturing and healthcare verticals consolidate indirect spend onto platform-based purchasing workflows after pandemic-era disruption.
For Market Incumbents: Compound fulfillment reliability advantages through backward integration into warehouse robotics programming and captive last-mile fleet expansion in Jakarta, Ho Chi Minh City, and Manila. Defend against ONDC-enabled regional merchant networks by embedding proprietary payment and credit services within commerce platforms. Prioritize technical training pipelines to offset digital logistics talent scarcity. For New Entrants and Emerging Players: Differentiate on B2B procurement workflow automation for German and French manufacturing verticals, where API-connected purchasing platforms remain underpenetrated relative to North American adoption. Target grocery and fresh food delivery in tier-two Indian cities where Blinkit and Zepto coverage remains sparse. Pursue fintech-logistics integration in Latin American markets as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated operators with captive supply chain control over asset-light marketplace models. Long-term viability over the next decade hinges on fulfillment network density and regulatory compliance infrastructure rather than pure transaction volume growth. Monitor India's DPI infrastructure expansion and data localization enforcement as the primary inflection signal for foreign operator capital requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Warehouse Robotics Deployment | Autonomous mobile robots in Mumbai and Shanghai facilities compress order-to-dispatch intervals for fashion and electronics categories. |
| ONDC Protocol Integration | Interoperable transaction infrastructure enables regional Indian merchants to bypass dominant platform fee structures. |
| Fintech-Logistics Convergence | Embedded payment and credit services in GoTo Financial and MercadoLibre platforms address unbanked populations across Indonesia and Brazil. |
| B2B Procurement Platform Expansion | API-connected purchasing workflows in German manufacturing verticals displace traditional distributor relationships for indirect spend. |
| Augmented Reality Visualization | AR tools for furniture and fixture purchases reduce return rates in Jakarta and Ho Chi Minh City compact urban apartment segments. |
Research Approach
Cross-validation between executive interviews at fulfillment automation vendors and secondary analysis of customs data for warehouse robotics imports anchors the qualitative findings in this study. Primary fieldwork encompassed conversations with e-commerce operations directors, third-party logistics procurement leads, platform engineering heads, and seller ecosystem managers across North American, European, and Asia-Pacific markets. Secondary sources included SEC 10-K filings, EU Digital Services Act regulatory disclosures, RBI payment system reports, and trade flow databases. Bottom-up transaction volume estimates triangulated against top-down GDP-attribution models.
Sensitivity analysis around fulfillment cost inflation and regulatory compliance timelines informs the projection framework across the analysis window. Segmentation dimensions encompass product type, sales channel, customer cohort, and payment method, with additional modeling of logistics ownership structure and geographic urban density tiers. CAGRs derive from logistic curve adoption modeling for warehouse robotics and mobile commerce penetration rates. Forecast inputs incorporate UPI transaction growth trajectories and EU algorithmic transparency implementation schedules.
The analysis sits within stated boundaries; outcomes outside sustained urbanization trends and smartphone penetration maintenance would require recalibration. Forecasts reflect documented assumptions regarding ONDC protocol adoption velocity and data localization enforcement intensity. Practitioners should keep alternative scenarios live as India's DPI infrastructure expansion and EU Digital Services Act compliance costs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Latin America E-Commerce Logistics Market
E-Commerce Solutions
Russia Alcohol E-Commerce Market
E-Commerce Solutions
Ambient Commerce Enablement Infrastructure Market
E-Commerce Solutions
Metaverse in E-Commerce Market
E-Commerce Solutions
Romania E-Commerce Market
E-Commerce Solutions
LAMEA Dropshipping Market
E-Commerce Solutions
Global Shopping Cart Market
E-Commerce Solutions
Argentina Alcohol E-Commerce Market
E-Commerce Solutions
China Ecommerce Logistics Market
E-Commerce Solutions
Italy Dropshipping Market
E-Commerce Solutions
Switzerland E-Commerce Market
E-Commerce Solutions
Business to Business E Commerce Market
E-Commerce Solutions
Bulgaria E-Commerce Market
E-Commerce Solutions
Croatia E-Commerce Market
E-Commerce Solutions
Saudi Arabia E-Commerce Logistics Market
E-Commerce Solutions
Hong Kong E-Commerce Market