
 Global Asset Tracking Software Market | 2026-2036
Global Asset Tracking Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Asset Tracking Software Market Foresight
Enterprise-grade visibility specifications is reorganizing competitive dynamics in asset tracking software. Zebra Technologies Corp. dominates ruggedized hardware-software integration for warehouse environments. Honeywell International Inc. leverages its building automation heritage to anchor indoor positioning solutions. Trimble Inc. specializes in GPS-dense applications for construction and agriculture equipment fleets.
Asset tracking software encompasses platforms that capture, process, and visualize location, condition, and utilization data from tagged physical assets through RFID readers, GPS receivers, barcode scanners, or Wi-Fi triangulation sensors, typically achieving location precision between one meter and ten meters depending on infrastructure density. Its primary commercial purpose is to eliminate phantom inventory, reduce equipment idle time, and enforce chain-of-custody documentation across distributed operations. Cloud-based deployment leads in new customer acquisitions due to minimal capital expenditure and rapid multi-site rollout, while edge computing configurations are capturing the fastest growth among manufacturers with sub-second latency requirements for automated material handling. RFID tracking solutions command premium pricing in pharmaceutical and aerospace verticals where lot-level traceability is mandatory.
The Federal Communications Commission governs spectrum allocation for GPS and cellular-based tracking devices in the United States, directly constraining hardware design choices and service coverage maps. The European Union's GDPR and the EU AI Act impose data localization and algorithmic transparency obligations that reshape how cross-border fleet data flows through cloud platforms. Stakeholders must monitor evolving cybersecurity certification requirements from ISO and national regulators, as breach liability for location data is hardening faster than vendor insurance frameworks can adapt.
Market Dynamics
Edge-computing architectures are supplanting centralized cloud processing as the dominant technical response to data sovereignty mandates from the EU AI Act and GDPR, forcing vendors to reengineer latency-sensitive applications for localized execution.
Growth Catalysts
- EU AI Act compliance deadlines:Fleet operators across Germany and France are accelerating procurement of edge-deployed tracking platforms to satisfy algorithmic transparency and data localization requirements before enforcement phases activate.
- Automated material handling:Warehouse robotics deployments in Japan and the United States demand sub-second location refresh rates that only edge-computing configurations can deliver.
- Pharmaceutical serialization mandates:Lot-level traceability requirements from the FDA and EMA are expanding RFID tagging programs beyond finished goods into active pharmaceutical ingredient shipments.
Market Restraints
- Lithium battery supply concentration:GPS-enabled tracking hardware depends on Chinese-processed lithium cells, exposing hardware vendors to export restriction volatility and forced localization pressures.
- Spectrum licensing fragmentation:The FCC's narrowband IoT allocations conflict with European harmonized frequency bands, forcing dual-SKU hardware strategies that inflate unit economics.
- Cellular module cost structure:5G RedCap modems carry 40-60% premiums over LTE-M equivalents, compressing margins for fleet-scale deployments exceeding ten thousand units.
Strategic Opportunities
- India industrial corridor expansion:The PLI scheme for electronics manufacturing is attracting tracking hardware assembly capacity to serve underpenetrated mining and agriculture equipment markets.
- Predictive maintenance convergence:Vibration and temperature sensors fused with location data create unified condition-monitoring platforms for construction equipment lessors.
- CSRD supply chain disclosure:The EU Corporate Sustainability Reporting Directive mandates Scope 3 emissions tracking, opening subscription revenue for carbon-intensity analytics layered atop movement data.
Industry Challenges
- Embedded systems firmware talent scarcity:Vendors struggle to hire engineers capable of optimizing RTOS kernels for millisecond-grade positioning pipelines.
- ISO 27001 certification timelines:Cybersecurity audit backlogs at accredited bodies extend vendor onboarding cycles by six to nine months, delaying enterprise sales closures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Asset Tracking Software Market |
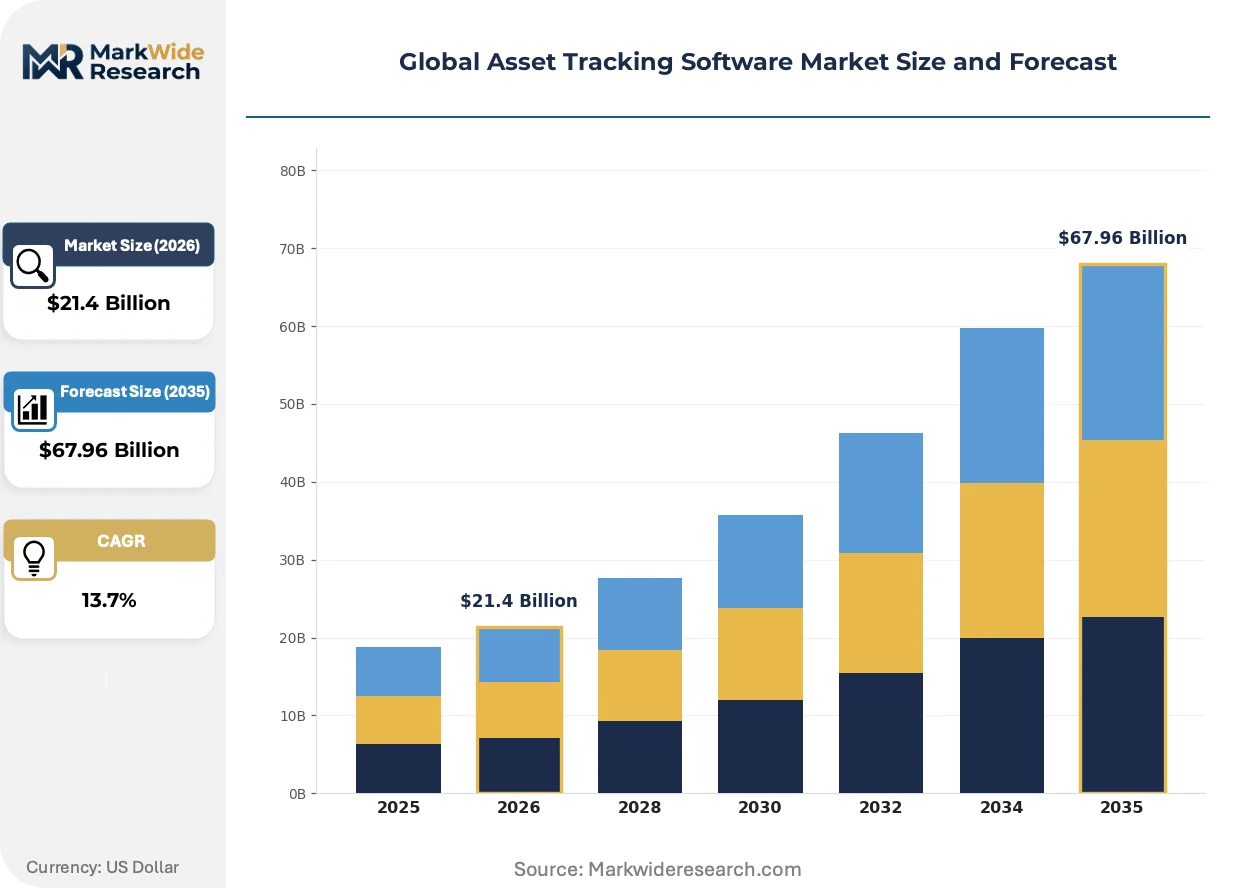
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $67.96 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing Solution Type: Real-Time Location System, RFID Tracking, GPS Tracking, Barcode Tracking, Wi-Fi Tracking Application: Logistics, Manufacturing, Construction, Oilfield Services, Warehousing End User: Third-Party Logistics, Equipment Rentals, Transportation Providers, Supply Chain Managers |
| Companies Covered | Zebra Technologies Corp., Honeywell International Inc., Trimble Inc., AT&T Inc., Samsara Inc., Asset Panda, ASAP Systems, GigaTrak, Fleet Complete, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Asset Tracking Software Market Shifts & Advancements
Real-time visibility specifications are hardening across logistics contracts, compressing acceptable location latency from minutes to seconds and rewarding vendors with deterministic edge-processing capabilities.
Ultra-wideband (UWB) ranging is supplanting Wi-Fi triangulation for indoor positioning in high-density warehouse environments. Amazon and DHL fulfillment networks are deploying UWB anchors at scale to achieve 10-30 centimeter precision for robotic picking coordination. The technology is compressing implementation timelines for automated storage and retrieval systems by eliminating RF interference dead zones that plagued earlier generations.
The EU AI Act's risk classification framework is restructuring how cross-border fleet data flows through cloud platforms. Algorithmic transparency obligations for high-risk applications now require explainable location inference models that document decision pathways. German automotive logistics providers are responding by segmenting data lakes between EU-resident edge nodes and stripped telemetry archives for global analytics.
Third-party logistics providers are unbundling visibility services from freight contracts and offering standalone tracking subscriptions to smaller shippers. This channel innovation displaces the traditional carrier-integrated model and concentrates buying power with software-native platforms. The shift is most visible in United States domestic trucking, where brokerages now resell white-labeled tracking dashboards to owner-operator networks.
Global Asset Tracking Software Market Segmentation
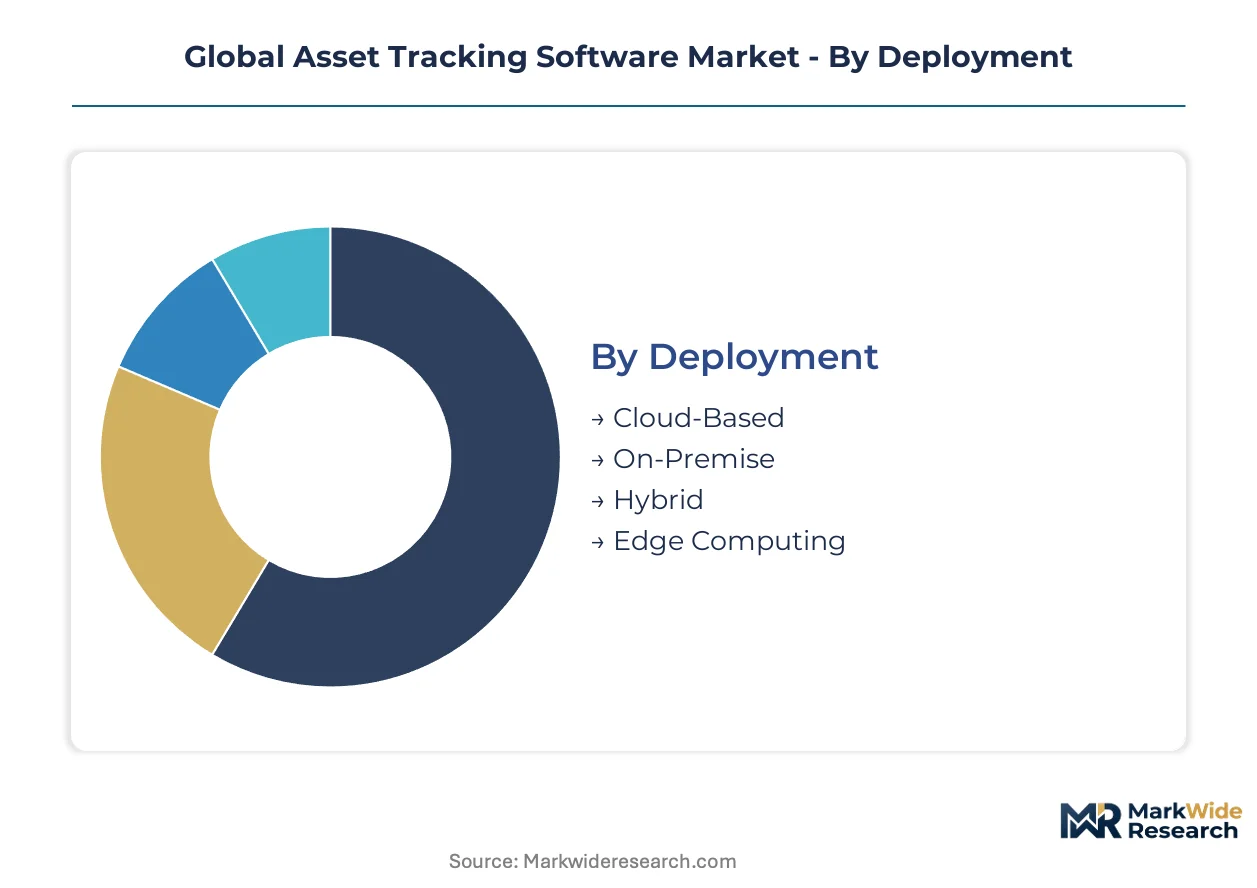
Asset tracking software segments fragment sharply across deployment architecture and solution type, with regulatory pressure on data localization forcing vendors to maintain parallel technology stacks. Procurement patterns diverge between latency-sensitive automation use cases and compliance-driven audit trails.
Deployment:
FCC spectrum governance in the United States and GDPR data residency rules in Europe create divergent infrastructure requirements that reshape vendor engineering priorities.
- Cloud-Based:Multi-tenant SaaS architectures dominate new customer acquisition due to minimal capital expenditure and rapid multi-site rollout capabilities. Third-party logistics providers in Germany and Japan favor this model for distributed fleet visibility without dedicated infrastructure teams.
- Edge Computing:Localized processing nodes execute positioning algorithms within facility boundaries to satisfy EU AI Act algorithmic transparency mandates and sub-second latency requirements for automated material handling. German automotive logistics providers are segmenting data lakes between EU-resident edge nodes and stripped telemetry archives.
- On-Premise:Air-gapped installations serve defense contractors and nuclear facilities with classified asset inventories requiring physical network isolation.
- Hybrid:Configurations blend cloud analytics with on-site data retention for pharmaceutical manufacturers navigating FDA 21 CFR Part 11 electronic record requirements.
Cloud-Based deployments handle the majority of new customer throughput; Edge Computing is expanding most quickly among manufacturers with automated material handling requirements.
Solution Type:
Precision specifications and infrastructure density requirements divide the market across indoor, outdoor, and hybrid positioning challenges.
- GPS Tracking:Satellite-dependent systems achieve 3-10 meter accuracy for construction equipment fleets and long-haul trucking across the United States and Australia. FCC narrowband IoT allocations constrain hardware design choices and service coverage maps for cellular-backhaul devices.
- RFID Tracking:Passive and active radio-frequency identification commands premium pricing in pharmaceutical and aerospace verticals where FDA and EMA lot-level traceability mandates require serialized item-level documentation. Tag costs have compressed to pennies for passive UHF implementations.
- Real-Time Location System:Ultra-wideband and Bluetooth AoA configurations deliver 10-30 centimeter precision for robotic picking coordination in Amazon and DHL fulfillment networks.
- Barcode Tracking:Linear and 2D optical scanning persists in low-velocity inventory environments where infrastructure investment must minimize capital outlay.
- Wi-Fi Tracking:Received signal strength triangulation retains installed-base relevance in facilities with dense access point deployments predating UWB availability.
GPS Tracking retains the largest installed base; Real-Time Location System is climbing the fastest on share as warehouse robotics deployments accelerate.
Application:
Operational tempo and asset mobility determine sensor durability, refresh rate requirements, and integration complexity.
- Logistics:Cross-modal shipment visibility platforms coordinate handoffs between ocean, rail, and road carriers with chain-of-custody documentation for customs authorities.
- Manufacturing:Work-in-process tracking integrates with MES and ERP systems to eliminate phantom inventory and reduce equipment idle time across multi-site production networks.
- Warehousing:Automated storage and retrieval systems demand deterministic positioning pipelines with millisecond-grade latency for robotic coordination.
- Construction:GPS-dense applications track equipment fleets across dispersed job sites with geofencing for theft prevention and utilization analytics for rental billing.
- Oilfield Services:Explosion-proof hardware and satellite backhaul serve remote drilling operations beyond cellular coverage in the Permian Basin and North Sea.
Logistics processes the highest transaction volume; Warehousing is gaining share fastest as e-commerce fulfillment networks expand.
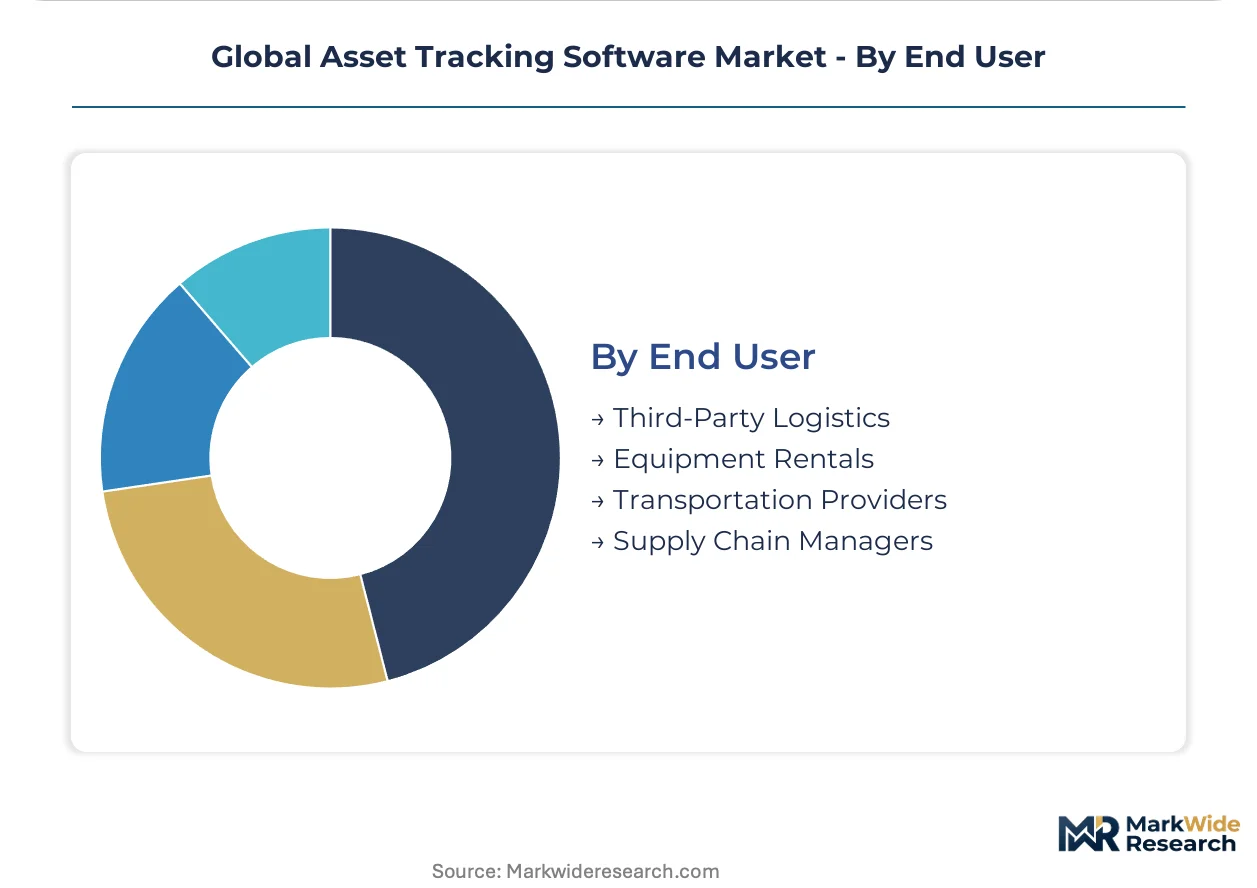
End User:
Buying center sophistication and integration requirements separate enterprise self-builders from outsourced visibility service consumers.
- Third-Party Logistics:3PLs unbundle visibility services from freight contracts and offer standalone tracking subscriptions to smaller shippers, concentrating buying power with software-native platforms in United States domestic trucking.
- Supply Chain Managers:Corporate logistics directors procure enterprise-grade platforms with API ecosystems for supplier onboarding and carbon-intensity analytics layered atop movement data to satisfy CSRD disclosure mandates.
- Transportation Providers:Fleet operators accelerate procurement of edge-deployed tracking platforms to satisfy EU AI Act compliance deadlines before enforcement phases activate.
- Equipment Rentals:Construction and agriculture lessors fuse vibration and temperature sensors with location data for unified condition-monitoring platforms and predictive maintenance revenue streams.
Third-Party Logistics captures the majority of subscription volume; Supply Chain Managers are the steepest expansion trajectory as CSRD mandates harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hardware assembly for tracking devices concentrates in Chinese lithium processing corridors, while software development and edge-computing integration cluster in German automotive logistics hubs and United States industrial digitization corridors.
United States
Fleet operators across the Permian Basin and Midwest manufacturing belts are accelerating edge-computing procurement for sub-second latency in automated warehouses. FCC narrowband IoT spectrum allocations constrain hardware design choices and force dual-SKU strategies for cross-border deployments. Amazon and DHL fulfillment networks in the Pacific Northwest and Southeast are deploying ultra-wideband anchors at scale for robotic picking coordination.
Germany
Automotive logistics providers in Stuttgart and Munich are segmenting data lakes between EU-resident edge nodes and stripped telemetry archives to satisfy GDPR and EU AI Act mandates. The KBA enforces algorithmic transparency obligations for high-risk fleet applications, pushing vendors toward explainable location inference models. Industrial digitization programs in Bavaria and North Rhine-Westphalia anchor the deepest demand for real-time visibility platforms in Europe.
Japan
METI industrial digitization incentives are driving warehouse robotics deployments in the Kanto and Kansai corridors that demand deterministic positioning pipelines. Pharmaceutical serialization mandates from the PMDA expand RFID tagging into active pharmaceutical ingredient shipments from Osaka and Nagoya production clusters. Construction equipment lessors in the Chubu region are fusing vibration sensors with location data for predictive maintenance revenue streams.
India
The PLI scheme for electronics manufacturing is attracting tracking hardware assembly capacity to serve underpenetrated mining and agriculture equipment markets in Maharashtra and Gujarat. CDSCO pharmaceutical traceability requirements are expanding lot-level RFID programs beyond finished goods. Mining operators in Karnataka and Telangana are piloting satellite-backhaul devices for equipment fleets beyond cellular coverage.
United Kingdom
Third-party logistics providers in London and the Midlands are unbundling visibility services from freight contracts to offer standalone tracking subscriptions to smaller shippers. The Information Commissioner's Office enforces GDPR data residency rules that reshape cross-border fleet data flows. Supply chain managers in the Southeast are procuring platforms with carbon-intensity analytics to satisfy emerging CSRD disclosure obligations.
Global Asset Tracking Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with ruggedized hardware-software integration specialists commanding premium positioning in warehouse environments while cloud-native platforms capture volume through minimal capital expenditure models. The vendor base organizes around three strategic archetypes: industrial automation conglomerates with building automation heritage, GPS-dense application specialists for construction and agriculture fleets, and software-native platforms unbundling visibility from freight contracts. Dominant competitive moves include strategic partnerships for edge-computing localization and portfolio diversification into predictive maintenance analytics.
Within the industrial automation tier, Zebra Technologies Corp. and Honeywell International Inc. exemplify hardware-software integration specialists, while Trimble Inc. occupies a position among GPS-dense application providers for equipment fleet management. These three entities anchor distinct competitive vectors without overlapping core positioning, reflecting the market's segmentation between indoor positioning precision, outdoor satellite-dependent tracking, and ruggedized warehouse automation systems.
| Leading Market Players |
|---|
| Zebra Technologies Corp. |
| Honeywell International Inc. |
| Trimble Inc. |
| AT&T Inc. |
| Samsara Inc. |
| Asset Panda |
| ASAP Systems |
| GigaTrak |
| Fleet Complete |
| Others |
Supply & Pricing Matrix
Ninety-day inventory cycles for cellular modem chipsets concentrate vendor exposure in Taiwanese foundry capacity, amplifying pricing power for 5G RedCap module suppliers while compressing margins for fleet-scale hardware deployers.
Pricing Analysis
The EU AI Act dictates the pricing tier structure across edge-computing configurations, with algorithmic transparency certification separating premium validated deployments from standard SaaS subscriptions. Three-tier pricing structure across premium, standard, and economy levels reflects latency specifications, with sub-second deterministic pipelines commanding substantial premiums over minute-grade cloud refresh rates. Cost compression in cellular-backhaul hardware intensifies because 5G RedCap modems carry significant premiums over LTE-M equivalents, squeezing margins on deployments exceeding ten thousand units. Third-party logistics providers exhibit highest price sensitivity due to thin brokerage economics, while pharmaceutical manufacturers with FDA serialization mandates demonstrate lowest sensitivity given lot-level traceability compliance requirements.
Supply Chain Analysis
Ninety-day inventory cycles for cellular modem chipsets expose hardware vendors to single-source vulnerability in Taiwanese semiconductor fabrication. Chinese-processed lithium cells, South Korean memory components, and German precision sensor modules anchor the bill-of-materials for ruggedized tracking devices. Supply chain risk centers on export restriction volatility for Chinese-processed lithium, with forced localization pressures threatening hardware cost structures. Distribution runs through direct enterprise sales for large fleet operators alongside value-added reseller networks serving mid-market logistics providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from the capital expenditure freeze cycle, with industrial digitization program restarts across German automotive corridors and United States Midwest manufacturing belts driving replacement demand for legacy tracking infrastructure.
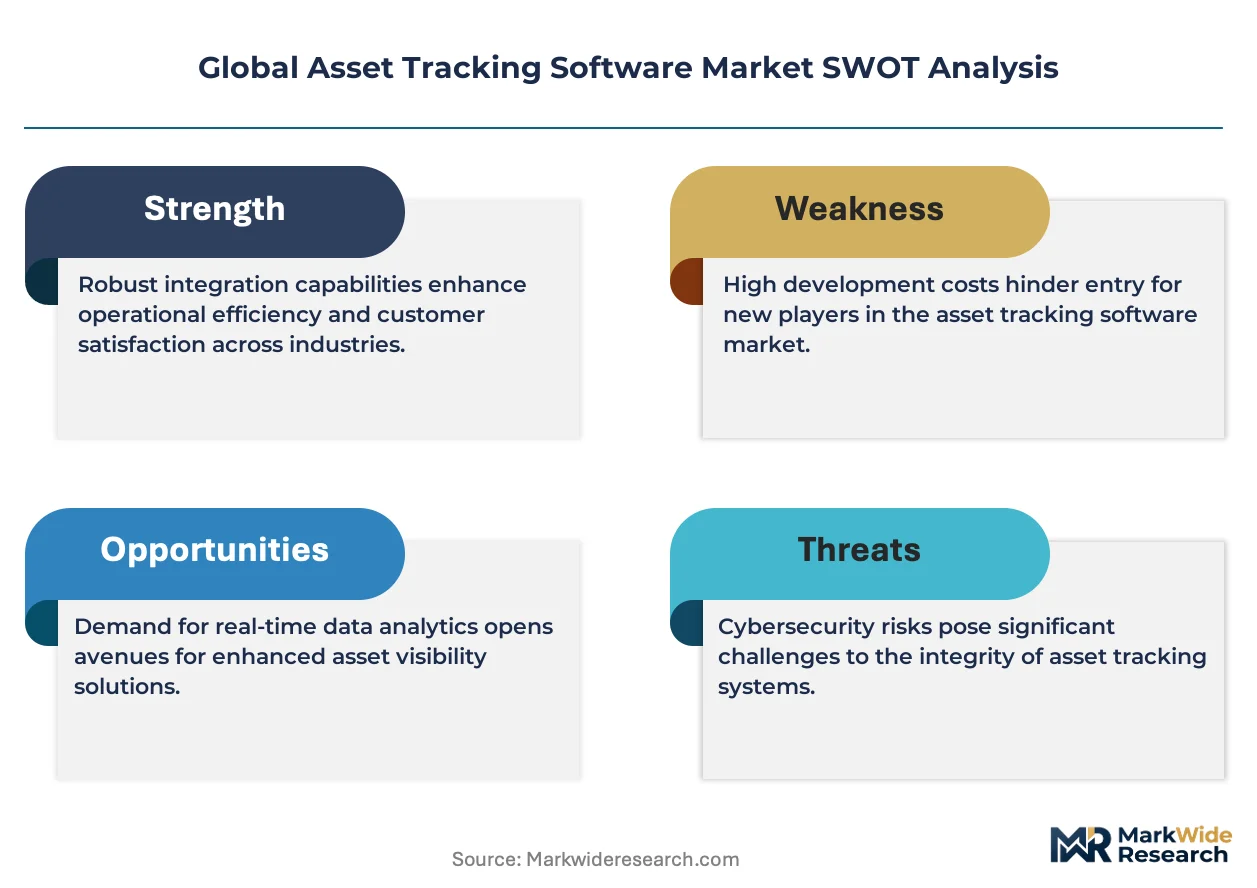
For Market Incumbents: Compound defensive positioning through backward integration into edge-computing hardware design to capture algorithmic transparency premiums mandated by the EU AI Act. Deepen certification investment in ISO 27001 and GDPR-compliant data architectures to extend cybersecurity audit backlogs into competitive moats against cloud-native challengers.
For New Entrants and Emerging Players: Anchor in India's underpenetrated mining and agriculture equipment markets where PLI scheme incentives are attracting assembly capacity and local demand lacks established vendor relationships. Target white-label visibility subscriptions for United States domestic trucking brokerages, offering stripped telemetry dashboards that displace carrier-integrated models without requiring freight contract bundling.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial automation conglomerates divesting non-core fleet visibility units amid portfolio rationalization pressures. Five-to-ten year viability favors vendors with deterministic edge-processing capabilities over pure-cloud architectures as latency specifications harden. Watch for inflection in warehouse robotics deployment velocity across Japanese Kanto and Kansai corridors as the signal for accelerated Real-Time Location System adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Localization Partnership | Establishes EU-resident data nodes satisfying GDPR and EU AI Act mandates for German automotive logistics providers. |
| Ultra-Wideband Anchor Scale Deployment | Achieves 10-30 centimeter precision for robotic picking coordination in Amazon and DHL fulfillment networks. |
| Predictive Maintenance Platform Integration | Fuses vibration sensors with location data for unified condition-monitoring revenue streams among construction equipment lessors. |
| RFID Serialization Program Expansion | Extends lot-level traceability from finished goods into active pharmaceutical ingredient shipments per FDA and EMA mandates. |
| White-Label Visibility Service Unbundling | Displaces traditional carrier-integrated models by offering standalone tracking subscriptions to United States owner-operator networks. |
Research Methodology
Cross-validation between primary interviews with fleet operations directors and secondary validation through FCC spectrum allocation filings anchors the qualitative findings in this study. Conversations with edge-computing systems architects, pharmaceutical supply chain managers, third-party logistics procurement leads, and warehouse robotics integration specialists combined with regulatory documentation from the EU AI Act, GDPR implementation guidance, and ISO 27001 certification timelines. Bottom-up triangulation across deployment architecture segments and top-down validation against industrial digitization program budgets shaped the analytical framework.
Sensitivity analysis across the projection horizon tests responsiveness to lithium battery supply volatility and cellular module cost structures. Segmentation dimensions modeled include deployment architecture, solution type precision specifications, application operational tempo, and end-user buying center sophistication. CAGRs derive from fitted growth curves calibrated against historical adoption patterns in warehouse automation and pharmaceutical serialization programs.
Material uncertainties — lithium export restriction volatility, cybersecurity certification audit backlogs, and spectrum licensing fragmentation — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and industrial capital expenditure recovery trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
ICT Investment in Government Market
Digital Solutions
Real Time Store Monitoring Platform Market
Digital Solutions
Global Personalization Engines Market
Digital Solutions
AI Powered Home Solution Market
Digital Solutions
Global Space Planning Software Market
Digital Solutions
Lecture Capture Systems Market
Digital Solutions
API Management Market
Digital Solutions
Construction Design App Market
Digital Solutions
IT Asset Management (ITAM) Software Market
Digital Solutions
Digital Business Support System Market
Digital Solutions
Global Digital Asset Management Software Market
Digital Solutions
Global Electronic Shift Operations Management Solutions (Esoms) Market
Digital Solutions
Electronic Document Management System (EDMS) Market
Digital Solutions
Data Converter Market
Digital Solutions
Europe Multichannel Order Management Market
Digital Solutions
Asia-Pacific Smart Government Market