
 Philippines E-Commerce Market | 2026-2036
Philippines E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines E-Commerce Market Outlook
Multi-source marketplace sourcing is pivoting as Philippine e-commerce platforms diversify merchant onboarding to reduce dependency on single-origin inventory. Shopee Philippines leverages its integrated logistics arm to control last-mile delivery costs across the archipelago. Lazada Philippines anchors its competitive stance through warehouse automation investments in Cavite and Bulacan. TikTok Shop Philippines differentiates via live-stream commerce formats that merge entertainment with instant checkout.
Philippines e-commerce constitutes digitally mediated retail transactions executed through web and mobile interfaces, encompassing product discovery, payment processing, order fulfillment, and post-sale service across the Philippine archipelago's fragmented geography. The sector relies on real-time inventory synchronization, multi-modal logistics coordination across 7,600+ islands, and localized payment gateways to serve a population where credit card penetration remains low but mobile internet usage ranks among Asia's highest. Fashion and electronics dominate transaction volumes within product categories, reflecting young demographic purchasing power and device upgrade cycles. E-wallets and cash-on-delivery split payment method preferences, with the former gaining ground in Metro Manila and the latter sustaining relevance in Visayas and Mindanao where banking access lags. B2C marketplace channels capture margin concentration through commission structures and advertising slots, while C2C platforms absorb long-tail seller volume with lighter fee models.
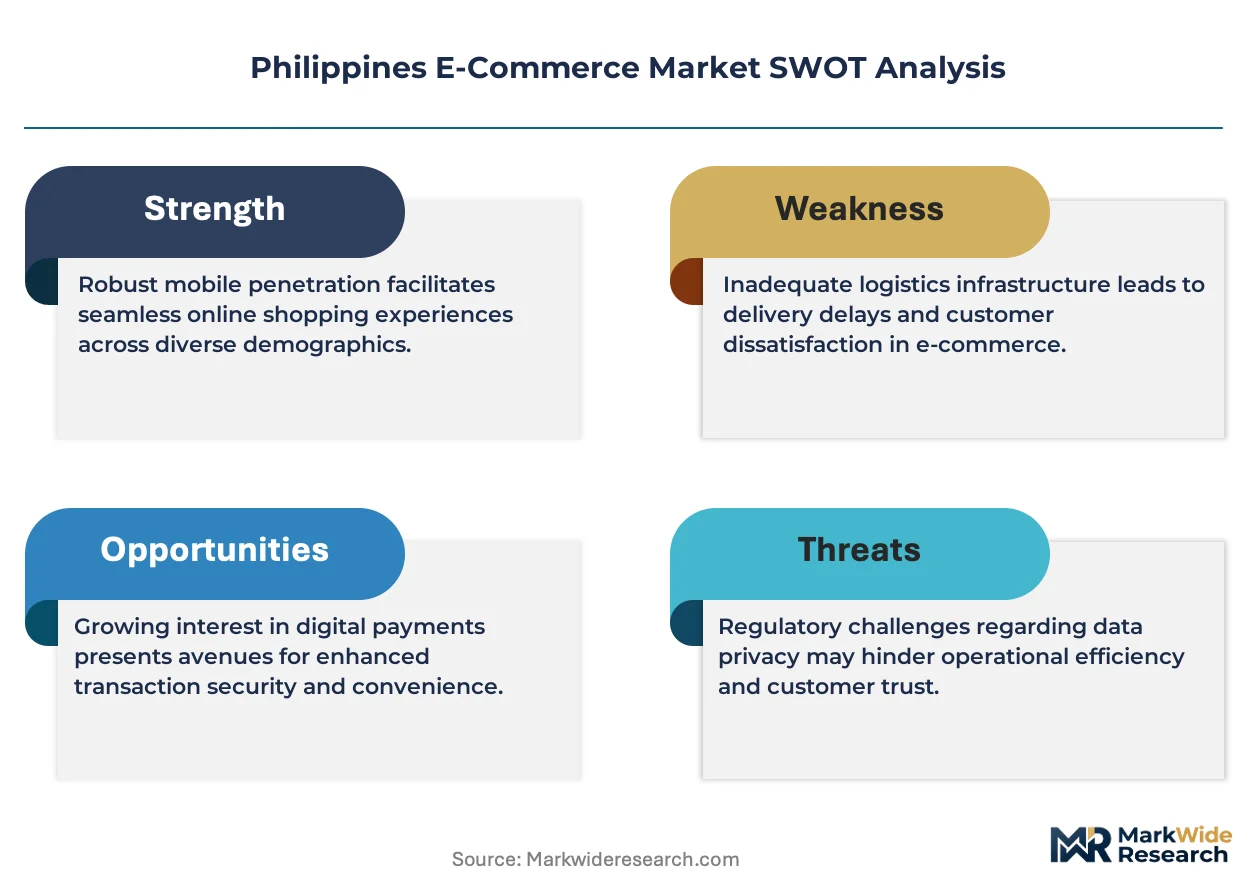
The Department of Trade and Industry enforces the Internet Transactions Act to standardize seller registration, consumer refund rights, and platform liability across Philippine e-commerce operations. The Bangko Sentral ng Pilipinas regulates e-wallet providers and digital payment aggregators under its National Payment Systems Act, mandating cybersecurity protocols and fund segregation that shape platform payment architecture. The National Privacy Commission enforces data localization and consent requirements that increase compliance costs for cross-border marketplace operators. Stakeholders must monitor how evolving digital services taxation and import duty enforcement on low-value parcels will reshape cross-border seller economics and domestic merchant competitiveness.
Market Dynamics
Mobile-first purchasing behavior among Filipino working professionals is compressing transaction cycles and forcing platform architecture toward instant checkout interfaces and embedded payment flows.
Growth Catalysts
- Internet Transactions Act:The Department of Trade and Industry mandates standardized seller registration and refund protocols, reducing consumer hesitation and expanding addressable buyer base.
- E-wallet penetration:Bangko Sentral ng Pilipinas cybersecurity mandates under the National Payment Systems Act accelerate digital payment trust in Metro Manila urban corridors.
- Visayas logistics gap:Cash-on-delivery persistence in island provinces sustains merchant relevance where banking infrastructure remains sparse.
Market Restraints
- Archipelagic fulfillment costs:Multi-modal coordination across 7,600 islands inflates last-mile expenditure relative to mainland Southeast Asian benchmarks.
- Credit card scarcity:Low plastic penetration forces platforms to maintain expensive cash-handling infrastructure and COD insurance reserves.
- Data localization mandates:National Privacy Commission consent requirements increase server infrastructure costs for cross-border marketplace operators.
Strategic Opportunities
- Mindanao expansion:Underpenetrated Davao and Cagayan de Oro corridors offer first-mover advantage as logistics networks extend southward.
- Live-stream commerce:Entertainment-integrated checkout formats merge content consumption with impulse purchasing among Gen Z demographics.
- Warehouse automation:Cavite and Bulacan industrial zones attract capital-intensive sorting and fulfillment robotics investments.
Industry Challenges
- Real-time inventory synchronization:Fragmented seller systems across C2C and B2C channels create stock-out disputes and rating volatility.
- Cross-border parcel taxation:Evolving digital services tax enforcement on low-value imports compresses margin for overseas merchant listings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines E-Commerce Market |
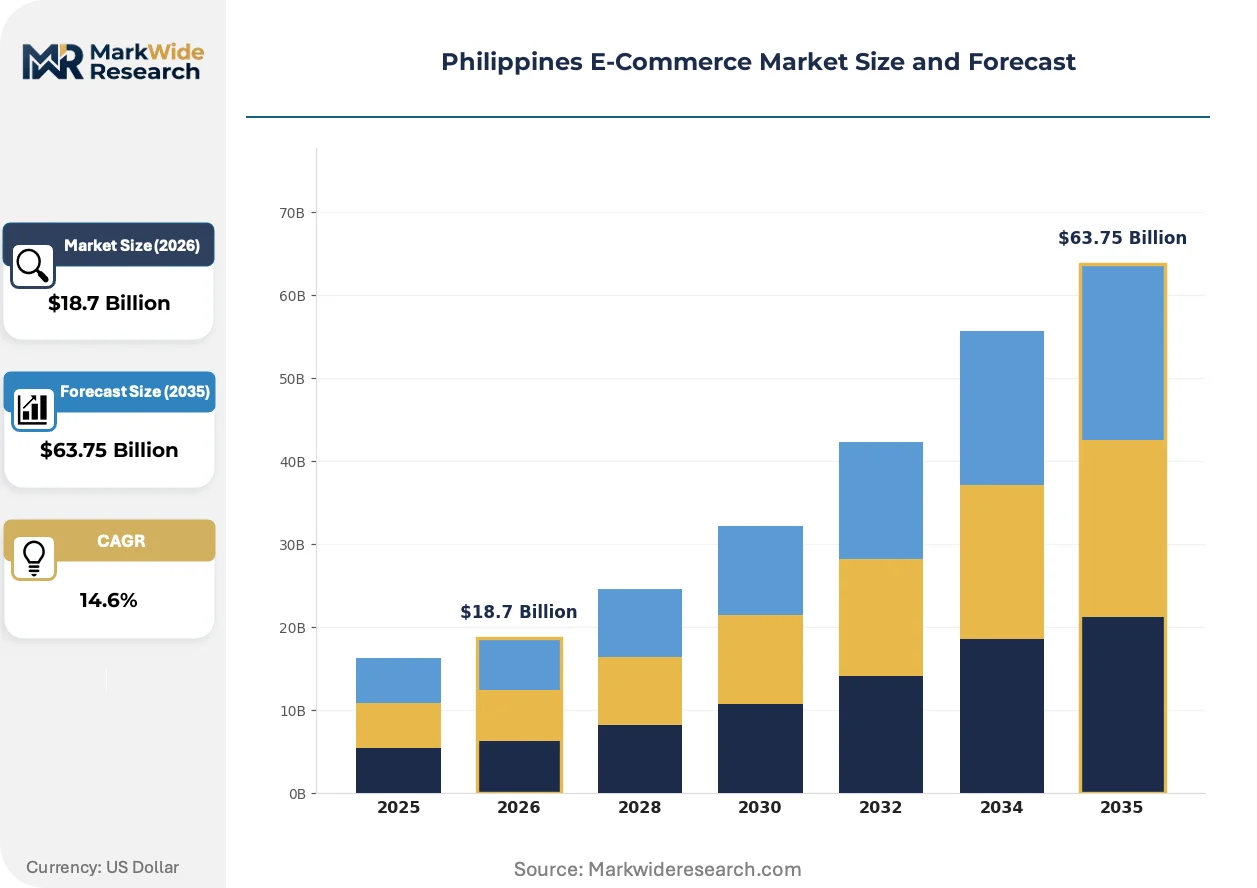
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $63.75 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Electronics, Fashion, Home Appliances, Beauty Products Sales Channel: B2C, C2C, Online Marketplace, Direct Sales Customer Type: Millennials, Gen Z, Working Professionals, Stay-at-home Parents Payment Method: Credit Card, E-wallets, Cash on Delivery, Online Bank Transfer |
| Companies Covered | Shopee Philippines, Lazada Philippines, TikTok Shop Philippines, Zalora Philippines, Carousell Philippines, Temu, Amazon Global Selling Philippines, BeautyMNL, Facebook Marketplace PH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines E-Commerce Market Strategic Shifts
Platform competition is fragmenting around fulfillment control, with integrated logistics arms replacing third-party delivery dependence as the primary differentiation mechanism.
Micro-fulfillment nodes positioned within Metro Manila barangays are modularizing same-day delivery economics. Shopee Philippines and Lazada Philippines deploy hyperlocal stock positioning to compress final-mile distance. This density strategy is modularizing cost structures that previously required centralized warehouse models.
Bangko Sentral ng Pilipinas fund segregation rules under the National Payment Systems Act reshape e-wallet architecture. Providers must segregate consumer balances from operational capital, tightening liquidity management. Fintech-merchant integration in Luzon urban centers accelerates as platforms seek compliant embedded finance partnerships.
Social commerce interfaces merge product discovery with entertainment consumption among Filipino mobile users. TikTok Shop Philippines anchors this shift through live-stream checkout formats that displace traditional search-based purchasing. Visayas and Mindanao younger demographics exhibit highest engagement velocity with influencer-mediated transactions.
Philippines E-Commerce Market Segmentation
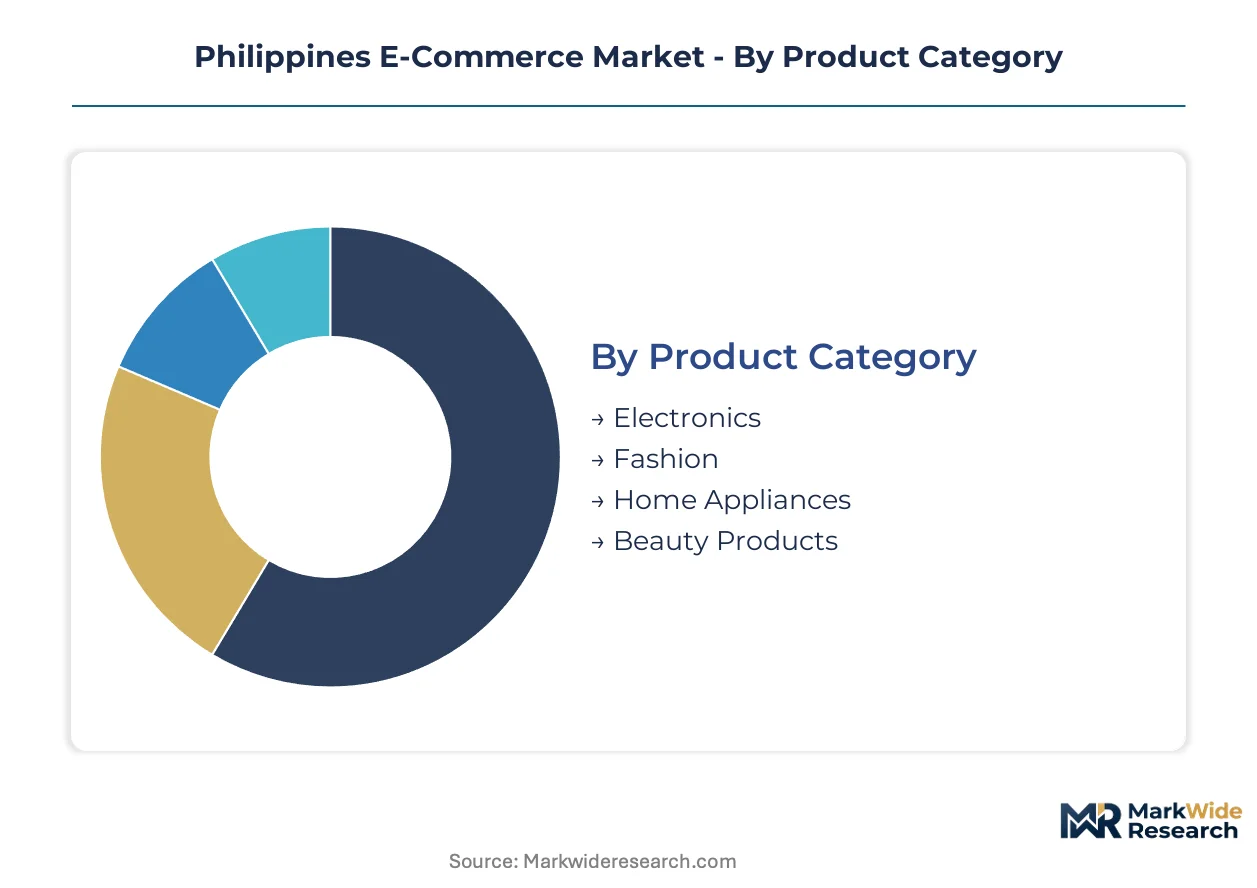
Philippine e-commerce segmentation reflects archipelagic logistics constraints, payment infrastructure gaps, and mobile-first demographics that reshape how platforms prioritize inventory, merchant onboarding, and checkout design across Luzon, Visayas, and Mindanao corridors.
Product Category:
Buyer willingness to absorb delivery delays and payment friction varies sharply by product type, with high-consideration purchases tolerating longer fulfillment windows than impulse categories.
- Electronics:Smartphone, laptop, and accessory transactions dominate average order values. Demand concentrates in Metro Manila and Cebu City where device upgrade cycles align with salary disbursement patterns and mall-based warranty service remains valued.
- Fashion:Apparel and footwear purchases exhibit highest return rates due to sizing mismatches. Volume clusters among Gen Z buyers in Greater Manila Area barangays with hyperlocal fulfillment nodes, though Mindanao expansion is accelerating as logistics networks extend southward.
- Home Appliances:Refrigerator, air conditioner, and small appliance sales spike during summer months and holiday bonus seasons. Buyers prioritize cash-on-delivery options for bulky items where in-person inspection reduces perceived risk.
- Beauty Products:Skincare and cosmetics transactions leverage influencer-mediated discovery on short-video platforms. Repeat purchase rates exceed other categories due to consumption replenishment cycles and sampling-driven trial.
Volume sits with Electronics; growth tilts toward Beauty Products.
Sales Channel:
Margin capture and merchant control differentiate channel economics, with platform-owned logistics arms reshaping competitive positioning between integrated and distributed fulfillment models.
- B2C:Brand-owned storefronts and flagship operations on marketplace platforms. Concentrates in Metro Manila corridors where warehouse automation investments in Cavite and Bulacan compress delivery windows for electronics and appliance categories.
- C2C:Individual seller listings with lighter fee structures and minimal inventory guarantees. Sustains relevance in Visayas and Mindanao where micro-entrepreneurs leverage social commerce interfaces for household goods and regional handicrafts.
- Online Marketplace:Multi-merchant aggregation with commission-based revenue and advertising slot monetization. The Department of Trade and Industry's Internet Transactions Act mandates seller registration standards that filter long-tail merchant quality.
- Direct Sales:Manufacturer-to-consumer bypass of platform intermediaries. Expanding most quickly among electronics brands seeking customer data ownership and margin recovery from marketplace commission structures.
Transaction volume concentrates in Online Marketplace; merchant migration favors Direct Sales.
Customer Type:
Digital payment readiness and delivery expectation thresholds segment addressable buyers, with mobile internet behavior patterns dictating platform interface investments.
- Millennials:Salary-earning demographic with established e-wallet adoption and subscription commerce tolerance. Dominates electronics and home appliance categories in Luzon urban centers where Bangko Sentral ng Pilipinas cybersecurity mandates accelerate digital payment trust.
- Gen Z:Entertainment-integrated commerce participants with highest engagement velocity on live-stream checkout formats. TikTok Shop Philippines anchors this segment through influencer-mediated transactions that merge content consumption with impulse purchasing.
- Working Professionals:Mobile-first purchasing behavior compresses transaction cycles and forces platform architecture toward instant checkout interfaces. Concentrates in Metro Manila and Cebu City corridors with same-day delivery network access.
- Stay-at-home Parents:Household procurement coordinators with high price sensitivity and bulk purchase orientation. Cash-on-delivery preference sustains relevance in Mindanao where banking infrastructure remains sparse.
Working Professionals anchor current volume; Gen Z exhibits the steepest expansion trajectory.
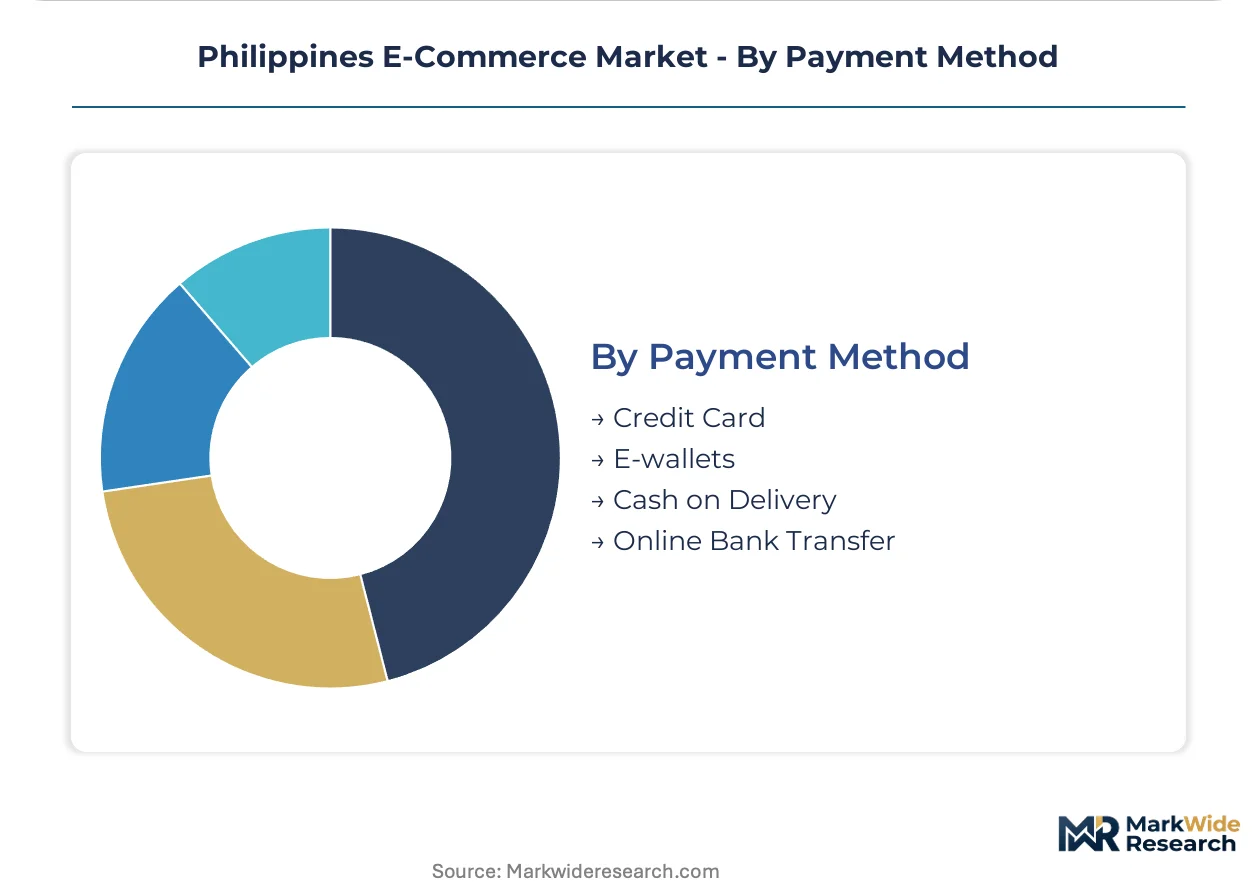
Payment Method:
Platform infrastructure costs and fraud exposure vary by payment rail, with regulatory mandates reshaping provider architecture and merchant integration requirements.
- Credit Card:Lowest-friction checkout with highest fraud chargeback exposure. Limited penetration outside Metro Manila due to plastic scarcity and income documentation barriers that constrain bank underwriting.
- E-wallets:GCash and Maya dominate through embedded finance partnerships and merchant incentive programs. Bangko Sentral ng Pilipinas fund segregation rules under the National Payment Systems Act tighten liquidity management for providers.
- Cash on Delivery:Persistent preference in Visayas and Mindanao where banking access lags. Forces platforms to maintain expensive cash-handling infrastructure and COD insurance reserves that inflate operational expenditure.
- Online Bank Transfer:Real-time payment rails gaining share through interoperable QR standards. Merchant adoption accelerates as settlement velocity improves and transaction fees undercut card network interchange.
E-wallets command transaction volume; Online Bank Transfer is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metro Manila's fiber-optic backbone and warehouse automation clusters anchor Philippine e-commerce infrastructure, while archipelagic logistics networks extend southward through Cebu and Davao corridors.
Metro Manila
Working professionals drive transaction volume through mobile-first purchasing habits and same-day delivery expectations. The Department of Trade and Industry's Internet Transactions Act mandates seller registration standards that filter merchant quality on platforms operating within the National Capital Region. Cavite and Bulacan industrial zones attract automated sorting investments from marketplace operators seeking to compress fulfillment windows.
Central Luzon
Provincial wage earners exhibit rising e-wallet adoption as Bangko Sentral ng Pilipinas cybersecurity protocols extend beyond urban cores. The National Privacy Commission's data localization requirements increase server infrastructure costs for cross-border marketplace operators serving Pampanga and Bulacan residents. Clark Freeport Zone logistics hubs function as alternative fulfillment nodes reducing Metro Manila congestion.
Visayas
Cash-on-delivery persistence sustains merchant relevance across Cebu, Iloilo, and Bacolod where banking infrastructure remains sparse. The Bangko Sentral ng Pilipinas regulates e-wallet providers under its National Payment Systems Act, mandating fund segregation that shapes platform payment architecture for island provinces. Cebu City concentrates demand through its dense logistics infrastructure serving as the central archipelagic distribution node.
Mindanao
Underpenetrated Davao and Cagayan de Oro corridors offer first-mover advantage as logistics networks extend southward. Stay-at-home parents in Mindanao maintain high cash-on-delivery preference, forcing platforms to maintain expensive cash-handling infrastructure. Davao City's emerging warehouse clusters attract capital positioning for southern Philippines e-commerce expansion.
Southern Tagalog
Calabarzon manufacturing zones supply electronics and fashion inventory feeding marketplace platforms nationwide. The Department of Trade and Industry enforces consumer refund rights that reduce buyer hesitation in Batangas and Laguna corridors. Lipa City and Santa Rosa industrial parks host micro-fulfillment nodes modularizing same-day delivery economics for southern Luzon.
Philippines E-Commerce Market Competitive Environment
Integrated logistics investments dominate the current landscape as marketplace operators replace third-party delivery dependence with captive fulfillment arms. The vendor base concentrates around three platform archetypes: integrated logistics-heavy operators, social commerce specialists, and cross-border direct-shipping entrants. Strategic differentiation pivots on warehouse automation density and payment ecosystem control. Competitive moves center on hyperlocal fulfillment node deployment and embedded finance partnerships with regulated e-wallet providers.
Within the integrated logistics tier, Shopee Philippines and Lazada Philippines occupy positions defined by captive supply chain control across the archipelago. TikTok Shop Philippines exemplifies the social commerce archetype, anchoring its stance through entertainment-integrated checkout formats. These three operators collectively represent the strategic spectrum spanning fulfillment infrastructure ownership, content-commerce merger, and regulatory compliance architecture under Bangko Sentral ng Pilipinas and Department of Trade and Industry oversight.
| Leading Market Players |
|---|
| Shopee Philippines |
| Lazada Philippines |
| TikTok Shop Philippines |
| Zalora Philippines |
| Carousell Philippines |
| Temu |
| Amazon Global Selling Philippines |
| BeautyMNL |
| Facebook Marketplace PH |
| Others |
Value Chain & Pricing Dynamics
Captive logistics integration by Shopee Philippines and Lazada Philippines anchors both supply position and pricing power across the archipelago. Their in-house delivery arms compress last-mile costs that third-party operators cannot match, creating margin buffers against COD insurance reserves and cash-handling infrastructure.
Pricing Analysis
Warranty and return policy bundling separates premium marketplace tiers from economy C2C listings. Three-tier pricing structure across premium, standard, and economy levels reflects fulfillment speed guarantees and seller verification depth. Price differentiation hinges on delivery window commitments and Bangko Sentral ng Pilipinas fund segregation compliance. Cost compression in the economy tier intensifies as cross-border direct-shipping entrants undercut domestic merchant margins. Stay-at-home parents in Mindanao exhibit highest price sensitivity, while working professionals in Metro Manila absorb premiums for same-day reliability.
Supply Chain Analysis
Reverse logistics flows for fashion and electronics returns strain warehouse automation investments in Cavite and Bulacan. Inventory sourcing concentrates in China, South Korea, and Vietnam for electronics and fashion categories. Component dependencies span semiconductor chips, lithium-ion cells, and synthetic textiles. Single-source vulnerability runs through Shenzhen-based electronics consolidation hubs. Distribution runs through hyperlocal micro-fulfillment nodes positioned within Metro Manila barangays for final-mile compression.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Philippines e-commerce sector sits in a payment-rail transition phase as e-wallets displace cash-on-delivery dominance. Embedded finance partnerships with regulated providers are replacing legacy COD infrastructure.
For Market Incumbents: Hedge against TikTok Shop Philippines live-stream commerce encroachment by accelerating influencer network exclusivity deals. Secure warehouse automation density in Davao before logistics networks mature. The threat of entertainment-integrated checkout formats demands defensive content-commerce investments. Vertical integration into captive delivery arms remains the priority lever for margin defense.
For New Entrants and Emerging Players: Stay-at-home parents in Mindanao represent the most penetrable buyer archetype given persistent COD preference and sparse banking access. White-space targets include Cagayan de Oro corridor micro-fulfillment and Visayas cash-handling infrastructure partnerships. A go-to-market angle anchored on TikTok Shop Philippines seller enablement tools bypasses direct platform competition.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated logistics-heavy operators seeking regional density. Long-term viability across the analysis window favors platforms with Bangko Sentral ng Pilipinas e-wallet partnerships and Department of Trade and Industry compliance architecture. Acquisition target archetypes include warehouse automation specialists and social commerce enablers. Practitioners should monitor cross-border parcel taxation enforcement for margin compression signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Warehouse Automation Investment | Cavite and Bulacan robotics deployments compress fulfillment windows for electronics categories. |
| E-wallet Embedded Finance Partnership | GCash and Maya integrations accelerate digital payment trust under Bangko Sentral ng Pilipinas mandates. |
| Live-stream Commerce Platform Launch | TikTok Shop Philippines formats merge entertainment with impulse checkout for Gen Z demographics. |
| Mindanao Logistics Network Extension | Davao warehouse clusters capture first-mover advantage in underpenetrated southern corridors. |
| Seller Verification Compliance Program | Internet Transactions Act registration standards filter merchant quality and reduce consumer disputes. |
Study Parameters
Independent corroboration across marketplace operations executives, logistics infrastructure planners, and e-wallet product managers underwrites the qualitative findings. Primary fieldwork with Department of Trade and Industry officials and Bangko Sentral ng Pilipinas payment specialists supplemented merchant interviews across Luzon, Visayas, and Mindanao. Secondary validation drew from customs trade records, National Privacy Commission filings, and platform commission structure disclosures. Bottom-up transaction volume estimates triangulated against top-down GDP digital commerce contribution benchmarks.
Rate-of-change decomposition across the modeling period isolates mobile internet penetration, e-wallet adoption velocity, and logistics network extension as demand drivers. Segmentation dimensions span product category, sales channel, customer type, and payment method alongside archipelagic logistics corridor clustering. CAGRs derive from logistic diffusion curves fitted to smartphone penetration and salary disbursement timing patterns. Forecast inputs include Bangko Sentral ng Pilipinas real-time payment rail expansion timelines and Cavite-Bulacan industrial zone capacity pipelines.
Revisions become necessary when cross-border parcel taxation enforcement intensifies or National Privacy Commission data localization mandates expand scope. Forecasts reflect assumptions around Internet Transactions Act implementation consistency and e-wallet fund segregation compliance adherence. Practitioners should monitor Mindanao logistics infrastructure capex commitments and TikTok Shop Philippines seller acquisition rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
India E-Commerce Warehousing Market
E-Commerce Solutions
Vietnam E-Commerce Market
E-Commerce Solutions
Clothing E-Commerce Platform Market
E-Commerce Solutions
Quick Commerce Market
E-Commerce Solutions
China Ecommerce Logistics Market
E-Commerce Solutions
Argentina Alcohol E-Commerce Market
E-Commerce Solutions
Indonesia E-Commerce Market
E-Commerce Solutions
India D2C E-Commerce Market
E-Commerce Solutions
North America E-Commerce Watch Market
E-Commerce Solutions
E-Commerce Technology Market
E-Commerce Solutions
Portugal E-Commerce Market
E-Commerce Solutions
New Zealand E-Commerce Market
E-Commerce Solutions
Croatia E-Commerce Market
E-Commerce Solutions
United Arab Emirates E-Commerce Market
E-Commerce Solutions
Cyprus E-Commerce Market
E-Commerce Solutions
Saudi Arabia E-Commerce Logistics Market