
 Netherlands E-Commerce Market | 2026-2036
Netherlands E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands E-Commerce Market Outlook
Premium fulfillment tier upgrades is unwinding across Dutch e-commerce as same-day and next-day delivery become baseline expectations rather than luxuries. Bol.com leverages its marketplace density to sustain fulfillment network efficiency across the Benelux region. Coolblue N.V. anchors its competitive position through proprietary logistics infrastructure and category-specialized customer service. Albert Heijn B.V. dominates online grocery penetration with integrated store-pick and dark-store operations.
The Netherlands e-commerce sector encompasses digitally mediated retail transactions spanning consumer goods, services, and B2B procurement, supported by payment orchestration platforms, warehouse management systems, and last-mile distribution networks operating at 99.5% address coverage. Electronics and home goods command substantial transaction volume within product category segmentation, reflecting Dutch household investment cycles and housing market dynamics. B2B client segments within customer type classification exhibit accelerating platform migration as procurement digitization replaces legacy purchase order systems. Same-day delivery and click-and-collect models within delivery model segmentation capture disproportionate growth velocity as urban density enables unit-economic viability.
The Netherlands Authority for Consumers and Markets (ACM) enforces platform transparency rules under EU Digital Services Act implementation, while Dutch environmental regulations mandate emission reductions from delivery fleets operating within municipal low-emission zones. Stakeholders must monitor evolving ACM enforcement patterns and municipal logistics restrictions to anticipate compliance cost trajectories and infrastructure investment requirements.
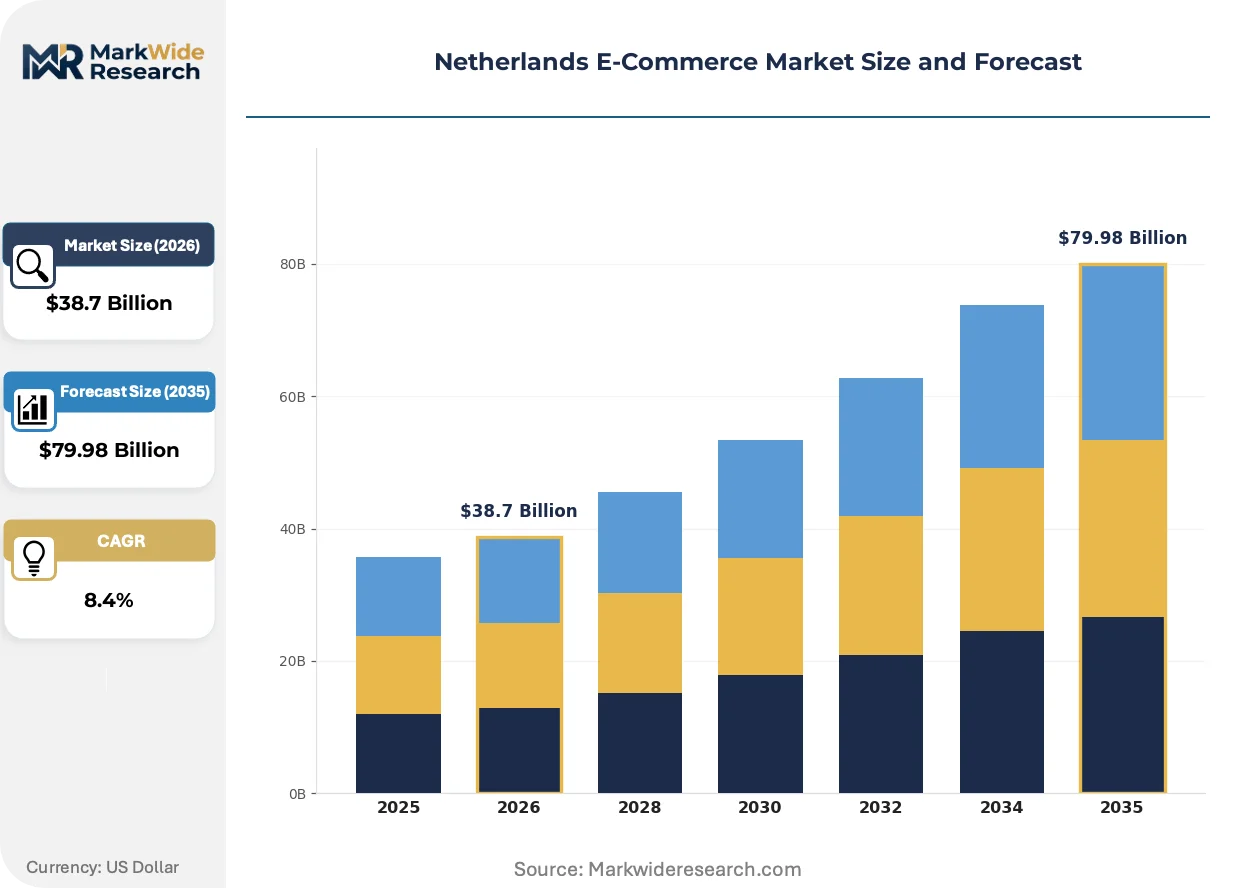
Market Dynamics
Same-day delivery infrastructure investments by Dutch grocery and general merchandise retailers are compressing fulfillment timelines and forcing capital reallocation toward urban micro-fulfillment nodes. The EU Digital Services Act implementation through the Netherlands Authority for Consumers and Markets is imposing new transparency obligations on marketplace operators.
Growth Catalysts
- EU Digital Services Act:Platform transparency mandates under ACM enforcement are standardizing disclosure requirements that reduce consumer friction and build transaction trust across Dutch marketplaces.
- Randstad urban density:Metropolitan concentration across Amsterdam, Rotterdam, The Hague, and Utrecht enables unit-economic viability for rapid delivery models that would fail in dispersed geographies.
- Dark-store fulfillment:Dedicated urban micro-fulfillment centers are collapsing last-mile distances and supporting sub-two-hour delivery windows for grocery and convenience categories.
Market Restraints
- Municipal low-emission zones:Dutch city councils in Amsterdam, Rotterdam, and Utrecht are restricting diesel delivery vehicle access, forcing fleet electrification investments that compress operating margins.
- Warehouse labor scarcity:E-commerce fulfillment centers in the Netherlands face persistent shortages of order-picking and sortation workers, constraining volume throughput capacity during peak demand periods.
- Last-mile cost absorption:Consumer expectation of free rapid delivery prevents full cost recovery of same-day and next-day fulfillment operations, pressuring unit economics.
Strategic Opportunities
- Cross-border Benelux integration:Belgian and Luxembourg consumer markets remain underpenetrated by Dutch e-commerce platforms, offering geographic expansion pathways with shared logistics infrastructure.
- B2B procurement digitization:Dutch industrial and wholesale buyers are migrating from legacy purchase order systems to platform-based procurement, opening enterprise customer segments with higher order values and lower return rates.
- Packaging waste reduction mandates:Dutch environmental regulations are accelerating demand for reusable packaging and consolidated delivery models that reduce per-shipment environmental impact.
Industry Challenges
- Warehouse management system integration:Dutch retailers operating hybrid store-pick and dark-store models face technical complexity synchronizing inventory visibility across multiple fulfillment nodes.
- Route optimization algorithm deployment:Real-time dynamic routing for same-day delivery requires specialized data science talent that remains scarce in the Dutch logistics labor market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands E-Commerce Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Apparel, Electronics, Home Goods, Beauty Payment Method: Credit Card, PayPal, Bank Transfer, Cash on Delivery Customer Type: Retail Consumers, B2B Clients, Subscription Services, Wholesalers Delivery Model: Standard Shipping, Same-Day Delivery, Click & Collect, International Shipping |
| Companies Covered | Bol.com, Albert Heijn B.V., Coolblue N.V., Zalando SE, Amazon.com, Inc., Jumbo Supermarkten B.V., Wehkamp B.V., Picnic B.V., De Bijenkorf B.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands E-Commerce Market Strategic Shifts
Artificial intelligence applications are reshaping Dutch e-commerce operations across demand forecasting, dynamic pricing, and customer service automation. Three distinct developments are restructuring competitive capabilities in the sector.
Machine learning demand forecasting is bifurcating inventory positioning strategies between high-velocity urban SKUs pre-positioned in micro-fulfillment nodes and longer-tail items retained in regional distribution centers. Dutch grocery retailers including Albert Heijn are deploying these systems to reduce stockouts in perishable categories while minimizing waste. The technology is compressing working capital requirements for rapid-delivery operations while increasing inventory carrying costs for non-urban distribution.
ACM enforcement of EU Digital Services Act transparency rules is mandating algorithmic disclosure and complaint-handling protocols for marketplace operators serving Dutch consumers. This regulatory pressure is increasing compliance costs for cross-border platforms while creating competitive advantage for domestic operators with established Dutch-language customer service infrastructure. Electronics and home goods marketplaces face particular scrutiny given high transaction volumes and elevated consumer complaint rates.
Subscription-based delivery memberships are displacing per-order shipping fees as the dominant consumer lock-in mechanism among Dutch e-commerce platforms. This model shift is concentrating purchase volume with platforms offering bundled rapid delivery and streaming content services. The Randstad metropolitan corridor shows highest adoption rates, where urban density supports consistent same-day fulfillment execution that justifies recurring membership expenditure.
Netherlands E-Commerce Market Segmentation
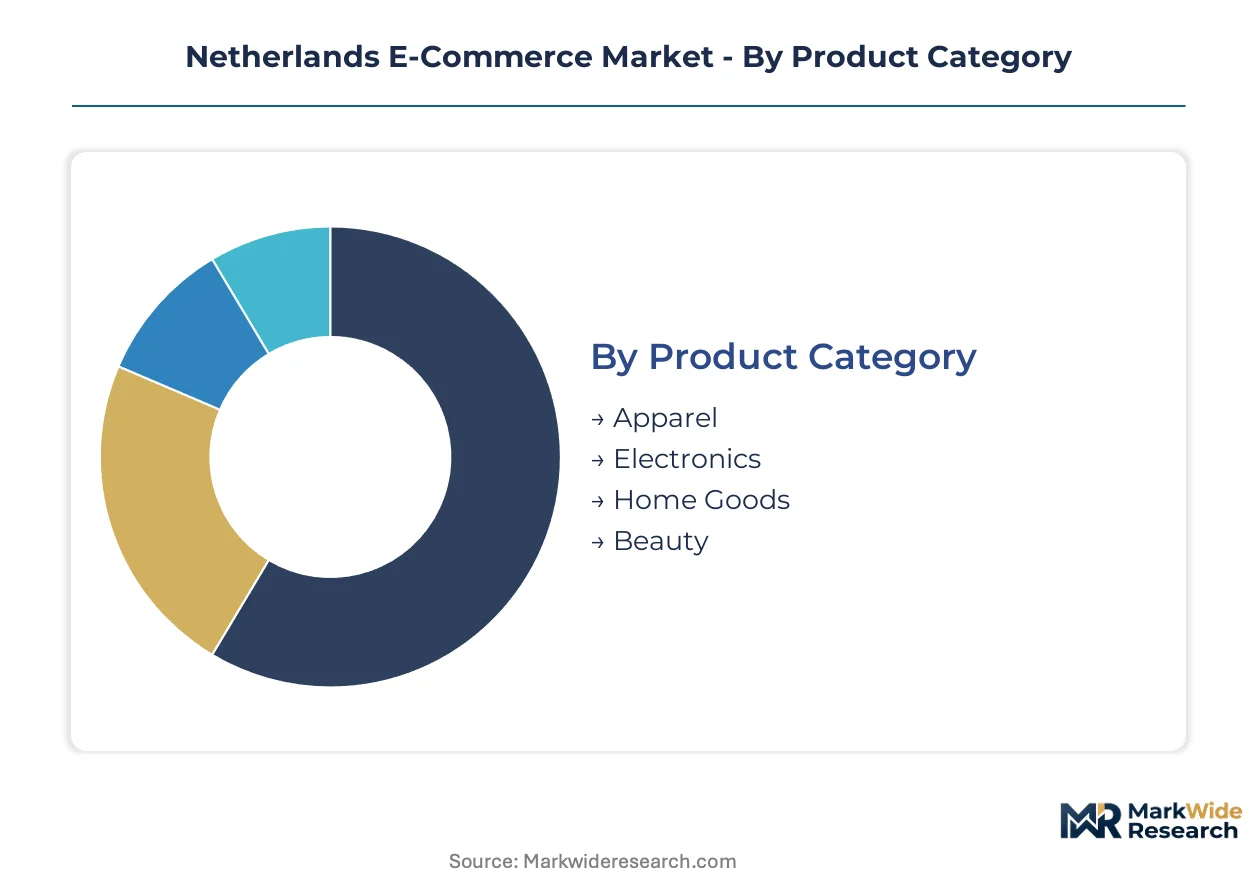
Segmentation reveals how Dutch e-commerce demand fragments across fulfillment expectations, procurement behaviors, and payment infrastructure. Each dimension carries distinct margin profiles and capital requirements that reshape platform strategy across the Randstad corridor and beyond.
Product Category:
Domestic consumption concentrates in home goods and electronics, while apparel and beauty segments show stronger cross-border export orientation toward Belgian and German consumers.
- Electronics:High-consideration purchases involving warranty complexity and return sensitivity. Demand clusters in Amsterdam and Rotterdam metropolitan zones where tech-savvy households upgrade devices frequently and expect integrated installation services.
- Home Goods:Bulky fulfillment requirements drive store-pick and scheduled delivery preferences. The Hague and Utrecht submarkets exhibit elevated activity tied to housing turnover cycles and renovation investment waves.
- Apparel:Return rates exceed other categories, compressing net margins for pure-play fashion platforms. Cross-border shipments to Belgium leverage shared Dutch-language customer service infrastructure.
- Beauty:Subscription bundling and sample-based discovery models predominate. Regulatory compliance with EU cosmetic safety regulations through ECHA frameworks adds platform verification costs.
Home goods commands the established base. The steepest expansion runs through electronics.
Payment Method:
Cost tier stratification separates premium friction-reduced methods from economy options with higher operational overhead.
- Bank Transfer:Domestic Dutch preference anchored in iDEAL infrastructure penetration. Amsterdam and Rotterdam merchants report lowest transaction abandonment where this method dominates checkout flows.
- Credit Card:International visitor and cross-border purchase standard. Higher interchange fees pressure platform margins on electronics transactions above threshold values.
- PayPal:Buyer protection features attract risk-averse consumers in beauty and apparel categories. Dispute resolution overhead creates operational complexity for marketplace operators.
- Cash on Delivery:Limited to specific demographic segments and rural delivery zones outside Randstad density. Collection failure rates and cash handling costs restrict scalability.
Bank transfer anchors domestic volume. Credit card methods are climbing the fastest for cross-border expansion.
Customer Type:
Volume concentration differs sharply between high-frequency low-margin retail and low-frequency high-value B2B procurement.
- Retail Consumers:Individual purchasers driving marketplace liquidity through repeat transaction density. Randstad urban corridors generate disproportionate order frequency for same-day fulfillment economics.
- B2B Clients:Enterprise procurement migrating from legacy purchase order systems to platform-based purchasing. Higher average order values and minimal return rates attract specialized platform development.
- Subscription Services:Recurring revenue models locking in predictable demand for consumables and replenishment categories. Grocery and beauty verticals show highest attachment rates.
- Wholesalers:Bulk purchasing entities requiring negotiated pricing tiers and consolidated shipment scheduling. Integration with warehouse management systems demands API sophistication.
Retail consumers command the established base. The steepest expansion trajectory runs through B2B clients.
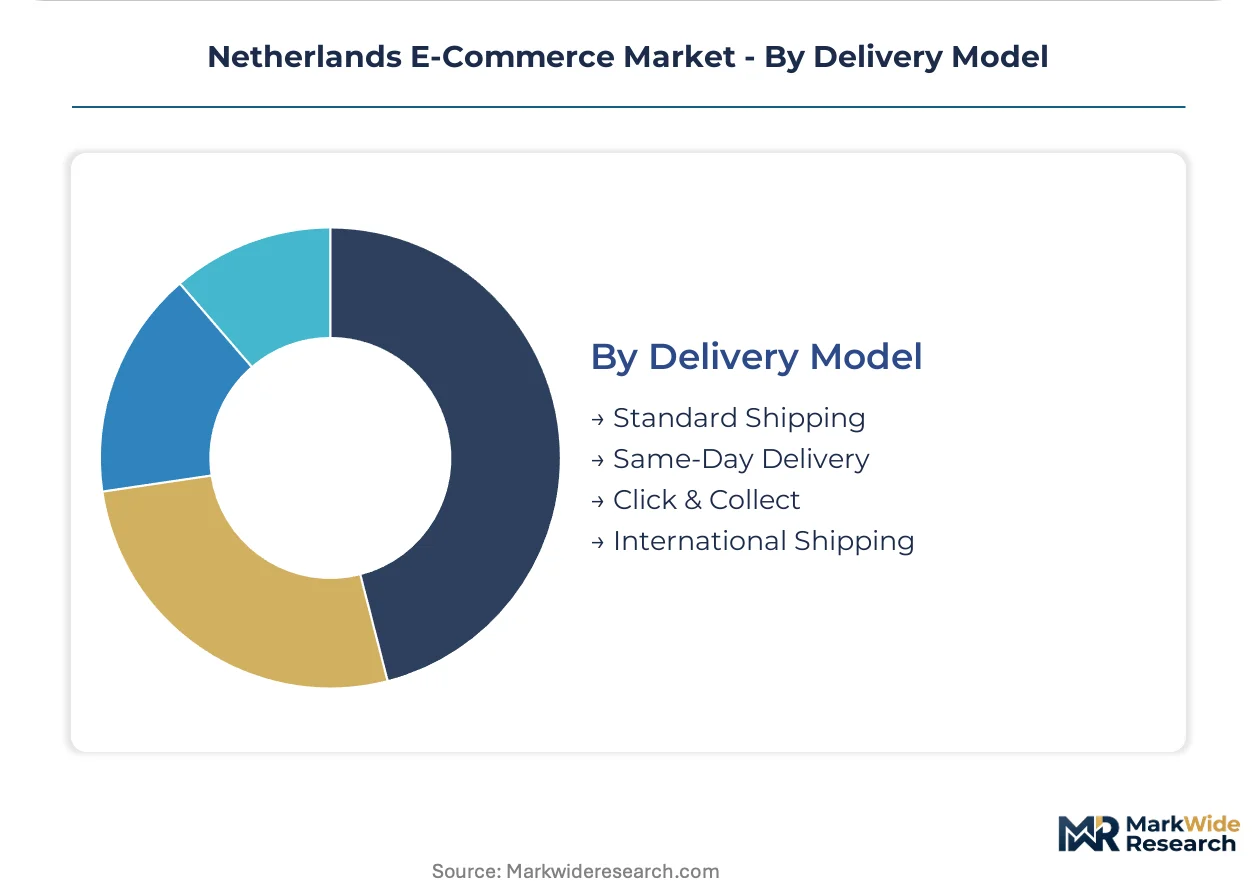
Delivery Model:
Supply concentration in urban micro-fulfillment nodes favors same-day and click-and-collect, while standard shipping retains rural coverage obligations.
- Same-Day Delivery:Urban micro-fulfillment infrastructure collapsing last-mile distances to sub-two-hour windows. Amsterdam, Rotterdam, The Hague, and Utrecht municipal low-emission zones force fleet electrification investments.
- Click & Collect:Store-based pickup reducing last-mile cost absorption while driving incremental foot traffic. Albert Heijn and other grocery anchors leverage existing retail footprint density.
- Standard Shipping:Regional distribution center fulfillment covering non-urban addresses at lower cost per shipment. Sustains viability for longer-tail product categories outside rapid-delivery economics.
- International Shipping:Cross-border fulfillment to Belgium, Germany, and Luxembourg exploiting shared logistics corridors. Customs complexity and VAT registration requirements favor established platforms with compliance infrastructure.
Standard shipping commands the established base. Same-day delivery is gaining share fastest as urban infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
E-commerce fulfillment infrastructure concentrates disproportionately in the Randstad metropolitan corridor, where urban density enables unit-economic viability for rapid delivery models that would fail in dispersed geographies across the country.
Randstad Metropolitan Corridor
Amsterdam, Rotterdam, The Hague, and Utrecht generate the majority of Dutch online transaction volume through concentrated household purchasing power and premium delivery expectations. Municipal low-emission zones in Amsterdam and Rotterdam restrict diesel vehicle access, forcing fleet electrification investments. Dark-store fulfillment nodes in Amsterdam's A10 ring and Rotterdam's port district support sub-two-hour grocery delivery windows.
North Brabant and Eindhoven Region
Tech-savvy consumers and high device turnover rates drive electronics e-commerce penetration above national averages. The Netherlands Authority for Consumers and Markets enforces EU Digital Services Act transparency rules uniformly across this manufacturing-heavy province. Eindhoven's Brainport technology cluster sustains above-average demand for consumer electronics through integrated installation and support services.
Northern Netherlands
Rural address dispersion elevates standard shipping cost absorption challenges and compresses same-day delivery feasibility. National sustainability mandates from the Dutch Environmental Management Act apply emission reduction targets to delivery fleets operating in Groningen and Friesland. Retail consolidation in Leeuwarden and Groningen city centers supports click-and-collect adoption as a last-mile cost mitigation strategy.
Zeeland and Limburg
Cross-border proximity to Belgian and German markets creates unique fulfillment complexity around VAT registration and customs processing. EU Digital Services Act implementation through ACM requires platform transparency for consumers in these peripheral provinces. Maastricht and Middelburg serve as logistics consolidation points for international shipping corridors into neighboring countries.
Utrecht Province
Central geographic positioning supports regional distribution center placement for nationwide fulfillment networks. Dutch environmental regulations mandate packaging waste reduction compliance for operations serving this densely populated province. Utrecht city's rail freight connections enable intermodal last-mile approaches that reduce road congestion and emission exposure.
Netherlands E-Commerce Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across Dutch e-commerce, with marketplace operators leveraging network density against specialized retailers investing in proprietary fulfillment infrastructure. The market structure consolidates around three to four dominant platforms controlling transaction liquidity, while niche specialists capture margin in category-specific service layers. Two strategic archetypes predominate: horizontal marketplaces optimizing cross-category purchase frequency, and vertical specialists commanding premium positioning through differentiated fulfillment promises. Competitive moves center on urban micro-fulfillment node expansion and subscription-based membership lock-in mechanisms.
Among domestic platform operators, Bol.com and Albert Heijn B.V. occupy positions exemplifying the marketplace density and integrated grocery fulfillment archetypes respectively. Coolblue N.V. represents the specialized electronics vertical, anchoring competitive positioning through proprietary logistics infrastructure rather than third-party dependency. These three entities collectively illustrate the strategic segmentation between horizontal scale pursuit and vertical service differentiation that structures Dutch e-commerce rivalry.
| Leading Market Players |
|---|
| Bol.com |
| Albert Heijn B.V. |
| Coolblue N.V. |
| Zalando SE |
| Amazon.com, Inc. |
| Jumbo Supermarkten B.V. |
| Wehkamp B.V. |
| Picnic B.V. |
| De Bijenkorf B.V. |
| Others |
Value Chain & Pricing Dynamics
Fleet electrification mandates are replacing diesel-powered last-mile delivery vehicles across Dutch municipal low-emission zones, simultaneously redrawing logistics node geography and compressing operating margins that pricing structures must absorb. This substitution dynamic forces platforms to recalibrate fulfillment premiums against electrification capital costs while repositioning micro-fulfillment centers within Amsterdam's A10 ring and Rotterdam's port district.
Pricing Analysis
The EU Digital Services Act dictates the pricing tier structure for Dutch marketplace operators through ACM-mandated compliance cost allocation. Three-tier pricing structure across premium, standard, and economy levels segments consumers by delivery velocity and service bundling, with subscription memberships displacing per-order fees as the dominant lock-in mechanism. Price differentiation rests on urban density enabling same-day fulfillment economics versus rural coverage requiring standard shipping absorption. Cost compression in premium tiers is intensifying because fleet electrification investments in Amsterdam and Rotterdam low-emission zones raise per-delivery overhead. Retail consumers in Randstad corridors show lowest price sensitivity due to convenience premiums, while rural households outside metropolitan density exhibit highest elasticity.
Supply Chain Analysis
Just-in-time inventory positioning dominates Dutch e-commerce fulfillment, with machine learning demand forecasting enabling SKU pre-positioning in urban micro-fulfillment nodes rather than strategic stockpiling. Geographic supply concentration draws from China for electronics components, Germany for industrial automation systems, and Belgium for cross-border grocery sourcing. Raw material dependencies center on lithium-ion battery cells for fleet electrification, recyclable packaging substrates for Dutch environmental compliance, and cloud compute capacity for demand prediction algorithms. Supply chain risk hinges on single-source vulnerability in specialized warehouse management system providers serving hybrid store-pick and dark-store operations. Distribution runs through proprietary last-mile networks for rapid delivery tiers, with third-party logistics retaining rural standard shipping coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dutch e-commerce sits at an inflection point where EU Digital Services Act enforcement through ACM is restructuring platform economics, creating asymmetric compliance burdens that favor domestic operators with established Dutch-language infrastructure over cross-border entrants.
For Market Incumbents: Compound defensive positioning through proprietary logistics infrastructure expansion and subscription membership density. Bol.com and Albert Heijn should deepen urban micro-fulfillment node coverage within Randstad corridors to sustain same-day delivery promises that justify recurring fees. Threat from emerging specialized platforms in B2B procurement digitization demands preemptive API development for enterprise customer integration. Vertical integration into electric fleet operations mitigates municipal low-emission zone compliance cost volatility.
For New Entrants and Emerging Players: B2B procurement platform gaps in industrial and wholesale buyer segments offer white-space penetration where legacy purchase order systems remain entrenched. Belgian and Luxembourg consumer markets present underexploited geographic expansion with shared Benelux logistics infrastructure. Cross-border fulfillment complexity around VAT registration favors entrants with compliance infrastructure specialization. Go-to-market execution should anchor in Dutch-language customer service capabilities that satisfy ACM transparency mandate enforcement.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated fulfillment specialists over pure marketplace liquidity plays. Long-term viability across the projection horizon rests on electrified fleet ownership and AI-enabled demand forecasting capabilities rather than transaction volume scale alone. Acquisition target archetype: mid-cap platforms with dark-store real estate in Amsterdam and Rotterdam municipal zones. Signal to watch is ACM enforcement pattern intensity against cross-border operators, which would accelerate domestic incumbent valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Urban Micro-Fulfillment Expansion | Dark-store placement within Amsterdam's A10 ring collapses last-mile distances below two-hour delivery windows. |
| Electric Fleet Deployment | Municipal low-emission zone compliance in Rotterdam and Utrecht requires zero-emission vehicle transition investments. |
| Subscription Membership Scaling | Recurring revenue models lock Randstad consumer purchasing frequency against competitor platform switching. |
| B2B Procurement Platform Development | Enterprise customer segments offer higher order values and minimal return rates versus retail marketplace economics. |
| Cross-Border Benelux Integration | Belgian and Luxembourg market penetration exploits shared Dutch-language customer service infrastructure compliance. |
Study Parameters
A spread of perspectives from marketplace operations executives, municipal logistics planners, ACM regulatory affairs specialists, and warehouse management system vendors converged on the working assumptions underlying demand and supply-side sizing. Primary interviews with Dutch grocery retailers including Albert Heijn and Jumbo Supermarkten supplemented secondary validation through ACM enforcement documentation, EU Digital Services Act implementation guidance, Dutch Environmental Management Act emission targets, and Benelux customs processing statistics. Bottom-up transaction volume modeling triangulated against top-down macroeconomic consumption indicators.
Segmentation dimensions modeled span product category, payment method, customer type, and delivery model across the analysis window. Electronics and home goods demand curves incorporated housing market investment cycles and device replacement frequencies. B2B procurement migration rates derived from enterprise survey data on legacy purchase order system displacement. CAGRs reflect compound annual progression from baseline market sizing through terminal year projections, with sensitivity testing around fleet electrification cost absorption and ACM compliance expenditure trajectories.
Forecasts assume regulatory continuity in EU Digital Services Act enforcement through ACM and Dutch municipal low-emission zone expansion; material policy shifts would require re-modeling. Specific risk factors include warehouse labor scarcity constraining peak season throughput, route optimization algorithm deployment delays, and packaging waste reduction mandate acceleration. Revision becomes warranted when same-day delivery cost absorption crosses margin sustainability thresholds or ACM enforcement intensity diverges from baseline assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Mexico E-Commerce Market
E-Commerce Solutions
Asia-Pacific E-Commerce Apparel Market
E-Commerce Solutions
Turkey E-Commerce Market
E-Commerce Solutions
Metaverse in E-Commerce Market
E-Commerce Solutions
Lithuania E-Commerce Market
E-Commerce Solutions
Online to Offline Commerce Market
E-Commerce Solutions
Bahrain E-Commerce Market
E-Commerce Solutions
Canada E-Commerce Market
E-Commerce Solutions
Poland E-Commerce Market
E-Commerce Solutions
France E-Commerce Market
E-Commerce Solutions
China Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
India Quick Commerce Market
E-Commerce Solutions
E-Commerce Search Software Market
E-Commerce Solutions
Pharma E-Commerce Market
E-Commerce Solutions
E-Commerce in Luxembourg Market
E-Commerce Solutions
Japan Cross Border E Commerce Market