
 Asia-Pacific Automotive E-Commerce Market | 2026-2036
Asia-Pacific Automotive E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Automotive E-Commerce Market Analytics
Commercial fleet procurement is expanding across Asia-Pacific automotive e-commerce as logistics operators digitize parts sourcing and maintenance scheduling. Alibaba Group Holding Limited leverages its Taobao and Tmall ecosystems to anchor supplier consolidation across tier-1 and tier-2 Chinese cities. JD.com competes through captive warehouse networks that sustain same-day fulfillment for brake pads, filters, and lubricants. Amazon.com navigates fragmented regulatory environments while extending its marketplace model into South Korea and Southeast Asian corridors.
Asia-Pacific automotive e-commerce encompasses digital transactions for original equipment, aftermarket parts, accessories, and complete vehicles, typically requiring real-time inventory synchronization with manufacturer databases and VIN-specific fitment verification to reduce return rates. The primary commercial purpose is disintermediating traditional multi-tier distribution by connecting parts manufacturers directly to repair shops, fleet operators, and retail consumers through searchable catalog interfaces. Parts and accessories dominate transaction volume within the Product Type dimension, though Vehicles commands higher per-unit value and longer decision cycles. Online Marketplaces capture the broadest SKU breadth under Sales Channel, while Repair Shops and Commercial Fleets generate the most predictable reorder patterns within Customer Type.
China's SAMR enforces platform antitrust and consumer protection standards that shape marketplace fee structures and seller verification protocols across domestic automotive transactions. South Korea's KBA and MFDS intersect with platform liability for safety-critical components, compelling fitment documentation and recall traceability. India's BIS certification mandates for auto parts filter which SKUs qualify for domestic platform listing, creating compliance moats for established suppliers. Stakeholders must monitor how divergent cross-border data localization rules between China, India, and ASEAN jurisdictions reshape inventory hosting and payment settlement architectures.
Market Dynamics
Platform consolidation across China's Tier-1 cities is compressing supplier margins while JD.com and Alibaba lock in captive logistics networks that same-day fulfill brake pads and filters. This infrastructure concentration forces independent marketplaces to specialize in VIN-specific fitment verification or cede volume entirely.
Growth Catalysts
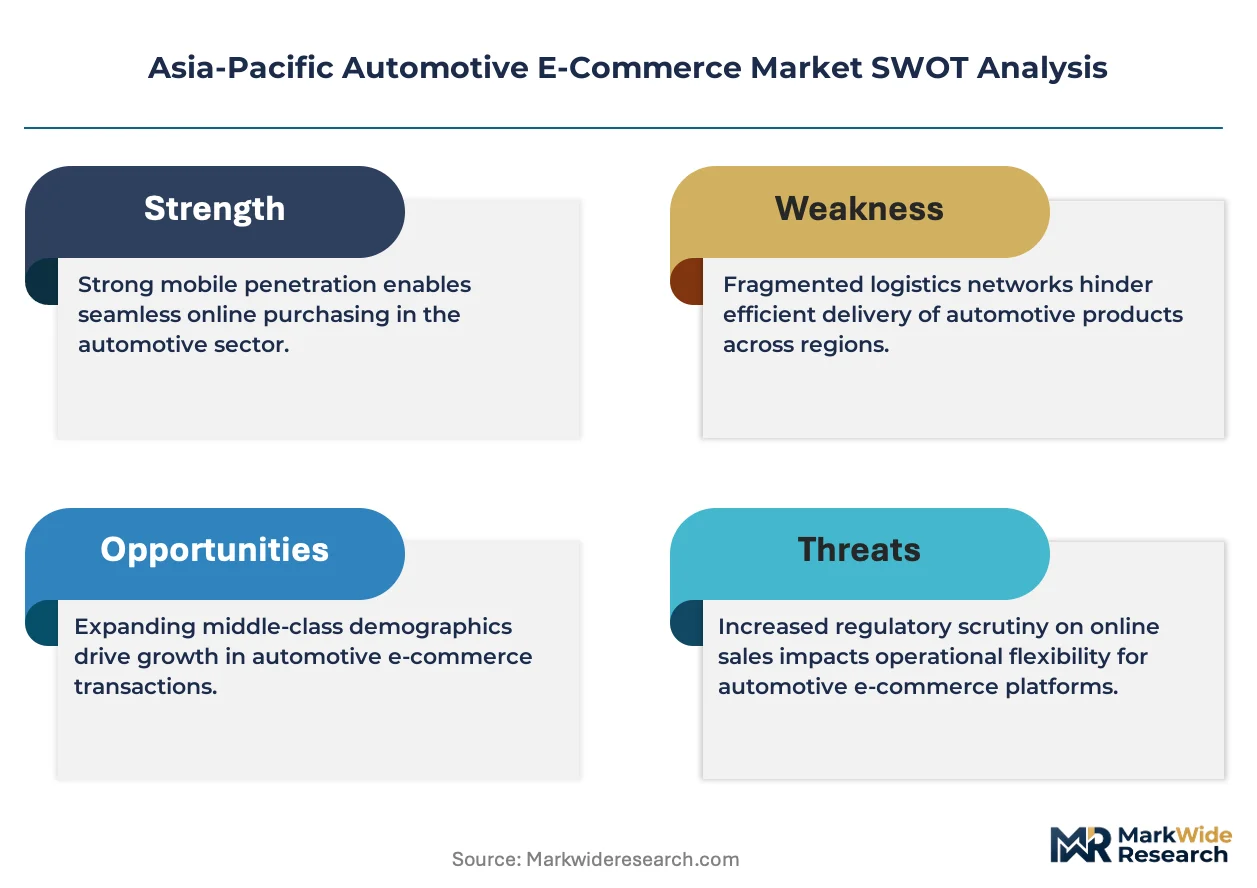
- India's PLI scheme for auto components:Localized inventory availability accelerates on domestic platforms as certified suppliers gain listing priority under BIS mandates.
- Fleet digitization:Logistics operators in South Korea and Vietnam are migrating parts sourcing and maintenance scheduling onto integrated procurement portals.
- Same-day fulfillment infrastructure:Captive warehouse networks in Chinese tier-2 cities compress delivery windows for high-velocity SKUs like lubricants and filters.
Market Restraints
- Cross-border data localization:Divergent hosting rules between China, India, and ASEAN jurisdictions fragment inventory architecture and inflate compliance overhead.
- Safety-critical component liability:South Korea's KBA and MFDS intersection compels fitment documentation and recall traceability that smaller sellers cannot operationalize.
- Last-mile cost structure:Archipelago geography across Indonesia and Philippines inflates per-unit delivery costs relative to continental markets.
Strategic Opportunities
- Vietnam's underpenetrated aftermarket:Low digital penetration among independent repair shops creates first-mover advantage for platforms offering Vietnamese-language VIN lookup tools.
- EV parts specialization:Battery management system components and charging infrastructure parts represent uncataloged white space as electric vehicle adoption accelerates.
- Indonesia's import tariff rationalization:Streamlined customs protocols under ASEAN harmonization reduce landed cost for cross-border auto parts transactions.
Industry Challenges
- VIN-database integration complexity:Legacy dealer management systems in Thailand and Malaysia lack API standardization, forcing expensive middleware development for real-time fitment verification.
- Counterfeit parts detection:Authentication protocols for safety-critical components require blockchain or NFC investments that strain platform capex budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Automotive E-Commerce Market |
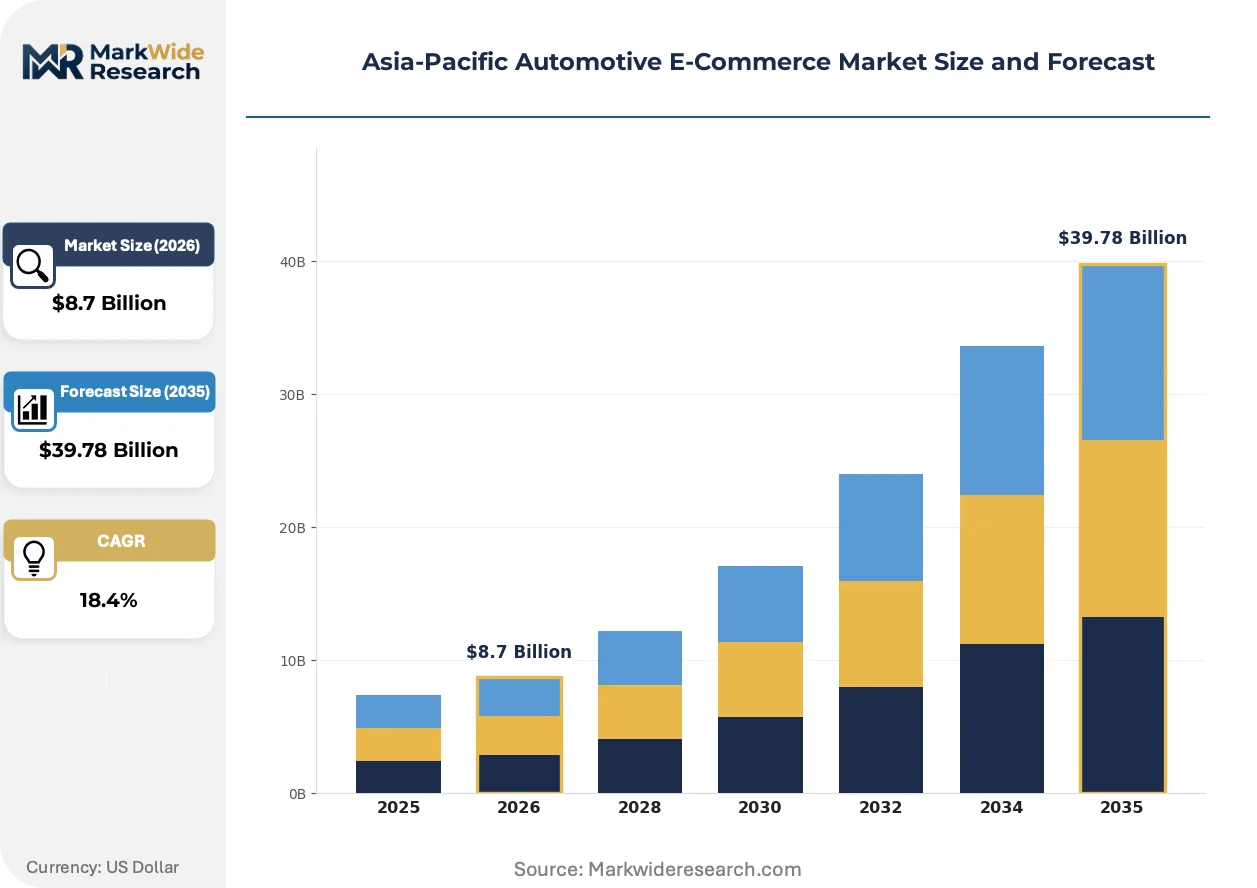
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Parts, Accessories, Tires, Vehicles Sales Channel: Online Marketplaces, Brand Websites, Distributors, Auctions Customer Type: Retail Consumers, Commercial Fleets, Repair Shops, Wholesalers Delivery Mode: Home Delivery, Store Pickup, Direct Shipping, Same-Day Delivery |
| Companies Covered | eBay, Advance Auto Parts, Alibaba Group Holding Limited, JD.com, Carro, Amazon.com, AutoZone, Coupang, Flipkart, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Automotive E-Commerce Market Evolving Landscape
Artificial intelligence is reshaping how automotive e-commerce platforms match parts to vehicles, compressing search friction while regulatory pressure on data governance intensifies across the region. These forces are converging to redefine competitive moats.
Visual search technology is overtaking text-based VIN entry as the primary parts-discovery interface. Repair shop technicians in Guangdong and Jiangsu provinces now photograph damaged components to retrieve exact-match SKUs. This capability is overtaking legacy catalog navigation by eliminating translation errors and accelerating purchase completion.
China's SAMR platform antitrust enforcement is tightening marketplace fee structures and seller verification protocols. Domestic automotive transactions now face mandatory consumer protection standards that elevate compliance costs. Tier-2 city sellers are consolidating under larger distributor umbrellas to absorb documentation burdens.
Subscription-based maintenance bundling is displacing transactional parts purchasing among commercial fleet operators. Logistics companies in South Korea negotiate fixed monthly rates covering predictive parts replacement and scheduled servicing. This model concentrates purchasing power with platform aggregators that can guarantee inventory availability across multiple OEM brands.
Asia-Pacific Automotive E-Commerce Market Segmentation
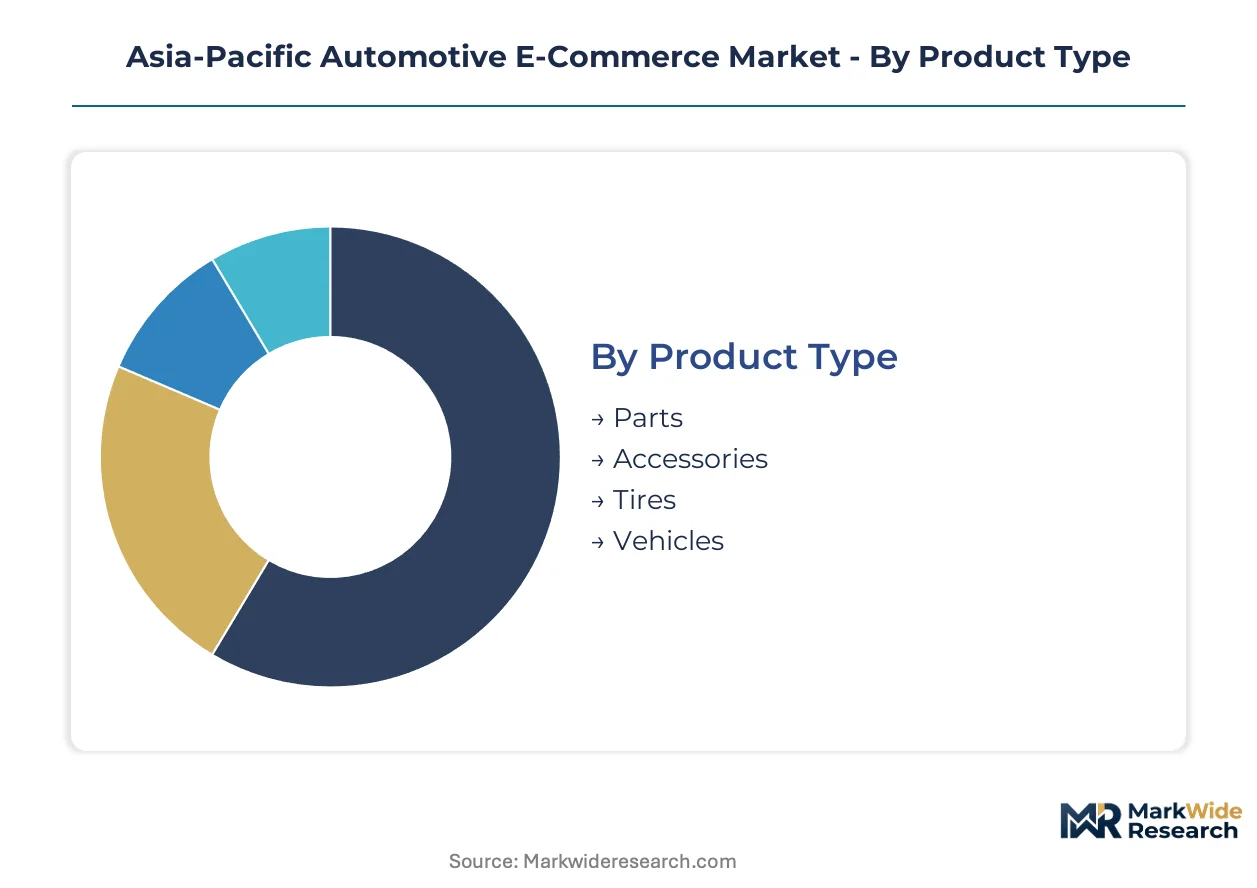
Segmentation in Asia-Pacific automotive e-commerce exposes where capital deployment, regulatory compliance, and logistics infrastructure concentrate. Platform operators must align inventory depth and fulfillment architecture to the specific transaction patterns each segment demands.
Product Type:
Capital intensity varies sharply across product categories, with inventory carrying costs and fitment verification systems driving platform investment priorities.
- Parts:Brake pads, filters, lubricants, and engine components require real-time VIN-database synchronization to minimize return rates. Demand concentrates among repair shops in China's Jiangsu and Guangdong provinces where technician shortages accelerate digital procurement adoption.
- Vehicles:Complete vehicle transactions demand the highest platform investment in trust infrastructure, including inspection certification and financing integration. China's JD.com and Alibaba anchor this segment through captive logistics networks that compress delivery windows for premium EV models.
- Accessories:Interior upgrades and exterior styling components carry lower fitment risk and faster inventory turns.
- Tires:Seasonal demand patterns and storage costs favor platforms with distributed warehouse networks.
Most installed capacity flows through Parts. Expansion is steepest in Vehicles.
Sales Channel:
Customer acquisition economics and margin profiles diverge substantially across channel architectures, with marketplace density determining supplier bargaining power.
- Online Marketplaces:Aggregator platforms like Alibaba's Tmall and JD.com deliver the broadest SKU breadth through consolidated supplier bases. Repair shops in South Korea and Vietnam generate the most predictable reorder patterns on these platforms as fleet digitization accelerates.
- Brand Websites:OEM-direct channels capture premium pricing through authenticated fitment guarantees and warranty integration. Japanese automakers leverage these portals to maintain margin control over safety-critical components subject to METI certification requirements.
- Distributors:Traditional wholesale channels retain relevance for bulk procurement by independent repair networks.
- Auctions:Disposition channels for salvage parts and excess inventory serve price-sensitive segments.
Transaction volume concentrates in Online Marketplaces. Margin expansion is strongest in Brand Websites.
Customer Type:
Procurement sophistication and inventory predictability separate commercial buyers from retail consumers, reshaping platform service level requirements.
- Commercial Fleets:Logistics operators negotiate subscription-based maintenance bundling that consolidates purchasing power across multiple OEM brands. South Korean fleet managers drive predictive parts replacement through integrated procurement portals.
- Repair Shops:Independent technicians in Vietnam's underpenetrated aftermarket represent first-mover opportunity for platforms offering localized VIN lookup tools. Visual search adoption in Guangdong province eliminates translation errors and accelerates purchase completion.
- Retail Consumers:Individual buyers exhibit highest price sensitivity and lowest purchase frequency.
- Wholesalers:Bulk resellers arbitrage regional price differentials across ASEAN corridors.
Revenue predictability is highest in Commercial Fleets. Digital penetration is climbing fastest in Repair Shops.
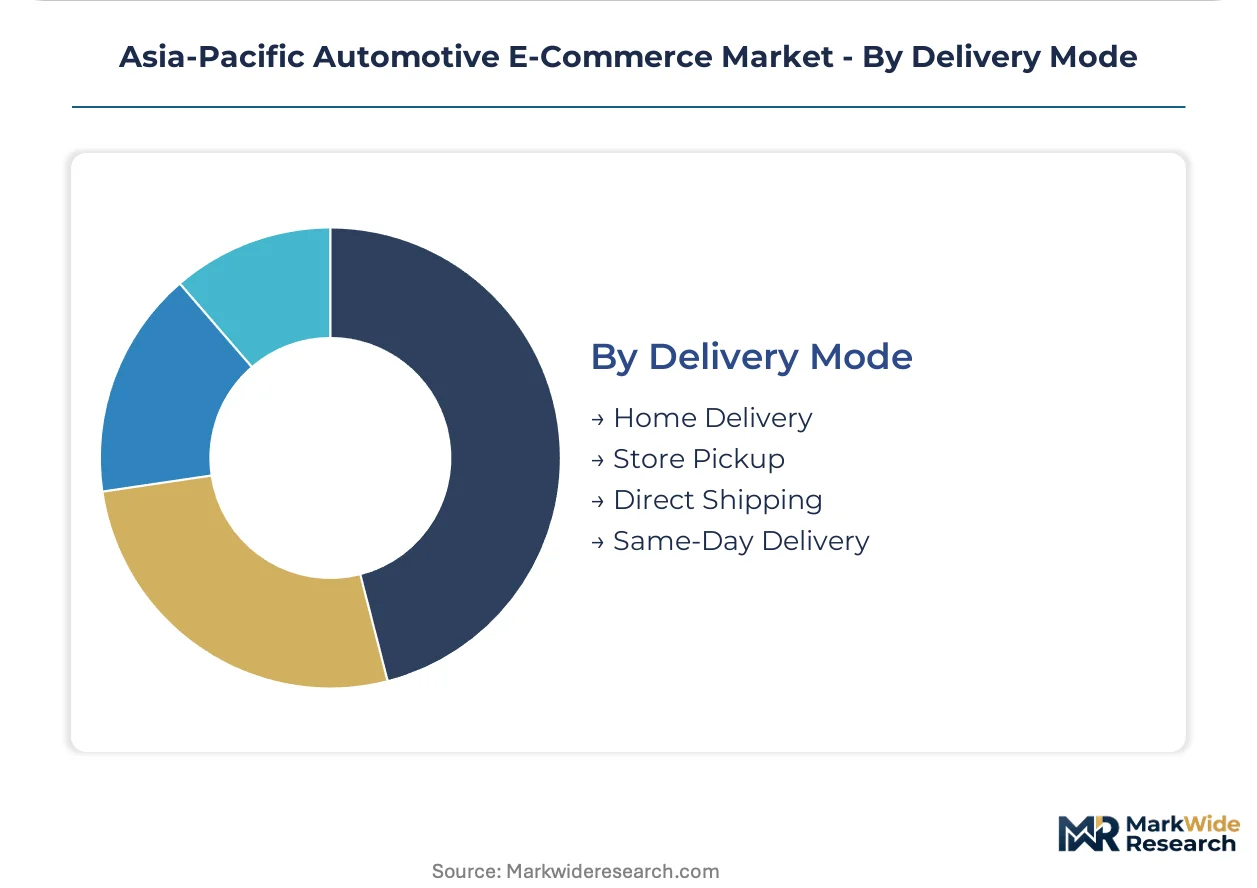
Delivery Mode:
Fulfillment infrastructure requirements scale with speed commitments, with same-day capabilities demanding the most capital-intensive warehouse networks.
- Same-Day Delivery:JD.com's captive warehouse networks in Chinese tier-2 cities sustain sub-24-hour fulfillment for high-velocity SKUs. This capability is displacing slower alternatives as fleet operators consolidate procurement onto platforms guaranteeing inventory availability.
- Home Delivery:Direct-to-consumer shipping dominates retail accessory transactions where fitment verification is less critical. Indonesia's archipelago geography inflates per-unit costs relative to continental markets.
- Store Pickup:Click-and-collect bridges online discovery with offline trust verification for tire and parts purchases.
- Direct Shipping:Manufacturer-to-buyer models bypass platform inventory risk but extend lead times.
Platform investment concentrates in Same-Day Delivery. Adoption is broadening fastest in Home Delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing automotive e-commerce infrastructure across Asia-Pacific as compliance cost differentials between China's SAMR regime and India's BIS framework attract platform investment toward lower-friction jurisdictions.
China
SAMR antitrust enforcement and dual carbon goals are reshaping marketplace economics as JD.com and Alibaba consolidate supplier bases across Jiangsu and Guangdong provinces. Tier-2 city warehouse networks now sustain same-day fulfillment for brake pads and lubricants. Visual search adoption among Guangdong repair shops eliminates translation errors and accelerates purchase completion.
India
BIS certification mandates and the PLI scheme for auto components are filtering which SKUs qualify for domestic platform listing. Localized inventory availability accelerates as certified suppliers gain priority on Flipkart and emerging automotive marketplaces. Maharashtra and Karnataka clusters concentrate platform fulfillment centers serving independent repair networks.
South Korea
KBA and MFDS intersection compels fitment documentation and recall traceability for safety-critical components. Fleet digitization drives subscription-based maintenance bundling as logistics operators migrate parts sourcing onto integrated procurement portals. Seoul Capital Area anchors predictive parts replacement platforms serving multi-OEM commercial fleets.
Vietnam
Low digital penetration among independent repair shops creates first-mover advantage for platforms offering Vietnamese-language VIN lookup tools. Ho Chi Minh City and Hanoi clusters concentrate emerging marketplace infrastructure as cross-border data localization rules remain less restrictive than Chinese or Indian equivalents. Fleet operators in the Mekong Delta region accelerate procurement portal adoption.
Indonesia
Archipelago geography inflates per-unit delivery costs relative to continental markets, favoring platforms with distributed warehouse networks. ASEAN harmonization under import tariff rationalization reduces landed cost for cross-border auto parts transactions. Java-based logistics hubs concentrate inventory staging for tire and filter distribution to secondary islands.
Asia-Pacific Automotive E-Commerce Market Competitive Landscape
Platform consolidation dominates the current landscape as JD.com and Alibaba lock in captive logistics networks across Chinese tier-1 and tier-2 cities. The market structures around three tiers: integrated marketplace-logistics hybrids, specialized fitment-verification platforms, and OEM-direct brand portals. Independent marketplaces face margin compression and must specialize in VIN-specific capabilities or cede volume entirely. M&A activity and same-day fulfillment infrastructure deployment represent the dominant competitive vectors.
Among integrated marketplace operators, Alibaba Group Holding Limited and JD.com exemplify the logistics-captive archetype through warehouse networks sustaining sub-24-hour fulfillment. Amazon.com occupies a position navigating fragmented regulatory environments while extending marketplace infrastructure into South Korea and Southeast Asian corridors. Within the regional specialist tier, Carro represents the vehicle-transaction platform model concentrated on Southeast Asian markets.
| Leading Market Players |
|---|
| eBay |
| Advance Auto Parts |
| Alibaba Group Holding Limited |
| JD.com |
| Carro |
| Amazon.com |
| AutoZone |
| Coupang |
| Flipkart |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between BIS-certified and uncertified auto parts splits both pricing power and sourcing architecture across India and China. SAMR enforcement in Chinese tier-1 cities elevates compliance documentation costs that tier-2 distributors absorb through consolidated umbrella structures, while India's PLI scheme redirects procurement toward certified domestic suppliers with listing priority on Flipkart and emerging platforms.
Pricing Analysis
Retailer markup compression in online marketplaces intensifies as JD.com and Alibaba lock in captive logistics networks that same-day fulfill brake pads and filters. Pricing stratifies across authenticated OEM-direct channels, consolidated marketplace tiers, and gray-market salvage auctions based on fitment documentation depth and warranty integration. Cost compression in tier-2 and tier-3 city supply runs through visual search adoption that eliminates translation friction and accelerates purchase completion. Commercial fleet operators exhibit lowest price sensitivity due to subscription-based maintenance bundling, while individual retail consumers drive volume through price-comparison behavior.
Supply Chain Analysis
India's domestic-content mandates under the PLI scheme for auto components reshape sourcing toward Maharashtra and Karnataka production clusters. Component supply draws from China for battery management systems, South Korea for precision electronics, and domestic Indian certified suppliers for brake pads and filtration. Single-source vulnerability concentrates in VIN-database synchronization middleware where legacy dealer management systems in Thailand and Malaysia lack API standardization. Distribution runs through captive warehouse networks in Chinese tier-2 cities, direct-to-repair-shop portals in Vietnam, and Java-based logistics hubs serving Indonesia's archipelago geography.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SAMR platform antitrust milestones compound regulatory compliance into a demand driver for verified-seller infrastructure and documentation-absorbing distributor umbrellas across Chinese automotive e-commerce.
For Market Incumbents: Deploy captive same-day fulfillment networks as the defensive anchor against specialized fitment-verification platforms. Absorb tier-2 city sellers under consolidated distributor umbrellas to distribute SAMR documentation burdens. Reinforce VIN-database API investments to neutralize middleware development costs that strain smaller competitors. For New Entrants and Emerging Players: Independent repair shops in Vietnam's underpenetrated aftermarket represent the most penetrable buyer archetype for platforms offering localized Vietnamese-language VIN lookup tools. Battery management system components and charging infrastructure parts for electric vehicles constitute uncataloged white space with minimal incumbent specialization. A direct-to-repair-shop portal model bypasses marketplace fee compression entirely. For Investors and Strategic Acquirers: Consolidation pressure builds where platform operators lack captive logistics infrastructure and face margin compression from JD.com and Alibaba same-day fulfillment capabilities. Viable acquisition targets include specialized fitment-verification platforms with proprietary VIN-database integrations serving underpenetrated Southeast Asian corridors. Watch for SAMR enforcement intensity as the signal indicating accelerated seller consolidation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Warehouse Network Expansion | JD.com's tier-2 city footprint compresses delivery windows below 24 hours for high-velocity SKUs. |
| VIN-Database API Standardization | Middleware investments unlock real-time fitment verification for repair shops in Thailand and Malaysia. |
| Subscription Maintenance Bundling | South Korean fleet operators consolidate purchasing power across multiple OEM brands through fixed-rate contracts. |
| Visual Search Technology Deployment | Guangdong technicians photograph damaged components to eliminate translation errors and accelerate SKU retrieval. |
| EV Parts Specialization | Battery management systems and charging infrastructure represent uncataloged white space as electric adoption accelerates. |
Research Methodology
Bottom-up repair shop and fleet operator modeling reconciled against top-down marketplace transaction tracking forms the analytical core of this study. Primary interviews with automotive e-commerce platform executives, Tier 1 supplier procurement leads, independent repair shop owners, and commercial fleet managers in China, India, and Southeast Asia combined with secondary validation from SAMR regulatory filings, BIS certification databases, vehicle production registries, and customs trade records. Top-down and bottom-up estimates triangulate through cross-referencing marketplace GMV disclosures against provincial automotive parts consumption indices.
Historical trendline analysis of digital procurement penetration across repair shop networks and fleet operator adoption curves informs the projection framework. Segmentation dimensions modeled include product type, sales channel architecture, customer procurement sophistication, and delivery speed commitment across the projection horizon. CAGRs derive from fitted adoption curves for visual search technology, subscription maintenance bundling, and EV parts catalog expansion. Forecast inputs incorporate SAMR enforcement intensity indices and PLI scheme certification velocity.
Underlying measurement precision varies by segment; same-day delivery infrastructure and online marketplace transaction volumes carry tighter precision than auction channels and direct shipping models. Forecasts incorporate assumptions regarding regulatory enforcement continuity, data localization rule stability, and logistics network expansion cadence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
UK Ecommerce Market
E-Commerce Solutions
Japan Same Day Delivery Market
E-Commerce Solutions
Automotive E-Commerce Market
E-Commerce Solutions
Turkey E-Commerce Market
E-Commerce Solutions
Live Commerce Platforms Market
E-Commerce Solutions
Slovak Republic E-Commerce Market
E-Commerce Solutions
Europe Automotive E-Commerce Market
E-Commerce Solutions
Vietnam E-Commerce Market
E-Commerce Solutions
Asia Pacific Same Day Delivery Market
E-Commerce Solutions
New Zealand E-Commerce Market
E-Commerce Solutions
E-Commerce Buy Now Pay Later Market
E-Commerce Solutions
China Ecommerce Logistics Market
E-Commerce Solutions
Second-Hand E-Commerce Market
E-Commerce Solutions
Digital Coupons Market
E-Commerce Solutions
India Alcohol E-Commerce Market
E-Commerce Solutions
E-Commerce Ecosystem Market