
 Spain E-Commerce Market | 2026-2036
Spain E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Spain E-Commerce Market Outlook
Spanish consumer purchasing is pivoting from fragmented neighborhood retail toward consolidated online basket-building, with metropolitan households now routing a majority of non-food spending through digital channels. Amazon leverages its fulfillment network to dominate next-day delivery expectations across the Iberian Peninsula. El Corte Inglés sustains its department store heritage through integrated click-and-collect infrastructure that bridges physical and digital touchpoints. Mercadona anchors fresh grocery e-commerce through proprietary dark-store operations in Valencia and Madrid.
Spain e-commerce encompasses digitally mediated transactions for goods and services executed through web-based platforms and mobile applications, relying on automated inventory management systems, encrypted payment gateways, and algorithmic recommendation engines to match supply with dispersed consumer demand. Online marketplace platforms capture the largest transaction volume by aggregating third-party sellers under unified logistics and trust frameworks, while direct-to-consumer channels are expanding fastest as brands bypass intermediaries to capture first-party data and protect margin pools. Fashion and electronics categories lead product-type revenue, though home goods is maturing as a repeat-purchase segment with established replenishment cycles.
Spain's national consumer protection authority enforces the EU Consumer Rights Directive on cooling-off periods and return obligations, while the Spanish Data Protection Agency applies GDPR standards to platform data processing practices, and the EU Digital Services Act imposes transparency requirements on algorithmic ranking and advertising disclosures. These frameworks elevate compliance costs for cross-border sellers but create structural advantages for domestic operators with established legal teams. Stakeholders must monitor how Madrid interprets forthcoming EU platform liability rules and whether Barcelona's regional tax authorities pursue separate digital services levies.
Market Dynamics
Spanish e-commerce is reconfiguring around last-mile density economics as metropolitan fulfillment networks achieve sub-two-hour delivery windows, compressing the competitive moat between pure-play digital operators and hybrid retail incumbents.
Growth Catalysts
- EU Digital Services Act:Platform transparency mandates are accelerating seller verification investments that reduce consumer fraud perception and lift conversion rates in cross-border transactions.
- Dark-store infrastructure:Dedicated urban fulfillment nodes are collapsing grocery delivery times from days to minutes in Madrid and Barcelona corridors.
- Embedded finance adoption:Buy-now-pay-later integration at checkout is expanding basket sizes for fashion and electronics purchases among under-35 demographics.
Market Restraints
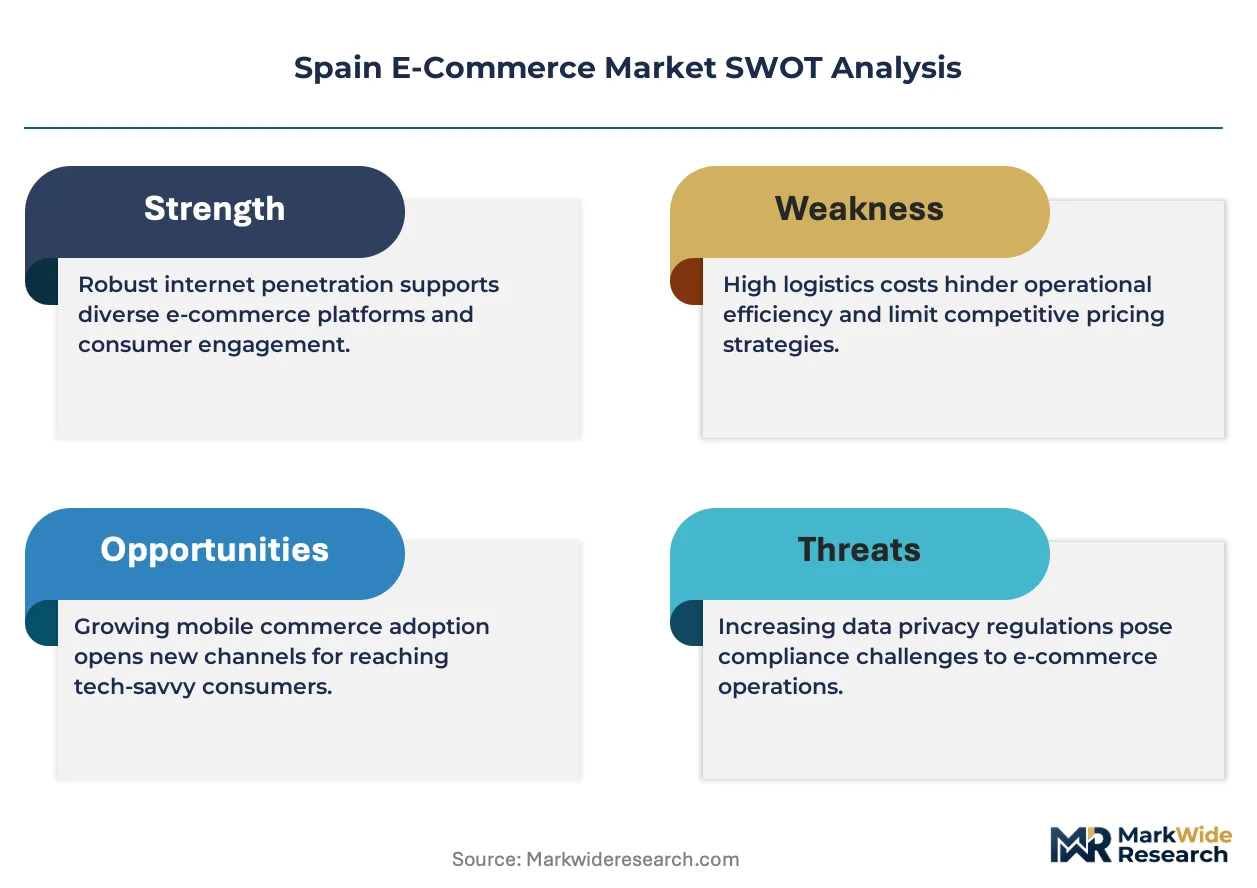
- Last-mile labor costs:Rider wage inflation and platform worker reclassification litigation are compressing unit economics in same-day delivery segments.
- Packaging waste levies:Spanish implementation of extended producer responsibility rules is adding per-parcel compliance costs for marketplace sellers.
- Payment fraud exposure:Card-not-present chargeback rates remain elevated relative to Northern European benchmarks, elevating risk premiums for cross-border merchants.
Strategic Opportunities
- Andalusian corridor expansion:Seville and Málaga metropolitan zones show underpenetrated grocery e-commerce adoption relative to Madrid-Barcelona baselines.
- Recommerce platform development:Circular economy incentives under Spain's waste framework are creating regulatory tailwinds for certified pre-owned electronics marketplaces.
- Voice commerce integration:Smart speaker penetration in Spanish households is enabling hands-free reordering for consumables categories.
Industry Challenges
- Data science talent scarcity:Demand forecasting and personalization engineering roles command premium compensation that mid-market platforms struggle to match.
- Legacy ERP integration:Family-owned retail chains face multi-year timelines to connect inventory systems with marketplace APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain E-Commerce Market |
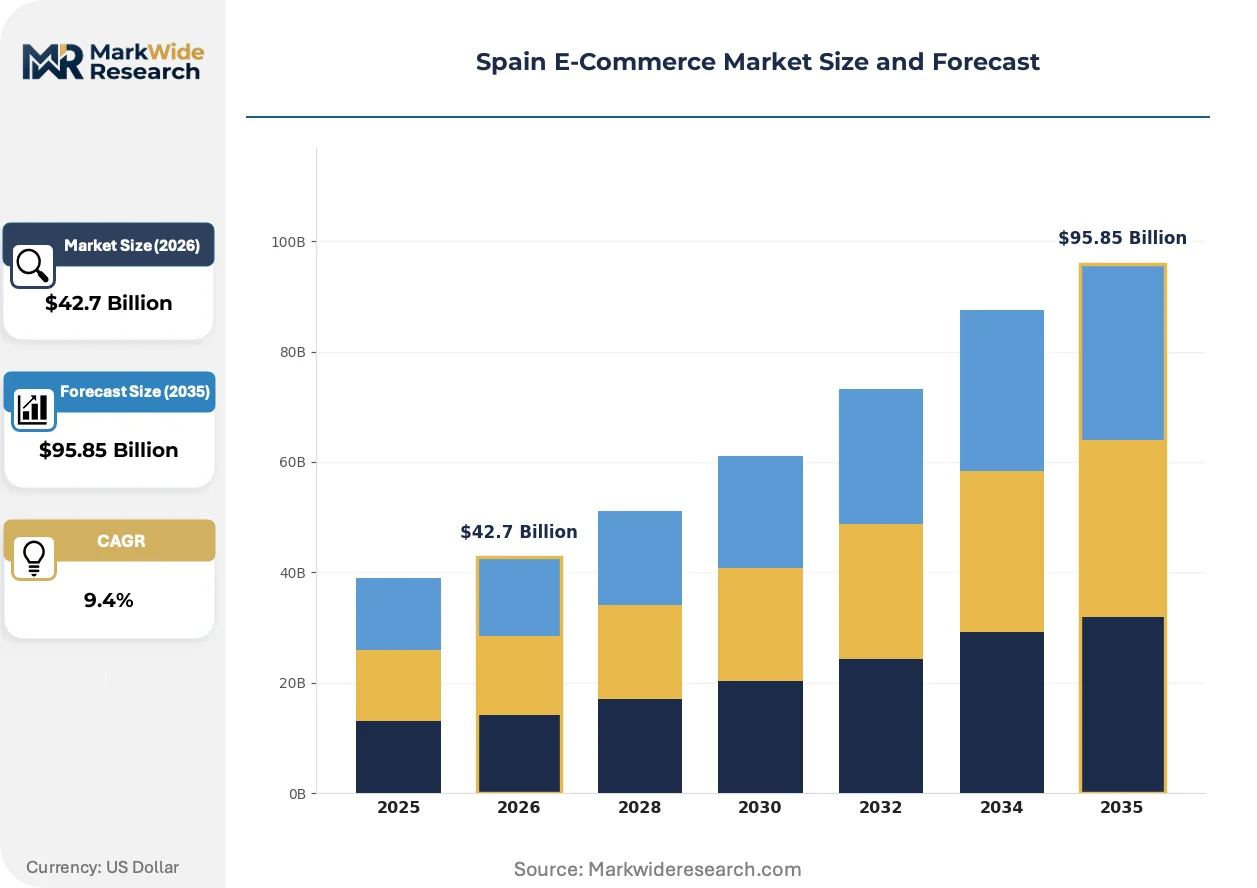
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $95.85 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronics, Fashion, Home Goods, Beauty Products Sales Channel: Direct-to-Consumer, Online Marketplace, Business-to-Business, Subscription Services Payment Method: Credit Card, PayPal, Bank Transfer, Digital Wallets Customer Type: Individual Consumers, Small Businesses, Retailers, Wholesalers |
| Companies Covered | Amazon, El Corte Inglés, Shein, AliExpress, Temu, MediaMarkt, Carrefour, Zalando, Mercadona, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain E-Commerce Market Strategic Shifts
Spanish digital commerce is pivoting from transaction facilitation toward predictive demand orchestration, with platforms investing in anticipatory logistics and AI-driven inventory positioning to compress fulfillment latency.
Distributed micro-fulfillment networks are decentralizing inventory placement across neighborhood-scale facilities. Mercadona and Amazon are deploying automated picking systems in converted urban retail spaces. This architecture is decentralizing delivery origin points, enabling 30-minute grocery windows that reshape consumer substitution patterns between planned and impulse purchases.
Spain's national consumer protection authority is enforcing cooling-off period extensions for digital subscriptions under EU Consumer Rights Directive amendments. Marketplace operators must now display total contract costs upfront and simplify cancellation workflows. Fashion rental and software-as-a-service verticals face the steepest compliance redesigns, with Barcelona-based platforms accelerating automated refund pipelines.
Subscription-based replenishment is displacing episodic basket-building in household consumables. Amazon's Subscribe & Save and Carrefour's programmed delivery locks are capturing recurring revenue streams that reduce customer acquisition cost burdens. This pattern concentrates most visibly among dual-income households in Madrid's northern districts, where time scarcity elevates convenience premiums above price sensitivity.
Spain E-Commerce Market Segmentation
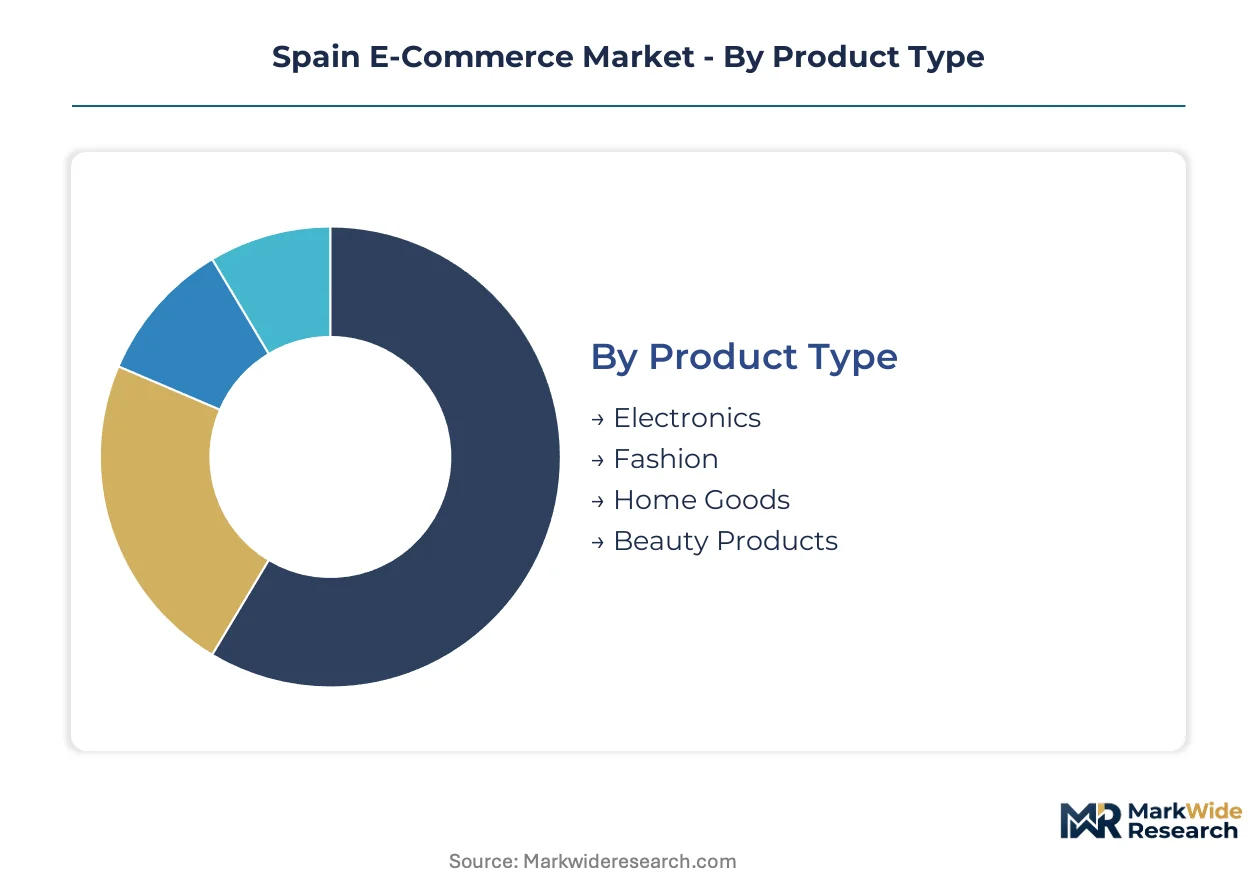
Spanish e-commerce segmentation reveals how purchase cycles, channel preferences, and payment infrastructures fragment across distinct buyer profiles. Understanding these divisions exposes where platform investments generate asymmetric returns versus commodity competition.
Product Type:
Upgrade and replacement cycles vary dramatically across product categories, with electronics demanding near-annual refresh rates while home goods stretch toward decade-long horizons.
- Electronics:Smartphones, laptops, and consumer electronics carry compressed replacement windows driven by planned obsolescence and 5G infrastructure rollouts. Madrid and Barcelona households concentrate demand for premium devices, with carrier-locked distribution dominating suburban corridors.
- Fashion:Apparel and accessories operate on seasonal refresh rhythms, with fast-fashion SKUs turning inventory six to eight times annually. Barcelona's design ecosystem feeds domestic brand development, while cross-border Zara and H&M capture standardized demand.
- Home Goods:Furniture and décor purchases tie to housing transaction cycles and renovation timelines, stretching replacement intervals to seven to ten years.
- Beauty Products:Cosmetics and skincare follow replenishment-driven purchasing with monthly restock patterns among subscribed households.
Volume placements concentrate in Electronics; the faster expansion belongs to Beauty Products.
Sales Channel:
Channel selection determines margin capture versus scale tradeoffs, with direct models preserving profitability at lower volumes and marketplaces sacrificing unit economics for reach.
- Direct-to-Consumer:Brand-operated storefronts bypass intermediary fees to capture first-party data and full margin pools. Valencia-based skincare brands and Basque food producers leverage this channel for regional identity differentiation.
- Online Marketplace:Aggregator platforms consolidate third-party inventory under unified logistics and trust frameworks, dominating transaction volume through Amazon and El Corte Inglés marketplaces.
- Business-to-Business:Wholesale procurement platforms serve hospitality and retail sectors with volume-tiered pricing and extended payment terms.
- Subscription Services:Recurring revenue models lock in household consumables through programmed delivery, gaining fastest traction among dual-income Madrid districts.
Transaction density clusters in Online Marketplace; Subscription Services show the steepest expansion trajectory.
Payment Method:
Payment infrastructure maturity shapes checkout completion rates, with trust frameworks and friction levels diverging sharply across demographic segments.
- Credit Card:Dominant instrument for high-value transactions, with Visa and Mastercard networks processing the majority of fashion and electronics purchases. Chargeback protections elevate consumer confidence for cross-border merchants.
- PayPal:Mediated wallet services reduce card-not-present fraud exposure, concentrating among under-35 demographics and international marketplace purchases.
- Bank Transfer:SEPA direct debits persist for B2B invoicing and high-ticket home goods, though friction delays impulse conversion.
- Digital Wallets:Apple Pay and Google Pay adoption accelerates in metropolitan corridors, collapsing checkout steps to biometric authentication.
Credit Card captures the largest transaction share; Digital Wallets are climbing the fastest as smartphone penetration deepens.
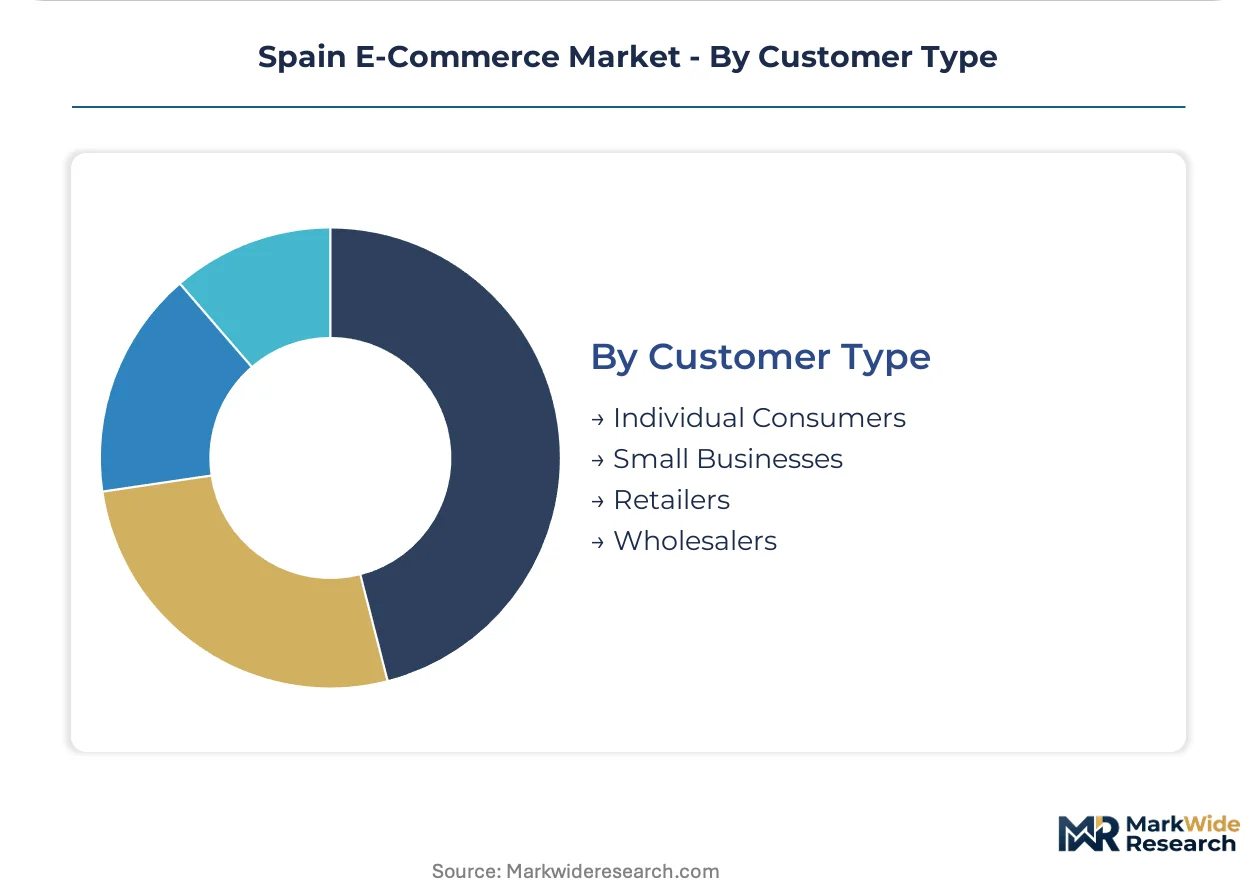
Customer Type:
Buyer sophistication and order scale create distinct service requirements, from individual convenience demands to wholesale logistics complexity.
- Individual Consumers:Fragmented demand across millions of households, with delivery speed and return flexibility commanding premium pricing tolerance in Madrid and Barcelona.
- Small Businesses:Procurement offices and independent retailers seek volume discounts without enterprise minimums, concentrating in Catalonia's industrial zones.
- Retailers:Multi-location chains require integrated inventory synchronization and consolidated invoicing across regional store networks.
- Wholesalers:Bulk purchasers drive pallet-scale logistics with negotiated freight terms and extended payment windows.
Individual Consumers anchor volume; Small Businesses gain share fastest as digital procurement tools democratize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan logistics density in Madrid and Barcelona anchors Spain's e-commerce fulfillment infrastructure, with dark-store networks and last-mile automation concentrating in these corridors before radiating toward secondary urban centers.
Madrid
Dual-income households in northern districts drive subscription-based replenishment demand for household consumables. The Spanish Data Protection Agency enforces GDPR standards on platform data processing practices. Amazon and Mercadona operate automated micro-fulfillment nodes in converted urban retail spaces, collapsing grocery delivery windows to thirty minutes.
Catalonia
Barcelona's design ecosystem feeds domestic fashion brand development while cross-border fast-fashion platforms capture standardized demand. Cooling-off period extensions for digital subscriptions under EU Consumer Rights Directive amendments force compliance redesigns. Fashion rental and software-as-a-service platforms accelerate automated refund pipelines in the metropolitan area.
Basque Country
Food producers leverage direct-to-consumer channels for regional identity differentiation in specialty categories. Extended producer responsibility rules add per-parcel compliance costs for marketplace sellers. Bilbao and San Sebastián host mid-market platforms struggling to match premium compensation for data science talent in demand forecasting roles.
Valencia
Skincare brands utilize proprietary storefronts to bypass intermediary fees and capture first-party data. The EU Digital Services Act imposes transparency requirements on algorithmic ranking and advertising disclosures. Mercadona anchors fresh grocery e-commerce through dedicated dark-store operations, enabling sub-two-hour delivery windows.
Andalusia
Seville and Málaga metropolitan zones show underpenetrated grocery e-commerce adoption relative to Madrid-Barcelona baselines. Platform worker reclassification litigation compresses unit economics in same-day delivery segments. Family-owned retail chains face multi-year timelines to connect legacy inventory systems with marketplace APIs.
Spain E-Commerce Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue cross-border marketplace aggregation and ultra-fast fashion logistics. The vendor base clusters around three strategic poles: integrated retail conglomerates with physical-digital hybrid infrastructure, pure-play digital marketplaces leveraging transnational fulfillment networks, and specialized vertical platforms dominating single-category replenishment cycles. Dominant competitive moves include strategic partnerships with last-mile delivery providers and portfolio diversification into financial services at checkout.
Among transnational marketplace operators, Amazon and AliExpress exemplify scale-driven logistics architectures that set consumer delivery expectations across the Iberian Peninsula. Within the hybrid retail tier, El Corte Inglés occupies a position bridging department store heritage with integrated click-and-collect infrastructure. Mercadona represents the vertical integration archetype, anchoring fresh grocery e-commerce through captive dark-store operations and proprietary fulfillment technology in metropolitan corridors.
| Leading Market Players |
|---|
| Amazon |
| El Corte Inglés |
| Shein |
| AliExpress |
| Temu |
| MediaMarkt |
| Carrefour |
| Zalando |
| Mercadona |
| Others |
Value Chain & Pricing Dynamics
Last-mile labor costs cascade through fulfillment economics to stratify platform pricing across premium express, standard next-day, and economy deferred tiers. Rider wage inflation in Madrid and Barcelona corridors compresses margins on same-day delivery, forcing surcharge unbundling or subscription bundling to recover unit economics.
Pricing Analysis
Warranty and return-policy bundling separates Amazon Prime's frictionless refunds from marketplace sellers charging restocking fees on electronics. Three-tier pricing structure across premium, standard, and economy levels reflects delivery speed guarantees, with metropolitan households absorbing convenience premiums above price sensitivity. Cost compression in grocery verticals is intensifying because Mercadona's captive dark-store network achieves density economies pure-play grocers cannot match. Small businesses in Catalonia's industrial zones exhibit highest price sensitivity, while dual-income Madrid districts prioritize speed over tariff.
Supply Chain Analysis
GDPR certification and algorithmic transparency audits under the EU Digital Services Act gate marketplace participation for cross-border sellers. Inventory positioning draws from China-manufactured electronics, Vietnamese textiles, and domestic Iberian fresh produce. Single-source vulnerability concentrates in cloud infrastructure dependencies for recommendation engines and payment processing. Distribution runs through Amazon's transnational fulfillment network, El Corte Inglés hybrid click-and-collect nodes, and Mercadona's proprietary urban dark-stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's e-commerce sector sits at a technology-transition inflection as AI-driven demand forecasting displaces legacy inventory planning systems. Embedded finance and voice commerce architectures are replacing conventional checkout flows.
For Market Incumbents: Acquire dark-store real estate in Seville and Málaga corridors before competitor density locks out last-mile positioning. Consolidate data science talent through targeted hiring in Bilbao and Valencia where compensation premiums strain mid-market platforms. Rider reclassification litigation threatens unit economics; preemptive employment-model restructuring preserves margin pools before regulatory enforcement hardens.
For New Entrants and Emerging Players: Family-owned retail chains in Andalusia present the most penetrable buyer archetype for API-integration services that bridge legacy ERP systems with marketplace infrastructure. Circular economy certification for recommerce platforms exploits regulatory tailwinds under Spain's waste framework. Voice commerce integration for consumables categories offers a defensible wedge against established app-based ordering habits.
For Investors and Strategic Acquirers: Dark-store network expansion announcements by grocery incumbents are the leading indicator that last-mile density economics are crossing threshold viability in secondary metros. Long-term viability hinges on proprietary fulfillment technology rather than third-party logistics dependence. Platform worker classification rulings from Spanish labor courts signal inflection points for unit-economics recalibration across the sector.
| Strategic Initiative | Industry Significance |
|---|---|
| Dark-Store Network Expansion | Enables sub-thirty-minute grocery delivery windows in Madrid and Barcelona corridors. |
| Embedded Finance Integration | Captures basket-size expansion through buy-now-pay-later at checkout for under-35 demographics. |
| AI-Driven Demand Forecasting | Compresses inventory carrying costs through predictive positioning in micro-fulfillment nodes. |
| Recommerce Platform Certification | Aligns with Spanish extended producer responsibility rules for electronics circularity. |
| Voice Commerce Architecture | Locks in recurring consumables demand through smart-speaker reordering interfaces. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with platform operations directors, last-mile logistics providers, grocery category managers, and fintech integration specialists complemented secondary validation. Spanish Data Protection Agency enforcement actions, EU Digital Services Act implementation guidance, and Madrid regional labor court rulings supplied regulatory context. Bottom-up seller-density modeling and top-down consumption-spend triangulation reconciled volume estimates.
Data-stream reconciliation across shipment manifests, payment-processor disclosures, and retail audit panels informed the analytical framework. Segmentation dimensions modeled include product category, sales channel architecture, payment instrument, and metropolitan delivery corridor. CAGRs were derived from trend extrapolation moderated by regulatory phase-in schedules and infrastructure deployment timelines. Dark-store rollout velocities and smart-speaker household penetration curves served as category-specific forecast inputs across the projection horizon.
Revisions become necessary when EU platform liability rules tighten, rider classification precedents shift, or macroeconomic conditions alter discretionary spending patterns. Forecasts reflect documented assumptions on technology adoption curves and regulatory enforcement intensity. A model refresh is warranted upon material change in last-mile labor cost trajectories or dark-store network saturation levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
China Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
Digital Coupons Market
E-Commerce Solutions
Southeast Asia Cross-Border E-Commerce Market
E-Commerce Solutions
India Digital Gift Card Market
E-Commerce Solutions
ASEAN E-Commerce Logistics Market
E-Commerce Solutions
UK Ecommerce Market
E-Commerce Solutions
Japan E-Commerce Market
E-Commerce Solutions
Hyperlocal Delivery App Market
E-Commerce Solutions
Brazil E-Commerce Market
E-Commerce Solutions
United Kingdom Same Day Delivery Market
E-Commerce Solutions
Lithuania E-Commerce Market
E-Commerce Solutions
Germany E-Commerce Market
E-Commerce Solutions
Asia Pacific B2B E-Commerce Market
E-Commerce Solutions
Slovenia E-Commerce Market
E-Commerce Solutions
United States E-Commerce Market
E-Commerce Solutions
Quiet Commerce Market