
 Commerce Cloud Market | 2026-2036
Commerce Cloud Market Size, Share, and Industry Trends Forecast 2026-2036
Commerce Cloud Market Intelligence
The European Union's General Data Protection Regulation (GDPR) is rebalancing the competitive landscape by imposing stringent data residency and privacy requirements on platform providers. Salesforce.com, Inc. leverages its extensive CRM ecosystem to offer deeply integrated B2B and B2C commerce solutions. Shopify Inc. specializes in providing accessible, scalable platforms that dominate the small to medium-sized business segment. Adobe, Inc. differentiates through its Experience Cloud, focusing on content-driven commerce and advanced personalization.
Commerce cloud refers to a suite of software-as-a-service (SaaS) applications for managing online sales, marketing, order processing, and customer service. These platforms operate on multi-tenant architecture, enabling businesses to scale operations without managing underlying physical infrastructure. While the Subscription service type remains dominant, API-first and Headless integration levels are gaining traction for their flexibility. Retailers and brand owners represent the largest end-user segments, driving platform innovation in personalization and omnichannel capabilities.
Compliance frameworks including the EU's GDPR, consumer protection directives from the US Federal Trade Commission (FTC), and China's GB standards for e-commerce fundamentally shape platform features. These regulations govern data security, cross-border data flows, and consumer rights, directly impacting development costs and market access strategies. Platform vendors must now decide between building globally standardized solutions versus region-specific architectures to effectively manage compliance risk.
Market Dynamics
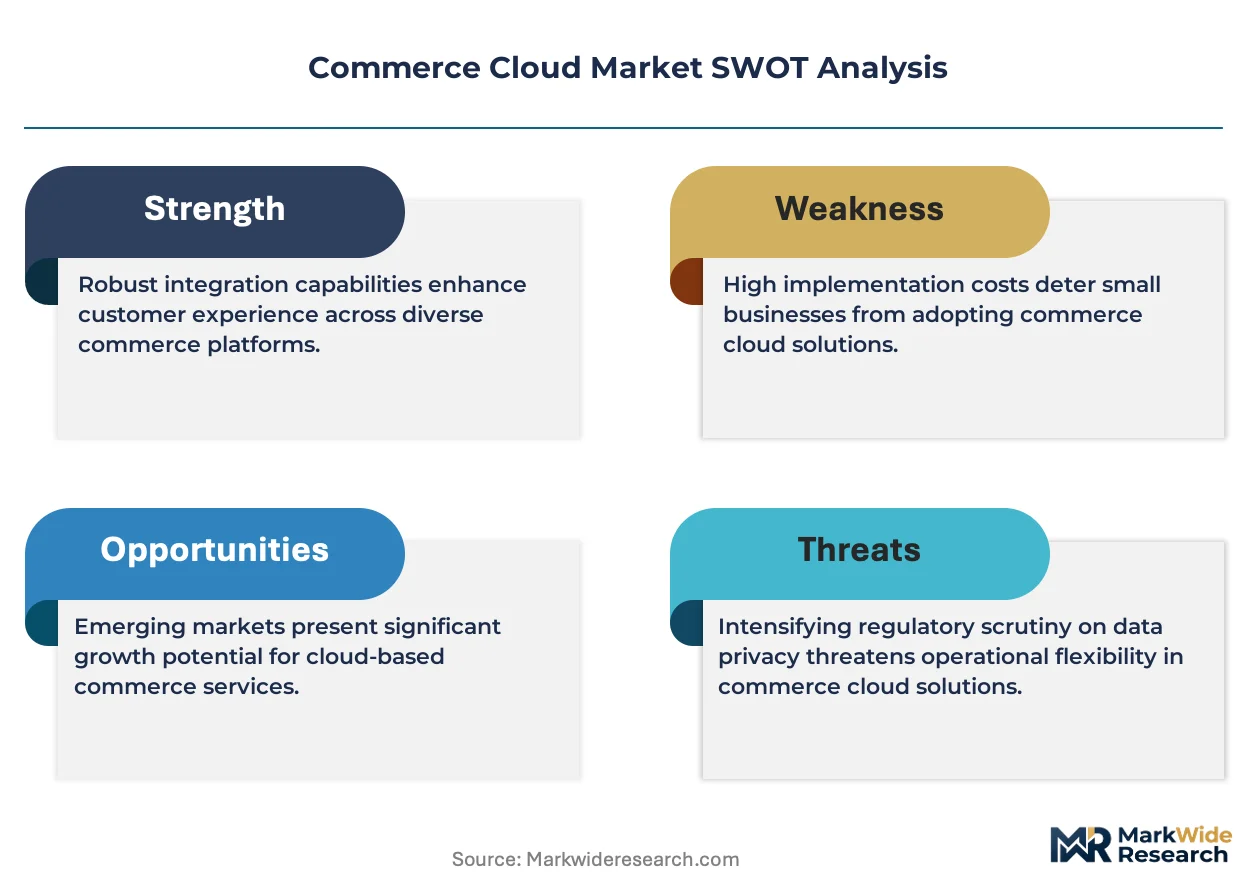
The conflict between globally standardized platform architectures and fragmented regional data sovereignty laws, like the EU's GDPR, is the central tension shaping the commerce cloud market. This forces vendors to balance scalability with the high cost of localized compliance.
Growth Catalysts
- Omnichannel Retail:Retailers require unified platforms to manage inventory and customer data across physical and online stores, driving adoption.
- API-First Architecture:Headless models offer developers flexibility to create custom user experiences, decoupling the front-end from back-end commerce functions.
- E-commerce in China:High-growth markets like China demand scalable, mobile-first platforms capable of handling massive transaction volumes and social commerce.
Market Restraints
- Integration Complexity:Connecting new commerce clouds with entrenched legacy ERP and CRM systems creates significant technical hurdles and implementation costs.
- Data Sovereignty Rules:Regulations like GDPR require region-specific data centers, increasing operational overhead and architectural complexity for global providers.
- Total Cost of Ownership:Beyond subscriptions, costs for customization, integrations, and specialized talent can make enterprise-grade platforms prohibitively expensive.
Strategic Opportunities
- B2B Commerce Digitization:The manufacturing and wholesale sectors represent an underpenetrated market for B2B platforms with features for complex pricing and quoting.
- Generative AI Personalization:Applying generative AI can create hyper-personalized shopping experiences, from unique product descriptions to individualized marketing campaigns.
- Social Commerce Integration:Developing deeper native integrations for in-app purchasing on platforms like TikTok and Instagram offers a direct sales channel.
Industry Challenges
- Specialized Talent Scarcity:A shortage of developers with expertise in specific commerce platforms and modern headless frameworks constrains implementation speed and quality.
- Escalating Cyber Threats:Commerce platforms are targets for data breaches, demanding continuous investment in security protocols and compliance with standards like PCI DSS.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commerce Cloud Market |
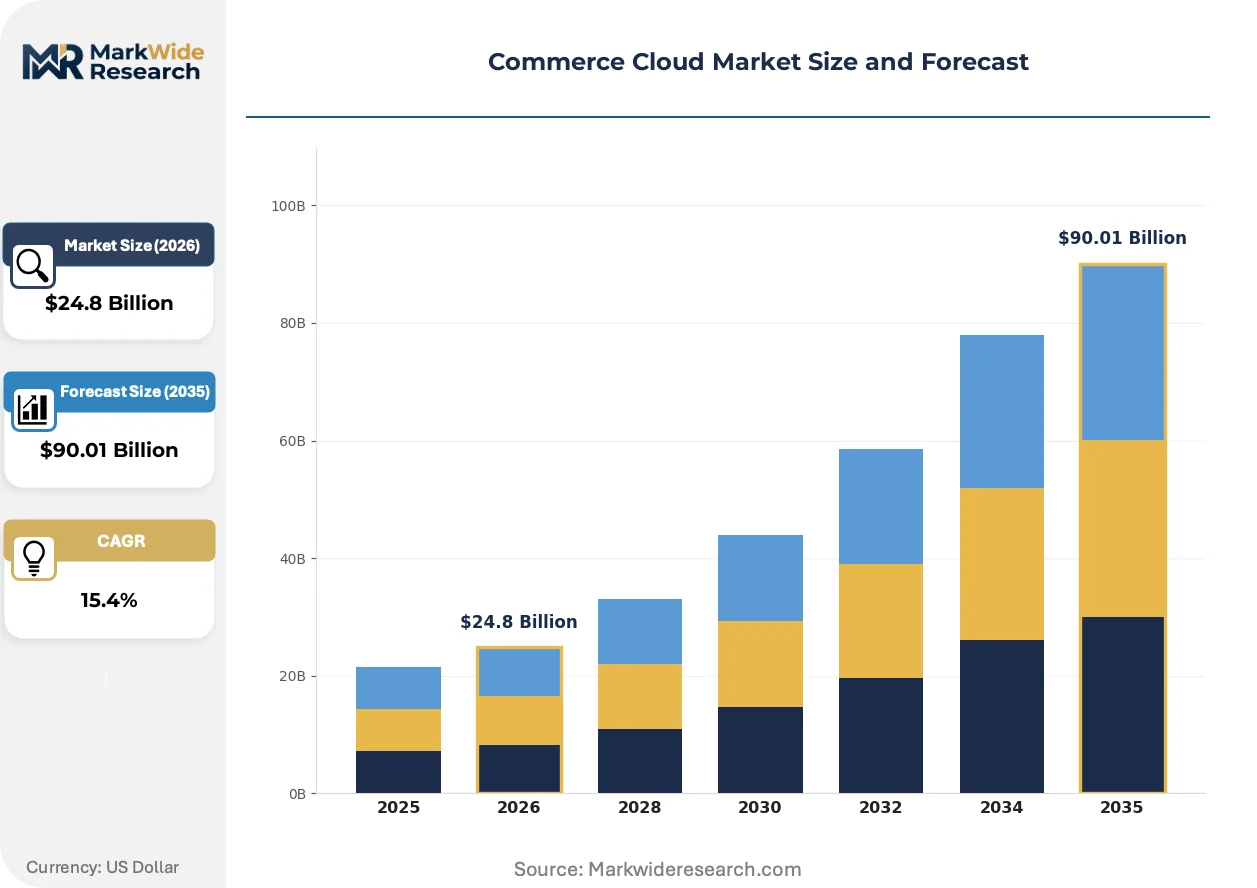
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $90.01 Billion |
| CAGR (2026 – 2036) | 15.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Subscription, Pay-As-You-Go, Freemium, Managed Services End User: Retailers, E-Commerce Platforms, Digital Agencies, Brand Owners Integration Level: Full Stack, Headless, API-First, Legacy Systems |
| Companies Covered | Salesforce.com, Inc., Shopify Inc., Oracle Corporation, SAP SE, Adobe, Inc., BigCommerce Pty. Ltd., IBM Corporation, Amazon Web Services, Inc., commercetools GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commerce Cloud Market Strategic Shifts & Innovations
Platform evolution is moving beyond monolithic applications toward intelligent, composable architectures. This shift prioritizes flexibility and content-driven experiences to meet increasingly complex consumer behaviors and regulatory demands.
Composable commerce allows businesses to assemble best-of-breed services via APIs instead of using a single suite. Large enterprises and digitally native brands are adopting this model to gain greater control over their technology stack. This approach is electrifying the market by enabling rapid innovation and challenging the dominance of all-in-one platforms.
New legislation like the European Union's AI Act introduces risk-based requirements for artificial intelligence systems in commerce. This forces vendors to audit algorithms for bias and ensure transparency in automated decisions like dynamic pricing. Platform providers serving EU clients are now re-engineering AI tools to meet these compliance standards.
Direct purchasing through social media is reshaping the customer journey. This disrupts reliance on brand websites, favoring platforms with seamless integrations into networks like TikTok. The social commerce model is most advanced in China but is quickly becoming standard for retailers in North America.
Commerce Cloud Market Segmentation
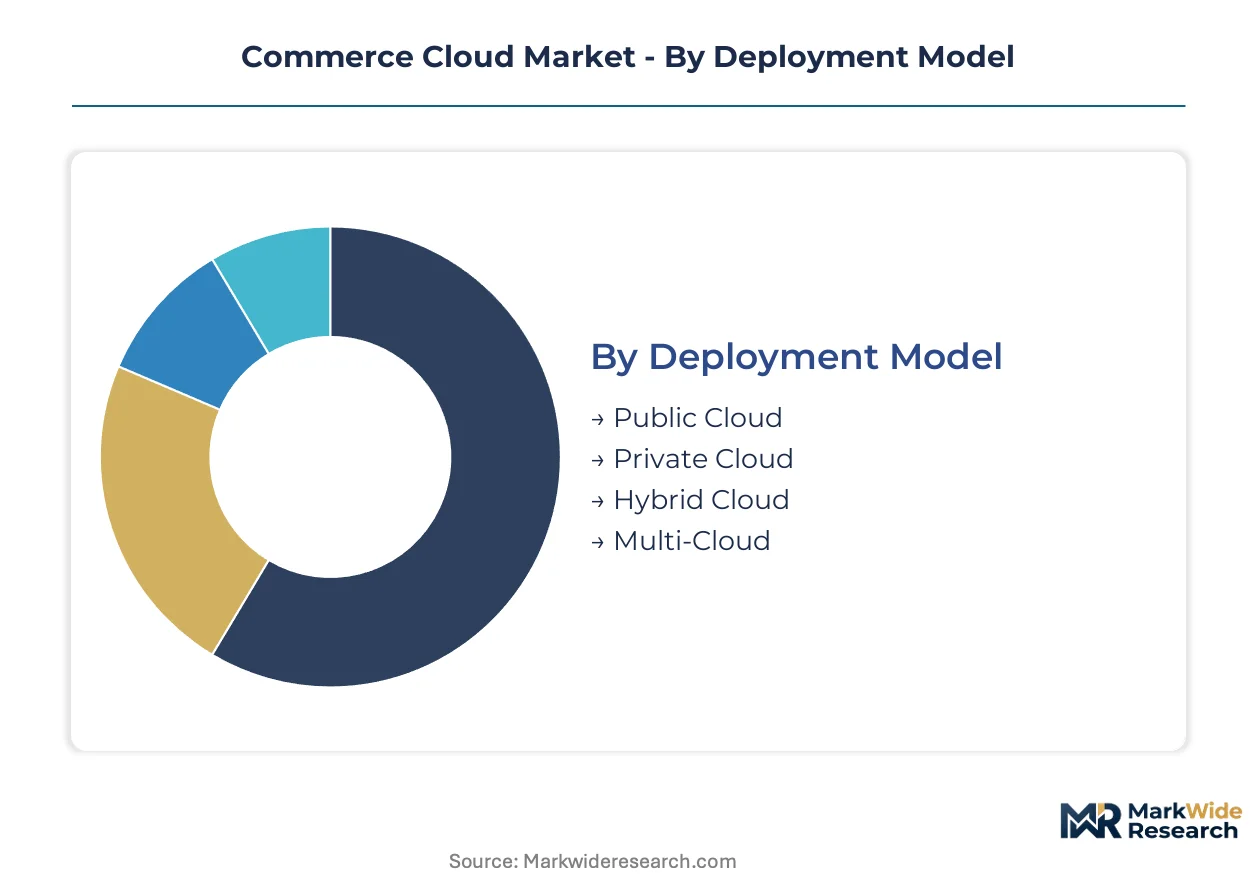
The Commerce Cloud market segmentation reflects diverse operational needs and strategic priorities across businesses adopting digital sales channels. Understanding these segments helps platform providers tailor solutions that align with specific infrastructure requirements, service expectations, and integration complexities.
Deployment Model:
The capital intensity of establishing and maintaining commerce cloud infrastructure heavily influences deployment model choices for enterprises.
- Public Cloud:This model leverages shared computing resources provided by third-party vendors, minimizing upfront hardware investment for businesses. Demand concentrates in high-growth e-commerce markets like China, where rapid scaling is essential for managing transaction volumes.
- Private Cloud:Dedicated infrastructure, either on-premises or hosted by a third party, offers enhanced security and customization for sensitive data and complex operations. European businesses often prefer private cloud options to meet stringent GDPR data residency requirements.
- Hybrid Cloud:This deployment blends public and private cloud environments, allowing businesses to manage sensitive data on private infrastructure while utilizing public cloud for scalable workloads. Hybrid solutions provide flexibility for organizations with fluctuating demand.
- Multi-Cloud:Utilizing multiple public cloud services from different providers mitigates vendor lock-in and enhances resilience against service outages. Businesses adopt multi-cloud strategies for optimizing performance and cost across diverse geographic regions.
Most installed capacity flows through Public Cloud. Expansion is steepest in Private Cloud.
Service Type:
The value proposition and cost structure for commerce cloud services vary significantly based on the chosen service type.
- Subscription:Businesses pay a recurring fee for access to platform features, updates, and support, providing predictable operational expenditure. This model is widely adopted by small to medium-sized businesses seeking comprehensive, ready-to-use solutions.
- Managed Services:Third-party providers handle the day-to-day operations, maintenance, and optimization of the commerce cloud platform, allowing businesses to focus on core activities. Large enterprises with complex IT environments increasingly rely on managed services for specialized support and compliance.
- Pay-As-You-Go:Customers pay only for the resources and services they consume, offering flexibility for businesses with variable demand patterns. Startups and seasonal retailers frequently utilize this model to control costs.
- Freemium:A basic version of the commerce cloud platform is offered for free, with advanced features available at a premium. This model attracts new users and helps small businesses enter the e-commerce landscape.
The predominant service type remains Subscription, reflecting its widespread adoption across various business sizes. However, Managed Services are gaining share fastest among large corporations.
End User:
The operational focus and specific requirements of different end-user segments drive distinct feature sets and platform development in the commerce cloud market.
- Retailers:These businesses leverage commerce cloud platforms to manage online storefronts, inventory, and customer interactions across multiple channels. Retailers demand robust omnichannel capabilities for seamless customer experiences, integrating physical and digital touchpoints.
- Brand Owners:Companies that manufacture their own products use commerce cloud to establish direct-to-consumer (D2C) sales channels, controlling brand messaging and customer relationships. Brand owners prioritize personalization and content-driven commerce to differentiate their offerings.
- E-Commerce Platforms:These entities provide marketplaces or infrastructure for other businesses to sell products online, requiring highly scalable and customizable cloud solutions. E-commerce platforms focus on robust API integrations and multi-vendor management tools.
- Digital Agencies:Agencies utilize commerce cloud platforms to build and manage online stores for their clients, demanding flexible tools and extensive integration capabilities. Agencies value platforms that support rapid development and customization.
The market dynamics favor solutions tailored for Retailers, while Brand Owners represent an emerging growth vector.
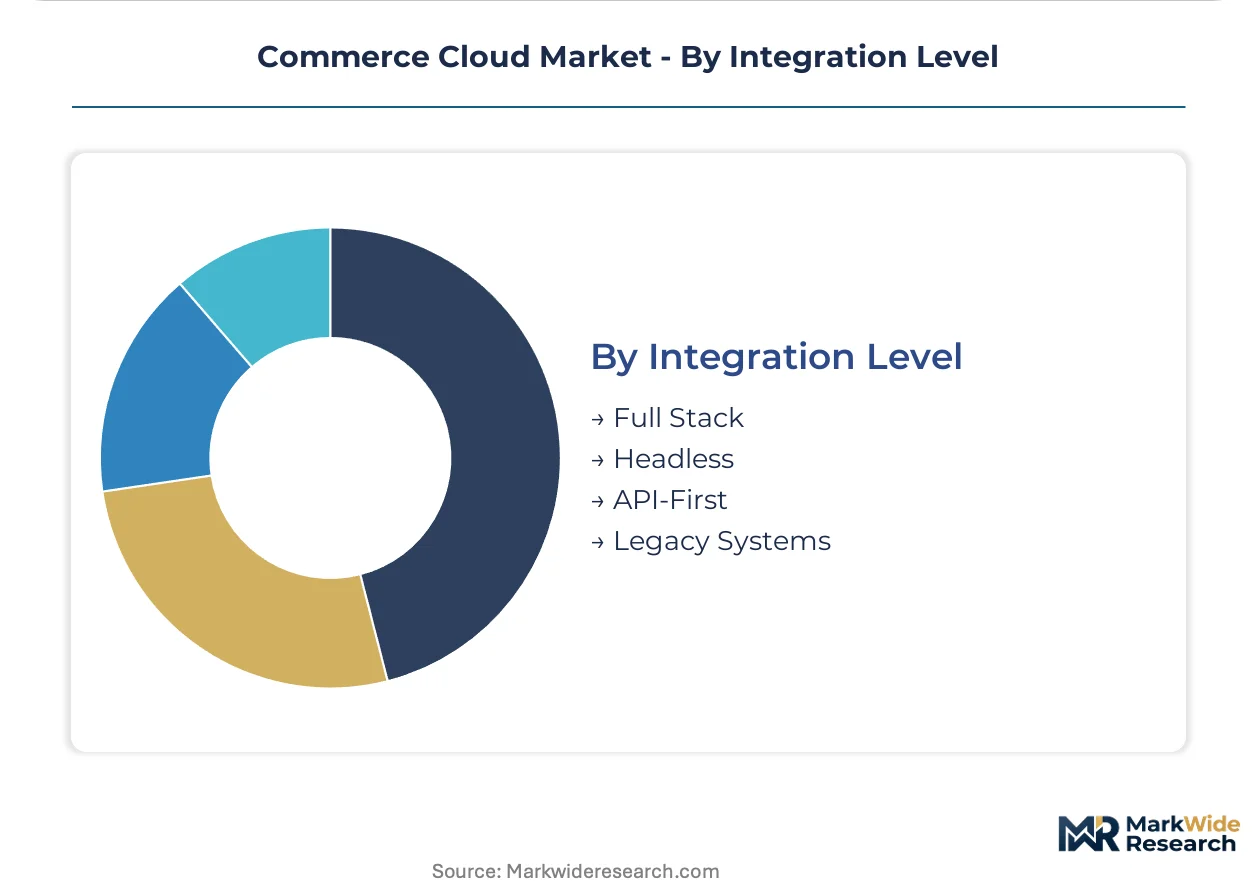
Integration Level:
The architectural flexibility required to connect commerce cloud solutions with existing enterprise systems defines various integration levels.
- Headless:This architecture separates the front-end user interface from the back-end commerce functionality, providing developers with maximum flexibility to create custom shopping experiences. Digitally native brands adopt headless solutions for unique customer journeys and rapid content deployment.
- API-First:Platforms designed with APIs as the primary interface enable seamless integration with various third-party systems and custom applications. Businesses seeking composable commerce solutions prioritize API-first designs for modularity and future-proofing.
- Full Stack:These monolithic platforms provide an all-in-one solution, including both front-end and back-end functionalities, offering ease of deployment for businesses preferring a single vendor. Small to medium-sized businesses often choose full-stack platforms for their comprehensive, out-of-the-box features.
- Legacy Systems:Integrating new commerce cloud platforms with existing, older enterprise resource planning (ERP) or customer relationship management (CRM) systems presents significant technical challenges. Businesses with substantial investments in legacy infrastructure require specialized connectors and integration services.
Headless solutions offer significant customization, enabling businesses to differentiate their online presence. The demand for API-First approaches is accelerating among enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States' highly skilled tech workforce anchors significant commerce cloud innovation, driving platform development for global markets. This talent concentration fuels advancements in composable architectures and AI-driven personalization. Other key regions also demonstrate distinct market dynamics and regulatory influences.
United States
Demand for unified omnichannel platforms and API-first solutions drives commerce cloud adoption across US retailers. The US Federal Trade Commission (FTC) enforces consumer protection directives influencing data handling and privacy features. Silicon Valley continues to lead in platform innovation, fostering startups specializing in headless commerce frameworks.
Germany
Germany's robust manufacturing and wholesale sectors generate strong demand for B2B commerce platforms with complex pricing capabilities. The EU's General Data Protection Regulation (GDPR) mandates strict data residency and privacy controls for all platform providers. Berlin's vibrant startup ecosystem actively develops specialized solutions addressing localized compliance requirements.
China
China's massive e-commerce market requires highly scalable, mobile-optimized platforms capable of handling immense transaction volumes and social commerce. China's GB standards for e-commerce fundamentally shape platform features and cross-border data flows. The Yangtze River Delta region, including Shanghai, acts as a hub for social commerce integration and advanced logistics solutions.
India
Digital transformation initiatives across Indian enterprises are fueling the adoption of subscription-based and managed commerce cloud services. The country's national payment regulators, like the Reserve Bank of India (RBI), influence payment gateway integrations and data localization. Bengaluru's booming tech hub sees significant investment in cloud infrastructure and specialized talent development.
Japan
Japanese enterprises prioritize mobile-optimized solutions and robust security features for their growing online retail presence. The Ministry of Economy, Trade and Industry (METI) promotes digital transformation initiatives, impacting cloud adoption strategies. Tokyo's dense urban retail landscape drives innovation in physical-digital integration and personalized customer experiences.
Commerce Cloud Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists for market share in the commerce cloud sector, creating a dynamic competitive environment. The market structure exhibits a tiered consolidation, with large technology vendors offering comprehensive suites and niche players providing specialized, modular solutions. Strategic archetypes include platform integrators, experience providers, and infrastructure specialists, each targeting distinct customer needs. Companies pursue competitive moves like portfolio diversification and strategic partnerships to expand their ecosystem reach and enhance their service offerings.
Within the platform integrator archetype, Salesforce.com, Inc. represents a comprehensive solution provider, leveraging its extensive CRM ecosystem for deeply integrated B2B and B2C commerce. Shopify Inc. exemplifies accessible, scalable platforms, anchoring the small to medium-sized business segment with its focused offerings and ease of use. Adobe, Inc. occupies a position as an experience provider, differentiating through its Experience Cloud, which supports content-driven commerce and advanced personalization capabilities. These leading entities collectively demonstrate the market's segmentation by customer size and strategic focus, influencing innovation across the sector and setting industry benchmarks.
| Leading Market Players |
|---|
| Salesforce.com, Inc. |
| Shopify Inc. |
| Oracle Corporation |
| SAP SE |
| Adobe, Inc. |
| BigCommerce Pty. Ltd. |
| IBM Corporation |
| Amazon Web Services, Inc. |
| commercetools GmbH |
| Others |
Cost & Logistics Intelligence
Highly skilled tech workforces in the United States and India create distinct labor-cost differentials, directly influencing the pricing-tier spreads for commerce cloud solutions. This talent concentration impacts service delivery costs across various deployment and service models.
Pricing Analysis
Bundled full-stack solutions contrast with unbundled API-first and headless offerings, creating diverse pricing structures across the commerce cloud market. Subscription-based models remain dominant, providing predictable operational expenditure for many businesses. Price differentiation stems from customization levels and the extent of managed services provided. Pricing softness stems from increasing competition among platform providers, while small to medium-sized businesses demonstrate the highest price sensitivity.
Supply Chain Analysis
Workforce availability for cloud infrastructure development concentrates in the United States, India, and Germany, influencing the geographic distribution of data centers. Commerce cloud solutions rely on robust data center infrastructure and specialized software licenses as key inputs. Regulatory restrictions, such as the EU's GDPR, introduce a structural risk by mandating region-specific data residency. Distribution runs through direct SaaS subscriptions and an expanding network of digital agency partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commerce cloud market represents a compelling margin-expansion story, driven by the shift towards composable architectures that reduce vendor lock-in and optimize operational costs. Advanced AI personalization capabilities further allow for premium service differentiation.
For Market Incumbents: Acquire specialist firms offering headless commerce frameworks to counter the threat from agile pure-play competitors. Deepen platform integrations with social commerce channels to maintain direct sales control. Invest heavily in Generative AI R&D to deliver hyper-personalized experiences and differentiate from commoditized offerings. Expand managed services to address integration complexity for large enterprises.
For New Entrants and Emerging Players: Price-point gaps exist between premium enterprise suites and basic freemium offerings, creating opportunities for value-added solutions. Target the underpenetrated B2B commerce segment with specialized features for complex pricing and quoting. Focus on API-first platforms offering superior flexibility for mid-market businesses transitioning to composable architectures. Offer compliance-as-a-service to address stringent data sovereignty rules like GDPR.
For Investors and Strategic Acquirers: Technology conglomerates are the most active acquirers in this space, seeking to expand their commerce cloud portfolios. Long-term viability for the market is strong, with sustained growth projected over the next decade. Identify niche providers specializing in generative AI personalization or deep social commerce integrations as prime acquisition targets. The signal to watch is the accelerating adoption of composable commerce models among digitally native brands.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Seamlessly connects commerce functions with existing CRM and ERP systems for unified operations. |
| Generative AI Development | Creates hyper-personalized shopping experiences and automated content generation, enhancing customer engagement. |
| B2B Feature Expansion | Caters to complex pricing, quoting, and order management needs of manufacturing and wholesale sectors. |
| Social Commerce Partnership | Enables direct in-app purchasing on major social media platforms, capturing new sales channels. |
| Data Sovereignty Compliance | Ensures adherence to regional regulations like GDPR, mitigating legal risks and fostering trust. |
Research Approach
Bottom-up retailer and brand owner modeling reconciled against top-down platform vendor tracking forms the analytical core of this study. Primary interviews with CTOs, IT procurement officers, and digital agency leads provide qualitative insights. Secondary validation draws from SEC filings, e-commerce federation reports, and government trade statistics. This approach ensures robust data triangulation.
Historical trendline analysis projects market evolution across the analysis window, integrating growth drivers and restraints. Segmentation dimensions modeled include deployment model, service type, end user, integration level, and regional adoption patterns. Compound annual growth rates derive from a weighted average of these segments. Key forecast inputs include e-commerce penetration rates and enterprise digitization budgets.
Caveats apply where new AI legislation, macroeconomic shifts, or disruptive technological breakthroughs could materially shift the outlook. Forecasts reflect assumptions documented at the time of publication. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud Continuum Market
Cloud Computing
GPU Virtualization Market
Cloud Computing
Asia Pacific Cloud Computing Market
Cloud Computing
North America Healthcare Cloud Computing Market
Cloud Computing
Platform As a Service (Paas) Market
Cloud Computing
Hybrid Cloud Services Market
Cloud Computing
Distributed Cloud System Market
Cloud Computing
Cloud Orchestration Market
Cloud Computing
Middle East and Africa Cloud Infrastructure Services Market
Cloud Computing
Public Finance Cloud Market
Cloud Computing
Global Mobile Cloud Market
Cloud Computing
Cloud Management Market
Cloud Computing
Government Cloud Market
Cloud Computing
China Cloud Computing Market
Cloud Computing
Cloud Load Balancers Market
Cloud Computing
Germany Cloud Computing Market