
 E-Commerce Technology Market | 2026-2036
E-Commerce Technology Market Size, Share, and Industry Trends Forecast 2026-2036
E-Commerce Technology Market Analysis
Direct-to-consumer storefront infrastructure is rewriting how brands reach buyers without intermediary retailers. Shopify leverages its merchant ecosystem to anchor subscription revenue across North America. Adobe competes through creative-to-commerce workflow integration that sustains enterprise retention. Salesforce dominates in CRM-linked personalization that extends average contract values for large retailers.
E-commerce technology encompasses software systems, payment architectures, and data platforms that enable online transaction processing, inventory synchronization, and customer analytics across digital sales channels. These systems typically operate through API-first architectures with sub-second latency requirements for checkout flows and real-time inventory visibility. Cloud-based deployment leads structural growth as retailers abandon on-premises data centers for elastic infrastructure. Payment gateway technology captures concentrated margin pools due to network effects and regulatory compliance burdens. SaaS delivery models now outpace hybrid installations among mid-market wholesalers seeking faster implementation cycles.
The Federal Trade Commission and state attorneys general in the United States scrutinize platform fees and data usage, while the European Union's Digital Services Act and GDPR impose algorithmic transparency and consent management obligations that shape product roadmaps. India's Digital Personal Data Protection Act and China's Personal Information Protection Law add compliance layers for cross-border marketplace operators. Stakeholders must monitor fragmentation between regional data sovereignty regimes and decide whether to architect region-specific instances or pursue unified global platforms with localized compliance modules.
Market Dynamics
Cloud-native commerce infrastructure is compressing deployment timelines from months to days while forcing legacy platform vendors to re-architect around API-first modularity. Retailers now demand sub-second checkout latency and real-time inventory synchronization across channels, reshaping vendor competitive priorities.
Growth Catalysts
- GDPR and state-level privacy statutes:Data localization mandates in Europe and California are accelerating investment in consent management platforms and region-specific data architectures.
- Headless commerce architectures:Decoupled frontend-backend systems enable retailers to deploy custom storefronts across mobile, social, and IoT channels without replatforming.
- Omnichannel inventory synchronization:Real-time visibility requirements across warehouse, store, and dropship nodes are pulling mid-market retailers toward cloud-native order management systems.
Market Restraints
- Payment processor concentration:Network effects and PCI-DSS compliance burdens limit viable gateway options, squeezing margin for smaller marketplace operators.
- Cloud infrastructure cost volatility:Elastic compute and egress pricing from hyperscalers creates unpredictable operating expense for high-transaction-volume merchants.
- Cross-border data friction:India's Digital Personal Data Protection Act and China's Personal Information Protection Law impose localization requirements that fragment global platform architectures.
Strategic Opportunities
- Social commerce integration:Live-streaming checkout and in-app purchasing on TikTok and Instagram are opening direct-to-consumer channels in Southeast Asian markets.
- AI-driven personalization engines:Convergence of predictive analytics and generative content tools enables dynamic pricing and individualized product discovery at scale.
- Open banking payment rails:PSD2-mandated account-to-account transfers in Europe are bypassing traditional card networks for lower-fee checkout options.
Industry Challenges
- Legacy ERP integration complexity:On-premises inventory and finance systems require custom middleware development, extending implementation timelines and failure rates.
- DevOps talent scarcity:Shortage of engineers skilled in Kubernetes orchestration and event-driven microservices architecture limits platform scaling velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Commerce Technology Market |
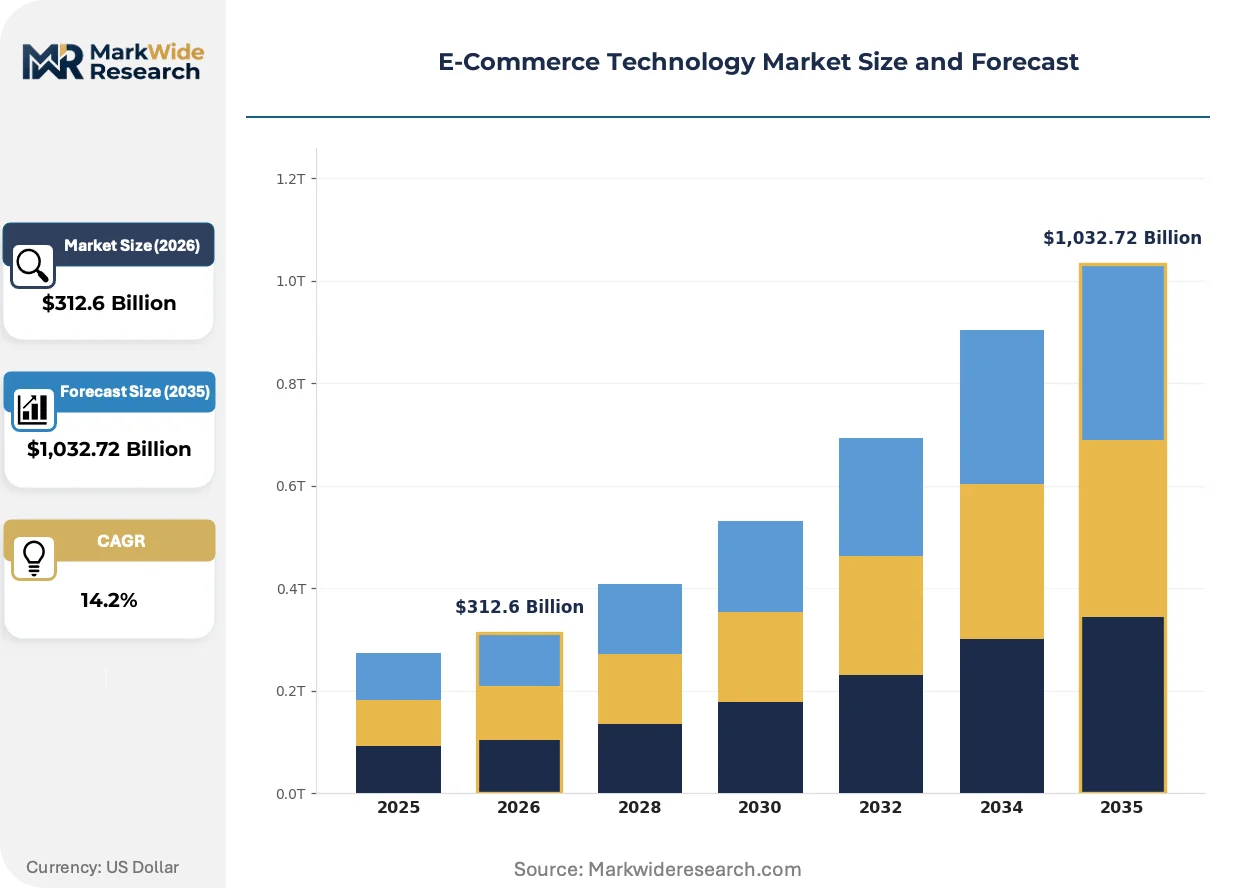
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $1,032.72 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Payment Gateway, Shopping Cart, Inventory Management, Analytics Tools Deployment: Cloud-based, On-Premises, Hybrid, SaaS End User: Retailers, Wholesalers, Marketplaces, Brands Service Type: Consulting, Implementation, Maintenance, Support |
| Companies Covered | Shopify, Adobe, Salesforce, SAP, BigCommerce, VTEX, Shift4, Lightspeed, HCL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Commerce Technology Market Emerging Trajectories
Composable commerce stacks are fragmenting monolithic platforms into interchangeable components, letting retailers swap vendors for cart, search, or fulfillment functions without full replatforming. This modularity is redistributing value capture across the software layer.
Edge computing nodes deployed at CDN points of presence are rendering obsolete centralized cloud processing for checkout flows. Direct-to-consumer brands operating high-velocity flash sales are adopting these distributed architectures to maintain sub-100-millisecond latency during traffic spikes. The shift compresses infrastructure costs while raising the bar for platform performance guarantees.
The EU Digital Services Act mandates algorithmic transparency for product recommendation engines and targeted advertising systems. Marketplace operators must now disclose ranking parameters and provide ad archive access, increasing compliance engineering overhead. Fashion and electronics verticals with heavy reliance on personalized discovery are restructuring data pipelines to meet audit requirements.
Merchant procurement of commerce technology is fragmenting from suite-based contracts toward best-of-breed component selection. Retailers now assemble storefronts from specialized vendors for search, reviews, and subscription billing rather than accepting bundled functionality. This pattern is most pronounced among digitally native brands in Germany and the Netherlands with in-house engineering teams capable of managing integration complexity.
E-Commerce Technology Market Segmentation
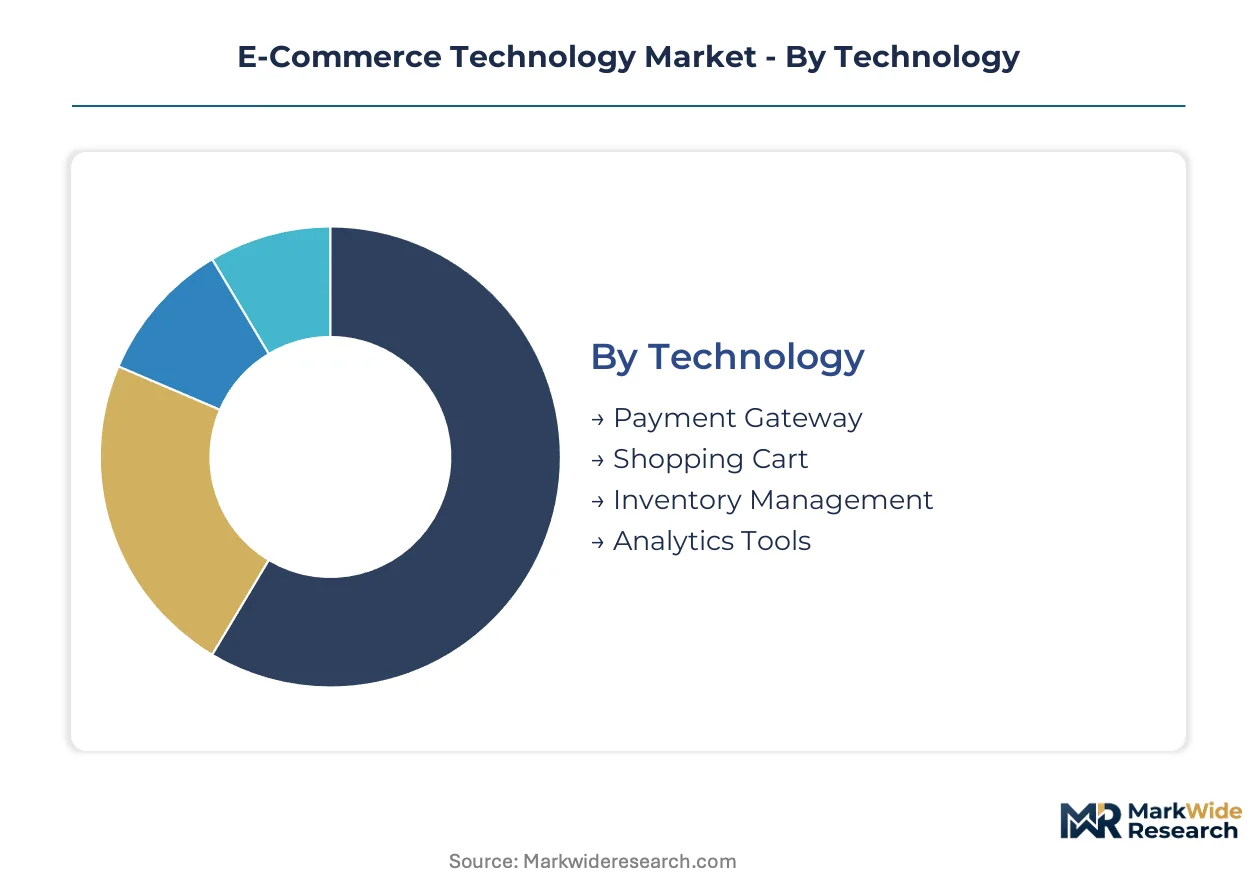
Technology choices in e-commerce infrastructure directly determine checkout latency, data sovereignty compliance, and total cost of ownership for merchants scaling across multiple jurisdictions. Deployment architecture decisions lock in operational flexibility for years while service type procurement patterns reveal whether retailers prioritize speed-to-market or long-term platform control.
Technology:
Cost tier structures within the technology layer separate high-margin payment orchestration from commoditized inventory synchronization tools.
- Payment Gateway:PCI-DSS certified transaction processing engines with tokenization and fraud scoring subsystems. Demand concentrates among direct-to-consumer brands in Germany and the Netherlands seeking PSD2-compliant account-to-account rails. Regulatory fragmentation between EU Open Banking and US Nacha standards forces dual-stack architectures for cross-border operators.
- Shopping Cart:Headless checkout engines with API-first cart persistence and abandoned-recovery automation. Mid-market retailers in California and New York are migrating from monolithic suites to decoupled frontends that support TikTok and Instagram commerce integrations.
- Inventory Management:Real-time stock visibility across warehouse, store, and dropship nodes with event-driven replenishment triggers.
- Analytics Tools:Customer journey attribution and predictive demand forecasting platforms with GDPR-compliant data pipelines.
Payment Gateway holds installed capacity. Shopping Cart is rotating up the share rankings.
Deployment:
Application requirements for elastic scaling and sub-second latency are pushing merchant selections toward cloud-native infrastructure over captive data centers.
- Cloud-based:Hyperscaler-hosted commerce workloads with auto-scaling compute and managed database services. Omnichannel retailers in France and Spain are abandoning on-premises installations to meet peak-traffic elasticity requirements during flash sales events.
- SaaS:Multi-tenant platform subscriptions with pre-integrated payment, tax, and shipping modules. Digitally native brands across Italy and Poland favor rapid implementation cycles over customization depth.
- Hybrid:Sensitive transaction data retained on-premises with customer-facing storefronts in public cloud edge nodes.
- On-Premises:Self-managed infrastructure in merchant-owned facilities with full data sovereignty control.
Cloud-based commands current deployment volumes. SaaS is climbing the fastest among mid-market entrants.
End User:
Customer type determines feature complexity, with marketplaces requiring multi-tenant architectures that brands and single-merchant retailers do not.
- Marketplaces:Multi-vendor platforms with seller onboarding, commission engines, and dispute arbitration workflows. Operators across Southeast Asia are integrating live-streaming checkout to capture social commerce growth.
- Brands:Direct-to-consumer storefronts with subscription billing and loyalty program integration. European fashion and electronics verticals are restructuring data pipelines to meet EU Digital Services Act algorithmic transparency mandates.
- Retailers:Multi-channel merchants with POS integration and buy-online-pickup-in-store fulfillment orchestration.
- Wholesalers:B2B order portals with tiered pricing, volume discounts, and purchase approval workflows.
Marketplaces dominate transaction volume concentration. Brands are gaining share fastest as direct channels displace wholesale dependency.
Service Type:
Margin capture in professional services varies dramatically by delivery model, with implementation commanding premium pricing against commoditized support contracts.
- Implementation:Platform configuration, data migration, and ERP integration services with fixed-fee or time-and-materials structures. System integrators in the United Kingdom and Germany are building specialized practices around composable commerce stack assembly.
- Consulting:Commerce strategy, organizational design, and technology roadmap advisory for enterprise transformations.
- Maintenance:Ongoing platform updates, security patching, and performance optimization retainers.
- Support:Tiered helpdesk services with SLA-governed response times for merchant technical issues.
Implementation holds the revenue concentration. Consulting is rotating up the share rankings as replatforming cycles accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that in India by a substantial margin, reflecting divergent infrastructure maturity and regulatory burden. European markets occupy a middle tier where GDPR compliance costs compress margins but sustain premium service differentiation.
United States
Direct-to-consumer brand proliferation and omnichannel retailer consolidation drive platform procurement in California and New York. The FTC scrutinizes platform fee structures and data usage practices, reshaping vendor contract terms. Seattle and San Francisco anchor cloud-native commerce development clusters where hyperscaler partnerships concentrate.
Germany
PSD2-mandated open banking adoption accelerates account-to-account payment rail integration among mid-market merchants. The Federal Financial Supervisory Authority enforces strict Strong Customer Authentication protocols that elevate technical compliance thresholds. Berlin and Munich host dense concentrations of composable commerce system integrators serving fashion and electronics verticals.
China
Live-streaming commerce infrastructure investment surges as social platform operators expand transaction capabilities. The Personal Information Protection Law imposes cross-border data localization requirements that fragment global platform architectures. Shenzhen and Hangzhou dominate edge computing node deployment for sub-100-millisecond checkout latency during flash sales events.
United Kingdom
Post-Brexit regulatory divergence from EU standards creates dual compliance obligations for marketplace operators serving both markets. The Competition and Markets Authority examines platform power concentration in digital advertising and recommendation algorithms. London anchors fintech-commerce convergence clusters where open banking payment orchestration specialists proliferate.
India
Digital Personal Data Protection Act implementation accelerates consent management platform adoption among cross-border marketplace operators. The Reserve Bank of India regulates payment aggregator licensing, constraining gateway provider market entry. Bangalore and Mumbai concentrate SaaS commerce platform development serving domestic digitally native brands.
E-Commerce Technology Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain, supplying interchangeable modules for cart, search, and fulfillment functions. The vendor landscape exhibits moderate consolidation at the enterprise tier with fragmentation proliferating among mid-market component providers. Three archetypes dominate: full-stack suite vendors, headless commerce infrastructure specialists, and payment-centric platform operators. Competitive moves center on API-first re-architecting of legacy stacks and strategic partnerships with hyperscaler cloud providers.
Within the platform integrator tier, Shopify and Salesforce occupy positions exemplifying divergent strategic vectors—merchant ecosystem subscription anchoring versus CRM-linked personalization extension. Adobe represents the creative-to-commerce workflow integration archetype. SAP anchors the enterprise ERP-anchored commerce segment where legacy system integration complexity sustains incumbent positioning. These three entities collectively illustrate the competitive tension between vertical integration depth and modular interoperability breadth.
| Leading Market Players |
|---|
| Shopify |
| Adobe |
| Salesforce |
| SAP |
| BigCommerce |
| VTEX |
| Shift4 |
| Lightspeed |
| HCL |
| Others |
Supply Flow & Price Mechanics
Hyperscaler cloud infrastructure concentration in the United States anchors margin capture downstream, with Amazon Web Services, Google Cloud, and Microsoft Azure controlling elastic compute pricing that cascades through SaaS commerce platform costs and ultimately determines merchant total cost of ownership.
Pricing Analysis
Configured-to-order implementation pricing commands substantial premiums over standard SaaS subscription tiers, with system integrators in Germany and the United Kingdom capturing margin through composable commerce stack assembly services. Three-tier pricing structure across premium, standard, and economy levels separates enterprise multi-tenant deployments from mid-market pre-integrated bundles and entry-level self-serve offerings. Price differentiation hinges on API call volume thresholds and PCI-DSS certification tier. Cost compression in the standard tier is intensifying because hyperscaler egress pricing volatility squeezes platform operators. Digitally native brands with in-house engineering teams exhibit highest price sensitivity, while enterprise retailers with legacy ERP integration requirements show lowest.
Supply Chain Analysis
Export control regimes limiting semiconductor and advanced chip flows from Taiwan and South Korea constrain edge computing node deployment for sub-100-millisecond checkout latency requirements. Cloud infrastructure draws from hyperscaler data centers concentrated in the United States, Ireland, and Singapore, with backup dependencies on Japanese and German facility expansions. Single-source vulnerability runs through Taiwan Semiconductor Manufacturing capacity for merchant hardware payment terminals. Distribution runs through direct hyperscaler marketplaces and systems integrator channel partners serving vertical-specific merchant segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward mid-market retailers with in-house DevOps capabilities, as merchant procurement fragments from suite-based contracts toward best-of-breed component selection across specialized vendors.
For Market Incumbents: Entrench API-first modularity through strategic hyperscaler partnerships that secure preferential compute pricing, while accelerating consent management platform development to preempt GDPR and state-level privacy statute enforcement actions. Vertical integration into payment orchestration layers defends margin against gateway concentration pressures. For New Entrants and Emerging Players: Mid-market fashion and electronics retailers in Germany and the Netherlands with composable commerce integration needs represent the most penetrable entry point, given their procurement shift away from monolithic suites. Southeast Asian social commerce infrastructure for live-streaming checkout offers secondary white-space expansion. Lead with headless shopping cart specialization that decouples from legacy ERP complexity. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed payment gateway operators facing PCI-DSS compliance burden escalation and processor concentration margin squeeze. Long-term viability centers on platform consolidation plays with sticky merchant ecosystems rather than point-solution vendors. Watch hyperscaler partnership exclusivity announcements as inflection indicators for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Re-architecture | Enables Shopify and Salesforce to retain enterprise merchants demanding sub-second checkout latency. |
| Hyperscaler Cloud Partnership | Secures elastic compute pricing advantages for Adobe and SAP serving high-transaction-volume retailers. |
| Consent Management Platform Acquisition | Addresses GDPR and Digital Services Act compliance overhead for marketplace operators in Europe. |
| Headless Commerce Specialist Purchase | Captures mid-market retailer procurement shift toward decoupled frontend-backend architectures. |
| Social Commerce Infrastructure Buildout | Positions VTEX and BigCommerce for TikTok and Instagram commerce integration in Southeast Asia. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with CTOs at direct-to-consumer brands, platform engineers at SaaS commerce providers, integration specialists at systems integrators, and procurement officers at omnichannel retailers. Secondary validation drew from SEC filings, hyperscaler capex disclosures, App Annie mobile commerce transaction data, and EU Digital Services Act implementation guidance documents. Bottom-up merchant spend estimates and top-down platform revenue analysis were triangulated across deployment model, organization size, vertical specialization, and regional adoption pattern dimensions.
Calibration against historical platform adoption curves and regulatory implementation timelines anchored the analytical framework across the projection horizon. Segmentation modeling incorporated technology layer, deployment architecture, end-user category, and service type procurement patterns. CAGRs were derived from elasticity-adjusted spend trajectories and vendor contract value expansion rates. Forecast inputs included cloud infrastructure cost volatility indices and cross-border data localization compliance burden estimates.
Practitioners should monitor hyperscaler pricing announcements, payment processor licensing actions by the Reserve Bank of India, and EU algorithmic transparency enforcement patterns for early signals of forecast deviation. Material shifts in cross-border data sovereignty regime fragmentation or PCI-DSS certification requirement changes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Alcohol E-Commerce Market
E-Commerce Solutions
United Arab Emirates E-Commerce Market
E-Commerce Solutions
Slovakia E-Commerce Market
E-Commerce Solutions
Turkey E-Commerce Market
E-Commerce Solutions
UAE Q-Commerce Industry Market
E-Commerce Solutions
South Korea Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
Egypt E-Commerce Market
E-Commerce Solutions
Online to Offline Commerce Market
E-Commerce Solutions
Quick Commerce Market
E-Commerce Solutions
North Macedonia E-Commerce Market
E-Commerce Solutions
E-Commerce Ecosystem Market
E-Commerce Solutions
C2C E-Commerce Market
E-Commerce Solutions
South Korea E-Commerce Market
E-Commerce Solutions
E-Commerce Buy Now Pay Later Market
E-Commerce Solutions
Malaysia E-Commerce Market
E-Commerce Solutions
Oman E-Commerce Market