
 Vietnam E-Commerce Market | 2026-2036
Vietnam E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam E-Commerce Market Outlook
Premium fulfillment tier is reorganizing buyer expectations across Vietnamese e-commerce. Shopee Pte. Ltd. leverages its integrated logistics arm to guarantee next-day delivery in tier-one cities. Tiki Corporation anchors its market position through captive warehousing and authentic product guarantees. Lazada South East Asia Pte. Ltd. competes via Alibaba-backed cross-border sourcing and flash-sale mechanics.
Vietnam e-commerce denotes digitally mediated transactions between buyers and sellers executed through websites, mobile applications, or social commerce interfaces, relying on electronic payment rails, order management systems, and last-mile distribution networks to move goods from merchant inventory to consumer doorsteps. Online marketplaces dominate transaction volume by aggregating third-party merchants under unified discovery and checkout layers, while B2C direct-to-consumer channels capture margin pools through brand-controlled pricing and customer data ownership. Electronics and apparel lead product category spend due to high SKU density and standardized return policies, though home and living segments are gaining traction as visual merchandising tools improve.
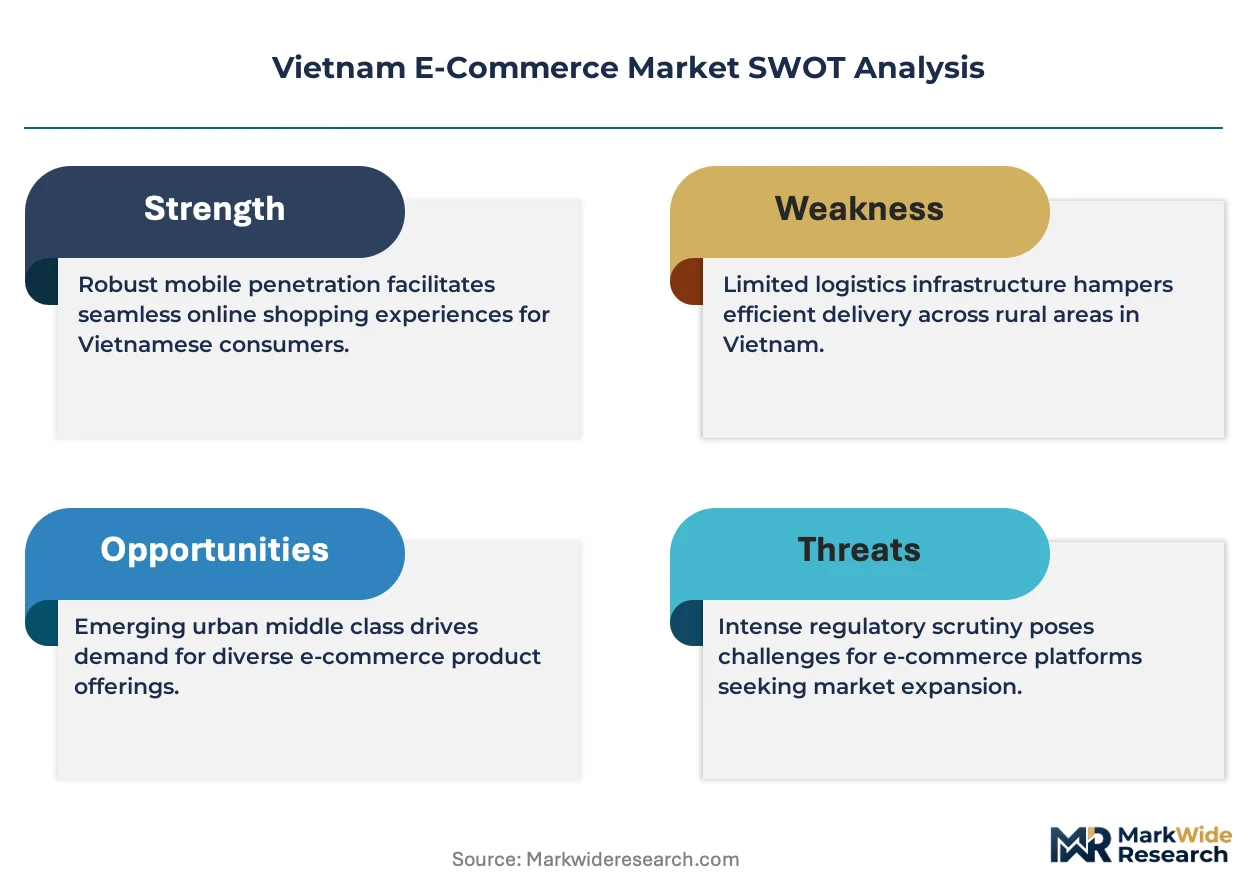
Vietnam's Ministry of Industry and Trade enforces Decree 85/2021/ND-CP, which mandates platform registration, consumer complaint resolution timelines, and data localization for foreign e-commerce operators. The State Bank of Vietnam governs e-wallet licensing and interoperability standards under its fintech regulatory framework, shaping how payment method segments evolve. Stakeholders must monitor whether enforcement capacity keeps pace with cross-border marketplace growth and whether domestic platforms can secure preferential treatment in data governance rules.
Market Dynamics
Decree 85/2021/ND-CP enforcement is compressing platform compliance timelines while rural logistics networks simultaneously expand fulfillment reach into previously unserved provinces. This dual pressure—regulatory tightening on one flank, geographic expansion on the other—is forcing capital reallocation toward warehouse automation and localized payment infrastructure.
Growth Catalysts
- Live-stream commerce integration:Merchant adoption of real-time video selling interfaces is converting social media engagement into direct transaction volume, particularly in fashion and cosmetics categories.
- Decree 85/2021/ND-CP platform accountability mandates:Vietnam's Ministry of Industry and Trade requirements for complaint resolution and data localization are legitimizing domestic marketplaces against cross-border competitors.
- Provincial logistics densification:Cold-chain investments in Mekong Delta and Central Highlands regions are unlocking fresh grocery e-commerce for households outside Ho Chi Minh City and Hanoi.
Market Restraints
- Cross-border fulfillment cost volatility:International shipping rate fluctuations and customs processing delays at Cat Lai and Hai Phong ports compress margins on imported electronics and cosmetics.
- Payment infrastructure fragmentation:E-wallet interoperability gaps between MoMo, ZaloPay, and VNPay create checkout friction and elevated cart abandonment rates.
- Last-mile labor scarcity:Motorbike courier turnover in tier-two cities exceeds recruitment capacity, capping delivery speed guarantees outside metropolitan cores.
Strategic Opportunities
- Central Highlands agricultural e-commerce:Direct-to-consumer channels for Dalat coffee and Lam Dong produce bypass traditional wholesale layers, capturing margin from export intermediaries.
- Buy-now-pay-later integration:Partnerships between e-commerce platforms and licensed consumer finance entities are expanding addressable customer segments among underbanked rural households.
- State Bank of Vietnam e-wallet interoperability standards:Regulatory push for unified QR code acceptance is reducing payment friction and consolidating transaction data visibility for merchants.
Industry Challenges
- Data localization compliance architecture:Foreign platforms must restructure server infrastructure and data governance workflows to meet Decree 85/2021/ND-CP requirements within enforcement timelines.
- Returns processing automation deficit:Reverse logistics networks lack standardized inspection and restocking protocols, elevating operational costs in apparel and electronics categories.
- Cross-border seller verification:Authentication of international merchant identities and product provenance strains platform trust-and-safety teams amid volume growth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam E-Commerce Market |
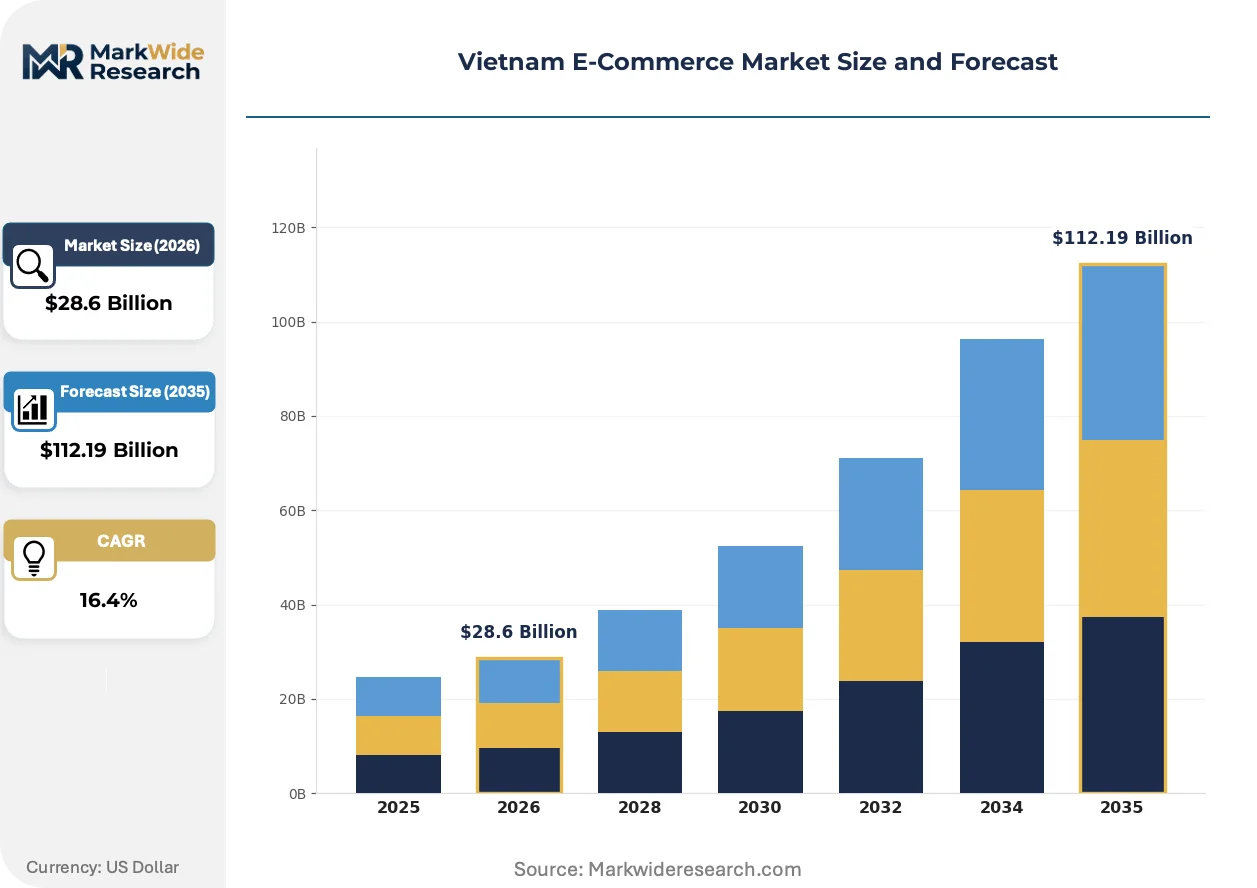
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $112.19 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Apparel, Electronics, Home & Living, Beauty Sales Channel: B2B, B2C, C2C, Online Marketplaces Customer Type: Retail Consumers, Small Businesses, Large Enterprises, Corporates Payment Method: Credit/Debit Cards, E-Wallets, Bank Transfers, Cash on Delivery |
| Companies Covered | Shopee Pte. Ltd., TikTok Shop, Lazada South East Asia Pte. Ltd., Tiki Corporation, Sendo Technology JSC, Mobile World Investment Corp., FPT Retail JSC, Chợ Tốt, Chiaki, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam E-Commerce Market Strategic Shifts
Artificial intelligence deployment is bifurcating platform capabilities between automated personalization engines and human-curated discovery experiences. Three distinct trajectories are crystallizing competitive differentiation.
Machine learning recommendation engines are bifurcating customer acquisition economics. Shopee and Tiki deploy neural networks trained on Vietnamese language search patterns and seasonal purchase cycles to predict demand spikes. Smaller merchants lacking data science capacity face escalating customer acquisition costs against algorithmically optimized competitors.
Vietnam's Ministry of Industry and Trade is tightening enforcement of Decree 85/2021/ND-CP cross-border registration requirements. Foreign platforms must now establish local legal entities and appoint resident representatives to maintain marketplace access. Domestic operators are leveraging compliance latency to capture merchant migration from unregistered cross-border sellers.
Rural consumers are consolidating purchase timing around monthly salary cycles and agricultural harvest periods. This behavioral shift compresses fulfillment demand spikes and strains warehouse labor scheduling in provinces like Nghe An and Thanh Hoa. Platforms responding with flexible workforce models and predictive inventory positioning are capturing loyalty in these high-growth corridors.
Vietnam E-Commerce Market Segmentation
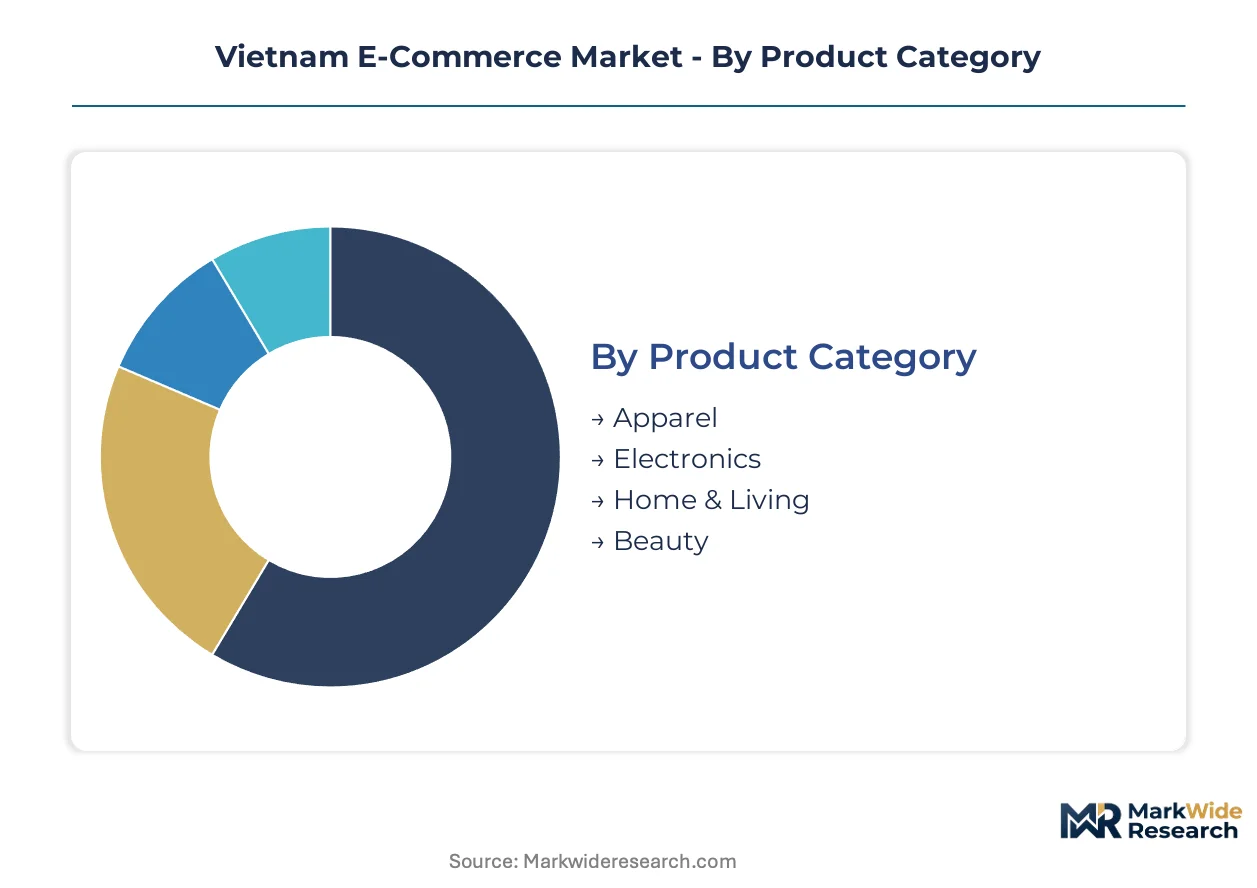
Vietnam's e-commerce segmentation reveals how transaction mechanics and buyer profiles diverge across payment rails and procurement scales. Understanding these fault lines exposes where platform infrastructure investments concentrate and where merchant acquisition costs escalate.
Product Category:
Domestic consumption dominates Apparel and Home & Living, while Electronics and Beauty segments carry heavier cross-border sourcing exposure through Chinese manufacturing corridors.
- Apparel:Fast-fashion SKUs with standardized sizing and visual-heavy merchandising drive volume in Ho Chi Minh City and Hanoi. Live-stream commerce converts browse-to-buy at higher rates here than in other categories due to fit visualization needs.
- Electronics:Smartphones, accessories, and small appliances with warranty localization requirements. Demand clusters in urban cores where authorized service networks validate authenticity claims and protect against grey-market risks.
- Home & Living:Furniture, kitchenware, and décor with high logistics cost-to-value ratios. Provincial expansion depends on third-party assembly partnerships and extended delivery windows outside tier-one cities.
- Beauty:Cosmetics and skincare with ingredient disclosure mandates under Decree 85/2021/ND-CP. Cross-border sellers face elevated compliance costs for product registration and labeling adaptation.
Electronics commands the established base. The steepest expansion runs through Beauty.
Sales Channel:
Margin structures vary sharply: B2B and Large Enterprise transactions reward volume commitments with preferential fulfillment pricing, while C2C and Retail Consumer segments absorb standard rate cards.
- B2B:Wholesale procurement platforms connecting manufacturers to distributors. Procurement cycles align with quarterly inventory planning, requiring credit terms and invoice-based reconciliation that consumer-facing platforms rarely support.
- B2C:Brand-controlled direct channels capturing first-party customer data. These operations concentrate margin pools in Electronics and Beauty where authorized distribution rights create pricing power against marketplace aggregators.
- C2C:Peer-to-peer resale through social commerce interfaces and classified platforms. Transaction density peaks in Apparel and Electronics depreciation cycles, with trust mechanisms substituting for formal merchant verification.
- Online Marketplaces:Aggregator models unifying discovery, payment, and logistics under single interfaces. These platforms absorb the majority of Vietnam's e-commerce transaction volume through merchant density and promotional subsidy programs.
Online Marketplaces command the established base. The steepest expansion runs through B2B.
Customer Type:
Procurement sophistication separates segments: Corporates and Large Enterprises negotiate service-level agreements, while Small Businesses and Retail Consumers accept standardized terms.
- Retail Consumers:Individual households purchasing for personal use. Payment method diversity peaks here—E-Wallets, Cash on Delivery, and Credit/Debit Cards all compete—with checkout friction directly impacting cart abandonment.
- Small Businesses:Micro-enterprises sourcing inventory or supplies through digital channels. These buyers bridge B2C convenience expectations with B2B volume needs, often lacking dedicated procurement staff.
- Large Enterprises:Mid-market companies with formal vendor onboarding and compliance requirements. Their procurement platforms demand API integrations and consolidated billing that strain marketplace infrastructure.
- Corporates:Multinational and domestic conglomerates with centralized purchasing functions. These accounts drive custom fulfillment solutions and dedicated account management resources from platform operators.
Retail Consumers command the established base. The steepest expansion runs through Small Businesses.
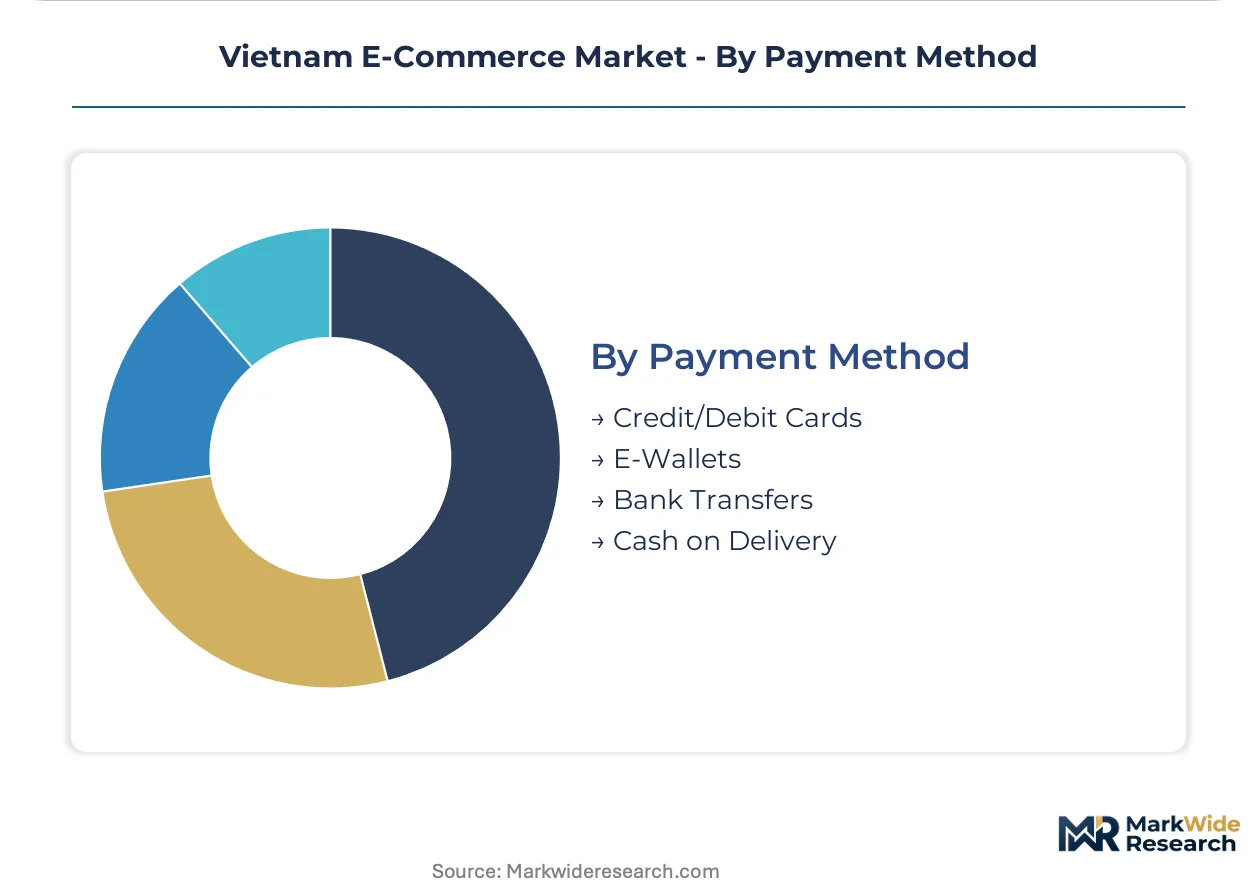
Payment Method:
Infrastructure maturity determines geographic reach: Cash on Delivery extends into provinces where E-Wallet penetration remains thin, while Credit/Debit Cards concentrate in Ho Chi Minh City and Hanoi financial districts.
- Credit/Debit Cards:Bank-issued payment instruments with chargeback protections. Issuance concentrates among salaried employees in formal sector employment, limiting rural penetration without co-branded rural outreach programs.
- E-Wallets:MoMo, ZaloPay, and VNPay compete for merchant acceptance and user balances. Interoperability gaps under State Bank of Vietnam standards create checkout friction that elevates transaction failure rates.
- Bank Transfers:Direct account-to-account settlement favored in B2B and high-value Electronics transactions. Real-time confirmation delays extend fulfillment timelines compared to instant E-Wallet debits.
- Cash on Delivery:Physical payment at delivery point, prevalent in Central Highlands and Mekong Delta provinces. Courier cash handling increases operational costs and fraud exposure for platforms.
E-Wallets command the established base. The steepest expansion runs through Bank Transfers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Warehouse density and last-mile coverage concentrate transaction volume in Vietnam's two primary urban corridors. Provincial logistics networks are expanding into secondary markets, though fulfillment speed guarantees remain uneven outside metropolitan cores.
Ho Chi Minh City
Live-stream commerce adoption peaks here, with merchant density in Districts 1, 2, and 7 driving fashion and cosmetics transaction velocity. The State Bank of Vietnam's e-wallet interoperability standards find strongest implementation in this corridor, reducing payment friction at checkout. Tan Binh and Binh Chanh districts host the highest concentration of automated sorting facilities serving same-day delivery guarantees.
Hanoi
B2B procurement platforms align with quarterly inventory cycles among distributors in Long Bien and Gia Lam industrial zones. Vietnam's Ministry of Industry and Trade maintains its northern enforcement office here, accelerating Decree 85/2021/ND-CP compliance verification for cross-border sellers. Cau Giay and Nam Tu Liem districts concentrate fintech development talent supporting payment infrastructure innovation.
Mekong Delta
Cold-chain investments in Can Tho and An Giang provinces unlock fresh grocery e-commerce for households previously dependent on wet markets. Provincial People's Committees coordinate with platform operators on rural logistics subsidies under national digital transformation programs. Vinh Long and Tien Giang are emerging as agricultural consolidation points for direct-to-consumer coffee and produce channels.
Central Highlands
Dalat and Lam Dong province anchor specialty agricultural e-commerce, with coffee and temperate vegetable producers bypassing traditional wholesale layers. Courier network coverage gaps in Kon Tum and Gia Lai provinces extend delivery windows beyond metropolitan benchmarks. Platform operators are testing flexible workforce models to address demand spikes tied to monthly salary cycles and harvest periods.
Da Nang and Central Coast
Electronics demand clusters in this corridor where authorized service networks validate authenticity claims for smartphones and accessories. The city's port infrastructure at Tien Sa handles cross-border fulfillment volumes subject to customs processing variability. Thua Thien-Hue and Quang Nam provinces represent growth corridors where logistics densification investments are accelerating.
Vietnam E-Commerce Market Competitive Environment
Concentration sits with integrated marketplace operators controlling discovery, payment, and fulfillment layers under unified interfaces. Three archetypes dominate: cross-border aggregators leveraging international sourcing networks, domestic platforms with captive warehousing infrastructure, and social commerce interfaces converting engagement through live-stream mechanics. Competitive moves center on warehouse automation investments and localized payment infrastructure partnerships.
Among Singapore-registered marketplace operators, Shopee Pte. Ltd. and Lazada South East Asia Pte. Ltd. exemplify the cross-border archetype with regional logistics integration. Tiki Corporation represents the domestic vertically integrated model through captive fulfillment networks and authentic product guarantees. TikTok Shop occupies a distinct position converting social media engagement into transaction volume through real-time video selling interfaces.
| Leading Market Players |
|---|
| Shopee Pte. Ltd. |
| TikTok Shop |
| Lazada South East Asia Pte. Ltd. |
| Tiki Corporation |
| Sendo Technology JSC |
| Mobile World Investment Corp. |
| FPT Retail JSC |
| Chợ Tốt |
| Chiaki |
| Others |
Value Chain & Pricing Dynamics
Capacity reservation contracts with cross-border fulfillment providers lock in inventory access and price visibility for Vietnamese marketplace operators navigating Decree 85/2021/ND-CP compliance timelines. These arrangements tether procurement costs to logistics performance guarantees while insulating domestic platforms from international shipping rate volatility at Cat Lai and Hai Phong ports.
Pricing Analysis
Decree 85/2021/ND-CP dictates the pricing tier structure across Vietnamese e-commerce platforms by imposing data localization and consumer protection compliance costs that stratify operational economics. Three-tier pricing structure across premium, standard, and economy levels separates Shopee and Tiki's next-day delivery guarantees from deferred fulfillment options in provincial corridors. Cost compression in cross-border electronics and cosmetics categories is intensifying because customs processing delays and currency fluctuation erode margin pools on grey-market imports. Small businesses and rural retail consumers exhibit highest price sensitivity, while corporate procurement accounts absorb premium tier pricing for dedicated account management and API integration.
Supply Chain Analysis
China and South Korea anchor component manufacturing for Vietnamese electronics marketplace inventory, with Shenzhen and Seoul corridor suppliers feeding smartphone accessories and small appliances into Ho Chi Minh City consolidation hubs. Domestic agricultural production from Lam Dong and Mekong Delta provinces draws from cold-chain infrastructure investments that unlock fresh grocery e-commerce outside metropolitan cores. Single-source vulnerability concentrates in cross-border fulfillment where Cat Lai port congestion creates inventory delays for imported SKUs. Distribution runs through captive warehousing networks operated by Tiki Corporation and Shopee's integrated logistics arm, with third-party last-mile partnerships extending coverage into Central Highlands provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnamese e-commerce functions as a service-attach opportunity where logistics subscription tiers and buy-now-pay-later financing layers expand faster than pure merchandise margin pools. Platform operators capturing recurring revenue from merchant fulfillment services and consumer credit products outpace competitors dependent on transactional commission economics.
For Market Incumbents: Secure merchant loyalty through exclusive warehousing capacity in Mekong Delta agricultural corridors and locked-in e-wallet interoperability under State Bank of Vietnam standards. Defensive consolidation must address TikTok Shop's live-stream commerce threat by building proprietary video selling infrastructure and creator monetization tools. Vertical integration into cold-chain networks for fresh grocery delivery represents the critical lever for rural market share defense against provincial challengers. For New Entrants and Emerging Players: Differentiate on specialized agricultural verticals in Central Highlands coffee and Lam Dong temperate vegetables where direct-to-consumer channels bypass traditional wholesale layers. White-space concentration sits in B2B procurement platforms serving Long Bien and Gia Lam industrial zone distributors with quarterly inventory planning and invoice-based reconciliation. Go-to-market execution should target micro-enterprise procurement needs bridging B2C convenience expectations with volume-based pricing. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated logistics operators with captive warehousing in tier-one cities and established Decree 85/2021/ND-CP compliance architecture. Long-term viability across the analysis window favors domestic platforms leveraging regulatory latency to capture merchant migration from unregistered cross-border sellers. The signal to watch is State Bank of Vietnam enforcement of unified QR code standards that would consolidate transaction data visibility and reshape payment infrastructure competitive dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Network Expansion | Unlocks fresh grocery e-commerce in Mekong Delta provinces previously dependent on wet markets. |
| Live-Stream Commerce Infrastructure | Converts TikTok Shop's social media engagement model into proprietary video selling capabilities for fashion merchants. |
| E-Wallet Interoperability Compliance | Positions platforms advantageously under State Bank of Vietnam unified QR code standards reducing checkout friction. |
| Provincial Logistics Subsidy Partnerships | Aligns platform operators with Provincial People's Committees under national digital transformation programs. |
| Buy-Now-Pay-Later Integration | Expands addressable segments among underbanked rural households through licensed consumer finance partnerships. |
Study Parameters
A spread of perspectives from marketplace operations executives, logistics network planners, merchant acquisition leads, and State Bank of Vietnam regulatory officers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against Vietnam Ministry of Industry and Trade enforcement disclosures, customs processing data at Cat Lai and Hai Phong ports, and e-wallet transaction flow reports. Bottom-up merchant density estimates and top-down gross merchandise value triangulation anchored market sizing across the projection horizon.
Segmentation dimensions modeled include product category concentration, sales channel economics, customer procurement sophistication, and payment method infrastructure maturity alongside logistics fulfillment speed tiers. CAGRs were derived from demand elasticity analysis against rural internet penetration curves and quarterly inventory cycle alignment in B2B procurement segments. Forecast inputs incorporated cold-chain investment pipelines in Mekong Delta provinces and live-stream commerce merchant adoption velocity in Ho Chi Minh City fashion corridors.
Forecasts assume regulatory continuity in Vietnam's Decree 85/2021/ND-CP enforcement regime and State Bank of Vietnam fintech licensing frameworks; material policy shifts would require re-modeling platform compliance costs and cross-border seller registration thresholds. Specific risk factors include courier labor turnover caps in tier-two cities and international shipping rate volatility compressing electronics import margins. Recalibration cycles align with material shifts in provincial logistics subsidy allocations and e-wallet interoperability standard implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Asia-Pacific Dropshipping Market
E-Commerce Solutions
E-Tailing Market
E-Commerce Solutions
Argentina E-Commerce Market
E-Commerce Solutions
Agricultural E-Commerce Market
E-Commerce Solutions
Asia Pacific B2B E-Commerce Market
E-Commerce Solutions
Global Digital Commerce Market
E-Commerce Solutions
C2C E-Commerce Market
E-Commerce Solutions
India D2C E-Commerce Market
E-Commerce Solutions
Estonia E-Commerce Market
E-Commerce Solutions
Food E Commerce Market
E-Commerce Solutions
Global Subscription E Commerce Market
E-Commerce Solutions
Europe E-Commerce Logistics Market
E-Commerce Solutions
Europe E-Commerce Market
E-Commerce Solutions
Canada E-Commerce Market
E-Commerce Solutions
Finland E-Commerce Market
E-Commerce Solutions
Middle East and Africa E-Commerce Apparel Market