
 Quick Commerce Market | 2026-2036
Quick Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Quick Commerce Market Analytics
Dark store operators across Western Europe is recalibrating fulfillment economics as labor and real estate costs tighten. Gopuff leverages captive warehouse networks to control last-mile density in metropolitan zones. Getir anchors rapid delivery through vertically owned micro-fulfillment centers in London and Berlin. Blinkit competes on localized assortment depth, tailoring SKUs to neighborhood consumption patterns in Indian cities.
Quick commerce denotes the ultra-fast delivery of everyday essentials—typically groceries, pharmaceuticals, and convenience retail—through distributed micro-fulfillment nodes positioned within three kilometers of target populations, with order-to-door cycles engineered under thirty minutes via algorithmic rider dispatch and predictive stocking. On-demand delivery models dominate transaction volume but bleed capital on per-unit economics, while subscription models capture higher lifetime value through predictable replenishment schedules. AI-driven technology layers extract margin by optimizing route sequencing and demand forecasting, though mobile apps remain the primary customer interface across all segments.
FDA oversight of food safety standards shapes product handling protocols for grocery and pharmacy SKUs in the United States, while the EU Green Deal's packaging waste directives pressure operators across France and Germany to abandon single-use plastics. India's FSSAI mandates cold-chain integrity for perishable deliveries, raising compliance costs for temperature-sensitive categories. Stakeholders must weigh regulatory compliance spend against unit economics as delivery speed expectations harden into baseline consumer assumptions.
Market Dynamics
Dark store networks and AI-driven rider dispatch systems are compressing fulfillment economics while labor costs and real estate premiums erode per-order margins across metropolitan zones.
Growth Catalysts
- EU Green Deal packaging directives:France and Germany mandate plastic reduction, forcing operators to redesign last-mile containers and triggering innovation in reusable packaging systems.
- Mobile-first consumption patterns:Urban millennials and Gen Z consumers in India, Turkey, and Brazil anchor transaction volume through smartphone-native grocery purchasing.
- Predictive stocking algorithms:Machine learning models forecast neighborhood-level demand, reducing inventory carrying costs and stockout rates in micro-fulfillment centers.
Market Restraints
- Last-mile labor cost inflation:Rider wages and benefits in London, Berlin, and São Paulo consume disproportionate share of unit economics.
- Real estate concentration:Premium urban warehouse space in Mumbai, Istanbul, and São Paulo faces supply constraints, inflating dark store lease rates.
- Cold-chain infrastructure gaps:Temperature-controlled logistics for perishables remains underdeveloped in secondary Indian and Brazilian cities.
Strategic Opportunities
- Subscription replenishment models:Predictable delivery schedules capture higher lifetime value than on-demand transactions, reducing customer acquisition costs.
- India's FSSAI cold-chain mandates:Compliance requirements create barriers for informal competitors, favoring capitalized operators with certified infrastructure.
- Pharmaceutical delivery expansion:Prescription and OTC medicines represent underpenetrated category with higher margins than grocery SKUs.
Industry Challenges
- Algorithmic dispatch optimization:Balancing rider utilization against delivery speed promises requires continuous machine learning refinement.
- Multi-temperature zone fulfillment:Simultaneous handling of ambient, chilled, and frozen SKUs complicates warehouse layout and picking workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quick Commerce Market |
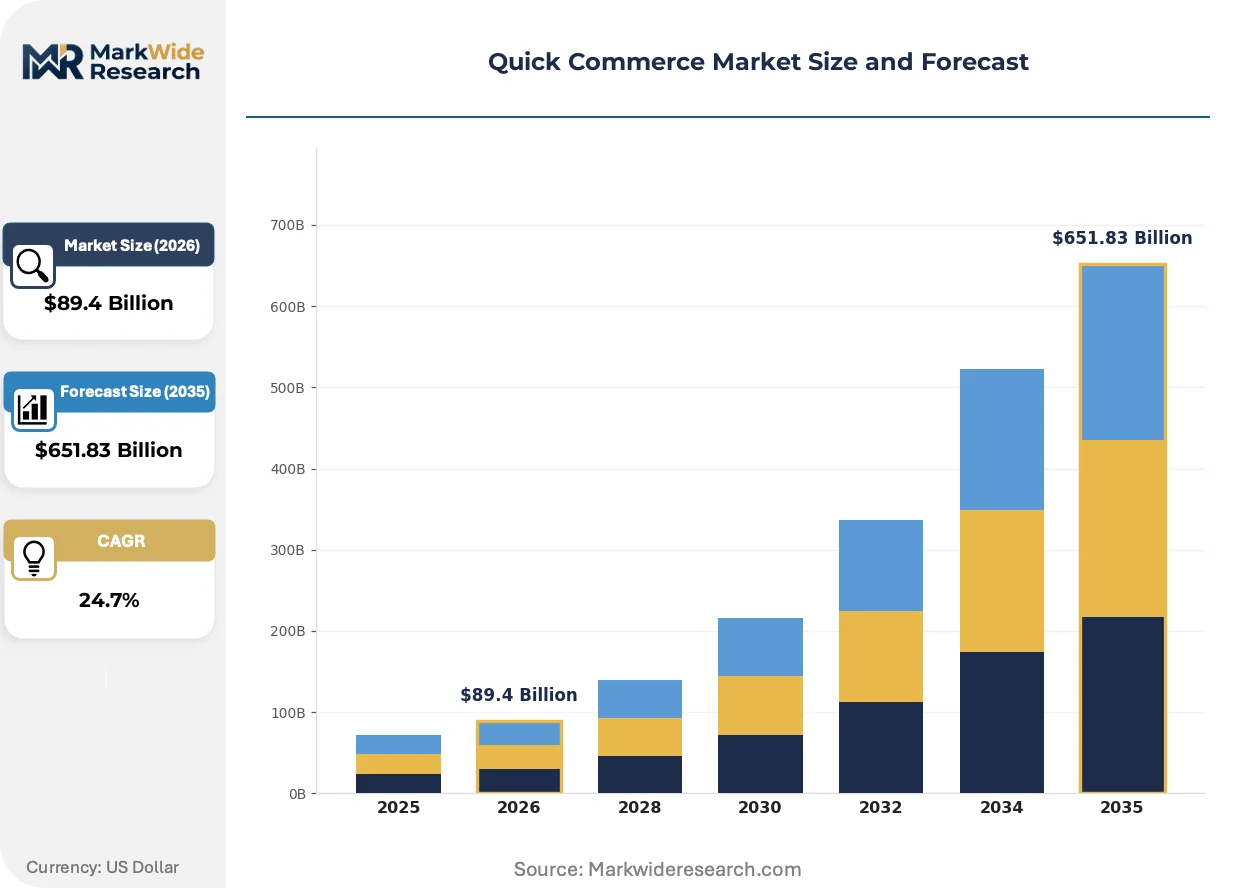
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $651.83 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
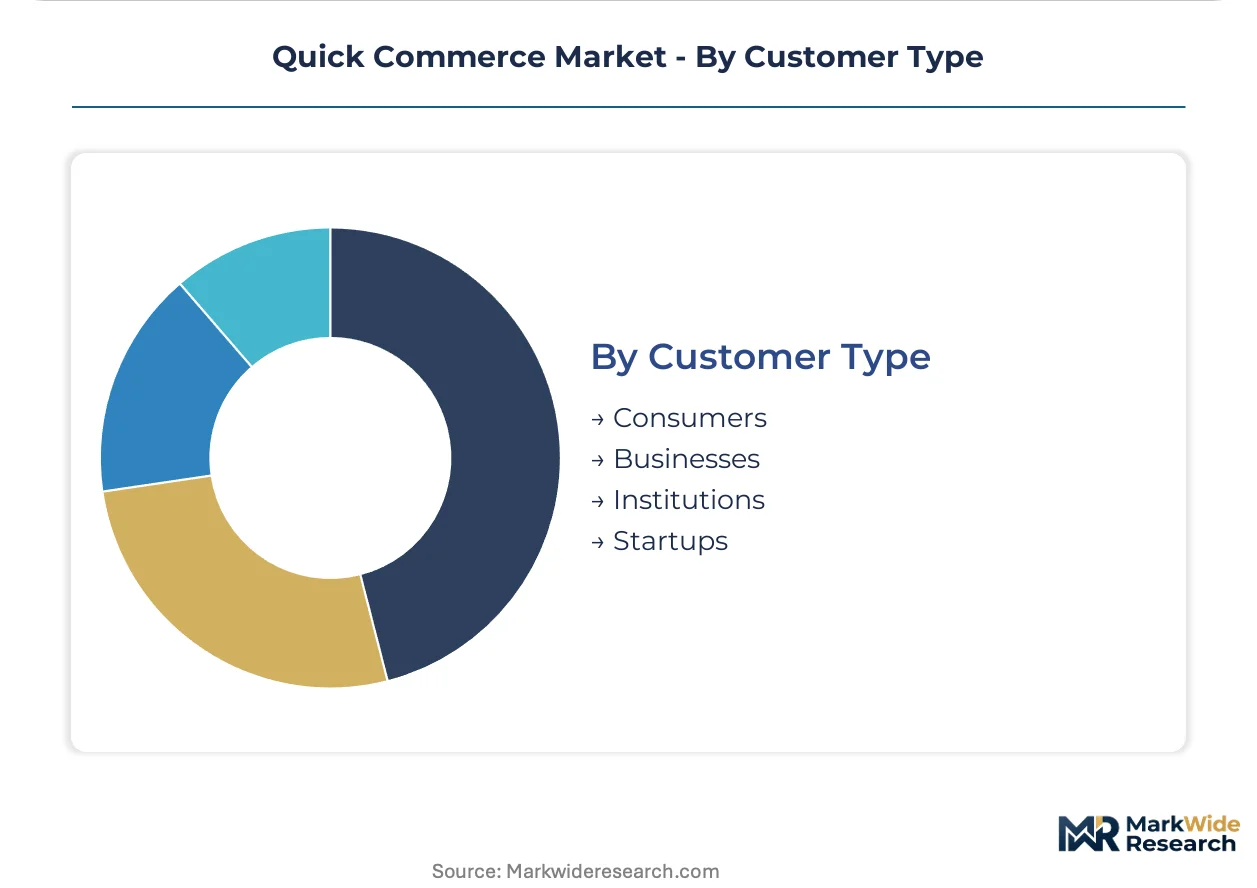
| Segmentation | Delivery Model: On-Demand, Scheduled, Subscription, Direct Service Type: Grocery, Food Delivery, Pharmacy, Retail Technology: Mobile App, Web Platform, API Integration, AI-Driven Customer Type: Consumers, Businesses, Institutions, Startups |
| Companies Covered | Amazon Fresh, Glovo, Gopuff, Blinkit, Getir, DoorDash, Uber Eats, Swiggy Instamart, Instacart, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quick Commerce Market Evolving Landscape
Automation layers are penetrating fulfillment infrastructure while regulatory pressure on packaging intensifies and consumer expectations harden around delivery speed guarantees.
Autonomous mobile robots are absorbing warehouse picking and sorting tasks in micro-fulfillment centers. Operators in Berlin and London deploy robotic arms for ambient SKU retrieval, reducing human picker headcount. This technology is absorbing labor cost pressure while enabling 24-hour fulfillment cycles.
India's FSSAI cold-chain integrity mandates reshape perishable handling protocols. Temperature logging and GPS tracking become mandatory for dairy, meat, and pharmaceutical deliveries. Quick commerce operators in Mumbai and Delhi invest in IoT-enabled refrigerated vehicles to maintain compliance.
Neighborhood-level assortment customization displaces standardized SKU lists. Operators tailor product mixes to local consumption patterns—premium international brands in affluent Istanbul districts, value staples in emerging São Paulo suburbs. Turkey and Brazil show fastest adoption of hyperlocal merchandising.
Quick Commerce Market Segmentation
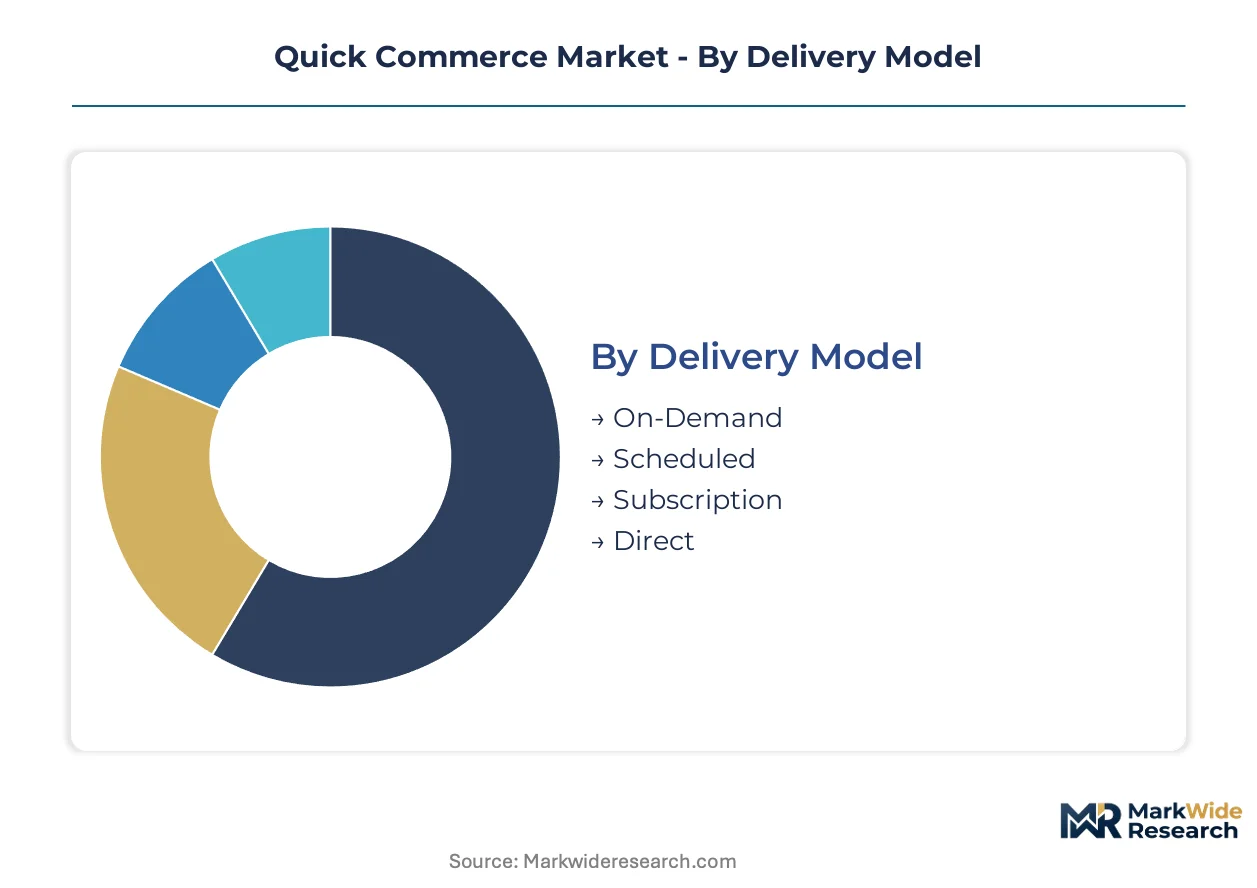
Quick commerce operators configure fulfillment infrastructure around distinct operational archetypes, each carrying differentiated regulatory obligations and margin profiles. Segment boundaries determine capital allocation between dark store density, rider networks, and technology stack investments.
Delivery Model:
FDA food safety protocols apply variably across delivery cadences, with temperature-controlled categories triggering stricter handling requirements for on-demand and scheduled formats.
- On-Demand:Immediate fulfillment within thirty minutes via algorithmic rider dispatch from hyperlocal micro-fulfillment nodes. Demand concentrates in Mumbai, São Paulo, and Istanbul where urban density supports sub-kilometer dark store spacing, though rider wage inflation erodes per-order economics in London and Berlin.
- Scheduled:Pre-booked delivery windows enabling batch optimization and route consolidation. European operators leverage this format to comply with EU Green Deal packaging directives through consolidated drop patterns.
- Subscription:Recurring replenishment contracts capturing higher lifetime value through predictable demand forecasting. This segment climbs fastest as Indian and Brazilian operators pivot from acquisition-heavy on-demand models toward retention economics.
- Direct:Merchant-owned fulfillment bypassing third-party platforms, typically anchored by grocery chains with captive dark store networks.
Volume leadership rests with On-Demand. Subscription shows steepest expansion trajectory.
Service Type:
Margin structures diverge sharply across service categories, with pharmaceutical and grocery SKUs carrying contrasting cold-chain compliance burdens.
- Grocery:Ambient, chilled, and frozen SKU handling requiring multi-temperature zone warehouse architecture. India's FSSAI mandates drive IoT-enabled vehicle investments for dairy and meat categories in Delhi and Mumbai.
- Food Delivery:Prepared meal logistics with compressed handoff windows and packaging waste scrutiny under France and Germany's plastic reduction frameworks.
- Pharmacy:Prescription and OTC medicine distribution subject to national pharmaceutical regulator oversight in each operating geography. This segment expands most quickly as operators seek margin relief from grocery unit economics.
- Retail:General merchandise and convenience goods with lower perishability risk but higher SKU fragmentation.
Grocery dominates transaction volume. Pharmacy gains share fastest.
Technology:
Platform architecture choices determine scalability economics and integration depth with merchant inventory systems.
- Mobile App:Primary consumer interface across all geographies, with India, Turkey, and Brazil showing near-total transaction concentration through smartphone-native purchasing patterns.
- Web Platform:Secondary access point for subscription management and bulk ordering workflows, more prevalent in European markets with desktop commerce heritage.
- API Integration:Backend connectivity enabling merchant direct fulfillment and enterprise procurement system linkage.
- AI-Driven:Predictive demand forecasting, route optimization, and dynamic pricing layers extracting margin from operational data.
Mobile App anchors consumer engagement. AI-Driven capabilities differentiate operator economics.
Customer Type:
Procurement patterns segment sharply between individual consumption and institutional replenishment needs.
- Consumers:Individual households driving transaction volume through convenience-seeking behavior, concentrated in urban millennial and Gen Z demographics across São Paulo, Istanbul, and Indian metros.
- Businesses:Small and medium enterprises sourcing office supplies and pantry replenishment through B2B platform variants.
- Institutions:Hospitals, schools, and corporate campuses with contracted delivery schedules and invoice-based payment terms.
- Startups:Early-stage companies and co-working spaces with irregular purchasing patterns and platform experimentation tendencies.
Consumers generate the majority of order flow. Businesses show strongest margin profile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban population density and smartphone penetration anchor quick commerce infrastructure investments across the most contested metropolitan markets.
India
FSSAI cold-chain mandates reshape perishable logistics as operators deploy IoT-enabled refrigerated vehicles. The PLI scheme for logistics infrastructure accelerates dark store construction in Delhi-NCR and Mumbai. Bangalore and Hyderabad concentrate AI-driven demand forecasting development for neighborhood-level inventory optimization.
Turkey
Hyperlocal merchandising tailors SKU mixes to district-level consumption patterns in Istanbul. The country's national food safety regulator enforces temperature logging for dairy and meat deliveries. Micro-fulfillment centers in Ankara and Izmir replicate Istanbul's vertically owned warehouse density.
Brazil
São Paulo's urban density supports sub-kilometer dark store spacing for sub-thirty-minute delivery windows. ANVISA oversight of pharmaceutical distribution creates compliance barriers for prescription medicine expansion. Rio de Janeiro and Belo Horizonte scale rider networks to match São Paulo's fulfillment velocity.
United States
FDA food safety protocols govern grocery and pharmacy SKU handling across metropolitan zones. The IRA's clean vehicle incentives nudge delivery fleets toward electric transition in California and New York. Chicago and Miami concentrate subscription replenishment model experimentation for higher lifetime value capture.
Germany
EU Green Deal packaging directives force reusable container redesign across Berlin and Munich fulfillment networks. ECHA chemical safety standards influence cleaning product assortment decisions. Hamburg and Cologne deploy autonomous mobile robots for warehouse picking to offset labor cost pressure.
Quick Commerce Market Competitive Landscape
Global majors compete with regional champions across fulfillment infrastructure density and regulatory compliance capabilities. The vendor base stratifies between vertically integrated dark store operators and platform-dependent aggregators. Three archetypes dominate: captive warehouse networks, algorithmic dispatch platforms, and hybrid grocery-retail incumbents. Geographic expansion and technology licensing represent the primary competitive vectors.
Among vertically integrated specialists, Getir anchors rapid delivery through owned micro-fulfillment centers, Blinkit exemplifies hyperlocal assortment customization, and Gopuff represents captive warehouse network economics. These operators occupy positions across distinct regulatory environments, with each archetype confronting specific compliance burdens from food safety, pharmaceutical distribution, and packaging waste frameworks.
| Leading Market Players |
|---|
| Amazon Fresh |
| Glovo |
| Gopuff |
| Blinkit |
| Getir |
| DoorDash |
| Uber Eats |
| Swiggy Instamart |
| Instacart |
| Others |
Value Network & Pricing Analysis
Rider workforce concentration in São Paulo, Mumbai, and Istanbul generates labor-cost differentials that widen pricing-tier spreads between premium guaranteed-delivery slots and economy windows.
Pricing Analysis
Warranty and service bundling separates premium subscription tiers from transactional on-demand purchases, with cold-chain integrity guarantees commanding higher rates in Indian and Brazilian markets. Three-tier pricing structure across premium, standard, and economy levels reflects delivery speed guarantees and temperature-control certification tiers. Price differentiation hinges on FSSAI compliance status and real estate proximity to dense urban cores. Cost compression in economy tiers intensifies because rider wage inflation in London and Berlin erodes per-order margins. Small and medium enterprises show least price sensitivity due to invoice-based procurement workflows, while individual consumers in emerging markets drive volume through promotional discounting.
Supply Chain Analysis
FDA food safety certification and FSSAI cold-chain qualification gating restrict supplier eligibility for temperature-sensitive categories, filtering fulfillment partners in the United States and India. Dark store construction concentrates in India, Turkey, and Brazil where urban density supports micro-fulfillment economics. Warehouse automation equipment and IoT-enabled refrigerated vehicles draw from German engineering suppliers and Chinese electronics manufacturers. Single-source vulnerability runs through autonomous mobile robot providers in European fulfillment networks. Distribution runs through vertically owned micro-fulfillment centers in metropolitan zones, bypassing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
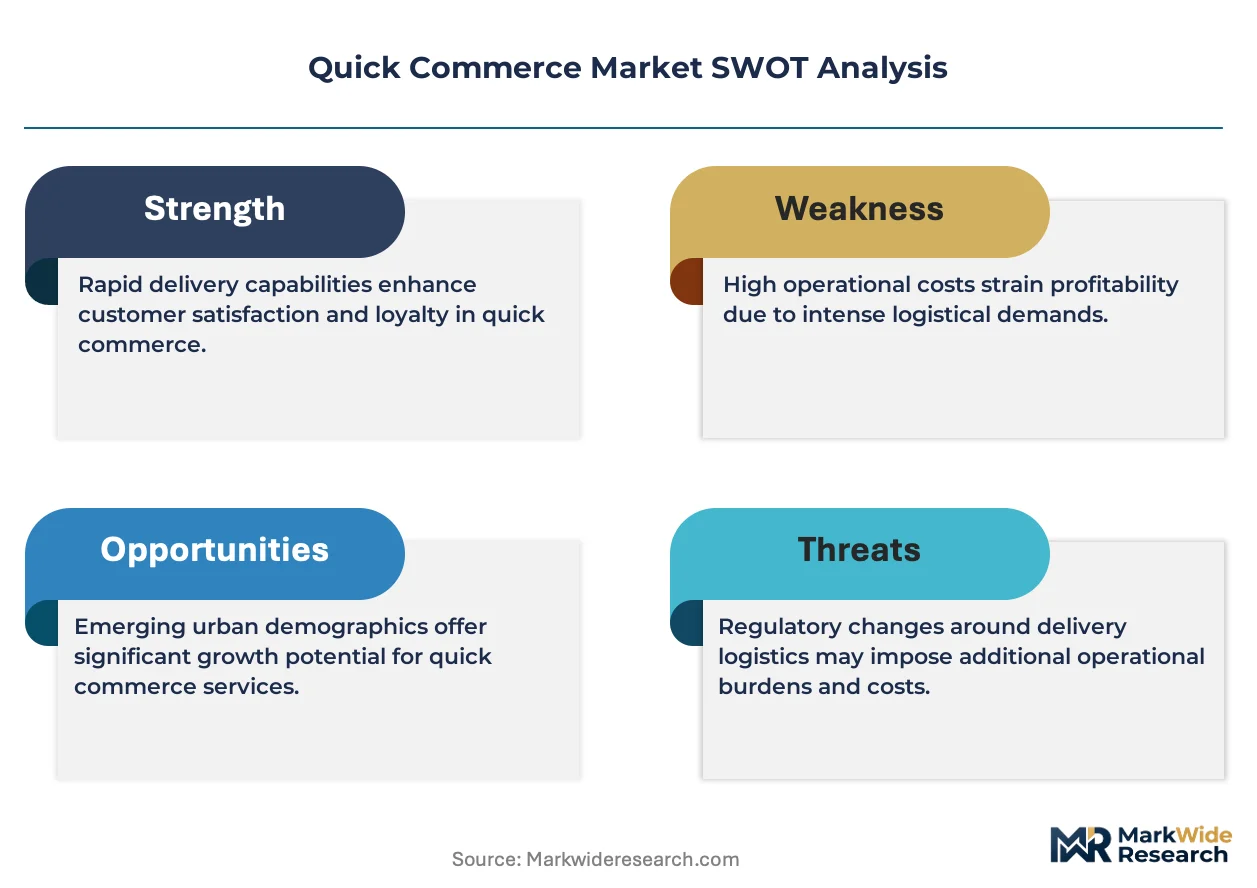
Dark store real estate scarcity in premium Mumbai, Istanbul, and São Paulo districts props pricing power, constraining rapid fulfillment capacity expansion.
For Market Incumbents: Hedge against rider wage inflation by accelerating warehouse automation deployment in Berlin and Hamburg fulfillment centers. Secure captive cold-chain certification under India's FSSAI mandates to lock out undercapitalized competitors. Build backward integration into reusable packaging manufacturing to preempt EU Green Deal compliance cost spikes. For New Entrants and Emerging Players: API integration routes into enterprise procurement systems represent the most penetrable white-space target, with institutional replenishment contracts showing stronger margin profiles than consumer on-demand volume. Pharmaceutical delivery in Brazilian cities offers regulatory moat potential given ANVISA oversight barriers. Launch through direct merchant partnerships rather than platform aggregation to capture higher per-unit economics. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated dark store operators given FSSAI compliance catalysts in Indian markets. Long-term viability favors capitalized players with certified cold-chain infrastructure and captive warehouse networks over asset-light platform models. Watch regulatory enforcement intensity on food safety protocols as inflection indicator for competitive consolidation pace.| Strategic Initiative | Industry Significance |
|---|---|
| Dark Store Network Expansion | Captive warehouse density in São Paulo and Mumbai compresses delivery windows below competitor reach. |
| Cold-Chain Certification Investment | FSSAI compliance in Delhi-NCR creates regulatory barriers protecting certified operators from informal rivals. |
| Autonomous Mobile Robot Deployment | Berlin and London warehouse automation offsets labor cost pressure while enabling 24-hour fulfillment cycles. |
| Subscription Model Pivot | Predictable replenishment schedules in Chicago and Miami capture higher lifetime value than on-demand transactions. |
| Reusable Packaging Redesign | EU Green Deal compliance in France and Germany preempts regulatory penalties while differentiating brand positioning. |
Research Methodology
Document review covered SEC filings of publicly traded delivery platforms, EU regulatory filings on packaging directives, and FSSAI compliance databases, complemented by interviews with quick commerce operations directors, dark store facility managers, last-mile logistics coordinators, and grocery category buyers. Secondary validation drew from customs records of warehouse automation equipment, urban real estate lease transaction databases, and rider wage surveys in metropolitan zones. Bottom-up dark store capacity modeling and top-down consumer spending pattern analysis enabled triangulation across data sources.
Segmentation outputs across delivery model, service type, technology platform, and customer archetype were generated through the projection horizon, with neighborhood-level demand density and regulatory cluster variables incorporated. CAGRs were derived from algorithmic rider dispatch efficiency curves and predictive stocking algorithm adoption rates. Cold-chain infrastructure investment flows and micro-fulfillment center construction permits served as industry-specific forecast inputs.
Inputs from FSSAI compliance registries and EU packaging directive enforcement records were available through the study window; gaps in informal competitor financial disclosure introduce uncertainty bands around market share estimates. Forecasts reflect documented assumptions on urban density thresholds and rider wage trajectory. A model refresh is warranted upon material change in national food safety regulator enforcement intensity or dark store zoning policy shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Quiet Commerce Market
E-Commerce Solutions
South Korea Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
United States Same-Day Delivery Market
E-Commerce Solutions
Pharmaceutical E-Commerce Market
E-Commerce Solutions
India E-Commerce Warehousing Market
E-Commerce Solutions
Pharma E-Commerce Market
E-Commerce Solutions
Japan Same Day Delivery Market
E-Commerce Solutions
Moldova E-Commerce Market
E-Commerce Solutions
Retail E-Commerce Market
E-Commerce Solutions
China Online Trading Platform Market
E-Commerce Solutions
Second-Hand E-Commerce Market
E-Commerce Solutions
North America E-Commerce Watch Market
E-Commerce Solutions
Denmark E-Commerce Market
E-Commerce Solutions
South Korea E-Commerce Market
E-Commerce Solutions
South Korea Ecommerce Logistics Market
E-Commerce Solutions
E-Commerce Household Appliances Market