
 Africa E-Commerce Market | 2026-2036
Africa E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Africa E-Commerce Market Intelligence
Last-mile delivery networks are rewriting competitive rules across African online retail. Jumia leverages its proprietary logistics arm to reach secondary cities where postal infrastructure remains weak. Takealot anchors South African demand through fulfillment center density in Gauteng and the Western Cape. Zando specializes in fashion-forward inventory tuned to local sizing and seasonal preferences.
Africa e-commerce denotes digital commercial transactions conducted via internet-connected devices, typically requiring mobile-optimized interfaces, localized payment gateways, and variable bandwidth accommodation for users across 2G to 4G networks. The primary purpose is to connect dispersed consumer populations with formal retail inventory previously accessible only in major urban centers. Fashion and electronics dominate current product category transaction flows, with mobile payments capturing the fastest-growing payment method slot as cash-on-delivery recedes in major metros. Marketplace platforms sustain the deepest seller liquidity, though direct sales channels are carving out margin pools in premium beauty and imported health products.
Nigeria's Central Bank, South Africa's Financial Sector Conduct Authority, and Kenya's Communications Authority collectively shape digital commerce through mobile money licensing, consumer protection frameworks, and data localization requirements. These regulators are tightening know-your-customer standards for wallet-based transactions while expanding interoperability mandates between competing payment rails. Stakeholders must monitor which regulatory body moves first on cross-border digital tax harmonization, as this will determine capital allocation priority between Anglophone and Francophone market entry strategies.
Market Dynamics
Mobile payment rails are collapsing the distance between informal cash economies and formal digital commerce across African markets. M-Pesa and interoperable wallet systems now process transactions in secondary cities where bank branches remain sparse.
Growth Catalysts
- Mobile Money Interoperability Mandates:Kenya's Communications Authority and Nigeria's Central Bank are forcing wallet-to-wallet settlement standards that reduce friction for cross-platform purchases.
- Fashion Inventory Localization:Young urban consumers in Lagos and Nairobi are pulling demand toward size-calibrated apparel that accounts for regional body-type variation and seasonal climate patterns.
- Last-Mile Logistics Proliferation:Fulfillment center density in Gauteng and the Western Cape is compressing delivery windows for South African online orders.
Market Restraints
- Postal Infrastructure Gaps:Weak addressing systems in secondary Nigerian cities force reliance on phone-based coordination, raising fulfillment costs.
- Bandwidth Asymmetry:Variable 2G-to-4G coverage across Kenya's Rift Valley and Nigeria's northern states degrades mobile checkout completion rates.
- Know-Your-Customer Friction:Tiered documentation requirements for wallet-based transactions in South Africa exclude underbanked populations from higher-value purchases.
Strategic Opportunities
- Francophone Market Entry:Côte d'Ivoire and Senegal present underpenetrated corridors where Orange Money infrastructure precedes e-commerce platform saturation.
- Cross-Border Digital Tax Harmonization:Priority attention to which regulator moves first on VAT collection for international shipments will determine capital allocation between Anglophone and Francophone zones.
- Direct Sales Channel Expansion:Premium beauty and imported health products are carving margin pools outside marketplace liquidity constraints.
Industry Challenges
- Data Localization Compliance:Divergent server-hosting requirements across Nigeria, South Africa, and Kenya fragment cloud architecture strategies.
- Payment Rail Integration:Technical debt from legacy cash-on-delivery systems in major metros slows wallet-first checkout adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa E-Commerce Market |
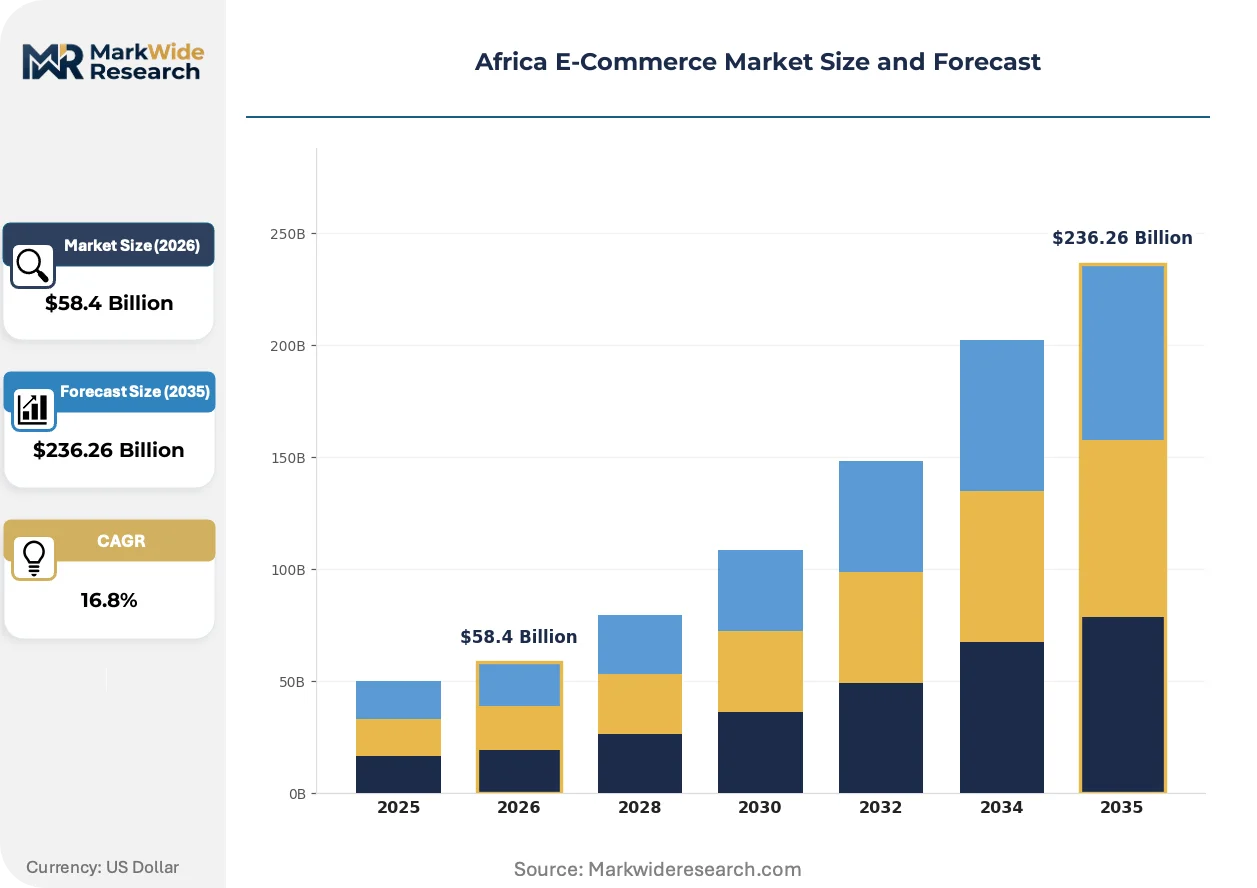
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $236.26 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Electronics, Fashion, Home Goods, Health Products Customer Segment: Individual Consumers, Small Businesses, Large Corporations, Institutional Buyers Payment Method: Credit/Debit Cards, Mobile Payments, Bank Transfers, Cash on Delivery Service Type: Marketplace Platforms, Direct Sales, Subscription Services, Auction Sites |
| Companies Covered | Shein, Zando, Takealot, Makro, Woolworths, Amazon, Superbalist, Noon.com, Jumia, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa E-Commerce Market Strategic Shifts & Innovations
Three forces are actively compressing the African e-commerce value chain: payment infrastructure convergence, regulatory tightening on consumer protection, and demand rotation toward mobile-first discovery.
Progressive Web Applications optimized for variable bandwidth are collapsing the performance gap between native apps and browser-based shopping. Urban consumers in Nairobi and Lagos with intermittent 3G connectivity are adopting these lightweight interfaces faster than full-app downloads. The structural consequence is platform cost reduction, as developers bypass app store gatekeeping and commission structures.
South Africa's Financial Sector Conduct Authority is tightening disclosure standards for marketplace seller vetting and refund processing. This policy compression is forcing Jumia and Takealot to restructure seller onboarding workflows and escrow timelines. Premium electronics and cross-border beauty categories face the steepest compliance recalibration.
Social commerce discovery through WhatsApp and Instagram is displacing traditional search-based purchasing among Nigerian fashion buyers. Young consumers in Lagos and Abuja now complete transactions through embedded payment links rather than dedicated marketplace apps. This behavioral pivot is most visible in apparel verticals where influencer curation drives inventory turnover.
Africa E-Commerce Market Segmentation
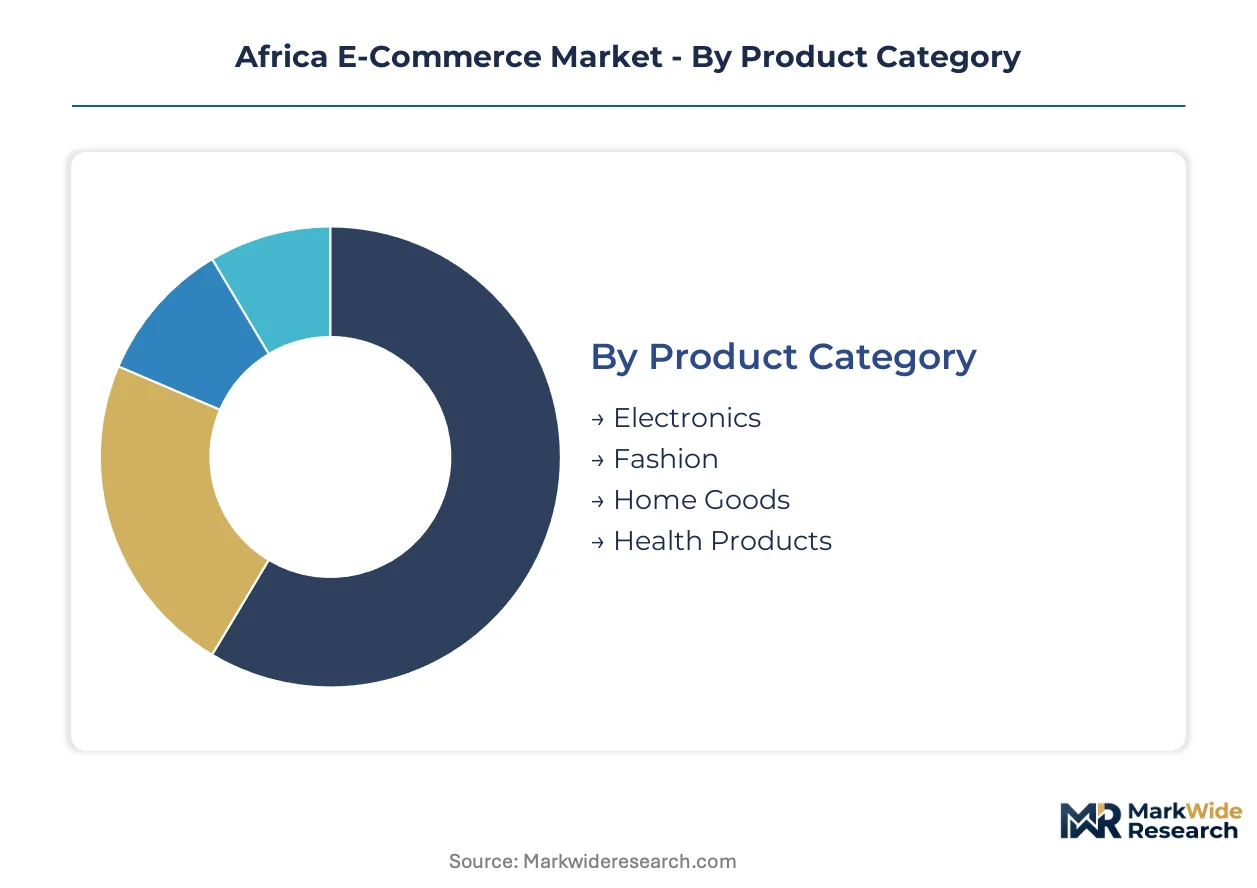
E-commerce platforms in Africa must architect inventory, payment, and fulfillment systems around four distinct fracture lines. Product preferences diverge sharply between Lagos fashion buyers and Nairobi electronics shoppers. Payment infrastructure maturity varies by city density and regulatory environment.
Product Category:
Mature categories dominate current transaction volume while emerging segments reshape platform inventory allocation.
- Electronics:Smartphones, accessories, and consumer appliances constitute the highest-value transaction flows. Nigerian buyers in Lagos and Abuja drive demand for mid-tier devices with localized warranty support, though import duty complexity raises landed costs.
- Fashion:Apparel and footwear calibrated to regional body measurements and seasonal patterns accelerates fastest among young urban consumers. Nairobi and Johannesburg buyers pull inventory toward size-inclusive ranges and climate-appropriate fabrics.
- Home Goods:Furniture and décor purchases concentrate in South African metros with established delivery infrastructure.
- Health Products:Cross-border supplements and pharmaceuticals carve margin pools outside marketplace liquidity constraints, particularly in Kenyan urban centers.
Electronics handles the majority of throughput; Health Products is the fastest mover on share.
Customer Segment:
Volume concentration sits with high-frequency small-ticket buyers while margin extraction targets organizational procurement.
- Individual Consumers:Young, mobile-first shoppers in Lagos, Nairobi, and Johannesburg generate the deepest transaction frequency. M-Pesa and interoperable wallet systems enable purchase completion without formal banking relationships.
- Small Businesses:Informal retailers sourcing inventory through B2B marketplace channels represent expanding order values. Kenyan and Nigerian micro-enterprises leverage bulk pricing for resale in physical markets.
- Large Corporations:Procurement digitization lags in Francophone markets but accelerates in South Africa's Gauteng corporate corridor.
- Institutional Buyers:Government and NGO procurement through dedicated platforms remains concentrated in Kenya and Nigeria.
Individual Consumers anchor platform liquidity; Small Businesses is climbing the fastest on transaction value contribution.
Payment Method:
Cost tier stratification determines checkout completion rates across bandwidth-constrained environments.
- Mobile Payments:M-Pesa, Airtel Money, and interoperable wallet rails process the fastest-growing transaction share. Kenya's Communications Authority interoperability mandates reduce friction for cross-platform settlement in Nairobi and Mombasa.
- Cash on Delivery:Legacy preference persists in northern Nigerian cities with weak addressing infrastructure, though fulfillment costs erode margins.
- Credit/Debit Cards:South African metros with established banking penetration sustain the deepest card transaction density.
- Bank Transfers:Large-ticket B2B purchases in Lagos and Johannesburg rely on real-time gross settlement systems.
Mobile Payments is gaining share fastest; Cash on Delivery retains volume concentration in infrastructure-constrained corridors.
Service Type:
Supply concentration favors marketplace liquidity while direct channels capture premium margin extraction.
- Marketplace Platforms:Jumia and Takealot sustain the deepest seller liquidity across electronics and fashion verticals. Third-party vendor density enables price discovery and inventory breadth in Lagos, Nairobi, and Johannesburg.
- Direct Sales:Premium beauty and imported health products bypass marketplace commission structures through owned channels. Kenyan and Nigerian consumers complete transactions via WhatsApp-embedded payment links.
- Subscription Services:Recurring delivery models for consumables test viability in South African metros with predictable addressing.
- Auction Sites:Secondary electronics and vehicle markets maintain niche presence in Nigeria.
Marketplace Platforms handle the majority of throughput; Direct Sales is expanding most quickly on margin contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
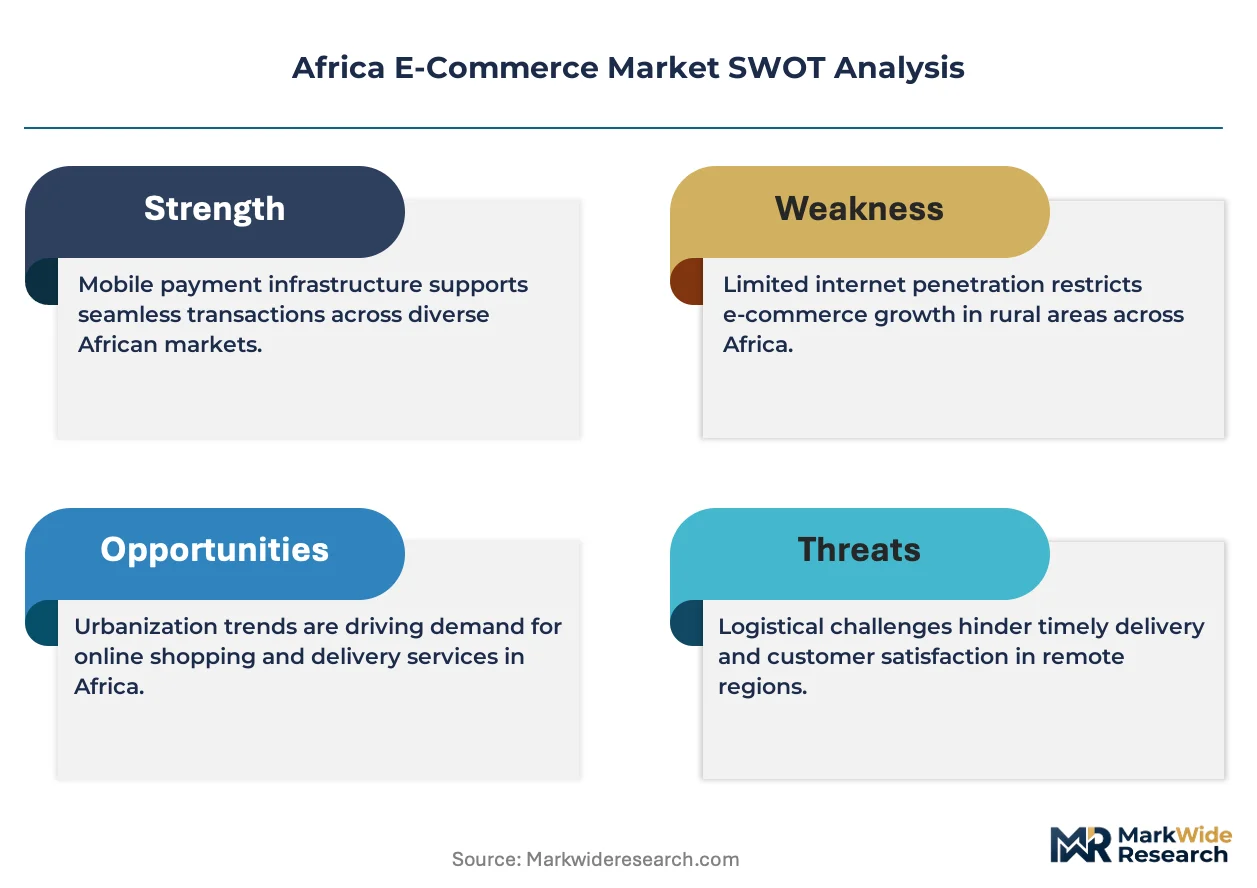
Nigeria's Central Bank anchors regulatory gravity for Africa e-commerce through mobile money licensing and interoperability mandates that reshape wallet-based transaction flows across the continent's largest consumer base.
Nigeria
Lagos and Abuja drive electronics demand through young urban consumers seeking mid-tier smartphones with localized warranty support. The Central Bank's tiered know-your-customer requirements for wallet transactions filter underbanked populations from higher-value purchases. Northern cities rely on phone-based delivery coordination where postal addressing remains underdeveloped.
South Africa
Gauteng and Western Cape fulfillment center density compresses delivery windows for online fashion and home goods orders. The Financial Sector Conduct Authority tightens disclosure standards for marketplace seller vetting and refund processing. Johannesburg anchors corporate procurement digitization that lags in neighboring markets.
Kenya
Nairobi and Mombasa consumers accelerate fashion inventory turnover through M-Pesa-enabled mobile checkout. The Communications Authority mandates wallet-to-wallet interoperability that reduces friction for cross-platform purchases. Rift Valley bandwidth asymmetry degrades mobile completion rates outside urban cores.
Côte d'Ivoire
Abidjan presents underpenetrated corridor opportunity where Orange Money infrastructure precedes platform saturation. The country's national telecommunications regulator shapes mobile payment licensing frameworks. Urban clusters pull demand toward Francophone-localized apparel sizing and seasonal calibration.
Senegal
Dakar's young professional demographic generates emerging demand for cross-border health products and premium beauty categories. The central bank's approach to digital wallet supervision determines merchant onboarding velocity. Coastal urban concentration enables last-mile logistics experimentation absent in landlocked neighbors.
Africa E-Commerce Market Key Industry Players
Pan-African marketplace operators and regional specialists split the market along geography and category depth vectors. Platform concentration favors players with proprietary logistics arms that reach secondary cities where postal infrastructure remains weak. Two archetypes dominate: vertically integrated marketplace platforms controlling fulfillment end-to-end, and fashion-specialized retailers tuning inventory to local sizing and seasonal patterns. Competitive moves center on last-mile network expansion and seller onboarding workflow restructuring under tightening consumer protection standards.
Among the vertically integrated tier, Jumia and Takealot occupy positions exemplifying logistics-controlled market coverage. Jumia leverages its proprietary delivery infrastructure to serve Nigerian and Kenyan secondary cities where competitors struggle with addressing gaps. Takealot anchors South African demand through Gauteng and Western Cape fulfillment density. Within fashion specialization, Zando represents inventory localization archetype, calibrating apparel ranges to regional body-type variation and climate patterns that pan-regional players often misprice.
| Leading Market Players |
|---|
| Shein |
| Zando |
| Takealot |
| Makro |
| Woolworths |
| Amazon |
| Superbalist |
| Noon.com |
| Jumia |
| Others |
Cost & Logistics Intelligence
Chinese electronics manufacturing concentration feeds margin compression for African marketplace platforms importing smartphones and consumer devices, while domestic fulfillment infrastructure investments in South Africa and Nigeria reshape where value capture concentrates downstream.
Pricing Analysis
Lagos-Abuja price spreads for identical electronics SKUs run 12-18% above Johannesburg benchmarks, driven by import duty layering and currency volatility. Three-tier pricing structure across premium direct-import, standard marketplace, and informal reseller channels segments buyer wallets by documentation tolerance and delivery urgency. Pricing pressure stems from Shein's aggressive entry in fashion verticals, forcing local inventory holders to absorb margin hits on seasonal clearance. Small businesses sourcing for resale exhibit highest price sensitivity, while individual consumers in South African metros accept premium tiers for warranty-backed electronics.
Supply Chain Analysis
Extended payment terms from Chinese OEMs to Lagos-based distributors now stretch 90-120 days, straining working capital for inventory-heavy marketplace sellers. Supply concentration rests on Shenzhen and Dongguan for electronics, Guangzhou for fast fashion, and Istanbul for mid-market apparel serving North African corridors. Semiconductor component dependencies, lithium-ion battery cells, and synthetic textile inputs anchor cost volatility. Single-source vulnerability through Lagos Apapa port congestion elevates landed cost unpredictability. Distribution runs through Jumia's proprietary logistics arm, Takealot's Gauteng fulfillment density, and informal cross-border courier networks in East Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across payment rails, logistics maturity, and regulatory enforcement creates niche entry points for specialists who can arbitrage infrastructure gaps between Anglophone and Francophone corridors.
For Market Incumbents: Harden M-Pesa and interoperable wallet integration to defend checkout completion rates against WhatsApp-embedded payment alternatives eroding marketplace app traffic. Expand proprietary logistics density into Nigerian secondary cities before postal addressing reforms close the competitive window. Vertical integration into last-mile fleets represents the critical lever for margin defense as fuel costs and driver wage inflation accelerate. For New Entrants and Emerging Players: Côte d'Ivoire and Senegal's underpenetrated corridors, where Orange Money infrastructure precedes platform saturation, represent the most penetrable entry points for Francophone-specialized marketplace operators. Direct sales channels for premium beauty and cross-border health products bypass Jumia's commission structures and capture margin pools in Nairobi and Lagos. Social commerce discovery through Instagram and TikTok Shop integration offers the lowest-friction go-to-market angle for fashion inventory localization. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated logistics operators with proprietary last-mile networks in secondary Nigerian and Kenyan cities, where infrastructure scarcity creates durable competitive moats. Five-to-ten-year viability hinges on interoperability mandate timing and cross-border digital tax harmonization sequencing. The signal to watch is which African central bank moves first on VAT collection framework for international shipments, as this determines capital allocation priority between Anglophone and Francophone zones.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Logistics Network Expansion | Jumia's secondary city reach in Nigeria compresses delivery windows where postal infrastructure remains underdeveloped. |
| Mobile Payment Rail Integration | Interoperable wallet settlement reduces checkout friction for M-Pesa and Airtel Money users in Nairobi and Mombasa. |
| Fashion Inventory Localization | Zando's size-calibrated apparel for regional body-type variation captures margin from mispriced pan-regional SKUs. |
| Direct Sales Channel Development | WhatsApp-embedded payment links bypass marketplace commission structures for premium beauty in Lagos and Abuja. |
| Francophone Market Entry | Orange Money infrastructure in Abidjan and Dakar precedes platform saturation, creating first-mover positioning. |
Research Approach
The analysis maps electronics, fashion, home goods, and health product verticals, each validated through marketplace operations directors, mobile payment platform executives, logistics network managers, and regulatory affairs leads at Central Banks and Communications Authorities. Primary fieldwork combined structured interviews with secondary triangulation against customs trade data, mobile money transaction disclosures, SEC filings for listed operators, and telecommunications regulatory filings. Bottom-up seller density estimates and top-down consumer expenditure patterns were reconciled across modeling approaches.
Assumptions held fixed include current mobile money interoperability mandate trajectories and existing postal infrastructure investment schedules, while variables tested included cross-border digital tax implementation timing and bandwidth upgrade pacing in secondary cities. Segmentation dimensions modeled encompass product category, customer segment, payment method, and service type across the analysis window. CAGRs derived from logistic penetration curves and wallet adoption S-cycles, with electronics demand elasticity and fashion inventory turnover velocity as category-specific inputs.
Practitioners should monitor regulatory movement on cross-border VAT harmonization and mobile money tiered KYC expansion for early signals of competitive regime shifts. Forecasts reflect documented assumptions about infrastructure investment continuity and payment rail interoperability progress. Macroeconomic currency volatility, regulatory enforcement divergence, or logistics cost spikes would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
North America E-Commerce Market
E-Commerce Solutions
North America E-Commerce Watch Market
E-Commerce Solutions
E-Commerce Lockers Market
E-Commerce Solutions
Cross Border Ecommerce Market
E-Commerce Solutions
US SMS Marketing Market
E-Commerce Solutions
Norway E-Commerce Market
E-Commerce Solutions
Second-Hand E-Commerce Market
E-Commerce Solutions
Social Commerce Market
E-Commerce Solutions
Cyprus E-Commerce Market
E-Commerce Solutions
Alcohol E-Commerce Market
E-Commerce Solutions
South Africa E-Commerce Market
E-Commerce Solutions
North America FMCG B2B E-Commerce Market
E-Commerce Solutions
Europe E-Commerce Logistics Market
E-Commerce Solutions
Automotive E-Commerce Market
E-Commerce Solutions
Ambient Commerce Market
E-Commerce Solutions
Estonia E-Commerce Market