
 Building and Construction Plastic Fasteners Market | 2026-2036
Building and Construction Plastic Fasteners Market Size, Share, and Industry Trends Forecast 2026-2036
Building and Construction Plastic Fasteners Market Intelligence
Skilled polymer-tooling technicians is rotating toward automated fastening-system production, tightening labor availability for conventional mold shops. Stanley Black & Decker leverages its channel density across big-box retail and professional distribution to sustain specification pull-through on job sites. Illinois Tool Works anchors its position through captive resin compounding and application-engineering support that dominates commercial-scale projects. Nifco Inc. specializes in precision injection-molded clips and anchors for curtain-wall and cladding systems, occupying a defensible niche in non-structural building envelope fastening.
Building and construction plastic fasteners are injection-molded or cold-formed polymeric components—typically nylon 6/6, polypropylene, or glass-reinforced grades—engineered to secure substrates where corrosion, thermal bridging, or electromagnetic neutrality disqualifies metal equivalents. Their primary commercial purpose is to reduce installation-cycle time and lifecycle maintenance cost in exterior envelope, interior finish, and MEP routing applications across residential, commercial, and infrastructure builds. The application dimension shows residential and commercial segments carrying the deepest specification volume, while infrastructure is registering the fastest project-award velocity as public spending on bridges, transit, and utilities accelerates. Within product type, anchors and screws absorb the majority of current demand, though clips are widening their share as unitized facade systems and prefabricated wall panels gain traction in multi-story construction.
REACH and the EU Green Deal constrain virgin-nylon formulations and mandate recyclability disclosures, redirecting R&D budgets toward bio-based and post-industrial feedstocks. In the United States, ICC-ES evaluation reports and state-level energy codes shape product acceptance for structural and thermal-barrier applications, while China's GB standards enforce fire-performance ratings that filter import eligibility. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance investments in one geography do not automatically transfer to approval regimes elsewhere.
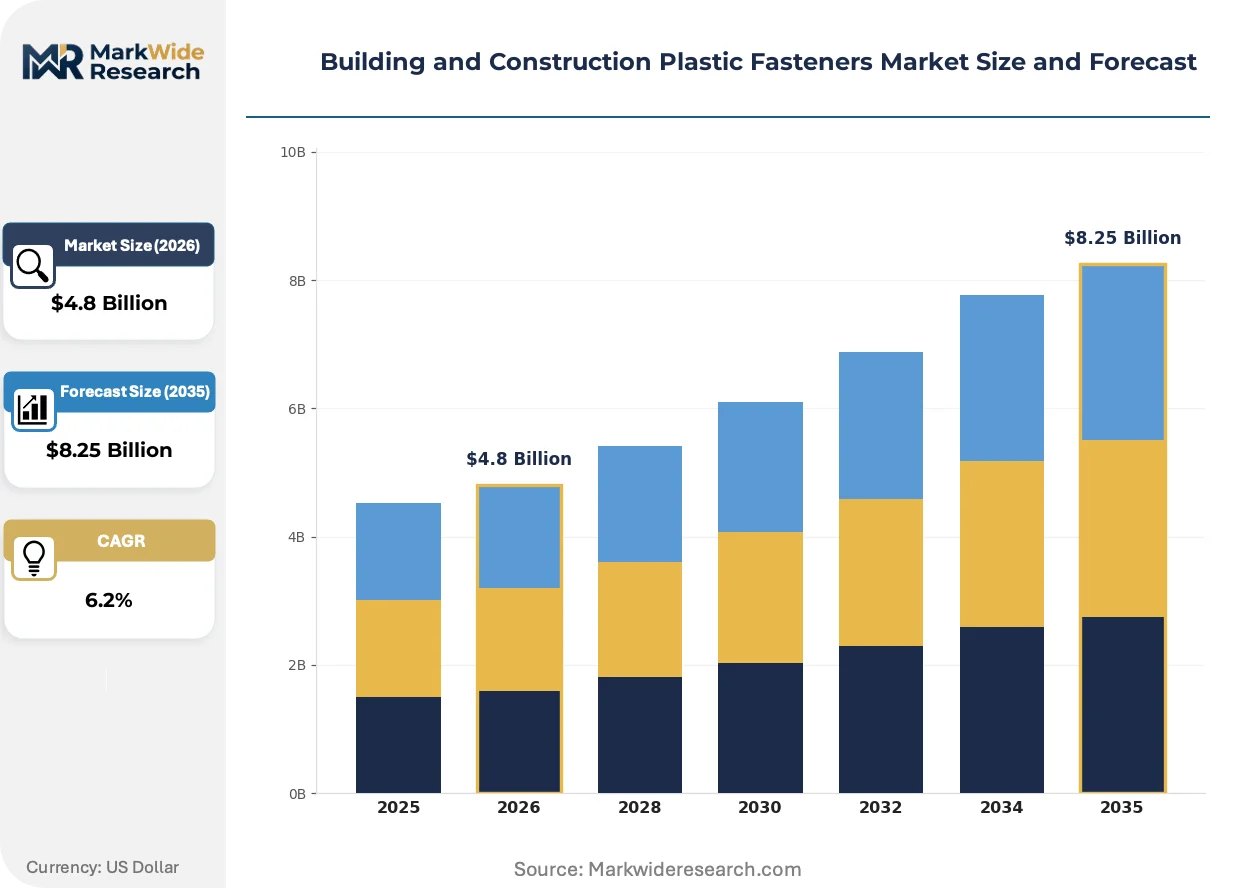
Market Dynamics
Corrosion-resistant anchoring systems are redirecting specification authority from metal-fastener incumbents toward polymer specialists as residential retrofit intensity accelerates across temperate coastal zones. REACH compliance deadlines and recycled-content mandates are compressing formulation development cycles while fragmenting supplier qualification pools.
Growth Catalysts
- Residential retrofit acceleration:Aging housing stock in Germany and the northeastern United States is driving specification of nylon 6/6 anchors for masonry and stucco remediation. Contractors prioritize installation speed over material cost in these applications.
- REACH recycled-content mandates:ECHA enforcement is redirecting R&D budgets toward post-industrial nylon feedstocks. Formulators achieving 30%+ recycled content gain preferred-supplier status with European envelope contractors.
- Curtain-wall prefabrication:Unitized facade manufacturers in China are consolidating clip and anchor procurement into single-source polymer contracts. This concentrates volume with injection molders capable of ±0.1mm tolerance control.
Market Restraints
- Caprolactam price volatility:Nylon 6/6 resin costs fluctuate with benzene derivatives markets, compressing margin stability for non-integrated fastener producers. Smaller molders lack hedging infrastructure.
- Fire-performance rating ceilings:GB 8624 classifications in China restrict polymer fastener deployment in high-rise structural connections. Metal retains mandatory specification above specific load thresholds.
- Tooling amortization burdens:Precision injection molds for glass-reinforced grades require 18-24 month payback periods at current volume. This deters entry into specialized clip geometries.
Strategic Opportunities
- India infrastructure build-out:National highway and metro expansion is creating first-mover advantage for corrosion-resistant anchoring in coastal Maharashtra and Tamil Nadu. Domestic molders lack technical depth in reinforced grades.
- Biopolymer formulation gaps:Bio-based polyamides from castor oil derivatives are approaching performance parity for non-structural clips. Early certification with BREEAM assessors unlocks premium positioning.
- Direct-to-contractor digital channels:Specialized distributors are bypassing traditional two-step distribution for mid-rise commercial projects. Digital specification tools reduce architect-to-installer information loss.
Industry Challenges
- Polymer-tooling technician scarcity:Automated fastening-system production is absorbing skilled labor from conventional mold shops. Maintenance and process optimization expertise concentrates with tier-one automotive suppliers.
- Multi-jurisdiction certification fragmentation:ICC-ES reports for US structural applications, CE marking for European envelope systems, and GB testing for Chinese fire ratings create parallel compliance cost structures. No mutual recognition exists between regimes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Building and Construction Plastic Fasteners Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anchors, Screws, Rivets, Clips Material: Polyethylene, Polypropylene, Nylon, PVC Application: Residential, Commercial, Industrial, Infrastructure Installation Method: Manual, Automated, Mechanical, Electric |
| Companies Covered | Nifco Inc, Stanley Black & Decker, Illinois Tool Works, ATF Inc., A. Raymond, MW Industries, Penn Engineering, Bossard Group, Hilti AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Building and Construction Plastic Fasteners Market Strategic Shifts & Innovations
Material substitution, regulatory disclosure requirements, and procurement centralization are compressing traditional competitive moats while opening specification pathways for specialized polymer formulators.
Glass-reinforced polyamide clips engineered for thermal-break curtain-wall systems are displacing aluminum counterparts in unitized facade assemblies across Germany and the United Kingdom. Facade contractors adopting these grades report 40% reduction in thermal bridging calculations. The displacement is compressing metal fastener share in envelope applications where electromagnetic neutrality and corrosion resistance outweigh structural load requirements.
ECHA's SCIP database obligations under REACH are forcing disclosure of Substances of Very High Concern across construction supply chains. Fastener manufacturers must now trace additives and stabilizers through three tiers of suppliers. European commercial developers are responding by pre-qualifying only those molders with certified closed-loop recycling partnerships, effectively filtering import competition from jurisdictions without equivalent disclosure infrastructure.
Consolidated procurement by multi-site general contractors is unbundling after-sales technical support from product supply. Tier-one construction groups in the United States are negotiating direct engineering partnerships with resin compounders, bypassing traditional distributor specification influence. This concentration is most visible in southeastern states where hurricane-rated envelope retrofits dominate commercial repair spending.
Building and Construction Plastic Fasteners Market Segmentation
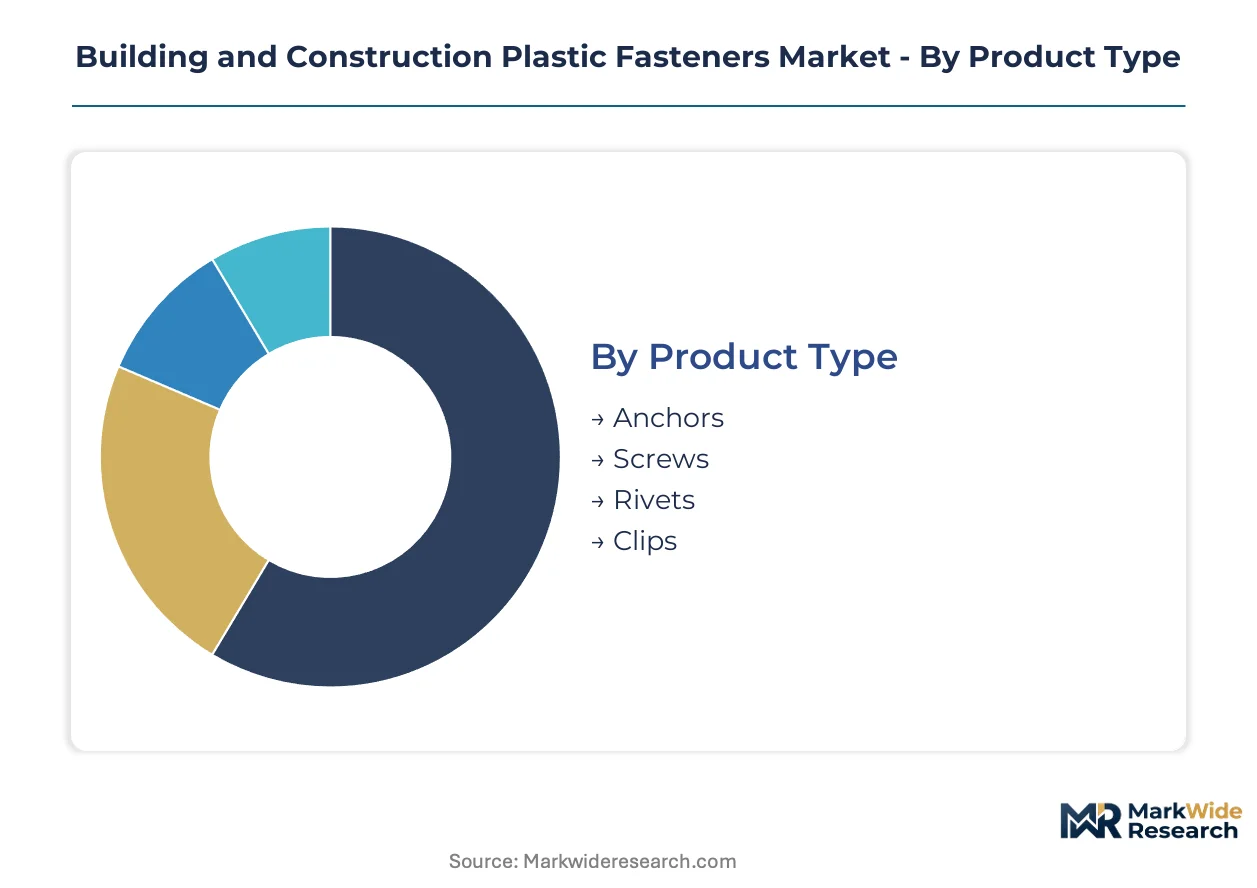
Plastic fastener procurement patterns diverge sharply across material grades, installation protocols, and end-use load requirements. Specification authority concentrates with contractors who prioritize corrosion immunity and thermal performance over upfront material cost.
Product Type:
REACH disclosure obligations and ECHA SCIP database requirements favor segments with simpler additive packages and established recycling pathways.
- Anchors:Nylon 6/6 and glass-reinforced polyamide formulations dominate masonry and concrete substrate applications. Residential retrofit contractors in Germany and the northeastern United States specify these grades for stucco remediation where corrosion resistance outweighs metal alternatives. ECHA enforcement on Substances of Very High Concern is filtering non-compliant import competition from suppliers without certified closed-loop partnerships.
- Clips:Precision injection-molded variants engineered for ±0.1mm tolerance control are displacing aluminum counterparts in unitized curtain-wall assemblies. Facade contractors report thermal bridging reductions that satisfy stricter energy codes. China's unitized facade manufacturers are consolidating procurement into single-source polymer contracts, concentrating volume with molders capable of sustained dimensional stability.
- Screws:Cold-formed and injection-molded thread designs serve interior finish and light-gauge metal applications where electromagnetic neutrality matters.
- Rivets:Specialty grades address permanent fastening in MEP routing and infrastructure cable management systems.
Anchors handle the majority of throughput; clips are expanding most quickly on specification share.
Material:
Cost tier stratification separates premium performance grades from commodity formulations used in non-structural applications.
- Nylon:Glass-reinforced and unfilled polyamide grades absorb the deepest specification volume across structural anchoring and thermal-break envelope systems. Caprolactam price volatility tied to benzene derivatives markets compresses margin stability for non-integrated producers. Smaller molders lack hedging infrastructure to buffer raw material swings.
- Polypropylene:Cost-optimized formulations serve high-volume interior finish and temporary fastening where load-bearing requirements remain minimal. India's domestic molders concentrate production here for highway and metro infrastructure projects in coastal Maharashtra and Tamil Nadu, though technical depth in reinforced grades remains scarce.
- Polyethylene:Lower-density grades address waterproofing membrane attachment and below-grade drainage applications.
- PVC:Rigid formulations serve specialized electrical conduit and cable management fastening in commercial builds.
Nylon commands premium positioning; polypropylene shows the steepest volume climb in emerging infrastructure markets.
Application:
Customer type and project scale dictate specification complexity, with large general contractors driving standardization across multi-site portfolios.
- Residential:Retrofit intensity across aging housing stock in Germany and the United States accelerates demand for rapid-installation anchoring systems. Contractors prioritize cycle-time reduction over material cost in remediation scenarios. ICC-ES evaluation reports and state-level energy codes shape product acceptance for structural and thermal-barrier applications.
- Infrastructure:Bridge, transit, and utility project awards are registering the fastest velocity as public spending activates pipelines. GB standards in China enforce fire-performance ratings that filter import eligibility, restricting polymer deployment below specific load thresholds where metal retains mandatory specification.
- Commercial:Multi-story construction and prefabricated panel systems concentrate procurement with tier-one construction groups negotiating direct engineering partnerships.
- Industrial:Manufacturing facility builds and process equipment installation generate specialized corrosion-resistant demand in chemical and coastal environments.
Residential retrofit absorbs the greatest specification volume; infrastructure project awards are climbing the fastest.
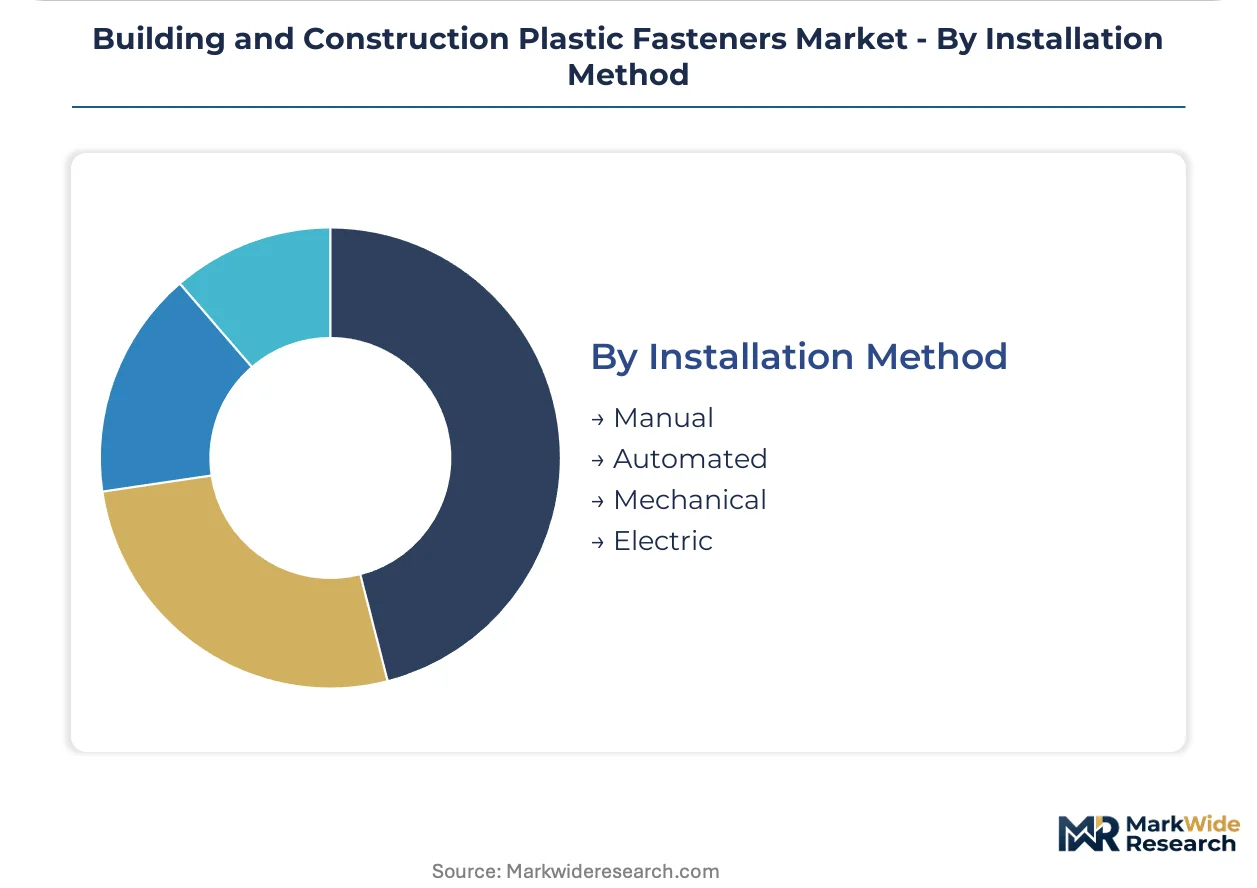
Installation Method:
Supply concentration among automated fastening-system producers is absorbing skilled polymer-tooling technicians from conventional mold shops.
- Manual:Hand-driven installation dominates residential retrofit and small-scale commercial repair where labor cost structures favor simplicity over speed. Tooling amortization for precision molds remains manageable at lower volumes.
- Mechanical:Pneumatic and gas-actuated systems serve mid-rise commercial projects where installation consistency reduces callback risk. Specialized distributors are bypassing traditional two-step distribution through digital specification tools that reduce architect-to-installer information loss.
- Automated:Robotic fastening lines in prefabrication facilities demand ±0.1mm component tolerance and dedicated process optimization expertise. Tier-one automotive suppliers concentrate this capability, tightening availability for construction-focused molders.
- Electric:Battery-powered torque-controlled drivers are penetrating commercial sites with noise and emissions restrictions.
Manual installation retains the deepest volume base; automated methods are gaining share fastest in prefabrication facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by climate exposure and regulatory maturity. Germany prioritizes thermal-break envelope performance under REACH mandates. China concentrates volume in unitized facade prefabrication. The United States splits demand between hurricane-rated coastal retrofits and interior commercial finish. India and the United Kingdom round out the five-country matrix with infrastructure stimulus and aging housing stock respectively driving procurement.
United States
Hurricane-rated envelope retrofits across Florida and the Gulf Coast accelerate specification of corrosion-resistant anchoring systems. ICC-ES evaluation reports and state-level energy codes shape product acceptance for structural applications. Southeastern general contractors consolidate procurement through direct engineering partnerships with resin compounders, bypassing traditional distributor channels.
Germany
Aging masonry housing stock in the Rhine-Ruhr and Berlin regions drives nylon 6/6 anchor demand for stucco remediation. ECHA enforcement of REACH recycled-content mandates filters non-compliant import competition. Bavarian facade contractors report thermal bridging reductions from glass-reinforced polyamide clips in unitized assemblies.
China
Unitized curtain-wall manufacturers in the Yangtze River Delta consolidate clip and anchor procurement into single-source polymer contracts. GB 8624 fire-performance ratings restrict polymer deployment above specific load thresholds in high-rise structural connections. Shanghai and Shenzhen prefabrication facilities demand ±0.1mm tolerance control from injection molders.
India
National highway and metro expansion in coastal Maharashtra and Tamil Nadu creates first-mover advantage for corrosion-resistant anchoring. Domestic molders concentrate in polypropylene formulations for cost-optimized infrastructure applications. Technical depth in glass-reinforced grades remains concentrated with tier-one automotive suppliers.
United Kingdom
Glass-reinforced polyamide clips displace aluminum counterparts in London commercial envelope retrofits targeting stricter energy codes. BREEAM assessors pre-qualify molders with certified closed-loop recycling partnerships. Midlands-based facade contractors drive specification share toward bio-based polyamide grades approaching performance parity.
Building and Construction Plastic Fasteners Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the Building and Construction Plastic Fasteners Market. Integrated compounders with captive resin production control specification authority on large commercial projects. Specialist injection molders occupy defensible niches in precision-tolerance curtain-wall applications. The two dominant competitive moves are direct-to-contractor digital channel development and backward integration into post-industrial nylon feedstock sourcing.
Among integrated tool and fastener conglomerates, Stanley Black & Decker and Illinois Tool Works exemplify the scale-driven archetype through channel density and captive compounding respectively. Nifco Inc. occupies a specialist position within the precision-molding tier. These three anchors represent the competitive spectrum from mass-market distribution pull-through to application-engineered niche dominance.
| Leading Market Players |
|---|
| Nifco Inc |
| Stanley Black & Decker |
| Illinois Tool Works |
| ATF Inc. |
| A. Raymond |
| MW Industries |
| Penn Engineering |
| Bossard Group |
| Hilti AG |
| Others |
Cost & Logistics Intelligence
Post-industrial nylon feedstock substitution for virgin caprolactam is compressing raw material cost differentials between integrated compounders and non-integrated molders while simultaneously shifting procurement geography toward European recyclers with ECHA-certified closed-loop partnerships. This displacement dynamic concentrates pricing power with compounders possessing captive resin production and qualified recycled-content streams.
Pricing Analysis
Long-term offtake contracts dominate volume procurement between tier-one construction groups and integrated resin compounders, insulating pricing from caprolactam spot volatility while compressing margins for spot-market-dependent molders. Three-tier pricing structure across premium glass-reinforced grades, standard unfilled nylon, and economy polypropylene formulations reflects certification tier and volume scale differentiation. Pricing pressure stems from benzene derivative cost swings and REACH compliance investments, with residential retrofit contractors exhibiting highest price sensitivity and unitized facade manufacturers least sensitive due to specification-locked procurement.
Supply Chain Analysis
Strategic stockpiling of glass-reinforced nylon pellets by German and Chinese injection molders buffers against caprolactam supply disruptions, while just-in-time resin delivery suffices for commodity polypropylene processors serving interior finish applications. Supply concentrates in Germany, China, and the United States for precision-tolerance molding, with raw material dependencies on benzene derivatives, recycled nylon flake, and glass fiber reinforcement. Single-source vulnerability runs through caprolactam production clusters, and distribution feeds through specialized construction distributors with direct-to-contractor digital channels penetrating mid-rise commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across REACH, ICC-ES, and GB standards is fragmenting supplier qualification pools, creating defendable niches for specialists achieving multi-jurisdiction certification ahead of scaled competitors.
For Market Incumbents: Consolidate specification authority through captive post-industrial nylon sourcing and direct engineering partnerships with multi-site general contractors. Threat from emerging biopolymer formulators demands accelerated BREEAM pre-qualification, while backward integration into recycled feedstock streams secures margin position against caprolactam volatility.
For New Entrants and Emerging Players: Lead with precision-tolerance clip manufacturing for India's coastal infrastructure build-out, where domestic technical depth in reinforced grades remains scarce. Target Maharashtra and Tamil Nadu highway contractors with corrosion-resistant anchoring solutions, deploying direct-to-contractor digital specification tools to bypass entrenched two-step distribution.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-cap injection molders with ECHA-certified recycling partnerships and ±0.1mm tolerance capabilities. Long-term viability hinges on regulatory compliance infrastructure rather than commodity scale, with acquisition targets screening for multi-jurisdiction certification progress. Watch for inflection when REACH recycled-content mandates tighten enforcement thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Nylon Feedstock | ECHA-certified closed-loop partnerships unlock preferred-supplier status with European envelope contractors. |
| Precision Tolerance Capability Investment | ±0.1mm injection molding secures single-source contracts from China's unitized facade manufacturers. |
| Direct-to-Contractor Digital Channel Development | Digital specification tools reduce architect-to-installer information loss in mid-rise commercial procurement. |
| Multi-Jurisdiction Certification Acceleration | Parallel ICC-ES, CE marking, and GB testing capability filters import competition lacking equivalent infrastructure. |
| Biopolymer Formulation Partnership | Castor oil-derived polyamide certification with BREEAM assessors enables premium positioning in UK retrofits. |
Research Approach
Cross-validation between primary interviews with polymer-tooling technicians, facade contractor procurement leads, and resin compounder technical directors and secondary sources including ECHA SCIP database filings, customs trade data on caprolactam derivatives, and SEC 10-K disclosures from integrated tool manufacturers anchors the qualitative findings. Bottom-up project pipeline tracking across German stucco remediation, Chinese prefabrication facilities, and US hurricane-rated retrofits triangulates with top-down construction spending forecasts.
Sensitivity analysis around caprolactam price trajectories, REACH enforcement intensity, and infrastructure stimulus timing tests forecast robustness across the projection horizon. Segmentation dimensions modeled include material grade tier, installation protocol, application load requirement, and regional regulatory cluster. CAGRs derive from volume-weighted project award velocity and substitution elasticity estimates for metal-to-polymer displacement in envelope applications.
The analysis sits within stated boundaries; outcomes outside sustained public infrastructure spending or stable benzene derivative pricing would require recalibration. Forecasts reflect assumptions on regulatory enforcement continuity and recycling partnership certification scalability. Revision becomes warranted when REACH recycled-content thresholds or GB fire-performance classifications cross material specification tipping points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Tower Bolt Market
Building & Construction Materials
North America Particle Board Market
Building & Construction Materials
East Africa Gypsum Plaster Market
Building & Construction Materials
Skirting Board Market
Building & Construction Materials
Electrically Dimmable Exterior Window Systems for Premium Cabins Market
Building & Construction Materials
Poland Ceramic Tiles Market
Building & Construction Materials
Vinyl Windows Market
Building & Construction Materials
Acoustic Panel Market
Building & Construction Materials
Particleboard Market
Building & Construction Materials
Europe AAC Blocks and Panels Market
Building & Construction Materials
US Terracotta Cladding Market
Building & Construction Materials
Composite Roof Shingle Market
Building & Construction Materials
Blanket Insulation Market
Building & Construction Materials
North America Laminated Veneer Lumber Market
Building & Construction Materials
Plumbing Components Market
Building & Construction Materials
Plumbing Fixtures Market