
 Particleboard Market | 2026-2036
Particleboard Market Size, Share, and Industry Trends Forecast 2026-2036
Particleboard Market Intelligence
Medium density fiberboard is pivoting away from traditional plywood in cabinetry and furniture substrates as manufacturers seek uniform surface quality and lower raw material costs. Georgia-Pacific leverages its integrated pulp-to-panel supply chain across the southeastern United States to sustain cost advantages in commodity grades. Kronospan anchors European supply through scale manufacturing in Austria and Poland, while EGGER Group differentiates via decorative laminated particleboard for ready-to-assemble furniture.
Particleboard consists of wood particles, chips, or flakes bonded with synthetic resin under heat and pressure, typically manufactured at densities between 590 and 800 kilograms per cubic meter for general-purpose applications. The material serves primarily as a cost-efficient substrate for furniture, flooring underlayment, and interior wall systems where structural performance requirements remain moderate. Laminated particleboard commands premium positioning in decorative surfaces and ready-to-assemble furniture due to pre-finished aesthetic layers that reduce downstream processing. Oriented strand board competes aggressively in structural sheathing for construction, while medium density fiberboard leads in fine-detail milling for cabinetry and molded components.
EPA TSCA Title VI regulates formaldehyde emissions from composite wood products sold in the United States, compelling manufacturers to certify compliance through third-party testing or risk market exclusion. The EU E1 classification and REACH chemical restrictions shape parallel requirements across European supply chains, while China's GB standards enforce domestic emission limits that affect export-oriented producers. Stakeholders must monitor evolving cross-border certification reciprocity and resin chemistry innovations as regulatory thresholds tighten without harmonization across major consuming regions.
Market Dynamics
Formaldehyde emission regulations are compressing supply chain economics as manufacturers absorb certification costs while competing against substitute materials in price-sensitive construction applications.
Growth Catalysts
- EU E1 Classification:Stricter emission thresholds in Europe are accelerating replacement cycles for older particleboard inventory in renovation markets.
- Furniture Manufacturing:Ready-to-assemble producers in Germany and Poland are expanding engineered wood procurement for flat-pack cabinetry and shelving systems.
- China:Urban residential construction in tier-two cities is sustaining panel demand for interior wall and flooring substrates despite broader construction moderation.
Market Restraints
- Resin Cost Volatility:Urea-formaldehyde and methylene diphenyl diisocyanate pricing fluctuations compress margins for commodity-grade producers without long-term chemical supply contracts.
- Oriented Strand Board Substitution:OSB manufacturers are capturing structural sheathing volume in North American residential construction through improved moisture resistance and code acceptance.
- EPA TSCA Title VI Compliance Burden:Third-party certification and record-keeping requirements impose fixed costs that disproportionately affect small-scale panel producers.
Strategic Opportunities
- India:Formaldehyde-compliant particleboard remains underpenetrated in commercial furniture despite BIS standards enforcement and growing organized retail infrastructure.
- Decorative Lamination Convergence:Digital printing technology and low-pressure melamine overlay systems are enabling mass-customization of surface aesthetics for residential interiors.
- EU Green Deal Procurement Mandates:Public construction projects in Germany and France are incorporating embodied carbon criteria that favor certified wood-based panels over mineral alternatives.
Industry Challenges
- Resin Chemistry Expertise Gap:Formulation chemists capable of optimizing no-added-formaldehyde adhesives for high-throughput production lines remain scarce across European and North American manufacturing bases.
- Legacy Equipment Retrofit Costs:Press modernization for thinner, higher-density panel grades requires capital outlays that strain mid-tier producers already managing emission control investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Particleboard Market |
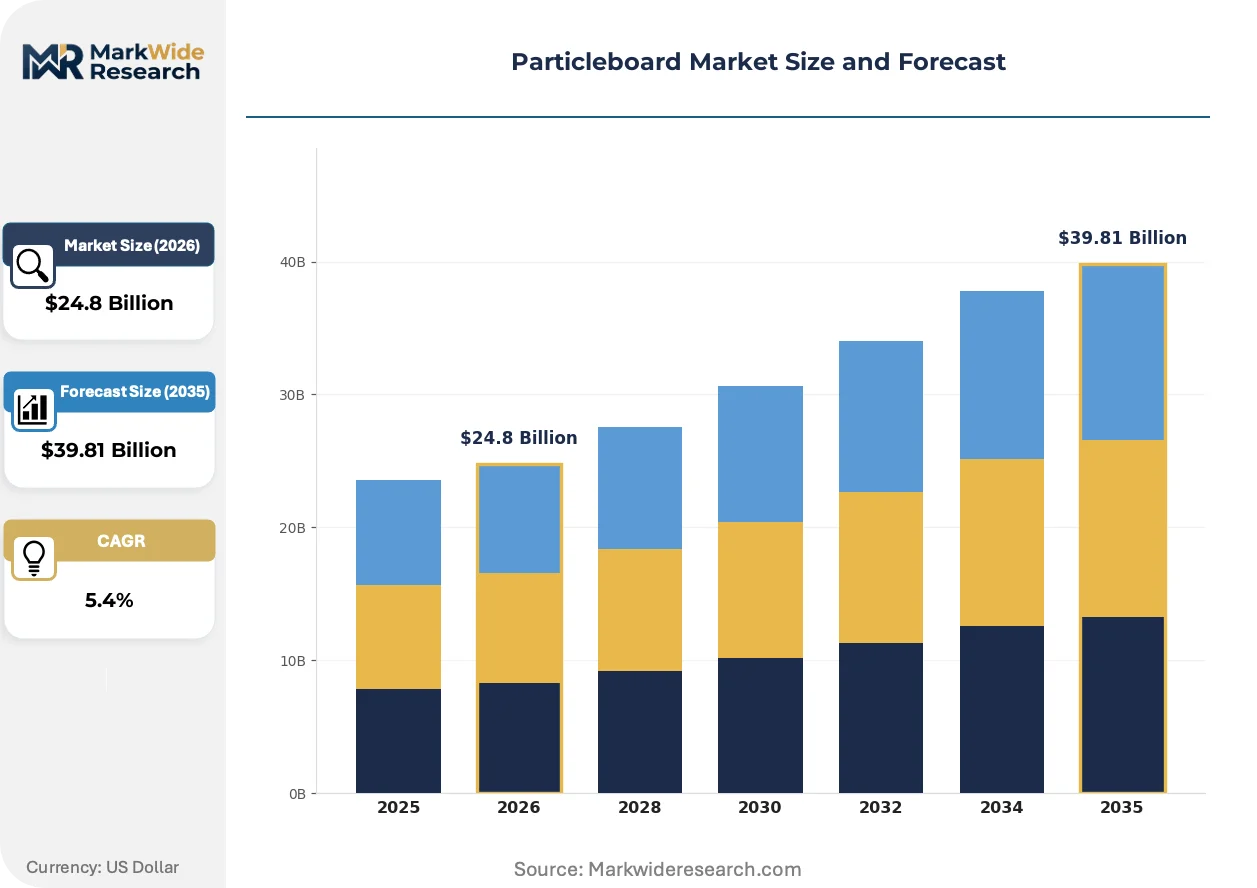
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $39.81 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medium Density Fiberboard, Oriented Strand Board, Plywood, Laminated Particleboard End User: Furniture, Construction, Interior Design, Automotive Application: Cabinetry, Flooring, Wall Panels, Decorative Surfaces Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | Georgia-Pacific, Kronospan, Kastamonu Entegre, Boise Cascade, Arauco, EGGER Group, Roseburg Forest Products, Timber Products Company, West Fraser, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Particleboard Market Strategic Shifts & Innovations
Adhesive chemistry advances and surface finishing digitization are redefining product differentiation while regulatory compliance automation reshapes quality assurance workflows across manufacturing operations.
Continuous pressing technology is expanding into thin high-density particleboard for furniture applications, enabling surface quality parity with medium density fiberboard at lower raw material input. Italian and German machinery suppliers are deploying these systems for European producers seeking to defend position in decorative panel segments. The technology is expanding into Asian markets as Chinese manufacturers upgrade from multi-opening batch presses.
REACH chemical restrictions are forcing reformulation of conventional urea-formaldehyde resins across European supply chains, with ECHA substance evaluations driving substitution toward phenol-formaldehyde and bio-based alternatives. Panel producers in Austria and Poland are front-loading R&D spending to secure pre-registration dossiers ahead of authorization deadlines. Decorative laminated grades face heightened scrutiny due to surface coating chemistry disclosure requirements.
Specification-driven procurement now dominates large-scale furniture manufacturing, with buyers mandating chain-of-custody certification and emission test reports prior to supplier qualification. Ready-to-assemble producers in Germany are consolidating vendor bases to reduce audit burden, favoring integrated mills with in-house resin production and laminating capacity. This concentration is most visible in Central European supply relationships where logistics costs amplify quality assurance economies.
Particleboard Market Segmentation
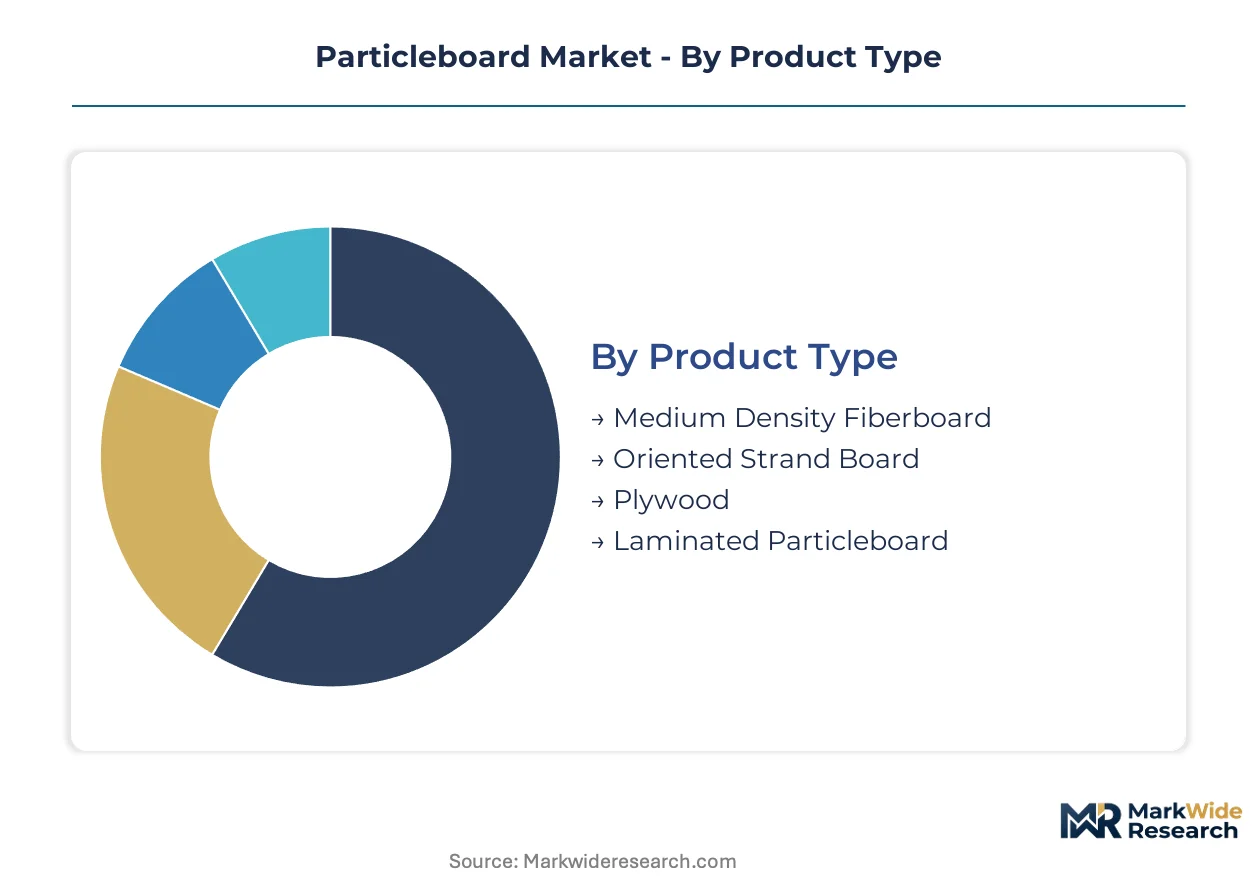
Particleboard segmentation reveals distinct value capture patterns across embedded substrates versus finished surfaces. Manufacturers optimize resin formulations and pressing technologies differently depending on whether panels serve as hidden structural layers or visible decorative elements.
Product Type:
Standalone panel products compete directly with each other in furniture and construction specifications, while embedded grades integrate into multi-material systems where substitution elasticity varies.
- Medium Density Fiberboard:Homogeneous wood fiber construction delivers superior machinability and surface uniformity for detailed edge profiling. Cabinetry producers in Germany and Poland specify MDF for painted finishes and molded components where fiber integrity outperforms particle alternatives. Tighter emission thresholds under EU E1 classification are accelerating MDF preference in premium residential interiors.
- Laminated Particleboard:Pre-finished decorative surfaces eliminate downstream sanding and coating steps for ready-to-assemble furniture manufacturers. Chinese flat-pack exporters leverage low-pressure melamine overlays to meet EU and US emission certifications while maintaining cost position. Digital printing advances enable mass-customization of wood grain and solid color aesthetics.
- Oriented Strand Board:Stranded wood flake construction delivers structural shear strength for wall sheathing and flooring substrates. OSB mills in the southeastern United States compete aggressively on moisture-resistant grades for residential construction.
- Plywood:Cross-laminated veneer construction retains specification in high-moisture applications and structural beams where dimensional stability is critical. Tropical hardwood sourcing constraints are compressing plywood cost advantages in commodity furniture.
Medium density fiberboard leads volumes today; laminated particleboard is gaining share fastest.
End User:
Customer concentration patterns diverge sharply between specification-driven contract buyers and price-sensitive spot purchasers.
- Furniture:Ready-to-assemble manufacturers in Germany, Poland, and China dominate procurement volumes for flat-pack cabinetry and shelving systems. These buyers mandate chain-of-custody certification and emission test reports prior to supplier qualification, consolidating vendor relationships around integrated mills with in-house resin and laminating capacity.
- Construction:Residential builders in the United States specify OSB and commodity particleboard for wall sheathing and flooring underlayment where code acceptance and moisture resistance determine selection. Multi-family developers in China's tier-two cities sustain panel demand for interior wall substrates.
- Interior Design:Commercial fit-out contractors source decorative laminated grades for office and retail environments where surface aesthetics and rapid installation reduce project timelines.
- Automotive:Tier suppliers mold lightweight particleboard composites for cargo area panels and seat substrates where acoustic dampening and weight reduction balance cost targets.
Furniture commands the largest revenue pool; construction exhibits the steepest price compression.
Application:
Performance requirements escalate from hidden structural layers to visible finished surfaces, driving specification complexity and margin stratification.
- Cabinetry:Frame and panel construction demands dimensional stability for door and drawer fronts where humidity cycling tests material integrity. European kitchen manufacturers specify E1-certified MDF and laminated particleboard for painted and wood-grain finishes.
- Flooring:Underlayment grades prioritize compressive strength and acoustic dampening beneath hardwood, laminate, and vinyl wear layers. Moisture-resistant particleboard competes with OSB in multi-story residential specifications.
- Wall Panels:Interior partition systems require fire-rated and acoustic-rated substrates for commercial and institutional construction. Continuous pressing technology enables thin high-density panels that rival MDF surface quality.
- Decorative Surfaces:Visible furniture and architectural elements command premium positioning through pre-finished melamine, thermally fused laminate, or digital print overlays. REACH chemical restrictions are forcing reformulation of surface coating chemistries across European supply chains.
Cabinetry anchors current volumes; decorative surfaces deliver the highest margin expansion.
Distribution Channel:
Channel economics reflect the tension between specification support requirements and logistics cost minimization.
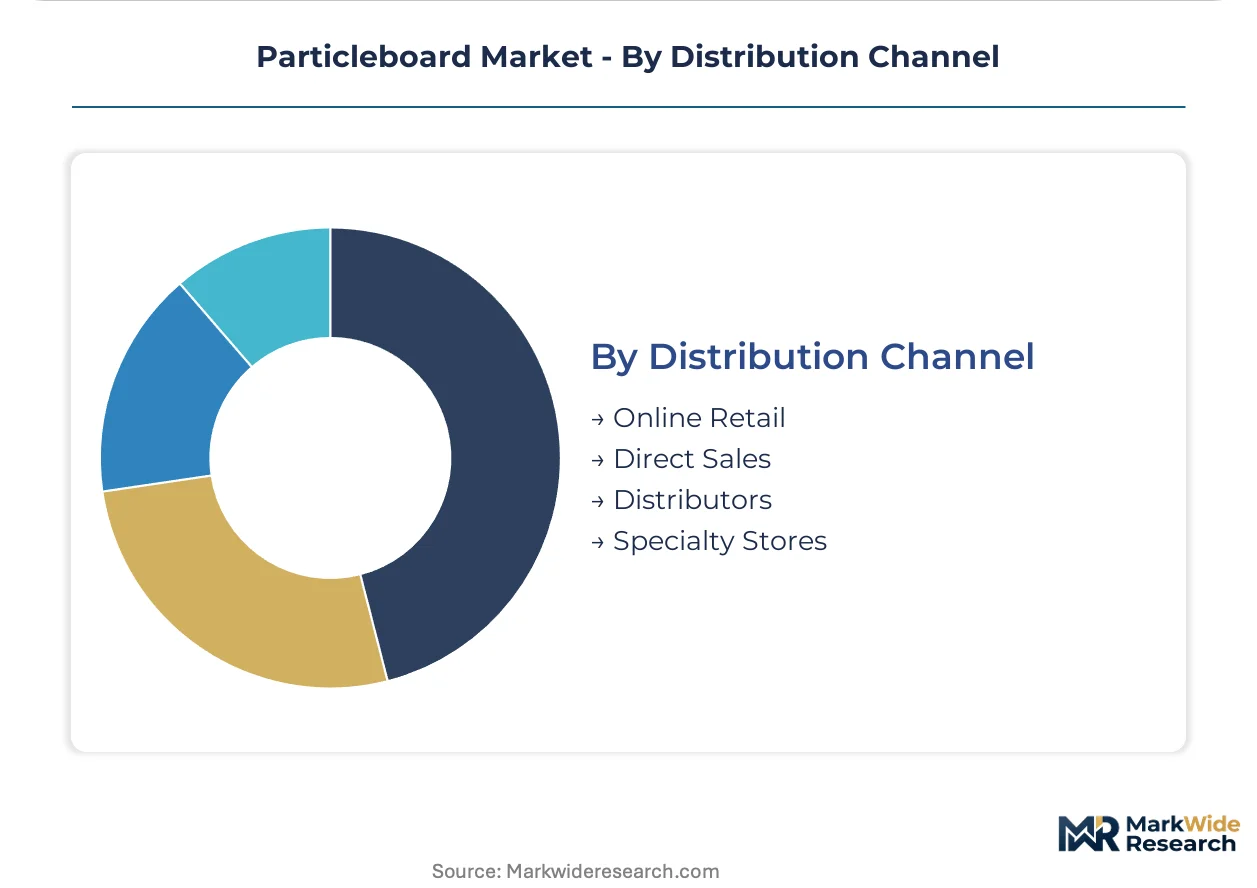
- Distributors:Regional building material distributors aggregate commodity grades for small-to-mid contractors, carrying inventory risk in exchange for margin capture. These intermediaries dominate North American construction procurement.
- Direct Sales:Large furniture manufacturers negotiate mill-direct contracts for volume grades, securing quality assurance economies and customized specifications. German ready-to-assemble producers consolidate vendor bases to reduce audit burden.
- Specialty Stores:Independent retailers serve renovation contractors and serious DIY consumers with cut-to-size services and technical consultation on grade selection.
- Online Retail:E-commerce platforms penetrate consumer and small contractor segments for standardized dimensions and pre-finished decorative panels, though freight economics limit penetration in bulk construction grades.
Distributors maintain volume leadership; direct sales channels are climbing the fastest as vendor consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The particleboard industry clusters around major furniture manufacturing hubs and integrated forest products regions. Panel demand concentrates where downstream cabinetry and ready-to-assemble furniture production co-locate with resin chemistry and laminating capabilities.
China
Tier-two city residential construction sustains particleboard consumption for interior wall and flooring substrates despite broader property sector moderation. GB standards enforcement on formaldehyde emissions compels domestic mills toward E1-equivalent certification for export-oriented production. The Yangtze River Delta hosts the densest concentration of laminating capacity serving flat-pack furniture exporters.
Germany
Ready-to-assemble furniture manufacturers in North Rhine-Westphalia drive specification-grade particleboard procurement with mandatory chain-of-custody documentation. EU E1 classification and REACH chemical restrictions shape resin formulation requirements across domestic supply chains. The Bavarian industrial corridor anchors decorative laminated panel production for premium kitchen and office furniture segments.
United States
Southeastern residential builders specify commodity particleboard and OSB for wall sheathing and flooring underlayment where code acceptance determines material selection. EPA TSCA Title VI certification requirements impose third-party testing burdens that favor integrated producers with captive resin operations. Georgia and Alabama host the largest concentrations of pulp-to-panel manufacturing capacity.
Poland
Flat-pack furniture exporters in the Łódź and Poznań regions expand engineered wood panel procurement to serve German and French retail channels. EU Green Deal procurement mandates for public construction projects favor certified wood-based panels over mineral alternatives in commercial fit-outs. The country's central European location enables just-in-time delivery consolidation for cross-border furniture assembly operations.
Austria
Decorative surface specialists in Upper Austria leverage continuous pressing technology for thin high-density particleboard rivaling MDF surface quality. ECHA substance evaluations drive pre-registration dossier preparation for phenol-formaldehyde and bio-based adhesive alternatives. The Alpine region's timber processing heritage supports vertically integrated operations from sawmilling through finished panel distribution.
Particleboard Market Key Industry Players
Capacity expansion dominates the current landscape as established producers retrofit legacy presses for thinner, higher-density grades while emission compliance investments reshape viable scale thresholds. The vendor base stratifies between integrated forest products conglomerates with captive chemical operations and mid-tier specialists concentrated in regional furniture manufacturing corridors. Two strategic archetypes define positioning: scale-driven commodity producers optimizing logistics and raw material sourcing, and specification-focused laminators commanding premium positioning through surface finishing capabilities. M&A consolidation and geographic expansion represent the dominant competitive vectors as compliance costs disproportionately burden smaller operators.
Among North American integrated producers, Georgia-Pacific exemplifies the scale-driven archetype through its southeastern United States pulp-to-panel supply chain control. Kronospan occupies a central position within European manufacturing, while EGGER Group represents the specification-focused tier emphasizing decorative laminated grades for ready-to-assemble furniture channels.
| Leading Market Players |
|---|
| Georgia-Pacific |
| Kronospan |
| Kastamonu Entegre |
| Boise Cascade |
| Arauco |
| EGGER Group |
| Roseburg Forest Products |
| Timber Products Company |
| West Fraser |
| Others |
Cost & Logistics Intelligence
Ready-to-assemble furniture manufacturers in Germany and Poland command disproportionate pricing leverage through consolidated vendor bases and mandatory chain-of-custody documentation requirements. This buyer concentration enforces contract-based long-term offtake structures that compress margins for commodity-grade producers while rewarding integrated mills with captive resin and laminating capacity.
Pricing Analysis
Resin chemistry costs pass through unevenly across particleboard tiers, with urea-formaldehyde and methylene diphenyl diisocyanate volatility hitting commodity producers hardest. Three-tier pricing structure across premium, standard, and economy levels separates E1-certified decorative laminates from uncertified construction substrates and spot-market OSB. Pricing pressure stems from OSB substitution in North American structural sheathing, where moisture-resistant grades capture code-compliant volume. Small-scale panel producers exhibit highest price sensitivity due to disproportionate EPA TSCA Title VI compliance burdens, while specification-grade laminators defend premium positioning through surface finishing differentiation.
Supply Chain Analysis
Domestic-content mandates in China's GB standards enforcement and EU Green Deal procurement criteria reshape sourcing toward certified regional mills. Supply concentrates in China, Germany, and the United States, where integrated forest products corridors anchor pulp-to-panel manufacturing. Raw material dependencies rest on softwood timber residuals, synthetic resin formulations, and melamine overlay films. Single-source vulnerability in specialized adhesive chemistry exposes European producers to ECHA substance evaluation disruptions. Distribution runs through regional building material distributors for construction grades and direct mill contracts for furniture manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EPA TSCA Title VI and EU E1 classification milestones accelerating replacement cycles and consolidation economics.
For Market Incumbents: Cement supply security through backward integration into resin chemistry and continuous pressing technology upgrades. Georgia-Pacific's southeastern pulp-to-panel model demonstrates cost defense against commodity-grade competitors. Prioritize press modernization for thin high-density grades that rival MDF surface quality in decorative segments. For New Entrants and Emerging Players: Capture white space in India's formaldehyde-compliant commercial furniture segment, where BIS standards enforcement meets underpenetrated organized retail infrastructure. Target tier-two Chinese cities for interior wall substrate demand sustained despite broader construction moderation. Lead with digital printing-enabled mass-customization capabilities to bypass incumbent lamination scale advantages. For Investors and Strategic Acquirers: Integrated forest products conglomerates are the most active acquirer in this space, seeking mid-tier specialists with stranded laminating assets and emission-compliant capacity. Long-term viability hinges on resin chemistry expertise and certification automation infrastructure. Watch for ECHA authorization deadlines as inflection indicators for phenol-formaldehyde and bio-based adhesive substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Press Technology Deployment | Italian and German machinery suppliers enable thin high-density particleboard surface quality parity with MDF. |
| Resin Chemistry Backward Integration | Captive urea-formaldehyde and phenol-formaldehyde production defends margin against chemical cost volatility. |
| Digital Printing Surface Customization | Low-pressure melamine overlay systems enable mass-customization for ready-to-assemble furniture channels. |
| EU Green Deal Certification Alignment | Embodied carbon criteria in German and French public construction favor certified wood-based panels. |
| Vendor Base Consolidation Programs | Large furniture manufacturers reduce audit burden by qualifying integrated mills with in-house laminating capacity. |
Research Approach
Bottom-up furniture and construction modeling reconciled against top-down panel production tracking forms the analytical core of this study. Primary interviews with plant managers, procurement leads at ready-to-assemble manufacturers, distribution channel partners, and technical R&D directors in resin chemistry were validated against customs and trade data, EPA certification registries, EU ECHA substance databases, and forest products industry association reports. Triangulation between demand-side specification patterns and supply-side capacity utilization ensures segmentation integrity.
Input-output matrices linking timber residual availability, resin formulation costs, and press capacity utilization drive volume projections across the analysis window. Segmentation dimensions include product type tier, end-use vertical, application performance requirement, and regional regulatory cluster. CAGRs derive from regression analysis of historical capacity expansion against downstream demand elasticity, incorporating continuous pressing technology diffusion rates and emission standard implementation timelines as industry-specific forecast inputs.
Resin cost volatility, regulatory reciprocity failures between EPA TSCA Title VI and EU E1 classifications, and OSB substitution acceleration in structural applications are the dominant revision risks. Forecasts reflect documented assumptions on technology adoption curves and certification compliance rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Runway Pavement Grade Asphalt Market
Building & Construction Materials
Philippines Building System Components Market
Building & Construction Materials
Poland Cement Market
Building & Construction Materials
Masonry Sealers Market
Building & Construction Materials
North America Concrete Superplasticizer Market
Building & Construction Materials
Canada Facade Market
Building & Construction Materials
Point Supported Glass Curtain Wall Market
Building & Construction Materials
US Glass Curtain Wall Market
Building & Construction Materials
Insulating Glass Window Market
Building & Construction Materials
Carbon Textile Reinforced Concrete Market
Building & Construction Materials
North America Industrial Flooring Market
Building & Construction Materials
GCC Concrete Blocks Market
Building & Construction Materials
Concrete Formwork System Market
Building & Construction Materials
Residential Non-metal Electrical Conduit Market
Building & Construction Materials
India Stainless Steel Plumbing Pipes and Fittings Market
Building & Construction Materials
Steel Wire Rope Products Market