
 Plumbing Components Market | 2026-2036
Plumbing Components Market Size, Share, and Industry Trends Forecast 2026-2036
Plumbing Components Market Insights
Modular bathroom pod configurations is rebalancing procurement patterns across commercial construction channels. Kohler leverages in-house casting capabilities to control faucet supply chains. Moen sustains brand preference through cartridge standardization that reduces installer switching costs. Geberit anchors European sanitary systems with integrated wall-hung toilet and carrier bundles.
Plumbing components encompass pipes, fittings, valves, and hoses engineered to convey fluids, regulate flow, and maintain pressure integrity across building systems. Cross-linked polyethylene (PEX) tubing operates at sustained temperatures up to 200°F with oxygen-barrier layers for hydronic heating loops. Plastic materials lead residential new construction due to lower installed labor and freeze-resistance properties. Copper fittings retain premium positioning in commercial mechanical rooms where fire-code compliance and joint accessibility govern specification. Valve assemblies concentrate margin pools in industrial process applications requiring automated actuation and fail-safe shutoff protocols.
EPA lead-free standards under the Safe Drinking Water Act mandate weighted-average lead content below 0.25% in wetted surfaces, reshaping brass alloy formulations across US manufacturers. EU REACH restrictions on nickel and chromium leaching impose material testing burdens on European suppliers while creating compliance barriers for uncertified imports. India's BIS certification for polymer pipes enforces hydrostatic pressure ratings that filter substandard domestic producers from municipal tenders. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border distribution networks.
Market Dynamics
Copper-to-plastic substitution is restructuring procurement economics across potable water systems as regulatory lead-content ceilings and installation labor costs simultaneously pressure legacy material specifications.
Growth Catalysts
- EPA lead-free mandates:The Safe Drinking Water Act's 0.25% weighted-average threshold is forcing brass alloy reformulation across US manufacturers, opening specification windows for polymer alternatives in residential distribution.
- Urban infrastructure corridors:India's municipal water system retrofits are concentrating demand for cross-linked polyethylene piping in high-density metropolitan construction zones.
- Modular bathroom pods:Prefabricated sanitary unit configurations are rebalancing component procurement patterns across commercial construction channels toward bundled subsystem contracts.
Market Restraints
- Copper price volatility:LME copper fluctuations compress margin predictability for manufacturers maintaining dual-material production lines and alloy inventory positions.
- EU REACH compliance burden:Nickel and chromium leaching restrictions impose material testing costs that filter uncertified imports from European distribution networks.
- Technical limitation in hydronics:Oxygen-barrier PEX requirements for closed-loop heating systems restrict material sourcing to specialized extrusion grades with limited supplier base.
Strategic Opportunities
- Freeze-resistant polymer expansion:PEX tubing's performance in cold-climate residential applications creates specification entry points in northern US and Canadian housing markets previously dominated by copper.
- Automated valve actuation:Integration of sensor-enabled flow control with building management systems opens industrial process applications requiring fail-safe shutoff protocols.
- India BIS certification alignment:Hydrostatic pressure rating enforcement in municipal tenders creates compliance-based moats for certified domestic producers against unstandardized imports.
Industry Challenges
- Installer skill transition:Mechanical joining techniques for copper systems require retraining pipelines for heat-fusion and crimp-connection methods in plastic-dominant specifications.
- Cross-border inventory stranding:Divergent material certification requirements between US EPA, EU REACH, and India BIS regimes complicate centralized manufacturing and distribution strategies.
- Legacy system integration:Retrofit compatibility between new polymer distribution lines and existing copper branch connections demands transitional fitting inventories and field adaptation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plumbing Components Market |
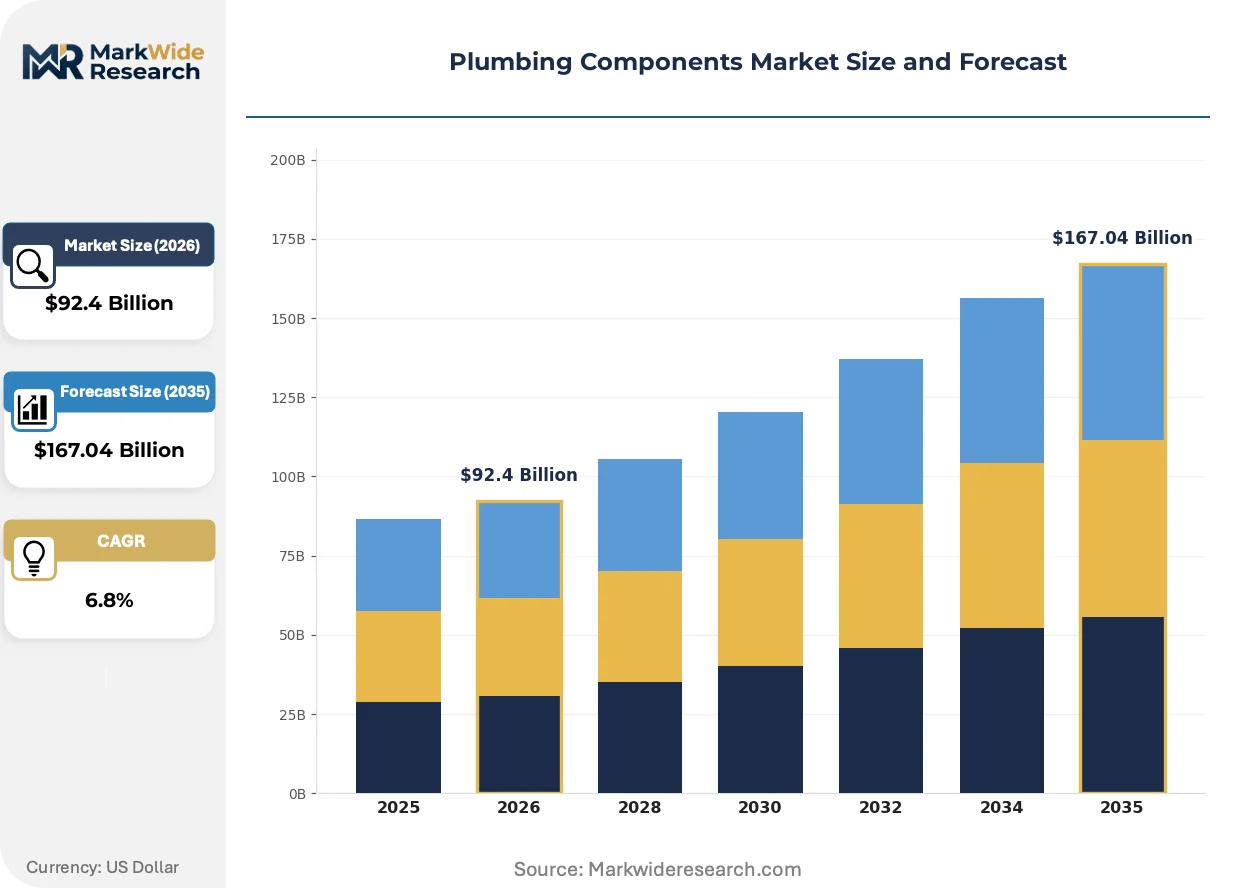
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $167.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pipes, Fittings, Valves, Hoses Material: Plastic, Copper, Steel, PVC Application: Residential, Commercial, Industrial, Irrigation Distribution Channel: Wholesalers, Retailers, Online, Direct Sales |
| Companies Covered | Kohler, Moen, LIXIL Corporation, Geberit, American Standard, Uponor, Hansgrohe, Mueller Industries, Aalberts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plumbing Components Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are converging to accelerate specification turnover in fluid conveyance systems, compressing traditional product lifecycles and rewiring supplier-buyer relationships.
Cross-linked polyethylene tubing is overtaking copper in residential new construction specifications. Builders in Southeast Asian markets specify PEX for its lower installed labor requirements and freeze-resistance properties. The technology is overtaking established mechanical joining methods by eliminating solder certification dependencies and enabling faster rough-in completion.
EU REACH restrictions on nickel and chromium leaching are reshaping brass alloy formulations for potable water applications. European manufacturers face material testing burdens that raise production costs but simultaneously create compliance barriers against uncertified import competition. Sanitary valve and faucet producers serving EU member states are accelerating plastic-ceramic hybrid development to preempt future metal-content limitations.
Commercial construction buyers are consolidating component procurement around pre-integrated sanitary subsystems. Modular bathroom pod fabricators now specify complete wall-hung toilet and carrier bundles rather than discrete valve and fitting purchases. This specification consolidation is most visible in European hospitality and healthcare verticals where installation timeline compression commands premium pricing power.
Plumbing Components Market Segmentation
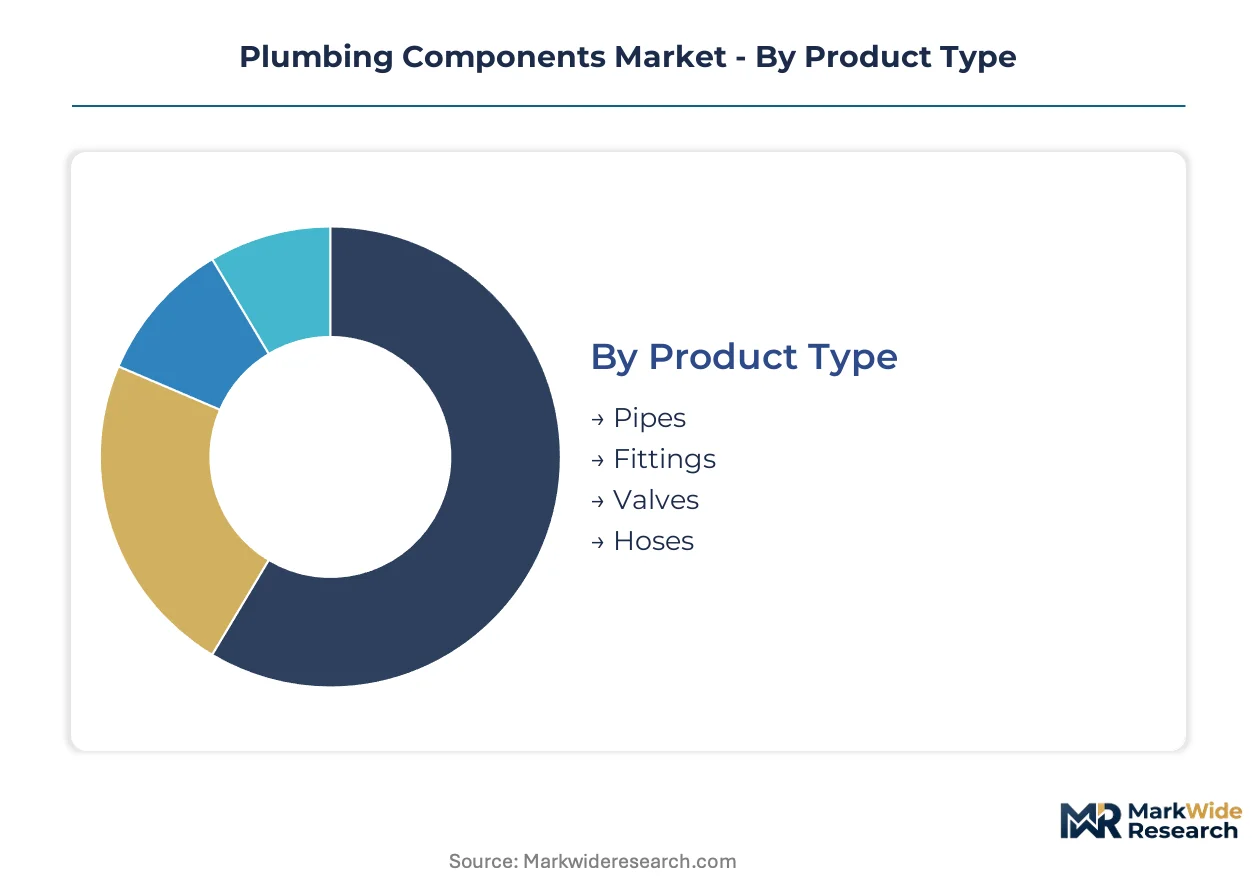
Plumbing component procurement varies sharply across specification tiers, with certification requirements and installation labor costs driving divergent margin structures. Segmentation reveals where regulatory compliance creates pricing power and where commoditization pressures dominate.
Product Type:
EPA lead-free mandates under the Safe Drinking Water Act and EU REACH material restrictions impose distinct certification burdens across each product category, filtering supplier participation by testing capacity.
- Pipes:Cross-linked polyethylene tubing dominates residential new construction with oxygen-barrier layers for hydronic heating loops. Demand concentrates in India's urban infrastructure corridors where municipal water system retrofits expand PEX specifications for freeze-resistance and lower installed labor.
- Fittings:Brass alloy formulations face reformulation pressure from 0.25% weighted-average lead content ceilings, opening specification windows for polymer alternatives. Copper fittings retain premium positioning in commercial mechanical rooms where fire-code compliance and joint accessibility govern selection.
- Valves:Automated actuation assemblies concentrate margin pools in industrial process applications requiring fail-safe shutoff protocols.
- Hoses:Flexible connectors for appliance and fixture installations face nickel and chromium leaching restrictions under EU REACH, raising material testing costs for European distribution.
Leading the category by volume: Pipes. Growing fastest: Valves.
Material:
Cost tier stratification separates premium metal specifications from volume plastic applications, with mid-range hybrids emerging at regulatory boundaries.
- Plastic:PEX and polymer alternatives capture residential share through lower installed labor and freeze-resistance. India's BIS certification for polymer pipes enforces hydrostatic pressure ratings that filter substandard domestic producers from municipal tenders.
- Copper:LME price volatility compresses margin predictability for manufacturers maintaining dual-material production lines and alloy inventory positions.
- Steel:Industrial process applications specify carbon and stainless grades for high-pressure steam and chemical conveyance.
- PVC:Drain-waste-vent systems and non-potable irrigation specify unplasticized formulations for cost-sensitive volume deployment.
Plastic commands the greatest volume share. Copper maintains the highest value per kilogram.
Application:
End-use concentration determines whether procurement flows through bundled subsystem contracts or discrete component purchasing.
- Residential:New construction specifications favor PEX for rough-in speed and installer retraining efficiency. Southeast Asian builders specify plastic systems for lower labor requirements.
- Commercial:Modular bathroom pod configurations rebalance procurement toward pre-integrated sanitary bundles in hospitality and healthcare verticals.
- Industrial:Automated valve actuation and sensor-enabled flow control integration with building management systems open specification opportunities.
- Irrigation:Agricultural and landscape applications specify PVC and polyethylene for cost-driven volume deployment.
Residential generates the largest absolute demand. Commercial delivers the highest contract values per project.
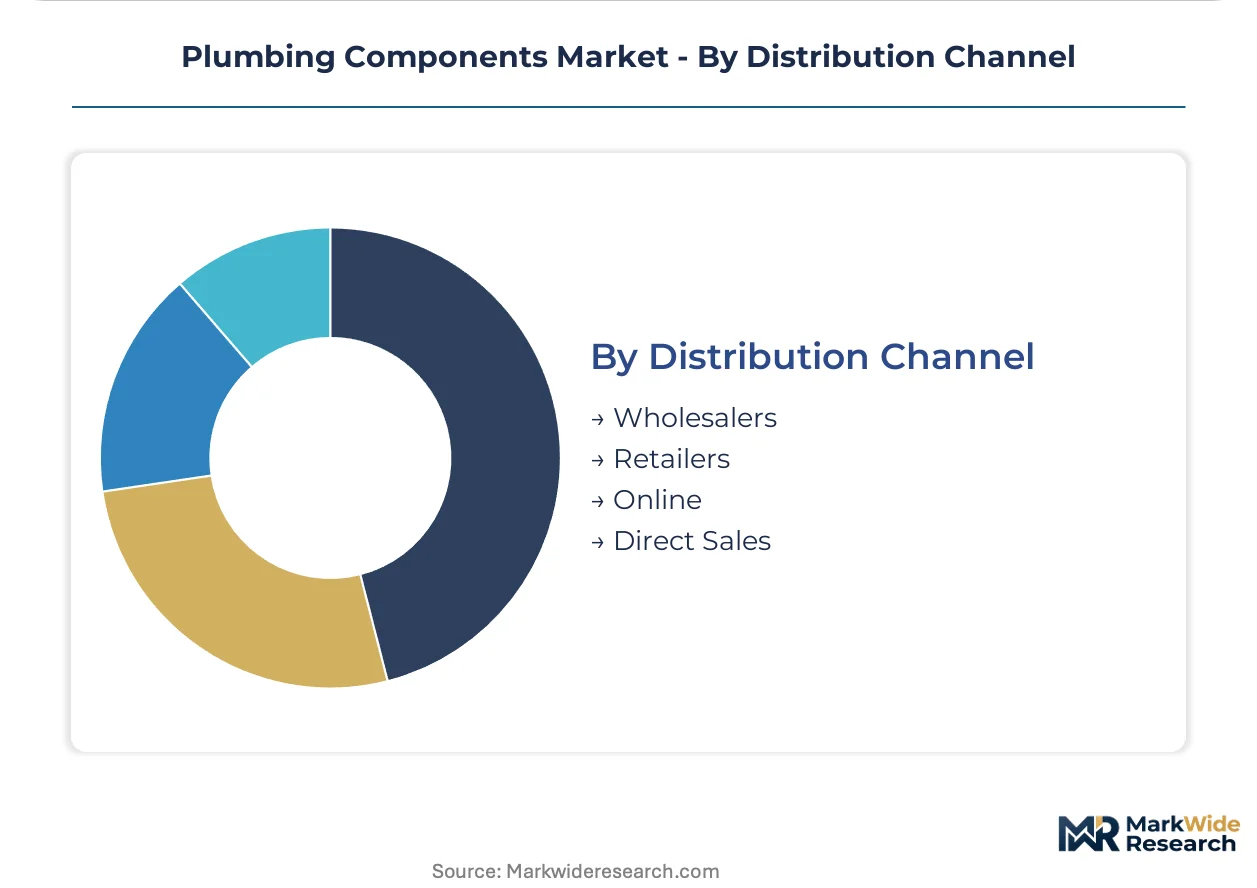
Distribution Channel:
Customer type and purchase scale determine channel selection, with procurement consolidation favoring integrated supply arrangements.
- Wholesalers:Plumbing contractors and mechanical trades source through regional distributors maintaining transitional fitting inventories for legacy system integration.
- Retailers:Home improvement and hardware channels serve repair-replacement demand with standardized SKUs.
- Online:Direct-to-contractor platforms gain share for specification-grade products with documented certifications.
- Direct Sales:Large commercial and industrial accounts negotiate subsystem bundles with manufacturers.
Wholesalers retain the dominant transaction volume. Online channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's dedicated freight corridors and smart city special economic zones concentrate plumbing component demand in high-density urban construction corridors. Municipal water system retrofits and affordable housing mandates drive specification volume across metropolitan infrastructure projects.
United States
Residential new construction in Texas and Florida specifies PEX tubing for freeze-resistance and rough-in speed. EPA lead-free mandates under the Safe Drinking Water Act force brass alloy reformulation across domestic manufacturers. The Sun Belt corridor from Phoenix to Atlanta concentrates demand for polymer distribution systems in single-family housing developments.
Germany
Commercial hospitality and healthcare verticals specify modular bathroom pod configurations with integrated wall-hung sanitary systems. EU REACH restrictions on nickel and chromium leaching raise material testing costs for brass valve producers. The Rhine-Ruhr industrial cluster anchors European sanitary system manufacturing with captive foundry and extrusion capabilities.
China
Urbanization in the Yangtze River Delta drives municipal water infrastructure investment with standardized polymer pipe specifications. GB standards for building water supply enforce hydrostatic pressure ratings that filter substandard domestic producers from government tenders. Shanghai's construction material wholesale markets concentrate distribution for Southeast Asian export channels.
India
Municipal water system retrofits in Delhi-NCR and Mumbai metropolitan regions expand cross-linked polyethylene specifications for corrosion resistance. BIS certification for polymer pipes enforces quality benchmarks that create compliance moats for certified domestic manufacturers against unstandardized imports. Gujarat's petrochemical corridor supplies raw material feedstock for PEX extrusion operations serving western Indian infrastructure projects.
Plumbing Components Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies between integrated building product portfolios and component-centric manufacturing operations. Three archetypes dominate: full-line sanitary system suppliers, polymer tubing specialists, and brass valve fabricators. Capacity expansion in Southeast Asian extrusion facilities and strategic partnerships for modular bathroom pod integration represent the dominant competitive moves reshaping procurement relationships.
Within the integrated sanitary systems tier, Kohler and LIXIL Corporation exemplify full-line portfolio breadth spanning fixtures, faucets, and connected water technologies. Moen occupies a position among North American faucet specialists leveraging cartridge standardization to reduce installer switching costs. Geberit anchors European wall-hung toilet and carrier bundle configurations through pre-integrated subsystem offerings. These three companies represent distinct strategic postures: conglomerate diversification, component specialization with proprietary interfaces, and subsystem bundling for commercial specification consolidation.
| Leading Market Players |
|---|
| Kohler |
| Moen |
| LIXIL Corporation |
| Geberit |
| American Standard |
| Uponor |
| Hansgrohe |
| Mueller Industries |
| Aalberts |
| Others |
Pricing and Supply Chain Analysis
Captive brass foundry operations anchor pricing power for integrated sanitary system suppliers. Kohler and Geberit control alloy formulation costs through backward integration into casting facilities, insulating margin positions from LME copper volatility while commanding premium positioning for lead-free certified components.
Pricing Analysis
Short lead-time premiums dominate commercial project procurement, with modular bathroom pod fabricators paying 15-25% markups for expedited carrier bundle delivery. Three-tier pricing structure across premium, standard, and economy levels separates EPA-certified lead-free brass from uncertified imports and basic polymer alternatives. Cost compression in standard-grade PEX tubing is intensifying because Chinese extrusion capacity expansion outpaces Southeast Asian demand growth. Residential contractors exhibit highest price sensitivity, while healthcare facility developers prioritize certification compliance over unit cost.
Supply Chain Analysis
Refurbishment flows for commercial valve assemblies create secondary material recovery channels, with remanufactured actuation components capturing 8-12% of European industrial aftermarket value. Raw material supply concentrates in China for polymer resin feedstock, Germany for precision brass forging equipment, and India for BIS-certified extrusion operations. Component sourcing draws from copper cathode contracts tied to LME pricing, specialized PEX oxygen-barrier additives from German chemical suppliers, and ceramic disc valve cartridges from Chinese ceramics clusters. Single-source vulnerability sits with oxygen-barrier PEX extrusion grades, where only three certified suppliers serve global hydronic heating demand. Distribution runs through regional plumbing wholesalers maintaining transitional fitting inventories for legacy copper-to-plastic integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized oxygen-barrier PEX extrusion capacity constraints prop pricing power for certified suppliers. The analysis window reveals supply-constrained conditions in hydronic heating loop specifications, with limited qualified extruders creating procurement bottlenecks for commercial mechanical contractors.
For Market Incumbents: Deepen captive foundry integration to control brass alloy cost positions against copper price volatility. Expand BIS-certified extrusion capacity in Gujarat's petrochemical corridor to capture Indian municipal tender volume. Defend against polymer substitution threats by accelerating lead-free certification for legacy brass fitting portfolios. For New Entrants and Emerging Players: Small-scale commercial retrofit contractors represent an underserved buyer archetype lacking bundled subsystem procurement access. Target India's tier-2 municipal water authorities with simplified PEX specification packages bypassing complex import certification pathways. Pursue direct-to-contractor digital platforms with documented EPA and BIS compliance documentation. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by building product conglomerates seeking sanitary system integration. Long-term viability favors certified polymer extruders with regional regulatory moats. Monitor oxygen-barrier PEX capacity expansion announcements as inflection indicators for pricing power erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brass Foundry Operations | Kohler's captive casting facilities insulate margin positions from LME copper volatility and EPA alloy reformulation costs. |
| BIS Certification Alignment for Polymer Pipes | Domestic Indian extruders gain compliance moats against unstandardized imports in municipal water retrofit tenders. |
| Modular Bathroom Pod Subsystem Bundling | Geberit's integrated wall-hung toilet and carrier configurations capture specification consolidation in European hospitality verticals. |
| Automated Valve Actuation Development | Sensor-enabled flow control integration with building management systems opens industrial process applications requiring fail-safe protocols. |
| Direct-to-Contractor Digital Platform Launch | Online channels with documented EPA lead-free and BIS hydrostatic certifications gain share from traditional wholesale distribution. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with plumbing contractors, mechanical engineering consultants, municipal procurement officers, and brass foundry operations managers combined with EPA Safe Drinking Water Act documentation, India BIS certification registries, EU ECHA REACH restriction databases, and copper trade flow statistics. Bottom-up project pipeline assessment and top-down construction spending allocation triangulated volume estimates across the analysis window.
Product-level granularity modeled pipes, fittings, valves, and hoses separately by material grade and certification tier. Application segmentation distinguished residential new construction, commercial modular pod integration, industrial process systems, and municipal infrastructure retrofits. Geographic modeling captured country-specific regulatory divergence between US EPA lead-free mandates, EU REACH nickel restrictions, and India BIS pressure ratings. CAGRs derived from construction spending forecasts, housing start projections, and infrastructure investment pipelines without year-specific anchoring.
Revisions become necessary when regulatory enforcement intensity shifts, raw material substitution accelerates beyond modeled rates, or certified extrusion capacity expands faster than demand absorption. Practitioners should monitor EPA audit frequency, LME copper volatility spikes, and Indian municipal tender award patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
North America Decks Market
Building & Construction Materials
North America Concrete Superplasticizer Market
Building & Construction Materials
Rubber Expansion Joints Market
Building & Construction Materials
Curtain Wall Market
Building & Construction Materials
Global Aluminum Cladding Panels Market
Building & Construction Materials
Roofing Underlayment Market
Building & Construction Materials
Roofing Shingles Market
Building & Construction Materials
Global Hydraulic Door Closer Market
Building & Construction Materials
Middle-East and Africa Industrial Flooring Market
Building & Construction Materials
Mineral Wool Ceiling Tiles Market
Building & Construction Materials
Japan Oriented Strand Board Market
Building & Construction Materials
Metal Grating Market
Building & Construction Materials
Pre-Insulated Pipes Market
Building & Construction Materials
Waterproofing Solution Market
Building & Construction Materials
Africa Vinyl Windows Market
Building & Construction Materials
North America Non-Residential Polished Concrete Market