
 North America Particle Board Market | 2026-2036
North America Particle Board Market Size, Share, and Industry Trends Forecast 2026-2036
North America Particle Board Market Analytics
Digital panel optimization and automated pressing control is reconfiguring how North American particle board achieves density uniformity and resin efficiency. Georgia-Pacific leverages extensive southern pine sourcing to sustain cost-advantaged furnish access across its southeastern mill network. Roseburg Forest Products anchors its position through integrated timberland-to-panel operations in Oregon and California. Arauco competes via specialized decorative particle board grades targeting cabinetry OEMs.
Particle board consists of wood particles, chips, and flakes bonded with synthetic resin under heat and pressure, typically achieving densities between 600-800 kg/m³ for general-purpose grades and serving primarily as a substrate for furniture, cabinetry, and interior construction applications. The dry process dominates North American manufacturing due to lower energy intensity and faster cycle times compared to wet-process alternatives. Moisture resistant particle board commands premium positioning in kitchen and bath applications where ANSI A208.1 Type M-2 certification governs performance claims. Standard particle board remains the volume leader in residential construction subflooring and shelving, though margin pools concentrate in decorative and specialty grades.
EPA's TSCA Title VI formaldehyde standards, California Air Resources Board ATCM Phase 2 limits, and ANSI A208.1 product specifications collectively define compliance thresholds for panel emissions and structural performance across the United States and Canada. Health Canada maintains aligned but distinct surface coating and indoor air quality guidelines affecting cross-border product certification. Stakeholders must monitor evolving state-level procurement preferences for low-emitting materials alongside potential harmonization gaps between U.S. and Canadian testing protocols.
Market Dynamics
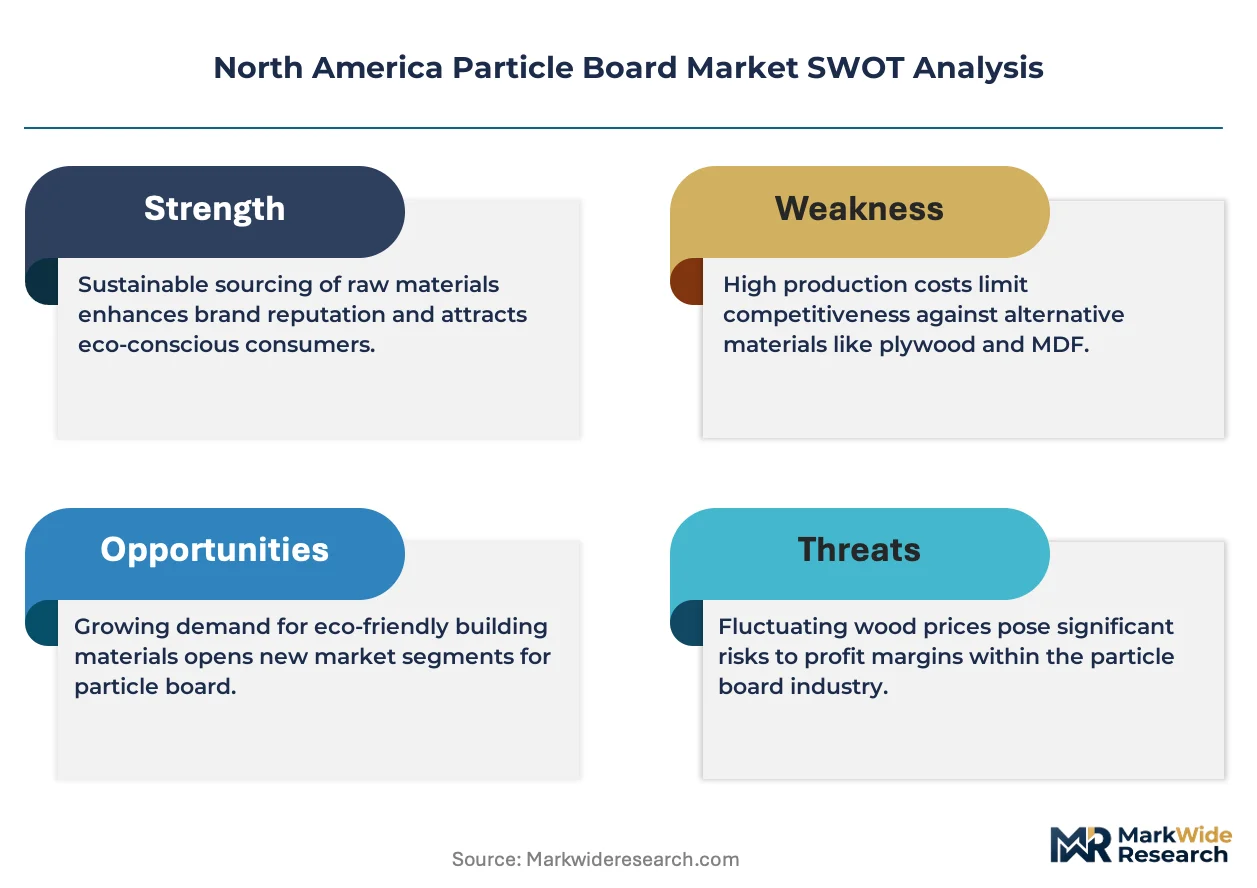
EPA's TSCA Title VI formaldehyde emission standards are compressing the competitive set by forcing capital-intensive compliance upgrades while simultaneously creating tiered product differentiation between certified and non-certified supply. This regulatory pressure is concentrating volume among producers with captive resin synthesis and testing infrastructure.
Growth Catalysts
- Multi-family housing construction:Residential builders across the southern United States are expanding particle board procurement for interior fit-outs as rental housing starts accelerate.
- ANSI A208.1 Type M-2 certification:Moisture-resistant grades are capturing premium positioning in kitchen and bath applications where performance claims govern specification decisions.
- Querétaro furniture manufacturing:Mexico's central corridor is concentrating demand from cabinetry OEMs sourcing decorative particle board substrates for North American distribution.
Market Restraints
- Southern pine furnish volatility:Timber supply concentration in the southeastern United States creates input cost exposure during weather-driven harvest disruptions.
- MDF substitution in premium cabinetry:Medium-density fiberboard is capturing specification share in high-end furniture applications where surface smoothness governs buyer preference.
- Cross-border testing protocol friction:Divergent surface coating guidelines between EPA and Health Canada complicate unified product certification for integrated North American supply chains.
Strategic Opportunities
- California Air Resources Board ATCM Phase 2 alignment:Early compliance with the nation's most stringent emission limits creates specification access to state-level green procurement programs.
- Dry process automation convergence:Digital panel optimization combined with automated pressing control is opening resin efficiency gains and density uniformity improvements.
- Direct-to-fabricator distribution:Bypassing traditional distribution layers to serve Querétaro-area cabinetry OEMs is compressing channel costs and accelerating order-to-delivery cycles.
Industry Challenges
- Resin chemistry expertise scarcity:Formulation talent capable of balancing emission compliance with cost targets is concentrated among legacy producers with captive R&D infrastructure.
- Press line reconfiguration capex:Continuous belt press upgrades required for digital control integration demand multi-year capital commitment amid uncertain certification timeline clarity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Particle Board Market |
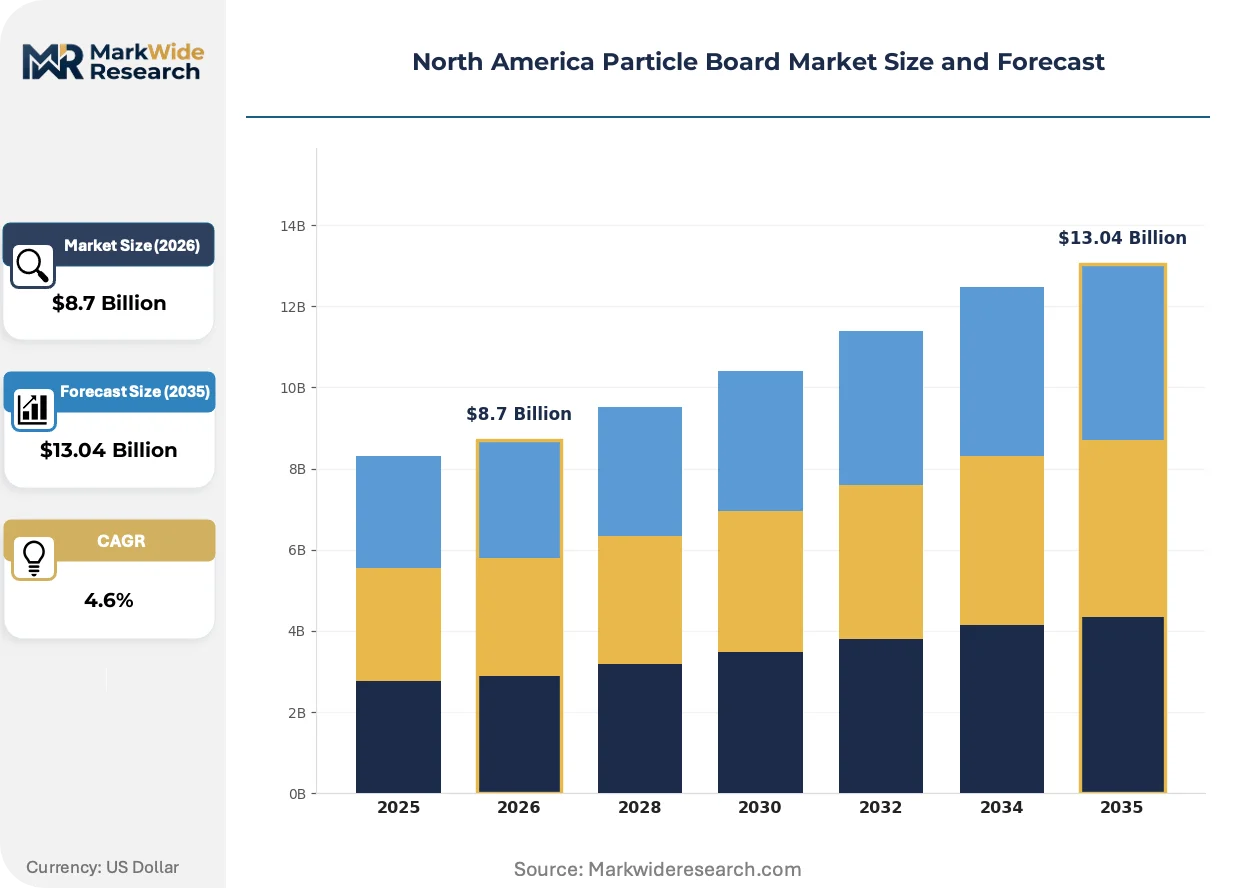
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Particle Board, Furniture Particle Board, Decorative Particle Board, Moisture Resistant Particle Board End User: Residential, Commercial Furniture, DIY Enthusiasts, Construction Thickness: 15 mm, 18 mm, 25 mm, 30 mm Manufacturing Process: Wet Process, Dry Process, Extrusion, Laminating |
| Companies Covered | Roseburg Forest Products, Georgia-Pacific, Arauco, Kronospan LLC, Egger Wood Products LLC, Uniboard, West Fraser Timber Co., Boise Cascade, Collins Products, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Particle Board Market Evolving Landscape
Digital manufacturing control and emission-compliant resin chemistry are converging to redefine how North American particle board achieves cost-positioned differentiation. These forces are compressing traditional quality-cost trade-offs while opening new specification channels.
Continuous belt pressing with real-time density scanning is hybridizing quality control with production throughput. Cabinetry OEMs in Mexico are adopting these grades at accelerating pace as surface consistency requirements tighten. The technology is hybridizing the historical separation between commodity subflooring and premium decorative applications.
EPA's TSCA Title VI third-party certification mandate is forcing testing infrastructure consolidation among smaller producers. Industrial consequence includes elevated compliance costs that disproportionately burden non-integrated mills without captive laboratory capacity. The standard is reshaping competitive positioning most visibly in the southeastern United States where mill density is highest.
Fabricators are consolidating purchase orders toward certified suppliers with documented chain-of-custody. Traditional distributor networks are losing share to direct mill relationships as large cabinetry OEMs in Querétaro and the southern United States seek supply assurance. This concentration is most advanced in kitchen and bath verticals where retailer liability exposure drives documentation requirements.
North America Particle Board Market Segmentation
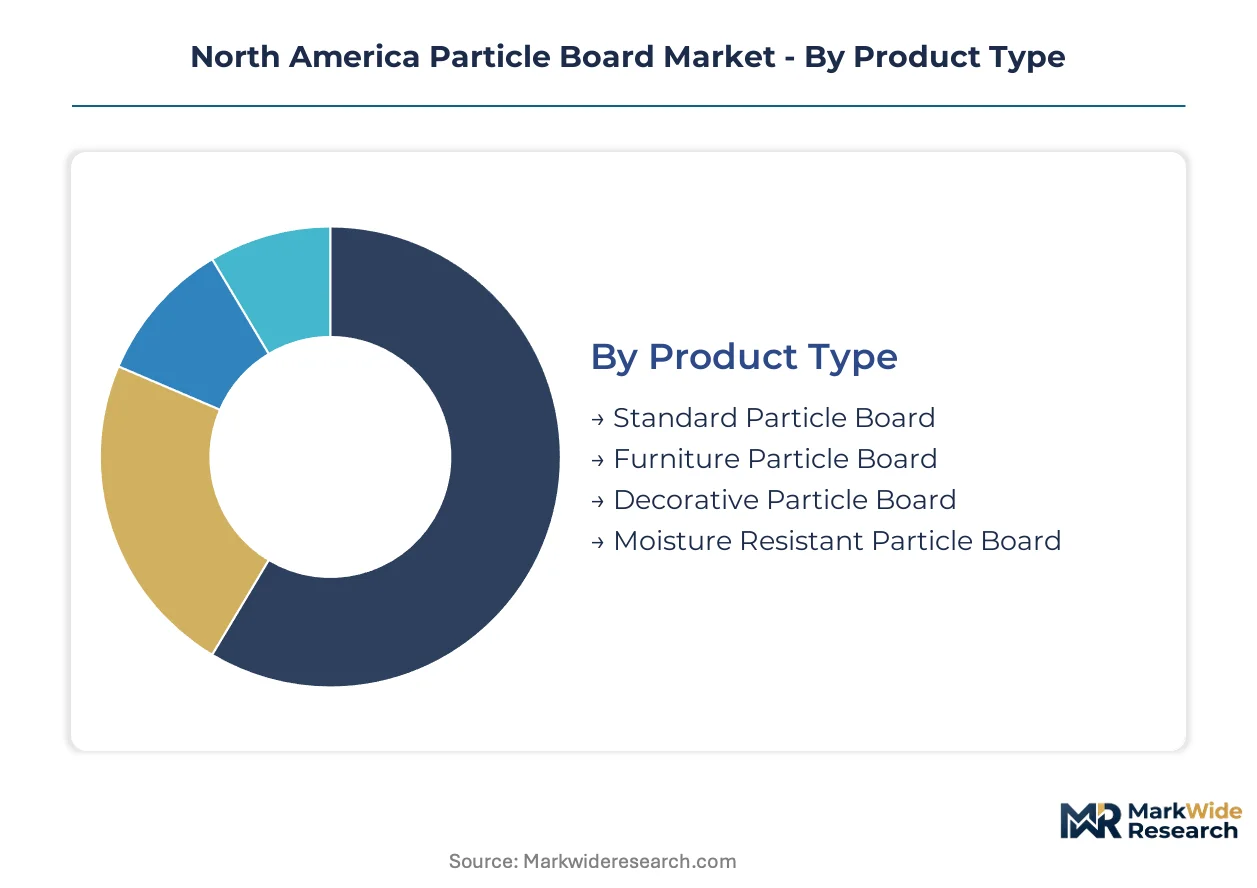
Particle board segmentation in North America reflects divergent performance requirements across furniture manufacturing, construction subflooring, and cabinetry applications. Each dimension—product grade, end-use vertical, thickness specification, and manufacturing method—carries distinct margin profiles and compliance obligations that shape procurement patterns.
Product Type:
Use-case spectrum spans commodity subflooring to decorative surfacing, with performance certification governing specification access in moisture-exposed environments.
- Standard Particle Board:General-purpose grades achieve densities of 600-800 kg/m³ through synthetic resin bonding of wood particles under heat and pressure. Residential construction subflooring and basic shelving in the southern United States absorb the majority of volume, though margin compression from furnish cost volatility limits producer returns.
- Moisture Resistant Particle Board:ANSI A208.1 Type M-2 certification qualifies these grades for kitchen and bath applications where humidity exposure demands dimensional stability. Procurement from Querétaro-area cabinetry OEMs is climbing fastest as surface consistency requirements tighten for North American distribution.
- Furniture Particle Board:Substrate grades optimized for lamination and veneer adhesion serve casegoods and ready-to-assemble furniture manufacturing.
- Decorative Particle Board:Pre-finished or specialty-surfaced grades target premium cabinetry OEMs requiring documented chain-of-custody for retailer liability compliance.
Established volume favors Standard Particle Board; emerging adoption favors Moisture Resistant Particle Board.
End User:
Customer type determines order scale, certification documentation burden, and channel structure from mill to final application.
- Residential:New construction and renovation activity across multi-family housing in the southern United States is expanding procurement for interior fit-outs. Builders concentrate purchase orders toward certified suppliers with TSCA Title VI documentation to limit liability exposure.
- Commercial Furniture:Office and hospitality casegoods manufacturers specify decorative grades with surface consistency guarantees. Querétaro's manufacturing corridor is capturing accelerating share as fabricators consolidate toward direct mill relationships.
- Construction:Subflooring and temporary structural applications demand cost-positioned standard grades with bulk delivery logistics.
- DIY Enthusiasts:Home improvement retailers stock limited thickness ranges for shelving and craft applications with lower certification documentation requirements.
Production planning prioritizes Commercial Furniture for margin stability; Residential absorbs volume fluctuations.
Thickness:
Dimension specification correlates directly with structural load requirements and lamination compatibility in finished goods manufacturing.
- 18 mm:The dominant specification for cabinetry carcasses and furniture components balances material cost with screw-holding strength. Querétaro OEMs specify this grade most heavily for North American kitchen and bath distribution.
- 25 mm:Shelving and countertop substrates requiring enhanced load-bearing capacity specify this dimension. Moisture-resistant certification adds premium positioning in bath vanity applications.
- 15 mm:Drawer bottoms and light-duty furniture applications use this thinner specification for cost minimization.
- 30 mm:Heavy-duty commercial shelving and structural applications demand maximum thickness for load distribution.
18 mm commands production priority; 25 mm is climbing fastest on moisture-resistant grade demand.
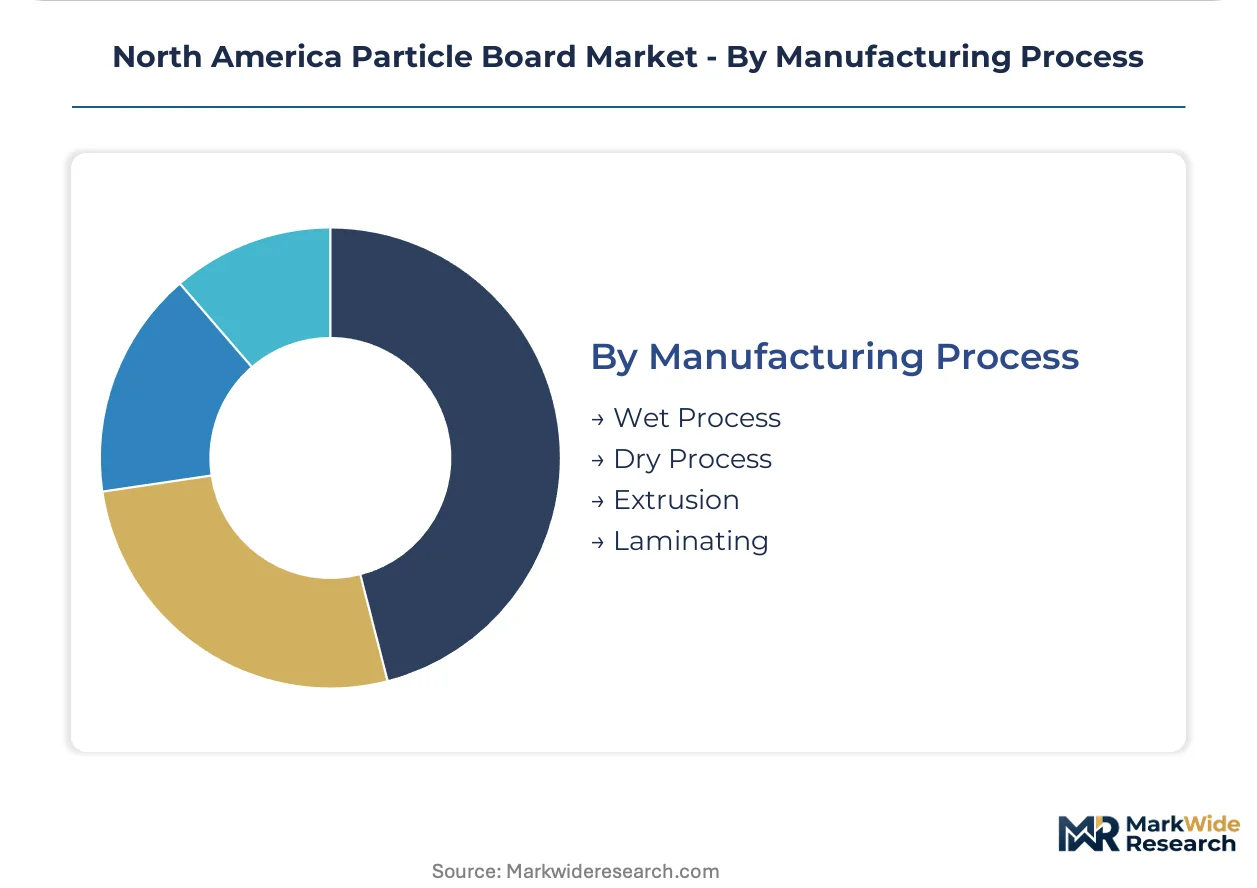
Manufacturing Process:
Process selection determines energy intensity, cycle time, and emission profile compliance with EPA and Health Canada standards.
- Dry Process:Wood particles are dried before resin application and pressing, achieving lower energy intensity and faster production cycles. This method dominates North American manufacturing due to cost efficiency and compatibility with continuous belt press automation.
- Wet Process:Slurry-based forming uses water as a distribution medium, producing higher density boards with smoother surfaces. Limited regional presence due to energy and water treatment cost disadvantages.
- Extrusion:Continuous forming through die extrusion creates specialized profiles for edgebanding and molding applications.
- Laminating:Post-press surface bonding of decorative overlays or functional coatings adds value in decorative grade production.
Dry Process anchors capacity investment; Laminating captures margin expansion in decorative grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multi-family housing developers, cabinetry OEMs, and furniture fabricators concentrate procurement across distinct sub-regional clusters governed by divergent emission certification frameworks.
United States
Residential builders in Texas, Florida, and Georgia are expanding particle board orders for rental housing interiors as multi-family construction accelerates. EPA's TSCA Title VI formaldehyde standards compel third-party certification documentation for specification access. The southeastern timber belt around Alabama and Mississippi anchors furnish supply for regional mill networks.
Canada
Health Canada maintains aligned but distinct surface coating guidelines affecting cross-border product certification for integrated supply chains. British Columbia and Quebec house decorative panel manufacturing serving North American distribution. Toronto-area fabricators consolidate purchase orders toward certified suppliers with documented chain-of-custody.
Mexico
Querétaro's furniture manufacturing corridor concentrates demand from cabinetry OEMs sourcing decorative particle board substrates for export to the United States. Mexico's federal environmental standards operate alongside state-level industrial permitting. Direct mill relationships are compressing traditional distributor layers in this central manufacturing cluster.
North America Particle Board Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a structure where scale advantages and certification infrastructure determine tier placement. The competitive set compresses toward producers with captive resin synthesis and testing laboratories. Three archetypes dominate: integrated timberland-to-panel operators, decorative-grade specialists, and scale-driven commodity producers. Capacity expansion in moisture-resistant grades and direct-to-fabricator distribution constitute the primary competitive vectors.
Among North American integrated operators, Roseburg Forest Products and Georgia-Pacific exemplify the timberland-backed archetype with extensive southern pine sourcing networks. Arauco represents the specialized decorative-grade competitor targeting cabinetry OEMs with certified substrate offerings. These three companies anchor the competitive structure through distinct resource positions rather than overlapping strategic postures.
| Leading Market Players |
|---|
| Roseburg Forest Products |
| Georgia-Pacific |
| Arauco |
| Kronospan LLC |
| Egger Wood Products LLC |
| Uniboard |
| West Fraser Timber Co. |
| Boise Cascade |
| Collins Products |
| Others |
Value Network & Pricing Analysis
Underutilized capacity across southeastern U.S. mills is compressing pricing power for standard-grade particle board while concentrating margin capture among producers with captive resin synthesis. This utilization asymmetry rewards integrated operators with cost-advantaged furnish access and forces non-integrated mills toward contract pricing indexed to southern pine fiber costs.
Pricing Analysis
Cost-plus contracts indexed to Random Lengths Framing Lumber Composite govern long-term supply agreements between major mills and multi-family housing developers across Texas and Florida. Price differentiation separates TSCA Title VI-certified grades from uncertified supply, with moisture-resistant M-2 certification commanding premium positioning in kitchen and bath verticals. Cost compression in standard subflooring grades is intensifying because furnish volatility and resin chemistry expertise scarcity concentrate among legacy producers. Residential construction buyers exhibit highest price sensitivity, while Querétaro-area cabinetry OEMs prioritize surface consistency documentation over unit cost.
Supply Chain Analysis
Contract manufacturing concentration among continuous belt press operators in Alabama, Mississippi, and Georgia anchors North American particle board capacity. Raw material dependencies center on southern pine furnish, methanol-based urea-formaldehyde resin, and release agents for automated pressing lines. Single-source vulnerability in resin chemistry expertise creates supply chain risk as EPA certification mandates consolidate testing infrastructure among fewer producers. Distribution runs through direct mill relationships with large fabricators, bypassing traditional distributor layers in the fastest-growing verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation talent capable of balancing emission compliance with cost targets has become the binding constraint on competitive expansion, creating asymmetric returns for producers with captive R&D infrastructure.
For Market Incumbents: Insulate margin position by deepening backward integration into resin synthesis and securing long-term timber supply agreements across the southeastern furnish belt. Defensive priority centers on continuous belt press automation upgrades that compress cycle times while maintaining density uniformity, as MDF substitution threatens specification share in premium cabinetry applications.
For New Entrants and Emerging Players: Build out direct-to-fabricator distribution infrastructure serving Querétaro-area cabinetry OEMs, where traditional distributor layers remain vulnerable to disintermediation. White-space opportunity concentrates in decorative particle board grades with documented chain-of-custody for retailer liability compliance, leveraging third-party certification as a specification wedge against established commodity producers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across moisture-resistant grade capacity as continuous press upgrades demand multi-year commitment amid uncertain certification timeline clarity. Long-term viability favors integrated timberland-to-panel operators with southern pine sourcing networks; signal to monitor is consolidation velocity among non-integrated southeastern mills lacking captive laboratory capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Captive supply of urea-formaldehyde chemistry insulates against formulation expertise scarcity and EPA testing infrastructure consolidation. |
| Continuous Belt Press Automation | Real-time density scanning hybridizes quality control with throughput gains required for Querétaro OEM surface consistency specifications. |
| TSCA Title VI Pre-Certification | Early compliance with EPA third-party mandates secures specification access to state-level green procurement programs before enforcement tightens. |
| Direct-to-Fabricator Distribution | Bypassing traditional layers compresses channel costs and accelerates order-to-delivery cycles for Mexico's central manufacturing corridor. |
| Moisture-Resistant Grade Capacity Expansion | ANSI A208.1 Type M-2 certification captures premium positioning in kitchen and bath applications where performance claims govern specification. |
Research Methodology
Initial hypotheses were tested against primary input from plant managers at southeastern U.S. mills, procurement leads at Querétaro cabinetry OEMs, distribution channel partners, and technical R&D directors at resin suppliers, and refined through secondary validation against U.S. Census Bureau construction spending data, EPA TSCA Title VI certification registries, Random Lengths lumber pricing indices, and SEC 10-K filings from integrated forest products companies. Bottom-up volume estimates from end-use segment interviews were triangulated against top-down capacity assessments across North American press lines.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product grade, end-use vertical, thickness specification, and manufacturing process. CAGRs were derived from installed capacity utilization trajectories and end-use demand elasticity modeling, incorporating furnish cost volatility, multi-family housing starts patterns, and cross-border certification friction between EPA and Health Canada protocols as industry-specific forecast inputs.
Stress conditions across southern pine harvest disruption severity, resin input cost spikes, and MDF substitution velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of EPA enforcement activity, Health Canada guideline harmonization progress, and Querétaro OEM order consolidation patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Remodeling Market
Building & Construction Materials
Decorative Concrete Market
Building & Construction Materials
Japan Prefab Wood Building Market
Building & Construction Materials
China Concrete Superplasticizer Market
Building & Construction Materials
Global Shotcrete/Sprayed Concrete Market
Building & Construction Materials
Concrete Conditioner Market
Building & Construction Materials
Indonesia Cement Market
Building & Construction Materials
India Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
United Kingdom Prefab Wood Buildings Market
Building & Construction Materials
Middle-East and Africa Gypsum Board Market
Building & Construction Materials
Reclaimed Lumber Market
Building & Construction Materials
Building Insulation Materials Market
Building & Construction Materials
Fiber Cement Rainscreen Panels Market
Building & Construction Materials
Stone Veneer Market
Building & Construction Materials
Asphalt Market
Building & Construction Materials
Clean Room Panels Market