
 Industrial Fasteners Market | 2026-2036
Industrial Fasteners Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Fasteners Market Analysis
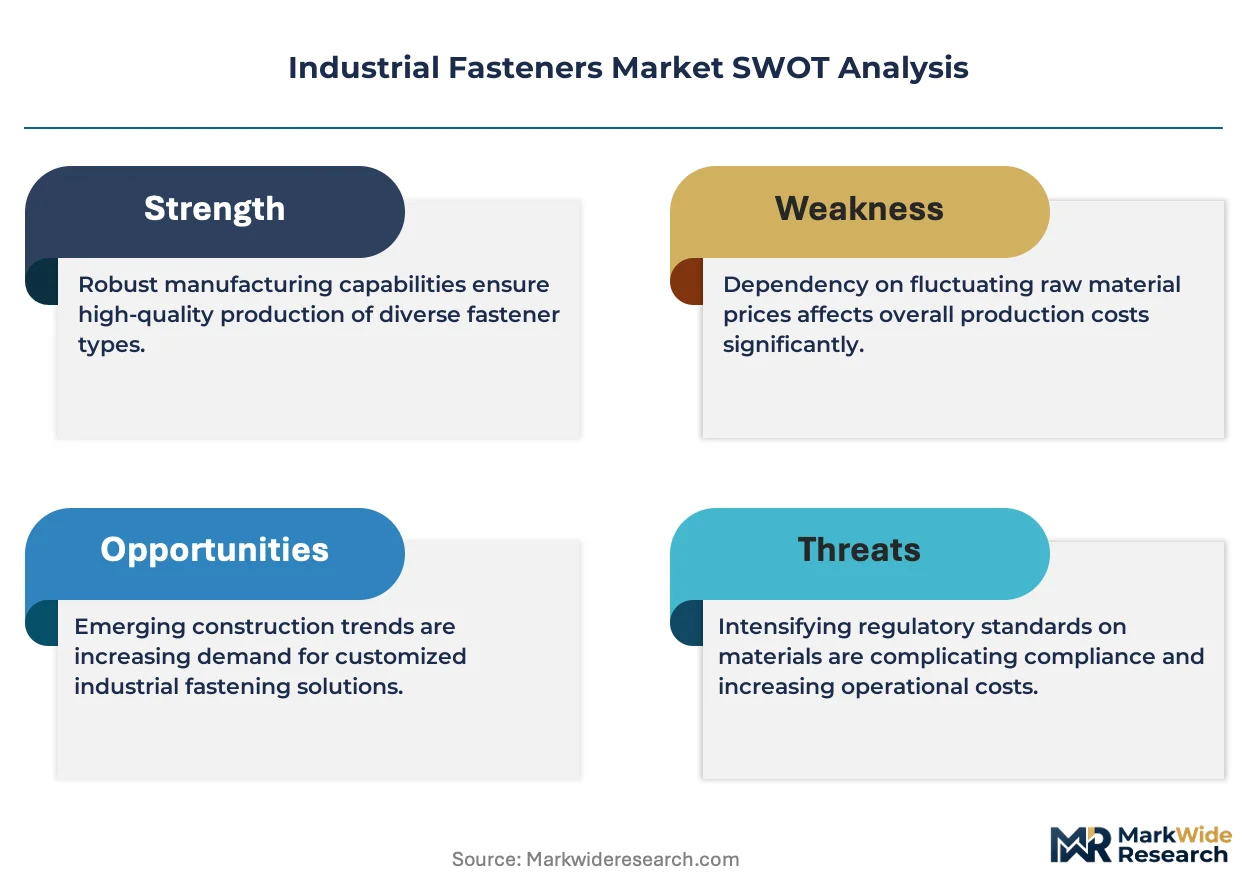
The gap between premium alloy fasteners and commodity carbon-steel variants is rebalancing as OEMs tighten specification bands for safety-critical joints. Illinois Tool Works leverages its captive metallurgy capabilities to sustain pricing power in aerospace-grade titanium offerings. Stanley Black & Decker anchors its position through channel density in construction distribution, while LISI Group specializes in precision cold-forming for automotive powertrain applications.
Industrial fasteners are mechanical joining devices—bolts, nuts, screws, and washers—typically manufactured through cold heading, thread rolling, or CNC machining to achieve precise tensile strength and torque specifications; they function to create detachable, load-bearing connections across machinery, infrastructure, and transport equipment. Steel remains the dominant material by volume, though titanium segments command disproportionate margin pools due to aerospace certification burdens and corrosion resistance requirements. The automotive end-user category is expanding fastest as electric vehicle platforms multiply joint counts per chassis, while construction applications retain mature, price-sensitive procurement patterns.
ISO 898-1 governs mechanical properties of carbon steel fasteners worldwide, while REACH in Europe restricts hexavalent chromium plating and EPA regulations in the United States govern effluent from electroplating operations; these frameworks elevate compliance costs for smaller forging houses and favor scaled producers with in-house finishing capacity. Stakeholders must monitor how battery-electric vehicle architectures reshape fastener specification sheets and whether domestic content rules in North America and Europe fragment procurement geography.
Market Dynamics
Automotive electrification is compressing fastener specification cycles as battery pack architectures demand novel joining solutions for dissimilar materials and thermal management interfaces.
Growth Catalysts
- REACH compliance deadlines:European ECHA enforcement is accelerating substitution away from hexavalent chromium plating toward zinc-nickel and trivalent chrome finishes.
- EV platform proliferation:Battery enclosure designs are multiplying joint counts per chassis, pulling aerospace-grade titanium into automotive supply chains.
- China's eastern manufacturing belt:Tier-one construction and heavy machinery suppliers in Jiangsu and Zhejiang provinces are anchoring procurement volumes for high-tensile structural fasteners.
Market Restraints
- Alloy input volatility:Sponge titanium prices fluctuate with aerospace demand cycles, compressing margin predictability for cold-forming houses.
- Electroplating capacity concentration:EPA effluent rules have shuttered smaller US finishing operations, consolidating supply among scaled producers with captive wastewater treatment.
- Adhesive bonding substitution:Structural acrylics and epoxy systems are displacing mechanical fasteners in composite-intensive EV body panels.
Strategic Opportunities
- India's PLI scheme for auto components:Domestic content incentives are creating captive demand for precision cold-formed fasteners in powertrain assemblies.
- Wind turbine OEM procurement:Offshore installation scale is pulling corrosion-resistant super-duplex stainless into nacelle and tower applications.
- Digital thread integration:RFID-embedded fasteners are converging with predictive maintenance platforms, enabling usage-based replacement models.
Industry Challenges
- Metallurgical talent scarcity:Cold-heading process engineers with titanium alloy expertise are concentrated among legacy aerospace suppliers.
- Multi-standard certification timelines:Simultaneous ISO 898-1, ASTM F568, and JIS B1181 qualification stretches new product introduction cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Fasteners Market |
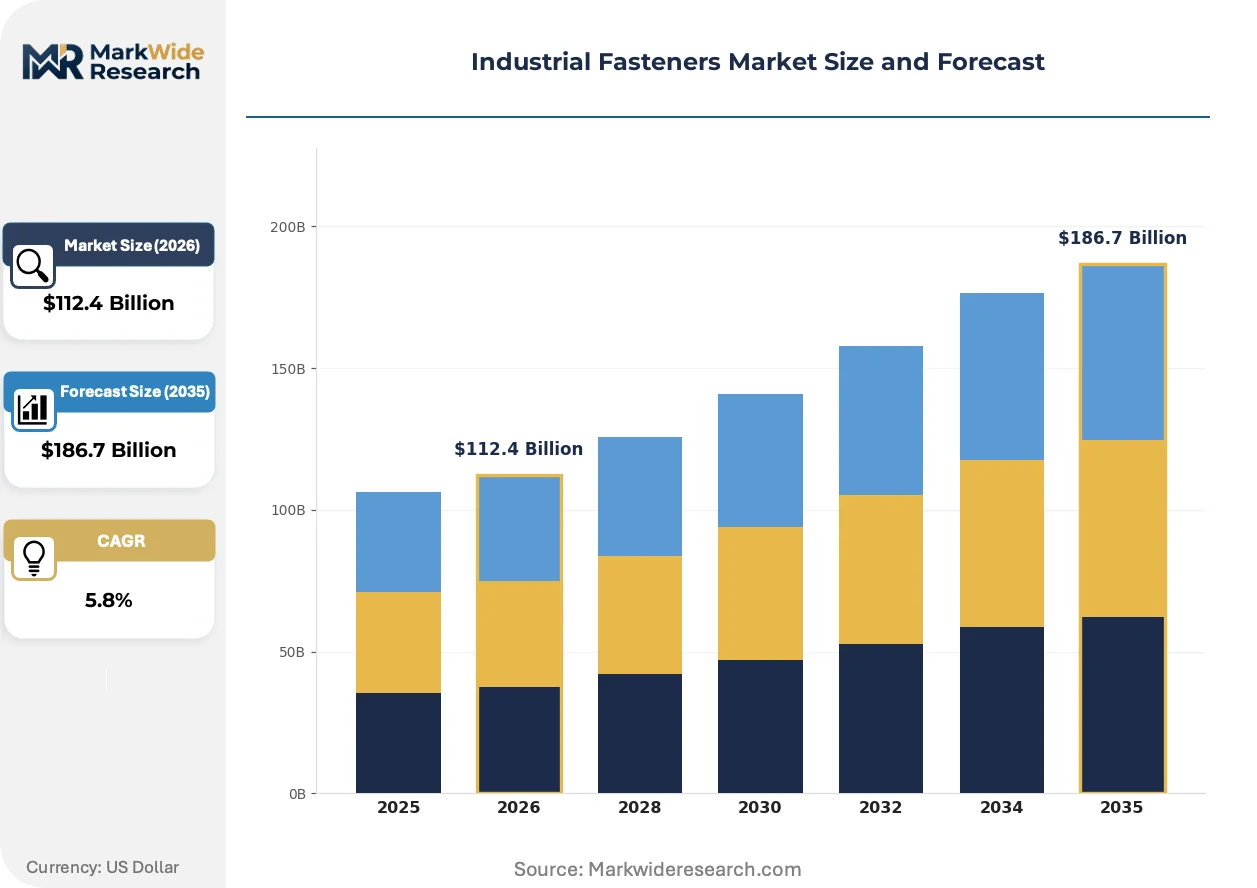
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $186.7 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bolts, Nuts, Screws, Washers Material: Steel, Aluminum, Plastic, Titanium End User: Aerospace, Automotive, Construction, Manufacturing Application: General Assembly, Structural, Electrical, Plumbing |
| Companies Covered | Illinois Tool Works, Stanley Black & Decker, Arconic Fastening Systems and Rings, Hilti Corporation, LISI Group, SFS Group, Nifco, MW Industries, Acument Global Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Fasteners Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are rewriting fastener specification sheets across transport and infrastructure end-uses.
Additive manufacturing is integrating topology-optimized fastener geometries that reduce weight while maintaining tensile ratings. Aerospace OEMs are adopting electron-beam melted titanium brackets for non-structural joints. This capability is compressing minimum order quantities and enabling lot-size-one production economics for maintenance operations.
EPA effluent guidelines are forcing electroplating operations to close-loop wastewater systems or relocate to jurisdictions with lighter enforcement. REACH Annex XVII restrictions on hexavalent chromium are elevating compliance costs for European forging houses. Automotive suppliers in Germany are responding by qualifying trivalent chrome and zinc-flake coating alternatives for underbody applications.
Consolidated procurement desks at wind turbine and construction OEMs are compressing supplier counts and demanding vendor-managed inventory arrangements. Distributors with regional stocking points are displacing traditional two-step wholesale channels. This concentration is most visible in Germany's wind energy corridor and Texas oilfield service territories.
Industrial Fasteners Market Segmentation
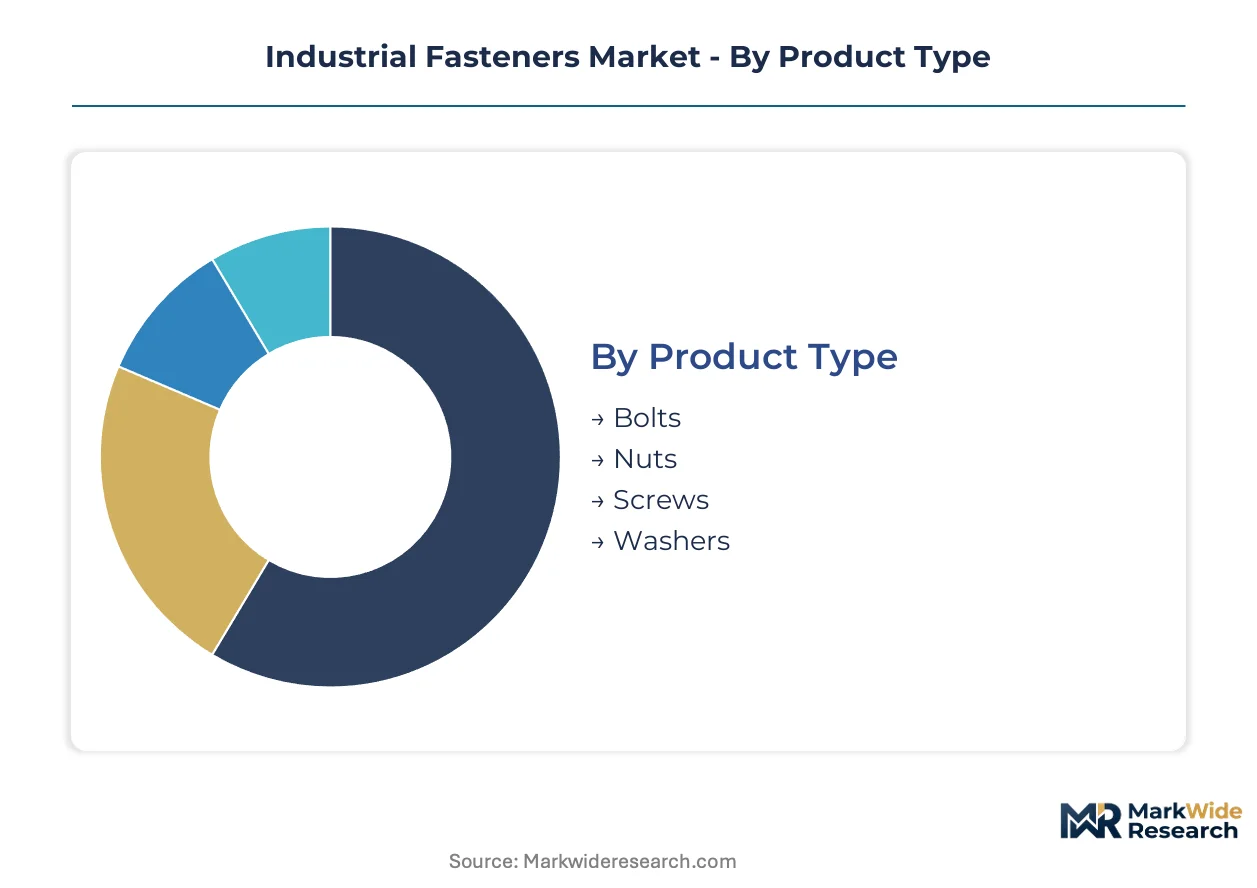
Fastener specification sheets diverge sharply across end-use categories, with material certification burdens and torque requirements dictating supplier qualification tiers. Procurement desks segment their vendor pools by metallurgical capability rather than product geometry alone.
Product Type:
Production tooling and cold-heading die configurations cluster around high-volume geometries, with capacity allocation following automotive and construction procurement cycles.
- Bolts:Externally threaded fasteners manufactured through cold heading and thread rolling to achieve precise tensile strength grades per ISO 898-1. Demand concentrates in Germany's automotive electrification programs, where battery enclosure architectures require high-tensile structural variants for aluminum-steel joints.
- Nuts:Internally threaded mating components produced via forging or machining to match bolt specifications. Jiangsu province's tier-one construction suppliers anchor procurement volumes for heavy machinery applications, with hex and flange variants dominating structural assemblies.
- Screws:Self-tapping and machine thread variants for lighter-duty applications across electronics and appliance manufacturing.
- Washers:Load-distribution and locking components for joint integrity in vibration-prone environments.
Bolts absorb the bulk of installed capacity; screws are expanding most quickly through electronics miniaturization trends.
Material:
Cost tier stratification separates commodity volume plays from margin-rich specialty alloys requiring captive metallurgy capabilities.
- Steel:Carbon and alloy grades dominate by volume, with cold-heading quality wire rod sourced from integrated mills. REACH compliance deadlines in Europe are accelerating substitution away from hexavalent chromium plating toward zinc-nickel finishes for underbody automotive applications.
- Titanium:Aerospace-certified grades command disproportionate margin pools due to corrosion resistance and strength-to-weight ratios. Sponge titanium price volatility tied to aerospace demand cycles compresses margin predictability for cold-forming houses serving medical and motorsport niches.
- Aluminum:High-grade alloys for lightweighting in electric vehicle battery enclosures and motor housings.
- Plastic:Nylon and PEEK variants for electrical insulation and corrosion-immune applications.
Steel absorbs the bulk of installed capacity; titanium is climbing the fastest through automotive electrification pull.
End User:
Application maturity determines procurement sophistication, with safety-critical joints demanding vendor-managed inventory and lot traceability.
- Automotive:EV platform proliferation is multiplying joint counts per chassis, with battery pack architectures requiring novel solutions for dissimilar material joining. Germany, Japan, and the United States are expanding fastener specifications for battery enclosures and electric motor housings.
- Construction:Mature, price-sensitive procurement patterns dominate, with China's eastern manufacturing belt anchoring volumes for structural fasteners in heavy machinery OEM supply chains.
- Aerospace:Certification burdens and torque specification precision requirements favor legacy suppliers with captive metallurgy.
- Manufacturing:General industrial machinery and equipment assembly with standardized procurement protocols.
Construction absorbs the bulk of installed capacity; automotive is gaining share fastest through electrification-driven specification expansion.
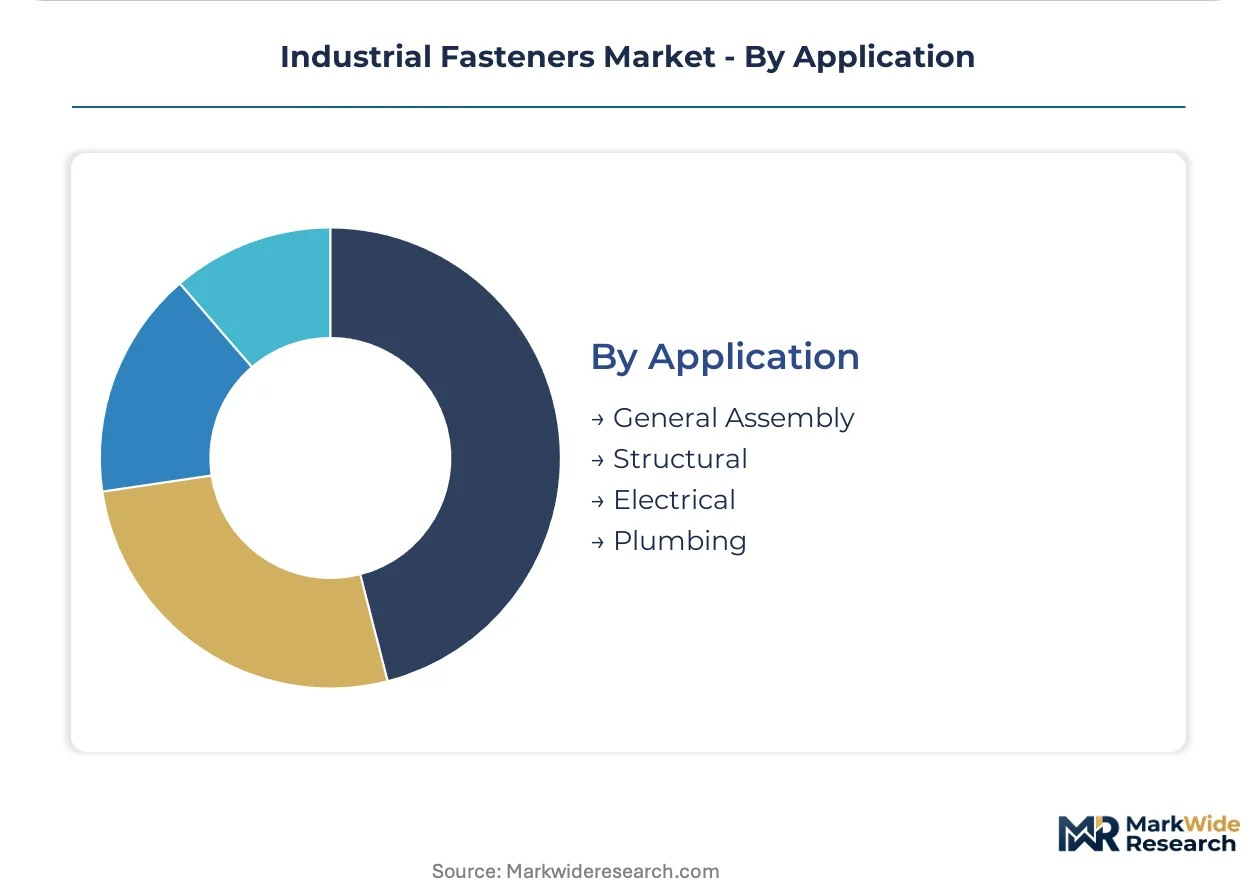
Application:
Functional performance requirements dictate material selection and coating chemistry, with regulatory restrictions fragmenting specification pathways.
- Structural:Load-bearing joints for infrastructure and heavy machinery requiring high-tensile grades and corrosion-resistant finishes. EPA effluent rules have shuttered smaller US electroplating operations, consolidating supply among scaled producers with captive wastewater treatment.
- General Assembly:Standard-duty fastening across machinery and appliance production with broad material acceptance.
- Electrical:Insulation-rated and conductive variants for power distribution and electronics.
- Plumbing:Corrosion-resistant grades for fluid handling systems and infrastructure.
General assembly absorbs the bulk of installed capacity; structural applications are expanding most quickly through wind turbine and infrastructure investment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Zhejiang provinces anchor procurement volumes for high-tensile structural fasteners serving construction and heavy machinery OEMs in China's eastern manufacturing belt.
China
Battery enclosure architectures for electric vehicles multiply joint counts per chassis in Jiangsu and Zhejiang provinces. MIIT dual carbon goals accelerate substitution toward high-grade aluminum alloys for motor housings. Tier-one suppliers in Suzhou and Ningbo anchor procurement volumes for automotive electrification programs.
Germany
Automotive OEMs expand fastener specifications for battery enclosures and electric motor housings across Bavaria and Baden-Württemberg. ECHA REACH compliance deadlines accelerate substitution away from hexavalent chromium plating toward zinc-nickel finishes. Stuttgart's automotive supply cluster pulls aerospace-grade titanium into powertrain applications.
United States
EPA effluent rules consolidate electroplating capacity among scaled producers with captive wastewater treatment in the Midwest and Southeast. NHTSA safety standards tighten specification bands for safety-critical joints in electric vehicle platforms. Illinois and Ohio cold-forming houses serve battery-electric vehicle architectures.
Japan
METI industrial policy supports precision cold-forming capabilities for automotive powertrain applications in Aichi and Kanagawa prefectures. JIS B1181 certification requirements stretch new product introduction cycles for multi-standard fasteners. Nagoya's automotive supply cluster specializes in titanium alloy expertise for motorsport niches.
India
PLI scheme incentives for auto components create captive demand for precision cold-formed fasteners in powertrain assemblies across Maharashtra and Tamil Nadu. BIS standards govern mechanical properties for carbon steel fasteners in infrastructure applications. Pune and Chennai manufacturing belts anchor procurement for construction and heavy machinery OEMs.
Industrial Fasteners Market Vendor Landscape
Premium-margin players sit above commodity-margin players across metallurgical capability and certification burden dimensions. The vendor base stratifies into legacy aerospace suppliers with captive titanium expertise, construction-channel distributors with regional density, and precision cold-forming specialists for automotive powertrain applications. Strategic moves concentrate on M&A for electroplating capacity consolidation and backward integration into wire rod supply.
Among North American diversified manufacturers, Illinois Tool Works and Stanley Black & Decker exemplify contrasting archetypes: the former represents metallurgy-forward positioning in aerospace-grade offerings, while the latter anchors construction distribution density. European specialists LISI Group occupy a position within precision cold-forming for automotive applications. These three entities collectively illustrate how certification burden and channel configuration separate margin tiers across the competitive landscape.
| Leading Market Players |
|---|
| Illinois Tool Works |
| Stanley Black & Decker |
| Arconic Fastening Systems and Rings |
| Hilti Corporation |
| LISI Group |
| SFS Group |
| Nifco |
| MW Industries |
| Acument Global Technologies |
| Others |
Supply Flow & Price Mechanics
Consolidated procurement desks at tier-one automotive and wind turbine OEMs command pricing power through vendor-managed inventory arrangements and multi-year offtake contracts. REACH compliance costs and captive electroplating capacity requirements stratify supplier tiers, compressing margins for unscaled forging houses while sustaining premium realizations for integrated metallurgy players.
Pricing Analysis
Value-based pricing anchors on joint reliability metrics and lot traceability for safety-critical applications. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-certified titanium offerings from commodity carbon-steel volumes. Cost compression in commodity grades intensifies because of sponge titanium price volatility and alloy input fluctuations. Construction procurement teams exhibit highest price sensitivity, while automotive electrification programs absorb premium grades with lower elasticity.
Supply Chain Analysis
Domestic content rules in North America and Europe are reshaping sourcing patterns for battery enclosure fasteners and powertrain components. Production gravity centers on China, Germany, and the United States, with Jiangsu province and the Midwest anchoring cold-heading capacity. Supply chains draw from sponge titanium, cold-heading quality wire rod, and zinc-nickel plating chemistries. Single-source vulnerability concentrates in aerospace-grade titanium forging. Distribution runs through regional stocking distributors displacing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where REACH and EPA effluent regulations erect barrier-to-entry moats favoring scaled producers with captive finishing capacity.
For Market Incumbents: Anchor pricing power through backward integration into wire rod supply and electroplating capacity consolidation. Cold-forming houses should deepen titanium alloy expertise to defend against adhesive bonding substitution in composite-intensive EV architectures. Certification investment in simultaneous ISO 898-1, ASTM F568, and JIS B1181 qualification stretches competitor new product introduction cycles. For New Entrants and Emerging Players: Launch via digital thread integration partnerships serving predictive maintenance platforms with RFID-embedded fasteners. India's PLI scheme for auto components offers the most penetrable white-space for precision cold-formed powertrain fasteners. Target wind turbine OEM procurement corridors in Germany's wind energy corridor with corrosion-resistant super-duplex stainless offerings. For Investors and Strategic Acquirers: The window for entry favors electroplating capacity consolidators with captive wastewater treatment infrastructure. Long-term viability hinges on exposure to automotive electrification specification expansion rather than mature construction procurement. Monitor battery-electric vehicle platform joint count trajectories as the inflection signal for titanium grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wire Rod Supply | Captive metallurgy secures margin control against alloy price volatility from integrated mills. |
| Electroplating Capacity Consolidation | EPA effluent compliance creates moats favoring scaled producers with closed-loop wastewater systems. |
| Multi-Standard Certification Investment | Simultaneous ISO 898-1 and REACH qualification stretches rival new product introduction timelines. |
| Digital Thread Integration Partnership | RFID-embedded fasteners converge with predictive maintenance platforms enabling usage-based replacement models. |
| Regional Stocking Point Expansion | Vendor-managed inventory arrangements displace traditional two-step wholesale channels in construction distribution. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with cold-forming process engineers, automotive Tier 1 procurement leads, construction distributor category managers, and electroplating operations directors complemented secondary validation. Bottom-up fastener volume estimates triangulated against top-down end-use demand projections from vehicle production databases and wind turbine installation records.
Data-stream reconciliation across shipment volumes, alloy consumption patterns, and OEM specification sheets informed the analytical framework. Segmentation dimensions modeled include product geometry, material grade tier, end-use industry, and regional regulatory cluster. CAGRs derived from slope analysis of historical procurement cycles and projected specification expansion trajectories. Battery-electric vehicle platform joint counts and REACH substitution deadlines served as industry-specific forecast inputs across the projection horizon.
Alloy price volatility, regulatory enforcement timing, and adhesive bonding substitution rates are the dominant revision risks to forecast outputs. Forecasts reflect documented assumptions regarding electrification program cadence and compliance deadline adherence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Slag Handling Equipment Market
Material Handling Equipment
Industrial Bag Dust Filter Market
Material Handling Equipment
Global Mechanical Seals Market
Material Handling Equipment
Belt Scales Market
Material Handling Equipment
Push-Back Racking System Market
Material Handling Equipment
Ball Screw Support Unit Market
Material Handling Equipment
Decoiler Machine Market
Material Handling Equipment
Air Hose Market
Material Handling Equipment
Pedestal Boom System Market
Material Handling Equipment
Hoist Controller Market
Material Handling Equipment
Debris Loaders Market
Material Handling Equipment
Automated Material Handling Systems Market
Material Handling Equipment
Die Casting Market
Material Handling Equipment
Pipe Wrapping Machines Market
Material Handling Equipment
Scissor Lift Market
Material Handling Equipment
High Pressure Grinding Rollers Market